
 Indonesia Oil and Gas Upstream Market | 2026-2036
Indonesia Oil and Gas Upstream Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Oil and Gas Upstream Market Foresight
Production-sharing contract flexibility and reserve-based lending structures are reshaping capital access for upstream operators in Indonesia. Medco Energi Internasional Tbk leverages its integrated domestic footprint to sustain drilling economics across marginal fields. ExxonMobil Corporation anchors deepwater exploration commitment through the Cepu block development. INPEX Corp. differentiates via subsea tieback expertise that reduces development capex for stranded reserves.
Indonesia oil and gas upstream encompasses exploration, development, and production of crude oil and natural gas from subsurface reservoirs, typically involving seismic surveys, directional drilling, and artificial lift systems to maintain reservoir pressure and flow rates. The sector supplies feedstock to domestic refineries, LNG export facilities, and gas-fired power plants that underpin national energy security. International oil companies dominate capital deployment for large field developments, while national oil companies control legacy infrastructure and pipeline access. Enhanced oil recovery applications are expanding fastest as operators target maturing basins with declining natural drive mechanisms. Small field clusters attract independent operators seeking lower entry thresholds through standardized subsea system packages.
SKK Migas enforces production targets and local content thresholds that dictate contractor selection and equipment sourcing for every development phase. Pertamina operates under Ministry of Energy and Mineral Resources directives that prioritize domestic supply obligations over export optimization. BIS-equivalent national standards govern steel grades and pressure equipment certification for offshore installations. Stakeholders must monitor regulatory enforcement consistency across provincial jurisdictions and pre-position fabrication partnerships to satisfy escalating domestic content mandates.
Market Dynamics
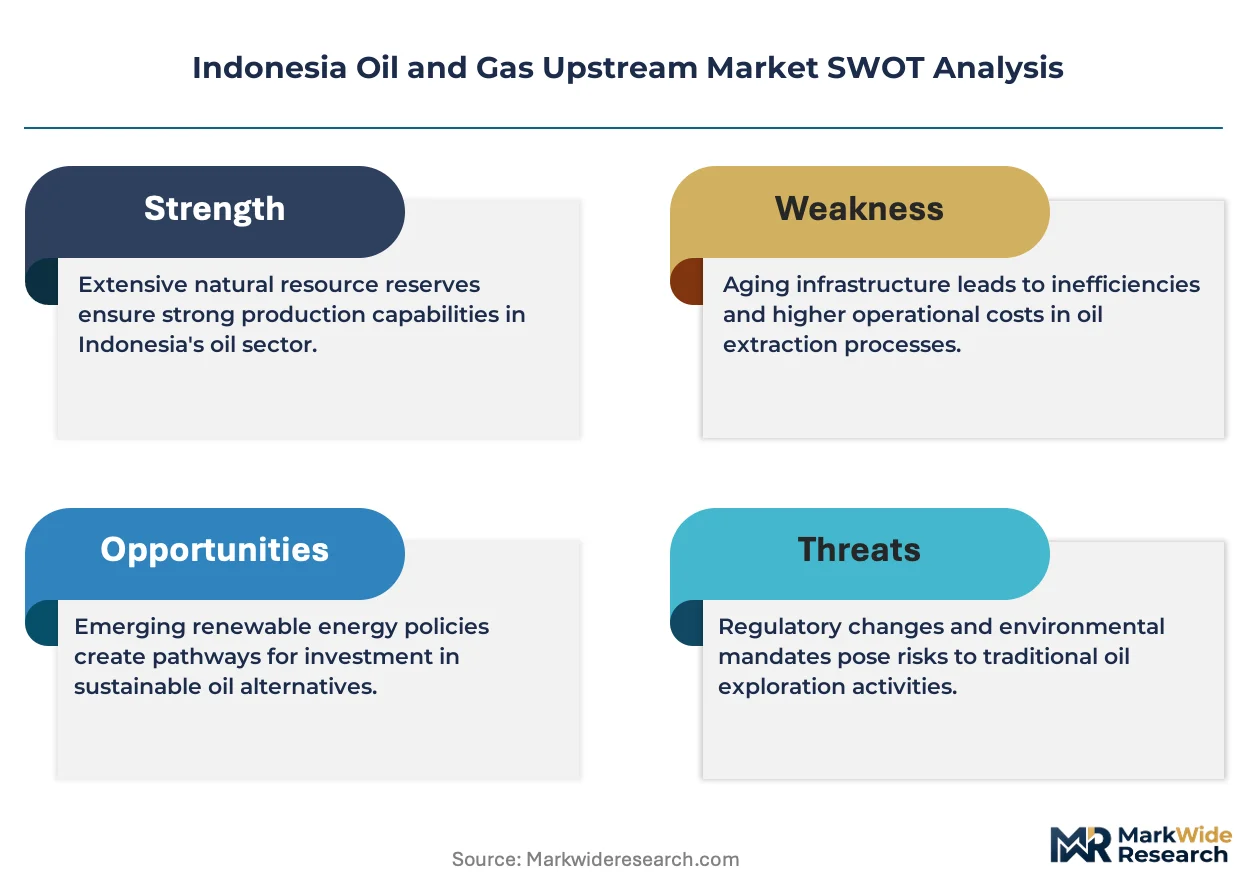
SKK Migas production targets and local content mandates are forcing operators to restructure contractor selection and equipment sourcing around domestic fabrication capacity. This regulatory pressure concentrates capital allocation toward fields with established infrastructure access.
Growth Catalysts
- Power generation offtake expansion:State-owned utilities are signing long-term domestic gas purchase agreements that de-risk upstream investment returns. This demand pull stabilizes field development economics.
- Enhanced oil recovery deployment:Thermal and chemical EOR methods are unlocking stranded reserves in mature Mahakam block formations. Operators deploy these techniques to offset natural decline rates.
- Production-sharing contract flexibility:Revised fiscal terms allow faster cost recovery for marginal field developments. SKK Migas implements these frameworks to sustain investment flows.
Market Restraints
- Domestic fabrication capacity constraints:Local yards face steel plate and skilled welder shortages that extend project timelines. This bottleneck inflates modular construction costs for offshore platforms.
- Reserve-based lending compression:International banks apply stricter discount rates to Indonesian reserve valuations. This credit tightening limits independent operator access to development capital.
- Subsurface complexity in deepwater frontiers:High-pressure high-temperature reservoirs beneath the Natuna Sea require specialized drilling packages. Technical uncertainty elevates exploration risk beyond threshold returns.
Strategic Opportunities
- Small field cluster development:Standardized subsea tieback packages reduce marginal field breakeven thresholds. Operators target these accumulations in the Java Sea.
- Carbon capture utilization integration:CO2-EOR applications align with Ministry of Energy and Mineral Resources decarbonization directives. This dual-purpose infrastructure attracts blended finance structures.
- Local content partnership models:Fabrication joint ventures with domestic yards satisfy SKK Migas domestic content mandates. These arrangements secure preferential contractor status.
Industry Challenges
- Directional drilling specialist scarcity:Complex well geometries in mature fields require experienced geosteering teams. Training pipelines for these competencies lag operational demand.
- Legacy pipeline integrity certification:Aging trunkline systems require pressure equipment recertification under BIS-equivalent national standards. Compliance timelines disrupt offtake scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Oil and Gas Upstream Market |
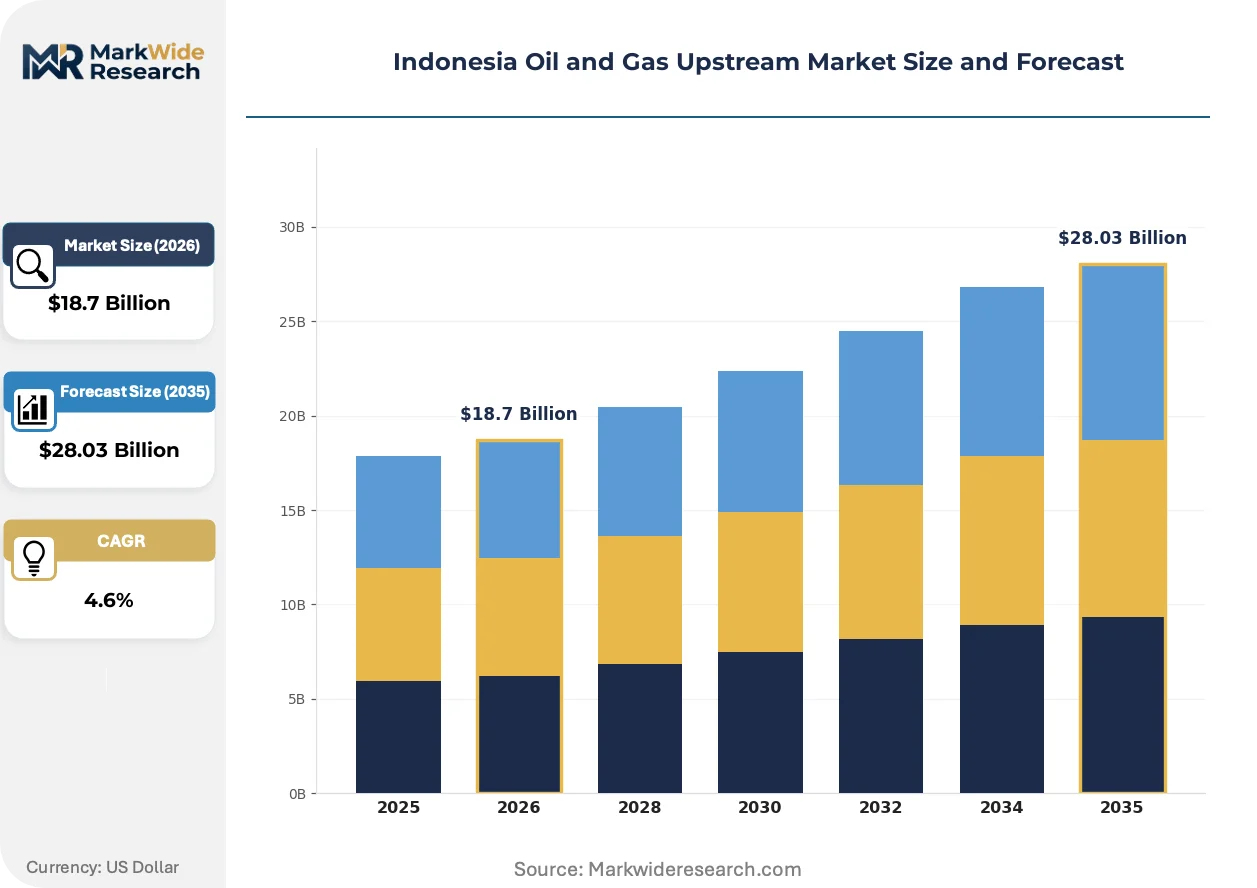
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Type: Exploration, Development, Production, Decommissioning Operator Type: National Oil Companies, Independent Operators, International Oil Companies, Service Providers Technology: Seismic Survey, Drilling, Enhanced Oil Recovery, Subsea Systems Field Size: Small Fields, Medium Fields, Large Fields, Super Giants |
| Companies Covered | PT Pertamina (Persero), Chevron Corporation, ExxonMobil Corporation, BP plc, INPEX Corp., TotalEnergies SE, Eni SpA, CNOOC Ltd., Medco Energi Internasional Tbk, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Oil and Gas Upstream Market Shifts & Advancements
Digital reservoir characterization and modular development architectures are compressing field appraisal-to-production cycles. These shifts reduce capital at risk and enable smaller operators to participate in marginal asset development.
Digital twin technology is virtualizing subsurface modeling workflows across Indonesian offshore operations. Pertamina and international partners deploy these platforms to optimize well placement in fractured carbonate reservoirs. The technology compresses exploration decision timelines from months to weeks.
SKK Migas local content enforcement is tightening equipment sourcing requirements for every project phase. Domestic fabrication partnerships now determine contractor qualification status. Operators respond by pre-positioning steel procurement and welding certification through Indonesian yard networks.
Integrated service contracting is consolidating drilling, completion, and subsea installation under single-source agreements. This procurement evolution displaces fragmented vendor management in deepwater developments. The Natuna Sea and eastern Indonesia basins exhibit the fastest adoption of bundled service structures.
Indonesia Oil and Gas Upstream Market Segmentation
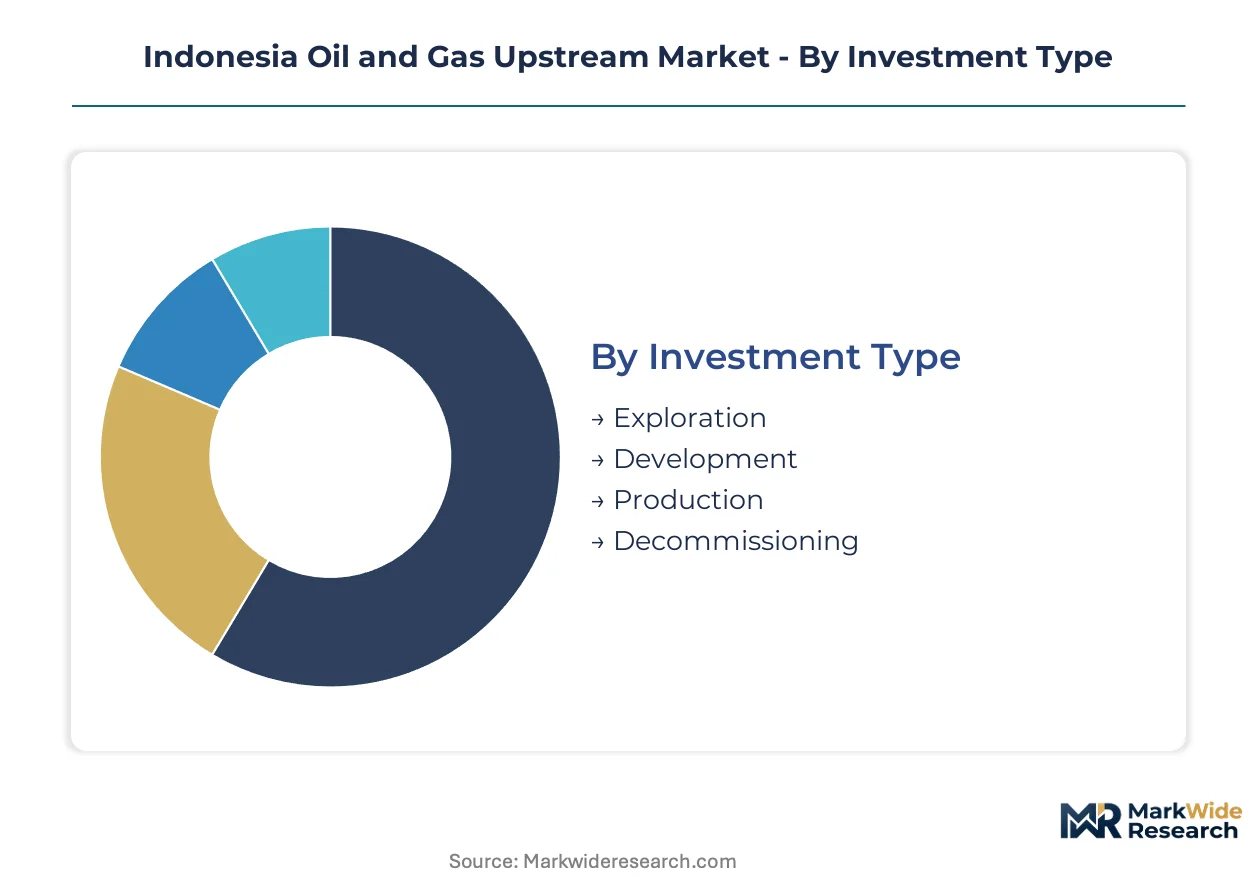
Upstream segmentation in Indonesia reflects capital deployment patterns shaped by SKK Migas production targets and Pertamina's drilling acceleration. Investment type and operator classification determine regulatory compliance pathways and local content thresholds.
Investment Type:
Capital allocation spans the full field lifecycle from frontier exploration through end-of-life decommissioning obligations.
- Exploration:Seismic surveys and wildcat drilling target untapped Natuna Sea and eastern Indonesia basins. SKK Migas cost recovery provisions under revised production-sharing contracts improve returns for high-risk frontier drilling programs.
- Development:Greenfield platform construction and subsea infrastructure installation dominate capital deployment. Mahakam block operators redirect spending toward standardized tieback packages that compress project schedules.
- Production:Sustaining output from mature reservoirs requires artificial lift systems and well intervention campaigns. This segment absorbs the largest share of operating expenditure across Indonesian upstream portfolios.
- Decommissioning:Platform removal and site restoration obligations escalate as North Sumatra and Java Sea fields reach end-of-life. Operators pre-fund these liabilities through escrow mechanisms mandated by the Ministry of Energy and Mineral Resources.
Established volume favors Production; emerging adoption favors Development.
Operator Type:
Regulatory access and capital scale differentiate contractor categories competing for SKK Migas work program approvals.
- National Oil Companies:Pertamina controls legacy infrastructure and pipeline networks across mature producing regions. Domestic supply obligations and ministerial directives constrain portfolio optimization flexibility.
- International Oil Companies:Deepwater exploration commitment and integrated project management capabilities anchor Cepu block and Natuna Sea developments. These operators navigate local content mandates through pre-positioned fabrication partnerships.
- Independent Operators:Medco Energi and comparable mid-cap specialists target marginal field clusters with standardized development architectures. Reserve-based lending compression limits capital access for this category.
- Service Providers:Schlumberger, Halliburton, and regional contractors supply directional drilling, completion, and subsea installation under integrated service contracts. Bundled procurement structures displace fragmented vendor management.
Contractor qualification status favors National Oil Companies; production growth contribution favors International Oil Companies.
Technology:
Technical capability requirements escalate with subsurface complexity and water depth across Indonesian offshore acreage.
- Seismic Survey:Multi-azimuth and wide-azimuth acquisition programs illuminate fractured carbonate reservoirs beneath the Natuna Sea. Digital twin integration compresses interpretation timelines from months to weeks.
- Drilling:High-pressure high-temperature packages and managed pressure drilling systems address HPHT conditions in deepwater frontiers. Directional drilling specialist scarcity constrains operational expansion.
- Enhanced Oil Recovery:Thermal and chemical EOR methods unlock stranded reserves in Mahakam block mature formations. CO2-EOR applications align with Ministry of Energy and Mineral Resources decarbonization directives.
- Subsea Systems:Standardized tieback packages and modular manifolds reduce marginal field breakeven thresholds. Small field clusters in the Java Sea attract this technology category.
Deployment scale favors Drilling; technology adoption velocity favors Enhanced Oil Recovery.
Field Size:
Development economics and regulatory treatment vary substantially across reserve scale categories.
- Super Giants:Cepu block and comparable billion-barrel accumulations anchor national production targets and LNG export commitments. These fields justify dedicated infrastructure and integrated development timelines.
- Large Fields:Mahakam block heritage assets and Natuna Sea developments sustain Pertamina and partner production bases. Established pipeline access and processing capacity support ongoing investment.
- Medium Fields:Cluster development approaches and shared infrastructure improve project returns. Operators target these accumulations between core producing regions and frontier acreage.
- Small Fields:Marginal accumulations below fifty million barrels require subsea tieback solutions and modular platform concepts. SKK Migas marginal field frameworks reduce fiscal burdens for this category.
Production volume concentration favors Super Giants; capital efficiency innovation favors Small Fields.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SKK Migas production targets and Pertamina's accelerated drilling program are redistributing upstream investment across Indonesia's archipelagic basins. Local content enforcement tightens contractor qualification pathways in every producing region.
Sumatra
Duri steamflood operations and Rokan block redevelopment sustain mature field production volumes. The Ministry of Energy and Mineral Resources mandates enhanced oil recovery deployment to offset natural decline rates. North Sumatra's legacy pipeline corridors require integrity recertification under BIS-equivalent national standards.
Java
Cepu block deepwater commitment anchors national crude output targets and refinery feedstock security. SKK Migas cost recovery provisions under revised production-sharing contracts improve frontier drilling economics. The Java Sea's marginal field clusters attract standardized subsea tieback packages from independent operators.
Kalimantan
Mahakam block gas offtake expansion serves state-owned power generation utilities under long-term purchase agreements. Pertamina operates under ministerial directives prioritizing domestic supply obligations over LNG export optimization. East Kalimantan's established processing capacity supports ongoing cluster development approaches.
Natuna Sea
High-pressure high-temperature reservoirs beneath these frontier waters require specialized drilling packages and managed pressure systems. SKK Migas implements revised fiscal frameworks to sustain investment flows into technically challenging acreage. Subsea infrastructure fabrication partnerships with domestic yards determine contractor qualification status.
Papua
Frontier basin exploration targets untapped eastern Indonesia formations with multi-azimuth seismic acquisition programs. International oil companies anchor deepwater commitment through integrated project management capabilities. Local content thresholds dictate equipment sourcing and fabrication partnerships for any commercial development.
Indonesia Oil and Gas Upstream Market Competitive Landscape
On the supply side, the industry is bifurcated between national oil companies controlling legacy infrastructure and international operators deploying capital for frontier developments. Pertamina anchors domestic supply obligations through ministerial directive compliance. International oil companies navigate local content mandates through pre-positioned fabrication partnerships. Competitive moves concentrate on integrated service contracting consolidation and carbon capture utilization integration for CO2-EOR applications.
Within the national operator tier, PT Pertamina (Persero) occupies the position of legacy infrastructure controller with domestic supply priority. Among international oil companies, ExxonMobil Corporation and INPEX Corp. exemplify deepwater exploration commitment and subsea tieback expertise respectively. These operators represent contrasting strategic archetypes: integrated project management capability versus specialized technical differentiation for stranded reserve development.
| Leading Market Players |
|---|
| PT Pertamina (Persero) |
| Chevron Corporation |
| ExxonMobil Corporation |
| BP plc |
| INPEX Corp. |
| TotalEnergies SE |
| Eni SpA |
| CNOOC Ltd. |
| Medco Energi Internasional Tbk |
| Others |
Supply & Pricing Matrix
Balikpapan's fabrication cluster capacity constraints directly constrain pricing power for offshore platform modules. Domestic yard bottlenecks inflate steel procurement premiums, forcing operators to absorb margin compression or extend project timelines.
Pricing Analysis
Certification level (BIS-equivalent national standards) creates the primary spread between premium and standard tier equipment sourcing. Contract-based long-term offtake agreements dominate, with price differentiation driven by local content compliance thresholds and volume scale commitments. Pricing pressure stems from reserve-based lending compression limiting independent operator budgets. National oil companies exhibit lowest price sensitivity due to ministerial directive backing; independent operators face acute cost compression.
Supply Chain Analysis
Domestic fabrication partnerships with Indonesian yards anchor contract-manufacturing concentration for subsea infrastructure. Supply draws from Indonesia, Singapore, and South Korea for specialized drilling packages and high-grade steel plate. Raw material dependencies center on nickel-alloy steel, subsea umbilicals, and managed pressure drilling systems. Single-source vulnerability runs through directional drilling specialist scarcity. Distribution feeds through integrated service contracting structures displacing fragmented vendor management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across operator categories and field size tiers creates entry niches for specialized service providers. Power generation offtake expansion is redistributing demand toward domestic gas field redevelopment.
For Market Incumbents: Entrench fabrication joint ventures with domestic yards to secure SKK Migas contractor qualification status. Deepen backward integration into steel procurement and welding certification to defend against emerging independent operators. Prioritize carbon capture utilization integration to align with Ministry of Energy and Mineral Resources decarbonization directives and access blended finance structures. For New Entrants and Emerging Players: Establish a beachhead in small field cluster development using standardized subsea tieback packages. Target Java Sea marginal accumulations where SKK Migas marginal field frameworks reduce fiscal burdens. Pursue local content partnership models with Balikpapan fabrication yards to satisfy domestic content mandates and secure preferential contractor pathways. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors subsea tieback specialists and digital reservoir characterization platforms over pure exploration exposure. Long-term viability hinges on integrated service contracting consolidation and CO2-EOR infrastructure deployment. Monitor SKK Migas local content enforcement consistency across provincial jurisdictions as the inflection indicator for capital allocation efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| Fabrication Joint Venture Formation | Domestic yard partnerships satisfy SKK Migas local content thresholds and secure contractor qualification. |
| Carbon Capture Utilization Integration | CO2-EOR applications align with Ministry of Energy and Mineral Resources decarbonization directives. |
| Integrated Service Contracting Consolidation | Single-source agreements for drilling, completion, and subsea installation displace fragmented vendor management. |
| Digital Twin Technology Deployment | Virtual subsurface modeling compresses exploration decision timelines from months to weeks for Pertamina partnerships. |
| Enhanced Oil Recovery Scale-Up | Thermal and chemical EOR methods unlock stranded reserves in mature Mahakam block formations. |
Research Methodology
Cross-validation between SKK Migas production reports and Pertamina drilling disclosures anchors the qualitative findings. Primary interviews with upstream project managers, fabrication yard procurement leads, reservoir engineers, and SKK Migas regulatory officers combined with secondary validation from Ministry of Energy and Mineral Resources directives, BIS-equivalent certification databases, and integrated service contractor filings. Bottom-up field-level data and top-down national production targets were triangulated to establish volume and value estimates.
Calibration against historical cost recovery timelines and local content compliance rates shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include investment type, operator classification, technology category, and field size tier. CAGRs were derived from regression analysis of capital deployment patterns and production target trajectories. Forecast inputs incorporated reserve-based lending availability indices and domestic fabrication capacity utilization rates.
Stress conditions across steel price volatility, SKK Migas local content enforcement intensity, and power generation offtake contract renewal rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about production-sharing contract flexibility persistence and Pertamina drilling acceleration continuity. Quarterly review of domestic fabrication yard backlog indicators and reserve-based lending spread movements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Gulf of Mexico Oil & Gas Decommissioning Market
Offshore Oil and Gas
North Sea Oil and Gas Market
Offshore Oil and Gas
Asia-Pacific Floating Offshore Wind Power Market
Offshore Oil and Gas
Europe Jackup Rig Market
Offshore Oil and Gas
High Pressure Oil and Gas Separators Market
Offshore Oil and Gas
East Africa Oil and Gas Upstream Market
Offshore Oil and Gas
Offshore Drilling Riser Market
Offshore Oil and Gas
India Oil and Gas Upstream Market
Offshore Oil and Gas
Denmark Oil and Gas Market
Offshore Oil and Gas
Global Floating LNG Power Vessel Market
Offshore Oil and Gas
Uzbekistan Oil and Gas Downstream Market
Offshore Oil and Gas
Jack-Up Rigs Market
Offshore Oil and Gas
Nigeria Oil and Gas Downstream Market
Offshore Oil and Gas
South America Offshore Energy Market
Offshore Oil and Gas
South Sudan Oil and Gas Downstream Market
Offshore Oil and Gas
Gulf of Mexico Subsea Systems Market