
 Marine Minerals Market | 2026-2036
Marine Minerals Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Minerals Market Foresight
Deep-sea mining engineers and submersible technicians is reorganizing the competitive landscape as specialized labor scarcity constrains project timelines across the Pacific basin. Nautilus Minerals Inc. leverages its early mover position in Papua New Guinea territorial waters to sustain exploration credibility despite operational setbacks. China Minmetals Corporation anchors its seabed strategy through state-backed research vessels and domestic processing capacity for polymetallic nodules. The Metals Company competes on extraction technology partnerships with Pacific island states, differentiating its approach through integrated collector vehicle designs.
Marine minerals encompass metallic and non-metallic deposits formed through hydrothermal, sedimentary, and biogenic processes at ocean depths exceeding 200 meters, with polymetallic nodules containing manganese, nickel, copper, and cobalt in concentrations of 20-30% combined metal content by dry weight. These resources serve critical industrial functions including battery cathode manufacturing, electronics substrate production, and renewable energy infrastructure alloys. Polymetallic nodules occupy the dominant position in current exploration portfolios due to their relatively flat seabed distribution and predictable grade profiles, while seafloor massive sulphides command premium interest from copper and gold processors seeking high-grade feedstock alternatives to depleting terrestrial mines. Deep-sea mining technology remains the most capital-intensive segment, though autonomous underwater vehicles are expanding fastest as survey and monitoring tools that reduce manned submersible deployment costs.
The International Seabed Authority governs exploration contracts in international waters, with its forthcoming exploitation regulations set to establish royalty frameworks and environmental threshold standards that determine project economics. National regulators including the EPA in United States territorial waters and China's MEE under domestic seabed jurisdiction impose overlapping compliance requirements that fragment permitting pathways for cross-border operators. Stakeholders must monitor how ISA member state negotiations resolve benefit-sharing mechanisms and environmental liability allocation before committing capital to production-scale equipment procurement.
Market Dynamics
Specialized submersible engineering capacity scarcity is compressing project timelines across the Pacific basin as contractors compete for finite deep-sea mining expertise.
Growth Catalysts
- Offshore wind cabling demand:Renewable energy developers in the North Sea and US Atlantic coast accelerate procurement of seafloor massive sulphides for turbine foundation alloys and grid interconnection hardware.
- ISA exploitation framework:The International Seabed Authority's anticipated mining code finalization will establish royalty structures and environmental thresholds that unlock institutional capital for production-scale equipment deployment.
- Polymetallic nodule grade stability:Clarion-Clipperton Zone deposits deliver predictable manganese-nickel-copper-cobalt concentrations that reduce metallurgical processing uncertainty for battery cathode manufacturers.
Market Restraints
- Capital intensity barriers:Autonomous underwater vehicle fleets and collector vehicle systems require nine-figure investment commitments before revenue generation, excluding mid-scale operators.
- Environmental liability concentration:The ISA's draft benefit-sharing mechanisms and ecosystem damage protocols expose contractors to uncapped remediation obligations in international waters.
- Terrestrial mining substitution:Indonesian nickel laterite expansion and Congolese cobalt artisanal output compete for battery supply chain offtake agreements.
Strategic Opportunities
- Cook Islands territorial licensing:Exclusive economic zone frameworks outside ISA jurisdiction offer streamlined permitting for polymetallic nodule extraction with sovereign-backed investment protections.
- Integrated collector-vehicle processing:Convergence of artificial intelligence-driven seabed mapping with real-time ore sorting technology enables selective nodule harvesting that minimizes sediment plume generation.
- Japan's METI seabed initiative:State-funded exploration contracts around Okinawa Trough seafloor massive sulphides create offtake partnerships for domestic rare earth element security.
Industry Challenges
- Submersible technician scarcity:Deep-sea operations require hybrid skill sets combining remotely operated vehicle piloting with marine geology interpretation that training programs have not scaled to match exploration contract growth.
- Multi-jurisdiction compliance stacking:Operators face overlapping EPA requirements for US territorial waters, China's MEE domestic seabed standards, and ISA international protocols that fragment permitting timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Minerals Market |
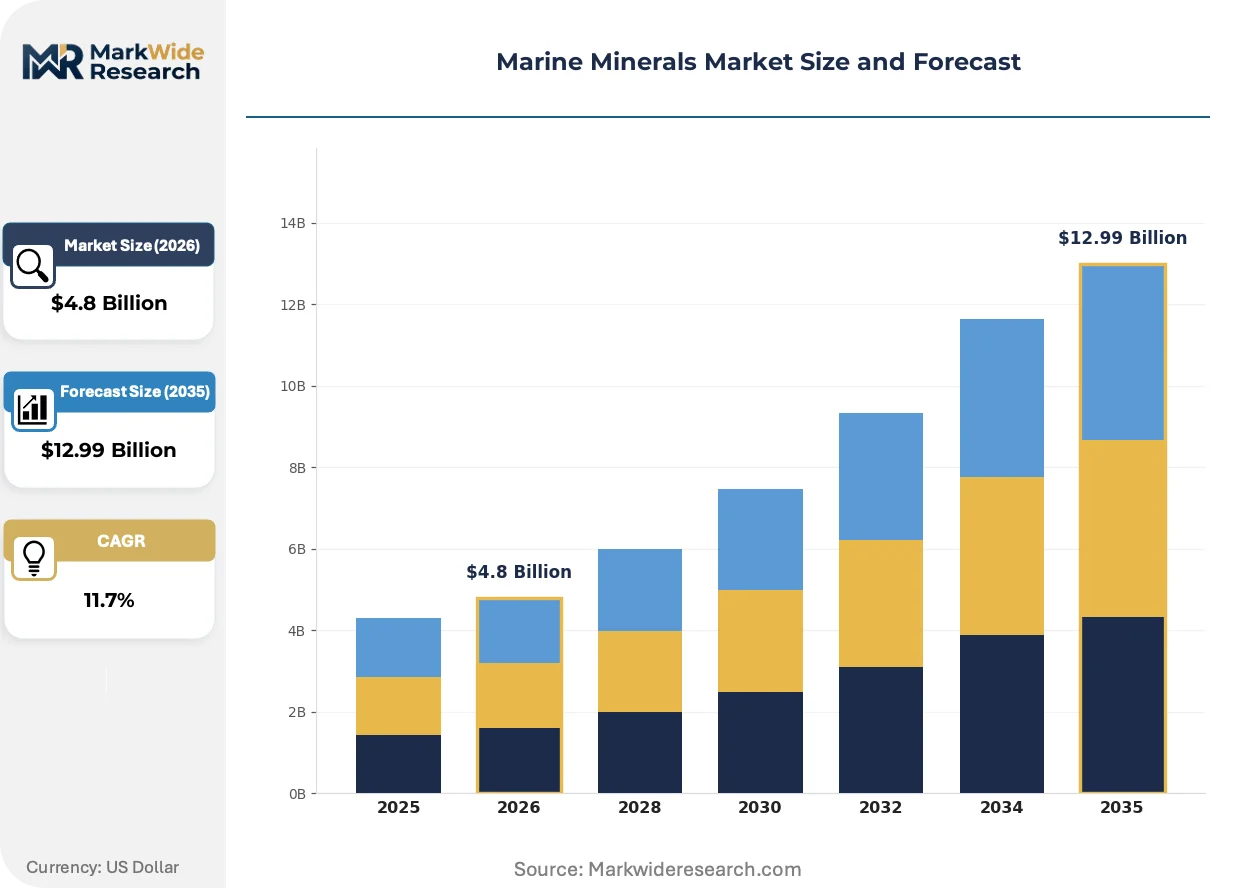
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymetallic Nodules, Hydrothermal Sulphides, Seafloor Massive Sulphides, Phosphorites Application: Electronics, Renewable Energy, Battery Manufacturing, Construction End User: Mining Companies, Environmental Organizations, Research Institutions, Energy Sector Technology: Deep-Sea Mining, Autonomous Underwater Vehicles, Submersibles, Remote Sensing |
| Companies Covered | Nautilus Minerals Inc., China Minmetals Corporation, De Beers Group, UK Seabed Resources, Royal IHC, DEME Group, Soil Machine Dynamics Ltd, The Metals Company, Global Sea Mineral Resources, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Minerals Market Shifts & Advancements
Extraction technology maturation is compressing the gap between exploration validation and commercial production, while regulatory frameworks crystallize around environmental liability allocation.
Autonomous underwater vehicles equipped with multi-beam sonar and hyperspectral imaging are displacing manned submersible deployments for baseline environmental surveys and deposit characterization. Offshore contractors in Papua New Guinea and Cook Islands waters adopt these systems at accelerating cadence to reduce operational costs and crew safety exposure. This displacement is compressing survey timelines from months to weeks while expanding the addressable seabed area per exploration contract.
The ISA's draft exploitation regulations introduce royalty frameworks tied to ad valorem mineral valuations and environmental performance bonds that reshape project finance structures. Contractors must model these obligations into feasibility studies before securing production equipment financing. Pacific island states with territorial licensing authority are responding by harmonizing domestic seabed laws with ISA standards to attract cross-border investment.
Buyers are consolidating procurement decisions through direct offtake agreements with exploration license holders rather than spot-market mineral purchases. Battery cathode manufacturers in South Korea and Japan negotiate multi-year supply contracts that specify cobalt and nickel grade thresholds, bypassing traditional commodity traders. This concentration is most visible in the Clarion-Clipperton Zone, where The Metals Company and comparable developers secure binding pre-production commitments to justify capital raises.
Marine Minerals Market Segmentation
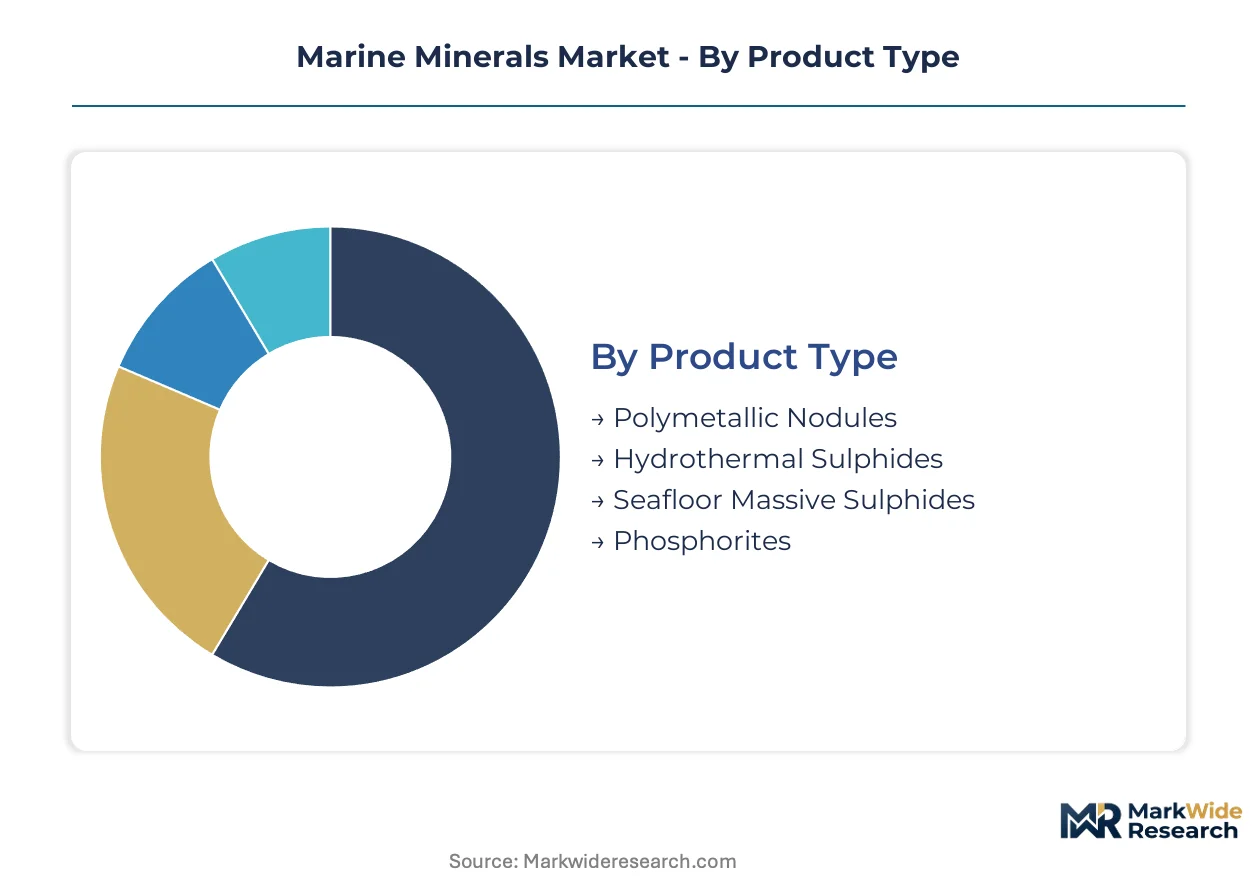
Marine minerals extraction requires distinct equipment configurations, permitting pathways, and metallurgical processing for each deposit type. Channel strategies diverge sharply between battery cathode manufacturers procuring polymetallic nodules and offshore wind developers sourcing seafloor massive sulphides for cabling alloys.
Product Type:
Polymetallic nodules and seafloor massive sulphides flow through different procurement channels, with nodules concentrating in long-term offtake agreements with Asian battery manufacturers while sulphides move through project-specific contracts with renewable energy developers.
- Polymetallic Nodules:These manganese-nickel-copper-cobalt concretions rest on abyssal plains at 4,000-6,000 meter depths with 20-30% combined metal content. Clarion-Clipperton Zone contractors ship nodules to Chinese and South Korean processors under binding pre-production supply contracts that bypass commodity traders.
- Seafloor Massive Sulphides:Copper-gold-zinc deposits formed at hydrothermal vents offer grades exceeding terrestrial mines. Offshore wind developers in the North Sea and US Atlantic coast accelerate direct procurement for turbine foundation alloys and grid interconnection hardware.
- Hydrothermal Sulphides:Active vent deposits near tectonic boundaries contain elevated rare earth concentrations. Japan's METI funds exploration around the Okinawa Trough to secure domestic supply chains for electronics manufacturing.
- Phosphorites:Sedimentary phosphate deposits support fertilizer production with lower capital intensity than metallic mineral extraction. Limited exploration activity concentrates in exclusive economic zones with streamlined permitting outside ISA jurisdiction.
Polymetallic nodules dominate installed base. Seafloor massive sulphides are where expansion concentrates.
Application:
Application segments stratify by margin structure, with battery manufacturing commanding premium pricing for cobalt and nickel specifications while construction absorbs lower-grade output.
- Battery Manufacturing:Cathode producers specify exact manganese-nickel-cobalt ratios for lithium-ion cells. South Korean and Japanese manufacturers negotiate multi-year contracts with grade thresholds that exclude spot-market variability.
- Renewable Energy:Offshore wind cabling and turbine foundations require copper-dominant alloys with corrosion resistance specifications. Developers procure through engineering-procurement-construction contractors rather than direct mineral traders.
- Electronics:Rare earth elements from hydrothermal deposits serve substrate and magnet applications. Processing constraints limit viable supply to integrated manufacturers with in-house separation capacity.
- Construction:Aggregate and cement applications absorb lower-purity phosphate and manganese output. Price sensitivity restricts this channel to territorial waters with reduced regulatory compliance costs.
Battery manufacturing captures value concentration. Renewable energy is climbing the fastest.
End User:
End user categories differ by procurement sophistication, with mining companies deploying technical specifications and environmental organizations influencing permitting timelines through litigation.
- Mining Companies:Integrated operators control vertical supply chains from extraction through processing. Nautilus Minerals and comparable developers seek offtake partnerships before committing to production-scale equipment procurement.
- Energy Sector:State-backed utilities and independent power producers enter direct supply agreements for critical minerals security. China's state-owned enterprises anchor seabed strategy through research vessel deployment and domestic processing investment.
- Research Institutions:Academic and government laboratories drive baseline environmental surveys that precede commercial extraction. Funding constraints limit their procurement to autonomous underwater vehicle charters rather than mineral purchase.
- Environmental Organizations:Advocacy groups participate in ISA stakeholder consultations and domestic litigation to delay licensing. Their influence concentrates on international waters where benefit-sharing mechanisms remain unresolved.
Mining companies dominate installed base. Energy sector expansion concentrates in Pacific island territorial waters.
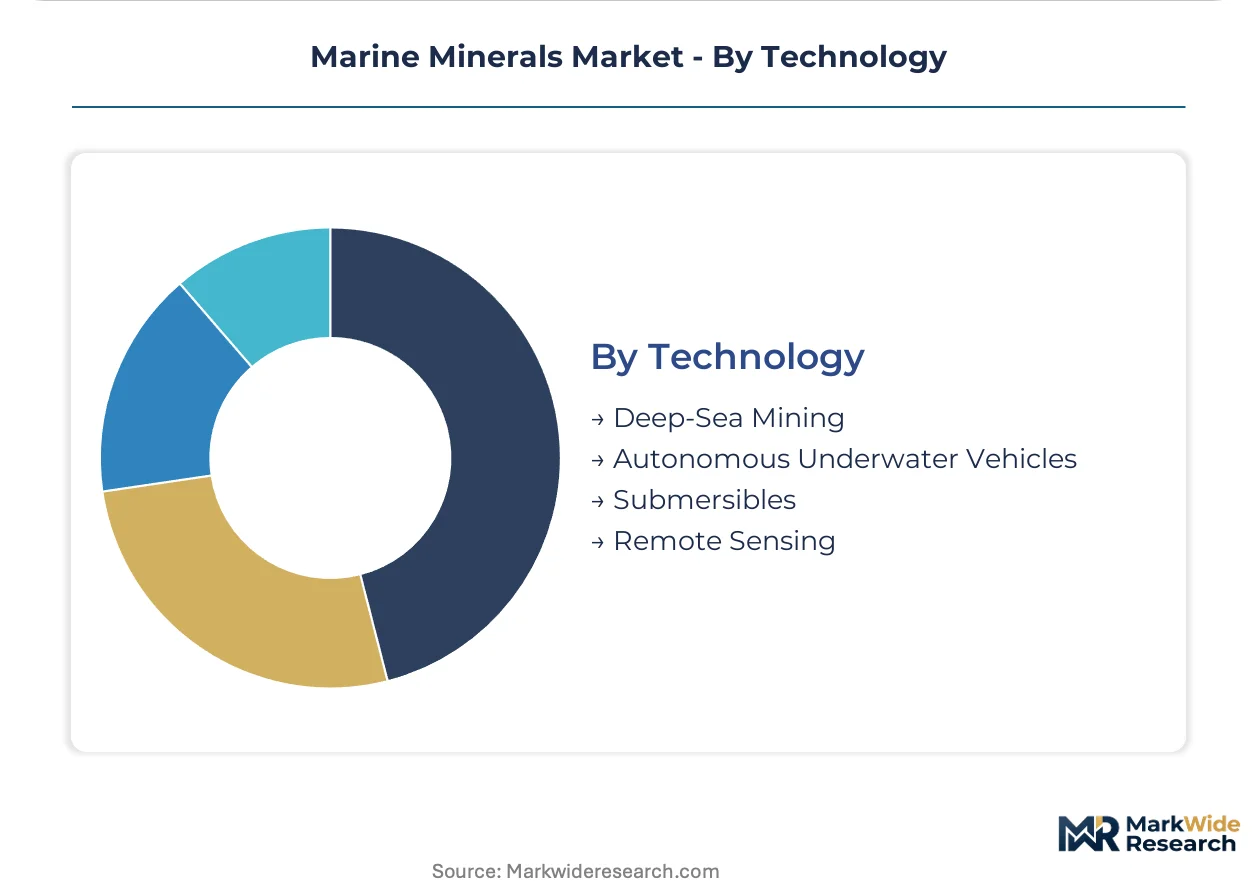
Technology:
Technology segments separate by capital intensity tiers, with deep-sea mining systems requiring nine-figure commitments while remote sensing platforms scale at lower thresholds.
- Deep-Sea Mining:Collector vehicles and riser systems represent the most capital-intensive segment with decade-long development cycles. The Metals Company competes on integrated designs that minimize sediment plume generation.
- Autonomous Underwater Vehicles:Multi-beam sonar and hyperspectral imaging platforms displace manned submersibles for survey work. Contractors in Papua New Guinea and Cook Islands waters adopt these systems to compress timelines from months to weeks.
- Submersibles:Manned and remotely operated vehicles retain niche roles in equipment maintenance and emergency intervention. Technician scarcity constrains fleet expansion across the Pacific basin.
- Remote Sensing:Satellite-derived bathymetry and seabed characterization support preliminary exploration targeting. Lower capital requirements attract junior exploration companies before transitioning to vessel-based survey.
Deep-sea mining dominates installed base. Autonomous underwater vehicles are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies, with Pacific island states prioritizing territorial licensing revenue while East Asian economies secure offtake agreements for battery supply chains. North American and European procurement concentrates on seafloor massive sulphides for renewable energy infrastructure rather than polymetallic nodules.
United States
Offshore wind developers along the Atlantic coast drive demand for copper-rich seafloor massive sulphides in turbine foundation alloys. The EPA imposes overlapping compliance requirements for territorial waters that fragment permitting timelines for cross-border operators. Massachusetts and Rhode Island cluster early procurement activity through state-level renewable energy mandates that specify domestic seabed mineral content.
China
State-backed battery manufacturers anchor polymetallic nodule demand for cobalt and nickel security in cathode production. The MEE under domestic seabed jurisdiction imposes standards that parallel ISA protocols for environmental threshold compliance. Qingdao and Shanghai house integrated processing capacity that receives research vessel deployments from the western Pacific exploration zones.
Japan
METI-funded exploration contracts around the Okinawa Trough target rare earth elements from hydrothermal sulphides for electronics manufacturing substrate security. The national seabed initiative channels state capital through JOGMEC to reduce import dependency on Chinese rare earth processing. Tokyo Bay clusters equipment fabrication capacity for autonomous underwater vehicle fleets serving domestic survey contracts.
Cook Islands
Exclusive economic zone licensing frameworks attract polymetallic nodule exploration investment with sovereign-backed protections outside ISA jurisdiction. Domestic seabed laws harmonize with international standards to streamline permitting for mid-scale operators excluded from nine-figure capital commitments elsewhere. Avarua serves as the administrative hub for exploration contract negotiations with Pacific basin contractors.
Papua New Guinea
Seafloor massive sulphide deposits in territorial waters command premium interest from copper and gold processors seeking high-grade feedstock alternatives. The national mining regulator coordinates with ISA-aligned environmental protocols to maintain exploration credibility despite operational setbacks in early mover projects. Port Moresby anchors submersible technician training programs that address Pacific basin labor scarcity.
Marine Minerals Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in marine minerals extraction. The upper tier controls vertical supply chains from exploration licensing through processing partnerships, while specialists concentrate on single-point technologies like collector vehicle design or autonomous survey platforms. State-backed enterprises and publicly traded developers constitute the dominant archetypes, with equipment fabricators and research contractors occupying supporting positions. Competitive moves center on territorial licensing acquisition in Pacific island exclusive economic zones and technology partnerships that reduce sediment plume generation in extraction systems.
Among state-backed enterprises, China Minmetals Corporation anchors the integrated archetype through domestic processing capacity and research vessel deployment. The Metals Company and Nautilus Minerals Inc. represent the publicly traded developer tier, with the former competing on extraction technology partnerships and the latter sustaining exploration credibility through early positioning in Papua New Guinea territorial waters. These three entities exemplify the strategic segmentation between state capital deployment and private capital risk-taking that defines competitive positioning.
| Leading Market Players |
|---|
| Nautilus Minerals Inc. |
| China Minmetals Corporation |
| De Beers Group |
| UK Seabed Resources |
| Royal IHC |
| DEME Group |
| Soil Machine Dynamics Ltd |
| The Metals Company |
| Global Sea Mineral Resources |
| Others |
Supply & Pricing Matrix
Nine-figure collector vehicle deployment commitments concentrate supply-side power among integrated operators with sovereign-backed financing, compressing price floors for mid-scale entrants while elevating barriers for speculative exploration contractors. Scale economies in Clarion-Clipperton Zone operations enable binding pre-production offtake terms that spot-market traders cannot match, locking battery cathode manufacturers into long-term supply hierarchies.
Pricing Analysis
Long-term offtake agreements dominate procurement, with South Korean and Japanese battery manufacturers negotiating multi-year contracts specifying cobalt-nickel grade thresholds that exclude commodity spot variability. Price differentiation rests on metallurgical processing integration and ISA environmental performance bond ratings, with certified low-sediment extraction commanding premiums. Cost compression in mid-tier exploration services is intensifying because autonomous underwater vehicle fleets displace manned submersible contracts. State-backed energy utilities show lowest price sensitivity; junior exploration companies dependent on spot-equity financing exhibit highest.
Supply Chain Analysis
Submersible engineering capacity chokepoints in Port Moresby and Qingdao constrain Pacific basin project timelines as contractors compete for finite technician pools. Supply concentrates in China, South Korea, and Japan for processing infrastructure; Papua New Guinea and Cook Islands anchor extraction licensing. Raw material dependencies include manganese-nickel-cobalt nodules, copper-gold sulphide deposits, and rare earth-bearing hydrothermal sediments. Single-source vulnerability in autonomous vehicle componentry threatens equipment delivery schedules. Distribution runs through direct offtake partnerships with battery manufacturers rather than mineral commodity exchanges.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine minerals developers face substitution defense against Indonesian nickel laterite expansion and Congolese cobalt artisanal output that compete for battery supply chain offtake commitments.
For Market Incumbents: Compound territorial licensing advantages in Pacific island exclusive economic zones before ISA exploitation regulations crystallize, securing sovereign-backed investment protections unavailable in international waters. Deepen backward integration into collector vehicle fabrication to reduce dependence on Soil Machine Dynamics and Royal IHC equipment suppliers. State-backed entrants from China Minmetals Corporation pose the primary competitive threat through integrated research vessel and processing capacity deployment. For New Entrants and Emerging Players: Anchor in Cook Islands territorial licensing frameworks that bypass ISA jurisdiction and nine-figure capital barriers, targeting polymetallic nodule exploration with streamlined permitting pathways. The penetrable white-space sits in autonomous underwater vehicle survey services for baseline environmental characterization, where technician scarcity has compressed contractor availability across the Pacific basin. Go-to-market leverage rests on AI-driven seabed mapping partnerships with mid-scale operators excluded from integrated extraction plays. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among autonomous underwater vehicle fleet operators serving multi-contract exploration programs, offering equipment-as-a-service models that decouple from extraction success rates. Long-term viability favors developers with secured offtake partnerships ahead of ISA royalty framework finalization. Target acquisition archetypes include integrated collector-vehicle designers with demonstrated sediment plume mitigation. The signal to watch is ISA member state consensus on benefit-sharing mechanisms that unlock institutional capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Collector Vehicle Technology Partnership | Integrated designs with sediment plume reduction secure ISA environmental certification preference. |
| Territorial Licensing Acquisition | Cook Islands and Papua New Guinea exclusive economic zones bypass ISA jurisdiction fragmentation. |
| Autonomous Underwater Vehicle Fleet Expansion | Multi-beam sonar platforms displace manned submersibles, compressing survey timelines from months to weeks. |
| Long-term Offtake Agreement Negotiation | South Korean and Japanese battery manufacturers bind supply chains before production-scale equipment deployment. |
| Submersible Technician Training Program | Port Moresby-based programs address Pacific basin labor scarcity constraining project timelines. |
Research Methodology
Operator-level perspectives from deep-sea mining engineers, submersible technicians, ISA regulatory affairs specialists, and battery cathode procurement managers anchored the qualitative base. Secondary validation drew from ISA contract registries, EPA territorial water filings, METI exploration disclosures, and customs records for research vessel equipment imports. Bottom-up project economics modeling triangulated with top-down market sizing across deposit types and application segments.
Sensitivity analysis tested royalty rate assumptions and environmental bond obligations across the projection horizon. Segmentation dimensions modeled include deposit type, application, end-user category, and technology tier. CAGRs derived from equipment deployment timelines and offtake contract ramp schedules. Forecast inputs incorporated ISA negotiation progress indicators and Pacific island licensing velocity.
Decision-makers should treat outputs as directional under stable ISA regulatory development assumptions; material deviation in benefit-sharing mechanisms or environmental liability protocols would warrant model refresh. Practitioners should keep alternative scenarios live as Indonesian nickel laterite capacity expansion and terrestrial mining substitution pressures evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Automotive Oil Strainer Market
Petroleum Products
North America Natural Gas Liquids Market
Petroleum Products
Saudi Arabia Refined Petroleum Products Market
Petroleum Products
Asia-Pacific Lubricants Market
Petroleum Products
Crude Oil Pour Point Depressant Market
Petroleum Products
Tar Oil Market
Petroleum Products
Natural Gas Liquid Market
Petroleum Products
Liquefied Petroleum Gas Market
Petroleum Products
Crude Oil Flow Improvers Market
Petroleum Products
Oil Storage Sales Market
Petroleum Products
Pyrolysis Gasoline Market
Petroleum Products
Pale Oil Market
Petroleum Products
Quenching Oil Market
Petroleum Products
Paraffin Oil Market
Petroleum Products
Southeast Asia Refined Petroleum Products Market
Petroleum Products
West Africa Refined Petroleum Products Market