
 Performance Oil Sales Market | 2026-2036
Performance Oil Sales Market Size, Share, and Industry Trends Forecast 2026-2036
Performance Oil Sales Market Insights
Bulk-to-blended packaging is expanding across fleet channels, converting traditional drum buyers to tote and intermediate bulk container programs. Shell leverages its integrated base oil refining network to control feedstock costs across synthetic and mineral product lines. Castrol Limited differentiates through OEM co-branding agreements with European and Asian automotive manufacturers. Valvoline sustains retail visibility via quick-lube service bay penetration in North America.
Performance oil comprises formulated lubricants engineered with Group III, IV, or V base stocks combined with additive packages containing detergents, dispersants, anti-wear agents, and viscosity modifiers, manufactured through controlled blending processes to achieve specific ISO viscosity grades and performance classifications. Motor oil dominates volume flows due to passenger car parc density and drain-interval extension trends. Hydraulic oil captures margin concentration in industrial machinery applications where equipment uptime penalties elevate specification stringency. Fleet operators represent the fastest-growing end user channel as centralized procurement shifts from spot purchasing to annual volume contracts.
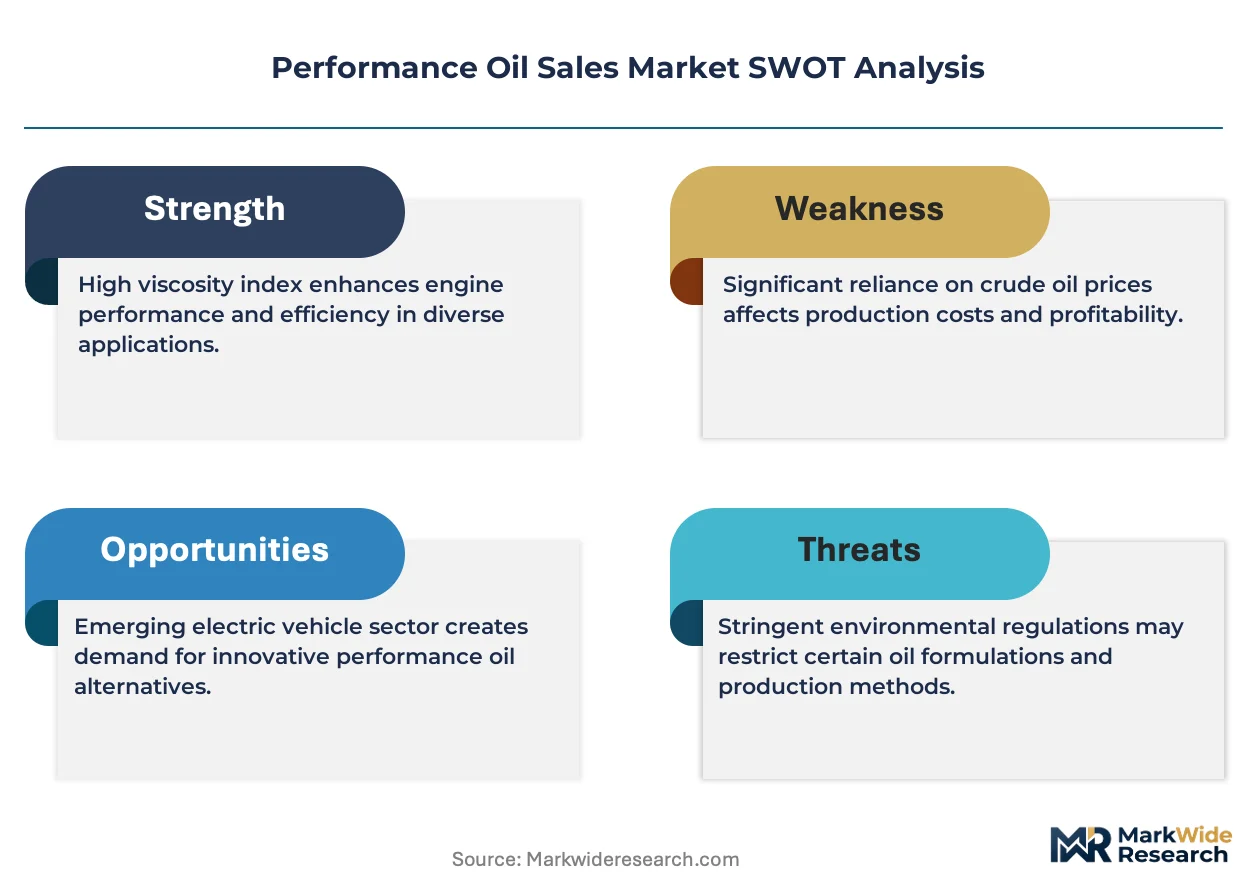
EPA fuel economy regulations and the EU F-Gas Regulation shape lubricant formulation requirements by mandating lower viscosity grades and reduced evaporative emissions profiles. China's MEE enforces national standards for industrial oil discharge that redirect demand toward biodegradable and extended-drain formulations. Stakeholders must monitor regulatory divergence between California's CARB framework and federal EPA standards, as compliance fragmentation threatens to bifurcate product portfolios and regional manufacturing configurations.
Market Dynamics
Drain-interval extension mandates from EPA fuel economy rules and EU Green Deal carbon targets are compressing specification cycles, forcing reformulation toward lower-viscosity synthetics that reduce internal engine friction and tailpipe emissions simultaneously.
Growth Catalysts
- Synthetic base stock substitution:Group III and Group IV formulations displace mineral oils in passenger car service fill as automakers chase Corporate Average Fuel Economy credits through reduced parasitic losses.
- EU F-Gas Regulation:Restrictions on high-global-warming-potential refrigerants cascade into compressor lubricant specifications, expanding demand for polyolester and polyalkylene glycol chemistries in mobile air conditioning systems.
- China's industrial corridor concentration:Sinopec and PetroChina captive refining complexes in Shandong and Liaoning provinces anchor domestic supply chains for high-viscosity hydraulic fluids serving construction equipment and wind turbine installations.
Market Restraints
- API Group II/II+ base oil oversupply:Refinery capacity expansion in the Middle East and Asia-Pacific has compressed Group II margins, trapping blenders between fixed additive costs and falling feedstock realizations for mineral product lines.
- Polyalphaolefin supply concentration:Four producers control roughly three-quarters of global PAO capacity, creating vulnerability to unplanned outages at Louisiana and Belgian crackers that supply synthetic motor oil feedstocks.
- California CARB fragmentation:Divergent evaporative emissions testing protocols from federal EPA standards force dual inventory maintenance, elevating working capital requirements for distributors serving the West Coast.
Strategic Opportunities
- Biodegradable hydraulic fluids in Nordic markets:Sweden, Norway, and Finland enforce mandatory environmental classification for forestry and marine equipment, opening formulation windows for vegetable-oil and synthetic-ester chemistries with enhanced aquatic toxicity profiles.
- Extended-drain fleet contracts:Centralized procurement departments at long-haul trucking operators are consolidating spot purchases into multi-year volume agreements with oil condition monitoring services bundled into per-mile pricing.
- Dual carbon goals alignment:China's MEE national standards for industrial oil discharge redirect state-owned enterprise procurement toward re-refined base stocks and closed-loop fluid management systems.
Industry Challenges
- Additive chemist shortage:Formulation expertise in ashless dispersant and zinc dialkyldithiophosphate chemistry is concentrating among retiring specialists at major additive houses, constraining independent blender R&D timelines.
- ILSAC GF-7 certification backlog:Sequence IVB and VH test stand availability bottlenecks at independent laboratories are extending product qualification cycles for passenger car motor oils targeting 2025 vehicle model years.
- Legacy drum-to-tote conversion friction:Fleet maintenance yards face capital expenditure requirements for intermediate bulk container handling infrastructure, slowing packaging format transitions despite per-unit cost advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Performance Oil Sales Market |
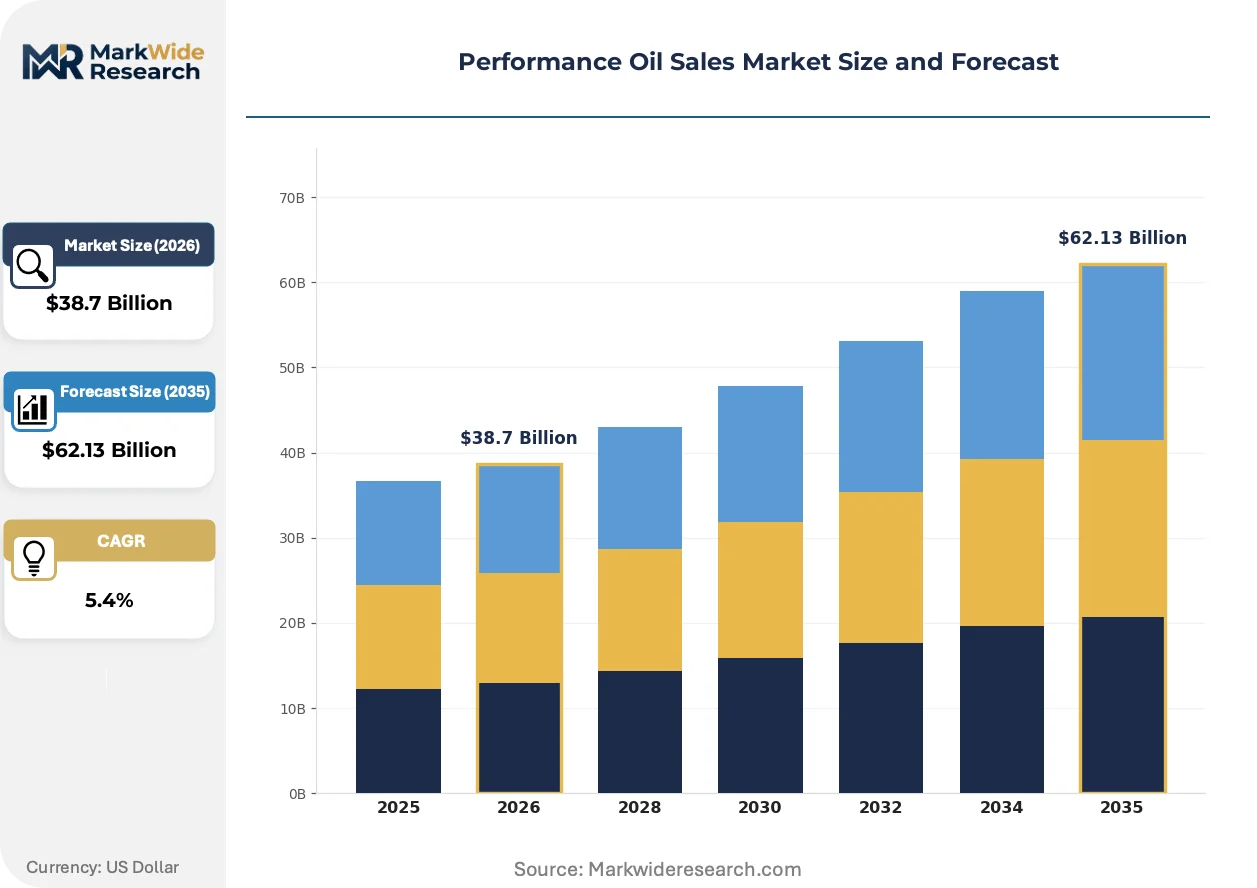
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $62.13 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Motor Oil, Transmission Fluid, Gear Oil, Hydraulic Oil Application: Commercial Vehicles, Passenger Cars, Industrial Machinery, Small Engines End User: Fleet Operators, Automotive Manufacturers, Repair Shops, DIY Consumers Distribution Channel: Retail Outlets, Online Stores, Direct Sales, Distributors |
| Companies Covered | Shell, ExxonMobil, Chevron Corporation, BP, Total, PetroChina, Sinopec, Valvoline, Castrol Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Performance Oil Sales Market Trends and Innovations
Formulation chemistry, regulatory stringency, and procurement centralization are converging to compress product lifecycles and elevate specification complexity across automotive and industrial applications.
Re-refined base oil technology is absorbing growing volumes of post-consumer lubricant through vacuum distillation and hydrotreating processes that restore Group II quality specifications. Municipal fleet operators in California and European waste-collection services are adopting re-refined content mandates, compressing virgin base oil offtake in price-sensitive segments while creating circular-economy compliance pathways.
REACH authorization requirements for zinc-based anti-wear additives are forcing reformulation toward boron and molybdenum chemistries in European industrial gear oils. The substitution imposes compatibility testing burdens on equipment OEMs, with German machine tool builders and Italian packaging machinery manufacturers most affected as they validate new lubricant chemistries against legacy elastomer seal inventories.
Fleet procurement departments are consolidating spot lubricant purchases into annual volume contracts with oil analysis and predictive maintenance services bundled into per-operating-hour pricing. North American Class 8 trucking operators and German freight forwarders are most visible in this transition, displacing traditional jobber distribution relationships with direct manufacturer agreements and telemetry-linked fluid monitoring.
Performance Oil Sales Market Segmentation
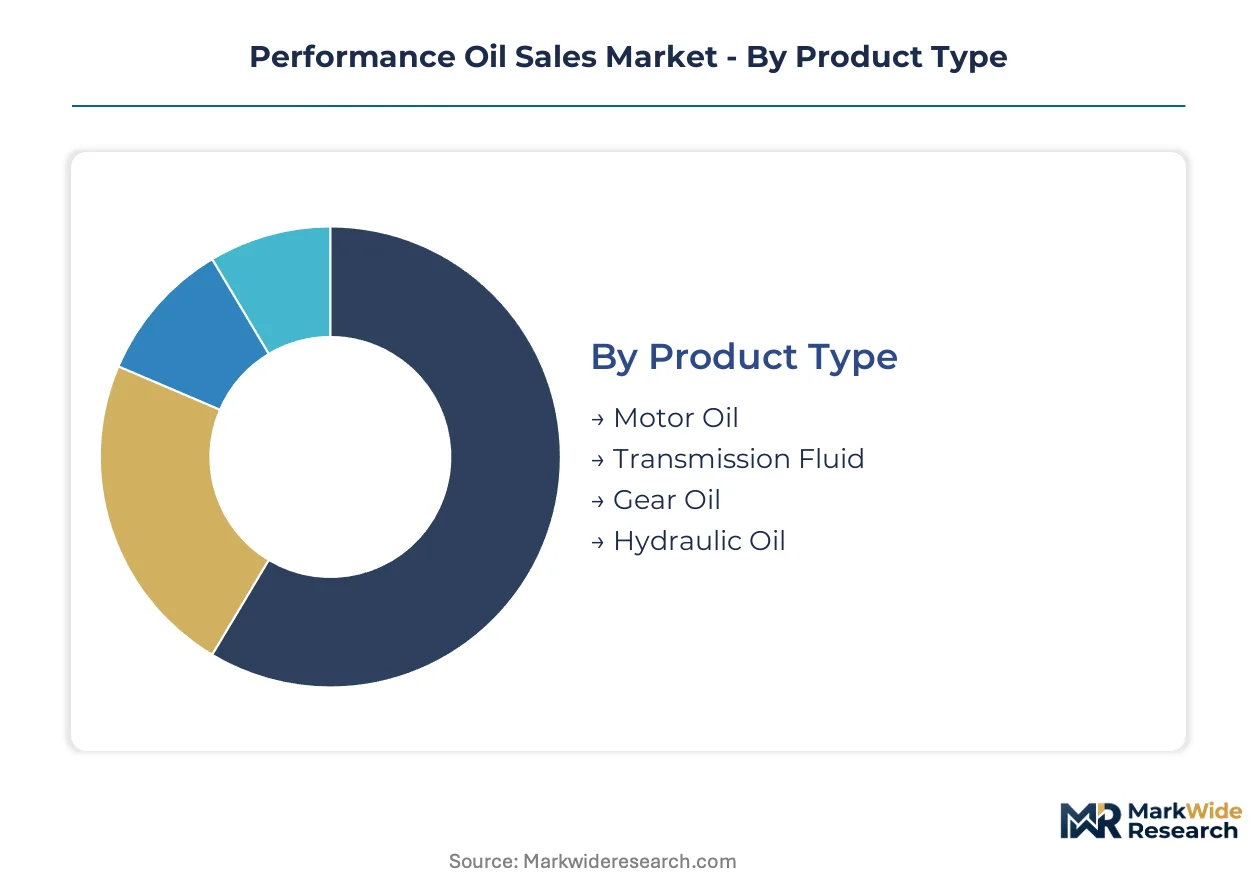
Performance oil segmentation reveals divergent capital requirements across formulation complexity, application engineering, and channel infrastructure. Understanding these structural differences exposes where margin concentrates and where volume scales.
Product Type:
Group III and Group IV base stock refining demands the heaviest upfront investment, with synthetic production facilities requiring integrated hydrocracking and isomerization units that mineral oil refineries bypass.
- Motor Oil:Formulated with viscosity modifiers and detergent-dispersant packages to meet ILSAC and API service categories. Demand concentrates in passenger car service fill across Germany and Japan as automakers pursue EPA fuel economy credits through lower-viscosity synthetics. Drain-interval extension mandates are compressing reformulation cycles toward 0W-16 and 0W-20 grades.
- Hydraulic Oil:Engineered with anti-wear zinc additives and oxidation inhibitors for high-pressure circulation systems. China's industrial corridor in Shandong and Liaoning provinces anchors demand for high-viscosity grades serving construction equipment and wind turbine installations where equipment uptime penalties elevate specification stringency.
- Transmission Fluid:Specialized friction modifiers enable clutch pack engagement in automatic transmissions. OEM fill specifications from Japanese and German automakers dominate procurement volumes.
- Gear Oil:Extreme-pressure sulfur-phosphorus chemistries protect hypoid gear sets in commercial vehicle axles. Mining and heavy-duty trucking fleets in North America drive specification evolution toward extended-drain synthetic formulations.
Motor oil absorbs the bulk of installed capacity; hydraulic oil is expanding most quickly.
Application:
Commercial vehicle procurement operates on the longest contract horizons and tightest total cost of ownership metrics, locking blenders into multi-year supply agreements with oil analysis services bundled into per-mile pricing.
- Commercial Vehicles:Class 8 trucking and freight forwarding fleets in Germany and North America are consolidating spot purchases into centralized procurement with telemetry-linked fluid monitoring. EPA emissions rules and EU Green Deal carbon targets mandate lower-viscosity lubricants that reduce parasitic friction losses across long-haul duty cycles.
- Industrial Machinery:German machine tool builders and Italian packaging machinery manufacturers validate lubricant chemistries against legacy elastomer seal inventories as REACH authorization forces zinc additive substitution toward boron and molybdenum alternatives. Equipment uptime penalties in continuous-process industries elevate specification stringency beyond automotive applications.
- Passenger Cars:OEM service fill specifications from Japanese and German automakers dominate synthetic motor oil offtake. Quick-lube service bay penetration in North America sustains retail visibility for national brands.
- Small Engines:Two-stroke and four-stroke power equipment in forestry and marine applications face mandatory environmental classification in Sweden, Norway, and Finland, redirecting demand toward biodegradable vegetable-oil and synthetic-ester formulations.
Commercial vehicles command the steepest contract values; industrial machinery delivers the highest per-unit margins.
End User:
Fleet operators are consolidating procurement authority away from decentralized maintenance yards, forcing distributors to restructure around annual volume agreements rather than spot sales.
- Fleet Operators:North American Class 8 trucking operators and German freight forwarders are displacing traditional jobber relationships with direct manufacturer agreements. Oil condition monitoring services bundled into per-operating-hour pricing reshape supplier selection criteria toward predictive maintenance capabilities.
- Automotive Manufacturers:Factory fill specifications from German and Japanese OEMs anchor synthetic base stock demand. Co-branding agreements with lubricant suppliers create switching costs that extend across vehicle model generations.
- Repair Shops:Independent service garages in North America rely on distributor networks for drum and tote packaging formats, though capital expenditure requirements for intermediate bulk container infrastructure slow conversion from legacy handling systems.
- DIY Consumers:Retail outlet penetration sustains brand visibility for national marketers, with synthetic motor oil premiumization offsetting volume compression from extended drain intervals.
Fleet operators are gaining share fastest in value terms; automotive manufacturers anchor volume stability through OEM fill contracts.
Distribution Channel:
Direct sales relationships require the most substantial working capital commitment, with inventory financing and technical service staff deployed at customer sites.
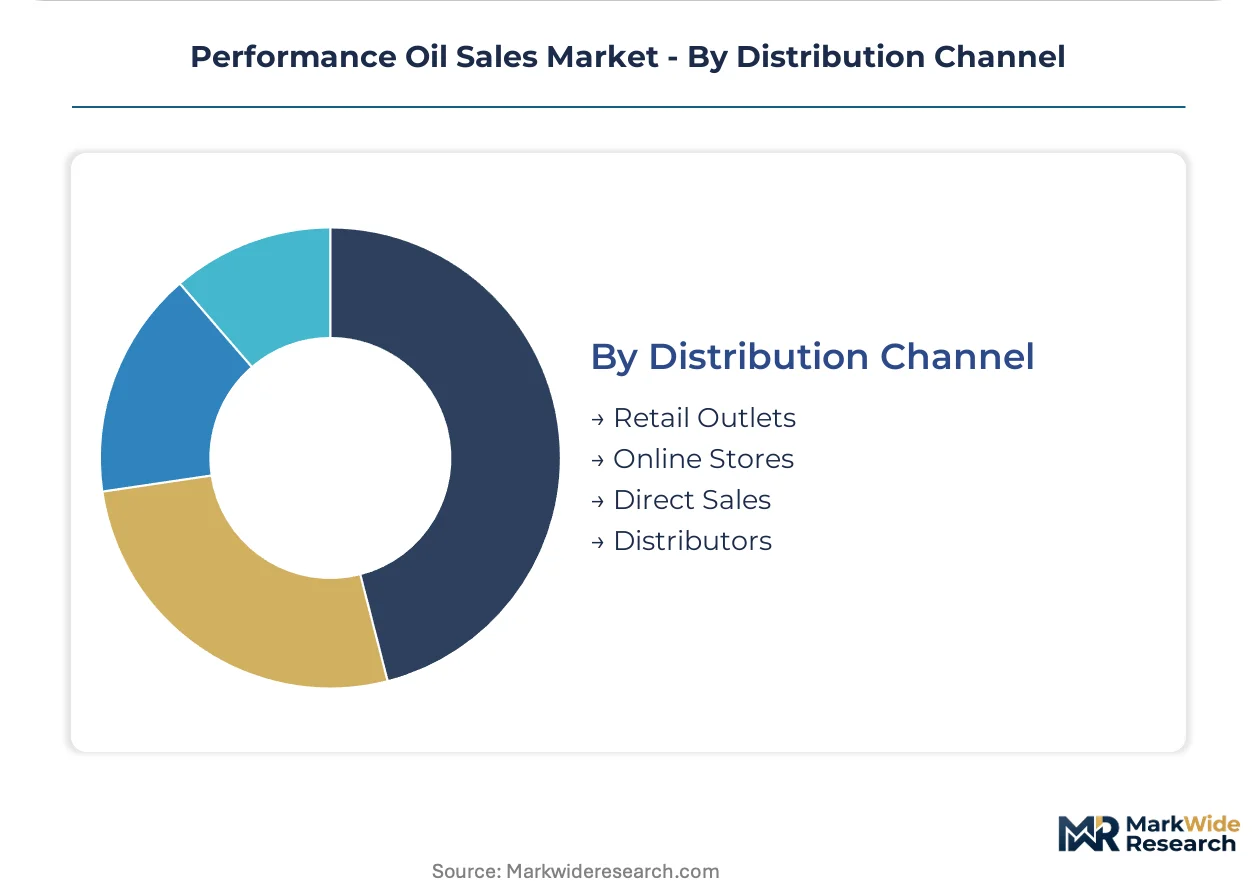
- Direct Sales:Manufacturer representatives negotiate multi-year volume contracts with fleet procurement departments and automotive OEMs, embedding oil analysis laboratories and predictive maintenance software into service level agreements. Technical service engineers validate formulation compatibility against customer equipment specifications.
- Distributors:Regional jobbers manage last-mile logistics to repair shops and small fleet accounts, though California CARB fragmentation forces dual inventory maintenance for West Coast operations. Working capital requirements elevate with packaging format transitions from drums to totes and intermediate bulk containers.
- Retail Outlets:Mass merchandisers and auto parts chains sustain consumer brand visibility through shelf space allocation and promotional programming. Quick-lube service bay penetration in North America creates pull-through demand for packaged motor oil.
- Online Stores:E-commerce platforms capture DIY consumer and small commercial accounts with bulk pricing transparency, though hazardous material shipping regulations constrain geographic reach for certain additive packages.
Direct sales commands the highest customer lifetime values; online stores are climbing the fastest as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong Province's petrochemical special economic zone concentrates China's synthetic base stock capacity, drawing blenders toward captive supply chains. Germany's Ruhr industrial corridor anchors European formulation expertise. The United States Gulf Coast refinery complex controls Group II/II+ feedstock flows.
China
Shandong and Liaoning provinces host Sinopec and PetroChina integrated refining complexes producing high-viscosity hydraulic fluids for wind turbine installations. The MEE enforces national discharge standards redirecting state-owned procurement toward biodegradable formulations. Construction equipment manufacturers in Jinan cluster demand specification-grade lubricants.
Germany
Ruhr Valley additive houses supply ashless dispersant chemistry to European blenders facing REACH authorization deadlines. The EU F-Gas Regulation mandates polyolester compressor lubricants for mobile air conditioning systems. Bavarian automotive OEMs specify 0W-16 synthetic service fill for Corporate Average Fuel Economy compliance.
United States
Louisiana crackers supply polyalphaolefin feedstocks to synthetic motor oil blenders serving Class 8 trucking fleets. EPA fuel economy rules compress reformulation cycles toward lower-viscosity grades. California CARB fragmentation forces West Coast distributors into dual inventory maintenance.
Japan
Kanto region automakers anchor OEM fill specifications for Group III and Group IV synthetic motor oils. METI efficiency standards accelerate drain-interval extension mandates. Nagoya industrial machinery builders validate zinc additive substitutions against legacy seal inventories.
Sweden
Forestry equipment operators in Norrland face mandatory environmental classification for biodegradable hydraulic fluids. National regulators enforce aquatic toxicity standards exceeding EU baseline requirements. Marine operators in Gothenburg adopt vegetable-oil and synthetic-ester chemistries.
Performance Oil Sales Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation tiers. Integrated energy majors leverage captive base oil refining to control feedstock costs. Independent additive houses concentrate formulation expertise in detergent-dispersant chemistry. The competitive arena rewards backward integration into synthetic base stock production and strategic partnerships with automotive OEMs for co-branding agreements.
Among integrated energy majors, Shell and ExxonMobil exemplify scale-driven positioning through captive supply networks. Castrol Limited occupies a specialist tier alongside Valvoline, representing formulation-focused archetypes that compete through OEM relationship depth rather than feedstock control. PetroChina and Sinopec anchor state-backed vertical structures serving domestic industrial corridors.
| Leading Market Players |
|---|
| Shell |
| ExxonMobil |
| Chevron Corporation |
| BP |
| Total |
| PetroChina |
| Sinopec |
| Valvoline |
| Castrol Limited |
| Others |
Pricing and Supply Chain Analysis
Captive base oil refining at Louisiana crackers and Shandong petrochemical zones anchors supply positions and pricing power for synthetic motor oil blenders serving EPA-regulated fleets and China's state-owned industrial procurement. This integration pattern insulates integrated majors from Group II margin compression while trapping independent blenders between fixed additive costs and falling mineral feedstock realizations.
Pricing Analysis
Short lead-time premiums command pricing power as unplanned PAO outages at Belgian crackers force emergency procurement at spot premiums above contract baselines. Three-tier pricing structure across premium synthetic, standard mineral, and economy re-refined levels differentiates by ISO certification grade and drain-interval performance. Cost compression in mineral product lines is intensifying because Middle East refinery expansion has flooded Group II/II+ supply. Fleet procurement departments show least price sensitivity due to uptime penalties, while independent repair shops face acute margin pressure from tote-conversion capital requirements.
Supply Chain Analysis
Polyalphaolefin feedstock rests on four producers controlling roughly three-quarters of global capacity concentrated in Louisiana and Belgium. Synthetic ester inputs draw from German Ruhr Valley specialty chemical houses, while zinc additive packages hinge on ashless dispersant chemistry from retiring specialist cohorts. Single-source vulnerability at PAO crackers creates outage risk that cascades through synthetic motor oil formulation. Distribution runs through direct manufacturer agreements with fleet procurement departments, displacing traditional jobber relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from EPA and EU regulatory divergence is forcing weaker blenders toward exit or acquisition as compliance fragmentation elevates working capital burdens beyond independent balance sheet capacity.
For Market Incumbents: To counter additive chemist shortage concentration among retiring specialists at major houses, secure captive supply through backward integration into base oil refining or long-term offtake agreements with Shandong and Louisiana producers. Deepen OEM co-branding agreements with German and Japanese automakers to create switching costs across vehicle model generations. For New Entrants and Emerging Players: Capture biodegradable hydraulic fluid formulation windows in Sweden, Norway, and Finland where mandatory environmental classification for forestry equipment exceeds EU baseline requirements. Enter through vegetable-oil and synthetic-ester chemistry specialization, bypassing saturated mineral motor oil channels. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of independent blenders with stranded mineral product portfolios and established fleet relationships. Five-to-ten year viability favors targets with re-refined base oil capabilities aligned to China's MEE discharge standards. Watch for ILSAC GF-7 certification backlog resolution as inflection signal for synthetic formulation capacity utilization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Refining | Captive supply of Group III and IV feedstocks insulates margin from Middle East oversupply. |
| Long-term Fleet Service Contracts | Telemetry-linked fluid monitoring locks in Class 8 trucking procurement across North America. |
| Biodegradable Formulation Certification | Aquatic toxicity compliance opens Nordic forestry and marine equipment procurement channels. |
| OEM Co-branding Agreement Expansion | German and Japanese automaker specifications create multi-generational switching costs. |
| Re-refined Base Oil Capacity Investment | Circular-economy alignment captures California municipal fleet mandates and China's MEE procurement. |
Research Methodology
Document review covered SEC 10-K filings from integrated energy majors, customs and trade flow data from Shandong and Louisiana petrochemical zones, and EPA fuel economy regulatory filings, complemented by interviews with fleet procurement directors at North American Class 8 operators, German automotive OEM lubricant specification engineers, and additive house formulation chemists. Bottom-up triangulation against top-down base oil production capacity data validated volume estimates.
Segment-level outputs across the projection horizon reflect modeled interactions between motor oil grade tier, end-use application, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating drain-interval extension mandates and synthetic substitution rates. Forecast inputs included PAO capacity utilization at Louisiana crackers and REACH authorization timelines for zinc additive alternatives.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to unplanned PAO cracker outages, California CARB-EPA regulatory divergence, and additive chemist retirement cohorts. A small set of triggers—including ILSAC GF-7 certification resolution and China's MEE enforcement intensity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Refined Petroleum Products Market
Petroleum Products
Uganda Petroleum Products Market
Petroleum Products
North America Natural Gas Liquids Market
Petroleum Products
Petroleum Liquid Feedstock Naphtha and Gas Oil Sales Market
Petroleum Products
Spindle Oil Market
Petroleum Products
Paraffin Oil Market
Petroleum Products
Oil Shale Market
Petroleum Products
Ultra Low Sulphur Fuel Oil (ULSFO) Market
Petroleum Products
Petcoke Market
Petroleum Products
Quenching Oil Market
Petroleum Products
East Africa Refined Petroleum Products Market
Petroleum Products
Gasoline-Naphtha-Crude-MTBE Market
Petroleum Products
Crude Oil Pour Point Depressant Market
Petroleum Products
Germany Refined Petroleum Products Market
Petroleum Products
South Africa Petroleum Market
Petroleum Products
Very Low Sulphur Fuel Oil (VLSFO) Market