
 PAG Base Oil Market | 2026-2036
PAG Base Oil Market Size, Share, and Industry Trends Forecast 2026-2036
PAG Base Oil Market Outlook
China is narrowing its supply deficit through domestic polyalkylene glycol capacity additions near Shanghai and Ningbo. Exxon Mobil Corporation leverages integrated olefin feedstock positions to control cost curves across Group IV PAG grades. BASF SE anchors European supply through Ludwigshafen-based alkoxylation assets purpose-built for synthetic lubricant precursors. Idemitsu Kosan Co., Ltd. competes on polyol ester-PAG blends targeting Japanese automotive thermal fluid specifications.
Polyalkylene glycol base oil comprises oxyalkylene polymers synthesized via controlled alkoxylation of starter alcohols, yielding products with viscosity indices exceeding 180 and pour points below minus forty degrees Celsius for extreme-temperature lubrication. These synthetic fluids serve primarily where mineral oils fail thermally, in compressor, gear, and metalworking systems. Group IV PAG formulations command margin premiums in automotive thermal management applications where dielectric stability and low conductivity matter. Industrial metalworking fluids represent the fastest-growing application segment as manufacturers phase out chlorinated paraffins under chemical safety mandates. Marine lubricant demand for PAG grades remains concentrated in stern tube and thruster applications where biodegradability regulations restrict mineral oil discharge.
EPA Significant New Alternatives Policy program evaluates PAG refrigerant lubricants for lower global warming potential HVAC systems, directly shaping R&D priorities among U.S. formulators. REACH substance restrictions and EU F-Gas Regulation phase-down schedules accelerate PAG adoption in compressor oils compatible with hydrofluoroolefin refrigerants. OEMs and aftermarket providers must monitor evolving OEM factory fill specifications and refrigerant-lubricant compatibility protocols to secure formulation approvals ahead of regulatory deadlines.
Market Dynamics
The PAG base oil market is being fundamentally restructured by the EU F-Gas Regulation phase-down, which mandates hydrofluoroolefin refrigerant compatibility and forces compressor oil reformulation across European HVAC and industrial cooling systems.
Growth Catalysts
- REACH substance restrictions:Chlorinated paraffin bans in metalworking fluids create immediate substitution demand for biodegradable PAG synthetics in German precision manufacturing corridors.
- Electric vehicle thermal management:Automotive OEMs specify Group IV PAG grades for battery cooling loops where dielectric stability and low conductivity prevent thermal runaway.
- Shanghai-Ningbo capacity expansion:Domestic Chinese alkoxylation assets reduce import dependency and lower landed costs for Asia-Pacific compressor manufacturers.
Market Restraints
- Ethylene oxide feedstock volatility:PAG production costs track ethylene oxide spot markets, exposing margins to petrochemical cycle swings without long-term offtake agreements.
- Ludwigshafen supply concentration:European PAG supply chains depend heavily on single-site alkoxylation assets, creating geographic vulnerability to energy disruption or force majeure events.
- Polyol ester substitution threat:Japanese automotive specifications increasingly favor ester-PAG blends for higher temperature stability, compressing pure PAG volumes in thermal fluid applications.
Strategic Opportunities
- Marine stern tube lubricants:Biodegradability mandates under MARPOL regulations open PAG penetration in commercial shipping where mineral oil discharge faces port-state restrictions.
- EPA SNAP program alignment:U.S. HVAC formulators pursuing lower-GWP refrigerant approvals need PAG lubricant validation, creating first-mover advantage for pre-qualified suppliers.
- Metalworking fluid convergence:Precision machining centers in South Korea and Taiwan adopt PAG-based minimum quantity lubrication systems that combine cooling and tool life extension.
Industry Challenges
- Refrigerant-lubricant compatibility testing:OEM factory fill specifications require extensive protocol validation, extending qualification timelines to 18-24 months and freezing supplier switches.
- Alkoxylation technician scarcity:Controlled polymerization expertise concentrates among aging workforces in German and U.S. Gulf Coast chemical clusters, constraining capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PAG Base Oil Market |
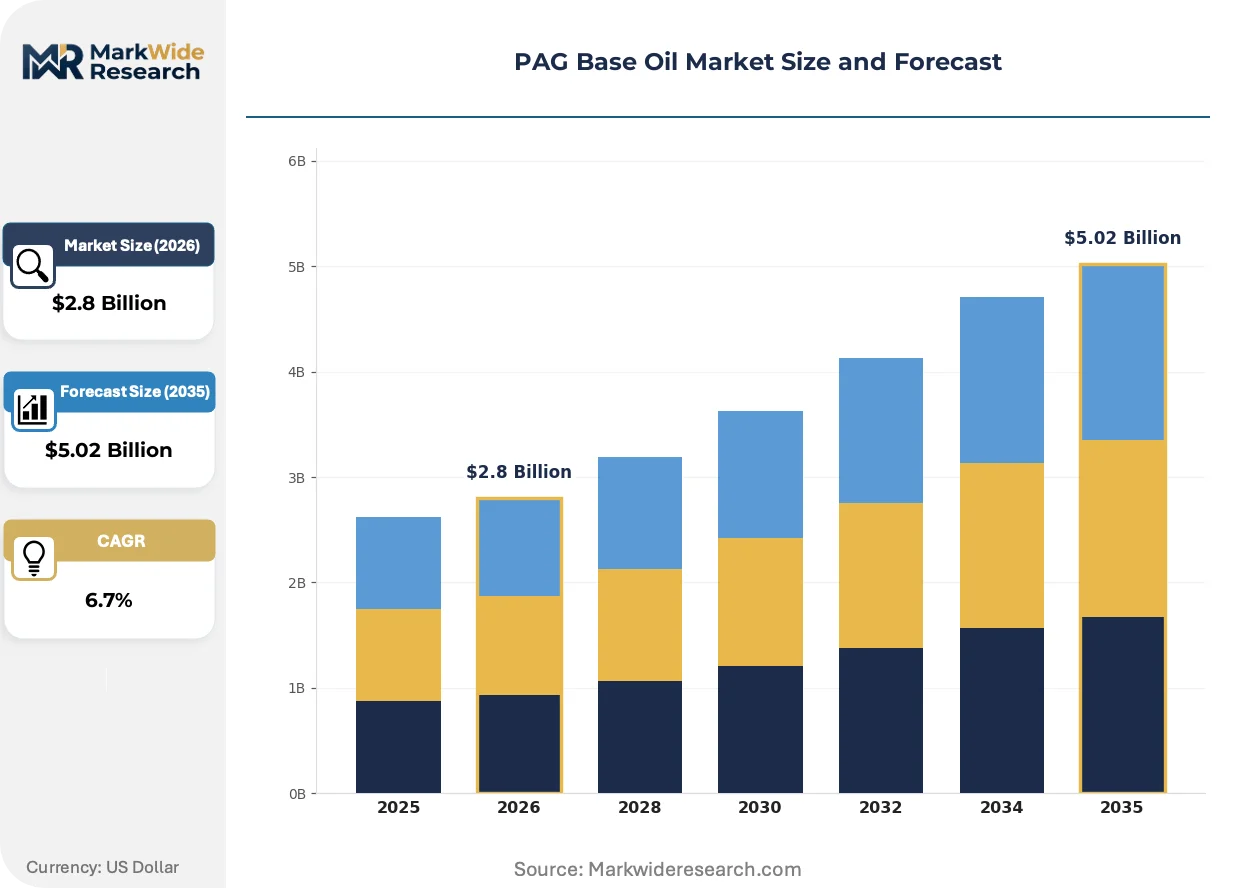
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Group I, Group II, Group III, Group IV Application: Automotive, Industrial, Marine, Metalworking End User: Manufacturers, Distributors, OEMs, Aftermarket Providers Distribution Channel: Direct Sales, Retail, Online, Third-Party Logistics |
| Companies Covered | Phillips 66 Company, Exxon Mobil Corporation, Total Energies, Royal Dutch Shell plc, BASF SE, Idemitsu Kosan Co., Ltd., Dow Chemical Company, Chevron Corporation, The Lubrizol Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PAG Base Oil Market Strategic Shifts
Refrigerant chemistry transformation and electric vehicle thermal architecture redesign are compressing traditional lubricant qualification cycles and demanding faster formulation-to-approval pipelines.
Water-soluble PAG variants with tailored cloud points are rendering obsolete mineral oil-based compressor lubricants in flooded screw and reciprocating systems. HVAC OEMs in Germany and Japan are fast-tracking factory fill approvals for these grades. The shift compresses aftermarket service intervals and redirects maintenance revenue toward synthetic fluid suppliers.
The EU F-Gas Regulation mandates 79% hydrofluorocarbon phase-down by 2030, forcing compressor oil compatibility with hydrofluoroolefin refrigerants like R-1234yf and R-513A. European equipment manufacturers are redesigning seal materials and lubricant viscosities simultaneously. This regulatory pressure concentrates R&D investment in low-molecular-weight PAG grades with enhanced refrigerant miscibility.
Automotive thermal fluid procurement is consolidating around dielectric property specifications rather than viscosity grades alone. Tier-1 suppliers in South Korea now require certified low-conductivity PAG batches with batch-level test documentation. This behavioral shift elevates quality assurance costs but locks in multi-year supply agreements with qualified synthetic base oil producers.
PAG Base Oil Market Segmentation
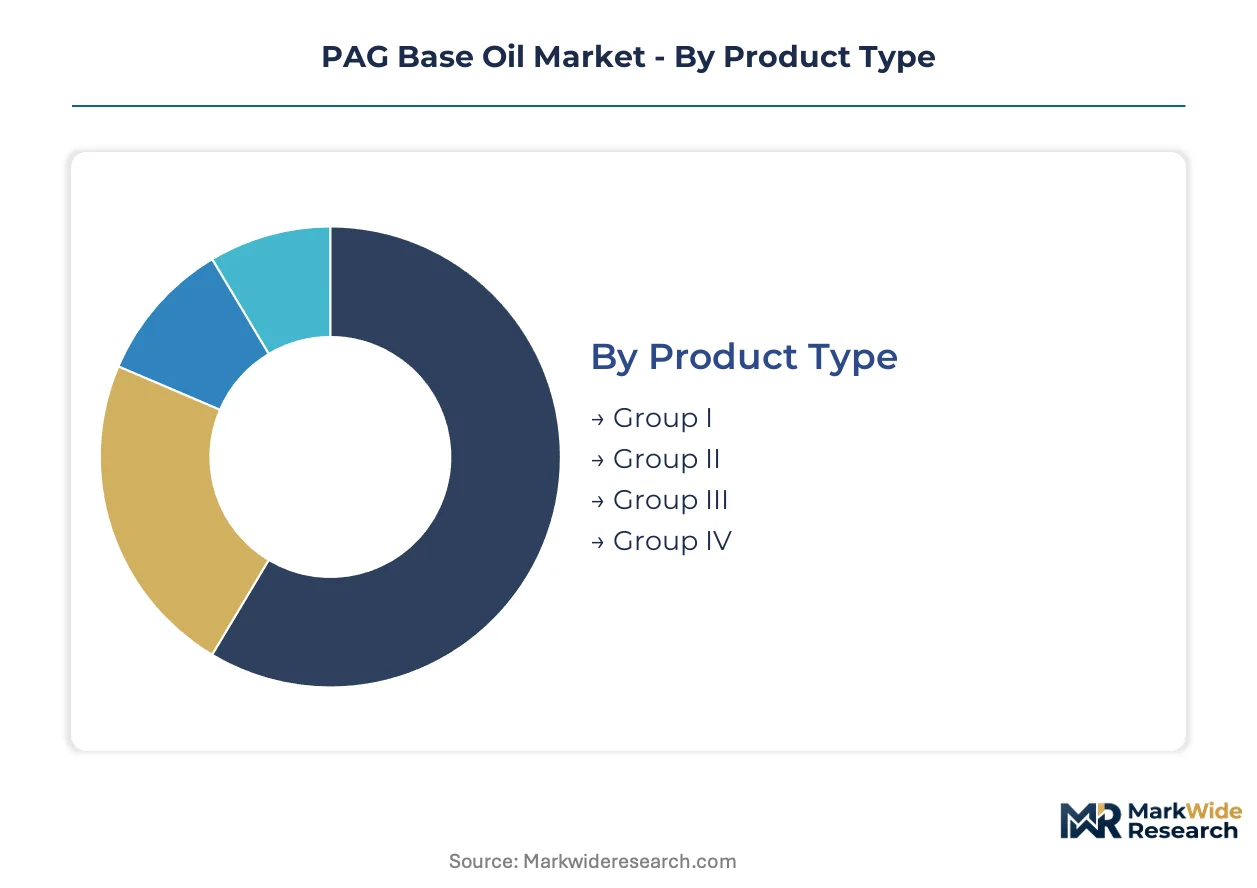
PAG base oil procurement patterns diverge sharply across product grades and end-use channels, with Group IV formulations commanding technical validation cycles that stretch 18-24 months while commodity grades turn faster. Channel selection directly determines margin capture, as direct sales to OEMs lock in multi-year thermal fluid specifications that aftermarket distributors cannot easily replicate.
Product Type:
After-sales service intensity escalates from mineral-equivalent Group I grades through fully synthetic Group IV formulations, with technical support obligations tracking inversely with product standardization.
- Group IV:Fully synthetic polyalkylene glycol polymers synthesized via controlled alkoxylation deliver viscosity indices exceeding 180 and dielectric stability critical for electric vehicle battery cooling loops. German automotive OEMs now mandate batch-level conductivity certification for thermal management fluids, embedding Group IV suppliers into vehicle platform development cycles. By volume, Group II leads. By growth pace, Group IV is ahead.
- Group III:Severely hydrocracked mineral oils with synthetic performance characteristics occupy the cost-performance midpoint for industrial compressor applications where HFO refrigerant compatibility is required but dielectric properties are secondary. Shanghai-based alkoxylation capacity expansions are compressing import premiums for Asia-Pacific HVAC manufacturers seeking F-Gas Regulation compliance without full synthetic pricing.
- Group II:Hydrocracked and hydrotreated base stocks serve price-sensitive metalworking fluid formulations where REACH chlorinated paraffin bans drive substitution demand without requiring extreme-temperature performance.
- Group I:Solvent-refined mineral base stocks retain residual demand in legacy marine stern tube applications where MARPOL biodegradability mandates have not yet fully displaced mineral oil formulations.
Margin structures compress toward Group I and expand toward Group IV, with technical service bundling capturing value that commodity pricing cannot sustain.
Application:
Application segmentation maps directly onto regulatory trigger points, with each end-use carrying distinct compliance timelines that reshape procurement urgency and supplier qualification depth.
- Metalworking:Precision machining centers in South Korea and Taiwan are adopting PAG-based minimum quantity lubrication systems that combine cooling performance with tool life extension under REACH substance restrictions. Chlorinated paraffin phase-outs in German manufacturing corridors are accelerating substitution timelines for biodegradable synthetics in high-speed cutting operations.
- Automotive:Battery electric vehicle thermal architectures specify low-conductivity PAG grades where dielectric stability prevents thermal runaway, with South Korean Tier-1 suppliers requiring certified batch documentation. OEM factory fill specifications now prioritize conductivity metrics over viscosity grades alone, elongating qualification protocols.
- Industrial:Flooded screw and reciprocating compressor systems are transitioning to water-soluble PAG variants with tailored cloud points, displacing mineral oil lubricants in HVAC applications subject to EU F-Gas Regulation phase-down schedules.
- Marine:Stern tube and thruster lubricant demand concentrates where MARPOL biodegradability regulations restrict mineral oil discharge, with port-state enforcement in Northern European shipping lanes driving specification changes.
Automotive applications command the steepest technical barriers. Metalworking fluids are climbing fastest as chemical safety mandates compress substitution timelines.
End User:
End user type determines contract structure durability, with OEM engagements locking in formulation approvals that aftermarket providers cannot displace without redesigning entire thermal systems.
- OEMs:Automotive and HVAC original equipment manufacturers specify factory fill PAG grades through 18-24 month validation protocols, freezing supplier switches and embedding base oil producers into platform development cycles. Exxon Mobil and BASF leverage these relationships to defend position against commodity challengers.
- Aftermarket Providers:Service networks and independent distributors capture maintenance-interval revenue as synthetic fluid lifetimes compress replacement cycles, though they lack influence over initial specification decisions.
- Manufacturers:Industrial lubricant blenders and compounders procure base stocks for reformulation under private labels, with Ludwigshafen-based supply concentration creating geographic vulnerability to energy disruption.
- Distributors:Bulk and packaged fluid distributors manage inventory across fragmented industrial end-users, with ethylene oxide feedstock volatility exposing margins to petrochemical cycle swings without long-term offtake agreements.
OEMs anchor volume commitments through multi-year agreements. Aftermarket providers are expanding most quickly as installed synthetic bases widen service revenue pools.
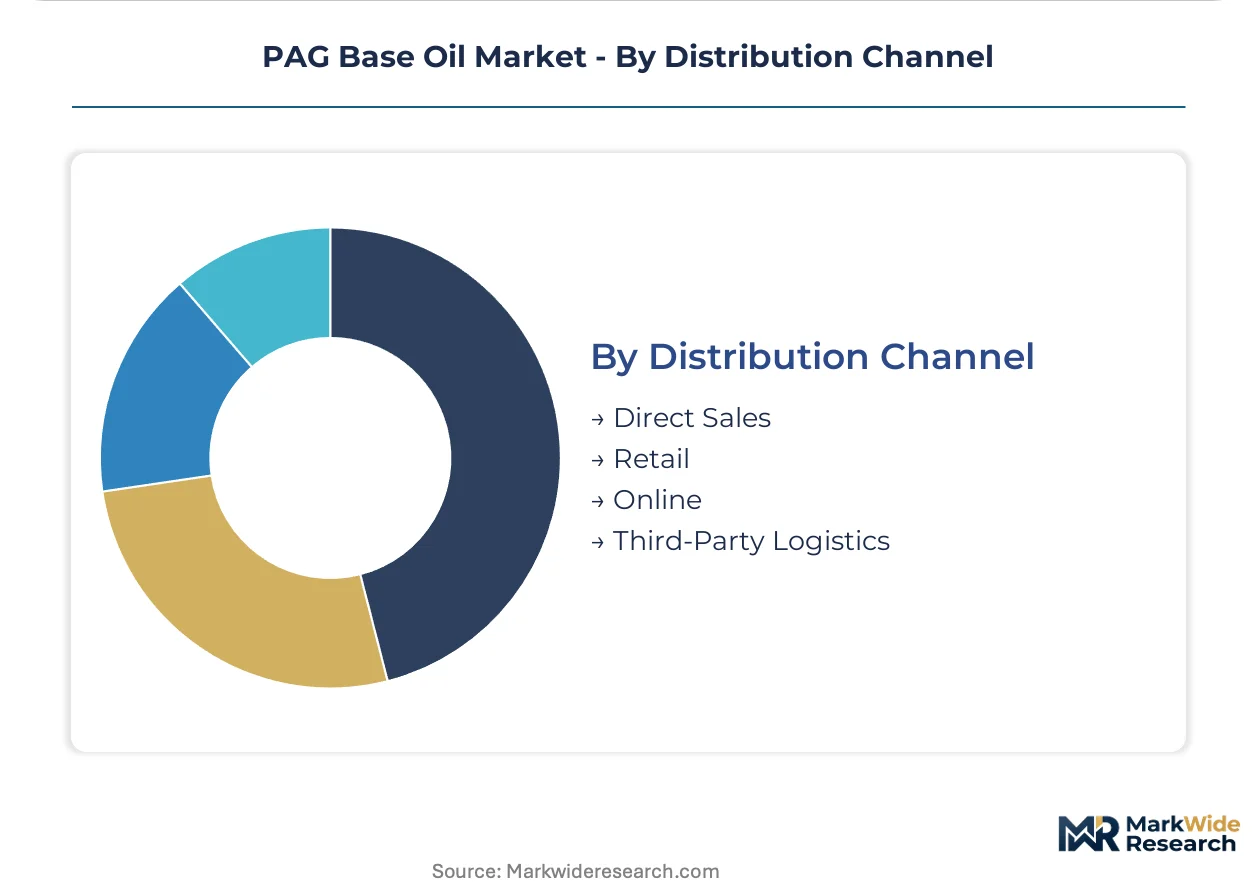
Distribution Channel:
Channel selection reflects customer scale and technical support requirements, with direct sales capturing specification influence that arm's-length channels cannot replicate.
- Direct Sales:Integrated base oil producers maintain dedicated technical service teams for OEM and large industrial accounts, embedding alkoxylation expertise into customer formulation development. This channel captures margin premiums unavailable through intermediaries.
- Third-Party Logistics:Specialized chemical distributors manage inventory and delivery for mid-scale industrial consumers, consolidating fragmented demand across metalworking and compressor applications.
- Retail:Packaged lubricant sales through industrial supply houses serve small-scale maintenance operations with standardized grades, carrying lower technical support obligations.
- Online:E-procurement platforms are emerging for commodity-grade PAG formulations where specifications are standardized and technical consultation requirements are minimal.
Direct sales dominate value capture. Online channels are gaining share fastest in standardized industrial grades where qualification barriers are lowest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH substance restrictions under ECHA jurisdiction anchor European demand dynamics, with Ludwigshafen-based alkoxylation assets serving as the continent's primary supply node for synthetic lubricant precursors.
Germany
Precision metalworking corridors in Baden-Württemberg and Bavaria drive chlorinated paraffin substitution demand under REACH Annex XVII restrictions. The EU F-Gas Regulation mandates hydrofluoroolefin refrigerant compatibility, forcing compressor oil reformulation across industrial cooling systems. BASF SE's Ludwigshafen complex anchors continental supply for Group IV PAG grades.
United States
EPA SNAP program evaluations shape R&D priorities for lower-GWP refrigerant lubricants among HVAC formulators. The Significant New Alternatives Policy creates first-mover advantage for pre-qualified PAG suppliers in commercial cooling applications. Gulf Coast petrochemical clusters concentrate controlled alkoxylation expertise, though aging workforces constrain capacity expansion timelines.
China
Domestic alkoxylation capacity additions near Shanghai and Ningbo narrow supply deficits for Asia-Pacific compressor manufacturers. MIIT industrial upgrading directives accelerate synthetic lubricant adoption in precision manufacturing. Yangtze River Delta metalworking centers adopt PAG-based minimum quantity lubrication systems under tightening environmental enforcement.
Japan
Automotive thermal fluid specifications increasingly favor polyol ester-PAG blends for higher temperature stability in battery electric vehicles. METI carbon neutrality roadmaps push OEMs toward low-conductivity dielectric fluids. Kansai-based Tier-1 suppliers now require certified batch documentation for thermal management procurement.
South Korea
Precision machining centers in Gyeonggi and Busan-Ulsan industrial belts adopt PAG metalworking fluids under REACH-equivalent chemical safety mandates. MFDS regulatory alignment with EU substance restrictions compresses substitution timelines for biodegradable synthetics. Seoul Capital Area battery manufacturers specify Group IV PAG grades for cooling loop dielectric stability.
PAG Base Oil Market Competitive Environment
Integrated petrochemical majors and specialized synthetic lubricant producers split the market between feedstock-integrated scale and formulation-specific technical service. The vendor base concentrates around alkoxylation asset ownership, with European supply chains exhibiting particular geographic vulnerability to single-site dependencies. Three archetypes dominate: olefin-integrated oil majors, alkoxylation-specialty chemical houses, and regional lubricant compounders. Competitive moves center on backward integration into ethylene oxide feedstocks and captive supply agreements with OEM thermal system designers.
Among integrated oil majors, Exxon Mobil Corporation and Chevron Corporation occupy positions defined by Gulf Coast olefin infrastructure and long-term offtake relationships with automotive OEMs. BASF SE anchors the specialty chemical archetype through Ludwigshafen-based alkoxylation assets purpose-built for synthetic lubricant precursors. Idemitsu Kosan Co., Ltd. represents the regional compounder model, with Japanese market presence shaped by domestic automotive thermal fluid specifications and ester-PAG blending capabilities.
| Leading Market Players |
|---|
| Phillips 66 Company |
| Exxon Mobil Corporation |
| Total Energies |
| Royal Dutch Shell plc |
| BASF SE |
| Idemitsu Kosan Co., Ltd. |
| Dow Chemical Company |
| Chevron Corporation |
| The Lubrizol Corporation |
| Others |
Value Chain & Pricing Dynamics
Ludwigshafen-based alkoxylation assets concentrate European PAG supply in a single-site configuration that transfers margin capture downstream toward OEM factory fill specifications. Ethylene oxide feedstock volatility exposes contract pricing to petrochemical cycle swings, compressing distributor margins while insulating integrated producers with captive olefin positions.
Pricing Analysis
Geographic price spreads widen between German-engineered Group IV grades and Asia-Pacific commodity formulations as Shanghai-Ningbo capacity additions compress import premiums. Three-tier pricing structure across premium, standard, and economy levels separates dielectric-certified automotive thermal fluids from industrial compressor grades. Cost compression in Group II metalworking segments is intensifying because REACH-driven chlorinated paraffin substitution outpaces supply elasticity. Aftermarket distributors exhibit highest price sensitivity; OEM thermal system designers prioritize conductivity certification over unit cost.
Supply Chain Analysis
Extended payment terms from German automotive OEMs cascade through alkoxylation supply chains, favoring integrated majors with balance-sheet capacity over independent compounders. Production gravity centers on Germany, China, and the United States, with feedstock supply drawing from Gulf Coast ethylene oxide crackers and Middle Eastern olefin complexes. Single-source vulnerability concentrates in Ludwigshafen alkoxylation assets where force majeure would disrupt continental synthetic lubricant precursors. Distribution runs through direct technical service teams for OEM accounts and specialized chemical distributors for fragmented industrial demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PAG base oil procurement is evolving into a service-attach model where fluid lifetime monitoring and conductivity certification generate recurring revenue faster than base stock volume growth. Technical support bundling now captures margin premiums unavailable through commodity transactions.
For Market Incumbents: Pre-empt polyol ester substitution in Japanese automotive thermal specifications by accelerating dielectric property validation cycles and embedding batch-level certification into OEM platform development. Backward integration into ethylene oxide feedstocks defends margin position against Shanghai-Ningbo cost compression. Capacity discipline at Ludwigshafen preserves pricing power despite Asia-Pacific supply expansion.
For New Entrants and Emerging Players: Marine stern tube lubricants in Northern European shipping lanes offer underpenetrated white space where MARPOL biodegradability mandates displace mineral oil without entrenched synthetic supplier relationships. South Korean precision machining centers present secondary entry points through REACH-equivalent chemical safety enforcement. Go-to-market execution should prioritize direct technical service partnerships with Tier-1 thermal system designers over distributor channel builds.
For Investors and Strategic Acquirers: Capital is best deployed toward alkoxylation-specialty chemical houses with Ludwigshafen-equivalent asset configurations and existing OEM validation protocols, as these command scarcity premiums in a market where controlled polymerization expertise concentrates among aging workforces. Long-term viability hinges on refrigerant-lubricant compatibility positioning ahead of EU F-Gas Regulation phase-down completion. The signal to watch is EPA SNAP program pre-qualification status among U.S. HVAC formulators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | Captive feedstock supply insulates Exxon Mobil and Chevron from petrochemical cycle volatility. |
| Dielectric Certification Investment | Batch-level conductivity documentation locks BASF into German OEM thermal platform development cycles. |
| Marine Biodegradability Positioning | MARPOL-compliant stern tube formulations open commercial shipping channels previously closed to synthetics. |
| Alkoxylation Capacity Expansion | Shanghai-Ningbo assets reduce Chinese import dependency and compress landed costs for Asia-Pacific HVAC manufacturers. |
| Refrigerant-Lubricant Compatibility Validation | Pre-qualification under EPA SNAP program creates first-mover advantage for lower-GWP HVAC system approvals. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs and trade data, SEC 10-K filings, and European Chemicals Agency regulatory submissions. Conversations with alkoxylation plant managers, automotive OEM procurement leads, compressor OEM technical directors, and marine lubricant distributors informed demand-side validation. Top-down market sizing triangulates against bottom-up segment build-ups across Group I through Group IV grade tiers.
Forecast inputs incorporate ethylene oxide feedstock cost trajectories, EU F-Gas Regulation phase-down schedules, and electric vehicle thermal architecture adoption curves across the projection horizon. Segmentation modeling spans product grade, end-use application, and geographic production hub. CAGRs derive from elasticity-adjusted volume projections and value-per-unit trends by certification tier.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese state-backed chemical groups or accelerated polyol ester substitution by Japanese automotive OEMs would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Uganda Petroleum Products Market
Petroleum Products
Floating Roof Tank Market
Petroleum Products
Longitudinal Submerged-Arc Welded (LSAW) Pipes Market
Petroleum Products
Underground Storage Tanks Market
Petroleum Products
Petroleum Liquid Feedstock Naphtha and Gas Oil Sales Market
Petroleum Products
North Africa Refined Petroleum Products Market
Petroleum Products
Oil Refinery Market
Petroleum Products
West Africa Refined Petroleum Products Market
Petroleum Products
Liquefied Petroleum Gas Market
Petroleum Products
Asia-Pacific Lubricants Market
Petroleum Products
Gasoline-Naphtha-Crude-MTBE Market
Petroleum Products
Africa Refined Petroleum Products Market
Petroleum Products
Pygas (Pyrolysis Gasoline) Market
Petroleum Products
Ultra Low Sulphur Fuel Oil (ULSFO) Market
Petroleum Products
South Africa Petroleum Market
Petroleum Products
Petroleum Wax Market