
 Very Low Sulphur Fuel Oil (VLSFO) Market | 2026-2036
Very Low Sulphur Fuel Oil (VLSFO) Market Size, Share, and Industry Trends Forecast 2026-2036
Very Low Sulphur Fuel Oil (VLSFO) Market Insights
Buyer concentration among container shipping alliances is shifting procurement power toward a smaller set of charterers negotiating long-term offtake agreements. TotalEnergies leverages integrated refining and bunkering networks to secure terminal access across major ports. Saudi Aramco anchors supply security through crude flexibility and marine terminal investments in Asia. ExxonMobil competes on hydroprocessing technology leadership that yields consistent low-sulphur residuals.
Very Low Sulphur Fuel Oil denotes residual-based marine fuels with sulphur content capped at 0.50% mass fraction, produced through vacuum residue hydrotreating, gasoil blending, or hydrocracking of intermediate streams, serving as the primary compliant fuel for two-stroke marine diesel engines operating outside Emission Control Areas. Marine fuel dominates volume throughput across the fuel type dimension, while bunker fuel suppliers control the critical distribution channel through port-side storage and barge delivery infrastructure. Power generation fuel represents a smaller but structurally growing segment as dual-fuel utilities substitute VLSFO for higher-sulphur residuals in coastal markets.
IMO 2020 sulphur limits, the EU Sulphur Directive, and designated Emission Control Areas with 0.10% sulphur caps collectively mandate product specifications and create compliance-driven demand floors. The US EPA and China's MEE enforce parallel emission standards that restrict high-sulphur fuel oil combustion in territorial waters. Stakeholders must monitor scrubber retrofit economics, alternative fuel competition from LNG and methanol, and refinery upgrading capacity additions that alter VLSFO supply availability.
Market Dynamics
IMO 2020 sulphur caps have permanently restructured marine fuel procurement, forcing container lines to abandon high-sulphur residuals and locking in VLSFO as the default compliance pathway for international shipping.
Growth Catalysts
- Emission Control Area expansion:The EU Sulphur Directive and China's MEE enforcement extend 0.10% sulphur zones beyond coastal waters, mandating VLSFO consumption in additional port clusters.
- Container shipping alliance consolidation:Ocean carrier alliances concentrate bunker purchasing into fewer procurement desks, generating volume commitments that underwrite refinery upgrading investments.
- Hydrocracking yield improvements:Advanced vacuum residue hydrotreating enables refiners to process heavier crude slates into compliant 0.50% sulphur products without yield penalties.
Market Restraints
- Crude slate inflexibility:Refineries lacking residue upgrading capacity face stranded asset risk as high-sulphur crude differentials compress against VLSFO output requirements.
- Singapore storage concentration:Overreliance on Singapore's Jurong Island tank farm creates single-point vulnerability for Asia-Pacific bunkering logistics.
- LNG substitution threat:Dual-fuel LNG propulsion systems displace VLSFO demand in newbuild container vessels above 14,000 TEU capacity.
Strategic Opportunities
- Rotterdam-ARA hub expansion:Antwerp and Rotterdam storage operators can capture transshipment flows from Baltic and North Sea routes as ECAs tighten.
- Power generation fuel pivot:Coastal utilities in Japan and South Korea substitute VLSFO for high-sulphur residuals in peak-load thermal units.
- Digital bunkering platforms:Blockchain-anchored fuel quality verification reduces sulfur content disputes and accelerates port turnaround times.
Industry Challenges
- Marine fuel chemist scarcity:Blending operations require specialized expertise in residual stability and compatibility testing that the workforce pipeline cannot replenish.
- Barge fleet reconfiguration:Segregated tank cleaning protocols between high-sulphur and VLSFO cargoes reduce asset utilization rates and inflate operating costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Very Low Sulphur Fuel Oil (VLSFO) Market |
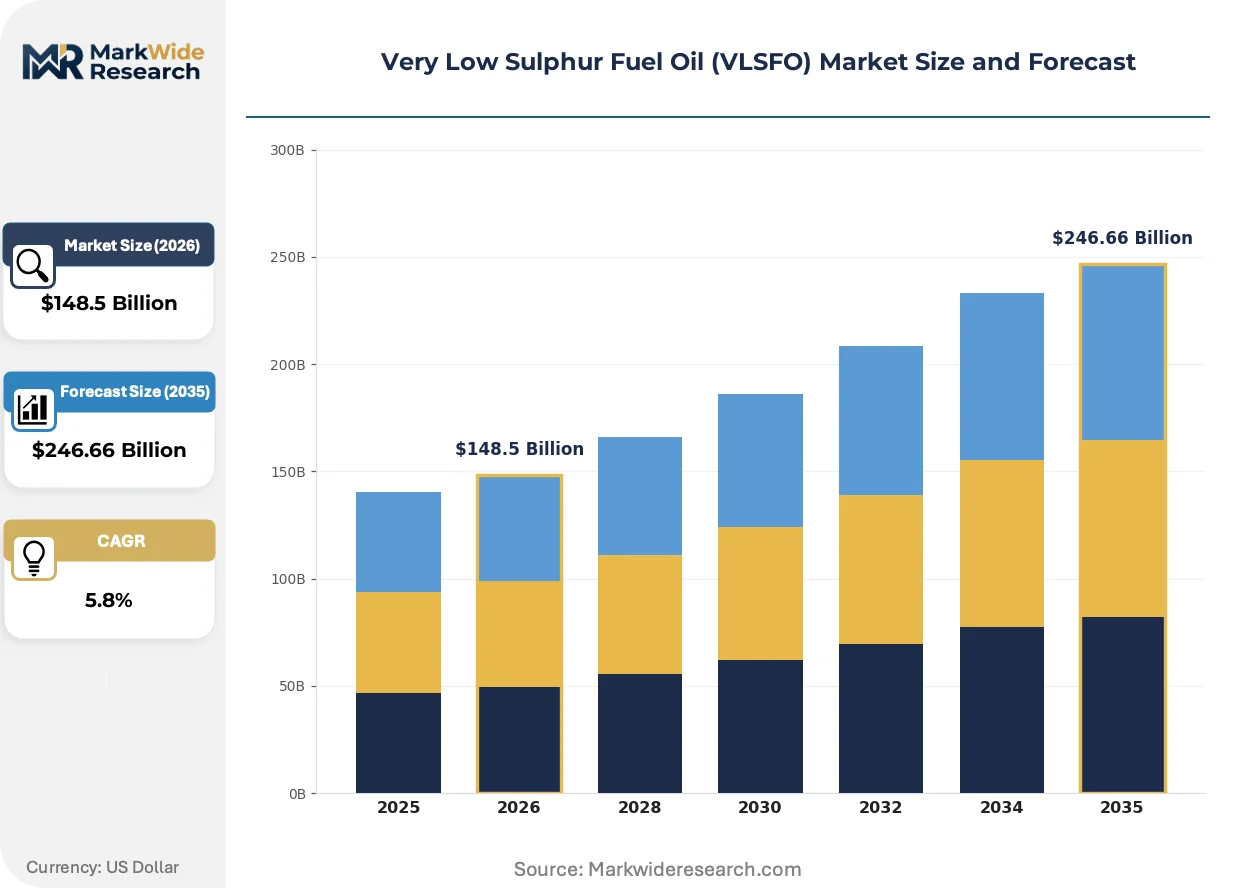
| Market Size in 2026 | $148.5 Billion |
| Market Size in 2035 | $246.66 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Marine Fuel, Industrial Fuel, Power Generation Fuel, Residential Heating Fuel Application: Shipping, Power Plants, Commercial Heating, Emergency Generators Distribution Channel: Direct Sales, Retail Sales, Bunker Fuel Suppliers, Online Platforms Regulatory Compliance: IMO 2020, EU Sulphur Directive, Environmental Regulations, Emission Control Areas |
| Companies Covered | TotalEnergies, Saudi Aramco, Royal Dutch Shell, Sinopec, Petrobras, ExxonMobil, Chevron, Hindustan Petroleum, BP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Very Low Sulphur Fuel Oil (VLSFO) Market Trends and Innovations
Refinery technology adaptation and digital supply chain instrumentation are compressing quality variance and delivery uncertainty in marine fuel markets.
Inline sulphur monitoring systems using X-ray fluorescence spectroscopy are converging with automated barge loading operations. Major bunkering terminals in Fujairah and Rotterdam deploy these sensors to certify fuel sulphur content before vessel departure. Real-time verification is compressing dispute resolution cycles and reducing laboratory testing bottlenecks at port.
REACH chemical registration requirements and the EU Green Deal's Fit for 55 package tighten marine fuel carbon intensity disclosures. Fuel suppliers must now document well-to-wake emissions alongside sulphur content. Container lines operating European trades face procurement mandates that extend beyond IMO compliance into lifecycle carbon accounting.
Long-term offtake contracting is displacing spot market purchasing among container shipping alliances. Charterers negotiate two- to three-year supply agreements directly with integrated oil companies, bypassing independent bunker traders. This pattern concentrates most visibly in Singapore-Strait of Malacca routes where alliance networks anchor their Asia-Europe rotations.
Very Low Sulphur Fuel Oil (VLSFO) Market Segmentation
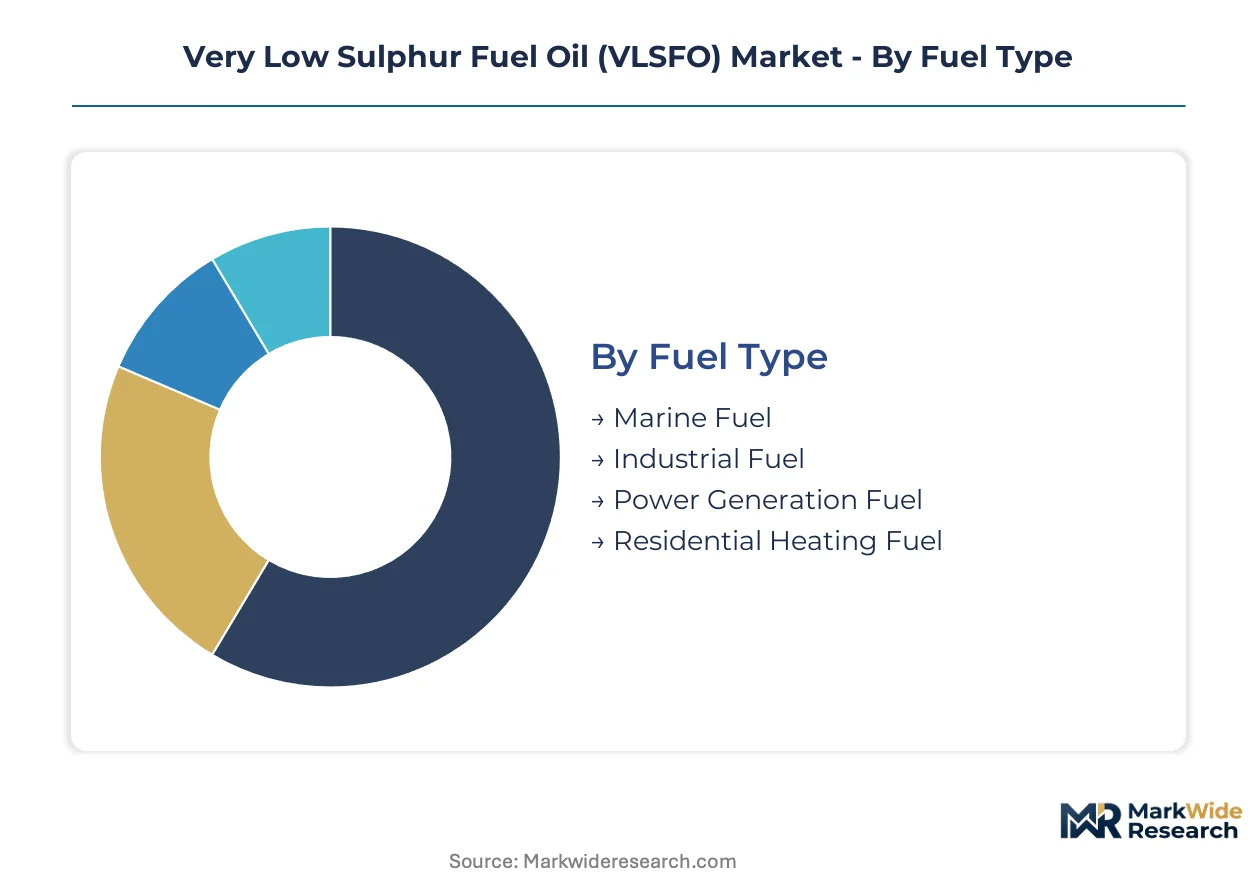
VLSFO procurement patterns diverge sharply across fuel specifications and end-use applications, with IMO 2020 compliance mandates forcing distinct upgrade cycles for marine operators versus stationary consumers. Refiners and distributors calibrate blending investments and storage configurations to match segment-specific sulphur thresholds and volume reliability requirements.
Fuel Type:
Upgrade cycles for residual fuel systems determine replacement urgency across consumer categories, with marine engines facing the most compressed compliance deadlines.
- Marine Fuel:Residual-based 0.50% sulphur formulations serve two-stroke marine diesel engines operating outside Emission Control Areas. Demand concentrates in Singapore, Rotterdam, and Fujairah bunkering hubs where container alliances anchor procurement desks under long-term offtake contracts.
- Power Generation Fuel:Dual-fuel coastal utilities in Japan and South Korea substitute VLSFO for high-sulphur residuals in peak-load thermal units. The EU Green Deal's carbon intensity disclosures are extending procurement criteria beyond sulphur content into well-to-wake emissions accounting.
- Industrial Fuel:Process heat applications in cement and chemical plants require consistent calorific value and low metals content.
- Residential Heating Fuel:Seasonal demand in Northern European markets faces competition from natural gas and heat pump electrification.
Volume placements concentrate in Marine Fuel; the faster expansion belongs to Power Generation Fuel.
Application:
Cost tier differentiation separates continuous-duty operations from intermittent backup systems, with fuel quality specifications tightening for the former.
- Shipping:Ocean carrier alliances concentrate bunker purchasing into consolidated procurement desks negotiating directly with integrated oil companies. The EU Sulphur Directive and China's MEE enforcement extend 0.10% sulphur zones beyond coastal waters, mandating additional VLSFO consumption in Baltic and North Sea routes.
- Power Plants:Baseload utilities require guaranteed supply security through storage terminal access and barge delivery infrastructure.
- Commercial Heating:District heating networks in Denmark and Sweden blend VLSFO with biomass and waste heat recovery.
- Emergency Generators:Hospital and data center backup systems prioritize fuel stability and extended storage life over unit cost.
Shipping commands the dominant volume share; Power Plants are climbing the fastest as coastal utilities retire high-sulphur residual contracts.
Distribution Channel:
Customer type segmentation separates large-volume charterers from fragmented spot purchasers, with channel selection determined by procurement scale and credit terms.
- Bunker Fuel Suppliers:Port-side storage operators and barge fleets control critical last-mile delivery infrastructure. Singapore's Jurong Island tank farm anchors Asia-Pacific logistics, though single-point vulnerability concerns are driving diversification into Antwerp and Rotterdam ARA hub expansion.
- Direct Sales:Integrated refiners negotiate multi-year supply agreements with container shipping alliances, bypassing independent traders.
- Retail Sales:Smaller industrial consumers purchase through local distributors with limited storage capacity.
- Online Platforms:Digital bunkering platforms using blockchain-anchored fuel quality verification are compressing sulfur content disputes and accelerating port turnaround times.
Bunker Fuel Suppliers handle the majority of physical volume; Online Platforms are gaining share fastest as alliance procurement digitizes.
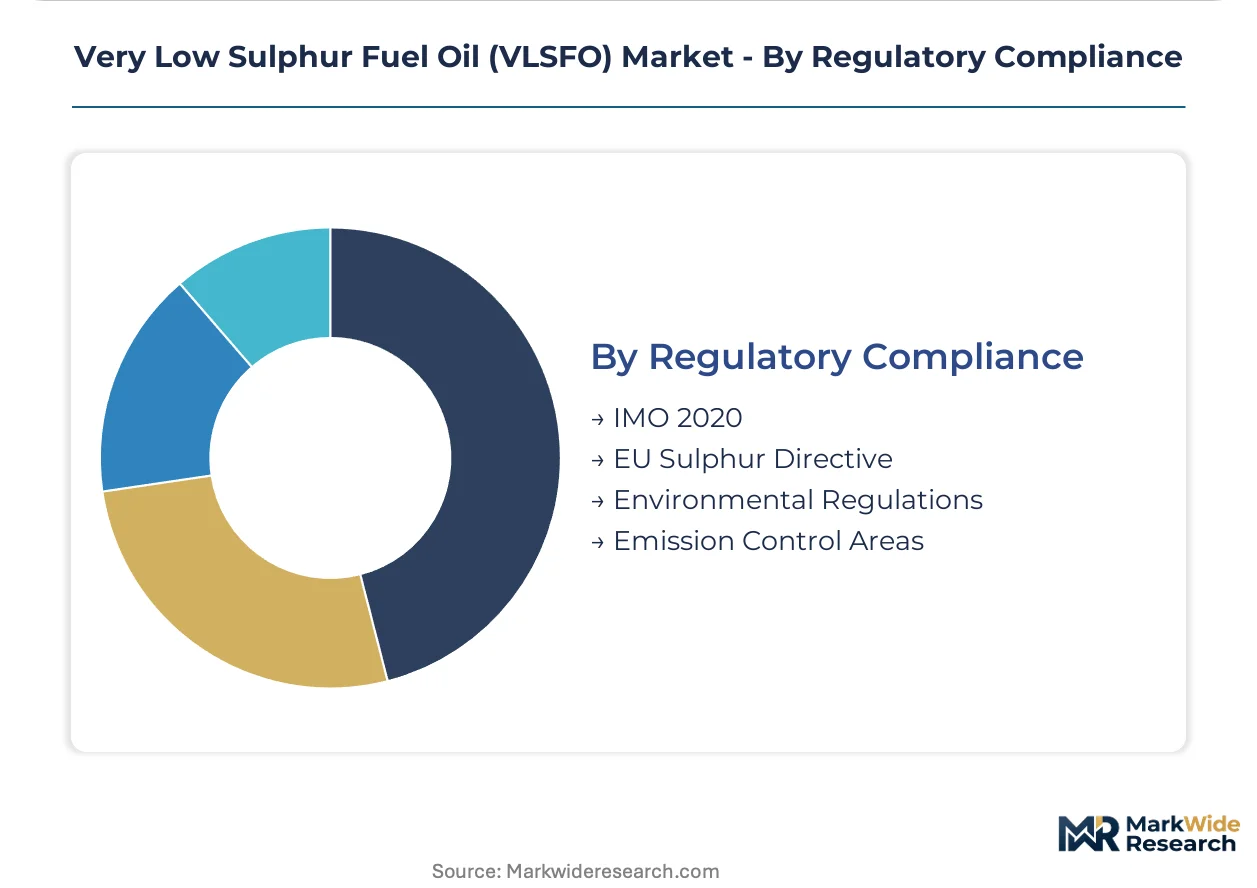
Regulatory Compliance:
Geography determines which sulphur thresholds apply, with overlapping mandates creating the strictest effective standards in overlapping jurisdiction zones.
- IMO 2020:The 0.50% mass fraction sulphur cap permanently restructured marine fuel procurement, forcing container lines to abandon high-sulphur residuals. The US EPA enforces parallel emission standards that restrict high-sulphur fuel oil combustion in territorial waters.
- Emission Control Areas:Designated zones including the North Sea, Baltic Sea, and North American coasts impose 0.10% sulphur caps.
- EU Sulphur Directive:REACH chemical registration requirements and the Fit for 55 package tighten marine fuel carbon intensity disclosures.
- Environmental Regulations:China's MEE and other national regulators enforce sulphur limits aligned with IMO standards.
IMO 2020 governs the broadest volume base; Emission Control Areas show the steepest expansion trajectory as zones multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Crude flexibility at Middle Eastern refineries anchors VLSFO supply security for Asian bunkering hubs. Container shipping rotations through the Strait of Malacca concentrate procurement desks in Singapore. European Emission Control Areas and China's coastal enforcement extend compliant fuel demand across multiple jurisdiction zones.
Singapore
Jurong Island storage terminals handle the largest bunkering volumes outside Emission Control Areas, with container alliances anchoring long-term offtake contracts for Asia-Europe rotations. The Maritime and Port Authority enforces sulphur verification through inline monitoring systems at barge loading points. Tuas Port expansion is consolidating tank farm operations to reduce single-point vulnerability in regional logistics.
Netherlands
Rotterdam-ARA hub operators capture transshipment flows from Baltic and North Sea routes as ECAs tighten sulphur thresholds. The EU Sulphur Directive and REACH chemical registration requirements extend compliance obligations into carbon intensity disclosures. Storage operators in Antwerp and Rotterdam are expanding capacity to handle VLSFO segregation from high-sulphur residual streams.
United Arab Emirates
Fujairah bunkering terminals serve crude tankers and bulk carriers transiting the Gulf of Oman and Arabian Sea. The UAE's Ministry of Energy and Infrastructure aligns port state control with IMO 2020 enforcement standards. Fujairah Oil Industry Zone operators are investing in residue hydrotreating capacity to process heavier regional crude slates into compliant marine fuels.
China
Shanghai and Ningbo-Zhoushan port clusters concentrate domestic bunkering demand from the world's largest container throughput base. The Ministry of Ecology and Environment extends 0.10% sulphur enforcement beyond designated ECAs into coastal waters. Sinopec and independent refiners in Shandong are upgrading vacuum residue hydrotreating units to supply compliant fuels for coastal shipping.
United States
Houston Ship Channel refineries supply VLSFO for Gulf Coast bunkering and Caribbean transshipment routes. The EPA enforces parallel emission standards restricting high-sulphur fuel oil combustion in territorial waters. Port authorities in Los Angeles and Long Beach are coordinating with California Air Resources Board mandates for vessel fuel switching at berth.
Very Low Sulphur Fuel Oil (VLSFO) Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue power generation fuel pivots and digital bunkering platforms. Integrated oil companies with residue upgrading capacity dominate supply security through captive refining networks. Three archetypes anchor competitive positioning: integrated majors with terminal access, national oil companies with crude flexibility, and specialized bunker suppliers with port-side logistics. Capacity expansion in hydrocracking units and strategic partnerships for storage terminal access constitute the dominant competitive moves.
Among integrated majors with global terminal networks, TotalEnergies, ExxonMobil, and BP occupy positions defined by hydroprocessing technology leadership and bunkering infrastructure control. TotalEnergies exemplifies the integrated archetype through combined refining and marine fuel distribution. ExxonMobil represents technology-driven positioning in vacuum residue upgrading. BP anchors European supply security through Rotterdam-ARA hub access. Saudi Aramco and Sinopec, as national oil companies, sit within crude-flexibility archetypes leveraging upstream control over heavy crude slates.
| Leading Market Players |
|---|
| TotalEnergies |
| Saudi Aramco |
| Royal Dutch Shell |
| Sinopec |
| Petrobras |
| ExxonMobil |
| Chevron |
| Hindustan Petroleum |
| BP |
| Others |
Pricing and Supply Chain Analysis
Dubai crude benchmark differentials cascade through refinery cracking spreads into VLSFO pricing tiers, with residue upgrading capacity concentration determining which refiners capture margin versus surrendering it to bunker traders. Singapore storage operators and Rotterdam-ARA hub terminals translate crude volatility into contract premiums for container lines seeking supply security.
Pricing Analysis
Quality certification bundling separates spot purchasers from long-term offtake clients, with ISO 8217 compliance testing and sulphur verification reports included in premium contracts but charged separately to spot buyers. Three-tier pricing structure across premium, standard, and economy levels reflects calorific stability, metals content, and delivery reliability guarantees. Cost compression in the standard tier is intensifying because independent refiners in Shandong and the Middle East expand hydrotreating capacity. Container shipping alliances show lowest price sensitivity due to compliance risk aversion, while coastal utilities in peak-shaving roles exhibit highest sensitivity to calorific value per dollar.
Supply Chain Analysis
Barge freight rates from Jurong Island storage to Singapore anchorage fluctuate with regional tanker availability, adding 8-15% to delivered fuel costs depending on vessel size and queuing delays. Supply concentrates in Singapore, Rotterdam, and Fujairah, with crude feedstock drawn from Middle Eastern heavy sour grades and Russian Far East residual streams. Single-point vulnerability at Singapore's tank farm creates systemic risk for Asia-Pacific bunkering logistics. Distribution runs through port-side storage operators with segregated tank cleaning protocols, barge fleet operators, and direct pipeline connections to refinery output.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IMO 2020 sulphur caps have transformed VLSFO procurement into a cost-of-compliance discipline where residue upgrading investments create defensive moats against high-sulphur fuel oil displacement. The regulation permanently elevated capital barriers for new refinery entrants.
For Market Incumbents: Hedge against LNG substitution in container newbuilds by anchoring long-term offtake contracts with alliance procurement desks before dual-fuel vessel orders accelerate. Deepen backward integration into vacuum residue hydrotreating capacity at Middle Eastern and Asian refining hubs to capture margin from crude flexibility. Lock terminal access in Rotterdam-ARA and Fujairah through joint ventures with storage operators facing single-point vulnerability concerns. For New Entrants and Emerging Players: Coastal utilities in Japan and South Korea represent an underserved buyer archetype with unmet demand for peak-load VLSFO supply security outside marine bunkering channels. Digital bunkering platforms with blockchain-anchored quality verification offer a white-space entry path against incumbent trader networks. Target power generation fuel pivot applications before marine fuel procurement fully consolidates around integrated oil company supply. For Investors and Strategic Acquirers: The window for entry favors national oil companies with captive heavy crude slates and existing residue upgrading infrastructure over independent traders lacking refinery integration. Mid-cycle viability extends through the analysis window as Emission Control Area expansion sustains compliant fuel demand floors. Watch scrubber retrofit economics in the Capesize bulk carrier segment as an inflection signal for VLSFO demand elasticity versus high-sulphur residual competition.| Strategic Initiative | Industry Significance |
|---|---|
| Residue Hydrotreating Capacity Expansion | Captures margin from heavier crude slates while meeting IMO 2020 sulphur specifications. |
| Long-term Offtake Agreement | Container alliances secure supply security through direct refinery relationships bypassing traders. |
| Storage Terminal Joint Venture | Rotterdam-ARA and Fujairah operators reduce single-point vulnerability through diversified access. |
| Digital Bunkering Platform | Blockchain-anchored sulphur verification compresses dispute resolution and accelerates port turnaround. |
| Power Generation Fuel Pivot | Japanese and South Korean utilities substitute VLSFO for high-sulphur residuals in peak-load units. |
Research Methodology
Refinery production databases, customs trade flows, and IMO compliance enforcement records formed the secondary backbone, cross-referenced with primary interviews involving refinery operations managers, bunker procurement leads at container shipping alliances, port authority fuel quality inspectors, and storage terminal operators. Bottom-up volume modeling triangulated against top-down macroeconomic demand projections across fuel type, application, and distribution channel dimensions.
Bottom-up segmentation analysis tracked marine fuel, power generation fuel, industrial fuel, and residential heating fuel categories through the projection horizon, with bunker fuel suppliers, direct sales, retail distributors, and online platforms as channel dimensions. CAGRs were derived from regression analysis against crude price differentials, refinery upgrading capacity additions, and ECA expansion schedules. Forecast inputs incorporated scrubber retrofit penetration curves and LNG newbuild orderbook ratios as demand displacement variables.
Revisions become necessary when scrubber economics shift materially, LNG propulsion costs decline below VLSFO parity, or refinery upgrading capacity additions exceed demand growth in key bunkering hubs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Petcoke Market
Petroleum Products
South Africa Lubricants Market
Petroleum Products
South Africa Refined Petroleum Products Market
Petroleum Products
Ultra Low Sulphur Fuel Oil (ULSFO) Market
Petroleum Products
Liquefied Petroleum Gas Market
Petroleum Products
West Africa Refined Petroleum Products Market
Petroleum Products
LPG [Liquefied Petroleum Gas] Market
Petroleum Products
Crude Oil Market
Petroleum Products
Petroleum Liquid Feedstock Naphtha and Gas Oil Sales Market
Petroleum Products
United States Refined Petroleum Products Market
Petroleum Products
Floating Roof Tank Market
Petroleum Products
Quenching Oil Market
Petroleum Products
Oil Shale Market
Petroleum Products
Pyrolysis Gasoline Market
Petroleum Products
Oil Storage Sales Market
Petroleum Products
Paraffin Oil Market