
 Liquefied Petroleum Gas Market | 2026-2036
Liquefied Petroleum Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Liquefied Petroleum Gas Market Outlook
Modular cylinder sizing and bundled appliance-plus-fuel subscription packages is restructuring buyer choice across emerging markets. Shell plc leverages its integrated supply chain to sustain competitive delivery economics in high-growth Asian corridors. Bharat Petroleum Corporation anchors its position through extensive last-mile distribution networks spanning semi-urban India. Saudi Arabian Oil Co. differentiates via captive feedstock access and large-scale export terminal capacity.
Liquefied Petroleum Gas comprises propane and butane hydrocarbons recovered from natural gas processing or crude oil refining, stored under moderate pressure as a liquid at ambient temperature for transport and vaporized at point of use for combustion. Its primary commercial purpose centers on clean-burning thermal energy delivery for cooking, heating, and industrial process applications where pipeline natural gas infrastructure remains unavailable. Propane dominates residential and commercial heating segments due to superior vapor pressure performance in cold climates, while butane commands stronger industrial margins in petrochemical feedstock applications. The automotive fueling segment shows structural growth potential where national governments mandate alternative transport fuels, though retail distribution infrastructure gaps constrain near-term scaling.
India's Petroleum and Natural Gas Regulatory Board, China's National Energy Administration, and the EU F-Gas Regulation collectively shape product standards, import tariffs, and clean cooking subsidies that determine market access and demand elasticity across major consumption zones. These frameworks increasingly tie LPG infrastructure investment to carbon-intensity benchmarks and household energy-transition targets. Stakeholders must monitor regulatory shifts in subsidy rationalization and blending mandates as policy uncertainty represents the dominant variable affecting long-term capacity planning and import contract structures.
Market Dynamics
India's PLI scheme for clean cooking fuels is compressing infrastructure buildout timelines and concentrating procurement volumes around national distributors with last-mile capabilities.
Growth Catalysts
- India's PLI scheme:Subsidy rationalization under India's Production Linked Incentive scheme accelerates cylinder penetration into semi-urban households previously dependent on biomass.
- Propane cold-climate performance:Superior vapor pressure characteristics drive residential heating adoption in northern China and the US Northeast where pipeline natural gas remains unavailable.
- EU F-Gas Regulation:Phase-down schedules for hydrofluorocarbons in commercial refrigeration create substitution pull for propane-based cooling systems across European industrial facilities.
Market Restraints
- Crude oil price volatility:Refinery-sourced butane supply fluctuates with OPEC+ production decisions, compressing margins for non-integrated distributors.
- Concentrated import terminal ownership:Gulf Coast and Rotterdam storage capacity sits with a limited set of integrated majors, creating bottleneck risk for independent traders.
- Pipeline natural gas substitution:Grid expansion in China's Yangtze River Delta and India's western industrial corridors displaces bulk LPG offtake for process heat.
Strategic Opportunities
- Brazilian autogas conversion:Tax differential policies favoring alternative transport fuels create fleet conversion demand in São Paulo and Rio de Janeiro commercial vehicle segments.
- Modular micro-distribution:Cylinder subscription platforms bundled with appliance financing unlock underpenetrated rural Indonesia and Philippines archipelago markets.
- Propane-r410A hybrid cooling:Convergence of hydrocarbon refrigerant technology with existing HVAC infrastructure creates retrofit opportunity in EU commercial building stock.
Industry Challenges
- Cryogenic handling certification:Specialized technician training for pressurized liquid fuel systems lags cylinder deployment rates in India's eastern states.
- Import terminal capex intensity:Deepwater berth and refrigerated storage requirements lock capital for 15-20 year horizons, constraining portfolio rebalancing.
- Legacy kerosene subsidy politics:Rationalization resistance in Bangladesh and Nigeria delays household fuel-switching program execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquefied Petroleum Gas Market |
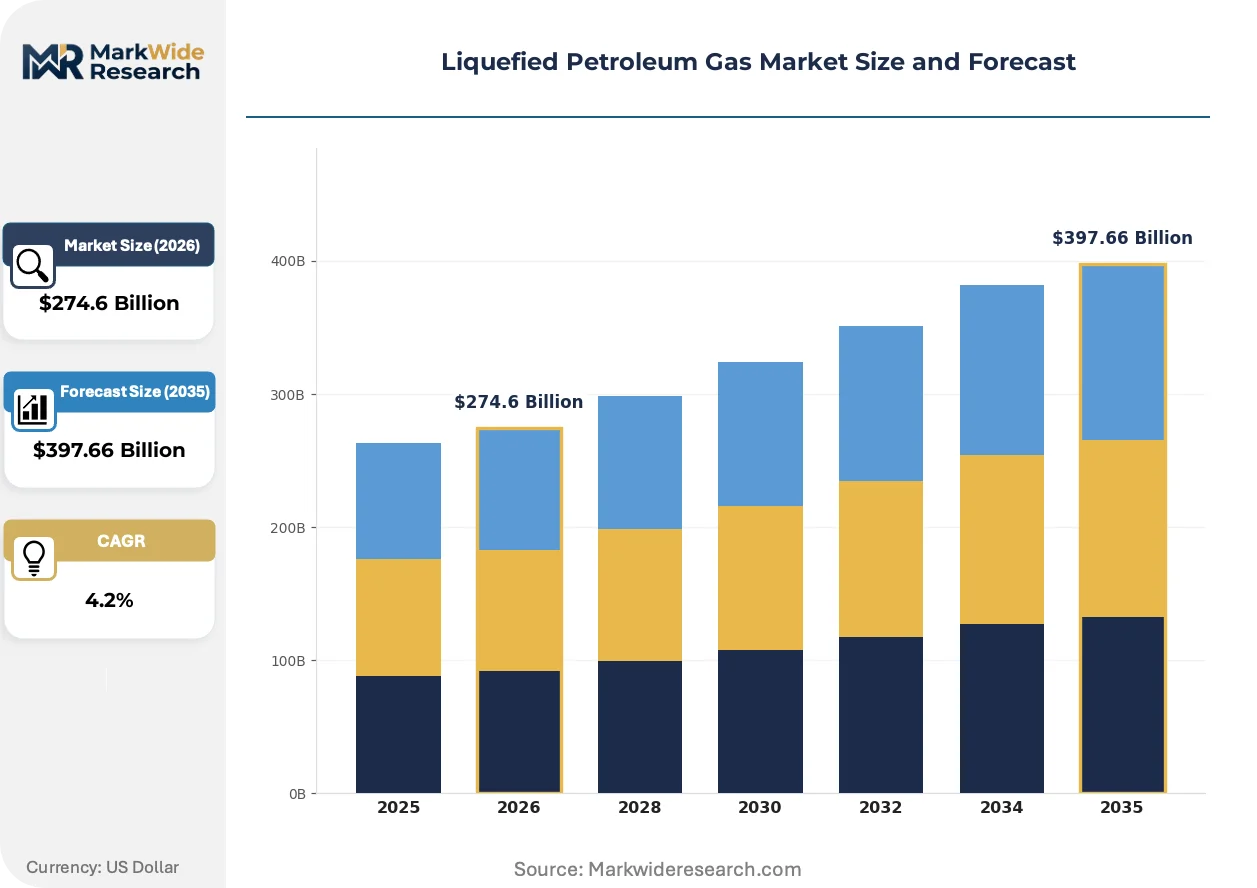
| Market Size in 2026 | $274.6 Billion |
| Market Size in 2035 | $397.66 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Propane, Butane, Mixture, Isobutane End Use Industry: Residential, Commercial, Automotive, Industrial Application: Cooking, Heating, Fueling, Refrigeration Distribution Channel: Direct Supply, Retail, Wholesale, Others |
| Companies Covered | BP p.l.c., Chevron Corporation, Shell plc, China Gas Holdings, Repsol, Exxon Mobil Corporation, Saudi Arabian Oil Co., Bharat Petroleum Corporation, TotalEnergies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquefied Petroleum Gas Market Strategic Shifts
Digital cylinder tracking and predictive refill algorithms are compressing inventory cycles and reshaping distributor working capital requirements across high-volume Asian corridors.
Composite fiber-wrapped cylinders are converging with IoT pressure monitoring to enable lightweight, transparent inventory management. Last-mile distributors in India and Indonesia are adopting these units for high-rise residential clusters. The technology is converging with mobile payment platforms to create fully automated subscription refills.
The EU F-Gas Regulation mandates hydrocarbon refrigerant quotas that phase down synthetic alternatives through 2030. European commercial cold-chain operators are retooling facilities to accommodate propane-based systems. Food retail and pharmaceutical storage segments in Germany and France face the most compressed compliance timelines.
Subscription bundling is displacing spot cylinder purchases in emerging market household segments. Distributors in Brazil and Mexico now package stoves, regulators, and refill credits into monthly plans. Urban middle-income households show strongest uptake where credit infrastructure supports automated billing.
Liquefied Petroleum Gas Market Segmentation
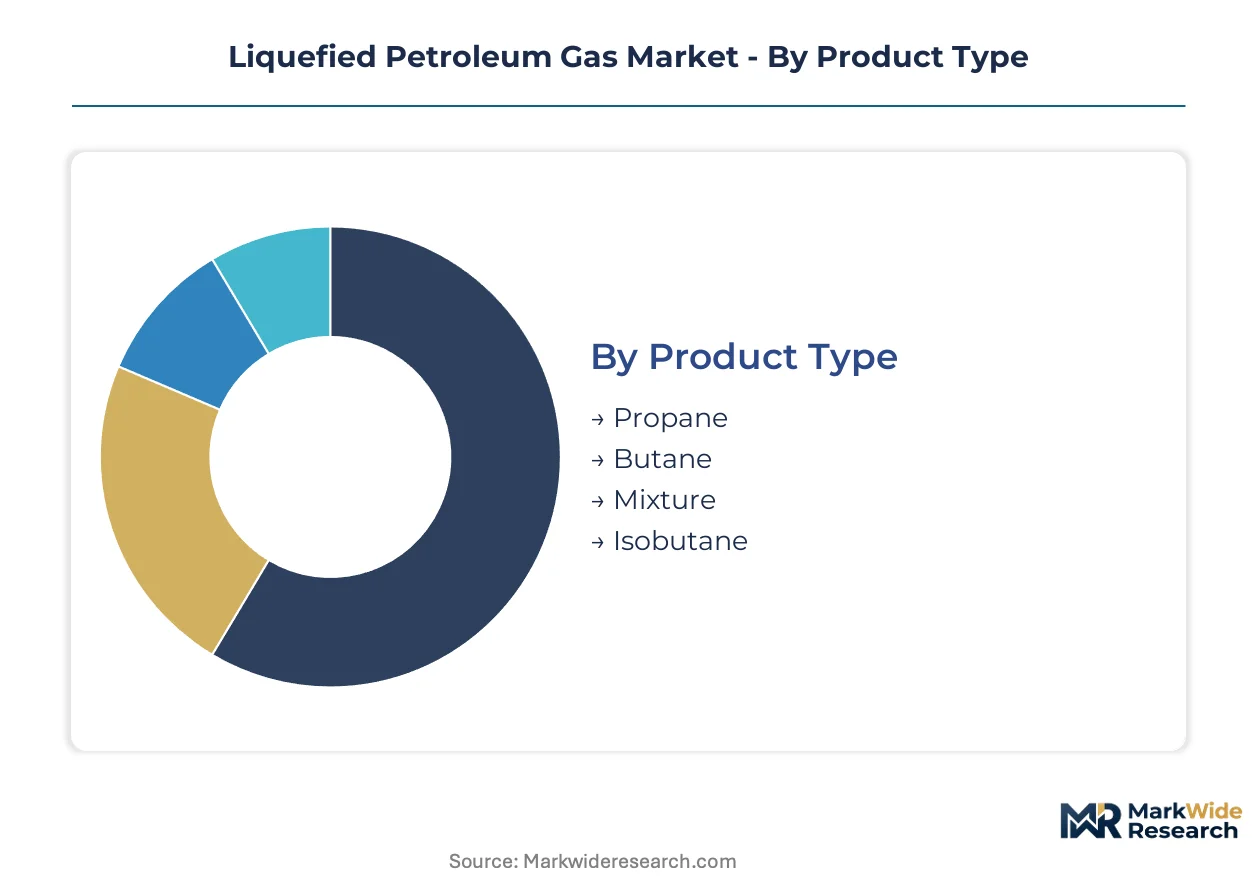
Segmentation in the Liquefied Petroleum Gas market determines procurement contract structures and infrastructure investment priorities. Product composition drives storage specifications and end-use compatibility, while distribution channel selection shapes working capital intensity and customer reach.
Product Type:
Replacement cycles for LPG storage and handling equipment vary sharply by hydrocarbon composition, with cold-climate performance requirements forcing faster turnover in northern installations.
- Propane:This C3 hydrocarbon delivers superior vapor pressure at sub-zero temperatures, making it the default specification for residential heating in the US Northeast and northern China. Demand concentrates in rural and semi-urban households lacking pipeline natural gas access, with India's PLI scheme accelerating cylinder penetration into previously biomass-dependent regions.
- Butane:The C4 variant offers higher energy density per liquid volume and dominates petrochemical feedstock applications where vaporization temperature is less critical. Industrial offtake clusters around coastal China and the US Gulf Coast, though refinery supply fluctuations tied to OPEC+ production decisions create margin compression for non-integrated buyers.
- Mixture:Blended propane-butane formulations balance vapor pressure performance with cost optimization for temperate climate distribution.
- Isobutane:This branched isomer serves specialized refrigerant applications under EU F-Gas Regulation compliance schedules.
Propane sits at the top of the volume ranking, with isobutane climbing the fastest on hydrocarbon refrigerant substitution mandates.
End Use Industry:
Customer type determines pricing power and contract duration, with residential subscribers locking in predictable refill volumes against industrial buyers exposed to spot market volatility.
- Residential:Household cooking and heating applications generate the most stable demand profile, with India's national distribution program and Brazil's cylinder subsidy schemes creating concentrated procurement volumes around licensed national distributors.
- Commercial:Restaurants, hotels, and small enterprises require flexible delivery frequencies and smaller lot sizes, driving adoption of digital tracking platforms and predictive refill algorithms.
- Automotive:Fleet conversion demand in São Paulo and Rio de Janeiro responds to Brazilian tax differentials favoring autogas over conventional transport fuels.
- Industrial:Process heat applications face displacement risk from pipeline natural gas grid expansion in China's Yangtze River Delta and India's western industrial corridors.
Residential commands the largest share of cylinder volumes, while automotive is expanding most quickly on regulatory-driven fleet conversion programs.
Application:
Application focus shapes margin structure, with fueling and refrigeration commanding premium pricing against commoditized cooking fuel sales.
- Cooking:Clean-burning thermal delivery for household meal preparation anchors emerging market demand, with India's eastern states and Indonesia's archipelago markets showing persistent infrastructure gaps.
- Heating:Cold-climate residential and commercial warmth generation depends on propane's vapor pressure reliability where pipeline natural gas remains unavailable.
- Fueling:Autogas for commercial vehicle fleets benefits from Brazilian and Turkish tax policy favoring alternative transport fuels.
- Refrigeration:Propane-based cooling systems gain share as EU F-Gas Regulation phases down hydrofluorocarbon alternatives in German and French commercial cold-chain facilities.
Cooking remains the dominant application by cylinder count, with refrigeration gaining share fastest on regulatory substitution mandates.
Distribution Channel:
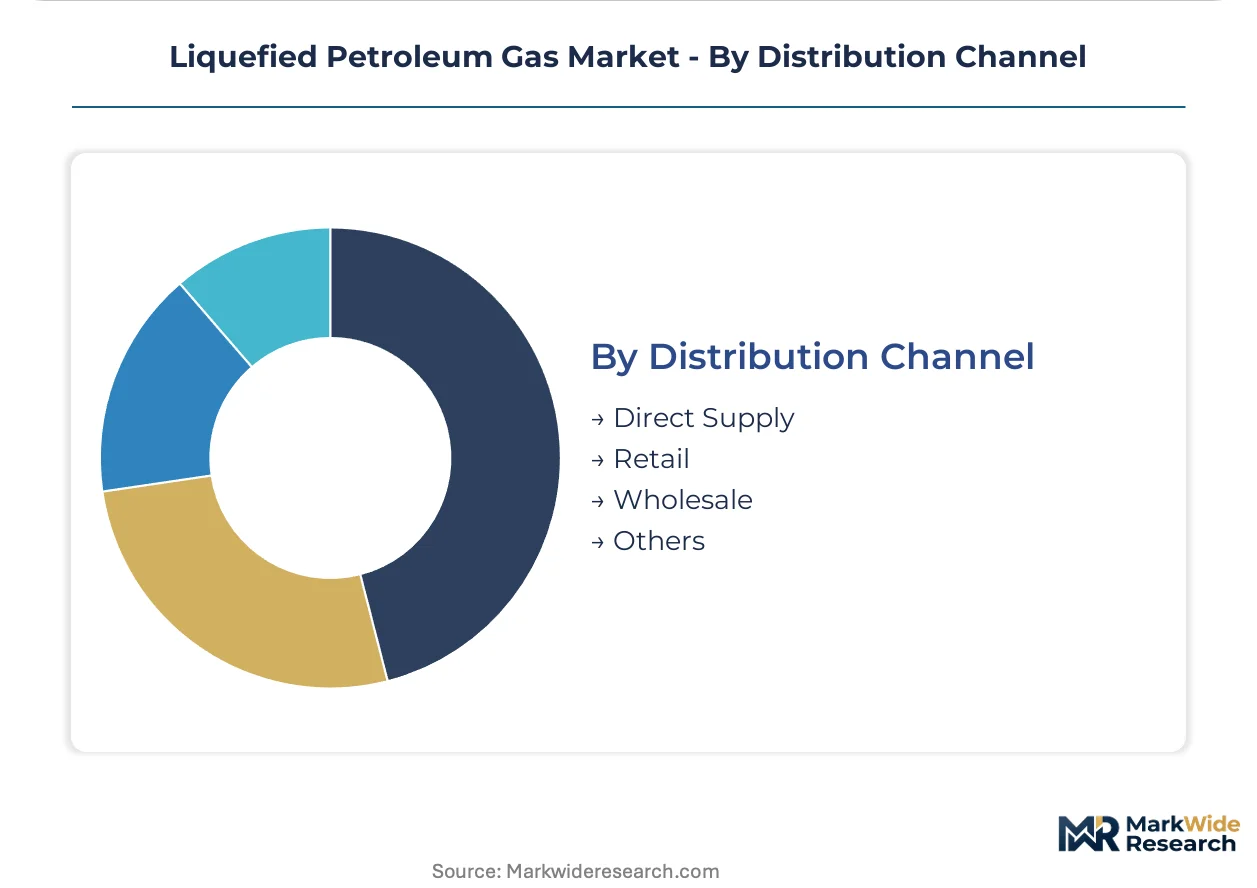
Channel selection determines capital intensity and customer intimacy, with direct supply relationships requiring dedicated infrastructure against retail's working capital flexibility.
- Direct Supply:Large-volume contracts between producers and industrial offtakers eliminate intermediary margins but demand dedicated storage and handling assets.
- Retail:Cylinder exchange networks and subscription bundling platforms capture urban middle-income households in Brazil and Mexico through automated billing integration.
- Wholesale:Independent traders and regional distributors aggregate volumes for secondary resale, facing bottleneck risk from concentrated import terminal ownership at Rotterdam and US Gulf Coast facilities.
- Others:Digital-native subscription platforms and IoT-enabled refill services represent emerging channel experimentation.
Retail dominates cylinder transaction volumes, with digital subscription platforms showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
LPG commercialization traces its industrial lineage to early 20th-century American refinery operations, with wartime fuel rationing accelerating cylinder distribution networks across temperate climates. Contemporary demand geography concentrates in economies where pipeline natural gas infrastructure remains incomplete and national governments subsidize household energy transition.
India
Residential cooking demand dominates procurement volumes as the PLI scheme accelerates cylinder penetration into Bihar and West Bengal. The Petroleum and Natural Gas Regulatory Board mandates safety standards for composite fiber-wrapped units. Kolkata and Patna distribution clusters show fastest refill frequency growth on subscription bundling adoption.
China
Propane cold-climate heating anchors northern demand in Heilongjiang and Jilin provinces where pipeline networks terminate. The National Energy Administration sets import tariff schedules and strategic reserve targets. The Yangtze River Delta industrial corridor faces displacement pressure from natural gas grid expansion.
Brazil
São Paulo and Rio de Janeiro fleet operators convert commercial vehicles to autogas under federal tax differential policies. ANVISA regulates cylinder certification for pressurized fuel systems. The Southeast region concentrates refinery-sourced butane supply and coastal import terminal capacity.
United States
Rural residential heating in the Northeast and Midwest sustains propane demand where pipeline natural gas remains uneconomic. EPA emissions standards shape burner appliance specifications. The Gulf Coast hosts concentrated export terminal infrastructure serving Atlantic basin markets.
Germany
Commercial refrigeration retrofit demand accelerates as the EU F-Gas Regulation phases down hydrofluorocarbon quotas through 2030. ECHA oversees hydrocarbon refrigerant safety certifications. The Rhine-Ruhr industrial cluster leads cold-chain facility retooling for propane-based cooling systems.
Liquefied Petroleum Gas Market Competitive Environment
Premium-margin players sit above commodity-margin players across integrated supply chain control, with captive feedstock access and dedicated terminal infrastructure determining profitability tiers. The market structure consolidates around national oil companies with upstream hydrocarbon production and international majors with global trading desks. Three archetypes dominate: integrated upstream-downstream operators, state-affiliated distributors with last-mile networks, and independent traders dependent on spot market access. Capacity expansion at deepwater berths and strategic partnerships for cylinder subscription platforms represent the dominant competitive moves.
Within the integrated major tier, Shell plc exemplifies global trading and terminal infrastructure dominance, while Saudi Arabian Oil Co. anchors the state-affiliated archetype through captive feedstock and export capacity. Bharat Petroleum Corporation occupies a position representing national distributor scale with extensive semi-urban last-mile networks. These three entities illustrate how geographic origin and corporate structure map to strategic positioning across production, trading, and retail endpoints.
| Leading Market Players |
|---|
| BP p.l.c. |
| Chevron Corporation |
| Shell plc |
| China Gas Holdings |
| Repsol |
| Exxon Mobil Corporation |
| Saudi Arabian Oil Co. |
| Bharat Petroleum Corporation |
| TotalEnergies |
| Others |
Value Chain & Pricing Dynamics
Mont Belvieu propane spot benchmarks cascade through contract structures to stratify pricing across integrated majors, national distributors, and independent traders. This commodity-linked foundation compresses margins for non-integrated buyers when OPEC+ production decisions tighten refinery-sourced butane availability.
Pricing Analysis
Contract-based long-term offtake agreements anchor procurement between integrated producers and industrial buyers, while spot-indexed pricing governs independent trader transactions. Price differentiation hinges on captive feedstock access and dedicated terminal infrastructure ownership, with integrated majors commanding premium margins against distributor thinness. Cost compression in the independent trader tier is intensifying because concentrated import terminal ownership at Rotterdam and US Gulf Coast facilities limits bargaining leverage. National distributors with last-mile networks show lowest price sensitivity due to subsidy-protected residential volumes, while industrial process heat buyers face highest sensitivity as pipeline natural gas substitution accelerates.
Supply Chain Analysis
Specialized technician certification gaps in India's eastern states and Indonesia's archipelago markets constrain cylinder deployment velocity. Supply concentrates in Saudi Arabia, the United States, and Qatar as primary production hubs, with India, China, and Brazil anchoring demand-side distribution infrastructure. Raw material flows draw from associated gas processing at crude oil fields and natural gas fractionation facilities, with refinery-sourced butane volumes fluctuating on OPEC+ output decisions. Single-source vulnerability sits with Gulf Coast and Rotterdam refrigerated storage capacity ownership among integrated majors. Distribution runs through national oil company cylinder exchange networks, wholesale aggregator channels, and emerging digital subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as household energy transition programs concentrate procurement around distributors with composite fiber-wrapped cylinder capabilities and IoT-enabled inventory systems.
For Market Incumbents: Anticipate displacement pressure from pipeline natural gas grid expansion in China's Yangtze River Delta and India's western industrial corridors by deepening backward integration into captive feedstock access and expanding composite cylinder certification investments. Secure strategic reserve partnerships with national distributors in Bihar and West Bengal ahead of PLI scheme procurement consolidation. For New Entrants and Emerging Players: The EU F-Gas Regulation in Germany and France opens a window for propane-based refrigeration retrofit specialists to capture commercial cold-chain facility retooling demand. Target modular micro-distribution platforms bundled with appliance financing in rural Indonesia and Philippines archipelago markets where legacy kerosene infrastructure persists. Deploy mobile payment-integrated subscription models to bypass capital-intensive import terminal requirements. For Investors and Strategic Acquirers: Asymmetric upside sits with national distributors possessing last-mile density in semi-urban India and cylinder subscription platform technology. Long-term viability over the coming decade rests on regulatory subsidy durability and household energy transition program execution. Monitor PLI scheme procurement volume concentration around licensed national distributors as the inflection signal for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Captive propane access insulates margin compression from OPEC+ production volatility. |
| Composite Cylinder Certification Investment | PNGRB safety mandates in India accelerate adoption of fiber-wrapped IoT-enabled units. |
| Digital Subscription Platform Deployment | Mobile payment integration captures urban middle-income households in Brazil and Mexico. |
| Refrigeration Retrofit Capability Buildout | EU F-Gas Regulation compliance timelines in Germany and France drive equipment demand. |
| Strategic Reserve Partnership Formation | National Energy Administration targets in China secure long-term offtake commitments. |
Study Parameters
Direct dialogue with refinery operations managers, national distributor procurement leads, composite cylinder manufacturers, and LNG-to-LPG switching planners grounded qualitative assessment, cross-referenced with customs trade data, Petroleum and Natural Gas Regulatory Board filings, EIA stock reports, and SEC 10-K disclosures from integrated majors. Bottom-up cylinder deployment estimates and top-down refinery output analysis were triangulated against national subsidy program targets.
Segment-level volume and value trajectories across the projection horizon were generated through multi-dimensional modeling incorporating product type composition, end-use industry concentration, distribution channel evolution, and regional regulatory framework intensity. CAGRs were derived from iterative convergence of historical offtake patterns and policy-incentivized deployment schedules, with India's PLI scheme cylinder targets and EU F-Gas Regulation phase-down timelines serving as primary demand-side calibration inputs.
Revisions become necessary when OPEC+ production decisions materially alter refinery-sourced butane availability, when pipeline natural gas grid expansion accelerates beyond modeled displacement rates, or when subsidy rationalization politics delay household fuel-switching program execution. Material deviation in these named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Southeast Asia Refined Petroleum Products Market
Petroleum Products
Automotive Oil Market
Petroleum Products
Uganda Petroleum Products Market
Petroleum Products
Crude Oil Pour Point Depressant Market
Petroleum Products
Gasoline-Naphtha-Crude-MTBE Market
Petroleum Products
Helical Submerged Arc Welded Pipe Market
Petroleum Products
Crude Oil Flow Improvers Market
Petroleum Products
Refined Petroleum Products Market
Petroleum Products
West Africa Refined Petroleum Products Market
Petroleum Products
South Africa Refined Petroleum Products Market
Petroleum Products
Global Petroleum Pitch Market
Petroleum Products
Green Petcoke Market
Petroleum Products
Petroleum Wax Market
Petroleum Products
Europe Ethane Market
Petroleum Products
Underground Storage Tanks Market
Petroleum Products
Petroleum Liquid Feedstock Market