
 Crude Oil Flow Improvers Market | 2026-2036
Crude Oil Flow Improvers Market Size, Share, and Industry Trends Forecast 2026-2036
Crude Oil Flow Improvers Market Analysis
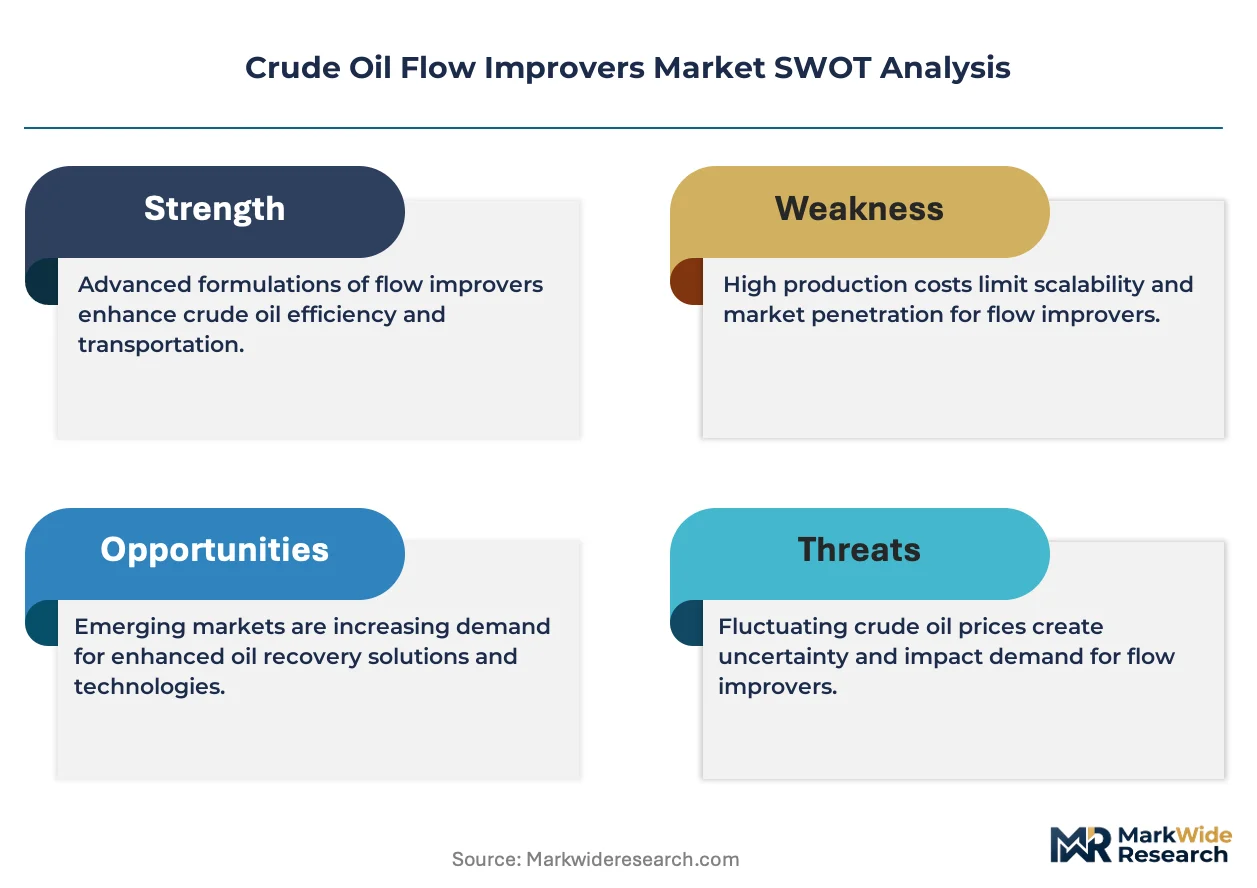
EPA discharge rules for produced water is recalibrating the cost-of-entry calculus for new flow improver suppliers seeking offshore contracts. Baker Hughes leverages its integrated chemical services platform to bundle treatment programs with subsea monitoring systems. SLB (Schlumberger) anchors its position through proprietary chemical formulation labs co-located with major production basins. Halliburton Energy Services differentiates via thermal treatment capabilities that address ultra-heavy crude challenges in mature fields.
Crude oil flow improvers are chemical additives designed to reduce viscosity, lower pour point, and inhibit wax or asphaltene deposition in hydrocarbon transport systems, typically comprising polymeric drag reducers, surfactant dispersants, or solvent-based diluents formulated for specific crude compositions. Their primary purpose is maintaining pipeline throughput, minimizing energy consumption for pumping, and preventing flow assurance failures in production and transportation infrastructure. Polymer-based drag reducers command the dominant share of product-type revenue due to established efficacy in turbulent flow regimes across long-distance pipelines. Pipeline transportation applications generate the largest absolute demand, though enhanced oil recovery represents the fastest-growing application segment as tertiary recovery projects expand in mature basins. Oil companies constitute the most concentrated end-user category, with integrated majors directly procuring flow improvers through long-term chemical management contracts rather than spot purchasing.
EPA regulations govern offshore chemical discharge limits in US waters, while REACH compliance requirements in Europe restrict certain surfactant chemistries, and Brazil's national petroleum regulator ANP mandates environmental impact assessments for chemical injection programs in pre-salt fields. These frameworks collectively elevate formulation complexity and documentation burdens, favoring suppliers with established regulatory affairs capabilities and regional compliance infrastructure. Stakeholders must monitor evolving biodegradability mandates and carbon-intensity disclosure requirements that will reshape procurement criteria and supplier qualification protocols.
Market Dynamics
The US Environmental Protection Agency's revised discharge standards for produced water are recalibrating formulation priorities across the offshore flow improver supply base, favoring biodegradable chemistries that maintain performance under subsea pressure-temperature conditions.
Growth Catalysts
- Pre-salt basin development:Brazil's ANP-mandated environmental impact assessments for chemical injection programs are accelerating demand for high-performance pour-point depressants tailored to high wax-content crudes in deepwater fields.
- REACH compliance evolution:ECHA restrictions on certain surfactant chemistries in European waters are driving R&D investment into next-generation biodegradable dispersant platforms for North Sea operators.
- Subsea infrastructure aging:Thermal treatment capabilities for ultra-heavy crude transport are gaining traction among integrated majors managing mature field decline in the Gulf of Mexico.
Market Restraints
- Specialty polymer feedstock volatility:Polyalphaolefin and polyacrylamide precursor costs fluctuate with olefin cracking margins, compressing drag reducer formulation economics during upstream chemical procurement cycles.
- Regional supplier concentration:Gulf Coast chemical manufacturing clusters dominate polymer-based drag reducer production, exposing buyers to hurricane-season supply disruption risks.
- Biodegradability-performance tradeoff:EPA discharge standards for produced water impose formulation constraints that reduce maximum effective temperature ranges for certain surfactant classes in deepwater applications.
Strategic Opportunities
- Enhanced oil recovery expansion:Tertiary recovery projects in mature Permian Basin formations are creating demand for viscosity-reducing chemical packages integrated with CO2 flood operations.
- Digital-chemical convergence:Real-time subsea monitoring systems combined with automated chemical injection skids enable precision dosing that cuts treatment volumes by double-digit percentages.
- Pre-salt regulatory tailwind:ANP environmental mandates position biodegradable formulation specialists to capture long-term chemical management contracts in Brazil's fastest-growing offshore province.
Industry Challenges
- Flow assurance engineering talent scarcity:Experienced specialists capable of integrating chemical treatment programs with subsea production systems command premium compensation, constraining supplier scaling velocity.
- Multi-jurisdiction certification timelines:Simultaneous EPA, REACH, and ANP approval processes for novel biodegradable surfactants extend product commercialization cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crude Oil Flow Improvers Market |
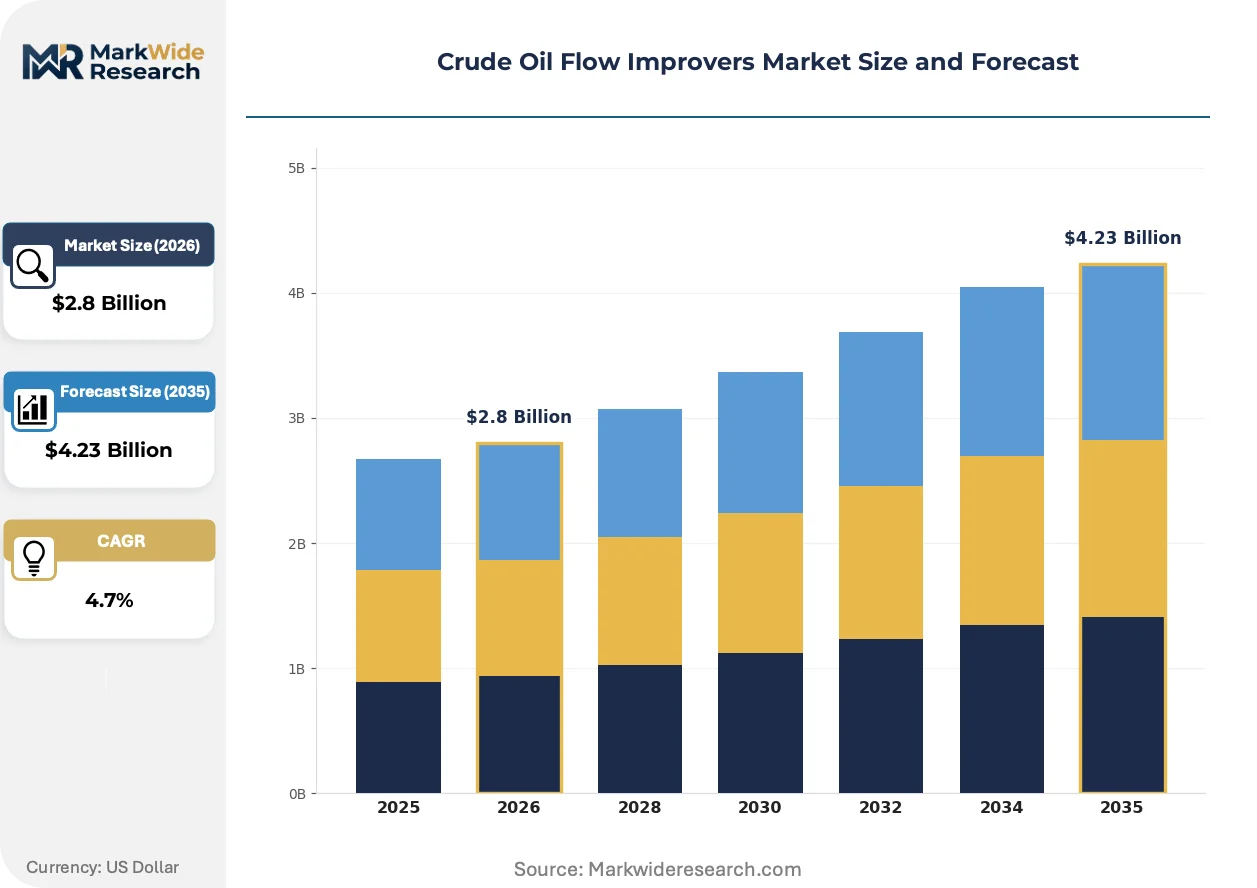
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
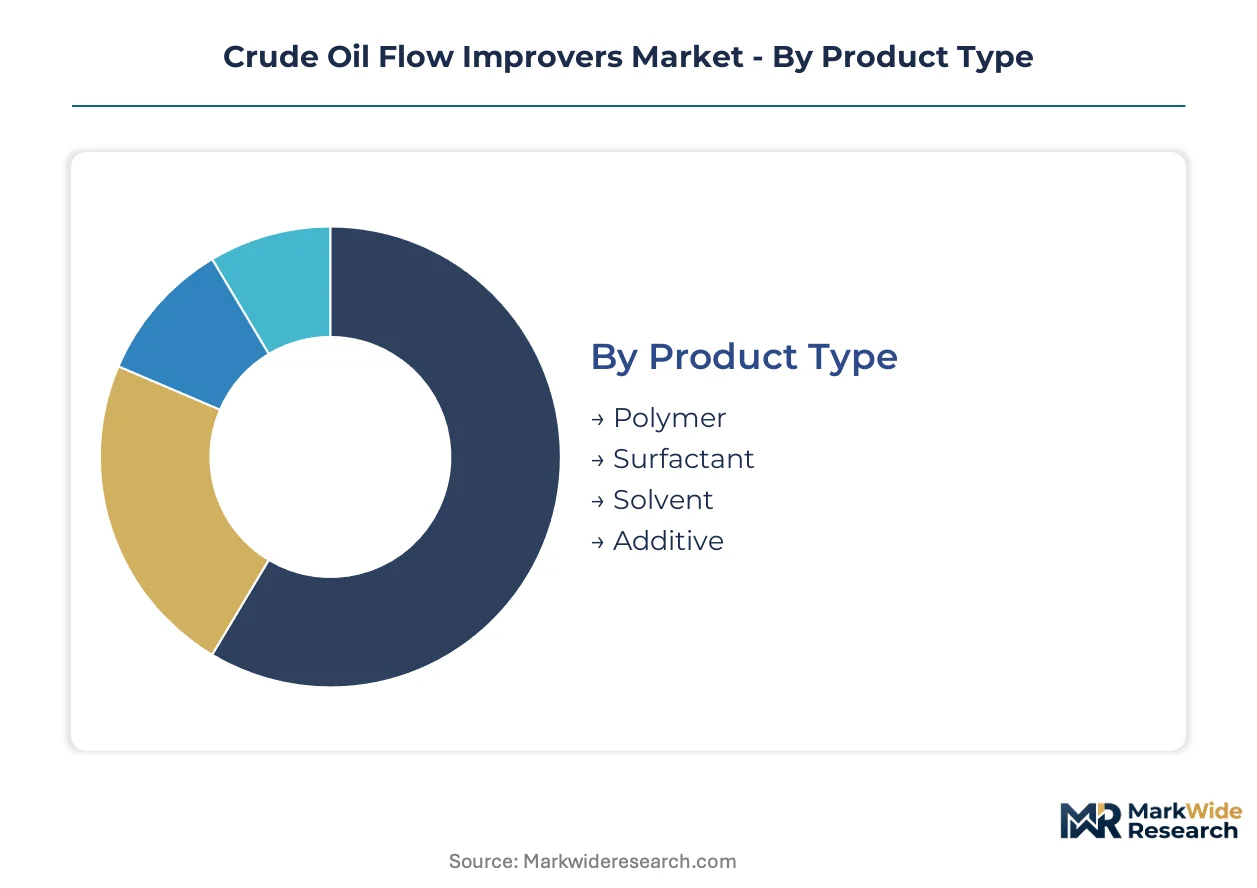
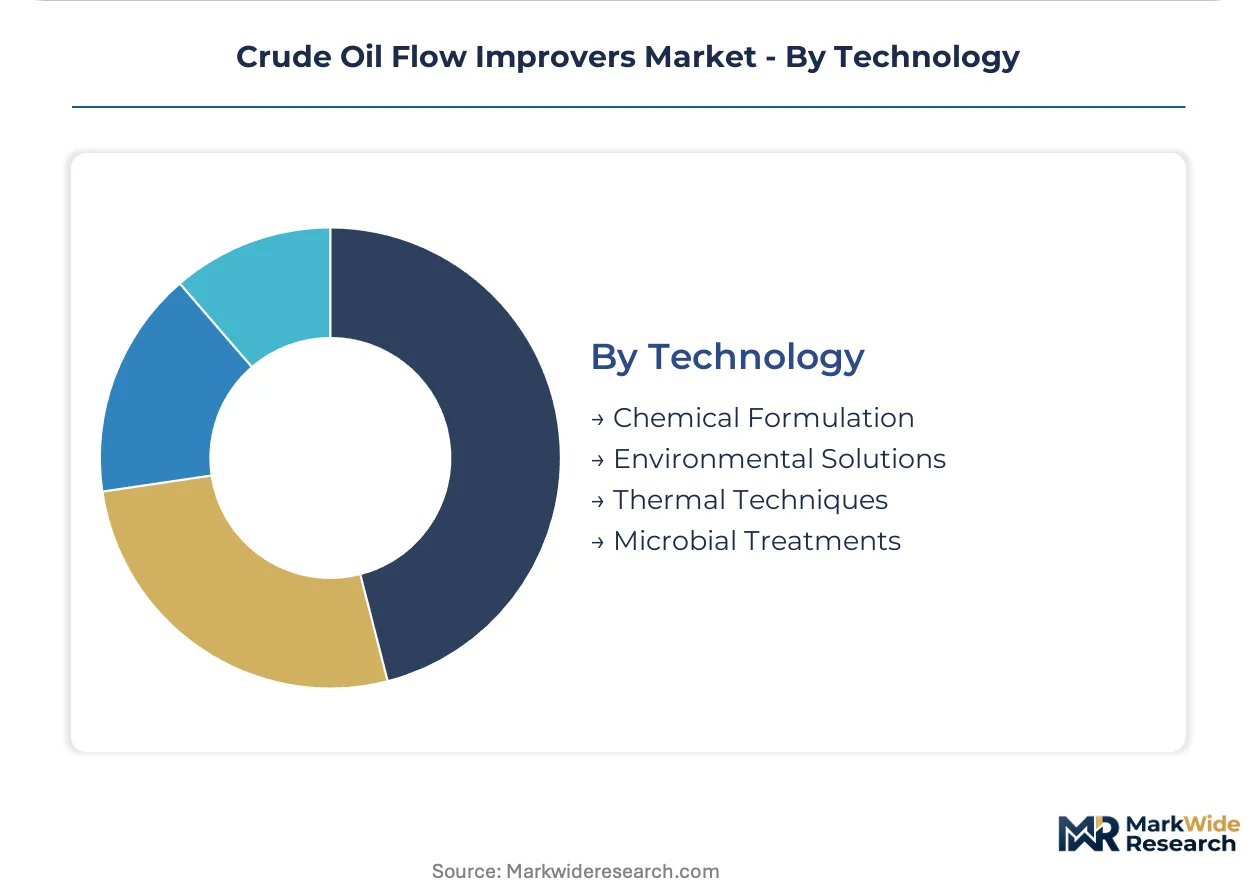
| Segmentation | Product Type: Polymer, Surfactant, Solvent, Additive Application: Pipeline Transportation, Enhanced Oil Recovery, Refining, Production End User: Oil Companies, Refineries, Service Providers, Independent Producers Technology: Chemical Formulation, Environmental Solutions, Thermal Techniques, Microbial Treatments |
| Companies Covered | Baker Hughes, Dorf Ketal, BASF, Clariant, SLB (Schlumberger), Halliburton Energy Services, The Lubrizol Corporation, Infineum International Limited, Evonik Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crude Oil Flow Improvers Market Emerging Trajectories
Formulation science and digital infrastructure are converging to reshape how flow improvers are specified, dosed, and monitored across offshore and onshore production systems.
Hybrid polymer-surfactant drag reducer platforms are unifying viscosity reduction and wax inhibition functions into single-treatment chemistries. Offshore operators in the Gulf of Mexico are adopting these dual-function formulations for subsea tiebacks where deck space limits chemical storage. The technology is unifying previously separate procurement categories, compressing supplier margins on standalone product lines while rewarding integrated formulation capabilities.
REACH authorization requirements for persistent organic pollutants are restricting certain ethoxylated surfactant chemistries in European waters. ECHA's evolving substance evaluation timeline is forcing North Sea operators to accelerate qualification of biodegradable alternatives ahead of sunset dates. Drag reducer suppliers with established European regulatory affairs infrastructure are capturing contract renewals that competitors forfeit due to compliance documentation gaps.
Integrated majors are consolidating chemical procurement under long-term performance-based contracts that bundle treatment supply with flow assurance engineering services. Spot purchasing for pour-point depressants is declining as operators seek single-accountability partners for subsea system reliability. This concentration is most visible in Brazil's pre-salt sector, where Petrobras and international partners favor chemical management contracts spanning multiple field developments.
Crude Oil Flow Improvers Market Segmentation
Flow improver procurement patterns diver sharply based on whether chemicals deploy as standalone treatments or integrate into broader production systems. Understanding these integration depths clarifies why certain segments command premium pricing while others face commoditization pressure.
Product Type:
Polymer-based formulations dominate standalone viscosity reduction applications, while surfactant and solvent chemistries increasingly embed into multi-functional treatment packages.
- Polymer:Polyalphaolefin and polyacrylamide drag reducers reduce turbulent friction in long-distance pipeline transport. Demand concentrates in Permian Basin midstream corridors where operators pump high volumes across extended distances. Gulf Coast chemical clusters supply these formulations, exposing buyers to hurricane-season disruption risks.
- Surfactant:Ethoxylated and biodegradable dispersant chemistries inhibit wax and asphaltene deposition in subsea flowlines. North Sea operators prioritize these formulations under ECHA REACH authorization timelines that restrict persistent organic pollutants. EPA discharge standards for produced water are accelerating biodegradable surfactant qualification in Gulf of Mexico deepwater fields.
- Solvent:Aromatic and aliphatic diluents blend with heavy crude to reduce viscosity for pipeline transport.
- Additive:Corrosion inhibitors and scale suppressants complement primary flow improver chemistries in integrated treatment programs.
Volume placements concentrate in Polymer; the faster expansion belongs to Surfactant.
Application:
Transport infrastructure applications generate recurring bulk demand, while recovery and production segments reward specialized technical service capabilities.
- Pipeline Transportation:Drag reducer injection maintains throughput across continental pipeline networks. Brazil's pre-salt developments require continuous pour-point depression for high wax-content crudes moving through subsea tiebacks. Chemical management contracts bundle these treatments with automated dosing skids.
- Enhanced Oil Recovery:Tertiary recovery projects integrate viscosity-reducing chemistries with CO2 flood operations in mature Permian Basin formations. Operators seek single-accountability partners spanning chemical supply and reservoir engineering.
- Refining:Desalter and tank-bottom treatments prevent asphaltene precipitation during crude preprocessing.
- Production:Wellbore and gathering system treatments address paraffin deposition at the point of extraction.
Pipeline Transportation captures the largest absolute placements; Enhanced Oil Recovery is climbing the fastest.
End User:
Integrated majors consolidate procurement under long-term performance contracts, while independent operators retain spot purchasing flexibility for price-sensitive applications.
- Oil Companies:ExxonMobil, Shell, and BP directly procure flow improvers through multi-year chemical management agreements spanning multiple production basins. Petrobras favors bundled contracts covering Brazil's pre-salt field developments.
- Refineries:Downstream processors source tank farm and desalter additives through separate procurement channels from upstream chemical programs.
- Service Providers:Schlumberger, Baker Hughes, and Halliburton intermediate flow improver supply to operators lacking in-house chemical engineering capabilities.
- Independent Producers:Smaller Permian and Bakken operators purchase drag reducers on spot markets, prioritizing cost over technical integration.
Oil Companies dominate contract value; Service Providers are gaining share fastest through bundled engineering offerings.
Technology:
Chemical formulation platforms mature alongside digital monitoring infrastructure, while environmental and thermal techniques capture premium positioning in regulated or extreme environments.
- Chemical Formulation:Proprietary polymer-surfactant hybrids unify viscosity reduction and wax inhibition into single-treatment chemistries. Gulf of Mexico operators adopt these dual-function formulations where deck space constrains chemical storage.
- Environmental Solutions:Biodegradable surfactant platforms satisfy EPA discharge standards and ANP environmental impact mandates. ECHA REACH restrictions on ethoxylated chemistries are forcing North Sea qualification of next-generation alternatives.
- Thermal Techniques:Heated pipeline segments and hot-oil circulation address ultra-heavy crude transport in mature Venezuelan and Canadian oil sands fields.
- Microbial Treatments:Bio-surfactant production using indigenous reservoir bacteria remains experimental in pilot field trials.
Chemical Formulation holds the dominant installed base; Environmental Solutions show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flow improver procurement concentrates in offshore basins with challenging crude chemistries and stringent environmental protocols. Brazil, the United States, Norway, the United Kingdom, and Saudi Arabia anchor absolute demand through distinct combinations of pre-salt development, mature field management, and regulatory stringency.
Brazil
Petrobras operates continuous pour-point depression programs across pre-salt fields where high wax-content crudes demand specialized chemical injection. ANP environmental impact assessments mandate biodegradable formulation standards for deepwater chemical programs. Santos Basin subsea infrastructure drives bundled chemical management contracts linking treatment supply with automated dosing systems.
United States
Gulf of Mexico deepwater operators expand chemical treatment portfolios to maintain throughput in aging subsea tiebacks. EPA revised discharge standards for produced water favor biodegradable surfactant chemistries over legacy formulations. Houston-Galveston chemical manufacturing clusters supply polymer-based drag reducers, exposing buyers to hurricane-season supply disruption risks.
Norway
North Sea operators prioritize wax inhibition and asphaltene dispersant programs for mature subsea infrastructure approaching end-of-design-life. ECHA REACH authorization timelines restrict ethoxylated surfactant chemistries, accelerating qualification of biodegradable alternatives. Stavanger and Bergen host integrated chemical service hubs serving Norwegian continental shelf developments.
United Kingdom
UKCS decommissioning delays extend chemical treatment requirements for aging pipeline networks and subsea production systems. ECHA REACH compliance documentation burdens favor suppliers with established European regulatory affairs capabilities. Aberdeen maintains concentration of flow assurance engineering specialists commanding premium compensation for subsea chemical program integration.
Saudi Arabia
Saudi Aramco manages chemical injection programs for enhanced oil recovery operations in mature carbonate reservoirs. The kingdom's national petroleum regulator imposes environmental compliance frameworks for offshore chemical discharge in Arabian Gulf waters. Dhahran and Jubail industrial cities host formulation laboratories serving domestic and regional export demand.
Crude Oil Flow Improvers Market Vendor Landscape
Gulf Coast producers anchor one tier; European and Middle Eastern specialists hold differentiated positions through regulatory compliance infrastructure and regional formulation capabilities. The supplier base concentrates around integrated energy service platforms and standalone chemical manufacturers. Three archetypes dominate: diversified energy service conglomerates bundling chemicals with engineering services; pure-play chemical formulators with proprietary polymer-surfactant platforms; and regional specialists capturing ANP-mandated contracts through local compliance infrastructure. Competitive dynamics center on long-term chemical management contract consolidation and qualification speed for biodegradable formulations under tightening discharge standards.
Within the integrated service tier, Baker Hughes, SLB (Schlumberger), and Halliburton Energy Services exemplify archetypes combining chemical supply with subsea monitoring and flow assurance engineering. These entities occupy positions where procurement concentration favors single-accountability partners over spot purchasing arrangements. Their geographic footprints span multiple regulatory jurisdictions, enabling simultaneous EPA, REACH, and ANP compliance documentation. Pure-play chemical specialists including BASF, Clariant, and Evonik Industries represent formulation science capabilities without bundled engineering services, competing on product performance and regulatory registration speed. The competitive boundary between integrated and standalone models is shifting as operators consolidate procurement under performance-based contracts.
| Leading Market Players |
|---|
| Baker Hughes |
| Dorf Ketal |
| BASF |
| Clariant |
| SLB (Schlumberger) |
| Halliburton Energy Services |
| The Lubrizol Corporation |
| Infineum International Limited |
| Evonik Industries |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up specialty chemical formulators anchor Gulf Coast production clusters, concentrating polymer precursor supply within hurricane-exposed corridors while extracting pricing premiums through long-term offtake commitments to integrated majors.
Pricing Analysis
Short lead-time premiums distinguish spot procurement from contract-based arrangements, with Permian Basin independents paying markups for drag reducer availability during upstream chemical procurement cycles. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under EPA, REACH, and ANP compliance frameworks. Cost compression in standard-grade polymer formulations is intensifying because olefin cracking margin volatility feeds into polyalphaolefin precursor economics. Independent producers exhibit highest price sensitivity, while Petrobras and international majors absorb premiums for bundled chemical management contracts.
Supply Chain Analysis
Direct-to-operator channels handle integrated major demand through Houston-Galveston chemical manufacturing clusters, while distributor intermediaries serve spot-purchasing independents in Permian and Bakken corridors. Production concentrates in the United States, Germany, and Brazil, with formulation laboratories anchored in Dhahran and Jubail serving Middle Eastern export demand. Polyalphaolefin and polyacrylamide precursor supply rests on olefin cracking economics tied to natural gas liquids feedstock pricing. Single-source vulnerability runs through Gulf Coast polymer manufacturing exposure to hurricane-season disruption. Distribution runs through long-term chemical management contracts bundling treatment supply with automated dosing skids.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty surfactant formulation capacity constraints prop pricing discipline, as multi-jurisdiction certification timelines for biodegradable alternatives extend commercialization cycles and limit qualified supplier expansion.
For Market Incumbents: Lock in pre-salt chemical management contracts through ANP-compliant formulation capabilities before REACH sunset dates restrict ethoxylated surfactant alternatives. Secure backward integration into polyalphaolefin precursor supply to defend margin position against olefin cracking volatility. Prioritize real-time subsea monitoring integration to differentiate bundled offerings from pure-play chemical competitors. For New Entrants and Emerging Players: Capture biodegradable surfactant qualification opportunities in Brazil's Santos Basin where ANP environmental mandates outpace incumbent registration timelines. Target North Sea operators facing ECHA REACH authorization gaps for ethoxylated chemistries. Lead with regulatory affairs infrastructure as primary go-to-market wedge, positioning ahead of sunset-driven contract renewals. For Investors and Strategic Acquirers: Distressed-cycle entries favor European regulatory affairs specialists with established ECHA documentation capabilities and North Sea operator relationships. Five-to-ten-year viability hinges on biodegradable formulation portfolios displacing legacy surfactant chemistries under tightening discharge standards. Monitor EPA enforcement patterns for produced water discharge as inflection indicator for accelerated qualification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Formulation Qualification | ANP-mandated environmental assessments in Brazil's pre-salt fields favor early movers with registered alternatives. |
| Backward Integration into Polymer Precursors | Captive polyalphaolefin supply insulates margins from Gulf Coast olefin cracking volatility and hurricane disruption. |
| Subsea Monitoring System Integration | Automated dosing skids combined with real-time sensors enable precision treatment cutting chemical volumes for operators. |
| Multi-Jurisdiction Regulatory Infrastructure | Simultaneous EPA, REACH, and ANP compliance capabilities compress competitor commercialization cycles by 18-24 months. |
| Long-Term Chemical Management Contracts | Performance-based bundling of treatment supply with flow assurance engineering displaces spot purchasing among integrated majors. |
Methodological Framework
Independent corroboration across flow assurance engineering directors, chemical procurement leads at integrated majors, subsea system operators, and specialty chemical R&D heads underwrites the qualitative findings. Primary interviews with plant managers at Gulf Coast formulation facilities, distribution channel partners serving Permian Basin independents, and regulatory affairs specialists navigating ECHA timelines combined with secondary validation from customs trade data, SEC 10-K filings, and ANP environmental assessment databases. Bottom-up segmentation modeling and top-down market sizing triangulate volume and value estimates.
Historical reference periods anchored the forecast window to established chemical injection program expansion patterns across pre-salt, North Sea, and Gulf of Mexico developments. Segmentation dimensions modeled include product type tier, application depth, end-user procurement archetype, and regional regulatory cluster. CAGRs derived from production baseline trajectories, tertiary recovery project pipelines, and environmental mandate implementation schedules. Industry-specific inputs encompassed subsea infrastructure age profiles, wax content differentials across crude assays, and biodegradable surfactant qualification timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA enforcement intensity, ECHA substance evaluation acceleration, and ANP mandate expansion beyond current pre-salt coverage. Forecasts reflect assumptions regarding regulatory timeline adherence, feedstock cost continuity, and operator procurement consolidation preferences. Practitioners should monitor biodegradable formulation registration completions, subsea tieback sanctioning rates, and integrated major chemical management contract renewal patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
South Africa Refined Petroleum Products Market
Petroleum Products
East Africa Refined Petroleum Products Market
Petroleum Products
Petroleum Liquid Feedstock Market
Petroleum Products
Germany Refined Petroleum Products Market
Petroleum Products
South Africa Lubricants Market
Petroleum Products
Crude Oil Market
Petroleum Products
Marine Minerals Market
Petroleum Products
India White Oil Market
Petroleum Products
Balanos Oil Market
Petroleum Products
PAG Base Oil Market
Petroleum Products
Quenching Oil Market
Petroleum Products
Oil Refining Market
Petroleum Products
Hydrocarbon Market
Petroleum Products
Alkylate Gasoline Market
Petroleum Products
Petroleum Benzine Market
Petroleum Products
Spindle Oil Market