
 Brazil Oil and Gas Downstream Market | 2026-2036
Brazil Oil and Gas Downstream Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Oil and Gas Downstream Market Outlook
Market Context
Multi-source crude procurement is expanding across Brazil's downstream sector as refiners diversify away from heavy domestic grades. Petroleo Brasileiro SA leverages its integrated upstream-downstream position to sustain captive feedstock supply for its refining network. Shell PLC competes through specialized lubricant and premium fuel formulations targeting fleet operators. Braskem SA anchors petrochemical demand by converting refinery outputs into polyethylene and polypropylene for packaging and automotive industries.
Technical Definition and Structural Segments
Brazil oil and gas downstream encompasses refining, processing, storage, and distribution of crude oil and natural gas into finished fuels and petrochemical feedstocks, with typical refinery complexity measured by the Nelson Complexity Index ranging from 6 to 14 for major facilities. Diesel leads product type output due to freight transport and agricultural machinery consumption, while jet fuel represents the fastest-growing product category as Brazilian aviation traffic rebounds. Industrial end users command the largest margin pool through long-term supply contracts, whereas retail outlets dominate distribution channel volume through Petrobras-branded service stations and independent resellers.
Regulatory Framework and Outlook
ANP regulates fuel specifications, pricing mechanisms, and import quotas, while ANVISA oversees additives and chemical safety standards affecting refinery product formulations. Environmental licensing through IBAMA and state-level environmental agencies constrains greenfield refinery development and mandates emissions controls at existing facilities. Stakeholders must monitor how proposed fuel market liberalization affects import parity pricing and third-party access to Petrobras infrastructure.
Market Dynamics
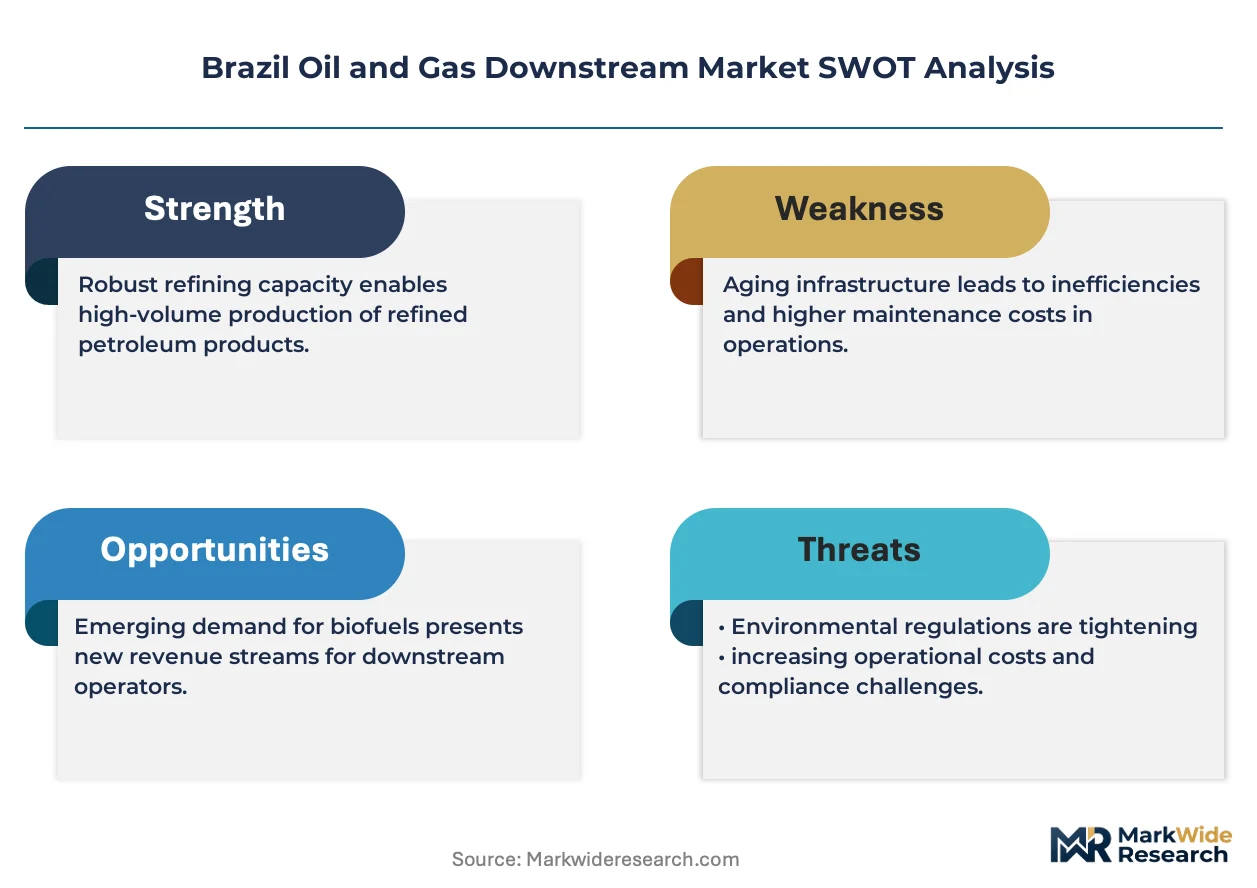
Petrobras's divestment of refining assets under the Fuel of the Future program is fragmenting Brazil's historically concentrated downstream structure. This forced unbundling creates openings for private operators while ANP's new import parity pricing mechanism exposes domestic refiners to international volatility.
Growth Catalysts
- ANP Fuel Quality Specifications:Stricter sulfur limits and biofuel blending mandates are forcing refinery upgrades that expand capacity for higher-margin clean products. Industrial buyers in São Paulo's manufacturing belt are locking in long-term supply contracts to secure compliant fuel streams.
- Pre-salt Crude Diversification:Lighter domestic crude grades are enabling refiners to optimize yield slates toward middle distillates. This feedstock flexibility supports margin expansion at complexes configured for variable crude diets.
- Southeast Industrial Cluster Concentration:Petrochemical demand from the ABC Paulista region absorbs growing volumes of refinery naphtha and aromatics. Pipeline connectivity between refining and chemical processing infrastructure minimizes logistics costs for integrated operators.
Market Restraints
- Import Parity Pricing Exposure:ANP's pricing mechanism ties domestic fuel values to international benchmarks, compressing margins when global crack spreads narrow. Refiners lack tariff protection against subsidized imports from regional competitors.
- Greenfield Licensing Friction:IBAMA environmental approvals for new refining capacity face multi-year timelines and judicial challenges. This constraint perpetuates dependence on aging facilities with higher emissions profiles and lower conversion efficiency.
- Natural Gas Substitution:Industrial boilers and captive power generation in Minas Gerais and Rio de Janeiro are switching to pipeline gas where distribution infrastructure exists. This fuel switching erodes residual fuel oil demand from traditional refinery output baskets.
Strategic Opportunities
- Northeast Regional Supply Gap:The Recife-Fortaleza corridor lacks sufficient refining capacity to serve growing agricultural and fishing fleet demand. Greenfield storage terminals and import facilities can capture this geographic arbitrage.
- Renewable Diesel Co-processing:Hydrotreating units at existing refineries can accept vegetable oil and animal fat feedstocks to produce drop-in renewable diesel. ANP's RenovaBio credit mechanism rewards operators with tradable decarbonization certificates.
- Third-Party Terminal Access:Petrobras's infrastructure divestiture includes coastal storage and pipeline networks. Independent traders and distributors can secure throughput agreements that were previously unavailable under integrated monopoly structures.
Industry Challenges
- Specialized Refining Engineering Talent:Brazil's technical universities produce insufficient process engineers with hydrocracking and coking unit expertise. Operators compete for the limited pool of professionals with experience in complex conversion facilities.
- ANP Certification Timelines:Product quality registrations and import authorization approvals extend operational lead times for new market entrants. Delays in laboratory testing and documentation review constrain supply chain responsiveness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Oil and Gas Downstream Market |
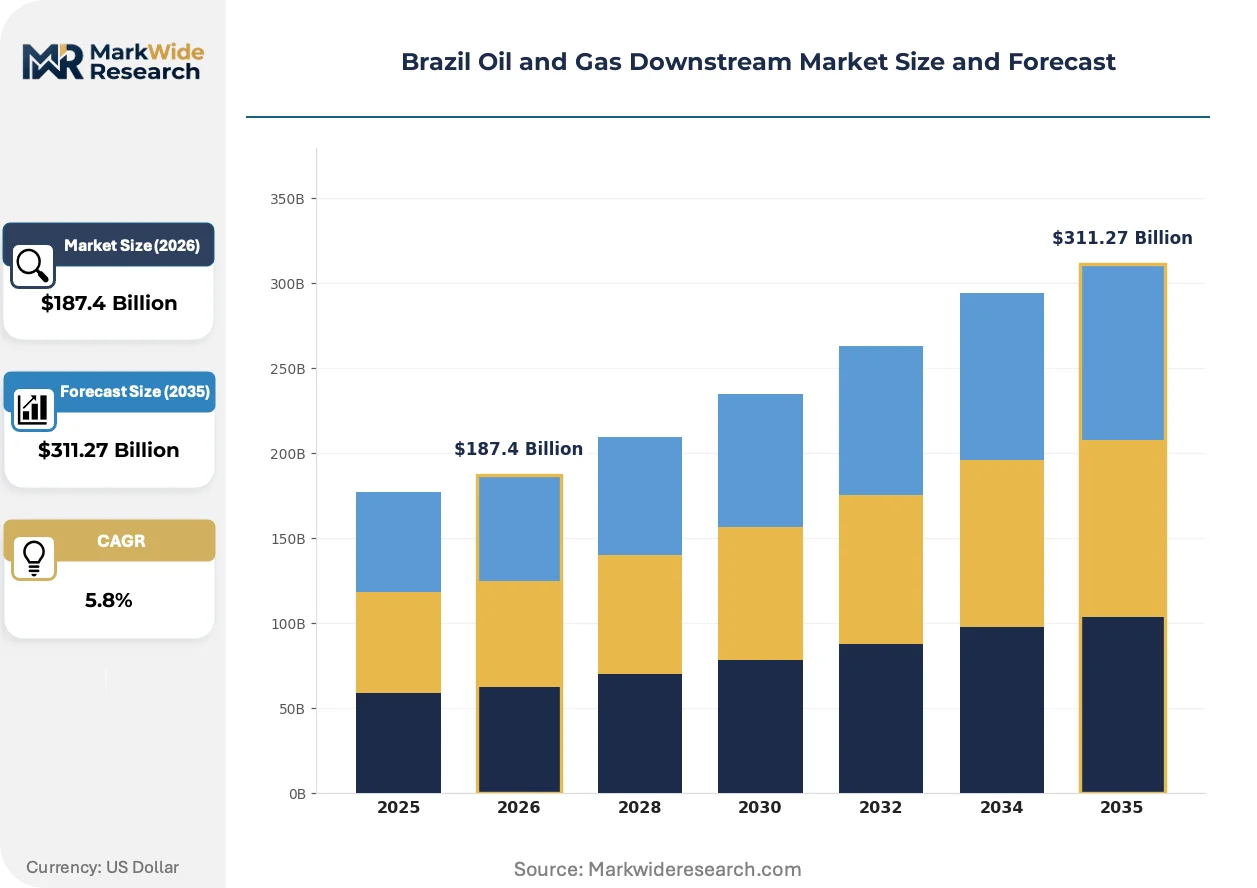
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $311.27 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gasoline, Diesel, Jet Fuel, Liquefied Petroleum Gas End User: Transport, Residential, Commercial, Industrial Distribution Channel: Retail Outlets, Commercial Supplies, Exports, Direct Sales Storage Type: Above Ground Tanks, Underground Tanks, Pipelines, Terminals |
| Companies Covered | Petroleo Brasileiro SA, Shell PLC, Repsol SA, Refinaria de Petróleo Riograndense SA, Chevron Corporation, Exxon Mobil Corporation, Braskem SA, BP plc, TotalEnergies SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Oil and Gas Downstream Market Strategic Shifts
Digitization of refinery operations and biofuel integration are converging to reshape Brazil's fuel production economics. These shifts alter both capital allocation patterns and competitive positioning across the value chain.
Modular renewable fuel processing units are decentralizing Brazil's downstream infrastructure geography. Agricultural cooperatives in Mato Grosso and Goiás are installing small-scale hydrotreaters at existing biodiesel facilities to produce renewable diesel for captive fleet consumption. This distributed production model bypasses traditional coastal refinery concentration and captures feedstock proximity advantages.
ANP's RenovaBio program mandates annual carbon intensity reduction targets for fuel distributors, with compliance verified through a national certification system. This obligation forces refiners to reconfigure product slates toward lower-carbon alternatives or purchase credits from biofuel producers. The policy most heavily impacts gasoline marketers in the Southeast, where urban air quality standards intensify enforcement scrutiny.
Fleet operators in São Paulo's logistics corridor are consolidating fuel purchasing through direct refinery offtake agreements rather than retail network procurement. Large transport companies negotiate volume commitments that bypass branded service station margins and secure dedicated storage capacity. This disintermediation concentrates buying power among the top twenty freight operators and compresses distributor margins in the country's most valuable fuel market.
Brazil Oil and Gas Downstream Market Segmentation
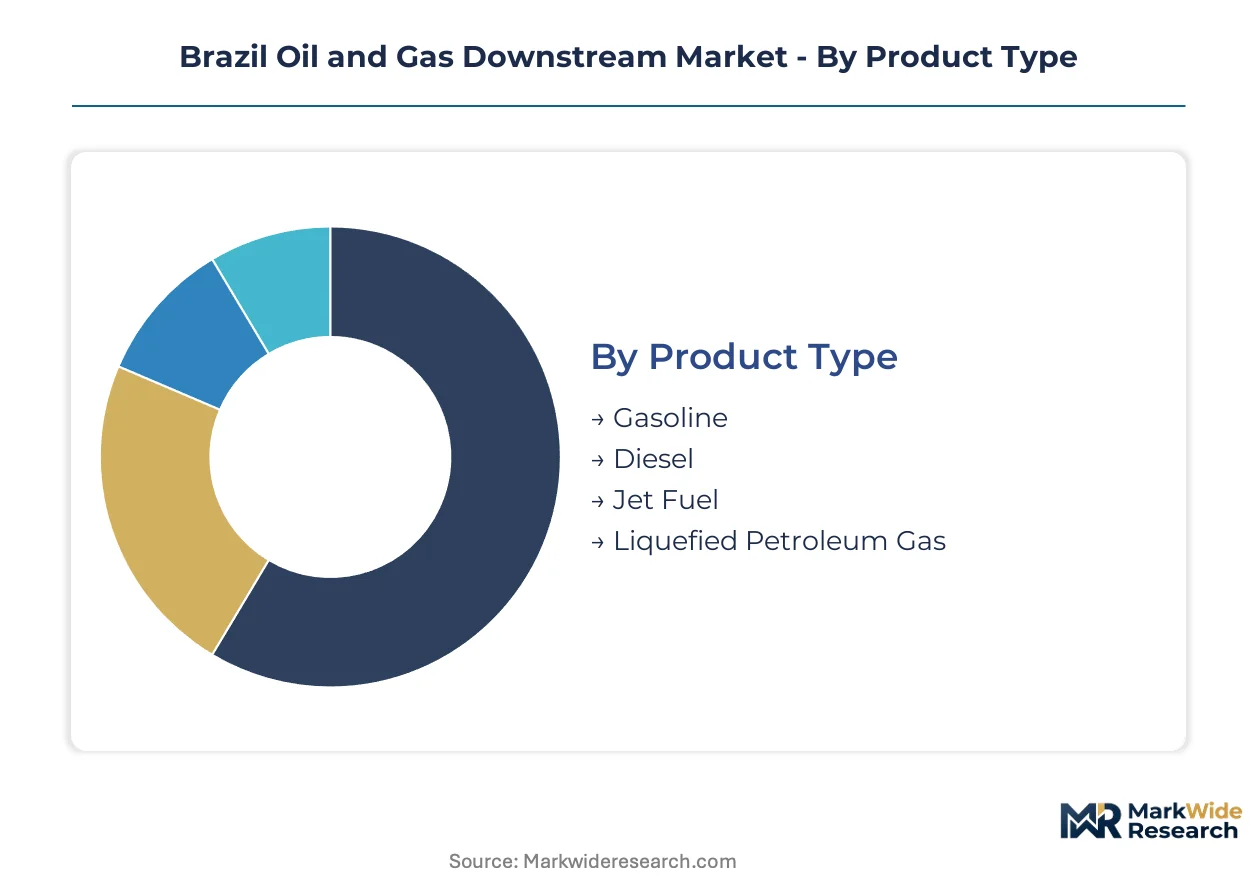
Segmentation in Brazil's downstream oil and gas market reveals how product flows, customer requirements, and infrastructure constraints create distinct competitive arenas. Each dimension—product type, end user, distribution channel, and storage configuration—carries unique margin profiles and regulatory exposure that shape operator strategies.
Product Type:
Integration depth varies sharply across fuel categories, with some products moving through standalone distribution networks while others require embedded refinery-to-consumer infrastructure.
- Diesel:High-cetane middle distillate formulated for compression-ignition engines across freight, agricultural, and marine applications. Demand concentrates in Mato Grosso's soybean belt and São Paulo's trucking corridors, where ANP sulfur specifications now mandate 10 ppm maximum content. Fleet operators in these regions are locking in direct refinery contracts to secure compliant supply.
- Gasoline:Light distillate blended with anhydrous ethanol under ANP's mandatory E27 specification, requiring integrated distribution with biofuel producers. São Paulo's urban vehicle fleet absorbs the largest volumes, with compliance verified through the national RenovaBio certification system.
- Jet Fuel:Kerosene-based aviation turbine fuel meeting strict smoke point and freeze point specifications for commercial air transport. Brazilian carriers at Guarulhos and Galeão international airports drive procurement.
- Liquefied Petroleum Gas:Propane-butane mixture distributed in pressurized cylinders for residential cooking and industrial heating. Bottled delivery networks in Northeast Brazil serve off-grid households.
Diesel leads volumes today; jet fuel is gaining share fastest as aviation traffic rebounds.
End User:
Cost tier differentiation separates mass-market consumers from premium-contract industrial buyers, with pricing power concentrated at the top of the value chain.
- Industrial:Large-scale manufacturing and process industries purchasing fuel through term contracts with volume commitments and dedicated storage. Petrochemical complexes in the ABC Paulista region anchor naphtha and aromatics offtake, while Minas Gerais steel mills procure residual fuel oil for captive power generation.
- Transport:Fleet operators and individual vehicle owners consuming refined products through retail networks or direct procurement. São Paulo's consolidated logistics sector is bypassing branded stations through refinery direct agreements.
- Commercial:Service businesses, retail establishments, and hospitality operators with moderate-volume, spot-market purchasing patterns.
- Residential:Household consumers primarily of LPG for cooking, with price sensitivity shaped by government subsidy mechanisms.
Industrial buyers command the highest margins; transport volume is expanding most quickly through fleet consolidation.
Distribution Channel:
Geographic concentration of infrastructure determines channel viability, with coastal refining hubs enabling export flows while interior markets rely on pipeline and terminal networks.
- Retail Outlets:Branded and independent service stations dispensing fuels to individual consumers and small fleets. The Petrobras divestiture program is fragmenting this channel as new operators acquire formerly integrated assets.
- Direct Sales:Refinery-to-consumer contracts eliminating intermediary margins for large-volume purchasers. Agricultural cooperatives in Goiás and Mato Grosso are migrating to this channel for diesel procurement.
- Commercial Supplies:Bulk deliveries to industrial facilities with on-site storage, common in Rio de Janeiro's manufacturing belt.
- Exports:International sales of surplus refined products, primarily from Petrobras complexes with coastal marine terminals.
Retail outlets dominate transaction volume; direct sales are climbing the fastest as buyer consolidation accelerates.
Storage Type:
Supply concentration in coastal refining zones creates infrastructure bottlenecks, with storage configuration determining market access for inland consumers.
- Terminals:Large-scale coastal and riverine facilities with marine loading capabilities and pipeline connectivity. The Suape and Itaqui terminals in Northeast Brazil are critical for regional supply security.
- Pipelines:Dedicated product transmission systems linking refineries to demand centers, with the São Paulo-Rio de Janeiro corridor representing the most heavily utilized route.
- Above Ground Tanks:Atmospheric storage for clean products at refineries, terminals, and industrial consumer sites.
- Underground Tanks:Subsurface storage at retail stations and strategic petroleum reserve facilities, with ANP-mandated leak detection systems.
Terminals lead installed capacity; pipeline infrastructure is expanding most quickly to serve interior agricultural demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's petrochemical cluster commands the largest downstream throughput in Brazil, absorbing refinery naphtha and aromatics for polyethylene and polypropylene production. The Southeast region concentrates refining capacity, pipeline infrastructure, and industrial demand in a tight geographic corridor.
São Paulo
The ABC Paulista region anchors petrochemical conversion, with Braskem SA complexes consuming refinery outputs for packaging and automotive supply chains. ANP's local content requirements mandate domestic feedstock sourcing for chemical processors. Pipeline connectivity between refineries and chemical plants in Cubatão minimizes logistics costs for integrated operators.
Rio de Janeiro
The state's refining hub processes pre-salt crude grades for middle distillate optimization. Petrobras operates conversion facilities configured for variable crude diets. The Duque de Caxias complex supplies jet fuel to Galeão International Airport as aviation traffic rebounds.
Minas Gerais
Steel mills in Belo Horizonte's industrial belt procure residual fuel oil for captive power generation. Natural gas substitution from pipeline networks is eroding traditional fuel oil demand. State environmental agencies enforce IBAMA-mandated emissions controls at industrial boiler installations.
Bahia
The Northeast's agricultural and fishing fleets drive diesel demand through the Recife-Fortaleza corridor. Greenfield storage terminals are capturing geographic arbitrage from insufficient regional refining capacity. ANP fuel quality specifications now mandate 10 ppm sulfur maximum for highway diesel statewide.
Rio Grande do Sul
Refinaria de Petróleo Riograndense SA operates the southernmost conversion complex, serving soybean belt machinery and freight corridors. The state's proximity to Mercosur markets positions it for potential export flows. Petrobras infrastructure divestiture includes coastal storage assets accessible to independent distributors.
Brazil Oil and Gas Downstream Market Competitive Environment
Global majors compete with regional champions across feedstock procurement and product specialization in Brazil's downstream sector. The market structure fragments between integrated state-affiliated operators, international oil companies with lubricant and premium fuel positions, and independent petrochemical converters. Three archetypes dominate: upstream-integrated refiners with captive crude supply, specialty product marketers leveraging brand differentiation, and chemical processors backward-integrated into refinery offtake. Competitive moves center on infrastructure divestiture acquisitions and renewable fuel co-processing capacity additions.
Within the integrated refiner tier, Petroleo Brasileiro SA exemplifies the state-affiliated archetype with upstream-downstream coordination. Shell PLC and BP plc occupy positions among international oil companies competing through specialized formulations. Braskem SA anchors the petrochemical converter segment, representing downstream integration into chemical manufacturing.
| Leading Market Players |
|---|
| Petroleo Brasileiro SA |
| Shell PLC |
| Repsol SA |
| Refinaria de Petróleo Riograndense SA |
| Chevron Corporation |
| Exxon Mobil Corporation |
| Braskem SA |
| BP plc |
| TotalEnergies SE |
| Others |
Value Chain & Pricing Dynamics
Captive refinery-to-petrochemical integration anchors both supply security and pricing power for Brazilian downstream operators. Petrobras's pipeline networks between Cubatão refining complexes and ABC Paulista chemical plants lock in feedstock flows that competitors cannot replicate, while ANP's import parity mechanism exposes independent refiners to international volatility they cannot hedge.
Pricing Analysis
Crude cost pass-through dominates Brazilian fuel pricing, with ANP's import parity formula tying domestic values to international benchmarks. Price differentiation separates premium low-sulfur diesel for São Paulo's urban fleet from standard highway grades for agricultural buyers. Pricing pressure stems from subsidized regional imports eroding refinery margins. Industrial offtakers show lowest price sensitivity through long-term contracts, while retail consumers face highest exposure to spot volatility.
Supply Chain Analysis
Dual-sourcing requirements from ANP and industrial buyers mandate multi-supplier qualification across crude feedstock and refined product procurement. Geographic supply concentration centers on domestic pre-salt grades and West African light crudes, with U.S. Gulf Coast middle distillates filling seasonal gaps. Raw material dependencies include heavy crude for coking units, naphtha for petrochemical crackers, and ethanol for gasoline blending. Single-source vulnerability runs through Petrobras-controlled coastal terminals. Distribution runs through pipeline corridors linking Southeast refining hubs to interior demand centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's downstream market rewards geographic arbitrage between Northeast supply deficits and Southeast refining overcapacity, with ANP fuel specifications creating compliance cost differentials across state boundaries.
For Market Incumbents: Lock in backward integration into pre-salt crude supply through dedicated offtake agreements with upstream operators. Secure pipeline capacity rights to ABC Paulista petrochemical complexes before infrastructure divestiture closes access. Defend against renewable diesel co-processors by accelerating hydrotreater upgrades for biofeedstock flexibility.
For New Entrants and Emerging Players: Independent storage terminal operators in the Recife-Fortaleza corridor offer the most penetrable entry point, with ANP-mandated sulfur specifications forcing legacy fleet upgrades that expand addressable market. Agricultural cooperatives in Mato Grosso seeking direct diesel procurement present a channel partner archetype bypassing branded retail networks.
For Investors and Strategic Acquirers: Consolidation pressure builds where Petrobras divestiture fragments formerly integrated assets into sub-scale operations unable to achieve conversion efficiency. Target acquisition archetypes include coastal terminals with marine loading capabilities and hydrotreating units configurable for renewable diesel. Watch ANP licensing timelines as the inflection signal—accelerated approvals would unlock stranded capacity valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Diesel Co-processing | Hydrotreater retrofits at Duque de Caxias capture RenovaBio credits for decarbonization certificates. |
| Third-Party Terminal Access | Throughput agreements at Suape and Itaqui terminals bypass Petrobras monopoly structures for independent distributors. |
| Direct Refinery Offtake Agreements | São Paulo fleet operators consolidate purchasing power through volume commitments that eliminate retail margins. |
| Northeast Storage Buildout | Greenfield terminals in Recife-Fortaleza corridor capture geographic arbitrage from regional refining deficits. |
| Pre-salt Crude Integration | Captive feedstock supply from Búzios and Mero fields insulates refiners from international price volatility. |
Study Parameters
Multiple input streams — regulatory filings with ANP and IBAMA, refinery operational disclosures, and petrochemical offtake contracts — were reconciled to construct supply-demand balances across the Brazilian downstream sector. Primary interviews with refinery operations managers, ANP compliance officers, petrochemical procurement leads, and fuel distribution channel heads were cross-validated against secondary sources including ANP statistical bulletins, Petrobras investor disclosures, and Brazilian customs trade data. Bottom-up capacity modeling and top-down demand projection triangulation ensured segment-level consistency.
Data-stream reconciliation across the projection horizon applied Nelson Complexity Index benchmarking to derive refinery margin sensitivities. Segmentation dimensions modeled include product type, end-user category, distribution channel, and storage configuration. CAGRs were derived from volume trajectory analysis incorporating ANP fuel specification phase-in schedules and RenovaBio credit market development. Forecast inputs included aviation traffic recovery patterns at Guarulhos and Galeão, plus agricultural diesel demand elasticity in Mato Grosso's soybean belt.
Revisions become necessary when ANP licensing timelines accelerate or stall, import parity pricing mechanisms shift, or pre-salt crude production profiles deviate from upstream guidance. Deviation in RenovaBio carbon intensity targets would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
China Oil and Gas Downstream Market
Offshore Oil and Gas
Egypt Oil and Gas Upstream Market
Offshore Oil and Gas
Asia-Pacific Offshore Energy Market
Offshore Oil and Gas
Deepwater Subsea Structure Integrity Acoustic Test Platforms Market
Offshore Oil and Gas
Nigeria Oil and Gas Downstream Market
Offshore Oil and Gas
Gulf of Mexico Subsea Systems Market
Offshore Oil and Gas
Oman Oil and Gas Market
Offshore Oil and Gas
Oil Rig Market
Offshore Oil and Gas
United Kingdom Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
Kuwait Oil and Gas Downstream Market
Offshore Oil and Gas
Denmark Oil and Gas Market
Offshore Oil and Gas
Iran Oil and Gas Downstream Market
Offshore Oil and Gas
Abyssinian Oil Market
Offshore Oil and Gas
Asia Pacific Oil and Gas CAPEX Market
Offshore Oil and Gas
Global Mobile Offshore Drilling Units Market
Offshore Oil and Gas
Marine Scrubber Market