
 Asia-Pacific Lubricants Market | 2026-2036
Asia-Pacific Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Lubricants Market Outlook
Direct-to-fleet distribution in India and Indonesia is rewriting lubricant procurement economics across the Asia-Pacific region. Sinopec leverages its captive refinery network to anchor supply contracts with state transport utilities. Shell plc competes through branded service bay partnerships that extend technical support to independent workshops. BP plc (Castrol) differentiates via motorsport-derived synthetic formulations that occupy premium positioning in Southeast Asian markets.
Lubricants are formulated fluids comprising base oils and additive packages engineered to reduce friction, dissipate heat, and prevent wear in mechanical systems, with viscosity grades typically spanning ISO VG 32 through 680 for industrial applications and SAE 0W-16 through 20W-50 for automotive engines. Their primary commercial purpose centers on extending equipment life intervals and maintaining energy efficiency in combustion engines, transmissions, and hydraulic circuits. Engine oil formulations dominate value generation across the region due to high replacement frequency in passenger and commercial vehicle parc, while synthetic lubricants represent the fastest-growing formulation category as OEM drain interval specifications lengthen and energy efficiency regulations tighten. Industrial machinery applications sustain substantial volume demand from steel, cement, and power generation installations, though margin pools remain thinner than automotive channels due to concentrated buyer power among plant operators.
China's SAMR enforces GB standards that mandate minimum performance benchmarks for lubricants sold into domestic automotive and industrial channels, while India's BIS certification requirements create compliance barriers for unqualified importers. Japan's METI promotes JIS-aligned lubricant specifications that influence procurement criteria across Northeast Asian manufacturing supply chains. Stakeholders must monitor how China's dual carbon goals and India's PLI scheme for advanced chemistry cell manufacturing reshape base oil demand patterns and additive formulation priorities across the region.
Market Dynamics
Synthetic lubricant formulations are displacing mineral-based products across Asia-Pacific automotive and industrial channels as OEM drain interval specifications lengthen and China's GB standards tighten base oil quality thresholds.
Growth Catalysts
- Automotive OEM Procurement Programs:Thailand and Indonesia fleet operators are expanding volume commitments to synthetic formulations through state transport utility contracts.
- BIS Lubricant Standards:India's certification requirements are forcing reformulation investments that upgrade domestic base oil quality across the western industrial belt.
- Dual Carbon Goals:China's energy efficiency mandates are accelerating synthetic adoption in eastern manufacturing corridors where process industries anchor bulk offtake.
Market Restraints
- Group II/III Base Oil Supply Concentration:Northeast Asian refinery capacity constraints create input cost volatility for lubricant blenders serving India's western industrial belt.
- Reformulation Capex Burden:Small-scale Indian blenders face technical limitations in meeting BIS additive package specifications without third-party technical partnerships.
- SAMR Compliance Timelines:China's GB standards update cycles create regulatory friction for importers lacking in-country testing infrastructure.
Strategic Opportunities
- Indonesian Direct-to-Fleet Distribution:Bypassing traditional distributor networks opens margin capture for blenders with logistics capabilities in the archipelago's commercial vehicle corridors.
- PLI Scheme for Advanced Chemistry:India's production-linked incentive framework creates regulatory tailwind for domestic additive manufacturing investments.
- Digital Oil Condition Monitoring:Sensor-integrated lubricant systems enable technology convergence between fluid formulations and predictive maintenance platforms in Chinese steel and cement installations.
Industry Challenges
- Formulation Chemist Scarcity:India's lubricant industry faces talent gaps in tribology and additive chemistry expertise needed for BIS-compliant synthetic development.
- Legacy Equipment Compatibility:Southeast Asian fleet operators encounter integration complexity when introducing low-viscosity synthetics into aging commercial vehicle parc.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Lubricants Market |
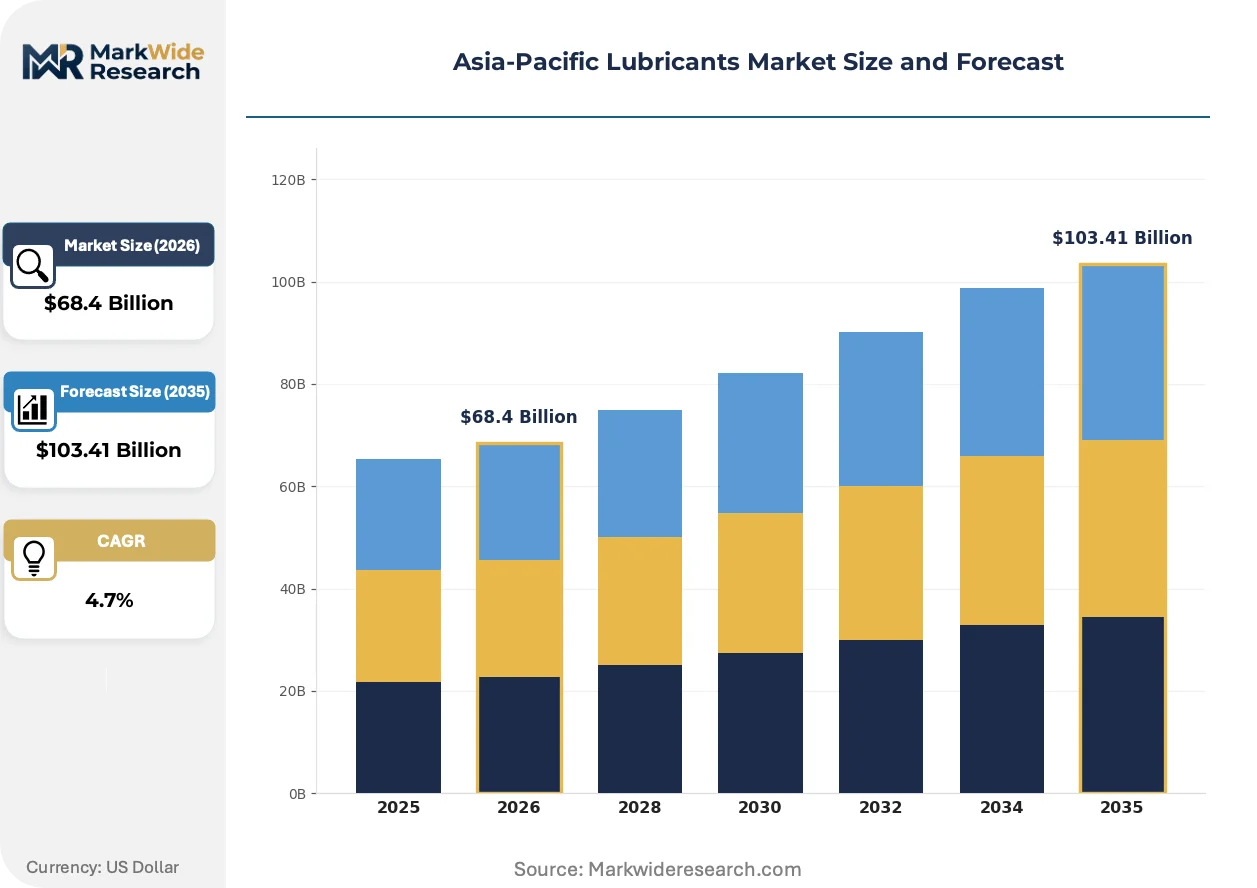
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $103.41 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Hydraulic Oil, Gear Oil, Greases Application: Automotive, Industrial Machinery, Marine, Aviation Formulation: Synthetic, Mineral, Bio-based, Blended End User: OEMs, Aftermarket Providers, Distributors, Retailers |
| Companies Covered | BP plc (Castrol), ENEOS Holdings, Shell plc, TotalEnergies SE, Chevron Corporation, China Petroleum & Chemical Corporation (Sinopec), China National Petroleum Corporation (PetroChina), Petroliam Nasional Berhad (PETRONAS), ExxonMobil Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Lubricants Market Strategic Shifts
Digital fluid monitoring platforms, regulatory tightening on base oil quality, and direct procurement relationships between blenders and large fleet operators are compressing traditional channel structures across the region.
Artificial intelligence-driven oil analysis systems are virtualizing the traditional laboratory testing workflow for lubricant condition assessment. Japanese steel mills and Chinese power generation operators are adopting cloud-connected sensor arrays that transmit viscosity and contamination data in real time. This capability is virtualizing the role of periodic manual sampling, compressing maintenance intervals and displacing third-party laboratory service contracts.
China's SAMR is enforcing updated GB standards that mandate minimum performance benchmarks for lubricants sold into domestic automotive channels. The industrial consequence is a phased elimination of Group I base oils from certified formulations over the coming compliance windows. Northeast Asian manufacturing supply chains are responding by accelerating Group II and III capacity investments to secure qualified feedstock positions.
Fleet operators across Thailand and Indonesia are consolidating procurement relationships directly with lubricant blenders, bypassing traditional distributor networks that previously captured 15-20 point margins. State transport utilities in both countries are leading this consolidation through multi-year supply contracts tied to technical support provisions. This pattern is most visible in commercial vehicle segments where annual volume commitments exceed 500,000 liters per fleet entity.
Asia-Pacific Lubricants Market Segmentation
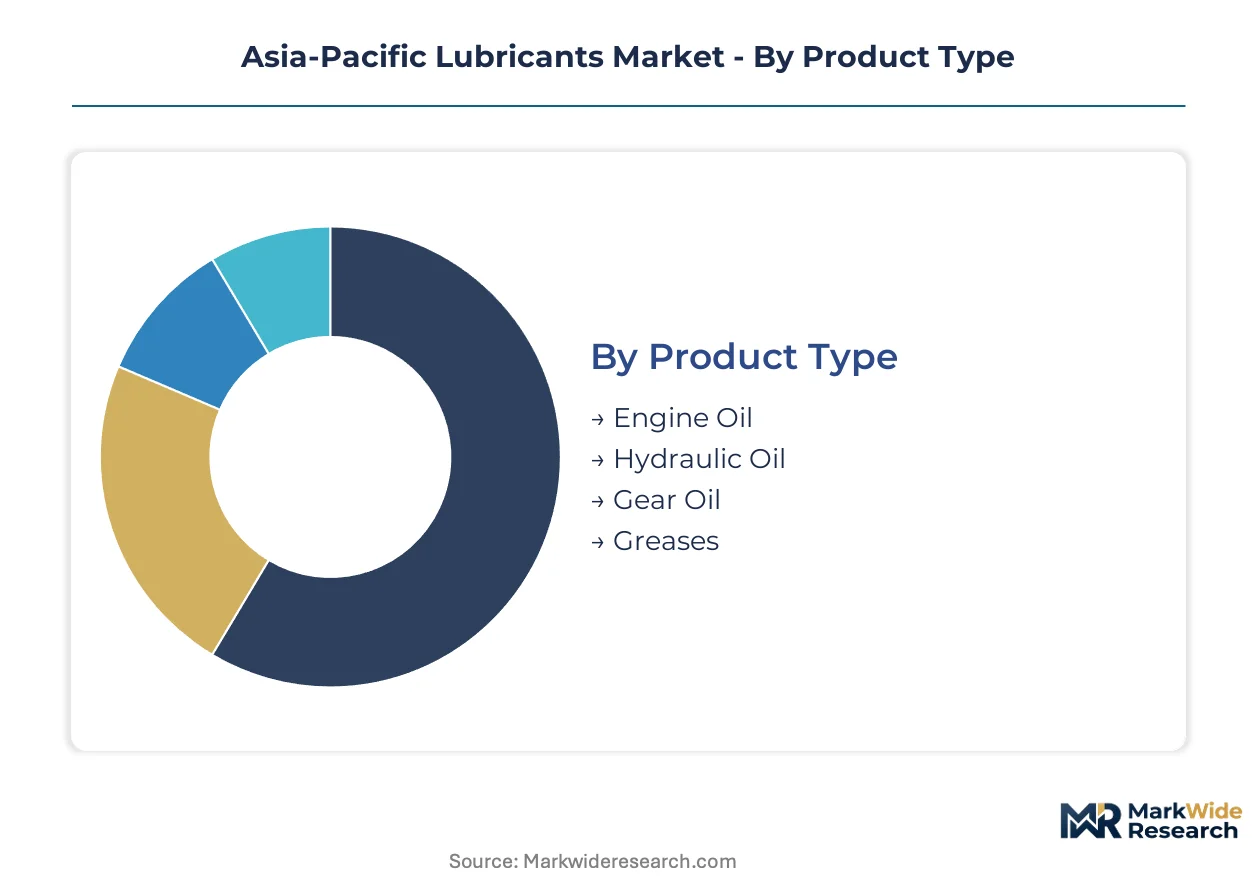
Asia-Pacific lubricant procurement patterns diverge sharply by replacement cadence. Engine oils turn over in months; industrial hydraulic systems run for years. These cycle-time differentials dictate inventory strategies, margin capture, and technical service intensity across the value chain.
Product Type:
Engine oil cycles fastest, requiring quarterly replenishment in high-mileage commercial fleets. Greases sit at the opposite extreme, with relubrication intervals stretching across annual maintenance windows.
- Engine Oil:Formulations span SAE 0W-16 through 20W-50 viscosity grades, blending Group II/III base stocks with detergent-dispersant additive packages. Demand concentrates in India's western industrial belt, where state transport utilities negotiate direct procurement contracts tied to technical support provisions.
- Hydraulic Oil:ISO VG 32 through 68 grades dominate, formulated with anti-wear zinc dialkyldithiophosphate compounds for high-pressure circuit protection. Eastern China's manufacturing corridors anchor bulk offtake from steel and cement installations where equipment uptime priorities override price sensitivity.
- Gear Oil:Extreme-pressure formulations with sulfur-phosphorus chemistry protect differentials and transmissions under boundary lubrication conditions. Marine and heavy commercial vehicle applications in Indonesia's archipelago drive volume.
- Greases:Thickened lubricants combining base oils with lithium or calcium soap matrices deliver sustained protection in sealed bearings and chassis points. Infrequent relubrication cycles compress margin opportunities for blenders.
Engine oil dominates installed base. Hydraulic oil is where expansion concentrates.
Application:
Cost tier differentiation separates commodity automotive volumes from premium industrial and aviation formulations where certification requirements inflate price points.
- Automotive:Passenger and commercial vehicle lubrication spans engine, transmission, and axle applications with drain intervals extending from 5,000 to 50,000 kilometers depending on formulation quality. Thailand's state transport utilities are consolidating procurement through multi-year synthetic supply contracts.
- Industrial Machinery:Steel mills, cement plants, and power generation installations consume circulating oils, compressor lubricants, and turbine fluids in continuous-duty environments. China's dual carbon goals are accelerating synthetic adoption in eastern manufacturing corridors.
- Marine:Cylinder oils and system lubricants for two-stroke crosshead engines operate under high-sulfur fuel combustion conditions. Port concentration in Singapore and Shanghai shapes distribution economics.
- Aviation:Type-certified turbine oils and piston engine lubricants meet strict OEM approvals from airframe and engine manufacturers. Regulatory barriers limit qualified supplier pools.
Automotive generates the highest absolute volumes. Aviation commands the steepest price premiums per liter.
Formulation:
Supply concentration in Group II/III base oil refining capacity constrains formulation choices for regional blenders.
- Synthetic:Polyalphaolefin, ester, and Group III hydrocracked base stocks deliver extended drain intervals and energy efficiency gains. India's BIS standards are forcing reformulation investments as certification thresholds tighten.
- Mineral:Solvent-refined Group I base oils face phased elimination from China's GB-certified formulations under SAMR-mandated performance benchmarks. Legacy equipment compatibility sustains residual demand in aging Southeast Asian fleets.
- Bio-based:Vegetable oil-derived base stocks with synthetic ester modifications offer biodegradability for environmentally sensitive applications. Cost premiums limit penetration to niche marine and forestry equipment segments.
- Blended:Semi-synthetic formulations balance performance upgrade against mineral base cost advantages. Indonesian commercial vehicle operators favor this intermediate tier for mid-life fleet assets.
Mineral formulations retain the largest installed base. Synthetic grades are gaining share fastest.
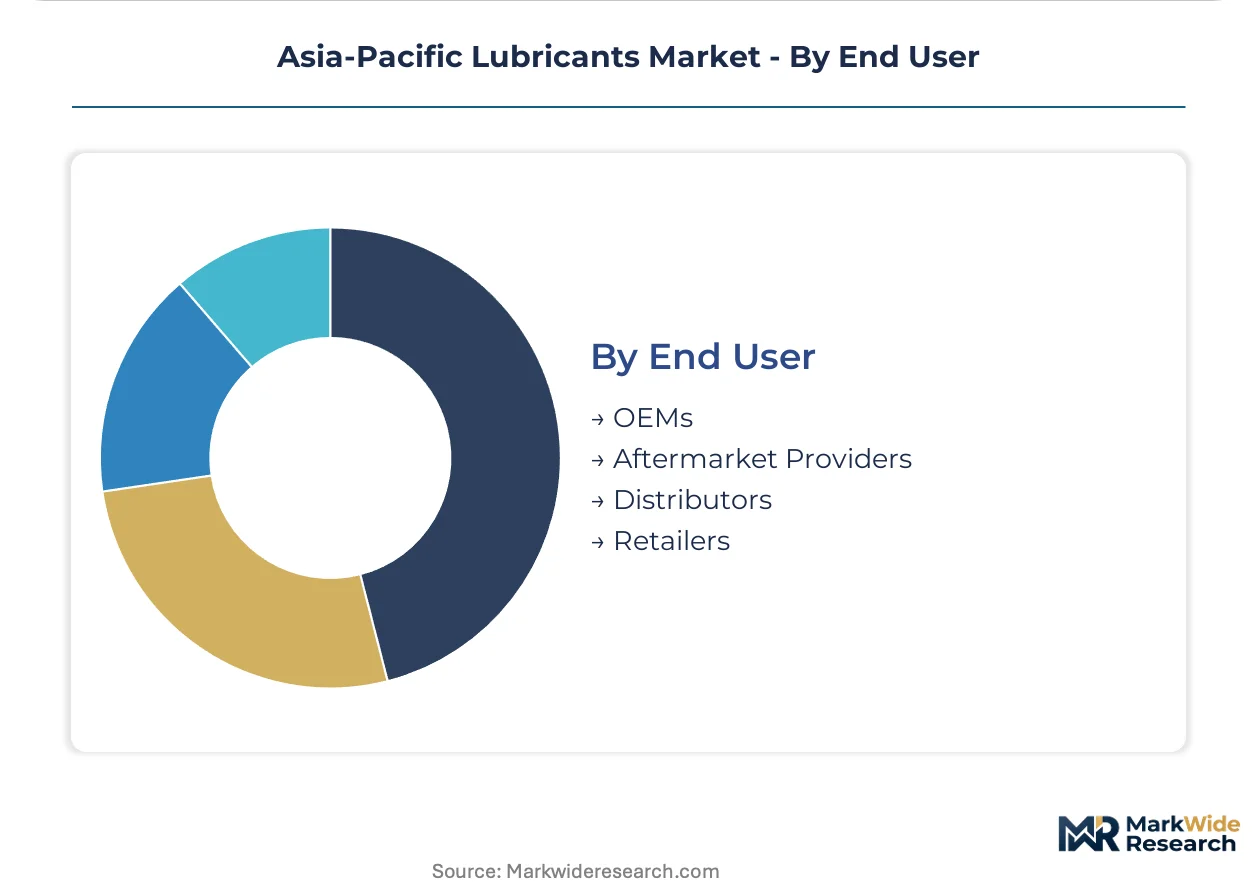
End User:
Customer type determines whether procurement flows through technical specification processes or price-driven spot purchasing.
- OEMs:Vehicle and equipment manufacturers specify factory-fill lubricants against proprietary performance tests, creating multi-year supply agreements with technical partnership obligations. Japanese automotive OEMs extend JIS-aligned specifications across regional manufacturing supply chains.
- Aftermarket Providers:Independent workshops and service chains purchase branded or private-label products for consumer vehicle maintenance. Technical support and training programs differentiate supplier relationships.
- Distributors:Traditional wholesale networks capture margins through inventory holding and credit extension to smaller accounts. Direct-to-fleet consolidation in Thailand and Indonesia is compressing their relevance.
- Retailers:Automotive parts stores and fuel station convenience channels serve DIY consumers with packaged lubricants. Price transparency from e-commerce platforms is squeezing shelf-space economics.
Aftermarket providers dominate transaction frequency. OEMs anchor the most defensible contract positions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern manufacturing corridors command pricing leverage over India's western industrial belt due to concentrated state transport utility procurement and tighter SAMR-mandated base oil quality thresholds. This asymmetry shapes formulation investments across the region.
China
SAMR-enforced GB standards are phasing Group I base oils from certified automotive formulations, forcing blenders toward Group II/III hydrocracked stocks. Dual carbon goals accelerate synthetic adoption in Yangtze River Delta steel mills and Pearl River Delta cement installations. Sinopec leverages captive refinery networks to anchor supply contracts with provincial transport utilities.
India
BIS certification requirements for lubricant additive packages are forcing reformulation investments among domestic blenders. The PLI scheme for advanced chemistry cell manufacturing creates regulatory tailwind for domestic additive production. Maharashtra's western industrial belt concentrates fleet operator demand, with state transport utilities negotiating direct procurement contracts.
Japan
METI-promoted JIS-aligned lubricant specifications influence procurement criteria across Northeast Asian manufacturing supply chains. Japanese automotive OEMs extend factory-fill specifications to regional assembly operations. Kanto region tribology expertise anchors formulation chemistry capabilities for synthetic development.
Thailand
State transport utilities are consolidating procurement through multi-year synthetic supply contracts exceeding 500,000 liters annually per fleet entity. Direct-to-fleet distribution bypasses traditional distributor networks that previously captured 15-20 point margins. Bangkok commercial vehicle corridors anchor volume concentration.
Indonesia
Archipelago logistics challenges favor blenders with integrated distribution capabilities across commercial vehicle corridors. Semi-synthetic formulations dominate mid-life fleet assets. Java-based manufacturing and port infrastructure concentrate blending capacity and bulk offtake.
Asia-Pacific Lubricants Market Competitive Environment
Integrated energy majors and national oil companies split the market between global brand equity and captive refinery economics. The vendor base concentrates around three strategic archetypes: state-linked refiners with backward integration into base oil production, international majors competing through technical service partnerships, and regional specialists exploiting direct fleet relationships. M&A activity targets additive formulation capabilities, while capacity expansion focuses on Group III hydrocracking investments.
Among integrated energy majors, BP plc (Castrol), Shell plc, and Sinopec occupy distinct competitive positions. Castrol represents premium motorsport-derived synthetic positioning in Southeast Asian markets. Shell exemplifies branded service bay partnerships extending technical support to independent workshops. Sinopec anchors the state-linked refiner archetype with captive supply integration into China's transport utility procurement channels.
| Leading Market Players |
|---|
| BP plc (Castrol) |
| ENEOS Holdings |
| Shell plc |
| TotalEnergies SE |
| Chevron Corporation |
| China Petroleum & Chemical Corporation (Sinopec) |
| China National Petroleum Corporation (PetroChina) |
| Petroliam Nasional Berhad (PETRONAS) |
| ExxonMobil Corporation |
| Others |
Value Chain & Pricing Dynamics
The Strait of Malacca shipping corridor anchors bulk base oil movements between Northeast Asian refineries and Indian blending facilities, with freight cost volatility feeding directly into both supply concentration economics and the spread between configured-to-order synthetic formulations and standard mineral products.
Pricing Analysis
The customization-premium spread separates synthetic formulations certified to India's BIS additive specifications from commodity mineral grades. Pricing stratifies across premium synthetic, standard hydrocracked, and economy mineral tiers, with certification grade and volume scale as primary differentiation drivers. Cost compression in economy tiers is intensifying because China's SAMR-mandated GB standards are phasing Group I base oils from automotive channels. Fleet operators in Thailand's state transport utilities demonstrate lowest price sensitivity due to technical support bundling, while independent Indonesian workshops remain most cost-conscious.
Supply Chain Analysis
Extended payment terms from Northeast Asian refinery operators to Indian blenders are compressing working capital cycles across the value chain. Geographic supply concentrates in South Korea, Japan, and Singapore for Group II/III hydrocracked base stocks. Raw material dependencies rest on polyalphaolefin feedstocks, detergent-dispersant additive packages, and anti-wear zinc compounds. Single-source vulnerability around Group III capacity creates structural exposure. Distribution runs through direct-to-fleet contracts in Thailand and Indonesia, bypassing traditional wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
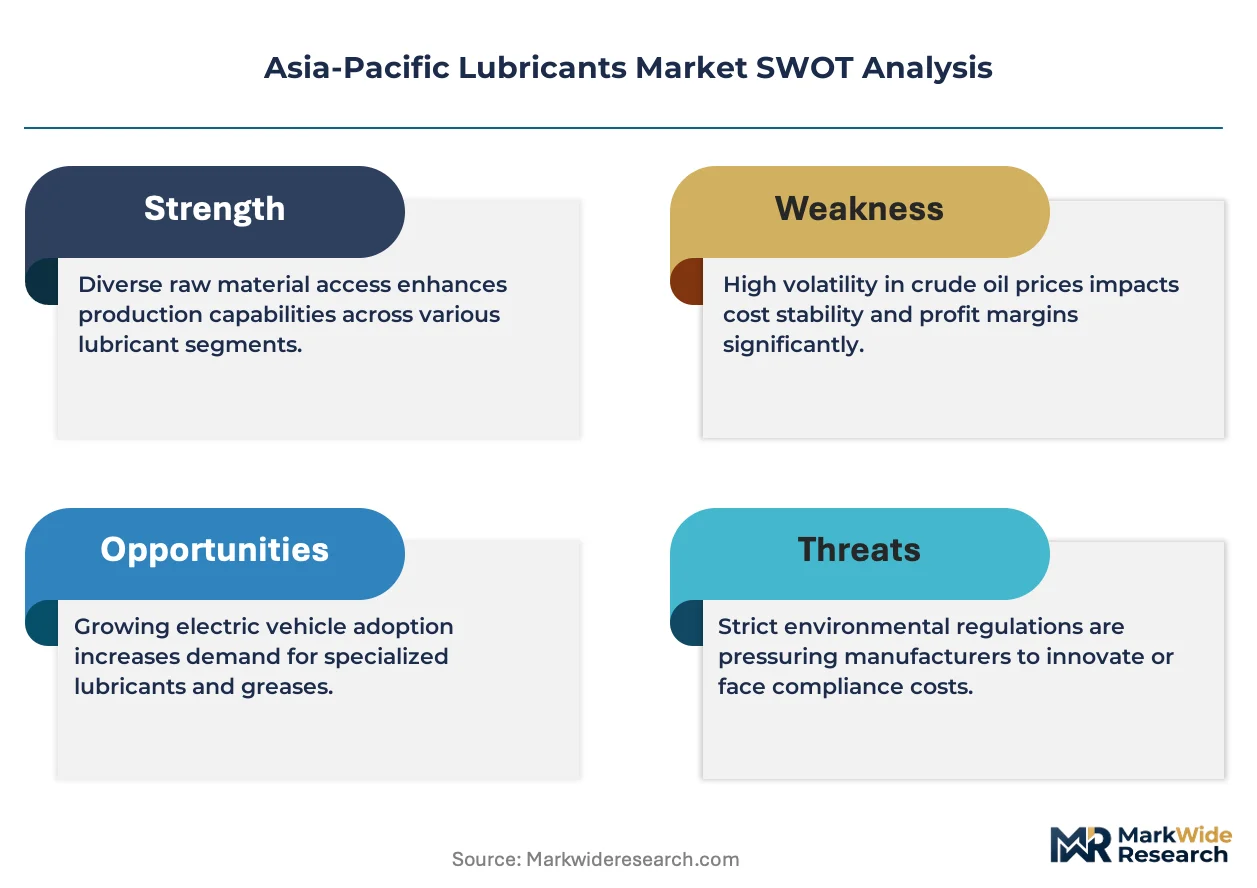
Synthetic lubricant disruption is accelerating across Asia-Pacific as China's dual carbon goals and India's BIS reformulation mandates simultaneously reshape base oil demand and certification requirements.
For Market Incumbents: Insulate market position by deepening captive refinery integration into Group III hydrocracking capacity in Northeast Asian corridors, and accelerate technical service partnerships with Indian state transport utilities before BIS compliance windows tighten. Margin pressure from unqualified importers lacking in-country testing infrastructure threatens established pricing architecture. For New Entrants and Emerging Players: Build out additive formulation capabilities targeting India's western industrial belt, where domestic PLI scheme incentives reduce import dependency for BIS-certified packages. The most penetrable white-space sits in semi-synthetic intermediate tiers for Indonesian mid-life fleet assets. A direct-to-fleet logistics play across Java's commercial vehicle corridors offers viable go-to-market positioning. For Investors and Strategic Acquirers: Regional blenders with backward integration into base oil production and established direct procurement relationships with state transport utilities represent the highest-conviction acquisition archetype. Long-term viability over the coming decade hinges on synthetic formulation chemistry capabilities and regulatory compliance infrastructure. The signal to monitor is BIS certification timeline acceleration and SAMR enforcement intensity across compliance windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Group III Hydrocracking | Sinopec and Korean refiners secure captive feedstock positions against China's GB standard phase-out of Group I oils. |
| Direct-to-Fleet Distribution Buildout | Thai and Indonesian blenders capture 15-20 point margin compression from traditional distributor bypass. |
| PLI-Aligned Additive Manufacturing Investment | Domestic Indian producers leverage production-linked incentives to reduce import dependency for BIS-certified packages. |
| Digital Oil Condition Monitoring Integration | Japanese steel mills and Chinese cement operators virtualize laboratory testing through cloud-connected sensor arrays. |
| Technical Service Partnership Expansion | Shell plc extends branded service bay networks to independent workshops across Southeast Asian markets. |
Study Parameters
A spread of perspectives from lubricant formulation chemists, fleet procurement managers at Thai state transport utilities, refinery operations directors, and aftermarket distribution channel heads converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against BIS certification databases, SAMR GB standard filings, customs trade records for base oil movements, and SEC disclosures from integrated energy majors. Bottom-up volume modeling triangulated against top-down macroeconomic drivers.
Demand-supply-balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled include formulation type, end-use application, base oil grade tier, and regional regulatory cluster. CAGRs derived from elasticity-adjusted volume projections incorporating OEM drain interval specification changes and energy efficiency mandate trajectories. Industry-specific forecast inputs captured PLI scheme implementation pace and dual carbon goal enforcement intensity.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese state-linked refiners or accelerated BIS timeline compression would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Natural Gas Liquid Market
Petroleum Products
Naphtha Market
Petroleum Products
South Africa Lubricants Market
Petroleum Products
Europe Ethane Market
Petroleum Products
Helical Submerged Arc Welded Pipe Market
Petroleum Products
Africa Refined Petroleum Products Market
Petroleum Products
Crude Oil Market
Petroleum Products
Underground Storage Tanks Market
Petroleum Products
Hydrocarbon Market
Petroleum Products
South Africa Petroleum Market
Petroleum Products
North Africa Refined Petroleum Products Market
Petroleum Products
Paraffin Oil Market
Petroleum Products
Pyrolysis Oil Market
Petroleum Products
Malaysia Refined Petroleum Products Market
Petroleum Products
Asia Pacific Base Oil Market
Petroleum Products
Very Low Sulphur Fuel Oil (VLSFO) Market