
 Petcoke Market | 2026-2036
Petcoke Market Size, Share, and Industry Trends Forecast 2026-2036
Petcoke Market Analysis
Aftermarket fuel blending and sulfur treatment service revenue is fragmenting across the petcoke value chain as refiners seek to capture margin from specification upgrades. ExxonMobil Corporation leverages its integrated refining network to control fuel-grade output quality at source. Reliance Industries Limited anchors massive calcination capacity at its Jamnagar complex. Valero Energy Corporation competes through Gulf Coast logistics dominance into Atlantic cement markets.
Petcoke is a carbonaceous solid residue from delayed coking of heavy residual oil fractions, typically containing 80-95% fixed carbon with sulfur content ranging from 1% to over 7% depending on crude feedstock. Its primary commercial purpose centers on high-Btu fuel substitution in cement kilns and as a calcined feedstock for aluminium anode production. Fuel-grade petcoke retains the largest volume position due to persistent cement sector demand across emerging economies, while calcined petcoke commands premium pricing from aluminium smelter technical specifications. Needle coke occupies a specialized niche supplying electric arc furnace graphite electrodes where ultra-low sulfur and low coefficient of thermal expansion properties justify substantial price premiums.
India's Bureau of Indian Standards enforces sulfur and metal content limits on domestic petcoke combustion, directly constraining high-sulfur grade marketability in power and cement applications. The European Chemicals Agency REACH framework and EU Green Deal carbon border adjustments are progressively restricting fuel-grade petcoke imports into European cement and power sectors. Stakeholders must monitor evolving national sulfur caps and carbon border tax implementations to reposition grade portfolios and geographic sales focus before regulatory arbitrage windows close.
Market Dynamics
India's Bureau of Indian Standards sulfur caps and the EU F-Gas Regulation are forcing simultaneous grade upgrades across fuel-grade and calcined product streams. Refiners must now treat sulfur at source or surrender premium cement and aluminium markets to lower-carbon substitutes.
Growth Catalysts
- Domestic infrastructure acceleration:India's cement producers are absorbing larger fuel-grade volumes as highway, rail, and urban construction projects expand kiln operating rates across Gujarat and Maharashtra.
- REACH framework compliance services:European cement and power sectors facing carbon border adjustments are contracting sulfur treatment and certification services to retain limited import quotas.
- Delayed coking capacity expansion:Heavy crude processing upgrades at refineries in Saudi Arabia, Russia, and the United States are expanding fuel-grade petcoke availability for Asian cement markets.
Market Restraints
- Crude sulfur content volatility:High-sulfur crude discounts fluctuate with OPEC+ production decisions, compressing refinery margins and destabilizing fuel-grade output economics.
- Western India refining concentration:Jamnagar and Vadodara clusters control disproportionate calcination capacity, creating single-point vulnerability for aluminium anode supply chains.
- Natural gas substitution:US Gulf Coast cement plants with pipeline gas access are switching feedstock during price troughs, eroding fuel-grade contract volumes.
Strategic Opportunities
- Southeast Asia cement demand:Vietnam, Indonesia, and the Philippines lack domestic calcination infrastructure and import fuel-grade petcoke for clinker production expansion.
- EU Green Deal carbon border adjustment:Certified low-sulfur fuel-grade cargoes command premium pricing into Mediterranean cement terminals as conventional imports face tariff exposure.
- Petcoke-alumina residue blending:Red mud co-processing trials at Indian cement kilns are creating new feedstock specifications that favor high-carbon, controlled-sulfur grades.
Industry Challenges
- Sulfur chemist talent scarcity:Refineries and traders lack personnel capable of navigating simultaneous BIS, REACH, and ISO certification requirements across blended cargo portfolios.
- Calciner retrofit capex cycles:Upgrading rotary kiln burners and gas cleaning systems to meet tightening metal content limits requires 18-24 month commissioning timelines.
- Multi-jurisdiction documentation:Each cargo now requires parallel certificates of analysis for sulfur, vanadium, nickel, and ash content under divergent national testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Petcoke Market |
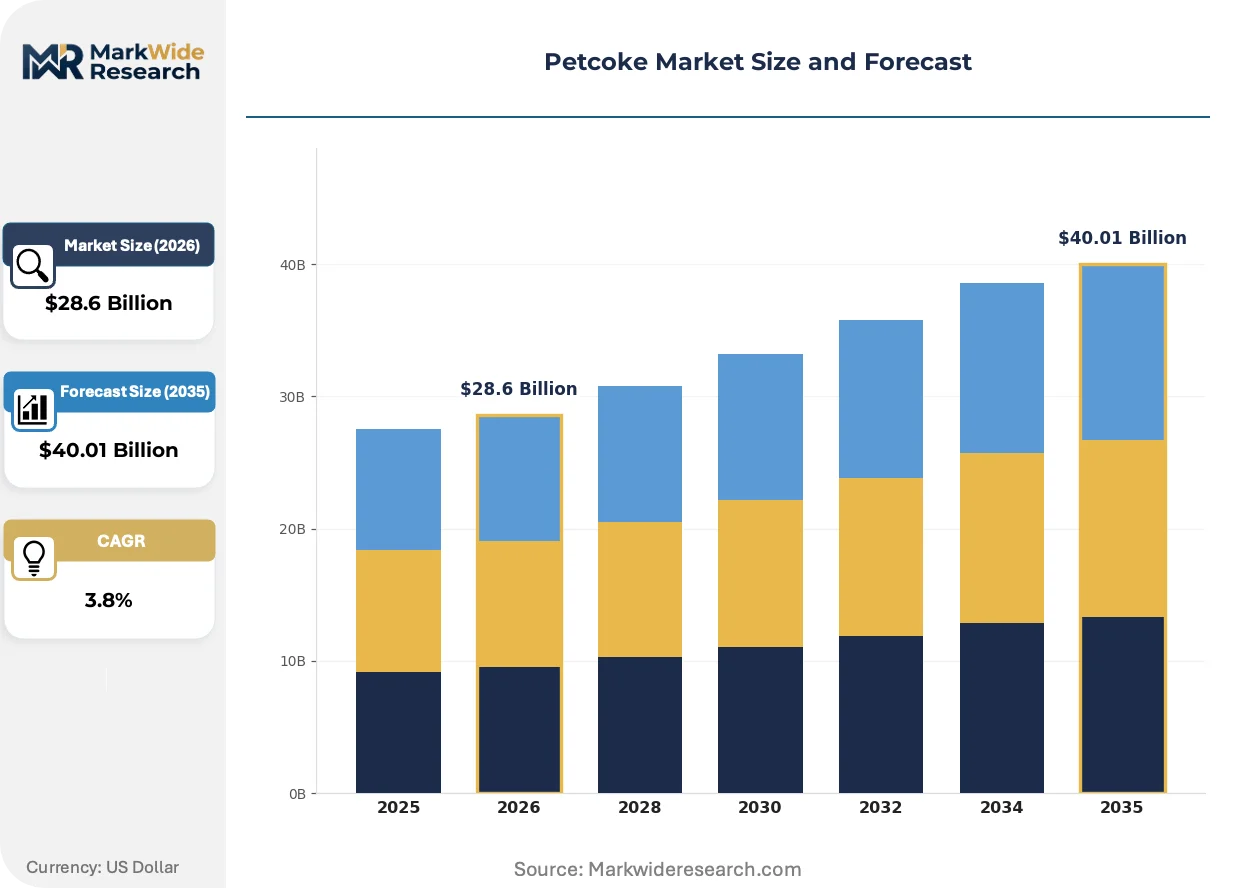
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $40.01 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Green Petcoke, Fuel-Grade Petcoke, Calcined Petcoke, Needle Coke End Use: Cement Industry, Power Generation, Aluminium Industry, Steel Manufacturing Grade: Low Sulfur, High Sulfur, Medium Sulfur, Ultra-Low Sulfur Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | BP plc, Chevron Corporation, ExxonMobil Corporation, Saudi Aramco, Reliance Industries Limited, Phillips 66 Company, Indian Oil Corporation Ltd., Valero Energy Corporation, Oxbow Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Petcoke Market Emerging Trajectories
Digital sulfur monitoring and automated blending systems are compressing quality variance in fuel-grade shipments. Regulatory digitization is accelerating certification turnaround times while reducing manual assay disputes between traders and cement buyers.
Inline X-ray fluorescence analyzers are digitizing real-time sulfur and metals tracking at refinery loading terminals. Indian cement producers with captive power units are installing these systems to pre-qualify cargoes before unloading. The technology is digitizing contract enforcement by replacing laboratory assay disputes with continuous digital certificates of quality.
The EU F-Gas Regulation and REACH authorization lists are tightening metal content thresholds for petcoke combustion residuals. Cement plants in Spain, Italy, and Greece face quarterly reporting obligations that exclude high-vanadium cargoes from carbon credit calculations. Smelter-grade calcined petcoke producers are responding with dedicated low-metal feedstock sourcing from specific Middle Eastern crude slates.
Long-term offtake contracts with fixed sulfur bands are displacing spot market purchases at major cement groups. UltraTech, Shree Cement, and Dalmia Bharat in India are consolidating procurement through annual tenders with penalty clauses for quality deviation. This concentration is most visible in Gujarat and Rajasthan states where kiln clusters negotiate collective volumes against Jamnagar refinery output.
Petcoke Market Segmentation
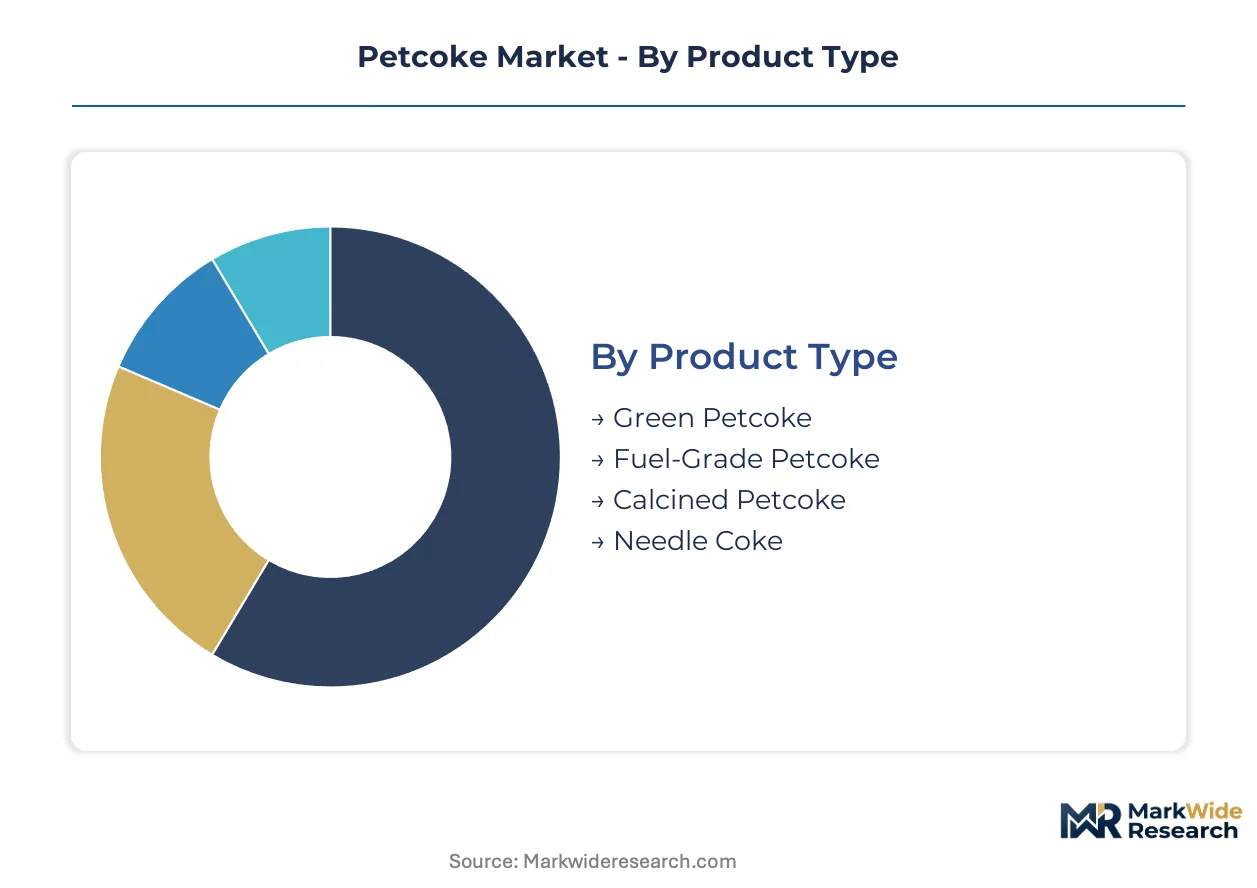
Petcoke segmentation tracks divergent sulfur tolerances across cement kilns, aluminium smelters, and power boilers. Each grade commands distinct pricing bands tied to crude slate origin and calcination intensity. Procurement teams negotiate annual contracts around these technical boundaries.
Product Type:
Refinery coking units output distinct carbon structures based on feedstock heaviness and thermal severity.
- Green Petcoke:Raw delayed coker output containing 8-12% volatile matter and uncontrolled sulfur levels. Indian cement plants in Gujarat absorb volumes directly from Jamnagar refineries for on-site blending and combustion.
- Fuel-Grade Petcoke:High-sulfur residue retaining 5-7% sulfur content, processed for energy-intensive industries. Demand concentrates in India's western cement corridor where BIS sulfur caps force pre-combustion treatment investments.
- Calcined Petcoke:Rotary kiln heat treatment drives volatile matter below 0.5% and boosts fixed carbon above 98%. Aluminium smelters in Saudi Arabia and the United States specify low-sulfur calcined grades for anode production.
- Needle Coke:Premium delayed coker variant with ultra-low sulfur and ordered crystalline structure. Electric arc furnace electrode manufacturers pay substantial premiums for coefficient of thermal expansion below 1.0 ppm per degree Celsius.
The dominant share belongs to Fuel-Grade Petcoke, while Calcined Petcoke is closing the gap fastest.
End Use:
Customer specifications diverge sharply on sulfur thresholds and metal content limits.
- Cement Industry:Clinker kilns consume 60-70% of global fuel-grade volumes, tolerating higher sulfur when equipped with scrubber systems. UltraTech and Shree Cement in India negotiate collective procurement tenders against Jamnagar refinery output.
- Power Generation:Fluidized bed combustors and circulating boilers burn high-sulfur grades where emission regulations permit. Indian captive power plants face tightening BIS sulfur caps that exclude untreated cargoes.
- Aluminium Industry:Smelters demand calcined petcoke with sulfur below 2.5% and vanadium-nickel limits specified in long-term offtake contracts. Middle Eastern crude slates supply preferred low-metal feedstock for anode-grade production.
- Steel Manufacturing:Electric arc furnaces and foundries utilize needle coke electrodes or fuel-grade for sintering operations. Graphite electrode specifications favor ultra-low sulfur needle coke from dedicated coker units.
Cement Industry retains volume leadership, though Aluminium Industry procurement is expanding most quickly.
Grade:
Sulfur bands determine marketability across regulatory jurisdictions and end-use equipment.
- Low Sulfur:Below 2% sulfur content, sourced from light sweet crude processing. Preferred for calcination feedstock and EU Green Deal compliant cement shipments.
- High Sulfur:Above 4% sulfur, typically from heavy sour crude slates. Indian cement plants with captive desulfurization absorb volumes at discounted pricing.
- Medium Sulfur:2-4% sulfur range requiring blending or treatment for compliance. Traders arbitrage price differentials between Indian BIS limits and spot market availability.
- Ultra-Low Sulfur:Below 1% sulfur, premium positioning for needle coke and specialized anode applications. Limited refinery output commands pricing multiples over standard grades.
High Sulfur dominates transaction volumes, while Ultra-Low Sulfur is gaining share fastest.
Distribution Channel:
Logistics configuration shapes margin capture between refinery gate and end-user silo.
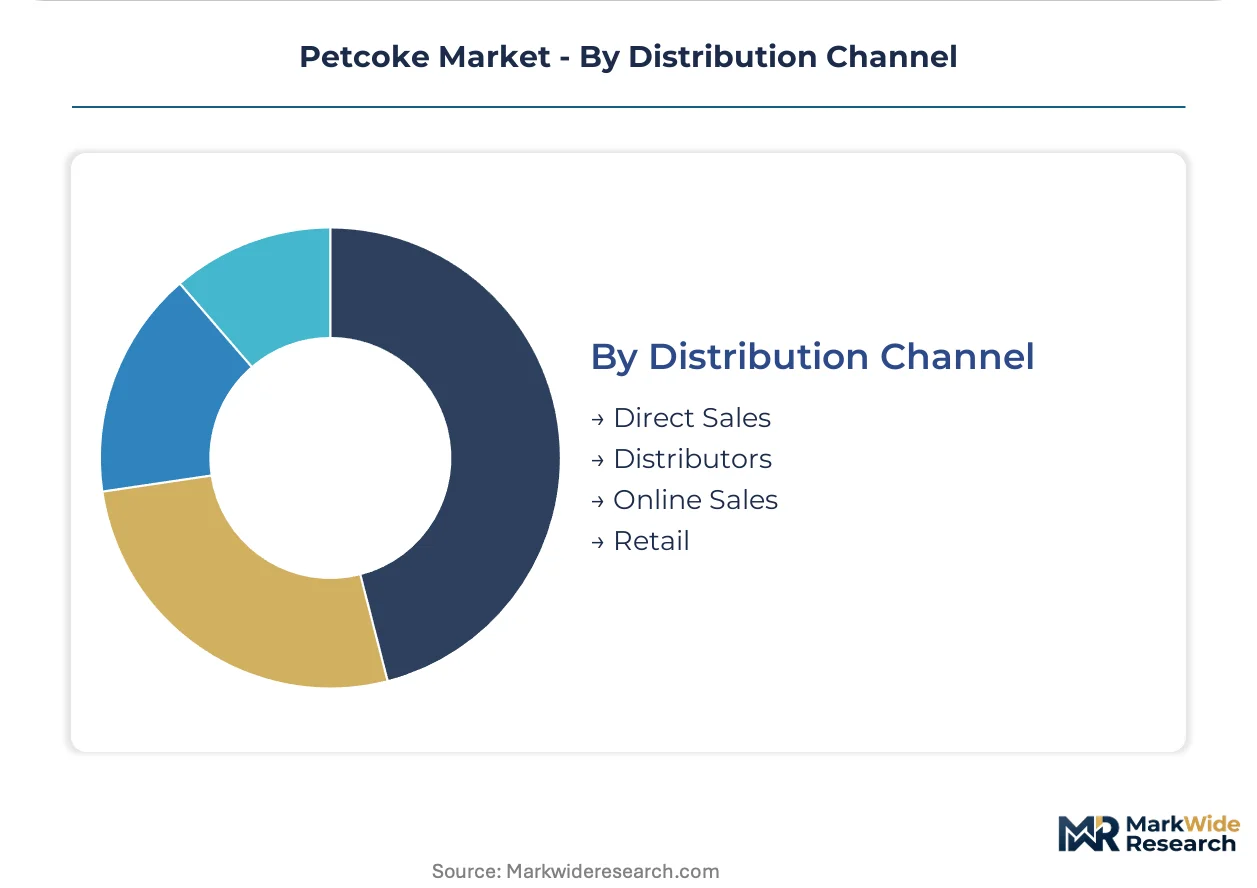
- Direct Sales:Refinery-to-plant contracts with fixed sulfur bands and annual volume commitments. Indian cement groups consolidate procurement through collective tenders.
- Distributors:Regional traders manage blending, storage, and certification services. Western India refining clusters rely on distributor networks for inland cement plant delivery.
- Online Sales:Digital platforms for spot cargo matching and real-time sulfur assay verification. Emerging channel for small-volume cement producers.
- Retail:Bagged petcoke for small industrial boilers and foundries. Minimal share concentrated in fragmented domestic Indian markets.
Direct Sales commands the largest share, though Distributors are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian cement buyers absorb fuel-grade volumes with minimal price elasticity as infrastructure deadlines tighten, while US Gulf Coast plants switch to natural gas at the first petcoke price spike. European buyers face carbon border exposure that compresses their willingness to pay premiums.
India
Cement kilns in Gujarat and Maharashtra operate at 85-90% capacity as highway and rail projects accelerate clinker demand. The Bureau of Indian Standards sulfur caps force pre-combustion treatment investments at captive power units. Jamnagar and Vadodara refining clusters supply 60% of domestic fuel-grade output to western India cement corridors.
United States
Gulf Coast cement plants with pipeline gas access arbitrage feedstock costs seasonally, eroding fuel-grade contract volumes during price troughs. EPA emission standards and state-level carbon pricing in California constrain high-sulfur combustion. Texas and Louisiana refineries export surplus fuel-grade cargoes to Atlantic cement terminals when domestic power demand softens.
Saudi Arabia
Aluminium smelters in the Eastern Province source low-metal calcined petcoke for anode production under long-term offtake contracts. The Saudi Standards, Metrology and Quality Organization enforces sulfur reporting for export cargoes. Yanbu and Jubail industrial cities host calcination capacity serving both domestic smelters and Asian buyers.
China
Delayed coking capacity expansions at Shandong and Liaoning refineries boost fuel-grade availability for domestic cement and power sectors. The Ministry of Ecology and Environment dual carbon goals tighten emission permits for high-sulfur combustion. Yangtze River Delta cement clusters import Middle Eastern low-sulfur grades to blend with domestic output.
Germany
Cement producers in North Rhine-Westphalia face EU Green Deal carbon border adjustments that exclude conventional fuel-grade imports from carbon credit calculations. The European Chemicals Agency REACH framework mandates quarterly metals reporting for combustion residuals. Duisburg and Cologne terminals now source certified low-sulfur Mediterranean cargoes at premium pricing.
Petcoke Market Vendor Landscape
Integrated oil majors and independent refiners split the market between captive supply control and trading flexibility. The structure concentrates upstream output among ten to twelve players with coker capacity, while midstream blending and logistics fragment across regional distributors. Strategic archetypes include refinery-integrated producers, independent calciners, and commodity traders. Capacity expansion and sulfur treatment technology licensing dominate competitive moves as regulatory thresholds tighten.
Within the integrated refiner tier, ExxonMobil Corporation and Saudi Aramco exemplify upstream control over fuel-grade quality at source. Reliance Industries Limited anchors massive calcination capacity within its Jamnagar complex. Among independent processors, Oxbow Corporation occupies a trading and logistics position connecting Gulf Coast refinery output to Atlantic cement markets.
| Leading Market Players |
|---|
| BP plc |
| Chevron Corporation |
| ExxonMobil Corporation |
| Saudi Aramco |
| Reliance Industries Limited |
| Phillips 66 Company |
| Indian Oil Corporation Ltd. |
| Valero Energy Corporation |
| Oxbow Corporation |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation tariff exposure determines both sulfur-grade pricing spreads and supply chain configuration across Mediterranean cement terminals and Indian refining clusters. Refiners with pre-certified low-sulfur cargoes capture premium positioning while high-sulfur volumes face carbon border exclusion, compressing viable sourcing geography to BIS-compliant Indian corridors and Middle Eastern low-metal slates.
Pricing Analysis
Aftermarket sulfur treatment and certification services now drive lifetime value capture across fuel-grade cargo portfolios. Long-term offtake contracts with fixed sulfur bands dominate procurement at UltraTech and Shree Cement, displacing spot market purchases through penalty clauses for quality deviation. Price differentiation rests on BIS certification tier and volume scale, with collective tenders from Gujarat kiln clusters commanding discounts against Jamnagar refinery gate pricing. Cost compression in high-sulfur grades is intensifying as natural gas substitution erodes US Gulf Coast contract volumes during price troughs. Indian captive power units with on-site desulfurization exhibit highest price sensitivity, while Saudi aluminium smelters with anode-grade specifications show least elasticity due to technical lock-in.
Supply Chain Analysis
Heavy residual oil feedstock quality from Saudi Arabia, Russia, and United States refineries anchors global fuel-grade output variability. Geographic supply concentrates in India, Saudi Arabia, and the United States, with Jamnagar and Yanbu industrial cities hosting disproportionate calcination capacity. Raw material dependencies include high-sulfur crude slates, natural gas for calcination energy, and caustic soda for sulfur scrubbing systems. Single-source vulnerability threatens aluminium anode supply chains through western India refining concentration around Vadodara clusters. Distribution runs through refinery-direct contracts for major cement groups, with regional distributors managing inland blending and BIS certification services for fragmented buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The petcoke market faces high-growth disruption as EU Green Deal carbon border adjustments and BIS sulfur enforcement simultaneously regrade product specifications and geographic marketability.
For Market Incumbents: Harden refinery-integrated positions through captive calcination capacity additions in Saudi Arabia and India to secure anode-grade supply chains against Jamnagar cluster vulnerability. Defend fuel-grade margins by licensing inline X-ray fluorescence sulfur monitoring technology to cement buyers, converting quality verification into recurring service revenue streams. Prioritize backward integration into dedicated low-metal crude slate sourcing from specific Middle Eastern fields to meet tightening REACH metal thresholds. For New Entrants and Emerging Players: Pursue sulfur treatment and certification service white space in Vietnam, Indonesia, and Philippines cement markets lacking domestic calcination infrastructure. Target collective procurement tender participation at Indian cement groups consolidating volumes through annual sulfur-banded contracts. Deploy digital cargo-matching platforms with real-time assay verification as go-to-market angle to bypass entrenched distributor relationships in fragmented Southeast Asian markets. For Investors and Strategic Acquirers: EU Green Deal implementation reshapes the acquisition landscape toward certified low-sulfur logistics operators and BIS-compliant treatment technology providers. Long-term viability favors assets with regulatory pre-certification and captive refinery relationships over pure trading positions. Target calciner retrofit specialists with 18-24 month commissioning capabilities as acquisition archetype. Watch quarterly EU carbon border adjustment mechanism expansion announcements as inflection signal for Mediterranean cargo premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Calcination Capacity Expansion | Reliance Industries anchors anode-grade supply security at Jamnagar against western India concentration risk. |
| Backward Integration into Low-Metal Crude Sourcing | Saudi Aramco secures preferred feedstock for smelter-grade calcined petcoke under long-term aluminium offtake contracts. |
| Digital Sulfur Monitoring Technology Licensing | Inline X-ray fluorescence deployment at Indian cement plants converts quality verification into recurring service revenue. |
| Long-term Supply Agreement Restructuring | UltraTech and Shree Cement consolidate procurement through collective tenders with penalty clauses for sulfur deviation. |
| Joint Venture in Southeast Asian Logistics | Oxbow Corporation extends Gulf Coast distribution dominance into Vietnam and Indonesia clinker production expansion. |
Methodological Framework
The analysis maps fuel-grade, calcined, and needle coke sub-sectors, each validated through refinery operations managers, cement plant procurement directors, aluminium smelter technical specifications leads, and sulphur treatment technology vendors. Primary interviews with Indian Oil Corporation supply planners and Saudi Aramco export coordinators combined with secondary validation from Bureau of Indian Standards certification records, European Chemicals Agency REACH authorization databases, customs trade manifests, and refinery coker capacity disclosures. Bottom-up cargo volume tracking and top-down refining capacity modeling triangulate segment splits.
Assumptions held fixed include current BIS sulfur caps and EU F-Gas Regulation metal thresholds, while crude slate sulfur content and carbon border adjustment implementation pace were varied across sensitivity scenarios. The projection horizon spans fuel-grade, calcined, and needle coke product types crossed with cement, aluminium, power, and steel end-use industries, further segmented by low, medium, high, and ultra-low sulfur grades. CAGRs were derived from refinery coker capacity expansion pipelines and cement kiln operating rate projections. Industry-specific inputs include heavy crude processing upgrade timelines and aluminium smelter anode consumption coefficients.
Macroeconomic conditions sit as an overlay; deviation in Indian infrastructure spending execution, OPEC+ production decisions affecting high-sulfur crude discounts, or EU carbon border tax acceleration would shift the trajectory. Forecasts reflect these assumptions without claiming predictive certainty. Cross-checking against refinery coker utilization rates reported in quarterly energy sector filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Australia Refined Petroleum Products Market
Petroleum Products
Pygas (Pyrolysis Gasoline) Market
Petroleum Products
Gasoline-Naphtha-Crude-MTBE Market
Petroleum Products
United States Refined Petroleum Products Market
Petroleum Products
Asia-Pacific Lubricants Market
Petroleum Products
Global Petroleum Coke Market
Petroleum Products
Automotive Oil Market
Petroleum Products
East Africa Refined Petroleum Products Market
Petroleum Products
Alkylate Gasoline Market
Petroleum Products
Pale Oil Market
Petroleum Products
Refined Petroleum Products Market
Petroleum Products
Asia Pacific Base Oil Market
Petroleum Products
Paraffin Oil Market
Petroleum Products
Automotive Oil Strainer Market
Petroleum Products
South Africa Refined Petroleum Products Market
Petroleum Products
Petroleum Liquid Feedstock Naphtha and Gas Oil Sales Market