
 Petroleum Liquid Feedstock Naphtha and Gas Oil Sales Market | 2026-2036
Petroleum Liquid Feedstock Naphtha and Gas Oil Sales Market Size, Share, and Industry Trends Forecast 2026-2036
Petroleum Liquid Feedstock Naphtha and Gas Oil Sales Market Insights
ISO 8217 marine fuel quality standards are unwinding competitive access for suppliers unable to meet sulfur and density specifications. ExxonMobil Corporation leverages integrated upstream-to-downstream control across Gulf Coast refining complexes. Saudi Arabian Oil Company anchors long-term offtake contracts with Asian petrochemical buyers. Reliance Industries Limited dominates domestic naphtha arbitrage flows through its Jamnagar refining hub.
Petroleum liquid feedstock naphtha and gas oil comprises hydrocarbon fractions distilled from crude oil at temperatures between 30°C and 350°C, with naphtha spanning C5-C12 paraffins and gas oil covering heavier C13-C25 distillates used primarily as steam-cracker feedstock and diesel blending components. The petrochemical feedstock application segment leads margin capture due to ethylene-propylene chain economics, while fuel production retains volume dominance despite regulatory pressure on carbon intensity. Direct sales channels concentrate around term contracts between refiners and chemical manufacturers, with traders arbitraging regional price differentials during supply disruptions.
The EPA enforces Tier 3 gasoline sulfur limits that cascade into naphtha hydrotreater investment requirements, while REACH compliance in Europe mandates full substance registration for imported gas oil streams. China's MEE implements dual carbon goals that restrict high-sulfur fuel oil blending and redirect refinery output toward petrochemical-optimized configurations. Stakeholders must monitor how carbon border mechanisms redefine feedstock sourcing economics before committing to long-term supply agreements.
Market Dynamics
Petrochemical feedstock demand from ethylene crackers is concentrating purchasing power among Asian refiners, forcing European and Middle Eastern suppliers to reconfigure sulfur specifications and carbon intensity certifications to maintain offtake access.
Growth Catalysts
- Asia-Pacific Ethylene Capacity Expansion:China, India, and Saudi Arabia are commissioning new steam crackers that lock in term naphtha contracts. Refinery capacity additions in these markets absorb regional feedstock output that previously flowed to export markets.
- EU Carbon Border Adjustment Mechanism:Import declarations for embodied emissions in gas oil streams are tightening product specifications. European petrochemical buyers now require certified low-carbon feedstock documentation from non-EU suppliers.
- Marine Fuel Specification Upgrades:ISO 8217 sulfur and density standards for residual fuel blending are redirecting middle distillate streams. Refiners with hydrotreater investments capture margin premiums on gas oil suitable for marine bunkering.
Market Restraints
- Crude Slate Volatility:Light sweet crude premiums versus heavy sour grades swing naphtha yield economics. Refiners processing discounted heavy barrels face lower naphtha output per barrel processed.
- Middle Eastern Supply Concentration:Saudi Aramco and ADNOC control substantial export-oriented naphtha volumes. Asian buyers face limited alternative sourcing during unplanned refinery maintenance in the Gulf.
- Electrification of Transport:Battery electric vehicle penetration in European and Chinese passenger fleets compresses long-term gas oil demand growth for on-road diesel applications.
Strategic Opportunities
- Chemical Recycling Feedstock Certification:Pyrolysis oil from plastic waste qualifies as circular naphtha under EU taxonomy rules. Refiners with co-processing capability access green premium pricing from brand-owner offtakers.
- India Petrochemical Demand Surge:Reliance Industries and Indian Oil Corporation are expanding derivative capacity faster than domestic naphtha supply growth. Import arbitrage windows for West African and Mediterranean cargoes are widening.
- Blue Hydrogen Production:Gas oil with carbon capture and storage certification serves as feedstock for low-carbon hydrogen projects. Netherlands and Germany are tendering offtake contracts with strict CI thresholds.
Industry Challenges
- Hydrotreater Catalyst Sourcing:Specialized cobalt-molybdenum and nickel-molybdenum formulations for ultra-low sulfur naphtha production face extended procurement lead times. Refiners report 18-24 month delivery schedules from catalyst manufacturers.
- Emissions Verification Documentation:EU F-Gas Regulation and carbon border mechanisms require third-party lifecycle assessment audits. Smaller trading houses lack internal compliance teams to manage certification workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Petroleum Liquid Feedstock Naphtha and Gas Oil Sales Market |
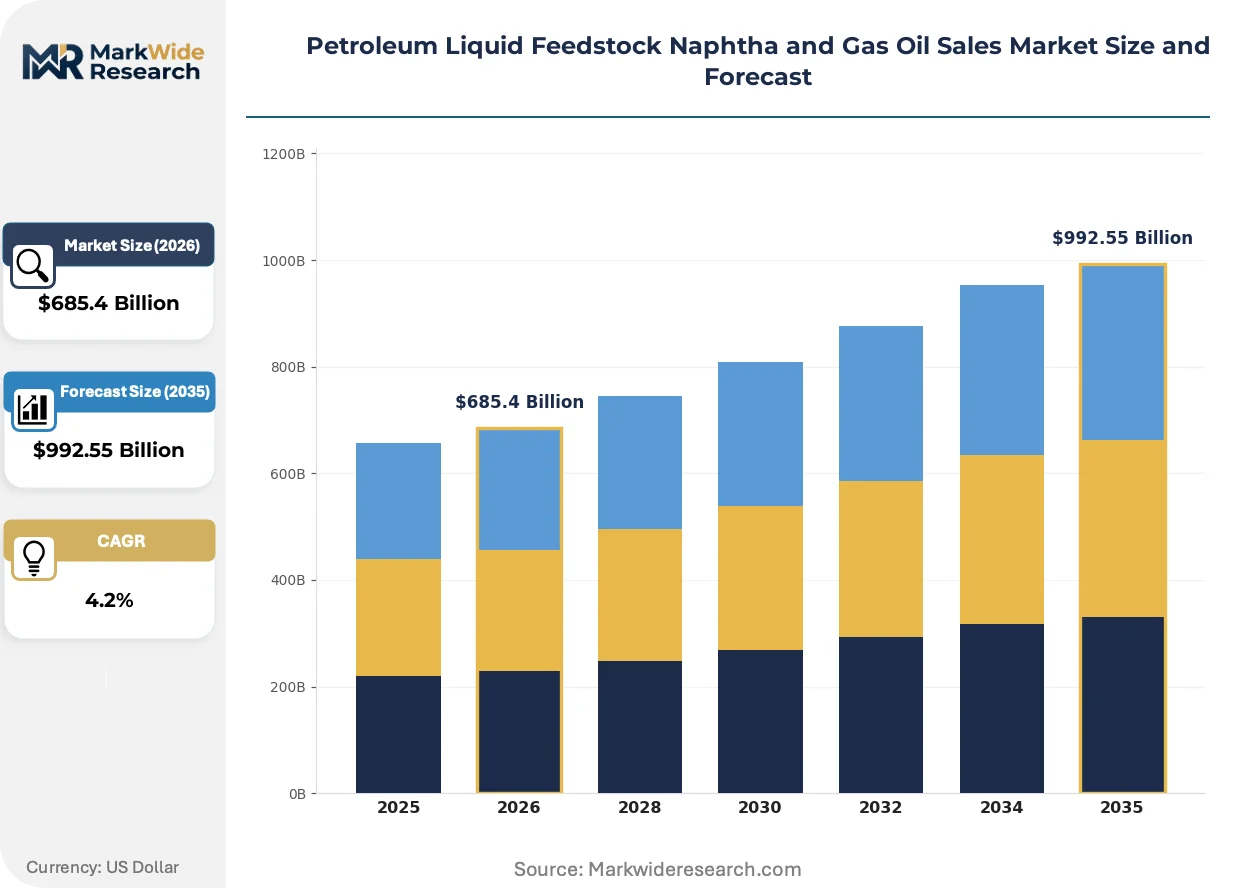
| Market Size in 2026 | $685.4 Billion |
| Market Size in 2035 | $992.55 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Naphtha, Gas Oil, Kerosene, Diesel Application: Fuel Production, Petrochemical Feedstock, Industrial Heating, Transportation End User: Refineries, Chemical Manufacturers, Power Plants, Transportation Companies Sales Channel: Direct Sales, Distributors, Retailers, Traders |
| Companies Covered | ExxonMobil Corporation, Chevron Corporation, Royal Dutch Shell, BP plc, China National Petroleum Corporation, Sinopec, TotalEnergies SE, Saudi Arabian Oil Company, Reliance Industries Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Petroleum Liquid Feedstock Naphtha and Gas Oil Sales Market Trends and Innovations
Digital assay platforms and real-time cargo tracking are compressing quality arbitrage windows that historically sustained trader margins. Refiners and petrochemical buyers now price cargoes against standardized spectral fingerprint databases rather than manual sampling protocols.
Advanced online near-infrared spectroscopy is displacing laboratory-based ASTM D86 distillation testing at loading terminals. Major Asian ethylene producers have adopted continuous assay monitoring to optimize cracker feed blending. This instrumentation compresses the 48-72 hour quality confirmation window to real-time acceptance decisions, reducing working capital tied up in transit inventory.
China's MEE dual carbon goals are enforcing mandatory carbon intensity reporting for refinery output streams. Domestic refiners must submit verified emissions data for naphtha and gas oil batches sold to chemical manufacturers. This regulatory layer is fragmenting the spot market into certified and uncertified cargo tiers with divergent pricing.
Petrochemical buyers are consolidating term contract volumes with fewer integrated suppliers capable of delivering certified low-carbon feedstock. Spot market liquidity for standard-specification naphtha is thinning as procurement teams prioritize supply security over price optimization. This concentration is most visible in South Korea and Taiwan, where ethylene crackers have reduced active supplier panels from twelve to four counterparties.
Petroleum Liquid Feedstock Naphtha and Gas Oil Sales Market Segmentation
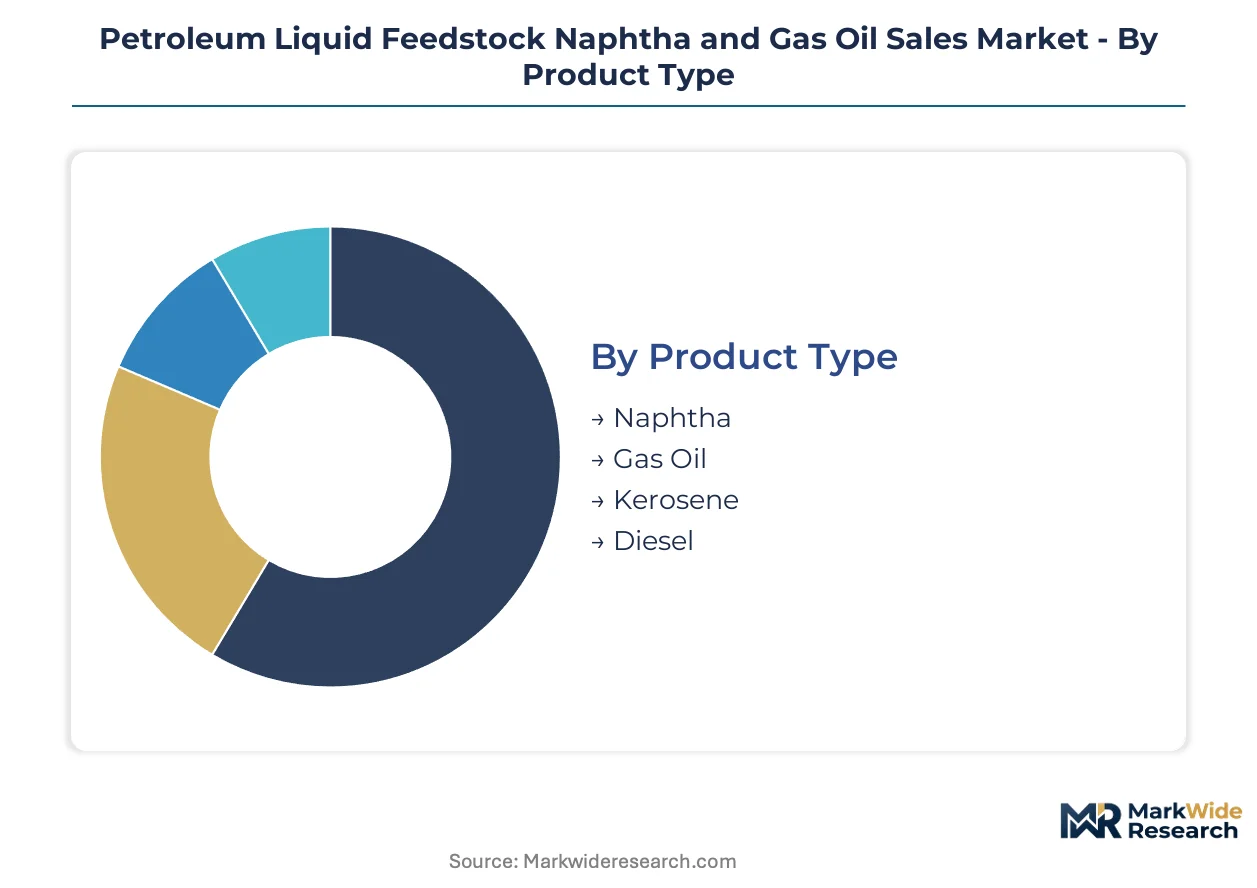
Naphtha and gas oil procurement patterns fragment across product specifications, application requirements, and sales channel economics. Buyers optimize feedstock selection against cracker yields, sulfur limits, and carbon intensity certifications that vary by end-use and geography.
Product Type:
Light distillate streams face intensifying substitution pressure from recycled pyrolysis oils and bio-based alternatives in European petrochemical procurement.
- Naphtha:C5-C12 paraffinic and aromatic hydrocarbons serve as the primary steam-cracker feedstock for ethylene and propylene production. Asian ethylene producers in China, India, and South Korea concentrate term contract demand on full-range naphtha with specific paraffin-to-aromatic ratios that optimize olefin yields.
- Gas Oil:C13-C25 distillates bridge marine bunkering, diesel blending, and emerging blue hydrogen feedstock applications. Refiners with deep hydrotreating capability capture margin premiums as IMO 2020 sulfur regulations and EU carbon border adjustments tighten product specifications for European import streams.
- Kerosene:Jet fuel-appropriate cut with narrow distillation range between naphtha and gas oil.
- Diesel:Heavier distillate fraction meeting on-road and off-road engine compression ignition requirements.
Naphtha anchors the volume base while gas oil gains share at the steepest rate.
Application:
Margin capture potential separates applications most sharply, with petrochemical feedstock commanding price premiums over commodity fuel uses.
- Petrochemical Feedstock:Steam cracker and catalytic reformer inputs where naphtha quality directly determines olefin and aromatics yields.
- Fuel Production:Transportation and heating fuel blending absorbs the largest absolute volumes despite regulatory compression on carbon intensity.
- Industrial Heating:Direct combustion in furnaces and kilns where sulfur and particulate specifications vary by facility permit.
- Transportation:On-road diesel, marine bunkers, and aviation turbine fuel with divergent certification requirements across EPA, EU MRV, and IMO frameworks.
Fuel production retains volume dominance while petrochemical feedstock expands most quickly.
End User:
Procurement sophistication divides end users, with integrated refiners capturing margin through captive supply while merchant buyers face price volatility.
- Chemical Manufacturers:Ethylene crackers and aromatics complexes requiring consistent naphtha quality for catalyst protection and yield optimization.
- Refineries:Inter-refinery transfers and blending operations for product slate optimization.
- Power Plants:Liquid fuel backup generation and peaking capacity in markets with grid reliability constraints.
- Transportation Companies:Fleet operators and marine charterers sourcing diesel and bunker fuel through term contracts or spot procurement.
Chemical manufacturers concentrate purchasing power while power plants represent the most price-sensitive demand segment.
Sales Channel:
Channel selection reflects transaction scale, quality verification requirements, and working capital constraints.
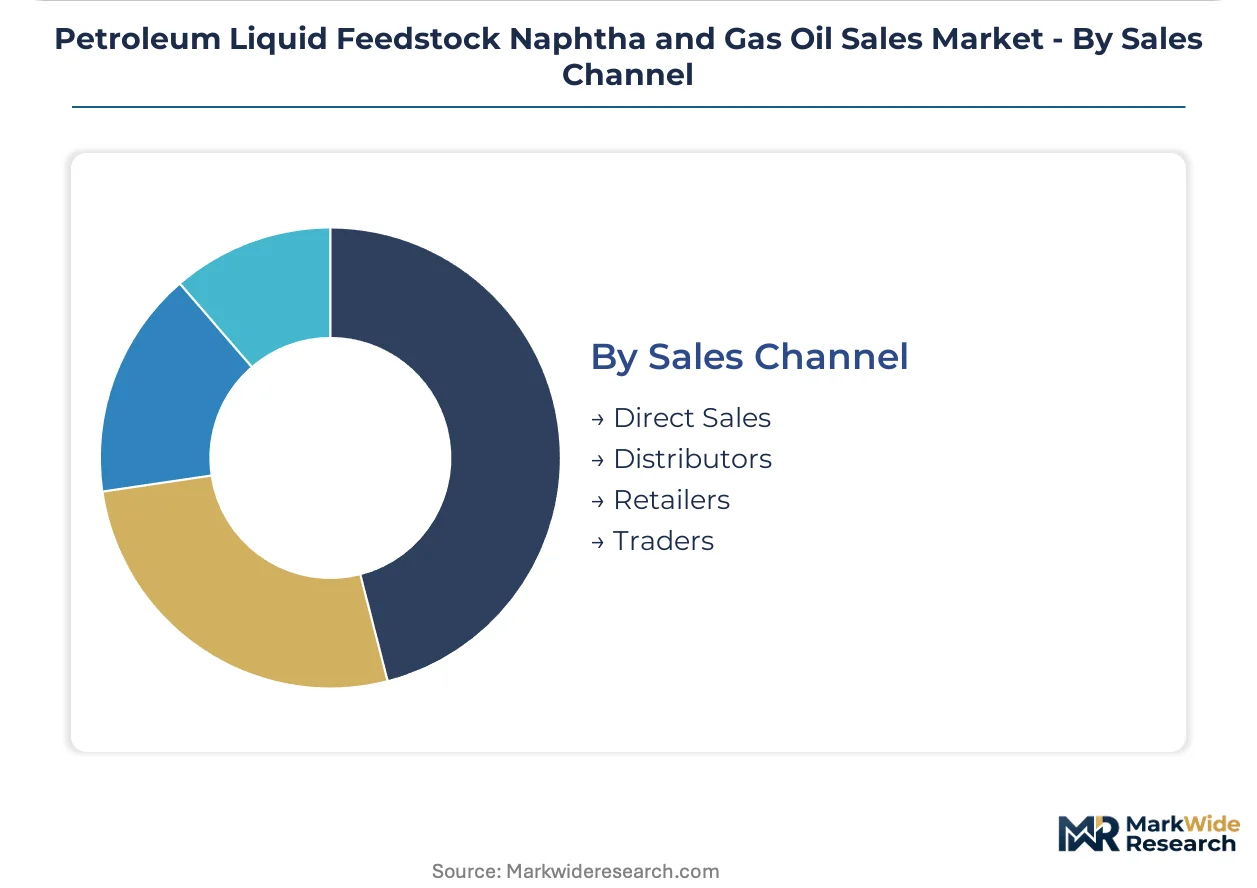
- Direct Sales:Term contracts between refiners and large-volume petrochemical buyers with dedicated assay protocols and carbon certification documentation.
- Traders:Merchants arbitraging regional price differentials and managing supply disruption risk for buyers without term contract coverage.
- Distributors:Regional intermediaries aggregating smaller volumes for industrial and transport end users.
- Retailers:Final point-of-sale for packaged or small-batch fuel deliveries.
Direct sales anchor contract stability while traders provide liquidity during supply disruptions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asian petrochemical buyers concentrate purchasing power through long-term offtake contracts, while European importers enforce carbon intensity documentation. Middle Eastern exporters anchor supply volumes through state-linked trading arms. Refinery capacity additions in China and India absorb regional output that previously reached Atlantic basin markets.
China
Steam cracker expansions in Zhejiang and Jiangsu provinces lock in naphtha term contracts with domestic refiners. The MEE enforces dual carbon goals that redirect refinery output toward petrochemical-optimized configurations. The Yangtze River Delta cluster hosts integrated complexes where Sinopec and private refiners process Middle Eastern crude into export-oriented gas oil streams.
Saudi Arabia
Saudi Aramco anchors long-term supply agreements with South Korean and Japanese ethylene producers. The national oil company controls substantial export-oriented naphtha volumes through Ras Tanura and Yanbu terminals. The Eastern Province refining corridor concentrates hydrotreater investments that produce ultra-low sulfur gas oil for European marine bunkering.
United States
Gulf Coast refiners leverage shale-sourced light sweet crude to maximize naphtha yields for export markets. The EPA enforces Tier 3 gasoline sulfur limits that cascade into hydrotreater investment requirements. The Houston Ship Channel complex serves as the primary aggregation point for spot naphtha cargoes bound for Latin American petrochemical buyers.
India
Reliance Industries and Indian Oil Corporation expand derivative capacity faster than domestic naphtha supply growth. The country's central energy regulator monitors refinery output allocations between fuel and petrochemical streams. The Jamnagar refining hub dominates domestic arbitrage flows and processes discounted heavy crude barrels into gas oil for African export markets.
Germany
European petrochemical buyers require certified low-carbon feedstock documentation under the Carbon Border Adjustment Mechanism. The ECHA administers REACH compliance mandates for full substance registration of imported gas oil streams. The Rhine-Ruhr industrial corridor hosts crackers that source naphtha through Rotterdam-originated term contracts with Middle Eastern suppliers.
Petroleum Liquid Feedstock Naphtha and Gas Oil Sales Market Competitive Landscape
Player mix skews toward integrated oil majors with captive upstream production and downstream refining assets. National oil companies from the Middle East and Asia anchor supply volumes through state-controlled trading mechanisms. Strategic archetypes include Gulf Coast-integrated majors, Middle Eastern state-linked exporters, and Asian refinery-petrochemical conglomerates. Competitive positioning depends on crude slate flexibility and carbon certification capability rather than price alone.
Among integrated majors with Gulf Coast refining dominance, ExxonMobil Corporation exemplifies upstream-to-downstream control across complex configurations. Chevron Corporation occupies a position within the same tier, leveraging shale-sourced crude access. Saudi Arabian Oil Company anchors the state-linked exporter archetype, controlling term contract flows to Asian buyers through long-term supply mechanisms. Reliance Industries Limited represents the Asian refinery-petrochemical conglomerate model, dominating domestic Indian arbitrage through integrated Jamnagar operations.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Chevron Corporation |
| Royal Dutch Shell |
| BP plc |
| China National Petroleum Corporation |
| Sinopec |
| TotalEnergies SE |
| Saudi Arabian Oil Company |
| Reliance Industries Limited |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts with Middle Eastern suppliers lock in supply access and price visibility for Asian petrochemical buyers, insulating procurement teams from spot volatility while committing them to fixed carbon intensity documentation requirements under EU CBAM rules. These structures concentrate pricing power among state-linked exporters and compress margins for traders unable to certify low-carbon feedstock.
Pricing Analysis
Cost-plus contracts indexed to Platts Japan naphtha assessments dominate term procurement between Asian ethylene crackers and Middle Eastern refiners. Price differentiation rests on sulfur content grades and certified carbon intensity tiers, with EU-bound gas oil commanding premiums for documented lifecycle emissions. Cost compression in standard-specification naphtha is intensifying because digital assay platforms erode quality arbitrage windows. Merchant chemical manufacturers without integrated refining exposure the most price-sensitive buyers, while state-backed conglomerates with captive supply face minimal spot exposure.
Supply Chain Analysis
Strategic stockpiling of hydrotreater catalysts and cobalt-molybdenum formulations has replaced just-in-time procurement as refiners confront 18-24 month delivery schedules from specialty chemical suppliers. Feedstock supply concentrates in Saudi Arabia, the United Arab Emirates, and Kuwait, with naphtha streams drawing from associated gas production and heavy crude distillation. Single-source vulnerability runs through Ras Tanura and Yanbu terminals during unplanned maintenance. Distribution feeds from Middle Eastern export terminals through Rotterdam and Singapore hub storage before final delivery to crackers in China, South Korea, and Taiwan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of certified low-carbon feedstock documentation capabilities is fragmenting competitive access, rewarding suppliers with in-house lifecycle assessment teams and third-party audit relationships while excluding smaller trading houses from EU offtake panels.
For Market Incumbents: Consolidate term contract positions with Asian ethylene producers before carbon border mechanisms harden supplier qualification requirements. Deepen backward integration into hydrotreater catalyst manufacturing or secure exclusive offtake agreements with cobalt-molybdenum suppliers to defend margin position against procurement delays. Prioritize certification investment for blue hydrogen feedstock streams to capture Netherlands and German tender premiums. For New Entrants and Emerging Players: Differentiate on circular naphtha certification by developing pyrolysis oil co-processing capabilities that qualify under EU taxonomy rules. Target Indian import arbitrage windows where Reliance Industries and Indian Oil Corporation outpace domestic supply growth. Pursue direct sales channel access with brand-owner offtakers seeking green premium pricing rather than competing for spot liquidity against established traders. For Investors and Strategic Acquirers: Capital is best deployed toward integrated refinery-petrochemical complexes with demonstrated carbon certification workflows and long-term Asian offtake relationships. Viability over the next decade hinges on crude slate flexibility and hydrotreater investment completion. Watch for inflection when EU CBAM enforcement tightens documentation requirements for non-certified cargoes, triggering supplier panel consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Catalyst Manufacturing | Secures cobalt-molybdenum supply for ultra-low sulfur naphtha production against 18-24 month procurement delays. |
| Long-term Supply Agreement | Locks in term offtake with Asian ethylene crackers ahead of carbon border mechanism enforcement. |
| Green Certification Program | Qualifies pyrolysis oil co-processing as circular naphtha under EU taxonomy for brand-owner premiums. |
| Joint Venture | Combines Middle Eastern crude access with Asian cracker demand through state-linked trading structures. |
| Capacity Expansion | Adds hydrotreater units to capture gas oil margin premiums for IMO 2020 marine bunkering compliance. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with refinery operations directors, petrochemical procurement managers, marine fuel traders, and catalyst manufacturing technical leads. Secondary validation drew from customs trade databases, SEC 10-K filings of integrated majors, Platts price assessment archives, and EIA refinery utilization reports. Bottom-up volume modeling from individual facility configurations was triangulated against top-down demand projections from ethylene capacity expansion announcements.
Across the analysis window, the forecasting framework modeled segmentation by product grade tier, end-use application, carbon certification status, and regional refinery hub. CAGRs were derived from trend extrapolation of historical trade flows adjusted for announced capacity additions and regulatory phase-in schedules. Industry-specific inputs included steam cracker yield curves by naphtha paraffin-to-aromatic ratio and hydrotreater investment completion timelines.
Forecasts assume regulatory continuity in EU F-Gas Regulation and CBAM implementation; material policy shifts would require re-modeling of import cost structures. Revision becomes warranted when carbon intensity verification requirements cross thresholds that eliminate uncertified cargo tiers from spot market liquidity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Petroleum Wax Market
Petroleum Products
Nigeria Petrol Station Market
Petroleum Products
Quenching Oil Market
Petroleum Products
France Refined Petroleum Product Market
Petroleum Products
Pale Oil Market
Petroleum Products
Crude Oil Market
Petroleum Products
Floating Roof Tank Market
Petroleum Products
Refined Petroleum Products Market
Petroleum Products
North America Natural Gas Liquids Market
Petroleum Products
Crude Oil Pour Point Depressant Market
Petroleum Products
Southeast Asia Refined Petroleum Products Market
Petroleum Products
East Africa Refined Petroleum Products Market
Petroleum Products
Base Oil Market
Petroleum Products
Naphtha Market
Petroleum Products
North Africa Refined Petroleum Products Market
Petroleum Products
Global Petroleum Coke Market