
 Pale Oil Market | 2026-2036
Pale Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Pale Oil Market Analytics
Buyer consolidation among multinational pharmaceutical formulators is realigning procurement volumes toward fewer, larger contracts. Exxon Mobil Corporation leverages its integrated refining base to secure long-term supply agreements with consolidated buyers. Nynas AB specializes in naphthenic pale oil grades that meet stringent pharmaceutical purity standards. TotalEnergies SE anchors its position through European distribution networks serving cosmetics compounders.
Pale oil denotes a highly refined, colorless to light-colored hydrocarbon oil with a Saybolt color typically exceeding +25, produced through severe hydrotreating and solvent extraction to remove aromatics and sulfur compounds. Its primary purpose spans cosmetic emollients, pharmaceutical excipients, and food-grade lubricants where oxidative stability and low toxicity are essential. The naphthenic oil segment leads in pharmaceutical applications due to superior solvency and low pour points, while white oil dominates cosmetic formulations where FDA 21 CFR 172.878 compliance is mandatory. Mineral oil retains volume leadership in industrial metalworking fluids, though margin pools concentrate in pharmaceutical and food-grade certifications.
EMA guidelines on residual solvent limits and FDA 21 CFR regulations for indirect food additives jointly define product qualification pathways for pale oil suppliers. REACH registration requirements and EU Green Deal carbon intensity benchmarks are forcing refiners to document supply chain emissions and reduce aromatic content below 0.1 percent by weight. Stakeholders must monitor evolving pharmacopeial monographs and carbon border adjustment mechanisms to preserve market access across regulated end-use segments.
Market Dynamics
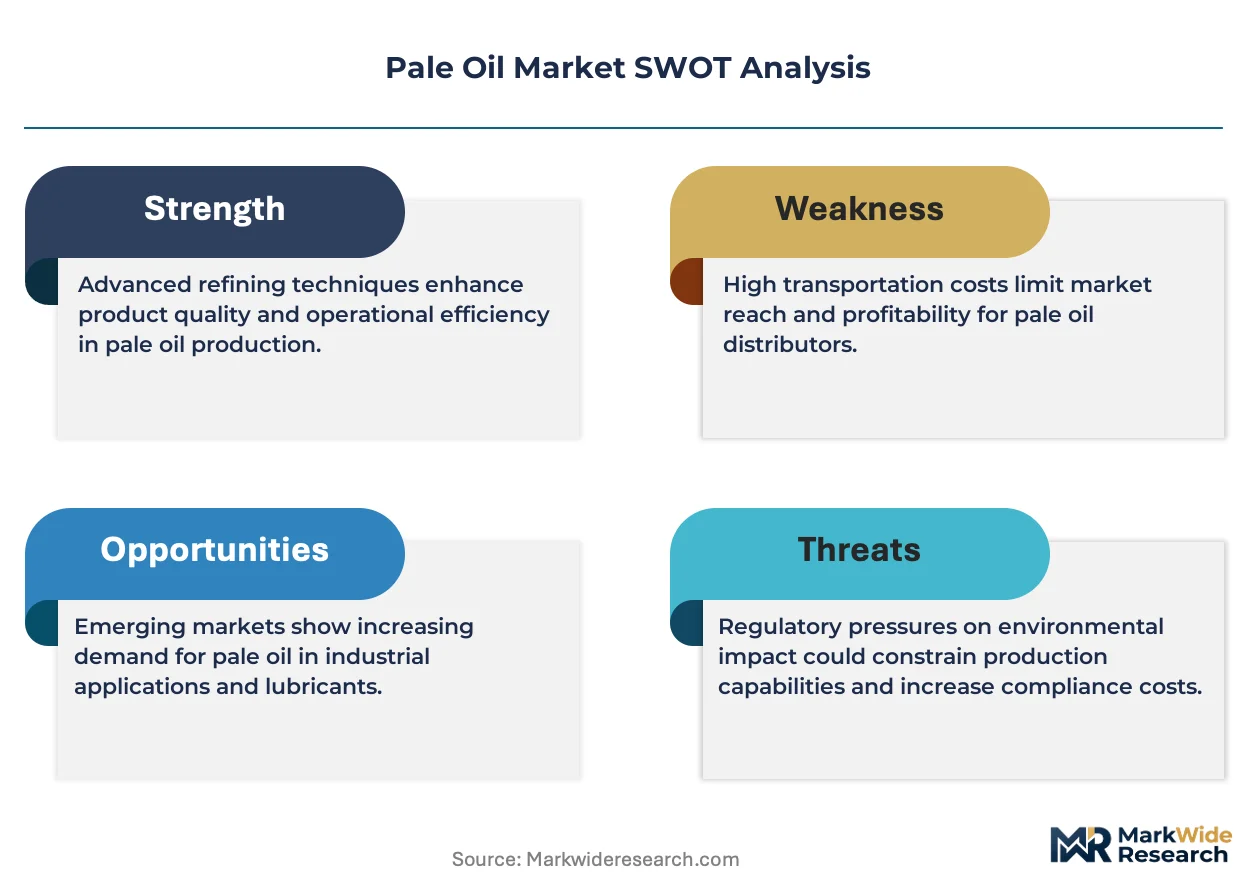
REACH and EU Green Deal compliance requirements are tightening impurity thresholds for cosmetic-grade pale oils, forcing refiners to document supply chain emissions and reduce aromatic content below 0.1 percent by weight. This regulatory compression is reshaping competitive positioning across the value chain.
Growth Catalysts
- EMA residual solvent guidelines:Pharmaceutical formulators are expanding pale oil use in topical excipient systems to meet stringent purity standards for drug delivery applications.
- Naphthenic oil solvency properties:Superior solvency and low pour points in naphthenic grades are accelerating adoption in pharmaceutical formulations requiring oxidative stability.
- Germany's specialty chemical corridor:Demand concentration in this industrial cluster is creating procurement efficiencies and technical collaboration opportunities between refiners and compounders.
Market Restraints
- Crude oil feedstock volatility:Hydrotreating and solvent extraction processes depend on stable paraffinic crude supplies subject to geopolitical disruption.
- Base oil supply concentration:Integrated refiners control hydrotreating capacity, limiting independent blenders' access to severely refined feedstocks.
- Synthetic ester substitution:Bio-based emollients are capturing share in premium cosmetic segments where carbon footprint disclosure is mandatory.
Strategic Opportunities
- Indian pharmaceutical excipient market:CDSCO alignment with ICH Q3C guidelines is opening qualification pathways for USP-grade pale oil imports.
- FDA 21 CFR 172.878 food-grade lubricants:Indirect food additive compliance is creating new volume pools in food processing equipment applications.
- Carbon border adjustment mechanisms:EU CBAM implementation is favoring low-aromatic pale oils with documented Scope 3 emissions data.
Industry Challenges
- Pharmacopeial monograph synchronization:USP, EP, and JP specification alignment requires redundant testing protocols and extended certification timelines.
- Hydrotreater catalyst replacement cycles:Severe operating conditions for aromatic saturation demand capital-intensive reactor maintenance and noble metal catalyst replenishment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pale Oil Market |
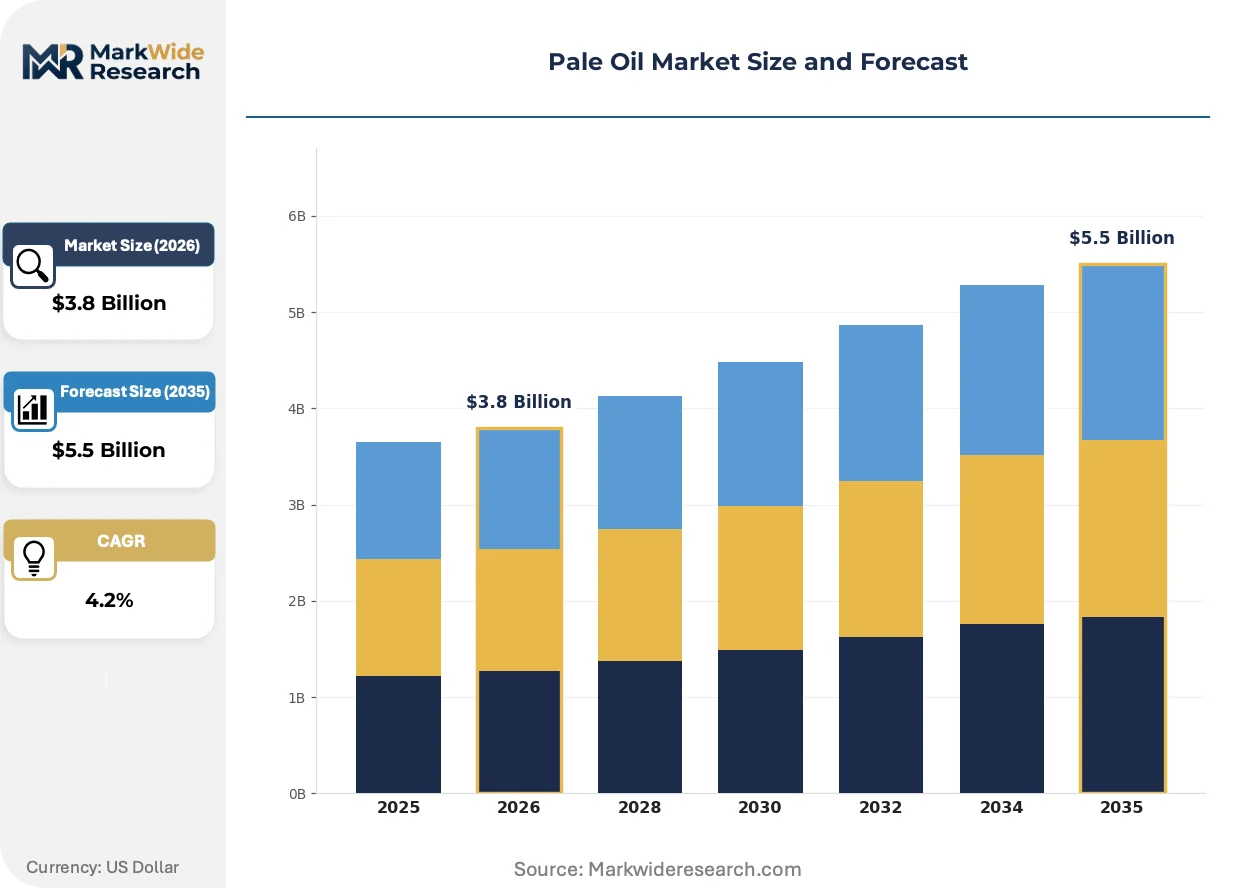
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Oil, Paraffin Oil, Naphthenic Oil, White Oil Application: Cosmetics, Pharmaceuticals, Food Industry, Industrial End User: Manufacturers, Distributors, Retailers, Consumers Distribution Channel: Online, Direct Sales, Wholesalers, Retail Shops |
| Companies Covered | Saudi Arabian Oil Company, PetroChina Company Limited, Exxon Mobil Corporation, China National Petroleum Corporation, Sinopec, Shell plc, TotalEnergies SE, Chevron Corporation, Nynas AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pale Oil Market Evolving Landscape
Process intensification and regulatory disclosure requirements are reshaping how pale oil refiners compete on purity certification and carbon accounting. Technical differentiation now hinges on traceability systems and hydrotreating precision rather than scale alone.
Membrane separation technology is overtaking conventional solvent extraction for final-stage aromatic removal in pale oil finishing. Specialty chemical producers in the cosmetics sector are adopting membrane-polished grades to meet sub-100 ppm aromatic specifications without multiple extraction passes. This shift is compressing capital requirements for new entrants while raising purity benchmarks industry-wide.
EU Green Deal carbon intensity benchmarks are forcing refiners to install continuous emissions monitoring and third-party verification systems. The industrial consequence is a bifurcation between integrated refiners with captive hydrogen supply and standalone processors facing stranded asset risk. Cosmetic compounders in France and Germany are now requiring product carbon footprint certificates as standard tender documentation.
Long-term supply agreements are displacing spot market purchases among consolidated pharmaceutical formulators. Multinational drug manufacturers are consolidating procurement volumes into fewer, larger contracts with integrated suppliers capable of multi-site delivery. Germany's specialty chemical corridor exhibits this pattern most visibly, with formulators negotiating three to five-year offtake commitments in exchange for dedicated hydrotreating campaigns.
Pale Oil Market Segmentation
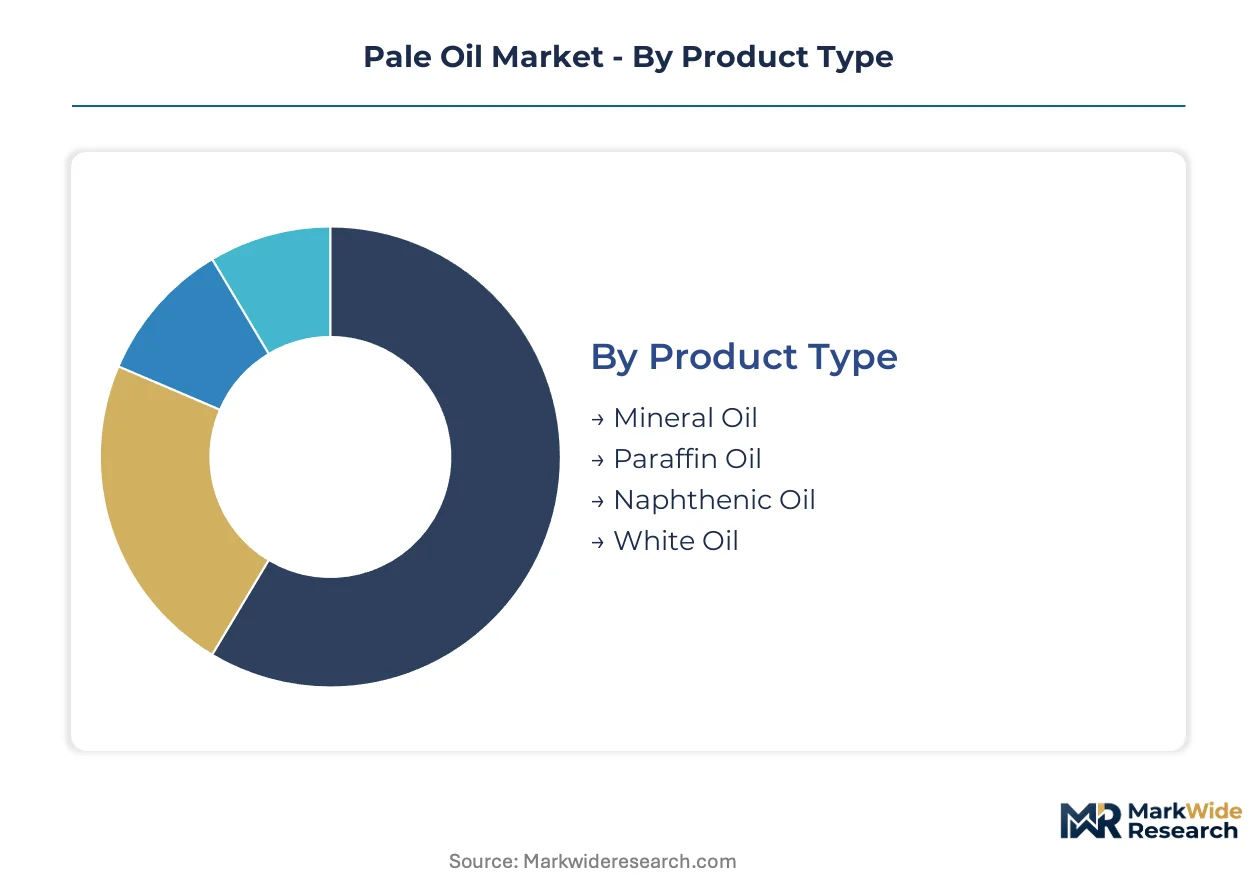
Pale oil refiners configure production campaigns around certification tiers rather than commodity grades. Segmentation reveals how hydrotreating intensity and pharmacopeial compliance separate margin pools across end-use verticals.
Product Type:
Customization intensity spans from bulk industrial mineral oil to pharmaceutical-grade white oil requiring dedicated reactor campaigns.
- Mineral Oil:Base-grade pale oil produced through moderate hydrotreating retains higher aromatic content suitable for industrial metalworking fluids. Demand concentrates in German automotive component machining where oxidative stability requirements are less stringent than pharmaceutical applications.
- White Oil:Severely hydrotreated to achieve Saybolt color exceeding +30 and aromatic content below 0.1 percent by weight. Pharmaceutical formulators in France specify USP-grade white oil for topical excipient systems where FDA 21 CFR 172.878 compliance is mandatory.
- Paraffin Oil:Saturated paraffinic structure delivers high oxidative stability for food-grade lubricant applications.
- Naphthenic Oil:Superior solvency and low pour points suit pharmaceutical formulations requiring cold-flow properties.
Most installed capacity flows through Mineral Oil. Expansion is steepest in White Oil.
Application:
Regulatory burden escalates from industrial lubricants through food contact to pharmaceutical and cosmetic systems.
- Pharmaceuticals:Topical excipient applications demand residual solvent compliance with EMA Q3C guidelines and oxidative stability for drug delivery matrices. German formulators in the specialty chemical corridor are consolidating procurement into multi-year supply agreements with integrated refiners.
- Cosmetics:Emollient formulations require REACH-registered grades with documented carbon footprints under EU Green Deal benchmarks. French compounders now mandate third-party verified Scope 3 emissions data as standard tender documentation.
- Food Industry:Indirect food additive applications under FDA 21 CFR 172.878 specify pale oil lubricants for processing equipment.
- Industrial:Metalworking fluids and textile processing consume volume grades with lower purity thresholds.
Cosmetics commands the highest certification premiums. Pharmaceuticals is gaining share fastest.
End User:
Procurement scale and technical collaboration intensity vary sharply across the value chain position.
- Manufacturers:Specialty chemical compounders and pharmaceutical formulators negotiate dedicated hydrotreating campaigns with integrated refiners. German cosmetics manufacturers in the Rhine-Ruhr cluster require membrane-polished grades meeting sub-100 ppm aromatic specifications.
- Distributors:Regional chemical distributors aggregate smaller volume orders for mid-tier cosmetics compounders lacking direct refinery relationships.
- Retailers:Pharmacy chains and cosmetic retailers stock finished formulations rather than bulk pale oil.
- Consumers:Direct purchases are limited to niche food-grade and pharmaceutical-grade packaged products.
Manufacturer direct procurement dominates volume. Distributor intermediation is expanding most quickly in mid-tier cosmetics.
Distribution Channel:
Channel selection tracks order size, certification documentation requirements, and geographic concentration of demand.
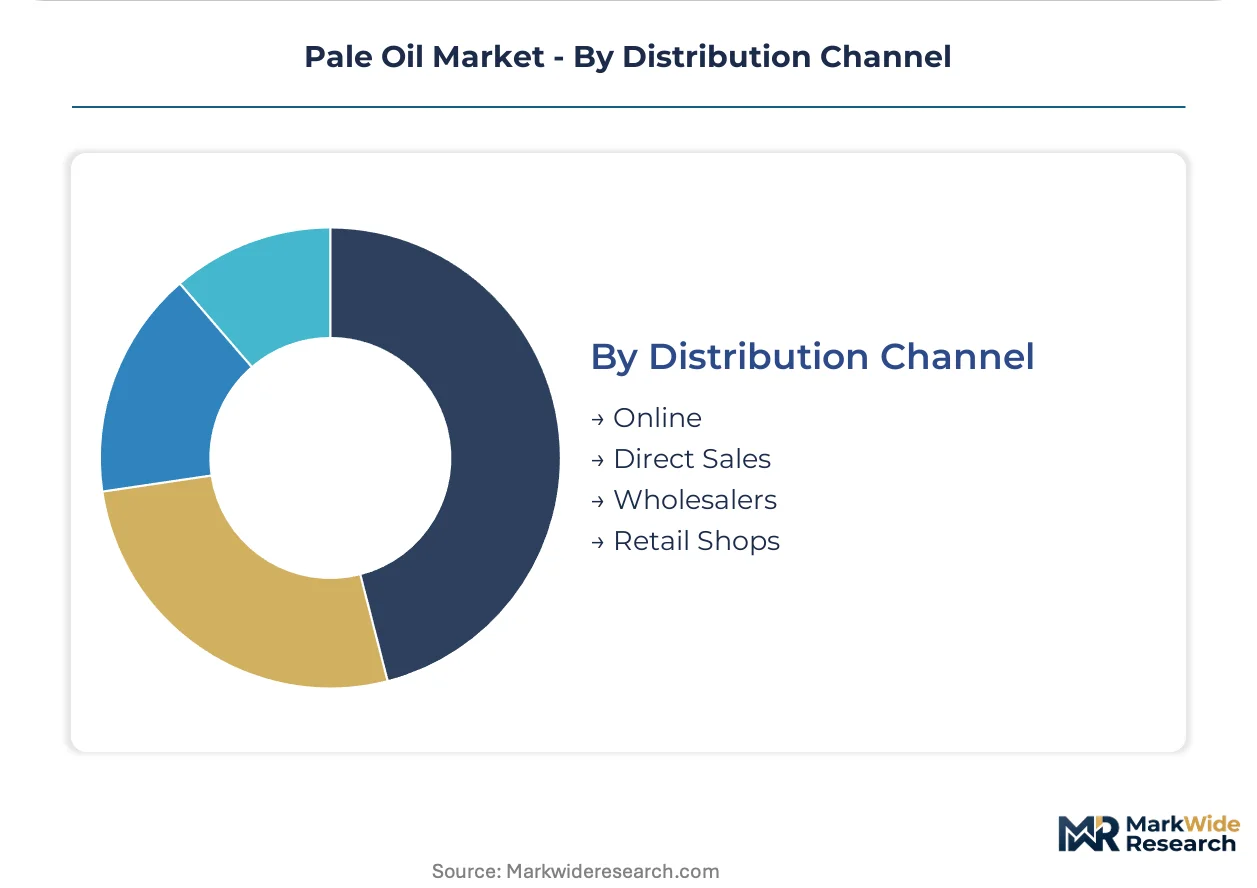
- Direct Sales:Long-term supply agreements with multinational pharmaceutical formulators consolidate procurement volumes into fewer, larger contracts. Exxon Mobil and TotalEnergies anchor European supply through direct relationships with Germany's specialty chemical corridor.
- Online:Digital procurement platforms serve small and mid-sized cosmetics compounders requiring rapid qualification of new grades.
- Wholesalers:Regional chemical wholesalers bridge standalone processors lacking integrated distribution networks.
- Retail Shops:Limited to packaged consumer products in pharmacy and specialty cosmetic retail.
Direct Sales channels capture the majority of pharmaceutical-grade volume. Online platforms are climbing the fastest among cosmetics compounders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's specialty chemical corridor commands premium pale oil procurement, while India's pharmaceutical excipient market accelerates on regulatory alignment with ICH standards.
Germany
Rhine-Ruhr cosmetics manufacturers demand membrane-polished grades with sub-100 ppm aromatic content. REACH registration requirements and EU Green Deal carbon intensity benchmarks force refiners to document supply chain emissions. The specialty chemical corridor concentrates multi-year offtake agreements between integrated suppliers and consolidated pharmaceutical formulators.
United States
FDA 21 CFR 172.878 compliance drives food-grade lubricant applications in processing equipment. EMA residual solvent guidelines influence multinational pharmaceutical formulators with US operations. Gulf Coast refining capacity anchors supply for topical excipient systems serving domestic drug manufacturers.
France
Cosmetic compounders in the Île-de-France region mandate third-party verified Scope 3 emissions data as standard tender documentation. EU Green Deal benchmarks tighten impurity thresholds for REACH-registered pale oils. Lyon-based formulators source severely hydrotreated white oils for premium emollient formulations.
India
CDSCO alignment with ICH Q3C guidelines opens qualification pathways for USP-grade pale oil imports. Maharashtra pharmaceutical clusters expand topical drug delivery applications requiring oxidative stability. Gujarat specialty chemical manufacturers negotiate direct supply relationships with naphthenic oil specialists.
China
Dual carbon goals and GB standards on industrial emissions reshape refinery investment priorities. Yangtze River Delta pharmaceutical formulators adopt pale oil excipients for dermatological products. State-controlled refining capacity dominates hydrotreating infrastructure for domestic cosmetic and food-grade applications.
Pale Oil Market Competitive Landscape
European producers anchor the premium certification tier; Gulf and Asian state-affiliated entities hold volume-scale positions. The competitive structure bifurcates between integrated refiners with captive hydrogen supply and standalone processors facing stranded asset risk. Three archetypes dominate: integrated majors with multi-site delivery networks, naphthenic specialists serving pharmaceutical purity standards, and national oil companies leveraging feedstock access. Capacity expansion in severe hydrotreating and long-term supply agreement consolidation represent the dominant competitive moves reshaping procurement relationships.
Within the integrated major tier, Exxon Mobil Corporation and TotalEnergies SE exemplify geographic anchoring through European distribution networks and direct refinery relationships. Nynas AB occupies the specialist position for naphthenic pale oil grades. Among state-affiliated producers, Saudi Arabian Oil Company and PetroChina Company Limited represent volume-scale capacity backed by captive crude supply. These entities illustrate how competitive positioning tracks hydrotreating intensity, certification documentation capabilities, and carbon accounting transparency rather than scale alone.
| Leading Market Players |
|---|
| Saudi Arabian Oil Company |
| PetroChina Company Limited |
| Exxon Mobil Corporation |
| China National Petroleum Corporation |
| Sinopec |
| Shell plc |
| TotalEnergies SE |
| Chevron Corporation |
| Nynas AB |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between pharmaceutical white oil and industrial mineral oil manifests in contract structures and procurement channels. Buyers of USP-grade material negotiate multi-year offtake agreements with integrated refiners, while commodity-grade purchasers face volatile spot pricing tethered to paraffinic crude benchmarks.
Pricing Analysis
Capacity additions in China's hydrotreating infrastructure are reshaping price floors for standard-grade pale oils. Three-tier pricing structure across pharmaceutical, cosmetic, and industrial grades separates margin pools by certification intensity. Cost compression in mineral oil grades is intensifying because bio-based ester substitutes capture premium cosmetic volumes. Pharmaceutical formulators exhibit lowest price sensitivity due to regulatory qualification costs, while mid-tier cosmetics compounders face acute margin pressure.
Supply Chain Analysis
Reverse-logistics flows for spent catalyst recovery and noble metal reclamation anchor supply chain economics for severe hydrotreating operations. Feedstock concentration centers on Saudi Arabia, Russia, and the United States for paraffinic crude supply. Production draws from specialty chemical corridors in Germany, the US Gulf Coast, and India's Gujarat cluster. Single-source vulnerability persists in hydrotreater catalyst supply dominated by German and Japanese chemical producers. Distribution runs through direct refinery relationships for pharmaceutical-grade volumes and regional chemical wholesalers for industrial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in pale oil hinges on carbon accounting transparency and pharmacopeial certification depth. Hydrotreating intensity upgrades and Scope 3 documentation systems represent the primary cost-down and premium-tier shift mechanisms.
For Market Incumbents: Lock in long-term supply agreements with consolidated pharmaceutical formulators before carbon border adjustment mechanisms fully activate. Defensive moves require captive hydrogen supply investments and membrane-polishing capacity additions in the Rhine-Ruhr corridor. Synthetic ester substitution in cosmetics and hydrotreater catalyst cost inflation constitute immediate threats. Certification investment in USP-grade campaigns and direct channel control over German specialty chemical buyers anchor sustainable positioning. For New Entrants and Emerging Players: Regional chemical distributors in mid-tier cosmetics represent the most accessible channel partner type for qualification-limited entrants. White-space targets include India's Maharashtra pharmaceutical clusters and France's Île-de-France cosmetic compounders requiring third-party verified carbon footprints. The most penetrable segment spans REACH-registered grades for cosmetics where membrane technology lowers capital barriers. A digital procurement platform strategy accelerates qualification timelines for smaller compounders lacking refinery relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with naphthenic specialists possessing pharmaceutical-grade purity capabilities and documented Scope 3 emissions systems. Long-term viability favors integrated refiners with captive hydrogen and multi-site delivery networks over standalone processors facing stranded asset risk. Acquisition targets should display severe hydrotreating intensity, EU Green Deal compliance infrastructure, and existing relationships with Germany's specialty chemical corridor. The signal to watch is carbon border adjustment mechanism implementation timing and pharmacopeial monograph synchronization progress across USP, EP, and JP standards.| Strategic Initiative | Industry Significance |
|---|---|
| Severe Hydrotreating Capacity Expansion | Enables aromatic content below 0.1 percent for REACH-registered cosmetic grades. |
| Backward Integration into Hydrogen Supply | Reduces feedstock cost volatility and secures reactor campaign scheduling flexibility. |
| Membrane Polishing Technology Deployment | Compresses capital requirements for sub-100 ppm aromatic specifications in cosmetics. |
| Long-term Supply Agreement Consolidation | Locks in procurement volumes from multinational pharmaceutical formulators in Germany. |
| Scope 3 Emissions Verification Partnership | Meets EU Green Deal tender requirements for French and German cosmetic compounders. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement included hydrotreating operations managers at integrated refiners, procurement leads at German pharmaceutical formulators, technical directors at French cosmetic compounders, and distribution channel partners across European chemical wholesale networks. Secondary validation drew from ECHA REACH registration databases, FDA 21 CFR filings, EU Green Deal implementation documents, customs trade data for pale oil grades, and SEC disclosures from publicly traded refiners. Bottom-up volume modeling and top-down value triangulation cross-checked segment outputs.
Segment-weighting approaches distributed value across product type, application, and end-user dimensions. The analytical framework modeled grade tier, end-use industry, and regional regulatory cluster throughout the forecast period. CAGRs derived from historical hydrotreating capacity utilization, certification timeline patterns, and carbon intensity disclosure adoption curves. Industry-specific inputs included EMA residual solvent guideline implementation schedules and CDSCO alignment progress with ICH Q3C standards.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to crude feedstock volatility, hydrotreater catalyst supply disruptions, and synthetic ester substitution rates in premium cosmetics. Forecasts reflect documented assumptions on regulatory timeline adherence and carbon border adjustment mechanism scope. Practitioners should monitor pharmacopeial monograph synchronization announcements and EU CBAM sectoral expansion decisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
PAG Base Oil Market
Petroleum Products
Alkylate Gasoline Market
Petroleum Products
Tar Oil Market
Petroleum Products
Petroleum Wax Market
Petroleum Products
United States Refined Petroleum Products Market
Petroleum Products
Spiral Submerged Arc Welded (SSAW) Steel Pipe Market
Petroleum Products
Floating Roof Tank Market
Petroleum Products
Base Oil Market
Petroleum Products
India White Oil Market
Petroleum Products
Africa Refined Petroleum Products Market
Petroleum Products
Liquefied Petroleum Gas Market
Petroleum Products
Oil Shale Market
Petroleum Products
Germany Refined Petroleum Products Market
Petroleum Products
North America Natural Gas Liquids Market
Petroleum Products
South Africa Petroleum Market
Petroleum Products
Naphtha Market