
 Global Liquid Gas Cylinder (LGC) Market | 2026-2036
Global Liquid Gas Cylinder (LGC) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Liquid Gas Cylinder (LGC) Market Foresight
China's manufacturing base expansion is reshaping competitive dynamics in liquid gas cylinder supply. Luxfer Gas Cylinders leverages advanced aluminum alloy formulations to sustain premium positioning in medical and aerospace applications. Worthington Industries anchors North American production through integrated steel processing capabilities. Chart Industries competes on cryogenic system integration, extending its reach beyond standalone cylinders into full gas delivery architectures.
Liquid gas cylinders are pressure vessels engineered to store liquefied gases—oxygen, nitrogen, argon, carbon dioxide, and liquefied petroleum gas—at pressures typically ranging from 150 to 300 bar, constructed from seamless steel, aluminum, or fiber-reinforced composite materials with standardized valve and safety relief systems. These containers serve as the critical interface between bulk gas production and point-of-use consumption across industrial, medical, and specialty gas applications. Steel cylinders retain dominance in high-volume industrial welding due to cost efficiency and established requalification protocols, while composite cylinders capture accelerated growth in medical oxygen supply and portable applications where weight reduction directly enables new use cases. Distribution through specialty dealers concentrates margin pools in calibration, testing, and compliance services rather than commodity cylinder sales alone.
The US Department of Transportation enforces 49 CFR specifications governing cylinder design, fabrication, and periodic requalification, while the EU Pressure Equipment Directive and ISO 9809 harmonize cross-border safety benchmarks. China's SAMR implements GB standards that increasingly align with international norms, reducing friction for exporters but raising compliance costs for domestic manufacturers. Stakeholders must monitor evolving composite material certification pathways and hydrogen-compatible cylinder standards as energy transition applications multiply.
Market Dynamics
Composite cylinder technology is virtualizing traditional steel manufacturing economics across medical and portable gas applications, compressing weight-to-capacity ratios that previously locked suppliers into commodity aluminum and seamless steel production paradigms.
Growth Catalysts
- ISO 9809 certification harmonization:Cross-border safety benchmarks now reduce technical barriers for composite cylinder exporters entering European and Asia-Pacific hospital networks.
- China industrial gas infrastructure scaling:Bulk liquefied gas distribution hubs in Jiangsu and Shandong provinces generate downstream cylinder replacement cycles at manufacturing clusters.
- Filament-wound carbon fiber processes:Automated winding equipment cuts composite cylinder production cycle times, enabling medical oxygen suppliers to meet surge capacity requirements.
Market Restraints
- High-pressure aluminum billet cost volatility:Aerospace-grade alloy feedstock prices swing with London Metal Exchange aluminum premiums, squeezing margin stability for mid-tier cylinder fabricators.
- Steel cylinder requalification protocol rigidity:DOT 49 CFR hydrostatic test mandates every five years create recurring compliance burdens that slow fleet turnover in North American welding supply chains.
- Composite delamination detection limitations:Non-destructive testing methods for fiber-reinforced pressure vessels remain less standardized than steel ultrasonic protocols, elevating insurance and liability exposure.
Strategic Opportunities
- India medical oxygen homecare penetration:Post-pandemic remote patient monitoring infrastructure creates first-mover openings for lightweight portable cylinder suppliers outside established hospital procurement channels.
- Hydrogen-compatible cylinder standards emergence:ISO/TC 58 working groups on hydrogen pressure vessels open certification pathways for composite designs in fuel cell forklift and bus refueling networks.
- Digital cylinder tracking integration:RFID-enabled fleet management systems allow gas distributors to unbundle asset tracking from commodity fill services, capturing recurring software revenue.
Industry Challenges
- Composite pressure vessel engineer scarcity:Specialized expertise in filament winding simulation and burst testing protocols concentrates at a handful of European and North American technical institutes, constraining workforce expansion.
- Multi-standard certification timeline compression:Simultaneous pursuit of DOT, TPED, and GB approvals for global product launches extends qualification periods and defers revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Liquid Gas Cylinder (LGC) Market |
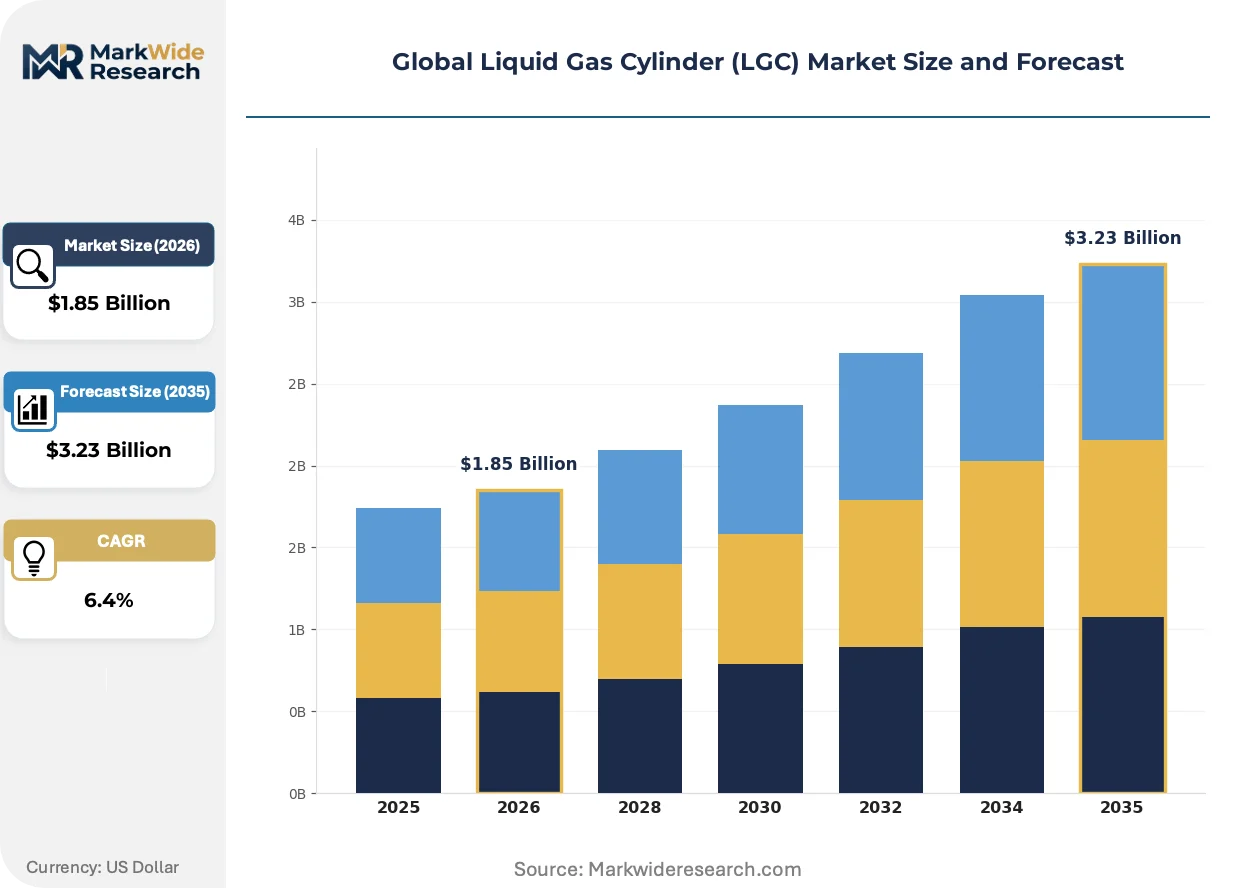
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Cylinders, Aluminum Cylinders, Composite Cylinders, High-Pressure Cylinders, Low-Pressure Cylinders Application: Industrial Welding, Medical Oxygen Supply, Food & Beverage Preservation, Laboratory Gas Storage, Refrigeration End User: Manufacturing Facilities, Hospitals, Laboratories, Food Processing Plants, HVAC Companies Distribution Channel: Direct Sales, Distributors, Online Retailers, Third-Party Logistics, Specialty Dealers |
| Companies Covered | Luxfer Gas Cylinders, Worthington Industries, Air Liquide, Chart Industries, Linde plc, Hexagon Composites, Faber Industrie, Everest Kanto Cylinder, Manchester Tank, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Liquid Gas Cylinder (LGC) Market Shifts & Advancements
Digital thread technologies are virtualizing cylinder lifecycle management from fabrication through retirement, collapsing information asymmetries between manufacturers, gas distributors, and end-use inspectors that historically obscured asset condition and utilization rates.
Filament-wound carbon fiber overwrapped pressure vessels (COPVs) with aluminum or polymer liners are virtualizing the weight-performance frontier in emergency medical services and home oxygen therapy. Ambulance operators and respiratory equipment suppliers are adopting these designs at accelerating rates to extend portable oxygen duration without compromising patient mobility. This technology is virtualizing the historical trade-off between cylinder capacity and transportability that constrained clinical workflow design.
REACH Regulation Annex XVII restrictions on persistent organic pollutants and the EU F-Gas Regulation phase-down schedules are tightening material traceability requirements for cylinder valve seals and lubricants. Industrial gas suppliers must now document fluorinated gas containment across their cylinder fleets or face distribution penalties. Medical and specialty gas segments in Germany and France are responding by specifying perfluoropolyether-free valve designs in new procurement tenders.
Hospital network consolidation is compressing procurement cycles and unbundling cylinder asset ownership from gas supply contracts. Integrated delivery networks in the United States are shifting toward managed cylinder pool programs where third-party logistics providers track utilization and maintenance. This behavioral pivot is most visible in Texas and Florida health systems where private equity-backed hospital rollups have centralized supply chain decision-making away from individual facility purchasing managers.
Global Liquid Gas Cylinder (LGC) Market Segmentation
Liquid gas cylinder segmentation reveals divergent technology economics across material classes and end-use requirements. Procurement patterns in medical oxygen diverge sharply from industrial welding, creating distinct margin pools and certification pathways.
Product Type:
Mature steel and aluminum formats anchor industrial volume, while emerging composite designs unlock weight-sensitive applications previously unreachable with metal construction.
- Steel Cylinders:Seamless carbon steel construction withstands 200-300 bar operating pressures with established DOT 49 CFR requalification protocols. Demand concentrates in US and German manufacturing clusters where welding gas distributors prioritize cost-per-fill-cycle over transport weight.
- Composite Cylinders:Filament-wound carbon fiber over aluminum or polymer liners achieve 50-70% weight reduction versus steel equivalents. Medical oxygen suppliers in Japan and ambulance operators in France adopt these designs to extend portable duration without compromising patient mobility.
- Aluminum Cylinders:Aerospace-grade alloy formulations from Luxfer and Worthington serve calibration gas and specialty applications requiring corrosion resistance.
- High-Pressure Cylinders:300+ bar ratings for hydrogen fuel cell and CNG vehicle refueling infrastructure.
- Low-Pressure Cylinders:Sub-150 bar designs for liquefied petroleum gas distribution in residential and commercial heating.
Steel cylinders retain volume leadership; composite cylinders hold the steepest expansion curve.
Application:
Cost tier differentiation separates commodity industrial gases from premium medical and specialty gas handling where contamination control commands price multiples.
- Industrial Welding:Oxygen-acetylene and shielding gas delivery for metal fabrication. Steel cylinders dominate Chinese and US construction markets where fleet turnover cycles align with five-year hydrostatic test mandates.
- Medical Oxygen Supply:Respiratory therapy and emergency transport applications requiring US FDA and EU MDR compliance. Composite cylinder adoption accelerates in Indian homecare networks and Japanese hospital systems prioritizing patient mobility.
- Food & Beverage Preservation:Carbon dioxide for beverage carbonation and modified atmosphere packaging. Aluminum cylinders preferred for flavor-critical applications.
- Laboratory Gas Storage:High-purity carrier and calibration gases demanding specialized valve configurations and internal surface treatments.
- Refrigeration:Industrial cooling and cryogenic preservation systems integrating cylinders with vaporizer equipment.
Industrial welding commands the largest installed base; medical oxygen supply is climbing the fastest.
End User:
Customer type fragmentation creates divergent procurement behaviors between centralized hospital networks and distributed manufacturing facilities.
- Manufacturing Facilities:Steel-intensive welding and cutting operations in automotive and shipbuilding sectors across China, South Korea, and Germany.
- Hospitals:Consolidated US health systems in Texas and Florida shifting toward managed cylinder pool programs with third-party logistics tracking.
- Laboratories:Research and quality control facilities requiring traceable calibration gas certification.
- Food Processing Plants:Modified atmosphere packaging lines and cold storage operations.
- HVAC Companies:Refrigerant recovery and charging equipment for installation and service.
Manufacturing facilities maintain the deepest cylinder penetration; hospitals are gaining share fastest through outsourcing.
Distribution Channel:
Supply concentration varies from direct manufacturer relationships for high-volume industrial accounts to fragmented specialty dealer networks capturing calibration and compliance service margins.
- Direct Sales:Large industrial gas producers—Air Liquide, Linde, Air Products—supplying integrated steel and chemical complexes with dedicated fleet management.
- Distributors:Regional welding supply houses bundling cylinder exchange with consumables across North American fabrication markets.
- Online Retailers:Emerging channel for small-volume specialty and medical oxygen accessories.
- Third-Party Logistics:Asset-light pool management providers tracking utilization via RFID for hospital networks.
- Specialty Dealers:Calibration gas and high-purity specialists concentrating margin in testing and certification services rather than commodity cylinder sales.
Distributors retain the broadest geographic coverage; third-party logistics providers are expanding most quickly through digital fleet integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR's alignment of GB standards with ISO 9809 has reduced export friction for Chinese cylinder manufacturers while elevating compliance costs for domestic fabricators. This regulatory pivot concentrates investment in Jiangsu and Shandong manufacturing clusters.
United States
Hospital network consolidation in Texas and Florida drives managed cylinder pool outsourcing to third-party logistics providers. DOT 49 CFR hydrostatic test mandates every five years slow fleet turnover in welding supply chains. Pittsburgh and Houston anchor steel-intensive industrial gas distribution.
Germany
REACH Annex XVII restrictions on persistent organic pollutants tighten material traceability for cylinder valve seals. The EU F-Gas Regulation phase-down schedules force documentation of fluorinated gas containment. The Ruhr industrial corridor sustains demand for high-pressure welding gas cylinders.
China
Bulk liquefied gas distribution hubs in Jiangsu and Shandong provinces generate downstream cylinder replacement cycles. SAMR's GB standard harmonization with ISO norms reduces technical barriers for composite cylinder exporters. Yangtze River Delta manufacturing clusters absorb automated filament-winding equipment.
India
Post-pandemic remote patient monitoring infrastructure creates first-mover openings for lightweight portable cylinder suppliers. CDSCO medical device regulations govern oxygen therapy equipment compliance. Maharashtra and Karnataka hospital networks prioritize patient mobility in procurement specifications.
Japan
Medical oxygen suppliers adopt composite designs to extend portable duration without compromising patient mobility. METI industrial standards govern pressure vessel certification pathways. Osaka and Nagoya manufacturing bases integrate carbon fiber overwrapped pressure vessels into emergency medical services.
Global Liquid Gas Cylinder (LGC) Market Competitive Landscape
Capability concentration sits with composite pressure vessel specialists; scale advantage sits with integrated steel processors. The market structures around three tiers: filament-wound carbon fiber innovators, seamless steel volume producers, and aluminum alloy premium-positioned suppliers. Strategic moves concentrate on automated winding equipment deployment and multi-standard certification timeline compression for global product launches.
Among North American fabricators, Luxfer Gas Cylinders and Worthington Industries occupy positions at opposite ends of the material spectrum. Luxfer represents the aerospace-grade aluminum alloy tier serving calibration and specialty gas applications. Worthington anchors integrated steel processing capabilities for industrial welding markets. Chart Industries exemplifies cryogenic system integration, extending competitive positioning beyond standalone cylinders into full gas delivery architectures.
| Leading Market Players |
|---|
| Luxfer Gas Cylinders |
| Worthington Industries |
| Air Liquide |
| Chart Industries |
| Linde plc |
| Hexagon Composites |
| Faber Industrie |
| Everest Kanto Cylinder |
| Manchester Tank |
| Others |
Supply & Pricing Matrix
The Shanghai-Rotterdam maritime corridor's freight cost volatility transmits directly into landed cylinder pricing, compressing margins for European distributors sourcing composite pressure vessels while amplifying price differentiation between regional manufacturing clusters and import-dependent markets.
Pricing Analysis
Geographic price spreads between Jiangsu manufacturing hubs and European distribution centers exceed 40 percent on equivalent composite cylinder specifications. Three-tier pricing structure across medical-grade ISO 9809-certified, industrial-standard DOT 49 CFR, and economy non-certified tiers dominates procurement negotiations. Pricing pressure stems from aluminum billet cost volatility indexed to London Metal Exchange premiums. Hospital networks demonstrate lowest price sensitivity due to patient mobility requirements, while construction welding suppliers operate on thin fill-cycle margins.
Supply Chain Analysis
Contract manufacturing concentrates at Worthington Industries' integrated steel facilities, Luxfer's aluminum extrusion operations, and Chart Industries' cryogenic system assembly plants. Geographic supply concentration centers on China, the United States, and Germany for finished cylinder fabrication, with carbon fiber prepeg sourcing from Japan and South Korea. Raw material dependencies include aerospace-grade aluminum billet, high-tensile steel plate, and filament-wound carbon fiber tow. Single-source vulnerability runs through Japanese carbon fiber suppliers for medical-grade COPV liners. Distribution runs through industrial gas majors—Air Liquide, Linde, Air Products—operating dedicated fleet logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The liquid gas cylinder market operates as a substitution defense against bulk cryogenic tanker delivery and on-site gas generation systems that threaten portable cylinder economics in hospital and industrial accounts.
For Market Incumbents: Build certification moats through simultaneous DOT, TPED, and GB standard pre-qualification to compress multi-market launch timelines. Secure filament-winding engineering talent through partnerships with European technical institutes. Defend against bulk tanker substitution by embedding RFID tracking into managed cylinder pool programs that lock hospital networks into asset-light service contracts rather than commodity sales. For New Entrants and Emerging Players: Post-pandemic home oxygen infrastructure in Maharashtra and Karnataka represents the most penetrable entry point outside established hospital procurement channels. Automated filament-winding equipment deployment in Yangtze River Delta manufacturing clusters enables cost parity with incumbent steel cylinder producers. Target third-party logistics partnerships with private equity-backed health systems in Texas and Florida that have centralized supply chain decision-making away from individual facility purchasing. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with under-optimized cylinder divisions lacking composite pressure vessel capabilities. Long-term viability hinges on hydrogen-compatible cylinder certification as fuel cell forklift and bus networks scale. Monitor ISO/TC 58 working group progress on hydrogen pressure vessel standards as the inflection signal for composite design premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Standard Certification Pre-Qualification | Simultaneous DOT, TPED, and GB approvals compress global product launch timelines by eliminating sequential testing. |
| Automated Filament-Winding Deployment | Carbon fiber overwrapped pressure vessel production cycle cuts enable medical oxygen surge capacity response. |
| RFID-Enabled Fleet Management Integration | Digital tracking unbundles asset management from commodity fill services, capturing recurring software revenue streams. |
| Hydrogen-Compatible Cylinder Development | ISO/TC 58 certification pathways open fuel cell forklift and bus refueling network participation. |
| Third-Party Logistics Partnership Structuring | Asset-light pool management contracts with consolidated hospital networks shift procurement toward outsourced cylinder lifecycle services. |
Research Methodology
Cross-validation between primary interviews with cylinder manufacturing executives, gas distribution procurement leads, and hospital biomedical engineering directors anchors the qualitative findings against secondary validation from DOT 49 CFR docket filings, SAMR GB standard publications, and ISO/TC 58 working group documentation. Bottom-up installed base modeling triangulates against top-down industrial gas consumption data from national statistics bureaus.
Calibration against historical cylinder replacement cycles and medical oxygen demand surges informs the projection framework. Segmentation dimensions span material class, pressure rating tier, application vertical, and regional regulatory cluster. CAGRs derive from weighted average of equipment replacement velocity and end-use demand elasticity. Industry-specific inputs include SAMR harmonization timelines and filament-winding automation adoption curves.
Macroeconomic conditions sit as an overlay; deviation in aluminum London Metal Exchange premiums, maritime freight indices, or hospital capital expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions regarding standard harmonization progress and composite material certification pathway clarity. Quarterly review of ISO/TC 58 hydrogen vessel standards, SAMR enforcement intensity, and Indian CDSCO medical device registration volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Hydrogen Fuel Tanks Market
Fuels
White Coal Market
Fuels
CNG Dispenser Market
Fuels
Synthetic Natural Gas (SNG) Market
Fuels
Aerospace Aviation Fuels Market
Fuels
Chafing Fuel Market
Fuels
Gasoline Octane Improvers Market
Fuels
South America Bunker Fuel Market
Fuels
India City Gas Distribution (CGD) Market
Fuels
India LNG Market
Fuels
Middle-East and Africa Defense Aircraft Aviation Fuel Market
Fuels
India Liquified Petroleum Gas (LPG) Market
Fuels
Wood Charcoal Market
Fuels
South Africa Bunker Fuel Market
Fuels
Asia-Pacific Bunker Fuel Market
Fuels
Turbine Drip Oil Market