
 Tar Oil Market | 2026-2036
Tar Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Tar Oil Market Analytics
Capital-intensity divergence between integrated refiners and regional blenders is reorganizing competitive tiers across the tar oil landscape. BP PLC leverages its upstream bitumen access to sustain integrated margins through captive feedstock. Shell PLC anchors its position through specialized refining configurations that differentiate on product consistency. ConocoPhillips competes via geographic dominance in North American heavy oil corridors where logistics scale matters.
Tar oil comprises complex hydrocarbon mixtures derived from the destructive distillation of organic materials such as coal or wood, or as a byproduct of petroleum refining, typically containing phenols, cresols, xylenols, and heavier aromatic compounds with boiling ranges from 200 to 400 degrees Celsius; its primary industrial purpose centers on binder applications in road construction and protective waterproofing systems. Refined Tar leads product type value capture due to specification-grade consistency demanded by infrastructure contracts, while Modified Tar represents the fastest-growing category as polymer-enhanced formulations displace conventional grades in high-performance paving. The Roofing Sector end user segment occupies mature margin pools in developed economies, whereas Chemical Manufacturing applications are deepening in Asia as aromatic feedstock demand expands.
EPA standards in the United States and REACH in Europe jointly constrain permissible polycyclic aromatic hydrocarbon content, forcing reformulation investments and shifting procurement toward certified-refined supply chains. China's MEE enforces emission controls on tar distillation facilities that limit regional capacity expansion and redirect trade flows. India's BIS certification requirements for road-grade binders create non-tariff barriers that favor domestic producers with established testing protocols. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and sourcing realignments.
Market Dynamics
Polymer modification chemistry is compressing the performance gap between conventional tar binders and synthetic alternatives, forcing reformulation investments across the supplier base while opening specification-grade contracts to new entrants with advanced blending capabilities.
Growth Catalysts
- India's National Highway Development Programme:Central government road construction budgets are absorbing record volumes of refined tar products for expressway and rural connectivity projects.
- REACH-compliant refined grades:European infrastructure contractors are consolidating procurement around certified-low-PAH supply chains that command specification premiums in public tenders.
- Polymer-enhanced modified tar:SBS and EVA additive systems are extending pavement service life in tropical climates where thermal cycling degrades conventional binders.
Market Restraints
- Crude oil-coupled feedstock costs:Vacuum residue and heavy sour crude differentials transmit volatility directly into tar oil production economics without hedging instruments available to regional blenders.
- Chinese MEE emission ceilings:Distillation capacity expansion in Shandong and Jiangsu provinces faces hard caps on atmospheric emissions that redirect export volumes toward Southeast Asian buyers.
- Bitumen substitution in warm-mix applications:Foamed asphalt and chemical additive systems are capturing specification share in temperature-sensitive paving contracts previously reserved for tar-modified binders.
Strategic Opportunities
- Vietnam's Mekong Delta infrastructure corridor:Deltaic soil conditions and monsoon exposure create demand for waterproofing-grade tar products in bridge and embankment applications.
- US EPA Brownfields remediation mandates:Contaminated site redevelopment rules are stimulating demand for tar-based sealants in landfill capping and vapor intrusion barrier systems.
- Direct-to-contractor digital platforms:B2B procurement marketplaces are disintermediating traditional distributor networks for standard-grade products in price-transparent spot transactions.
Industry Challenges
- Distillation operator certification gaps:Experienced process engineers capable of managing coal-tar fractionation units are retiring faster than vocational training programs replenish the workforce.
- Multi-jurisdictional PAH testing protocols:Divergent EPA, REACH, and BIS analytical methods force producers to maintain parallel laboratory accreditations that extend product qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tar Oil Market |
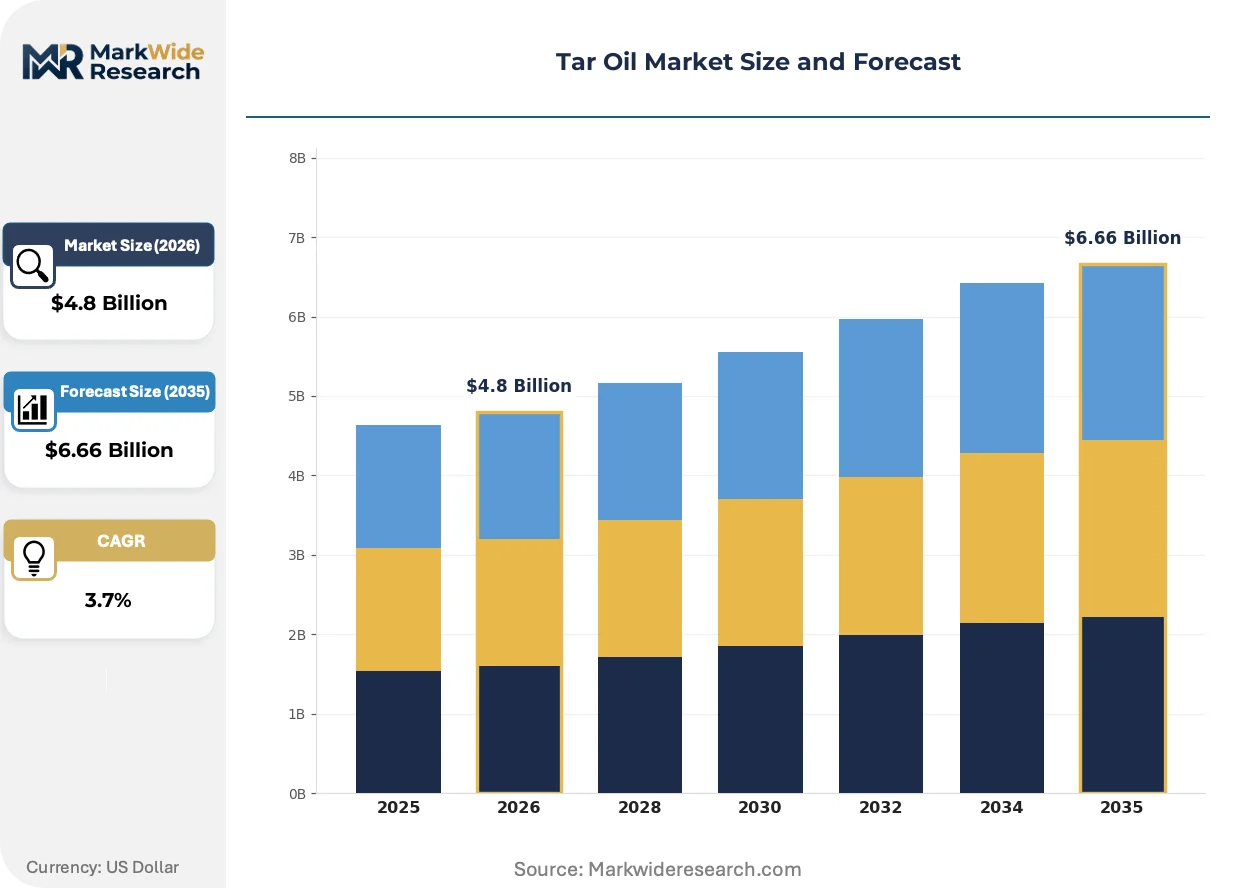
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Tar, Synthetic Tar, Modified Tar, Refined Tar End User: Paving Industry, Roofing Sector, Chemical Manufacturing, Energy Production Application: Road Construction, Waterproofing, Adhesives, Coatings Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | BP PLC, Shell PLC, Chevron Corp, Exxon Mobil Corp, Canadian Natural Resources Ltd, Cenovus Energy Inc, ConocoPhillips, China National Petroleum Corp, LUKOIL PJSC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tar Oil Market Evolving Landscape
Formulation science is converging with digital quality assurance systems to compress development cycles and enable real-time compliance verification across dispersed production networks.
Polymer-microencapsulation technology is miniaturizing additive delivery systems within tar matrices, enabling uniform SBS distribution without high-shear milling equipment. Municipal paving authorities in Brazil and Indonesia are piloting these pre-blended formats to reduce field variability. The technology is miniaturizing capital barriers for mid-scale blenders seeking specification-grade output without continuous production infrastructure.
EPA's updated National Emission Standards for Hazardous Air Pollutants are tightening benzene fugitive emission limits at tar storage and transfer facilities. Refiners are retrofitting floating roof tanks and vapor recovery units to maintain operating permits. Storage terminal operators in the US Gulf Coast corridor face the steepest compliance deadlines and are accelerating capital deployment ahead of enforcement phases.
Contractor procurement teams are consolidating supplier panels around integrated quality-documentation systems that bundle material certification with logistics tracking. Large infrastructure developers in India and Australia are displacing spot-market purchasing with multi-year framework agreements that embed compliance data directly into ERP workflows. This concentration is most advanced on federally funded projects where audit trails carry liability weight.
Tar Oil Market Segmentation
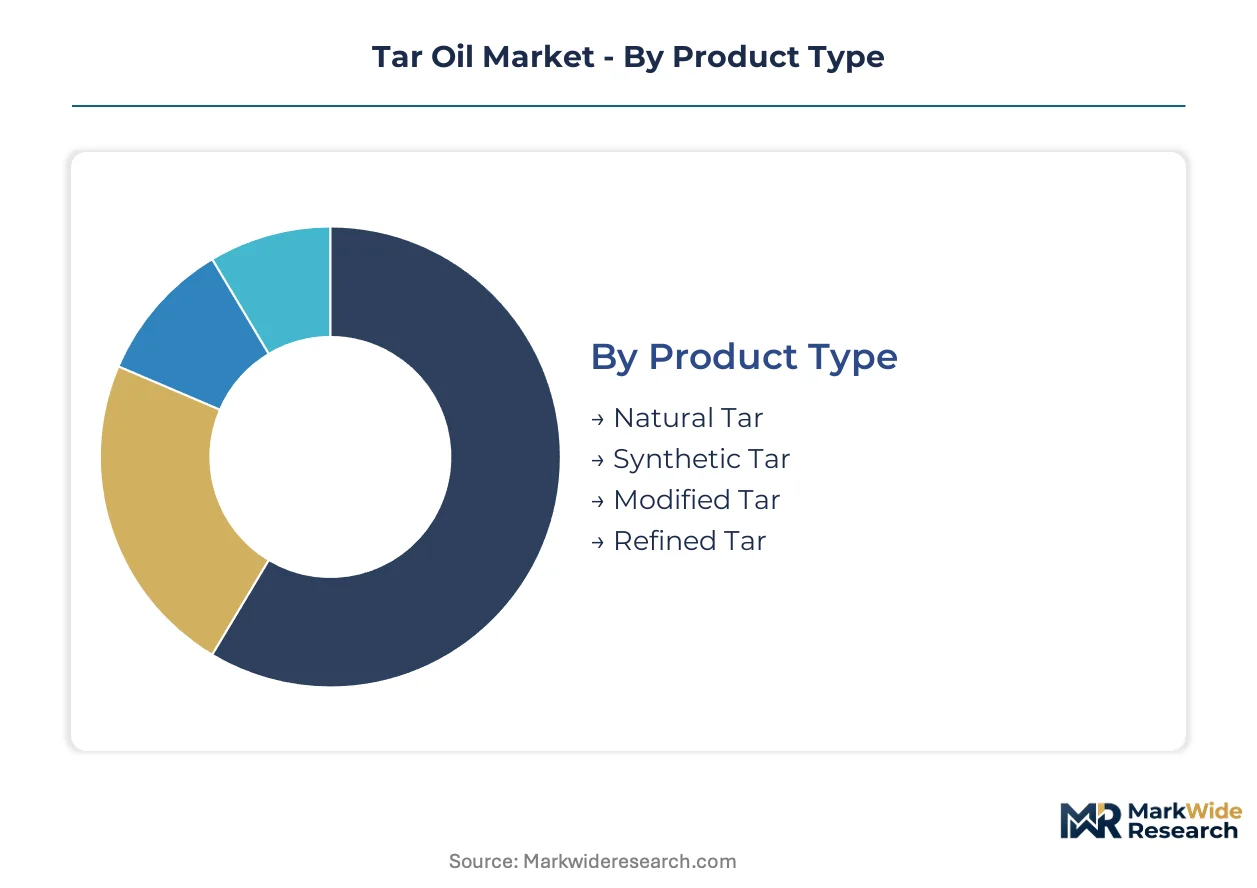
Tar oil segmentation reflects divergent supply chain architectures across product grades and end-use applications. Specification requirements from infrastructure contractors and chemical processors create distinct procurement channels that reshape competitive positioning in each category.
Product Type:
Refined Tar and Modified Tar dominate export-led supply chains serving international infrastructure contractors, while Natural Tar and Synthetic Tar concentrate in domestic markets with established coal-chemical or petroleum-refining bases.
- Refined Tar:Vacuum-distilled fractions meeting low-PAH specifications for highway binders. European REACH-compliant tenders and India's National Highway Development Programme absorb the bulk of specification-grade volumes, with certified supply chains commanding procurement premiums.
- Modified Tar:Polymer-enhanced formulations incorporating SBS or EVA additives for thermal stress resistance. Tropical climate paving contracts in Brazil and Indonesia drive formulation innovation as service-life requirements extend beyond conventional binder performance.
- Natural Tar:Coal-creosote derivatives from destructive distillation serving traditional wood preservation and marine piling applications.
- Synthetic Tar:Petroleum-based alternatives from catalytic cracking or steam cracking byproduct streams, competing on feedstock cost stability.
Refined Tar commands the established base. The steepest expansion runs through Modified Tar.
End User:
Cost-tier stratification separates specification-sensitive public infrastructure buyers from price-driven industrial processors, with margin structures diverging sharply across these customer categories.
- Paving Industry:Public works contractors consuming refined and modified grades for asphalt binders. India's central government road budgets and US state DOT specifications concentrate demand for certified-low-PAH products that carry documentation requirements through project completion.
- Chemical Manufacturing:Aromatic feedstock processors extracting phenols, cresols, and naphthalene for downstream synthesis. Asian petrochemical corridors deepen vertical integration into tar distillation to secure captive aromatic supply.
- Roofing Sector:Waterproofing membrane producers in mature North American and European construction markets.
- Energy Production:Combustion applications for process heat in carbon-black manufacturing and metallurgical operations.
Paving Industry absorbs the dominant volume share. Chemical Manufacturing is climbing the fastest as aromatic feedstock demand expands.
Application:
Volume concentration tracks infrastructure investment cycles, with road construction absorbing bulk commodity flows while specialty applications sustain differentiated margin pools.
- Road Construction:Binder applications in asphalt concrete and surface treatments. India's expressway buildout and Southeast Asian rural connectivity programs absorb record volumes of refined tar products through multi-year framework agreements.
- Waterproofing:Bridge deck membranes, roofing systems, and below-grade barrier applications. Vietnam's Mekong Delta infrastructure corridor creates specification demand for moisture-resistant formulations in deltaic soil conditions.
- Adhesives:Industrial bonding agents leveraging tar's adhesive properties and chemical resistance.
- Coatings:Protective surface treatments for marine, pipeline, and structural steel applications.
Road Construction anchors the volume base. Waterproofing is gaining share fastest as climate-adaptation infrastructure accelerates.
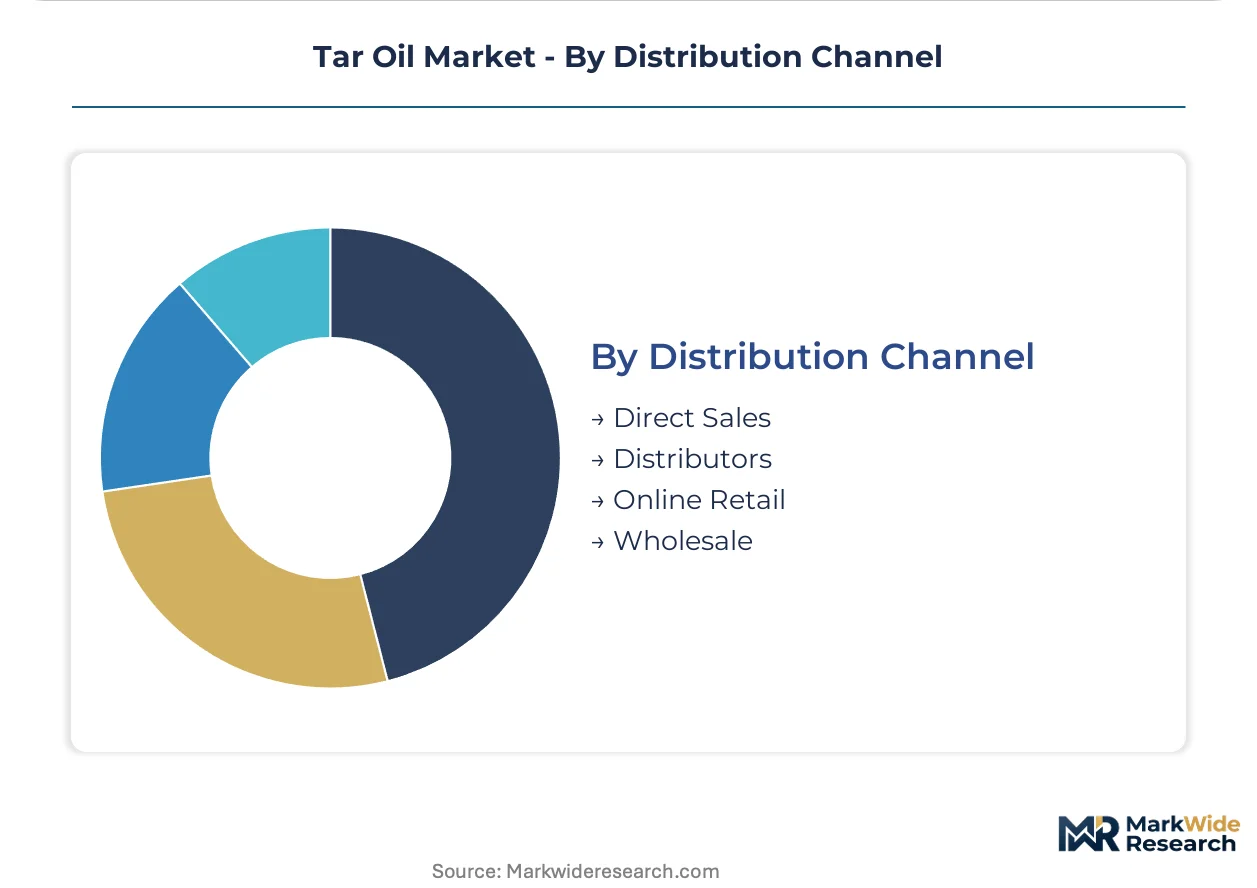
Distribution Channel:
Customer-type stratification separates large contractor direct relationships from fragmented spot-market purchasing, with digital platforms beginning to compress traditional distributor margins.
- Direct Sales:Long-term supply agreements between integrated refiners and national infrastructure developers. India's NHAI and Australia's federal project authorities consolidate procurement around embedded compliance documentation systems.
- Distributors:Regional stockists serving mid-scale contractors with fragmented demand patterns and irregular project timing.
- Wholesale:Bulk terminal operators supplying blending facilities and secondary processors.
- Online Retail:Emerging B2B platforms enabling spot-market price discovery and disintermediation for standard-grade products.
Direct Sales commands the value concentration. Online Retail is expanding most quickly as procurement digitization penetrates construction supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in tar oil track refinery output corridors and infrastructure investment cycles, with surplus regions exporting refined grades to deficit markets where domestic distillation capacity lags road construction demand. Import dependence concentrates in economies with expanding highway programs but limited upstream bitumen access.
United States
Gulf Coast refineries supply modified binders to state DOT specifications across the Sun Belt, where thermal stress resistance commands premium pricing. EPA's updated National Emission Standards for Hazardous Air Pollutants mandate vapor recovery retrofits at storage terminals ahead of enforcement deadlines. Houston and Corpus Christi anchor the export base, with terminal operators accelerating capital deployment to maintain operating permits.
India
The National Highway Development Programme absorbs record volumes of refined tar through multi-year framework agreements with embedded compliance documentation. BIS certification requirements for road-grade binders create non-tariff barriers favoring domestic producers with established testing protocols. Industrial clusters in Gujarat and Maharashtra concentrate distillation capacity serving western and southern expressway corridors.
China
Shandong and Jiangsu province refiners face hard emission caps under MEE regulations that redirect export volumes toward Southeast Asian buyers. Domestic demand concentrates in provincial road budgets and aromatic feedstock processing for downstream chemical synthesis. The Yangtze River Delta hosts the deepest concentration of coal-tar fractionation units serving both construction and petrochemical offtake.
Germany
REACH-compliant refined grades command specification premiums in public tenders across federal infrastructure contracts. The country's national pharmaceutical regulator influences occupational exposure standards that extend into construction chemical applications. The Rhine-Ruhr industrial corridor sustains specialized refining configurations optimized for low-PAH product consistency.
Brazil
Municipal paving authorities in São Paulo and Rio de Janeiro pilot polymer-microencapsulated pre-blended formats to reduce field variability. Tropical climate contracts drive formulation innovation as service-life requirements extend beyond conventional binder performance. ANVISA oversight of construction chemical safety shapes import qualification timelines for modified tar products.
Tar Oil Market Competitive Landscape
Concentration sits with integrated petroleum refiners that leverage captive heavy crude access to sustain margin positions through upstream-downstream coordination. The competitive structure tiers between global majors with dedicated bitumen units, national oil companies with regional distribution dominance, and specialized blenders competing on formulation agility. Two archetypes define the field: upstream-integrated refiners optimizing feedstock economics, and technology-led modifiers capturing specification premiums through polymer innovation. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with players securing long-term offtake agreements to anchor volume commitments.
Within the integrated refiner tier, BP PLC and Shell PLC exemplify archetypes of upstream-integrated and specialized-refining positioning respectively. ConocoPhillips occupies a position reflecting geographic concentration in North American heavy oil corridors. These entities anchor the competitive field without exhausting its diversity, as regional blenders and national oil companies populate adjacent tiers with distinct capability profiles.
| Leading Market Players |
|---|
| BP PLC |
| Shell PLC |
| Chevron Corp |
| Exxon Mobil Corp |
| Canadian Natural Resources Ltd |
| Cenovus Energy Inc |
| ConocoPhillips |
| China National Petroleum Corp |
| LUKOIL PJSC |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between Indian highway authorities and domestic refiners lock in both feedstock access and price visibility across multi-year infrastructure buildouts, insulating contract holders from vacuum residue volatility that punishes spot-market participants.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake pricing structure where specification-grade refined tar commands premiums tied to REACH certification and BIS compliance documentation. Price differentiation rests on quality grade and certification level, with low-PAH certified products separating from standard grades. Cost compression in the economy tier is intensifying because crude-coupled feedstock volatility transmits directly into production economics. Mid-scale regional blenders exhibit the highest price sensitivity, while integrated refiners with captive heavy crude access maintain margin resilience.
Supply Chain Analysis
Strategic stockpile preferences dominate among Indian and Chinese state contractors managing monsoon-season construction windows, whereas just-in-time procurement prevails among European infrastructure developers with predictable tender calendars. Geographic supply concentrates in India, China, and the United States Gulf Coast corridor. Raw material dependencies draw from vacuum residue, heavy sour crude differentials, and coal-tar pitch feedstocks. Single-source vulnerability around Shandong province distillation units under MEE emission caps poses structural risk. Distribution runs through direct sales agreements with national infrastructure developers and bulk terminal operators serving secondary blenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Experienced process engineers capable of managing coal-tar fractionation units are retiring faster than vocational programs replenish the workforce, compressing operational capability availability across the supplier base.
For Market Incumbents: Consolidate around embedded compliance documentation systems that bundle material certification with logistics tracking, locking in multi-year framework agreements with India's NHAI and Australia's federal project authorities. Add distillation capacity in Gujarat and Maharashtra industrial clusters to capture National Highway Development Programme volume growth. Invest in polymer-microencapsulation R&D to defend specification-grade positioning against synthetic binder substitution.
For New Entrants and Emerging Players: Differentiate on formulation agility by targeting Vietnam's Mekong Delta infrastructure corridor where deltaic soil conditions and monsoon exposure create unmet demand for waterproofing-grade tar products. Pursue direct-to-contractor digital platforms for standard-grade spot transactions, disintermediating traditional distributor networks in price-transparent procurement channels.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated refiners with captive heavy crude access and established testing protocol certifications. Acquisition targets should display backward integration into vacuum residue supply or specialized SBS blending capabilities. Watch for EPA enforcement phase acceleration around benzene fugitive emission limits as the inflection indicator that triggers distressed asset availability among non-compliant terminal operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Adding distillation units in Gujarat industrial clusters captures National Highway Development Programme volume commitments. |
| Backward Integration | Captive vacuum residue supply insulates margin positions from crude volatility transmitted through spot feedstock markets. |
| Long-term Supply Agreement | Multi-year framework agreements with Indian and Australian federal authorities embed compliance data into ERP workflows. |
| Joint Venture | Partnerships with polymer additive suppliers accelerate SBS microencapsulation technology deployment in tropical climate markets. |
| Green Manufacturing Transition | Low-PAH refining configurations meet REACH and EPA standards while commanding specification premiums in public tenders. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs and trade data, SEC filings from integrated petroleum refiners, and national highway authority procurement records across the analysis window. Primary interviews engaged plant managers at coal-tar fractionation units, procurement leads at downstream paving contractors, distribution channel partners in bulk terminal operations, and technical R&D directors in polymer modification chemistry. Secondary validation drew from EPA emission standard filings, BIS certification registries, and ECHA REACH compliance databases. Bottom-up volume modeling triangulates against top-down macroeconomic infrastructure investment forecasts.
Segmentation dimensions modeled span product type tier, end-use industry concentration, application format, and regional regulatory cluster across the projection horizon. CAGRs derive from trend extrapolation anchored in disclosed infrastructure budget allocations and historical offtake patterns. Forecast inputs incorporate vacuum residue price differentials, MEE emission ceiling enforcement trajectories, and polymer additive cost curves.
Material uncertainties — feedstock volatility, regulatory enforcement timing, and substitution technology penetration rates — sit outside the modeled envelope. Forecasts reflect assumptions around continued highway program execution and certification protocol stability. Revision becomes warranted when bitumen substitution in warm-mix applications crosses threshold penetration in specification-sensitive contracts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Europe Ethane Market
Petroleum Products
Liquefied Petroleum Gas Market
Petroleum Products
Automotive Oil Strainer Market
Petroleum Products
Underground Storage Tanks Market
Petroleum Products
Paraffin Oil Market
Petroleum Products
Malaysia Refined Petroleum Products Market
Petroleum Products
Automotive Oil Market
Petroleum Products
Crude Tall Oil Market
Petroleum Products
Crude Oil Pour Point Depressant Market
Petroleum Products
Crude Oil Market
Petroleum Products
Oil Shale Market
Petroleum Products
Crude Oil Flow Improvers Market
Petroleum Products
France Refined Petroleum Product Market
Petroleum Products
Southeast Asia Refined Petroleum Products Market
Petroleum Products
Australia Refined Petroleum Products Market
Petroleum Products
Base Oil Market