
 DC Circuit Breaker Market | 2026-2036
DC Circuit Breaker Market Size, Share, and Industry Trends Forecast 2026-2036
DC Circuit Breaker Market Intelligence
The increasing modularization of DC circuit breaker components into pre-assembled panel units is recalibrating buyer preferences toward simplified installation and maintenance. This trend benefits large-scale deployments in data centers and electric vehicle charging infrastructure. Schneider Electric leverages its extensive distribution network to capitalize on this shift. Meanwhile, ABB specializes in high-voltage solutions for utility-scale renewable projects, and Siemens Energy positions its portfolio for industrial and grid applications.
A DC circuit breaker is an automatic electrical switch designed to protect a direct current circuit from damage caused by overcurrent or short circuit. Its core function involves extinguishing a stable DC arc, which lacks the zero-crossing point found in AC systems. Molded Case Circuit Breaker variants dominate the industrial end-user segment due to their robustness and higher current ratings. Concurrently, the renewable energy segment shows strong demand for Miniature Circuit Breakers for distributed generation systems.
Global product design and market access are governed by standards such as the IEC 60947 series for low-voltage switchgear. In key markets, compliance with specific national standards like UL 489B in the United States and GB standards in China is mandatory for market entry. Navigating these varied certification pathways while managing the cost of advanced arc-quenching technologies remains a critical challenge for manufacturers.
Market Dynamics
The fundamental shift from alternating current to direct current in power generation and transmission systems is the central force shaping the market. This transition, driven by renewable energy sources and high-voltage direct current networks, creates inherent demand for specialized protection devices.
Growth Catalysts
- Policy Mandates:China's dual carbon goals and Europe's Green Deal are accelerating investments in solar, wind, and HVDC infrastructure, which depend on reliable DC circuit protection for operational safety and grid stability.
- EV Infrastructure Expansion:The global build-out of high-power DC fast-charging stations for electric vehicles creates a substantial, high-volume demand driver for circuit breakers designed to handle high DC loads and frequent switching cycles.
- Technological Advancement:The development of more efficient and cost-effective solid-state and hybrid DC circuit breakers is expanding their application scope from niche utility projects to broader industrial and commercial use cases.
Market Restraints
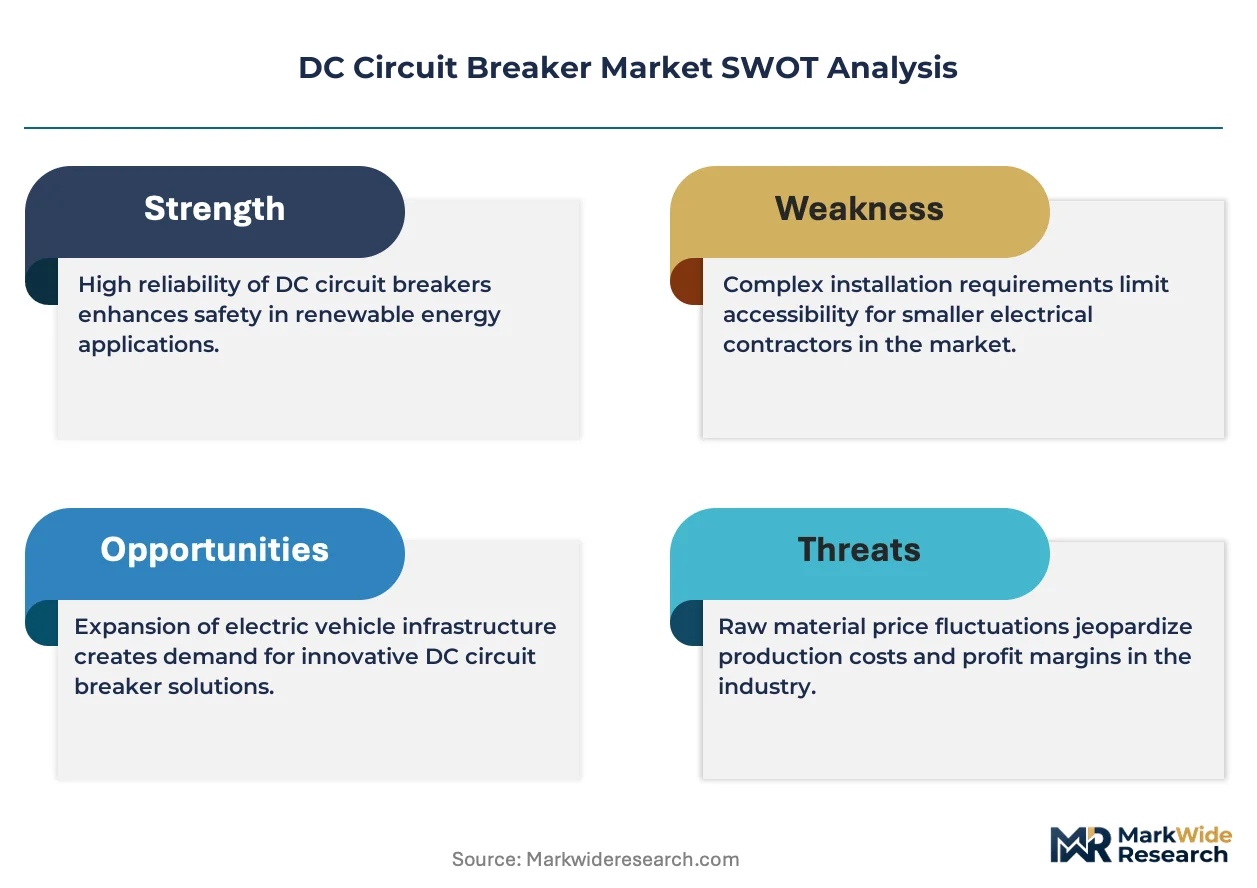
- Elevated Component Cost:The sophisticated arc-quenching mechanisms required for DC interruption, particularly in high-voltage applications, result in significantly higher manufacturing costs compared to conventional AC breakers, limiting adoption in price-sensitive segments.
- Technical Complexity:Interrupting a stable DC arc without a natural zero-crossing point remains a core physics challenge, demanding complex designs that increase size, weight, and potential points of failure, especially at higher voltages.
- Material Supply Concentration:Certain advanced breaker designs rely on components like rare-earth magnets, whose supply chain is highly concentrated in a few countries, exposing manufacturers to price volatility and geopolitical supply risks.
Strategic Opportunities
- DC Microgrids:The emergence of DC microgrids for data centers, commercial buildings, and remote communities represents a significant new application area, offering opportunities for standardized, modular protection solutions.
- Regulatory Incentives:The US Inflation Reduction Act (IRA) offers tax credits and funding for grid modernization and energy storage projects, creating a strong financial incentive for utilities to upgrade infrastructure with modern DC components.
- Marine and Aerospace Electrification:The transition toward electric propulsion systems in marine vessels and future aircraft concepts opens a long-term, high-specification market for compact and highly reliable DC circuit breakers.
Industry Challenges
- Certification Fragmentation:Manufacturers face significant cost and time burdens navigating disparate mandatory standards, such as UL 489B in the United States and GB standards in China, to achieve global market access for a single product line.
- Legacy System Integration:Integrating modern DC protection and control systems into existing grid infrastructure, which is predominantly designed for AC power, presents substantial technical and interoperability challenges for utility operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DC Circuit Breaker Market |
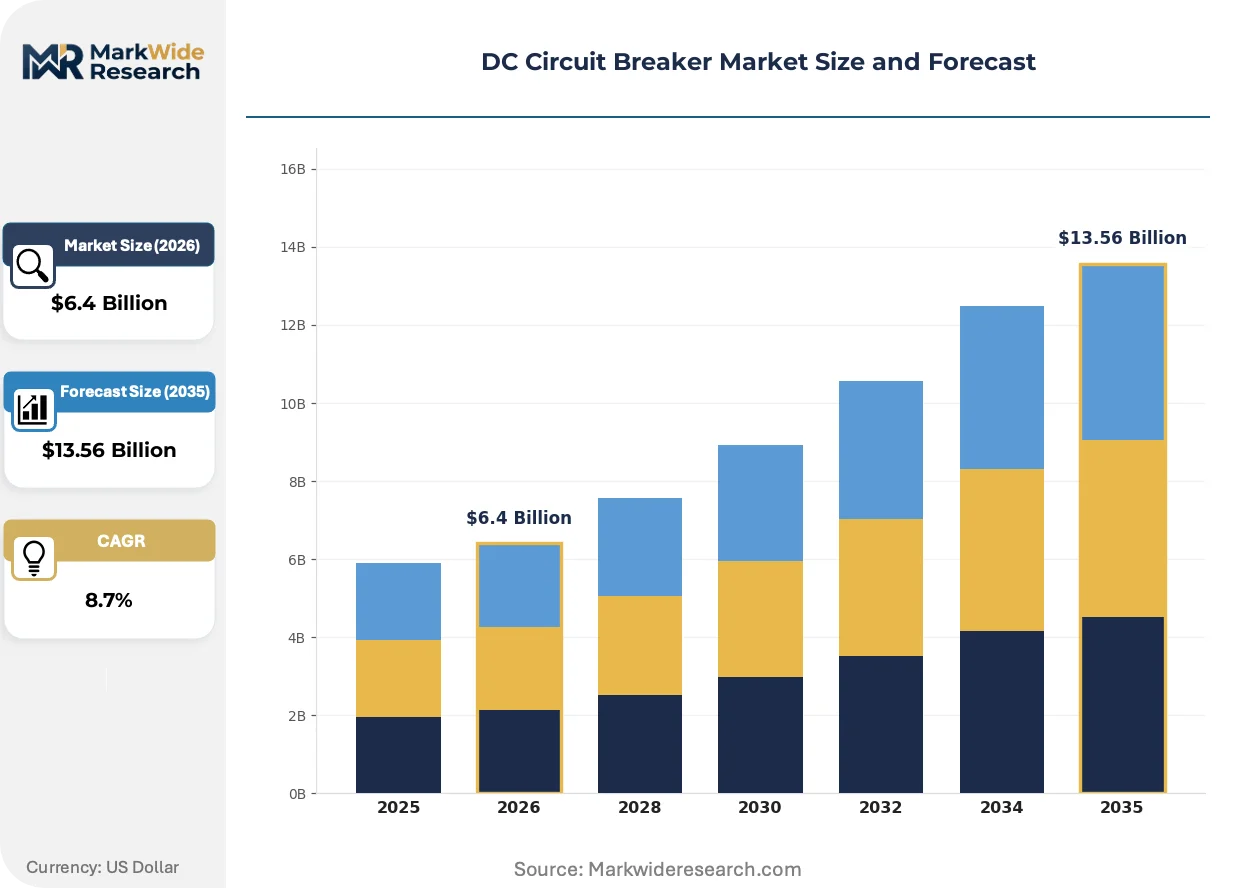
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $13.56 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Miniature Circuit Breaker, Earth Leakage Circuit Breaker, Standard Circuit Breaker, Molded Case Circuit Breaker End User: Residential, Commercial, Industrial, Renewable Energy Material: Plastic, Copper, Aluminum, Steel Installation Type: Panel Mount, DIN Rail Mount, Surface Mount, Standalone |
| Companies Covered | Schneider Electric, Mitsubishi Electric Corporation, ABB, Littelfuse, Fuji Electric, Siemens Energy, Eaton, BENY, Hitachi Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DC Circuit Breaker Market Strategic Shifts & Innovations
Product development is shaped by the dual requirements of standardization for safety compliance and system-level integration for deployment speed. These forces are pushing manufacturers toward more intelligent and modular designs that simplify installation in complex electrical environments like data centers and renewable power plants.
Hybrid DC circuit breakers, which integrate solid-state switches with traditional mechanical interrupters, deliver ultra-fast fault clearing with minimal energy loss. Utility operators and HVDC project developers are adopting these systems to enhance grid stability and protect sensitive power electronics. This technology is modularizing protection schemes into containerized or skid-mounted subsystems, which reduces on-site commissioning time and engineering complexity.
The IEC 60947 series of standards for low-voltage switchgear acts as a critical gatekeeper for global commerce, defining performance and safety benchmarks. Compliance requires rigorous testing for arc-quenching capability and thermal management, directly influencing material selection and product design. The industrial and renewable energy segments are most impacted, as adherence to IEC standards is a prerequisite for market entry in Europe and much of Asia.
A notable shift in purchasing behavior involves end-users specifying complete, pre-engineered electrical panels rather than sourcing individual breaker components. This pattern disrupts traditional distribution models that focus on component sales, favoring manufacturers who can provide integrated system design and assembly services. This demand for turnkey solutions is most pronounced within the battery energy storage and utility-scale solar sectors.
DC Circuit Breaker Market Segmentation
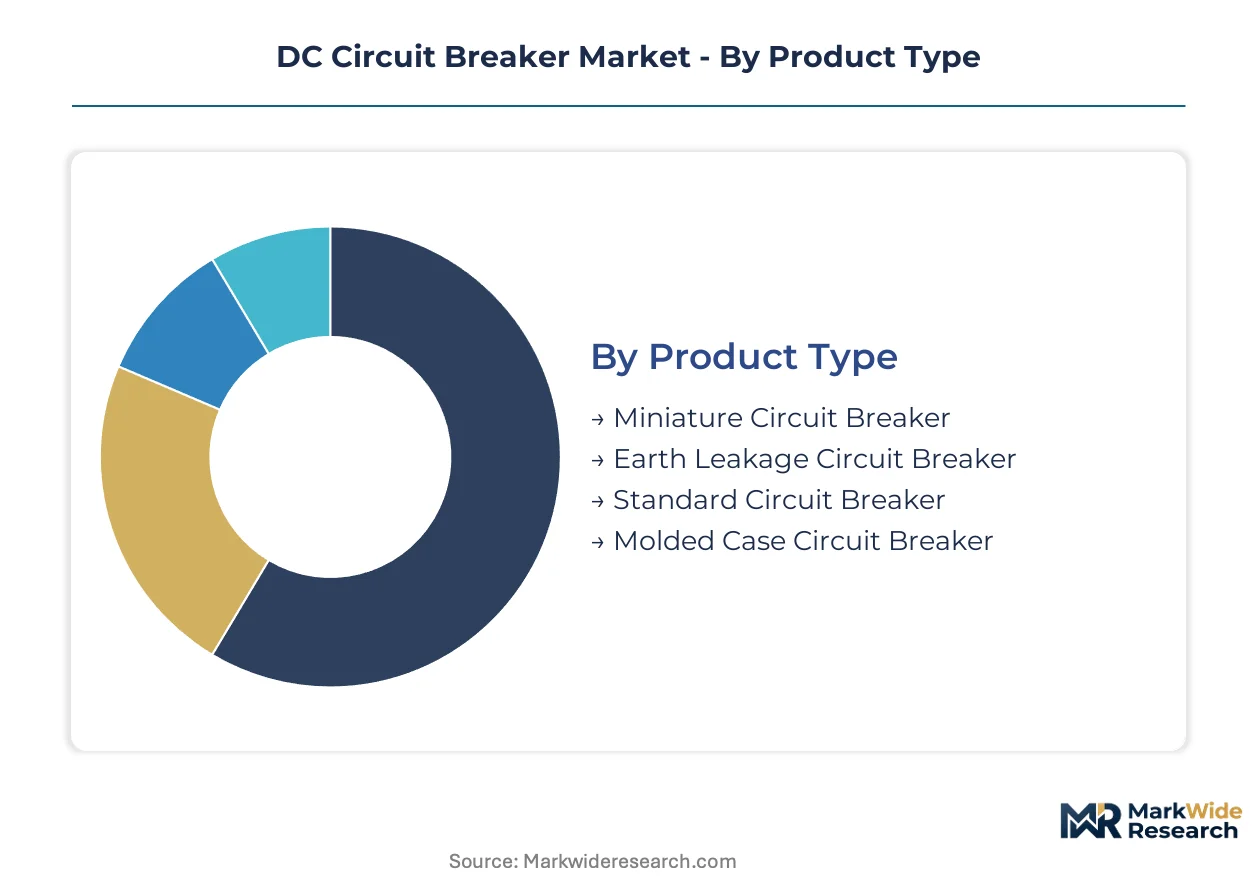
The DC circuit breaker market segments reflect the diverse technical demands and regulatory landscapes across various end-use applications. Understanding these distinctions is critical for manufacturers to align product development with specific customer needs and market entry requirements.
Product Type:
Market access for specific DC circuit breaker product types often hinges on rigorous certification processes, with UL 489B critical in the United States and IEC 60947 compliance essential for European and Asian markets.
- Miniature Circuit Breaker:These compact devices provide fundamental overcurrent protection for low-voltage DC circuits, typically up to 125A. Demand concentrates in distributed generation systems and battery energy storage applications, driven by their small footprint and cost-effectiveness for individual string protection.
- Molded Case Circuit Breaker:Encased in a molded composite material, these breakers offer robust protection for higher current applications, ranging from 100A to over 2500A. The industrial end-user segment drives significant demand for these devices, particularly in heavy machinery and large-scale power distribution panels requiring high breaking capacities.
- Earth Leakage Circuit Breaker:These devices detect and interrupt ground faults, safeguarding personnel from electric shock in DC installations.
- Standard Circuit Breaker:This category encompasses general-purpose DC breakers designed for various protection tasks without specialized features.
Molded Case Circuit Breakers sit at the top of the volume ranking, with Miniature Circuit Breakers climbing the fastest.
End User:
The end-user landscape for DC circuit breakers is defined by diverse application requirements, ranging from distributed power generation to heavy industrial machinery.
- Renewable Energy:This segment includes solar photovoltaic arrays, wind turbine DC links, and battery energy storage systems, requiring specialized breakers for reliable operation. The global build-out of utility-scale solar farms and microgrids in China and the United States creates substantial demand for robust DC protection solutions.
- Industrial:This segment comprises manufacturing plants, mining operations, and heavy industrial facilities utilizing DC motors, rectifiers, and specialized machinery. These environments demand high-current, robust breakers capable of frequent switching and enduring harsh operating conditions.
- Commercial:Commercial buildings, data centers, and telecommunications infrastructure rely on DC circuit breakers for uninterruptible power supplies and critical load protection.
- Residential:Residential applications primarily involve small-scale solar installations, electric vehicle charging points, and home automation systems requiring compact DC protection.
The industrial segment commands significant market share, while renewable energy applications show the most substantial investment growth.
Material:
Material selection for DC circuit breaker components reflects a balance between performance specifications and manufacturing cost tiers.
- Copper:Utilized for busbars, contacts, and current-carrying components due to its high electrical conductivity and thermal management properties. High-voltage DC applications, particularly in HVDC transmission projects, prioritize copper for its superior performance and reliability under extreme loads.
- Plastic:Primarily used for the insulating molded cases and internal structural components due to its dielectric strength, lightweight nature, and cost-effectiveness. This material is prevalent in Miniature Circuit Breakers and Molded Case Circuit Breakers, providing essential insulation and mechanical integrity.
- Aluminum:Employed in certain structural elements or for heat dissipation in less current-intensive applications, offering a lighter alternative to copper.
- Steel:Used for mounting brackets, enclosures, and mechanical parts requiring high strength and rigidity in industrial-grade breakers.
Copper components drive premium performance tiers, as plastic enclosures enable cost-effective deployments.
Installation Type:
Installation preferences within the DC circuit breaker market are increasingly driven by efficiency and ease of integration into complex electrical systems.
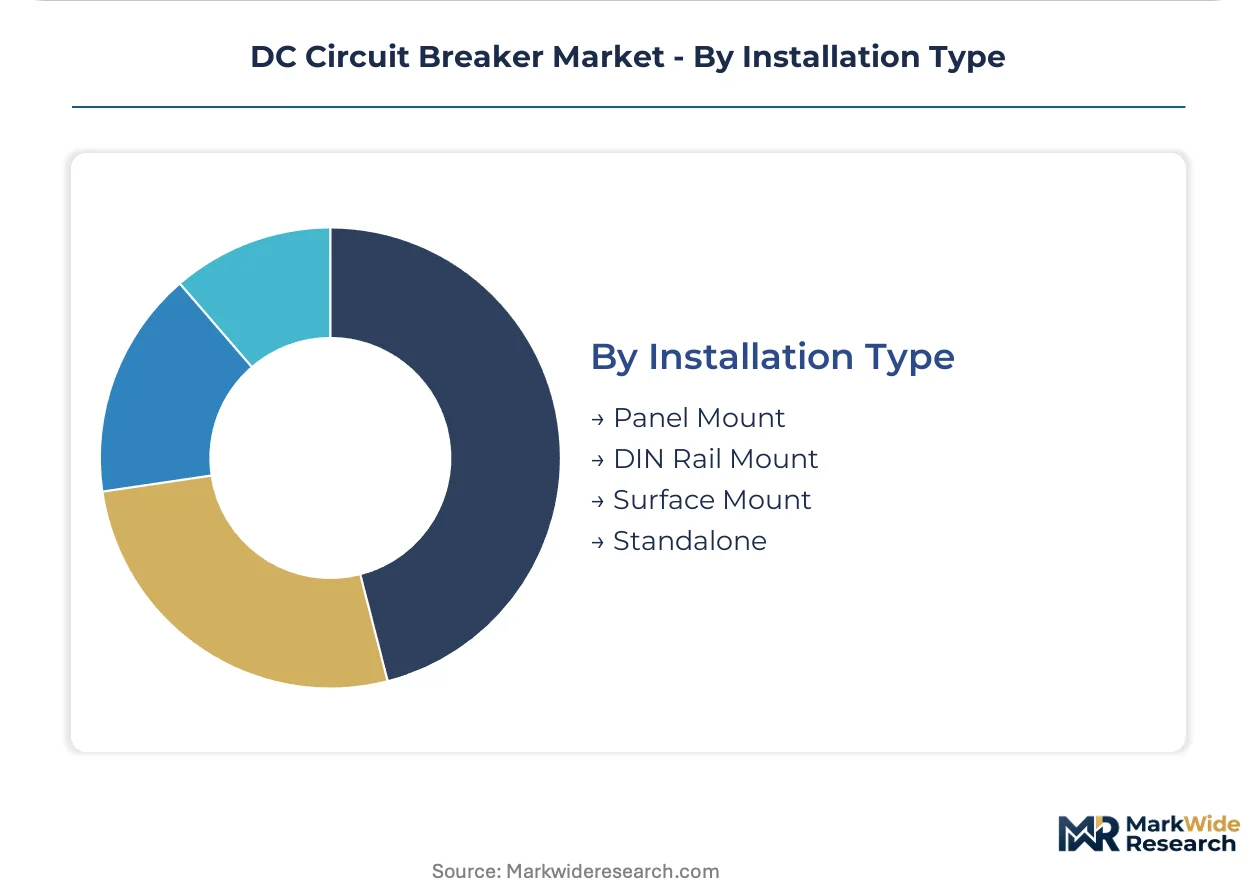
- DIN Rail Mount:This standardized mounting method allows for quick and secure installation of circuit breakers onto a metal rail within electrical enclosures. Industrial control panels and renewable energy combiner boxes frequently adopt DIN Rail Mount solutions for their modularity and simplified wiring in Europe and Asia.
- Panel Mount:Circuit breakers designed for panel mounting integrate directly into the front or rear of electrical panels and switchgear. This type is common in larger industrial equipment and power distribution units, providing a secure and aesthetically integrated solution.
- Surface Mount:Surface mount breakers are affixed directly to a flat surface, often used in standalone applications or where space constraints are significant.
- Standalone:This category includes larger, independent circuit breaker units not integrated into a panel or rail system, typically for high-power or specialized installations.
DIN Rail Mount solutions simplify panel assembly, reflecting a broader trend toward modular integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The DC circuit breaker industry initially scaled in regions pioneering large-scale electrical grids and industrial electrification. Early advancements in power distribution systems in North America and Europe established foundational demand for robust protection devices. Modern market expansion is now significantly influenced by global renewable energy integration efforts.
United States
Demand for DC circuit breakers in the United States stems from expanding data centers and electric vehicle charging infrastructure. The US Inflation Reduction Act (IRA) offers tax credits, accelerating grid modernization projects with DC components. Silicon Valley and Texas are witnessing significant investment in large-scale solar and battery storage installations.
China
China's demand for DC circuit breakers is driven by its ambitious dual carbon goals and extensive HVDC network build-out. GB standards mandate specific compliance for all electrical safety equipment, influencing product design. The Yangtze River Delta region leads in renewable energy projects and EV charging station deployments.
Germany
German demand for DC circuit breakers arises from widespread renewable energy integration and industrial applications. Europe's Green Deal policies support solar and wind power expansion, requiring advanced DC protection. Bavaria and North Rhine-Westphalia host significant manufacturing and utility-scale renewable energy infrastructure.
Japan
Japan's market for DC circuit breakers is shaped by its focus on smart grid technologies and high-efficiency industrial systems. JIS standards govern electrical equipment safety and performance, necessitating specific product certifications. The Tokyo metropolitan area drives demand for compact DC solutions in commercial buildings and data centers.
India
India's DC circuit breaker demand accelerates with its solar power capacity expansion and growing electric vehicle ecosystem. The country's national energy policies promote renewable energy projects and grid upgrades. Gujarat and Rajasthan are key states for utility-scale solar farms, requiring robust DC protection.
DC Circuit Breaker Market Key Industry Players
Premium-margin players sit above commodity-margin players across product sophistication and application specificity in the DC circuit breaker market. This market exhibits a tiered structure, with established industrial giants coexisting with specialized protection technology firms. Strategic archetypes include diversified electrical equipment manufacturers offering broad portfolios and focused innovators concentrating on advanced arc-quenching solutions. Companies are increasingly pursuing portfolio diversification and strategic partnerships to expand their application scope and address emerging DC applications.
Within the diversified electrical equipment manufacturer archetype, Schneider Electric, a French multinational corporation, represents a broad market presence through its extensive distribution network. ABB, a Swiss-Swedish multinational, exemplifies a focus on high-voltage solutions for utility-scale renewable projects. Siemens Energy, a German energy technology company, occupies a position specializing in industrial and grid applications for its protection portfolio. These entities anchor distinct segments of the market, leveraging their legacy in electrical infrastructure to address specific DC protection needs.
| Leading Market Players |
|---|
| Schneider Electric |
| Mitsubishi Electric Corporation |
| ABB |
| Littelfuse |
| Fuji Electric |
| Siemens Energy |
| Eaton |
| BENY |
| Hitachi Energy |
| Others |
Cost & Logistics Intelligence
The increasing modularization of DC circuit breaker components simultaneously reshapes cost economics and supply concentration. This transition simplifies installation and reduces on-site labor costs, yet it also favors manufacturers capable of integrating complex sub-assemblies from specialized component suppliers.
Pricing Analysis
A tiered pricing structure differentiates DC circuit breakers based on performance specifications and application suitability. Price differentiation stems from certification levels, such as UL 489B or IEC 60947 compliance, and the integration of advanced arc-quenching technologies. Pricing pressure stems from the elevated component cost of sophisticated arc-extinction mechanisms, particularly in high-voltage applications. Residential and small commercial segments exhibit the highest price sensitivity, while utility-scale renewable projects prioritize reliability and technical performance over initial cost.
Supply Chain Analysis
Certification requirements for market access in key regions like the United States and China fundamentally shape the DC circuit breaker supply chain. Geographic supply concentration for manufacturing centers on China, Germany, and Japan for specialized components and assembly. The industry relies on raw material dependencies including high-purity copper for conductors and rare-earth magnets for magnetic blow-out systems. Geopolitical supply risks for rare-earth elements introduce significant vulnerability. Distribution runs through extensive manufacturer-owned networks and specialized electrical distributors serving industrial and utility customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The DC circuit breaker market presents a geographic-arbitrage play, driven by lower manufacturing costs in Asian markets versus stringent certification and higher value-add service requirements in North America and Europe.
For Market Incumbents: Hedge against emerging solid-state competition by accelerating R&D investment in hybrid DC breaker technologies. Strengthen channel control through strategic partnerships with large-scale system integrators, especially in the rapidly expanding EV charging infrastructure segment. Expand modular protection solutions to simplify integration for data centers, leveraging existing distribution networks. Reinforce compliance teams to navigate varied national standards like UL 489B and GB standards efficiently.
For New Entrants and Emerging Players: The US Inflation Reduction Act in the United States opens a window for specialized DC component manufacturers. Target the distributed generation and DC microgrid segments with cost-effective, standardized Miniature Circuit Breakers. Focus go-to-market efforts on offering pre-assembled electrical panels, simplifying procurement for solar and battery storage developers. The residential and small commercial sectors represent the most penetrable segments due to lower current requirements and simpler installation needs.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized component suppliers with strong intellectual property in arc-quenching technologies. The long-term viability of the DC circuit breaker market remains robust over the next 5-10 years, driven by electrification trends. Identify acquisition targets that offer complementary product lines, such as advanced power electronics or grid control systems, to capture broader system integration value. A signal to watch for inflection is the widespread adoption of standardized DC bus architectures in commercial buildings.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Hybrid Breaker R&D | Accelerates fault clearing speeds for sensitive power electronics in HVDC systems. |
| Expand Modular Panel Solutions | Simplifies installation and reduces commissioning time for data centers and renewable projects. |
| Strengthen Global Certification Teams | Ensures market access and compliance with diverse national standards for international deployment. |
| Target DC Microgrid Integration | Captures new application growth in commercial buildings and remote community power systems. |
| Secure Rare-Earth Material Supply | Mitigates geopolitical supply risks for critical components in advanced arc-quenching designs. |
Research Approach
Multiple input streams — primary interviews, secondary publications, and quantitative modeling — were reconciled to construct this market analysis. Primary research involved discussions with R&D engineers, utility operators, procurement managers, and system integrators across key geographies. Secondary sources included IEC standards documents, national energy agency reports like the EIA, and company financial filings, triangulated for consistency.
Historical market data was cross-referenced with expert panel input to establish baseline figures and growth trajectories over the projection horizon. The analytical framework modeled market dynamics across product type, end-user, installation type, material, and regional deployment. Compound Annual Growth Rates were derived from a comprehensive assessment of historical trends and projected future demand drivers, including renewable energy capacity additions and EV charging station build-out forecasts.
Forecast precision tightens around the base case; tail outcomes carry wider variance under significant policy shifts or material supply disruptions. All forecasts reflect assumptions regarding technological advancements and regulatory stability. A model refresh is warranted upon material change in global electrification policy or arc-quenching technology breakthroughs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Analog Switches Market
Switches
Push Button Dropper Market
Switches
DC Switchgear Market
Switches
Contactor-based Transfer Switch Market
Switches
Solid State Relay Market
Switches
Smart Pole-Mounted Switch Market
Switches
5G Solid State Switches Market
Switches
Reed Switch Market
Switches
Europe Switchgear Market
Switches
South Korea Reed Sensors Switches Market
Switches
APAC Push Buttons and Signaling Devices Market
Switches
Asia-Pacific High Voltage Switchgear Market
Switches
Surface Mount Switch Market
Switches
Hazardous Location Limit Switches Market
Switches
China Switchgear Market
Switches
Temperature and Pressure Switches Market