
 Southeast Asia Uninterruptible Power Supply (UPS) Market | 2026-2036
Southeast Asia Uninterruptible Power Supply (UPS) Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Uninterruptible Power Supply (UPS) Market Analytics
CE marking under the EU's Electromagnetic Compatibility Directive is redrawing competitive entry requirements for Southeast Asian UPS exporters serving European-owned data center operators. Schneider Electric SE leverages its regional manufacturing footprint in Vietnam to sustain cost-competitive modular platforms. Delta Electronics Inc anchors its position through captive production of power semiconductors and magnetics. EATON Corporation PLC differentiates via channel control across ASEAN's electrical distributor networks.
Uninterruptible Power Supply systems are electromechanical or solid-state power conditioning apparatus that store energy in lead-acid, lithium-ion, or nickel-cadmium battery arrays and deliver conditioned alternating current through double-conversion or line-interactive topologies, maintaining voltage and frequency within IEC 62040-3 tolerances during utility disturbances. Their primary purpose is eliminating downtime for mission-critical loads in facilities where power interruption causes operational loss or safety failure. Online UPS configurations dominate margin pools in the above 10 kVA range where data center operators prioritize zero transfer time, while the 1-5 kVA segment competes on price in distributed IT deployments. Rack mount installations lead in new construction, though modular architectures are gaining traction for capacity-scaling flexibility in co-location facilities.
Indonesia's Directorate General of Electricity and Thailand's Energy Regulatory Commission enforce efficiency standards and grid interconnection codes that directly shape UPS procurement specifications for industrial and commercial installations. Singapore's Building and Construction Authority embeds resilience requirements into data center licensing that mandate redundant power conditioning. Stakeholders must monitor evolving battery chemistry regulations and local content thresholds that could alter supply chain configurations across ASEAN manufacturing zones.
Market Dynamics
Hyperscale data center construction across Indonesia's Jakarta-Bandung corridor and Thailand's Eastern Economic Corridor is compressing UPS procurement timelines while utility grid upgrades lag, forcing operators toward modular battery-backed systems with faster deployment cycles.
Growth Catalysts
- Indonesia's renewable energy integration mandates:The Directorate General of Electricity requires distributed generation backup systems for grid-connected industrial facilities, directly expanding three-phase UPS specifications for manufacturing campuses in Batang and Bekasi.
- Lithium-ion battery cost curves:Chemistry improvements and regional cell manufacturing scale in Vietnam are collapsing price premiums versus lead-acid alternatives, accelerating replacement cycles in co-location facilities.
- Singapore's data center licensing resilience requirements:The Building and Construction Authority mandates N+1 power conditioning redundancy, locking in minimum UPS capacity thresholds for new facility approvals.
Market Restraints
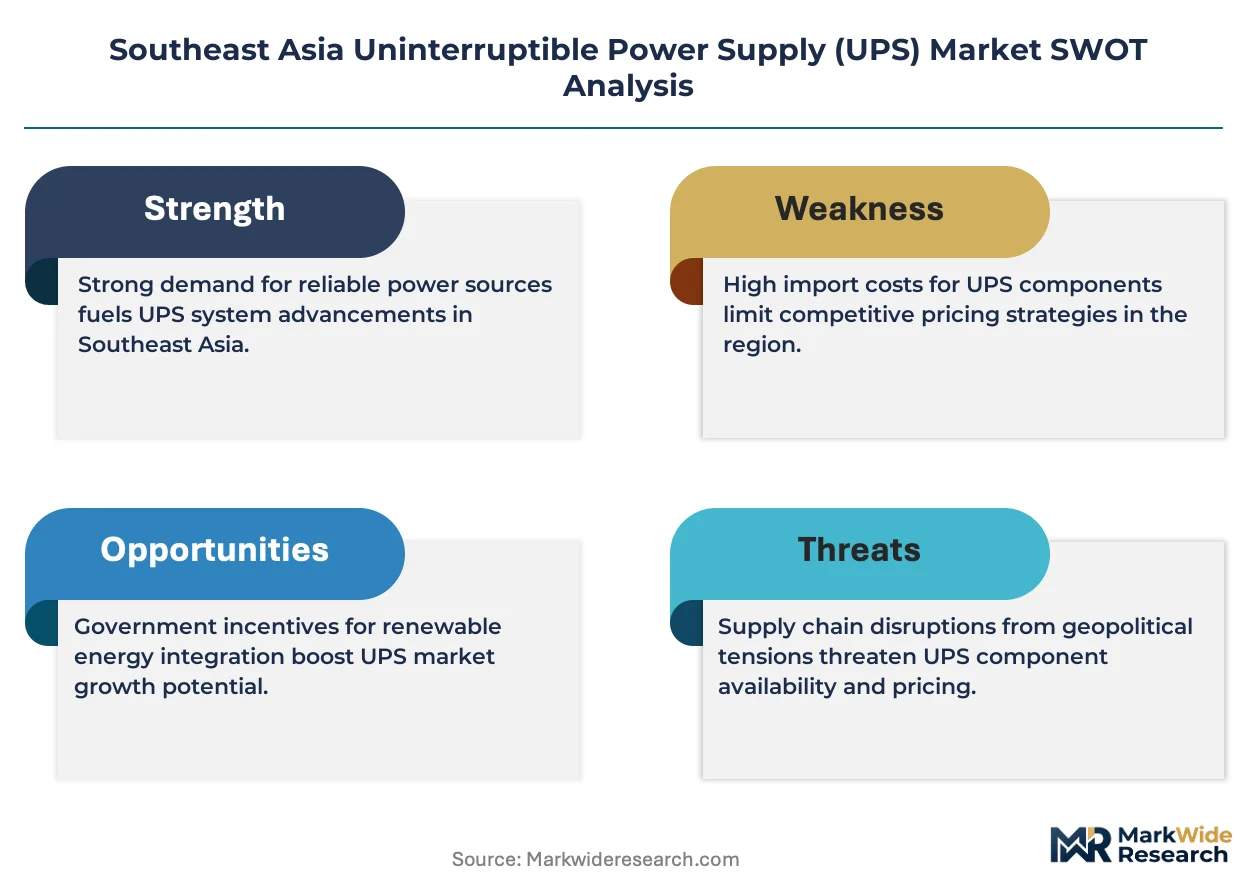
- Power semiconductor supply concentration:IGBT and SiC module fabrication concentrates in East Asian foundries, exposing ASEAN integrators to allocation bottlenecks during capacity constraints.
- Technical limitation in tropical humidity tolerance:IEC 62040-3 thermal cycling specifications strain passive cooling designs in ambient conditions exceeding 35°C across Philippine and Indonesian installations.
- Regulatory friction from local content thresholds:Indonesia's Ministry of Industry mandates domestic assembly quotas for government-procured electrical equipment, complicating supply chain configurations for imported chassis.
Strategic Opportunities
- Vietnam's underpenetrated northern industrial zones:Bac Ninh and Hai Phong electronics manufacturing clusters lack redundant power infrastructure depth versus southern counterparts, creating first-mover positioning for modular UPS-as-a-service models.
- Technology convergence of UPS with energy storage:Grid-interactive bi-directional inverters enable frequency regulation revenue streams, allowing data center operators to monetize battery assets beyond backup functions.
- Thailand's Board of Investment tax incentives:BOI-promoted smart city developments in Chiang Mai and Khon Kaen embed microgrid resilience requirements that specify battery-backed power conditioning in tender documents.
Industry Challenges
- Certification timeline compression for CE marking:EU Electromagnetic Compatibility Directive testing protocols require six-month validation cycles that conflict with hyperscale construction schedules, forcing parallel-track documentation strategies.
- Integration complexity with legacy diesel rotary UPS:Financial institutions in Singapore and Bangkok maintain decades-old kinetic energy systems, creating hybrid architecture engineering costs during phased modernization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Uninterruptible Power Supply (UPS) Market |
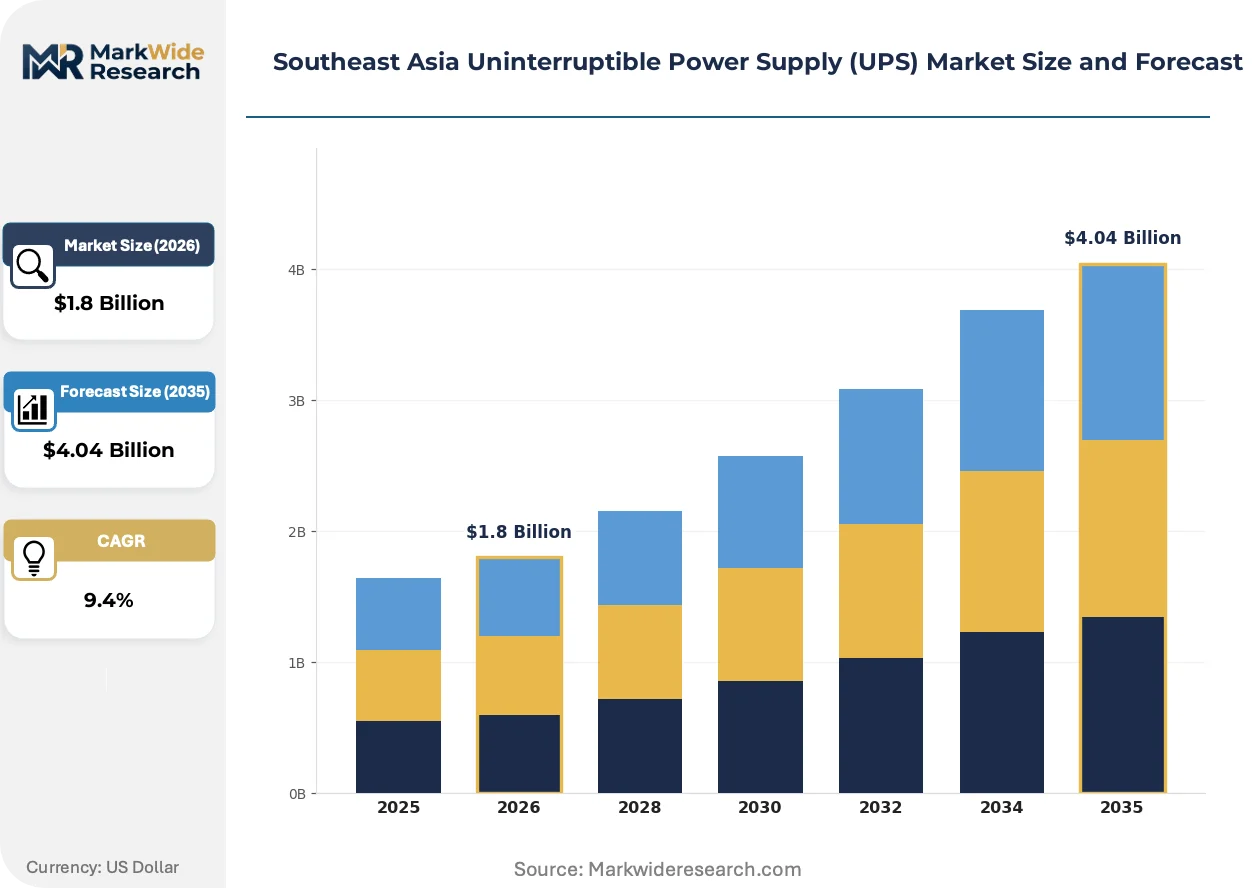
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Online UPS, Offline UPS, Line-Interactive UPS, Ferroresonant UPS Power Capacity: Below 1 kVA, 1-5 kVA, 5-10 kVA, Above 10 kVA End User: IT & Telecom, Healthcare, Industrial, Data Centers Installation Type: Rack Mount, Floor Stand, Modular, Portable |
| Companies Covered | ABB Ltd, Emerson Electric Co, EATON Corporation PLC, Mitsubishi Electric Corporation, Hitachi Ltd, Schneider Electric SE, Riello Elettronica SpA, Cyber Power Systems Inc, Delta Electronics Inc, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Uninterruptible Power Supply (UPS) Market Evolving Landscape
Lithium-ion battery chemistries and intelligent power management software are restructuring competitive positioning in Southeast Asian UPS procurement, compressing traditional hardware-centric business models toward lifecycle service architectures.
Solid-state transformer technology is displacing conventional magnetic isolation in 100-500 kVA three-phase platforms. Hyperscale operators in Indonesia and Thailand are piloting silicon carbide-based power conversion for 40% footprint reduction. This displacement is collapsing mechanical component supplier relevance while elevating semiconductor sourcing capabilities as a core vendor competency.
Singapore's Building and Construction Authority resilience mandates are cascading into procurement specifications across ASEAN data center developments. The policy requires documented power continuity testing under simulated grid failure scenarios. Vietnam and Philippine facility operators are adopting these standards preemptively to attract regional headquarters tenants demanding operational parity.
Co-location buyers are consolidating vendor relationships around integrated power and cooling service contracts. Traditional equipment-only distributors in Bangkok and Jakarta face margin compression as direct manufacturer engagement captures recurring revenue streams. This consolidation is most visible in Singapore's Changi and Tuas data center clusters where lease structures now embed power availability SLAs.
Southeast Asia Uninterruptible Power Supply (UPS) Market Segmentation
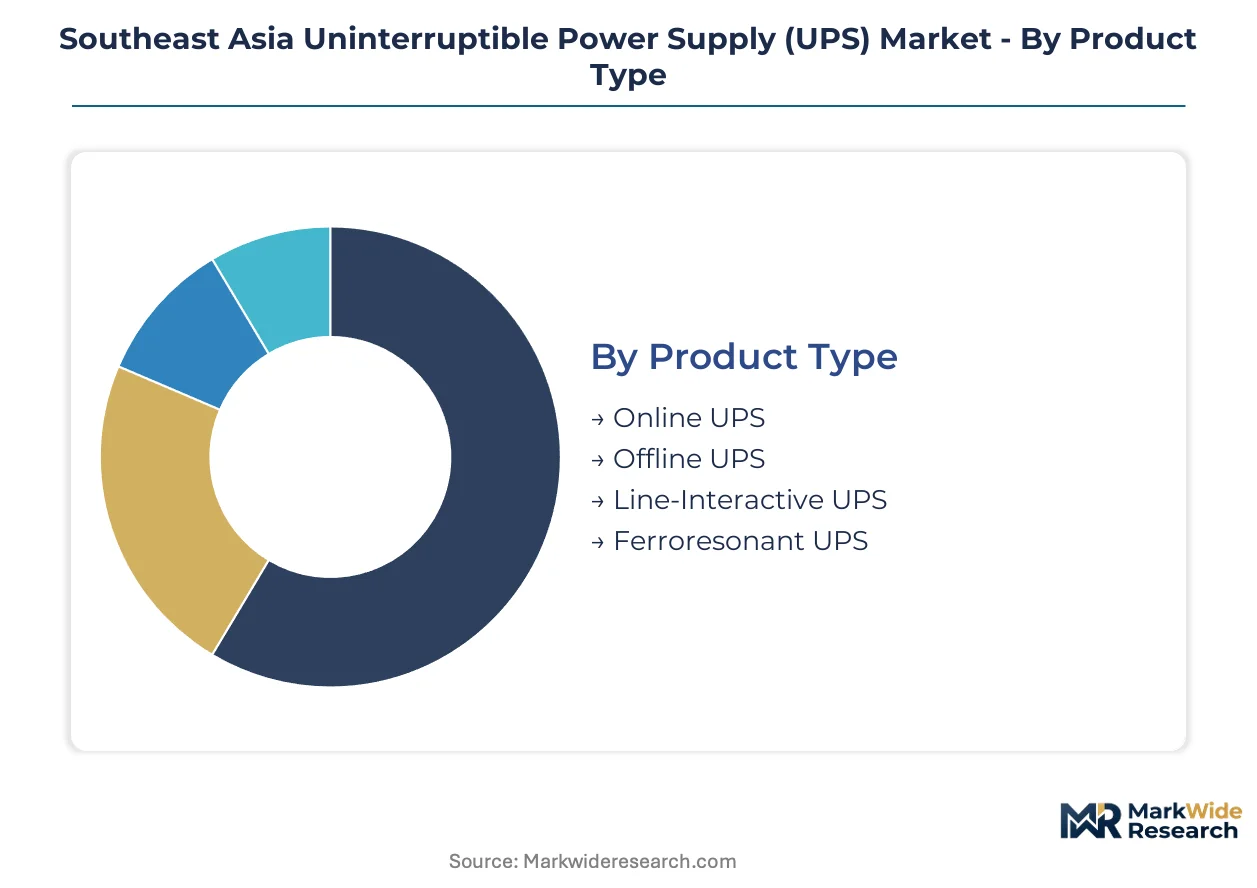
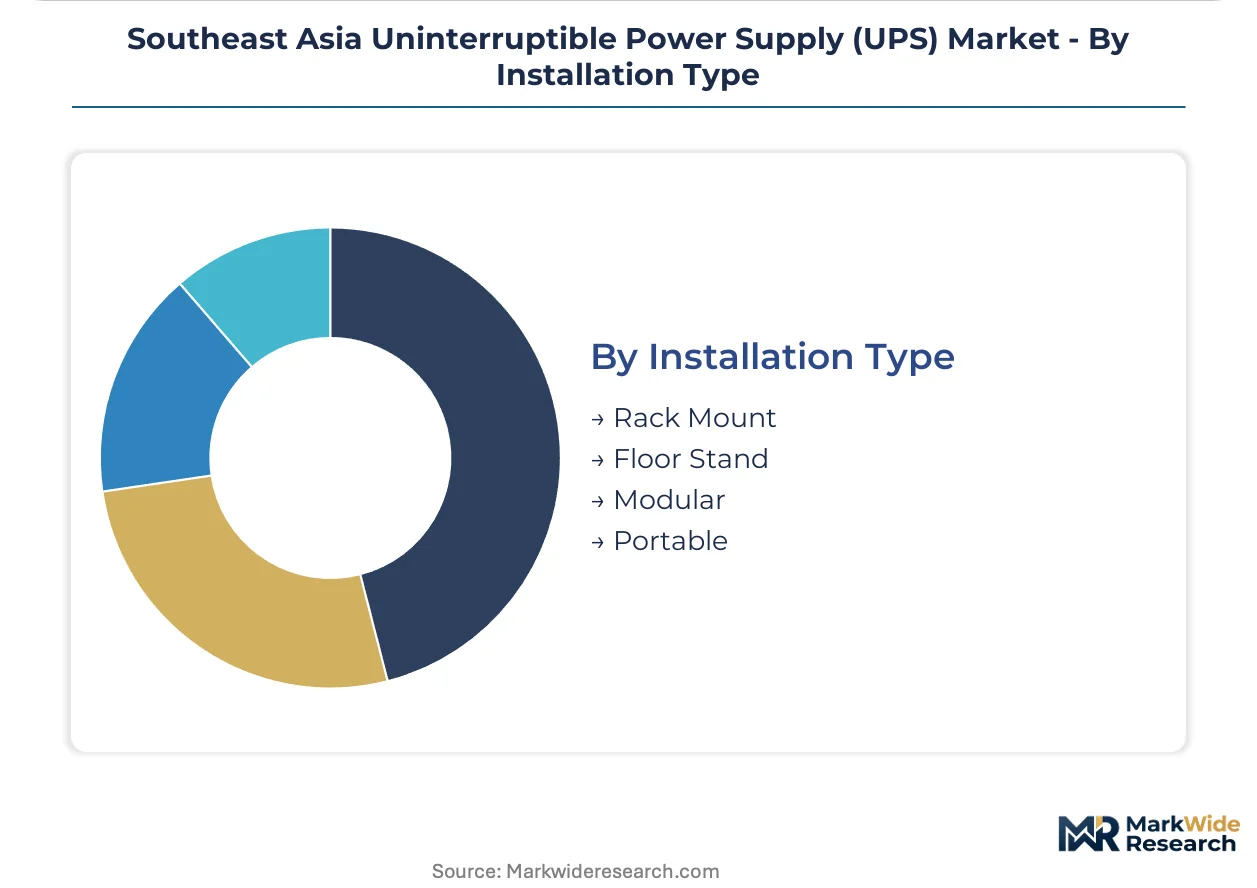
UPS procurement patterns across Southeast Asia diverge sharply by facility scale and grid reliability context. Segmentation reveals how modular architectures capture hyperscale construction while rack-mount systems dominate distributed IT refresh cycles.
Product Type:
Margin pools concentrate in double-conversion architectures where data center operators pay premiums for zero transfer time.
- Online UPS:Double-conversion topology maintains continuous AC regeneration through rectifier-inverter stages. Demand concentrates in Singapore's Tuas and Changi data center clusters where the Building and Construction Authority mandates N+1 redundancy with documented failure simulation testing.
- Line-Interactive UPS:Buck-boost voltage regulation with battery backup during outages. Procurement accelerates in Vietnam's Bac Ninh electronics manufacturing zones where grid instability exceeds 20 voltage events monthly but full online conversion costs strain facility budgets.
- Offline UPS:Standby switching topology activates inverter only during utility failure. Compact units serve home office and retail POS applications across Philippine archipelago installations.
- Ferroresonant UPS:Saturable transformer designs provide inherent voltage regulation. Limited deployment persists in legacy industrial motor drive protection across Thai Eastern Economic Corridor manufacturing campuses.
Online UPS holds installed capacity. Line-Interactive UPS is rotating up the share rankings.
Power Capacity:
Volume leadership sits in sub-5 kVA ranges, though revenue gravity pulls toward three-phase platforms above 10 kVA.
- Above 10 kVA:Three-phase modular and monolithic systems serve mission-critical infrastructure. Co-location facilities in Indonesia's Jakarta-Bandung corridor specify scalable 500-2000 kVA blocks to match hyperscale tenant expansion timelines.
- 1-5 kVA:Single-phase tower and rack units protect distributed server closets and network edge equipment. Healthcare digitization across Thai provincial hospitals drives refresh cycles for imaging and patient record systems.
- 5-10 kVA:Mid-range platforms bridge small server rooms and light industrial loads. Deployment concentrates in Malaysian Penang semiconductor packaging facilities requiring clean power for precision equipment.
- Below 1 kVA:Desktop and workstation units address individual device protection. E-commerce logistics boom across Vietnamese urban centers expands POS and handheld scanner backup requirements.
Above 10 kVA commands pricing power. 1-5 kVA is expanding most quickly through distributed IT proliferation.
End User:
Application-specific duty cycles and runtime requirements fragment procurement specifications across verticals.
- Data Centers:Hyperscale and colocation operators specify lithium-ion compatible, high-efficiency (96%+) double-conversion systems. Indonesia's Directorate General of Electricity renewable integration mandates require grid-interactive bi-directional capability for frequency regulation revenue.
- Industrial:Manufacturing campuses in Batang and Bekasi demand three-phase systems with motor load compatibility and extended runtime for controlled process shutdown. Local content thresholds complicate imported chassis procurement.
- Healthcare:Hospital accreditation standards in Thailand and Singapore mandate minimum 30-minute runtime for life safety circuits. Diagnostic imaging equipment requires voltage conditioning beyond simple backup.
- IT & Telecom:Mobile network operators across Philippine archipelagos deploy outdoor-hardened units with passive cooling for base station continuity during typhoon grid failures.
Data Centers anchor technology roadmaps. Healthcare is climbing the fastest on regulatory compliance investment.
Installation Type:
Physical form factor selection tracks facility lifecycle stage and capacity scaling requirements.
- Modular:Hot-swappable power and battery modules enable capacity growth without facility shutdown. Singapore co-location lease structures embedding power availability SLAs favor pay-as-you-grow architectures.
- Rack Mount:Standard 19-inch chassis integrate into server cabinets. New construction across Thai smart city developments specifies integrated power and cooling rows.
- Floor Stand:Tower configurations serve dedicated electrical rooms in legacy industrial and healthcare facilities. Replacement cycles accelerate as lithium-ion density enables equivalent runtime in smaller footprints.
- Portable:Wheeled units address temporary power for events, construction, and emergency response. Limited commercial significance in permanent infrastructure markets.
Rack Mount dominates new build specifications. Modular is gaining share fastest on scalability premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center operators and industrial facility managers concentrate procurement authority across five Southeast Asian markets. Grid reliability gaps and renewable integration mandates shape UPS specifications differently in each national context.
Indonesia
Hyperscale construction in the Jakarta-Bandung corridor outpaces utility upgrades, forcing modular battery-backed procurement. The Directorate General of Electricity mandates distributed generation backup for grid-connected industrial facilities. Manufacturing campuses in Batang and Bekasi specify three-phase systems with local content compliance.
Singapore
The Building and Construction Authority embeds N+1 power conditioning redundancy into data center licensing requirements. Operators in Tuas and Changi clusters document failure simulation testing for facility approvals. Co-location lease structures now embed power availability SLAs that favor scalable architectures.
Thailand
The Board of Investment promotes smart city developments in Chiang Mai and Khon Kaen with microgrid resilience requirements. The Eastern Economic Corridor compresses UPS procurement timelines for manufacturing expansion. Provincial hospitals drive refresh cycles for imaging equipment backup systems.
Vietnam
Electronics manufacturing clusters in Bac Ninh and Hai Phong lack redundant power infrastructure depth versus southern counterparts. Grid instability exceeds twenty voltage events monthly in northern industrial zones. Regional cell manufacturing scale collapses lithium-ion price premiums versus lead-acid alternatives.
Philippines
Archipelagic grid fragmentation and typhoon exposure accelerate demand for outdoor-hardened units with passive cooling. Mobile network operators deploy base station continuity systems across island installations. E-commerce logistics expansion in urban centers drives POS and handheld scanner backup requirements.
Southeast Asia Uninterruptible Power Supply (UPS) Market Competitive Landscape
Player mix skews toward diversified electrical equipment conglomerates with captive semiconductor or magnetic component production. Tiering separates integrated power management platforms from hardware-centric distributors. Strategic archetypes include modular architecture specialists, channel-controlled electrical distributors, and captive component fabricators. Competitive moves center on direct manufacturer engagement capturing recurring service revenue and geographic manufacturing footprint optimization for cost positioning.
Among diversified electrical equipment conglomerates, Schneider Electric SE and EATON Corporation PLC occupy positions reflecting integrated power management platform breadth. Delta Electronics Inc exemplifies the captive component fabrication archetype through in-house power semiconductor and magnetics production. Mitsubishi Electric Corporation represents Japanese electrical conglomerate positioning with historical strength in industrial drive systems. These three anchors illustrate how vendor selection increasingly weights supply chain control and service contract integration over standalone equipment procurement.
| Leading Market Players |
|---|
| ABB Ltd |
| Emerson Electric Co |
| EATON Corporation PLC |
| Mitsubishi Electric Corporation |
| Hitachi Ltd |
| Schneider Electric SE |
| Riello Elettronica SpA |
| Cyber Power Systems Inc |
| Delta Electronics Inc |
| Others |
Value Network & Pricing Analysis
CE marking under the EU Electromagnetic Compatibility Directive gates both supply qualification and price differentiation for Southeast Asian UPS manufacturers, compressing margins for uncertified assemblers while rewarding integrated players with documented compliance pathways.
Pricing Analysis
Cost-plus contracts with lithium carbonate indexation dominate procurement between Vietnamese cell manufacturers and ASEAN system integrators. Pricing stratifies across IEC 62040-3 certified premium tiers, standard commercial grades, and uncertified economy units serving price-sensitive Philippine retail deployments. Cost compression in the economy tier is intensifying because regional lead-acid battery oversupply enables aggressive distributor discounting. Co-location operators in Singapore's Tuas cluster exhibit least price sensitivity, prioritizing N+1 redundancy documentation over unit economics.
Supply Chain Analysis
Inventory cycles for IGBT and silicon carbide modules stretch to twenty-six weeks, forcing ASEAN integrators toward buffer stock strategies that tie up working capital. Power semiconductor fabrication concentrates in Taiwan, South Korea, and Japan, while lithium-ion cell production draws from China, South Korea, and Vietnam. Single-source vulnerability in SiC wafer supply exposes modular UPS manufacturers to allocation bottlenecks during foundry capacity constraints. Distribution runs through electrical wholesale networks in Bangkok and Jakarta, with direct manufacturer engagement capturing recurring service contracts in Singapore's Changi cluster.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from grid-interactive battery energy storage systems that bypass traditional double-conversion architectures, forcing defensive repositioning around service integration and semiconductor supply security.
For Market Incumbents: Consolidate backward integration into power semiconductor sourcing to secure IGBT and SiC module allocations during foundry constraints. Deepen channel control across ASEAN electrical distributor networks to defend against direct manufacturer engagement capturing recurring revenue streams in Singapore co-location facilities.
For New Entrants and Emerging Players: Lead with modular UPS-as-a-service models targeting Vietnam's Bac Ninh and Hai Phong electronics manufacturing zones, where grid instability exceeds twenty voltage events monthly and incumbent service coverage remains thin. Anchor go-to-market strategy around lithium-ion runtime guarantees that displace lead-acid refresh cycles in northern industrial parks.
For Investors and Strategic Acquirers: Indonesia's Ministry of Industry local content mandates reshape the acquisition landscape, elevating domestic assembly capabilities above pure technology differentiation in government procurement eligibility. Target UPS integrators with certified Batang or Bekasi production footprints. Monitor Directorate General of Electricity enforcement intensity as inflection indicator for import substitution velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Semiconductors | Captive SiC sourcing insulates Schneider Electric and Delta Electronics from Taiwan foundry allocation bottlenecks. |
| Modular Architecture Platform Launch | Hot-swappable 500-2000 kVA blocks match hyperscale tenant expansion timelines in Jakarta-Bandung corridor. |
| Direct Service Contract Engagement | Manufacturer-captured recurring revenue displaces Bangkok and Jakarta distributor margins in co-location clusters. |
| Local Content Compliance Investment | Domestic assembly quotas in Batang and Bekasi unlock Indonesian government and state-owned enterprise procurement. |
| Grid-Interactive Bi-Directional Certification | Frequency regulation revenue streams monetize battery assets beyond backup functions for data center operators. |
Research Methodology
A spread of perspectives from data center infrastructure directors, electrical contractor procurement leads, power semiconductor supply managers, and ASEAN regulatory affairs specialists converged on the working assumptions underpinning this analysis. Primary fieldwork combined structured interviews with secondary validation across IEC certification databases, customs import records, and national electricity regulator filings. Bottom-up facility-level capacity assessments triangulated against top-down national grid investment disclosures.
Segmentation dimensions modeled span product topology, power capacity tier, installation form factor, and end-use vertical across the projection horizon. CAGRs derive from facility construction pipeline tracking and battery chemistry substitution curves. Forecast inputs incorporate Directorate General of Electricity mandate enforcement schedules and Building and Construction Authority licensing throughput.
Forecasts assume regulatory continuity in Indonesian local content regimes and Singapore resilience licensing; material policy shifts would require re-modeling. Supply chain disruption scenarios and lithium price volatility represent specific revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Global Synchronous Motor Market
Power Systems
Shunt Reactor Market
Power Systems
Thyristor Market
Power Systems
Global Flexible Batteries Market
Power Systems
Global Data Center Transformer Market
Power Systems
Thermal Management Systems Market
Power Systems
Asia Pacific Transformer Monitoring System Market
Power Systems
Laptop Battery Market
Power Systems
South America Battery Management System Market
Power Systems
Transformer Tap Changers and Voltage Control Relay Market
Power Systems
Japan Surge Protector Market
Power Systems
Pulse Generator Market
Power Systems
USB Power Adapters Market
Power Systems
Power Electronics Equipment Cooling System Market
Power Systems
Battery Equalizer Market
Power Systems
Embedded Power Generation Market