
 E-Axle Inverter and Control Unit Systems Market | 2026-2036
E-Axle Inverter and Control Unit Systems Market Size, Share, and Industry Trends Forecast 2026-2036
E-Axle Inverter and Control Unit Systems Market Insights
Platform licensing revenue is rewriting margin capture rules for e-axle suppliers as automakers internalize control software while outsourcing power hardware. Robert Bosch leverages its integrated manufacturing scale to supply combined inverter-control modules across European and Asian OEM programs. ZF Friedrichshafen anchors its position through deep vertical integration into motor-inverter gear assembly, reducing interface complexity for vehicle assemblers. Nidec Corporation specializes in compact, high-revving motor-inverter units for the A-segment and kei-car electrification pipeline in Japan.
E-axle inverter and control unit systems comprise power semiconductor modules, gate drivers, DC-link capacitors, and thermal management hardware that convert battery DC to variable-frequency AC for traction motors, typically handling 300-800V architectures and continuous outputs from 50 kW to 300 kW. Silicon carbide technology is displacing silicon IGBT in premium battery electric vehicle platforms due to reduced switching losses and higher thermal tolerance, though silicon IGBT retains cost advantages in hybrid electric vehicle applications where voltage and duty cycles remain moderate. Combined module configurations concentrate the highest value per unit as OEMs pursue packaging density and assembly line simplification, while modular inverter architectures serve commercial electric vehicle builders needing scalable power ratings across truck and bus duty cycles.
FDA oversight of electromagnetic compatibility in medical-grade vehicle applications, EPA emissions compliance deadlines for commercial fleets, and the EU AI Act's algorithmic transparency requirements for autonomous drive systems all shape product certification burdens and R&D allocation for inverter suppliers. NHTSA motor vehicle safety standards in the United States and China's GB standards for electric vehicle power systems create divergent testing protocols that fragment homologation costs. Stakeholders must monitor how battery electric vehicle platform consolidation among OEMs alters sourcing leverage between captive in-house production and tier-1 supplier relationships.
Market Dynamics
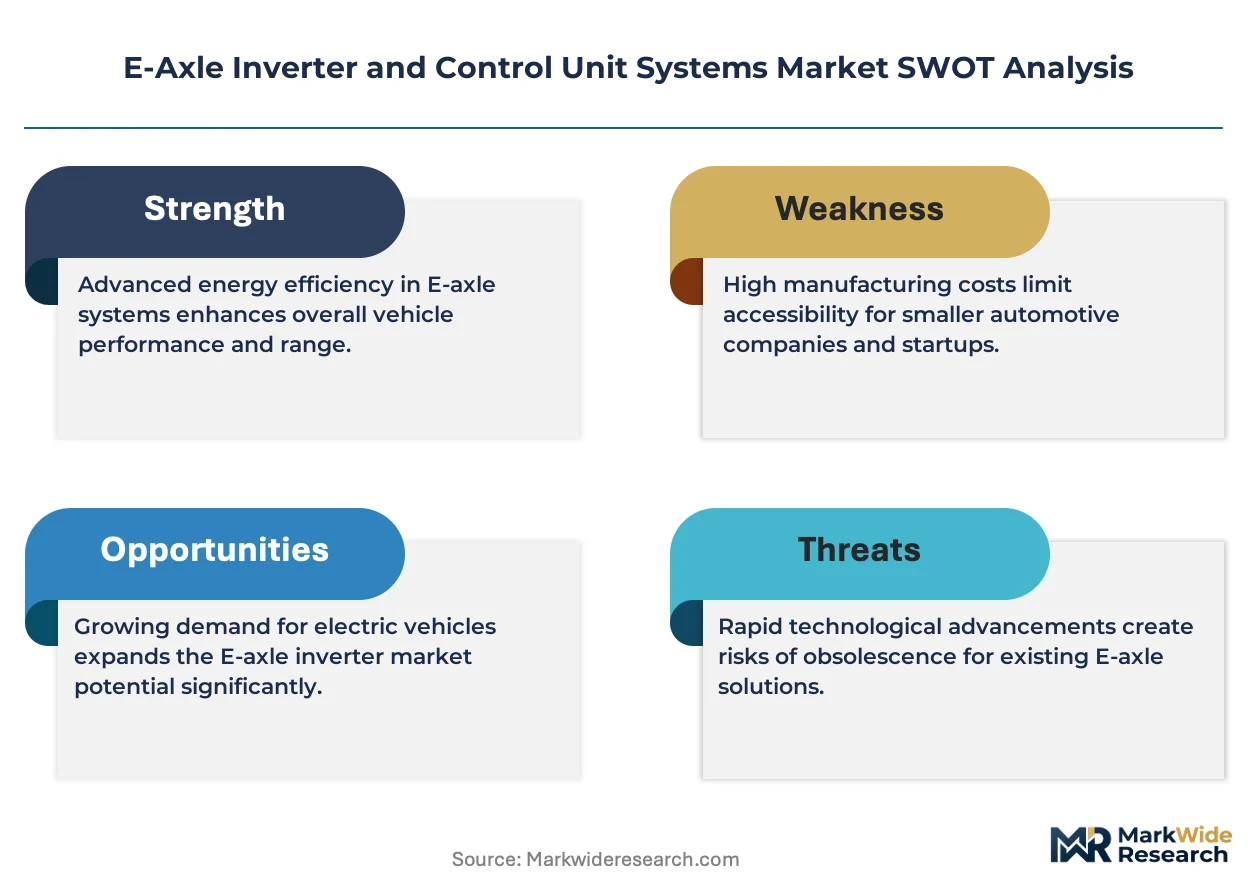
Silicon carbide semiconductor adoption is compressing inverter thermal budgets while simultaneously inflating bill-of-materials costs, forcing OEMs to recalibrate platform sourcing strategies between captive production and tier-1 supply.
Growth Catalysts
- EPA commercial fleet emissions deadlines:United States truck and bus electrification mandates accelerate 800V architecture procurement for heavy-duty powertrains.
- Yangtze River Delta manufacturing cluster:Concentrated domestic EV output in China generates procurement scale that reduces per-unit inverter costs through localized SiC wafer processing.
- Silicon carbide MOSFET technology:Reduced switching losses enable smaller thermal management hardware, shrinking package dimensions for passenger vehicle underfloor mounting.
Market Restraints
- Silicon carbide substrate shortage:Limited 150mm wafer fabrication capacity concentrates supply risk among three dominant substrate vendors.
- GB standards compliance fragmentation:China's electric vehicle power system testing protocols diverge from NHTSA safety standards, multiplying homologation costs for dual-market suppliers.
- Silicon IGBT residual cost advantage:Mature silicon foundry capacity maintains pricing pressure on SiC modules in hybrid applications below 400V.
Strategic Opportunities
- EU Green Deal CO2 fleet targets:Tightening automotive compliance windows create regulatory pull for integrated inverter-motor-gearbox modules that reduce assembly complexity.
- Commercial vehicle electrification:Scalable modular inverter architectures address truck and bus duty cycles where standardized power ratings reduce engineering overhead.
- Japan kei-car electrification pipeline:Compact high-revving motor-inverter units serve A-segment vehicles where packaging density commands premium positioning.
Industry Challenges
- Power electronics engineering scarcity:Specialized gate driver and thermal design expertise concentrates among automotive tier-1 veterans, constraining new entrant ramp speed.
- EU AI Act algorithmic transparency:Autonomous drive system certification burdens extend inverter control unit validation timelines for AI-integrated traction management.
- 800V platform integration complexity:Battery electric vehicle architectures require redesigned DC-link capacitors and contactor sequencing that strain legacy supplier development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Axle Inverter and Control Unit Systems Market |
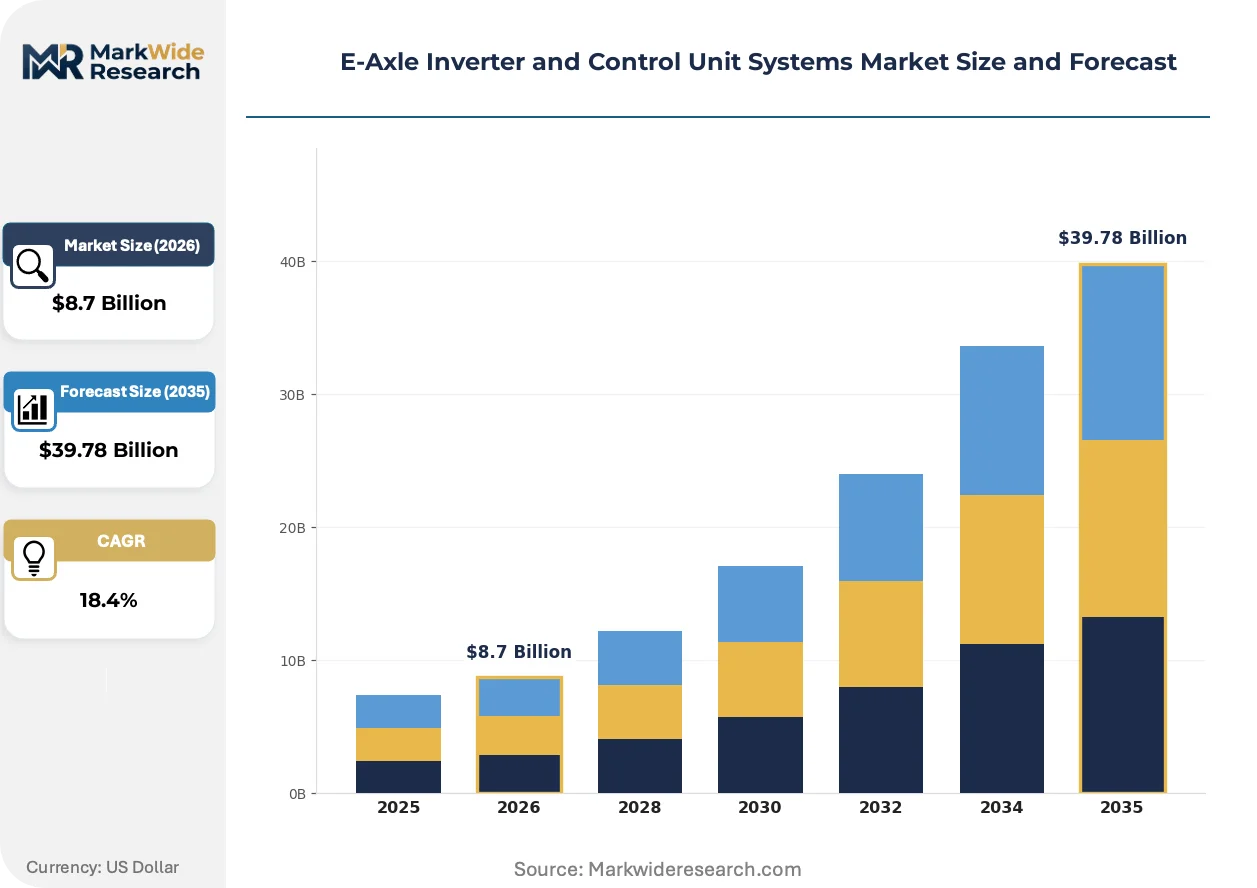
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Integrated Inverter, Separate Control Unit, Combined Module, Modular Inverter Technology: Silicon Carbide, Gallium Nitride, Silicon IGBT, MOSFET, Wide Bandgap Application: Battery Electric Vehicles, Hybrid Electric Vehicles, Commercial Electric Vehicles, Specialty Electric Vehicles End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Robert Bosch, ZF Friedrichshafen, Nidec Corporation, Continental AG, BorgWarner, DENSO Corporation, Valeo, Mitsubishi Electric, Hitachi Astemo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Axle Inverter and Control Unit Systems Market Trends and Innovations
Power semiconductor packaging and thermal interface materials are converging to enable continuous power density improvements that alter competitive positioning between integrated module suppliers and discrete component vendors.
Silicon carbide power modules convert battery DC to variable-frequency AC with switching frequencies above 20 kHz, enabling smaller DC-link capacitors. Premium battery electric vehicle platforms in Germany and South Korea adopt these modules aggressively. The technology is hybridizing traditional inverter and motor housing boundaries into single mechanical assemblies.
EU AI Act algorithmic transparency requirements impose documentation burdens on autonomous drive systems that integrate traction control with path planning. Inverter suppliers must now validate control software interpretability alongside hardware safety. Commercial vehicle programs targeting European deployment face extended type-approval timelines.
Vehicle assemblers now specify combined inverter-control modules rather than discrete power electronics stacks, collapsing traditional tiering structures. Tier-1 suppliers with integrated manufacturing scale capture expanded scope per platform. China's Yangtze River Delta manufacturing cluster exhibits this procurement compression most visibly, where domestic OEMs consolidate sourcing leverage through single-module contracts.
E-Axle Inverter and Control Unit Systems Market Segmentation
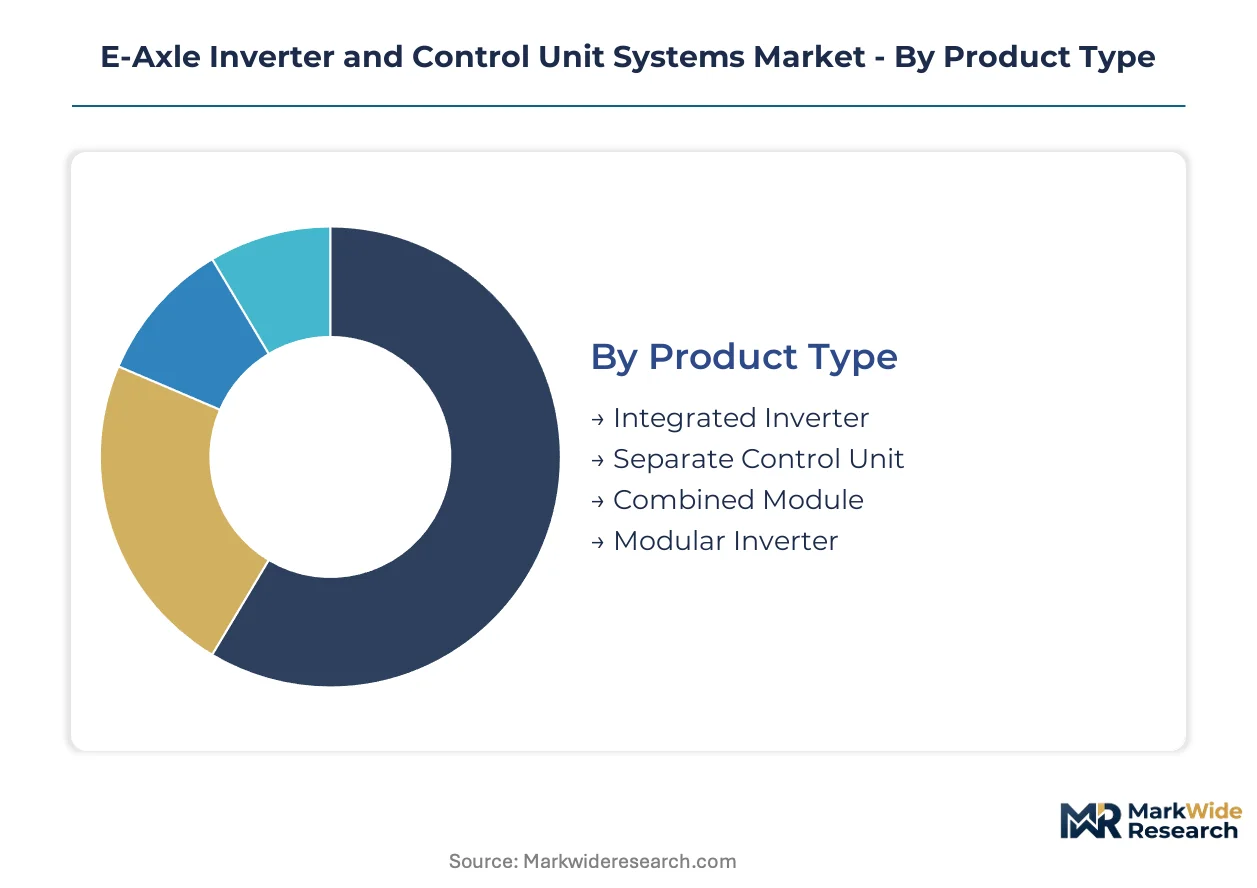
E-axle inverter segmentation reflects divergent sourcing strategies between integrated platform builders and modular procurement specialists. Technology choices and application requirements fragment supplier portfolios across voltage classes and thermal architectures.
Product Type:
Mature integrated configurations dominate premium passenger programs while emerging modular formats capture commercial vehicle flexibility needs.
- Integrated Inverter:Combines power semiconductor modules, gate drivers, and DC-link capacitors within a single housing optimized for underfloor mounting. German and South Korean OEMs specify these units for 800V battery electric vehicle platforms where packaging density reduces assembly line complexity.
- Combined Module:Merges inverter hardware with motor control firmware in unified assemblies that collapse traditional tiering structures. China's Yangtze River Delta manufacturing cluster sources these most aggressively as domestic OEMs consolidate procurement leverage through single-module contracts.
- Separate Control Unit:Discrete control electronics that manage traction algorithms independently from power hardware. Tier-1 suppliers in Japan favor this architecture for kei-car electrification programs requiring software customization.
- Modular Inverter:Scalable power electronics stacks enabling standardized ratings across truck and bus duty cycles. Commercial vehicle builders in the United States specify these for EPA fleet compliance timelines.
Combined Module handles the majority of throughput; Modular Inverter is the fastest mover on share.
Technology:
Cost tiers separate premium wide bandgap platforms from mature silicon architectures serving hybrid applications.
- Silicon Carbide:Wide bandgap semiconductors switch above 20 kHz with reduced thermal losses, enabling smaller DC-link capacitors and compact cooling hardware. Premium battery electric vehicle platforms adopt these modules aggressively despite substrate supply constraints.
- Silicon IGBT:Mature bipolar transistors retain cost advantages in hybrid electric vehicle applications below 400V where voltage stress and duty cycles remain moderate. Foundry capacity abundance sustains pricing pressure on SiC alternatives.
- Gallium Nitride:Emerging high-frequency devices targeting auxiliary power conversion and onboard charging integration. Japanese suppliers pilot these for A-segment vehicle cost reduction.
- MOSFET:Metal-oxide-semiconductor field-effect transistors serving lower-power traction applications and voltage regulation subsystems. Chinese domestic suppliers scale these for regional EV cost targets.
- Wide Bandgap:Umbrella category encompassing next-generation materials beyond silicon for thermal tolerance and efficiency gains. European OEMs specify these for EU Green Deal CO2 fleet compliance.
Silicon IGBT maintains the largest installed base; Silicon Carbide is climbing the fastest on technology substitution.
Application:
Volume concentration in passenger battery electric platforms contrasts with emerging commercial vehicle electrification pipelines.
- Battery Electric Vehicles:Pure-electric architectures demanding 300-800V inverter systems with continuous outputs from 50 kW to 300 kW. OEM procurement concentrates in Germany and China for silicon carbide module integration.
- Commercial Electric Vehicles:Truck and bus platforms requiring scalable thermal management and extended duty cycle reliability. EPA commercial fleet emissions deadlines in the United States accelerate 800V architecture procurement for heavy-duty powertrains.
- Hybrid Electric Vehicles:Dual-powertrain systems utilizing lower-voltage inverters below 400V with moderate switching frequencies. Silicon IGBT cost advantages persist in this segment where electrification serves emissions reduction rather than full propulsion.
- Specialty Electric Vehicles:Niche applications including mining equipment, agricultural machinery, and marine propulsion requiring customized ingress protection and shock tolerance. Aftermarket retrofit demand emerges in European industrial sectors.
Battery Electric Vehicles absorbs the dominant procurement volume; Commercial Electric Vehicles shows the steepest expansion trajectory on regulatory mandate acceleration.
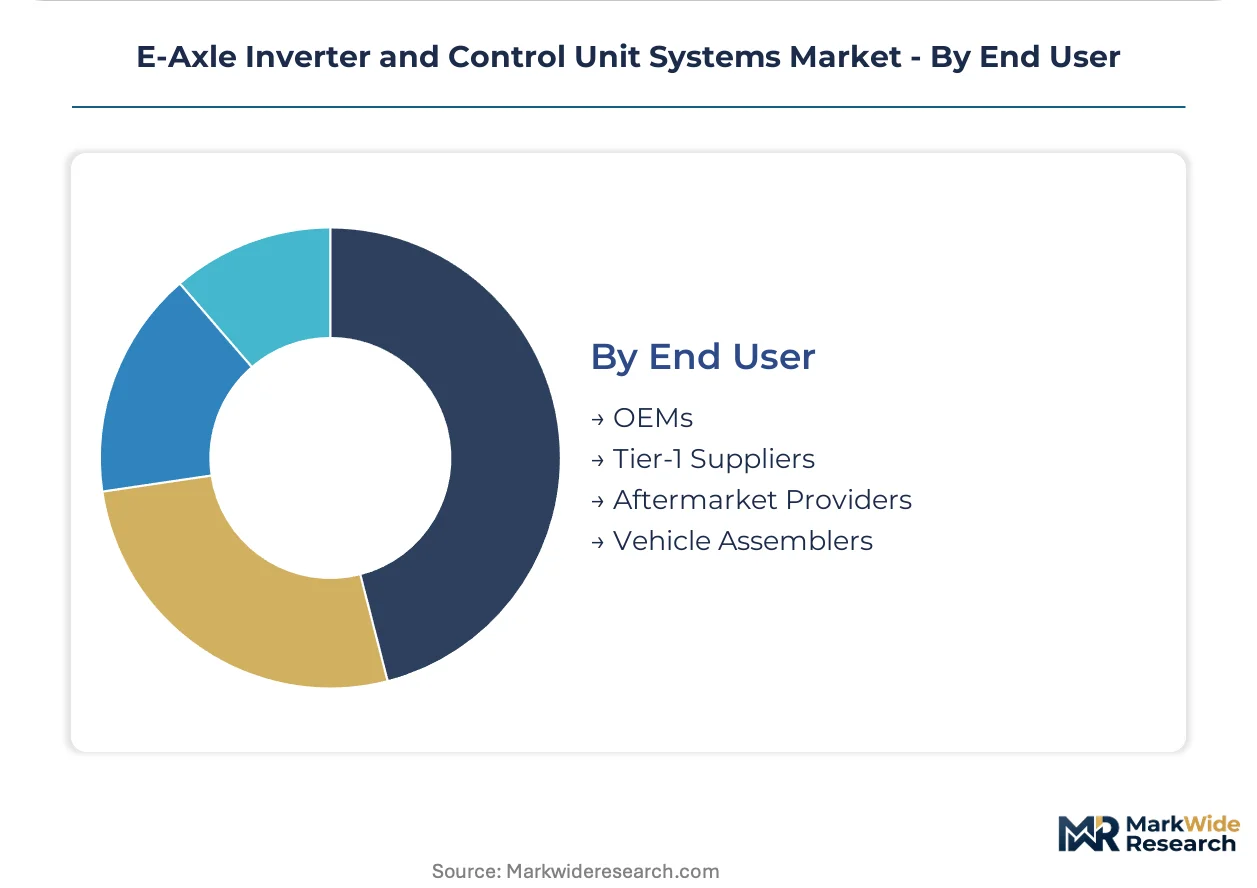
End User:
Customer type determines margin structure, with captive OEM production competing against tier-1 supplier outsourcing decisions.
- OEMs:Vehicle manufacturers internalizing control software development while outsourcing power hardware fabrication. Platform consolidation among German and Chinese OEMs alters sourcing leverage between captive production and external supply.
- Tier-1 Suppliers:Integrated module specialists capturing expanded scope per platform through combined inverter-control manufacturing scale. Robert Bosch and ZF Friedrichshafen anchor European and Asian procurement programs.
- Vehicle Assemblers:Contract manufacturers and regional builders specifying modular architectures for flexible powertrain integration. China's Yangtze River Delta cluster exhibits this procurement pattern most visibly.
- Aftermarket Providers:Service networks and retrofit specialists addressing warranty replacement and performance upgrade demand. Specialty electric vehicle segments in Europe generate niche aftermarket traction.
OEMs direct the largest procurement decisions; Tier-1 Suppliers are gaining share fastest on outsourcing acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys integrated combined modules at volume scale while Germany and the United States pursue premium silicon carbide platforms for 800V architectures. Japan maintains specialized demand for compact high-revving units in A-segment vehicles. This consumption-mix differential shapes supplier investment allocation across manufacturing footprints.
China
Domestic OEM procurement concentrates in the Yangtze River Delta manufacturing cluster where localized silicon carbide wafer processing reduces per-unit inverter costs. GB standards for electric vehicle power systems mandate testing protocols that diverge from Western safety regimes. Shanghai and surrounding Jiangsu and Zhejiang provinces generate procurement scale that dominates global EV output volume.
Germany
Premium battery electric vehicle platforms from BMW, Mercedes-Benz, and Volkswagen specify silicon carbide modules for underfloor mounting density. EU Green Deal CO2 fleet targets tighten compliance windows through 2035, accelerating integrated inverter-motor-gearbox procurement. Baden-Württemberg and Bavaria host concentrated power electronics engineering talent and tier-1 supplier headquarters.
United States
EPA commercial fleet emissions deadlines accelerate 800V architecture procurement for heavy-duty truck and bus electrification. NHTSA motor vehicle safety standards create testing protocols that fragment homologation costs for dual-market suppliers. Michigan and California anchor OEM engineering centers and commercial vehicle pilot programs.
Japan
Kei-car electrification programs drive demand for compact high-revving motor-inverter units where packaging density commands premium positioning. METI industrial policy supports domestic semiconductor substrate development to reduce import dependency. Kanto and Kansai regions concentrate automotive electronics manufacturing and tier-1 supplier engineering.
South Korea
Hyundai and Kia battery electric vehicle platforms adopt silicon carbide switching above 20 kHz for reduced thermal management hardware. MFDS medical-grade EMC requirements shape certification burdens for specialized vehicle applications. Seoul Capital Area and Busan-Ulsan corridor host integrated powertrain manufacturing and semiconductor packaging facilities.
E-Axle Inverter and Control Unit Systems Market Competitive Landscape
Capability concentration sits with tier-1 automotive electronics veterans possessing gate driver and thermal design expertise; scale advantage sits with diversified industrial conglomerates leveraging integrated manufacturing across multiple OEM programs. The vendor base organizes around three strategic archetypes: integrated module specialists capturing combined inverter-control contracts, discrete component suppliers serving modular procurement needs, and captive OEM production units internalizing control software. Dominant competitive moves include strategic partnerships for silicon carbide substrate access and portfolio diversification into commercial vehicle scalable architectures.
Among German-based diversified suppliers, Robert Bosch and ZF Friedrichshafen exemplify the integrated module archetype through combined inverter-control manufacturing scale across European and Asian OEM programs. Nidec Corporation represents the compact specialization vector, occupying a position within Japan's kei-car electrification supply base. These three anchors illustrate how geographic manufacturing concentration aligns with distinct technology-application pairings in customer procurement decisions.
| Leading Market Players |
|---|
| Robert Bosch |
| ZF Friedrichshafen |
| Nidec Corporation |
| Continental AG |
| BorgWarner |
| DENSO Corporation |
| Valeo |
| Mitsubishi Electric |
| Hitachi Astemo |
| Others |
Pricing and Supply Chain Analysis
Silicon carbide substrate fabrication in Japan, Germany, and the United States concentrates upstream margin capture among three dominant wafer vendors, while downstream pricing power fragments across OEM captive production and tier-1 supply decisions. This structural asymmetry forces inverter suppliers to arbitrage between long-term offtake security and spot-market flexibility in procurement contracts.
Pricing Analysis
Long-term offtake agreements dominate silicon carbide procurement between substrate vendors and tier-1 module suppliers, locking in volume commitments against spot-price volatility. Price differentiation hinges on certification grade—automotive AEC-Q100 qualification commands substantial premiums over industrial-tier modules—and volume scale, where Yangtze River Delta OEMs extract concessions through consolidated platform sourcing. Cost compression in silicon IGBT tiers is intensifying because mature foundry capacity sustains pricing pressure on wide bandgap alternatives. Commercial vehicle builders exhibit highest price sensitivity due to total-cost-of-ownership procurement models, while German premium OEMs prioritize thermal performance over unit economics.
Supply Chain Analysis
Silicon carbide feedstock draws from Japan, Germany, and the United States, where 150mm wafer fabrication capacity remains constrained against ramping EV platform demand. Critical inputs span high-purity silicon carbide boules, ceramic substrate materials, and specialized gate driver integrated circuits. Single-source vulnerability concentrates in substrate supply, where qualification timelines exceed eighteen months for alternative vendors. Distribution runs through tier-1 integrated module specialists that consolidate power semiconductor, thermal management, and control firmware into unified assemblies for OEM direct procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
E-axle inverter procurement is consolidating around software-defined platform economics, where automakers internalize control algorithms while outsourcing power hardware fabrication to capture interoperability gains across vehicle generations.
For Market Incumbents: Harden silicon carbide substrate access through backward integration or multi-year offtake with Japanese and German wafer vendors, insulating against supply interruption as EV platform volumes accelerate. Deepen captive supply of gate driver and thermal interface expertise to defend against modular inverter specialists encroaching on combined module contracts. EPA commercial fleet deadlines and EU AI Act certification burdens constitute immediate margin pressure points requiring preemptive compliance investment. For New Entrants and Emerging Players: Establish a beachhead in commercial vehicle modular inverter architectures, where scalable power ratings and standardized thermal management reduce engineering overhead for truck and bus duty cycles. Japan's kei-car electrification pipeline offers secondary penetration opportunity through compact high-revving motor-inverter units where packaging density commands premium positioning. Partner with Yangtze River Delta vehicle assemblers on software customization for discrete control unit procurement, bypassing integrated module incumbents. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed tier-1 automotive electronics specialists possessing gate driver and thermal design engineering benches but lacking silicon carbide substrate security. Long-term viability over the next decade hinges on demonstrated qualification with 800V battery electric platforms and autonomous drive system integration capability. Watch for inflection signals in OEM platform consolidation announcements that shift sourcing leverage from captive production to external supply.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Substrate Partnership | Secures wafer supply from Japanese and German vendors against EV platform demand surge. |
| Combined Module Manufacturing Scale-Up | Captures consolidated procurement leverage from Yangtze River Delta domestic OEMs. |
| Commercial Vehicle Modular Architecture | Addresses EPA fleet compliance timelines with scalable power ratings for heavy-duty duty cycles. |
| Gate Driver and Thermal Design Investment | Builds defensive capability moat as power electronics engineering scarcity intensifies. |
| EU AI Act Control Software Validation | Extends type-approval timelines for autonomous drive system traction management integration. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, vehicle production databases, and semiconductor trade data. Primary interviews engaged OEM platform engineers, tier-1 supplier procurement leads, power semiconductor substrate vendors, and thermal management specialists. Secondary validation drew from EPA emissions compliance records, NHTSA safety standard documentation, China's GB standards publications, and EU Green Deal regulatory texts. Bottom-up unit demand modeling triangulated against top-down market sizing across voltage class, technology substitution, and regional production cluster dimensions.
Forecast inputs span silicon carbide adoption curves, platform consolidation announcements, and regulatory compliance deadline acceleration across the projection horizon. Segmentation modeling incorporated product type, semiconductor technology, vehicle application, and end-user sourcing strategy. CAGRs derived from unit volume trajectories and value-per-unit evolution through technology substitution effects. Industry-specific inputs included OEM 800V architecture deployment schedules and commercial vehicle electrification pipeline visibility.
Stress conditions across silicon carbide substrate supply disruption, hybrid electric vehicle demand persistence, and regulatory timeline delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about technology substitution pace and OEM sourcing strategy evolution. Cross-checking against IHS Markit vehicle registration data and semiconductor industry association capacity announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Nimh Rechargeable Battery Market
Power Systems
Battery Electronic Control Unit Market
Power Systems
High Voltage Direct Current Power Supply Market
Power Systems
Digital Inverter Market
Power Systems
APAC Variable Frequency Drives Market
Power Systems
Superconducting Magnet Systems Market
Power Systems
Asia-Pacific Automotive DC-DC Converters Market
Power Systems
High Voltage Ceramic Zinc Oxide Surge Arrester Market
Power Systems
Gan-Powered Chargers Market
Power Systems
Thyristor Market
Power Systems
Synchronous Condenser Market
Power Systems
Automotive Power Electronics Market
Power Systems
Power Amplifier Modules Market
Power Systems
Thermoelectric Assemblies Market
Power Systems
Surface Mounted Medium Voltage Distribution Panel Market
Power Systems
Hybrid Inverters Market