
 Switch Mode Power Supply (SMPS) Market | 2026-2036
Switch Mode Power Supply (SMPS) Market Size, Share, and Industry Trends Forecast 2026-2036
Switch Mode Power Supply (SMPS) Market Analytics
Aftermarket service revenue for legacy rack power units is rewriting margin allocation across the SMPS value chain. Delta Electronics leverages its captive semiconductor fabrication to sustain cost leadership in high-density server supplies. Infineon Technologies anchors European industrial demand through silicon carbide MOSFET integration. MEAN WELL dominates the mid-wattage LED driver segment through direct distribution control across Asia.
A switch mode power supply converts electrical power using high-frequency switching regulators with operating frequencies typically spanning 20 kHz to several megahertz, enabling compact magnetics and reduced energy loss compared to linear alternatives. AC-DC converters occupy the largest revenue pool due to universal grid-interface requirements across consumer and industrial equipment, while DC-DC converters within automotive systems represent the fastest structural expansion as 48-volt mild-hybrid architectures proliferate. Flyback converter technology leads in sub-150-watt applications where cost minimization governs design, whereas full-bridge topologies command premium positioning in multi-kilowatt renewable energy inverters.
The US Department of Energy enforces minimum efficiency standards under its External Power Supply program, while the EU Ecodesign Directive and CE marking requirements mandate standby power below 0.5 watts for most categories. China's GB standards and NMPA certification protocols for medical power supplies create parallel compliance tracks that shape export manufacturing footprints. Japan's METI Top Runner program continuously ratchets efficiency benchmarks, forcing design refreshes every three to four product cycles. Stakeholders must monitor gallium nitride transistor cost curves and corresponding ripple specifications that determine whether next-generation topologies displace incumbent silicon architectures in volume applications.
Market Dynamics
Topology migration from silicon to wide-bandgap semiconductors is compressing converter footprints while forcing wholesale redesign of magnetic components and thermal management systems across the supply base.
Growth Catalysts
- EU Ecodesign Directive:Standby power mandates below 0.5 watts accelerate topology refreshes in consumer electronics and office equipment, pulling demand for resonant converters.
- 48-volt mild-hybrid architectures:Automotive DC-DC converter procurement multiplies as European and Chinese OEMs electrify powertrains without full battery-electric conversion.
- Server rack density:Data center power density requirements above 50 kW per rack drive procurement of gallium nitride-based totem-pole PFC stages.
Market Restraints
- Silicon carbide substrate shortages:Wafer supply concentration in Japan and the United States constrains MOSFET availability for industrial drives above 10 kW.
- EMI certification timelines:FCC Part 15 and CISPR 32 testing cycles extend 8-14 weeks, gating product launches in medical and aerospace verticals.
- Copper and ferrite price volatility:Magnetics constitute 25-35% of bill-of-materials cost, exposing margins to commodity swings.
Strategic Opportunities
- India BIS certification expansion:Compulsory registration for power adapters above 20W opens replacement demand in consumer electronics as local assembly scales.
- Wireless power transfer convergence:Integration of resonant inductive coils with conventional SMPS creates unified charging infrastructure for electric vehicle fleets.
- Refurbishment channel development:Enterprise IT asset disposition programs generate secondary revenue streams for legacy rack power unit servicing.
Industry Challenges
- Magnetics design expertise scarcity:High-frequency transformer engineering for megahertz-class converters requires specialized simulation capabilities concentrated in Germany and Taiwan.
- Multi-jurisdiction certification overlap:Simultaneous UL, CE, and GB standard compliance forces redundant testing and documentation overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Switch Mode Power Supply (SMPS) Market |
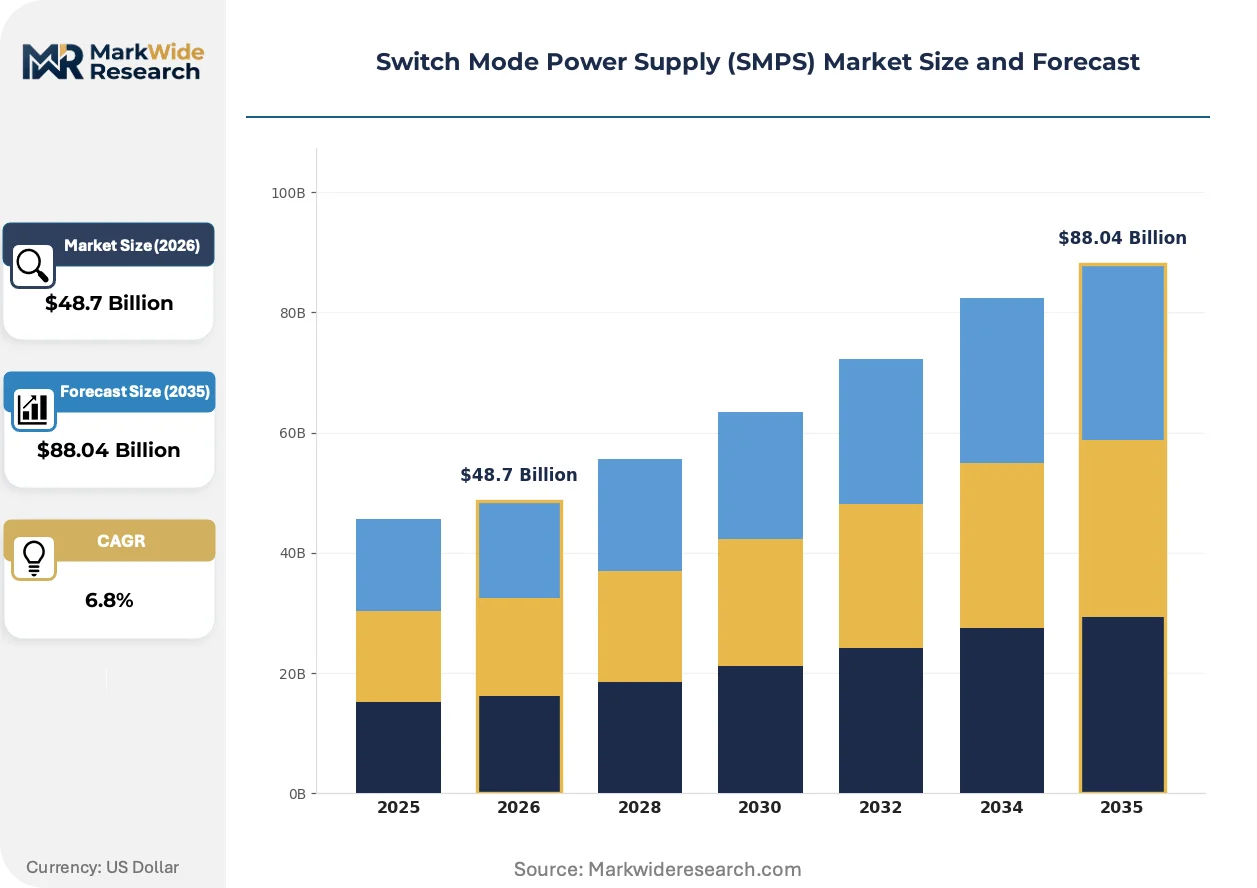
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC-DC Converters, DC-DC Converters, Isolated Converters, Non-Isolated Converters End User: Consumer Electronics, Industrial Equipment, Telecommunications, Automotive Systems Technology: Forward Converter, Flyback Converter, Half-Bridge Converter, Full-Bridge Converter Application: Power Tools, Lighting Systems, Computer Hardware, Renewable Energy Systems |
| Companies Covered | ON Semiconductor, Delta Electronics, Infineon Technologies, Schneider Electric, MEAN WELL, TDK Corporation, STMicroelectronics, ABB Group, Texas Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Switch Mode Power Supply (SMPS) Market Evolving Landscape
Active power device evolution and procurement model fragmentation are simultaneously compressing product lifecycles and redistributing value capture toward semiconductor fabrication and aftermarket service layers.
Gallium nitride high-electron-mobility transistors are collapsing the cost-performance boundary between hard-switched and soft-switched topologies in sub-500-watt applications. Server power supply manufacturers now specify GaN for totem-pole PFC stages below 3 kW, eliminating bridge rectifier losses that silicon superjunction MOSFETs cannot match. The resulting efficiency gains above 98% are enabling 80 Plus Titanium certification without interleaved converter complexity.
The EU Ecodesign Directive's 2026 standby power tier is forcing redesigns across external adapter portfolios sold into European markets. Manufacturers must eliminate bleed resistors and reconfigure burst-mode controllers to meet sub-0.3-watt thresholds for high-volume mobile phone chargers. Medical power supply vendors face parallel pressure from the EU MDR's electromagnetic compatibility annex, extending documentation requirements for patient-contact equipment.
Direct procurement from semiconductor foundries is displacing traditional distributor relationships among tier-one server OEMs. Foxconn and Quanta now negotiate wafer starts directly with TSMC and GlobalFoundries for integrated power stage silicon, compressing margin for conventional component distributors. This pattern concentrates most visibly in Taiwan and China's Guangdong province, where vertically integrated electronics manufacturing services dominate hyperscale server assembly.
Switch Mode Power Supply (SMPS) Market Segmentation
SMPS segmentation reflects divergent physics requirements across voltage conversion tasks and end-use reliability standards. Topology selection, isolation needs, and load characteristics create distinct procurement channels with limited substitutability between segments.
Product Type:
Mature AC-DC architectures dominate unit volume, while emerging wide-bandgap DC-DC designs reshape automotive and data center procurement.
- AC-DC Converters:Grid-interface rectification circuits with active power factor correction handle 85-264V universal input ranges. Demand concentrates in external adapters for consumer electronics bound by EU Ecodesign standby power mandates below 0.5 watts.
- DC-DC Converters:Point-of-load regulators step voltage between battery or bus levels and processor rails. Automotive 48-volt mild-hybrid architectures in Germany and China multiply procurement for buck-boost stages between subsystems.
- Isolated Converters:Transformer-coupled topologies provide galvanic separation for medical and industrial safety compliance. Japan's METI efficiency benchmarks force design refreshes every three to four product cycles.
- Non-Isolated Converters:Synchronous buck and boost regulators without magnetic isolation serve cost-sensitive embedded systems. Point-of-load modules in server motherboards prioritize density over electrical separation.
AC-DC Converters handle the majority of throughput; DC-DC Converters are the fastest mover on share.
End User:
Application cost tiers separate commodity consumer volumes from premium industrial reliability requirements.
- Consumer Electronics:External adapters and internal subsystems for smartphones, laptops, and appliances. China's GB standards and NMPA certification protocols shape export manufacturing footprints for medical-adjacent devices.
- Industrial Equipment:Motor drives, programmable logic controllers, and process automation power modules. Silicon carbide MOSFET integration from European suppliers anchors demand above 10 kW.
- Telecommunications:Base station rectifiers and optical network terminal power supplies. Data center power density requirements above 50 kW per rack drive procurement of gallium nitride-based stages.
- Automotive Systems:Battery management, infotainment, and electrified powertrain converters. 48-volt architectures proliferate across European and Chinese OEMs without full battery-electric conversion.
Consumer Electronics commands the largest addressable base; Automotive Systems is climbing the fastest on electrification intensity.
Technology:
Topology selection maps directly to power level and switching frequency trade-offs.
- Forward Converter:Two-transistor and active-clamp variants serve medium-power industrial applications. Magnetics design expertise scarcity in Germany and Taiwan constrains megahertz-class transformer engineering.
- Flyback Converter:Single-switch topology with energy storage in the transformer core dominates sub-150-watt applications. Cost minimization governs design in consumer adapters and LED drivers.
- Half-Bridge Converter:Balanced switching reduces voltage stress on power semiconductors. Mid-range server and telecom power supplies balance efficiency against magnetic complexity.
- Full-Bridge Converter:Four-switch topology achieves highest efficiency in multi-kilowatt renewable energy inverters. Premium positioning in solar string inverters and energy storage systems.
Flyback Converter handles the majority of unit shipments; Full-Bridge Converter is gaining share fastest on renewable energy deployment.
Application:
Customer type fragmentation separates aftermarket replacement from OEM-specified designs.
- Power Tools:Cordless device battery chargers and brushless motor drives. EMI certification timelines extending 8-14 weeks gate product launches in professional-grade equipment.
- Lighting Systems:LED drivers and fluorescent ballast replacements. MEAN WELL's direct distribution control across Asia dominates mid-wattage procurement.
- Computer Hardware:Server rack power units, desktop supplies, and graphics card converters. Aftermarket service revenue for legacy rack units is rewriting margin allocation.
- Renewable Energy Systems:Solar microinverters, power optimizers, and energy storage converters. Copper and ferrite price volatility exposes margins in magnetics-heavy designs.
Computer Hardware anchors procurement volume; Renewable Energy Systems shows the steepest expansion trajectory on inverter deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across geographies. Chinese buyers prioritize unit cost in high-volume procurement, while German and Japanese purchasers absorb premiums for efficiency-certified industrial units.
China
Domestic server deployment and electric vehicle manufacturing expand converter procurement at scale. GB standards and NMPA certification protocols for medical power supplies create parallel compliance tracks that shape export manufacturing footprints. Yangtze River Delta clusters around Shanghai and Suzhou concentrate captive semiconductor fabrication for integrated power stages.
Germany
Automotive 48-volt mild-hybrid architectures from Munich and Stuttgart OEMs multiply DC-DC converter demand. EU Ecodesign Directive efficiency mandates compress standby losses and force topology upgrades across industrial equipment. Bavaria's industrial automation corridor anchors silicon carbide MOSFET integration for drives above 10 kW.
United States
Data center power density requirements above 50 kW per rack drive gallium nitride-based procurement. Department of Energy External Power Supply program enforces minimum efficiency standards that eliminate legacy linear alternatives. Texas and Arizona hyperscale server campuses negotiate direct wafer starts with foundries, bypassing component distributors.
Japan
METI Top Runner program continuously ratchets efficiency benchmarks, forcing design refreshes every three to four product cycles. Industrial equipment manufacturers in Nagoya and Osaka prioritize medical-grade isolation for patient-contact applications. Chubu region engineering centers concentrate high-frequency transformer simulation capabilities for megahertz-class converters.
South Korea
Consumer electronics OEMs in Seoul and Suwon bind external adapter suppliers to sub-0.3-watt standby thresholds under EU export requirements. Domestic battery-electric vehicle production expands onboard charger procurement for DC-DC stages. Gyeonggi-do semiconductor packaging clusters support integrated power module assembly for automotive tier-ones.
Switch Mode Power Supply (SMPS) Market Competitive Landscape
Capability concentration sits with semiconductor-integrated tier-one suppliers; scale advantage sits with high-volume electronics manufacturing services. The market structures around three tiers: captive fabrication specialists, broad-line industrial distributors, and fabless power semiconductor designers. Consolidation pressure runs through direct foundry procurement by server OEMs and aftermarket service revenue capture for legacy rack units. Competitive moves center on backward integration into semiconductor fabrication and geographic certification expansion for emerging markets.
Among semiconductor-integrated suppliers, ON Semiconductor, Infineon Technologies, and Delta Electronics exemplify the capability tier where captive wafer processing and magnetic component design converge. These entities occupy positions that bundle power stage silicon with thermal management expertise, serving data center and automotive verticals where efficiency certification gates procurement. Their archetype represents the boundary between component supply and subsystem integration, with geographic footprints concentrated in East Asian manufacturing corridors and European industrial zones.
| Leading Market Players |
|---|
| ON Semiconductor |
| Delta Electronics |
| Infineon Technologies |
| Schneider Electric |
| MEAN WELL |
| TDK Corporation |
| STMicroelectronics |
| ABB Group |
| Texas Instruments |
| Others |
Value Network & Pricing Analysis
The Shanghai-Rotterdam maritime corridor's freight cost volatility compresses margins for magnetics-heavy converter shipments while amplifying price spreads between captive-fabrication specialists and distributor-dependent assemblers across the SMPS value chain.
Pricing Analysis
Aftermarket service contracts for legacy rack power units now generate lifetime value exceeding original hardware sales. Three-tier pricing structure across premium, standard, and economy levels separates 80 Plus Titanium-certified server supplies from industrial-grade units and consumer adapters. Cost compression in external adapter tiers is intensifying because EU Ecodesign standby mandates force controller redesigns. Consumer electronics OEMs exhibit highest price sensitivity; data center operators absorb premiums for gallium nitride-based density.
Supply Chain Analysis
Tariff exposure between China and the United States dominates strategic sourcing decisions for magnetic component procurement. Taiwan, China, and Japan concentrate wafer supply for wide-bandgap semiconductors; Vietnam and Mexico expand final assembly alternatives. Copper windings, ferrite cores, and silicon carbide substrates constitute critical input dependencies. Single-source vulnerability in Japanese silicon carbide wafer supply threatens industrial drive availability above 10 kW. Distribution runs through direct foundry relationships for hyperscale server OEMs and broad-line industrial distributors for mid-market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise IT asset disposition programs for legacy rack power units expand faster than new hardware procurement, repositioning aftermarket service as the primary margin capture mechanism in mature converter segments.
For Market Incumbents: Pre-empt margin erosion in consumer adapter tiers by accelerating backward integration into gallium nitride wafer supply through TSMC or GlobalFoundries partnerships. Defend data center positioning through captive thermal management expertise that distributor-dependent competitors cannot replicate. Certification investment for India's BIS expansion creates defensive moats against emerging Asian assemblers. For New Entrants and Emerging Players: Mid-wattage LED driver refurbishment in Southeast Asian commercial buildings represents the most penetrable entry point given MEAN WELL's distribution concentration in premium tiers. Automotive 48-volt DC-DC converter subsystems for Chinese tier-two suppliers offer second-mover advantages as European OEMs consolidate preferred vendor lists. Direct procurement relationships with Yangtze River Delta semiconductor packaging clusters enable cost-competitive gallium nitride module assembly. For Investors and Strategic Acquirers: Fabless power semiconductor designers with validated megahertz-class transformer simulation capabilities offer asymmetric upside as topology migration accelerates. Long-term viability hinges on differentiation from commodity converter assembly through intellectual property in magnetic component design. Watch gallium nitride transistor cost curves relative to silicon superjunction MOSFETs as the inflection signal for next-generation topology displacement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Fabrication | Captive gallium nitride wafer supply secures cost leadership in high-density server power stages against distributor-dependent competitors. |
| Certification Expansion for Emerging Markets | India BIS registration for adapters above 20W unlocks replacement demand as local electronics assembly scales. |
| Aftermarket Service Channel Development | Enterprise IT asset disposition programs generate recurring revenue streams from legacy rack power unit refurbishment. |
| Magnetics Design Capability Acquisition | Specialized high-frequency transformer engineering expertise concentrates in Germany and Taiwan, creating scarcity value. |
| Wireless Power Transfer Convergence | Resonant inductive coil integration with conventional SMPS creates unified charging infrastructure for electric vehicle fleets. |
Research Methodology
Cross-validation between primary interviews with power supply design engineers, semiconductor procurement managers, data center infrastructure directors, and aftermarket service heads anchors the qualitative findings. Secondary validation draws from SEC filings of captive-fabrication suppliers, EU Ecodesign Directive implementation reports, hyperscaler capital expenditure disclosures, and customs data for magnetic component trade flows. Bottom-up unit shipment modeling and top-down value chain triangulation reconcile volume estimates across the analysis window.
Calibration against historical efficiency standard adoption curves and wide-bandgap semiconductor price elasticity informs the projection framework. Segmentation dimensions include converter topology, isolation requirement, end-use reliability tier, power density specification, and regional regulatory cluster. CAGRs derive from installed base replacement cycles and electrification intensity coefficients across automotive and data center verticals. Forecast inputs incorporate METI Top Runner efficiency benchmark trajectories and gallium nitride transistor cost curve assumptions.
Practitioners should monitor silicon carbide substrate supply constraints, EU Ecodesign standby tier enforcement timing, and copper-ferrite commodity price swings for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Gan-Powered Chargers Market
Power Systems
Automotive Power Semiconductor Market
Power Systems
Marine Variable Frequency Drives Market
Power Systems
Charge Controller System Market
Power Systems
Global Rugged Power Supply Market
Power Systems
BCD Power IC Market
Power Systems
Middle East and Africa Low Voltage Drives Market
Power Systems
Global Inverter Market
Power Systems
Smart Power Strips Market
Power Systems
Power Integrated Modules Market
Power Systems
Embedded Power Generation Market
Power Systems
Solid-State Relay and Fuse Box Component Platforms Market
Power Systems
Liquid Cooling Systems Market
Power Systems
High Current Power Supply for Electrophoresis Market
Power Systems
Global Fault Current Limiter Market
Power Systems
Organic Fixed Power Capacitors Sales Market