
 Burner Management System (BMS) Market | 2026-2036
Burner Management System (BMS) Market Size, Share, and Industry Trends Forecast 2026-2036
Burner Management System (BMS) Market Outlook
The Middle East is rewriting competitive dynamics for burner management systems as petrochemical complexes in Saudi Arabia and the UAE commission new capacity. Emerson Electric Co. leverages its distributed control architecture to anchor large refinery contracts across the region. Schneider Electric sustains its position through integrated safety instrumented systems that merge BMS with fire and gas detection. Siemens dominates the European retrofit segment with SIL-certified platforms that operators trust for legacy boiler upgrades.
A burner management system is a safety-critical control apparatus that governs burner ignition, flame monitoring, and fuel shutoff through programmable logic controllers, flame scanners, and redundant safety relays operating under IEC 61511 functional safety standards. Its primary purpose is preventing furnace explosions, uncontrolled combustion events, and hazardous energy releases in fired equipment. Integrated systems command the largest installed base because operators prefer unified platforms that consolidate BMS, combustion control, and safety instrumented functions behind single operator interfaces. Cloud-based solutions represent the fastest-expanding technology segment as remote diagnostics reduce unplanned outage costs for utilities managing geographically dispersed power generation assets. Software solutions capture disproportionate margin pools since recurring license revenue from predictive analytics modules outperforms hardware-only business models.
OSHA process safety management rules in the United States mandate systematic burner safety interlocks for facilities handling threshold quantities of flammable materials, directly shaping procurement specifications. The EU F-Gas Regulation and CE marking under the Machinery Directive compel European vendors to certify flame safeguard components for electromagnetic compatibility and environmental compliance. India's BIS standards for industrial electrical equipment add conformity testing requirements that filter market access for imported BMS hardware. Stakeholders must monitor how cybersecurity frameworks for operational technology networks reshape product roadmaps as cloud-connected burner systems expand attack surfaces.
Market Dynamics
Cloud-based diagnostics are compressing maintenance cycles across power generation and petrochemical fleets, forcing vendors to rearchitect software revenue models around recurring analytics subscriptions rather than perpetual hardware sales.
Growth Catalysts
- OSHA Process Safety Management:US refineries face mandatory burner safety interlock upgrades for flammable material handling above threshold quantities, triggering systematic replacement of legacy relay-based systems.
- India's PLI Scheme for Industrial Automation:Domestic manufacturing facility upgrades under production-linked incentives are accelerating BMS procurement for new boiler installations and brownfield retrofits.
- SIL-Certified Platform Convergence:Chemical processors in Germany prioritize integrated safety instrumented systems that merge burner management with fire and gas detection behind unified operator interfaces.
Market Restraints
- Specialized Flame Scanner Supply Concentration:UV and infrared flame detection sensor production clusters in Japan and Germany create vulnerability to semiconductor input shortages and extended lead times.
- IEC 61511 Functional Safety Certification Burden:Third-party validation of programmable logic controller software for SIL 3 applications extends product development timelines by 12-18 months and inflates engineering overhead.
- Mechanical Relay Substitution Threat:Hardwired safety interlock systems retain preference in Russian and Central Asian markets where cybersecurity concerns block cloud-connected architectures, fragmenting technology adoption.
Strategic Opportunities
- Saudi Petrochemical Greenfield Expansion:New capacity commissions in Jubail and Yanbu Industrial Cities create demand for large-scale distributed control architectures with embedded BMS modules.
- Predictive Analytics Module Penetration:Utilities managing geographically dispersed power generation assets seek unplanned outage cost reduction through remote flame stability monitoring and combustion efficiency algorithms.
- EU F-Gas Regulation Tailwind:CE marking requirements for electromagnetic compatibility and environmental compliance favor European vendors with certified flame safeguard component portfolios, creating regulatory moats against unqualified imports.
Industry Challenges
- Functional Safety Engineering Talent Scarcity:SIL certification expertise and IEC 61511 implementation experience concentrate among aging specialist workforces in Germany and the United States, constraining vendor scaling.
- Legacy Boiler Integration Complexity:Retrofit deployments in European industrial facilities require custom engineering to marry modern programmable controllers with 1970s-era mechanical fuel trains and pneumatic actuators.
- Operational Technology Cybersecurity Skill Gap:Cloud-connected burner systems expand attack surfaces, yet process control engineers lack training in network segmentation and zero-trust architecture implementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Burner Management System (BMS) Market |
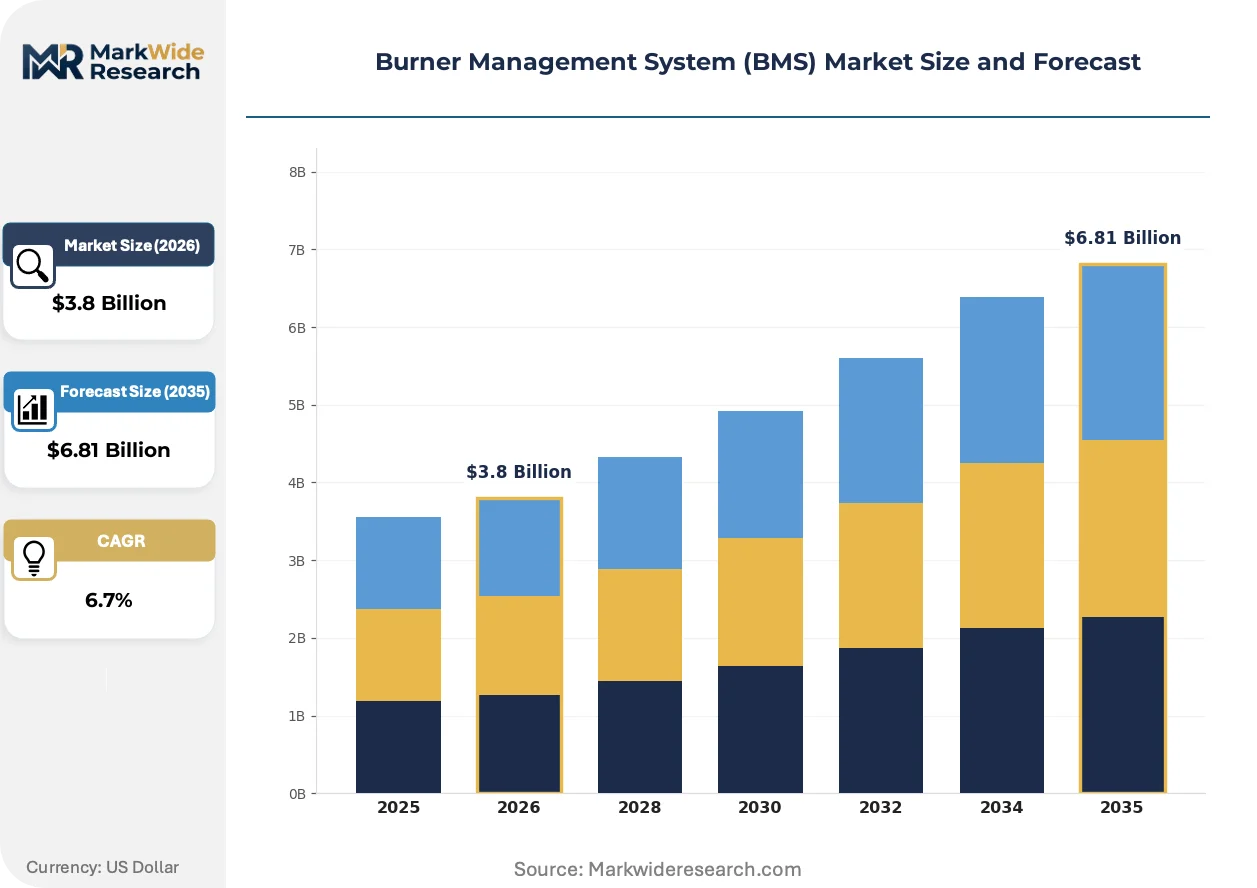
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Systems, Integrated Systems, Software Solutions, Hybrid Systems Technology: Fired Systems, Non-Fired Systems, Advanced Analytics, Cloud-Based Solutions Application: Power Generation, Oil & Gas, Chemical Processing, Aerospace End User: Utilities, Industrial Plants, Manufacturing Facilities, Refineries |
| Companies Covered | Emerson Electric Co., Schneider Electric, ABB, The Cleaver-Brooks Company, Inc, Babcock & Wilcox Enterprises, Inc, GE Vernova, Siemens, Rockwell Automation, Honeywell International Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Burner Management System (BMS) Market Strategic Shifts
Digital twin architectures and edge computing deployments are redefining how combustion safety systems generate value, shifting competitive advantage toward software-centric vendors capable of real-time flame signature analysis.
Edge-deployed machine learning inference engines for flame pattern recognition are rendering obsolete scheduled manual burner tuning protocols that relied on technician visual inspection and handheld combustion analyzers. US independent power producers operating combined-cycle gas turbine facilities are deploying these systems at pilot scale, with full fleet rollout timelines compressing from five-year cycles to eighteen-month implementation windows. The structural consequence is collapsing aftermarket service revenue for traditional field engineering contracts.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon-based fire suppression agents is forcing petrochemical operators to reassess integrated safety system designs that coupled BMS with halon-alternative flooding systems. Industrial consequence includes redesign of fuel shutoff valve sequencing logic to accommodate inert gas injection delays. Facilities in Rotterdam and Antwerp port clusters are most affected, with engineering procurement specifications now mandating fluorine-free suppression compatibility.
After-sales service unbundling is fragmenting traditional vendor-customer relationships as large refinery operators insource burner tuning and flame scanner calibration using third-party specialist contractors. The channel disruption concentrates in the US Gulf Coast, where staffing company technicians directly on-site displaces OEM service agreements. This pattern is most visible among supermajor operators in Texas and Louisiana seeking to compress annual maintenance expenditure through competitive tendering of previously captive service scopes.
Burner Management System (BMS) Market Segmentation
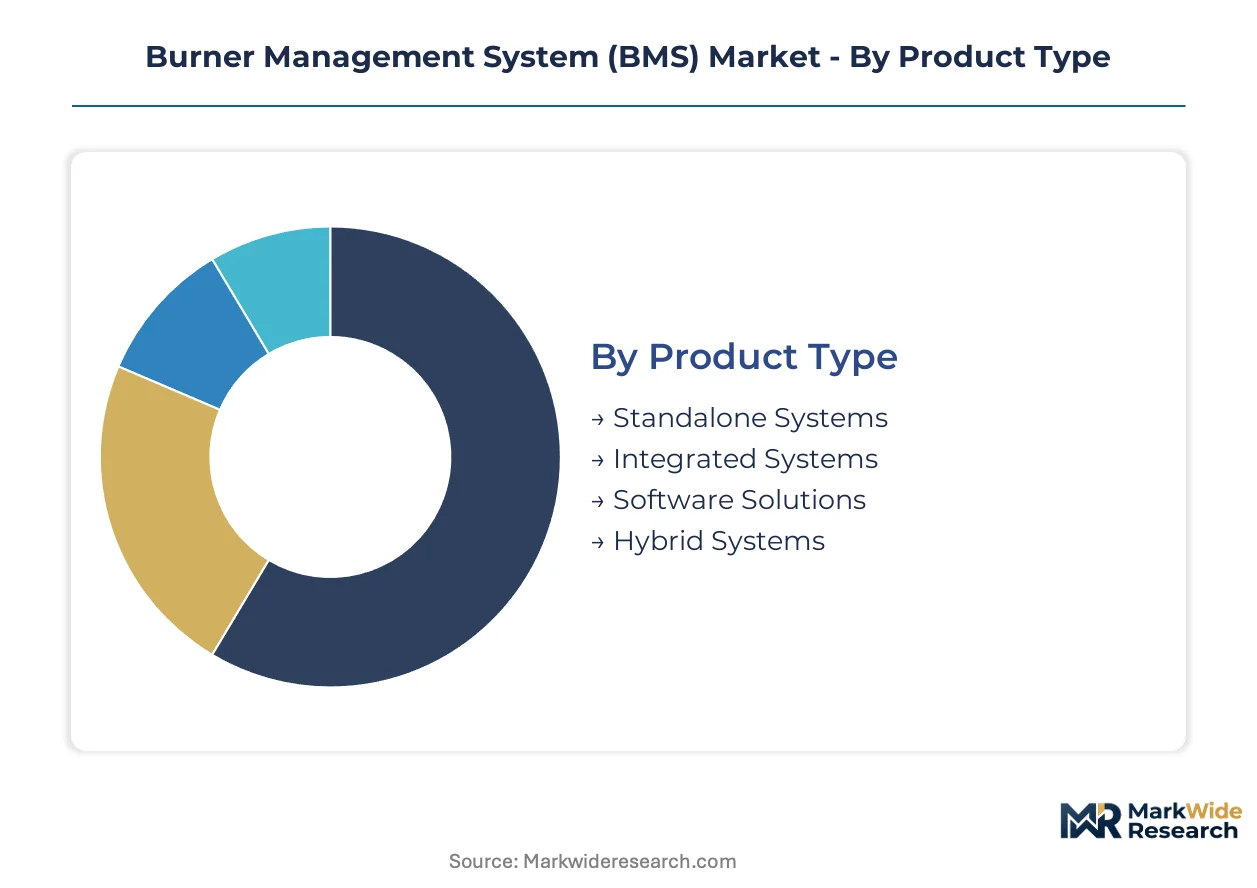
Burner management systems fragment across four critical dimensions that shape procurement cycles, engineering complexity, and vendor competitive positioning. Understanding these segment boundaries clarifies where replacement demand concentrates versus where greenfield expansion drives new installations.
Product Type:
Replacement cycles vary dramatically—from 15-20 year hardware lifecycles for integrated platforms to 3-5 year refresh rates for analytics software subscriptions.
- Integrated Systems:These platforms consolidate burner management, combustion control, and safety instrumented functions behind unified operator interfaces. German chemical processors in Ludwigshafen and Leverkusen prioritize these configurations to compress operator training overhead and reduce panel footprint.
- Software Solutions:Predictive analytics modules and remote diagnostic platforms generate recurring license revenue through cloud-deployed flame stability monitoring. US independent power producers in Texas deploy these fastest to cut unplanned outage costs across dispersed combined-cycle fleets.
- Standalone Systems:Dedicated BMS hardware without combustion control integration retains preference for budget-constrained brownfield retrofits in Eastern European industrial zones.
- Hybrid Systems:Configurations blending local PLC-based safety with cloud analytics connectivity serve mid-size refineries seeking staged modernization paths.
Integrated systems dominate installed base. Software solutions are where expansion concentrates.
Technology:
Cost tiers separate proven hardware architectures from emerging digital layers that command premium pricing through outcome-based contracting.
- Cloud-Based Solutions:Remote diagnostics platforms with edge-deployed machine learning inference engines enable real-time flame pattern recognition. Saudi Aramco's Jubail petrochemical complex pilots these systems to eliminate scheduled manual burner tuning protocols.
- Advanced Analytics:Combustion efficiency algorithms and flame signature databases optimize fuel-air ratios across variable load conditions. Indian power utilities under CEA mandates deploy these fastest to meet stringent emission norms.
- Fired Systems:Conventional flame scanner and fuel shutoff valve architectures certified to IEC 61511 SIL 3 standards anchor refinery safety specifications in the US Gulf Coast.
- Non-Fired Systems:Electric heater and thermal fluid control platforms serve pharmaceutical cleanroom applications in Switzerland's Basel region where combustion risks are prohibited.
Fired systems dominate installed base. Cloud-based solutions are climbing the fastest.
Application:
Volume concentration tracks capital expenditure cycles in energy infrastructure, with project timelines stretching from utility procurement to aerospace qualification.
- Oil & Gas:Upstream production platforms, midstream processing terminals, and downstream refining complexes deploy SIL-certified BMS for wellhead heaters, flare stacks, and process furnaces. Abu Dhabi National Oil Company's Ruwais refinery expansion specifies integrated safety architectures.
- Power Generation:Combined-cycle gas turbine facilities and coal-fired steam plants require flame safeguard systems for duct burners and auxiliary boilers. Independent producers in Pennsylvania's Marcellus shale region upgrade these fastest to capture capacity market revenues.
- Chemical Processing:Ethylene crackers and ammonia synthesis loops demand redundant burner management for reaction furnace integrity. Rotterdam port cluster operators redesign fuel shutoff sequences to accommodate EU F-Gas Regulation compliance.
- Aerospace:Jet engine test cells and thermal vacuum chambers require specialized non-fired thermal control with extreme precision specifications. Toulouse and Hamburg manufacturing sites qualify these systems through multi-year certification protocols.
Oil & gas dominates installed base. Power generation is gaining share fastest.
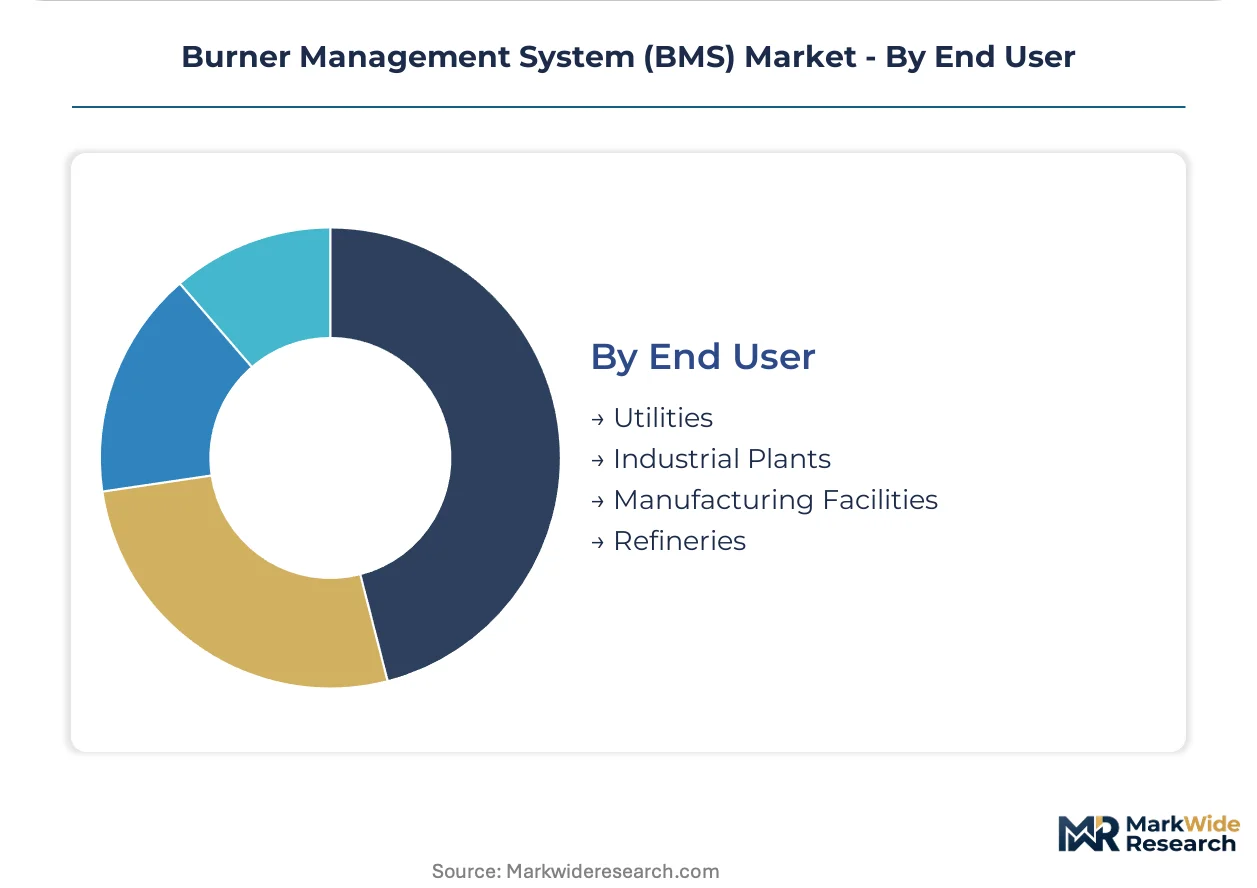
End User:
Customer type determines procurement sophistication—from centralized engineering standards at multinational utilities to fragmented maintenance budgets at discrete manufacturing plants.
- Refineries:Integrated downstream complexes with centralized reliability engineering teams specify distributed control architectures embedding BMS modules. Reliance Industries' Jamnagar facility operates among the world's largest single-site BMS deployments.
- Utilities:Regulated power generation companies with fleet-wide standardization programs prioritize vendor consolidation and long-term service agreements. EDF's French nuclear and thermal fleet exemplifies this procurement discipline.
- Industrial Plants:Petrochemical and specialty chemical operators with site-specific safety studies custom-engineer flame safeguard configurations for unique furnace geometries.
- Manufacturing Facilities:Food processing, pulp and paper, and cement plants with limited in-house combustion expertise rely on OEM service contracts for burner tuning and scanner calibration.
Refineries dominate installed base. Utilities are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA process safety mandates anchor procurement intensity in the United States, while India's PLI scheme and Germany's SIL certification requirements reshape competitive positioning across three continents. Demand concentrates where refinery expansions, power generation upgrades, and chemical processing capacity intersect with stringent functional safety enforcement.
United States
Refinery operators along the Gulf Coast face systematic burner safety interlock upgrades for flammable material handling above OSHA threshold quantities. The EPA and OSHA jointly enforce process safety management rules that trigger replacement of legacy relay-based systems. Houston and Port Arthur industrial clusters host the largest concentration of brownfield BMS retrofits.
Germany
Chemical processors in Ludwigshafen and Leverkusen prioritize integrated safety instrumented systems that merge burner management with fire and gas detection. The EU F-Gas Regulation and CE marking under the Machinery Directive compel electromagnetic compatibility certification for flame safeguard components. Ruhr Valley industrial zones drive retrofit demand for SIL-certified platforms on legacy boiler infrastructure.
India
Domestic manufacturing facility upgrades under the PLI scheme for critical industrial automation accelerate BMS procurement for new boiler installations. The BIS standards for industrial electrical equipment add conformity testing requirements that filter market access for imported hardware. Jamnagar and Gujarat industrial corridors host the fastest-expanding greenfield petrochemical capacity requiring distributed control architectures.
Saudi Arabia
New petrochemical capacity commissions in Jubail and Yanbu Industrial Cities create demand for large-scale distributed control architectures with embedded BMS modules. The SFDA and national industrial safety frameworks mandate systematic flame monitoring for reaction furnace integrity. Riyadh-based engineering procurement specifications increasingly require cloud-compatible safety architectures.
United Arab Emirates
Abu Dhabi National Oil Company's Ruwais refinery expansion specifies integrated safety architectures for wellhead heaters and process furnaces. The MOHAP and federal environmental regulations enforce emission monitoring that ties burner efficiency to operating permits. Dubai industrial zones attract technology pilots for edge-deployed flame pattern recognition systems.
Burner Management System (BMS) Market Competitive Environment
Integrated platform specialists and standalone hardware fabricators split the market along the fault line of operator preference for unified versus modular architectures. Vendor concentration remains moderate, with tier-one electrical conglomerates commanding refinery and utility contracts while regional specialists capture brownfield retrofit scopes. Two archetypes dominate: diversified industrial automation conglomerates with distributed control heritage, and combustion equipment specialists with deep furnace engineering expertise. Competitive intensity centers on strategic partnerships with systems integrators and geographic expansion through local certification compliance.
Among diversified automation conglomerates, Emerson Electric Co., Schneider Electric, and Siemens occupy positions that exemplify contrasting regional strengths. Emerson anchors large refinery contracts through distributed control architecture penetration. Schneider sustains market presence through integrated safety instrumented system positioning. Siemens dominates European retrofit segments with SIL-certified platform credibility. These three represent the archetype of electrical conglomerates leveraging control system heritage into burner safety applications.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Schneider Electric |
| ABB |
| The Cleaver-Brooks Company, Inc |
| Babcock & Wilcox Enterprises, Inc |
| GE Vernova |
| Siemens |
| Rockwell Automation |
| Honeywell International Inc |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Japanese and German UV infrared flame detection sensor production determines both the premium commanded by SIL-certified integrated platforms and the elongated procurement cycles that fragment supply chain architecture. Buyers facing semiconductor input shortages absorb extended lead times through advance contracting, while vendors leverage scarcity to defend margin pools in safety-critical hardware tiers.
Pricing Analysis
North American refinery operators pay 15-25% premiums over Eastern European industrial zones for identical IEC 61511-certified hardware due to OSHA enforcement stringency and localized service bundling. Three-tier pricing structure across premium, standard, and economy levels separates cloud-integrated predictive analytics subscriptions from standalone PLC-based safety systems and relay-based retrofit configurations. Cost compression in the economy tier is intensifying because Indian domestic manufacturers under PLI schemes are flooding brownfield replacement markets with BIS-certified alternatives. Price-sensitive manufacturing facilities in food processing and pulp and paper sectors drive standard-tier volume, while least-sensitive utilities with fleet-wide standardization programs absorb premium-tier SaaS diagnostics.
Supply Chain Analysis
Export-control regimes restricting programmable logic controller firmware with embedded machine learning inference engines limit technology flows from US and German vendors into Russian and Central Asian markets, fragmenting competitive access. Component manufacturing concentrates in Japan for flame scanner optics, Germany for SIL-certified safety relays, and China for non-certified pneumatic actuators. Raw material dependencies span semiconductor wafers for sensor arrays, specialty alloys for high-temperature valve components, and rare-earth elements for optical coatings. Single-source vulnerability in Japanese UV sensor production creates systemic exposure to seismic disruption and trade policy shifts. Distribution runs through systems integrators with IEC 61511 implementation credentials, who capture 30-40% of end-customer value through engineering procurement construction bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The burner management system market sits in a cyclical recovery phase driven by refinery capacity expansion across the US Gulf Coast and Middle East, where OSHA and SFDA mandates are triggering systematic replacement of pre-2000 relay-based safety architectures.
For Market Incumbents: Insulate margin pools by deepening captive supply of flame scanner sensor arrays through backward integration into Japanese optical component partnerships, while accelerating cloud-native platform certification to outpace emerging software-only entrants threatening hardware attachment rates. The substitution threat from standalone analytics vendors demands defensive bundling of predictive modules with base safety system sales. For New Entrants and Emerging Players: Build out white-space penetration in Indian domestic manufacturing corridors where PLI scheme incentives are compressing import dependency and creating procurement preference for locally certified BMS hardware. The most penetrable segment lies in mid-size chemical processing facilities seeking hybrid modernization paths. A go-to-market angle through state-level industrial development authorities unlocks faster qualification than direct OEM competition. For Investors and Strategic Acquirers: The market sits at a mid-cycle expansion phase that favors acquisition of specialized systems integrators with IEC 61511 implementation credentials and established refinery operator relationships. Long-term viability over the next decade hinges on software revenue mix and recurring analytics attachment rates. The signal to watch is cloud-connected burner system penetration in utility fleets, which indicates tipping point timing for platform consolidation plays.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Captive supply of Japanese UV flame detection components insulates against semiconductor shortage volatility. |
| Cloud-Native Platform Certification | IEC 62443 cybersecurity compliance for cloud-connected architectures unlocks utility fleet procurement. |
| Systems Integrator Acquisition | IEC 61511-certified implementation expertise concentrates in aging German and US specialist workforces. |
| Predictive Analytics Module Development | Remote flame stability monitoring commands recurring SaaS revenue from Texas independent power producers. |
| Indian PLI Scheme Localization | BIS certification for domestically manufactured hardware filters import competition in Jamnagar industrial corridors. |
Study Parameters
Operator-level perspectives from refinery reliability engineers, power generation fleet managers, chemical processing safety directors, and systems integrators with IEC 61511 certification anchored the qualitative base. Primary interviews combined with secondary validation across OSHA enforcement databases, EPA process safety incident reports, EU F-Gas Regulation implementation filings, and Indian BIS conformity assessment records. Bottom-up unit economics from individual BMS deployments triangulated against top-down capital expenditure tracking across petrochemical and utility sectors.
Scenario-bracketing around regulatory enforcement intensity, semiconductor supply recovery trajectories, and cloud adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture tier, technology deployment mode, application vertical, and end-user procurement sophistication. CAGRs derived from replacement cycle analysis, greenfield capacity commissioning schedules, and software subscription renewal rates. Industry-specific forecast inputs incorporated SIL certification backlog durations and flame scanner sensor lead time volatility.
Stress conditions across OSHA inspection frequency escalation, Japanese seismic disruption probability, and Indian PLI scheme subsidy renewal were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory continuity and supply chain normalization. Material shifts in IEC 61511 certification timeline requirements or export control expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Embedded Power Generation Market
Power Systems
High Voltage Direct Current Power Supply Market
Power Systems
Global Excitation Systems Market
Power Systems
Power Supply Isolation Equipment Market
Power Systems
Global DC Power Supply Module Market
Power Systems
Insulated Gate Bipolar Transistor (IGBT) Market
Power Systems
Low Voltage AC Drive Market
Power Systems
Electric Vehicle Power Inverter Market
Power Systems
Traction Inverter Market
Power Systems
Hybrid Inverters Market
Power Systems
Global Inverter Market
Power Systems
North America Telecom Power Systems Market
Power Systems
AC Voltage Transducer Market
Power Systems
Liquid Cooling Systems Market
Power Systems
BCD Power IC Market
Power Systems
Integrated UPS Market