
 Asia-Pacific Electric Vehicle Power Inverter Market | 2026-2036
Asia-Pacific Electric Vehicle Power Inverter Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Electric Vehicle Power Inverter Market Analytics
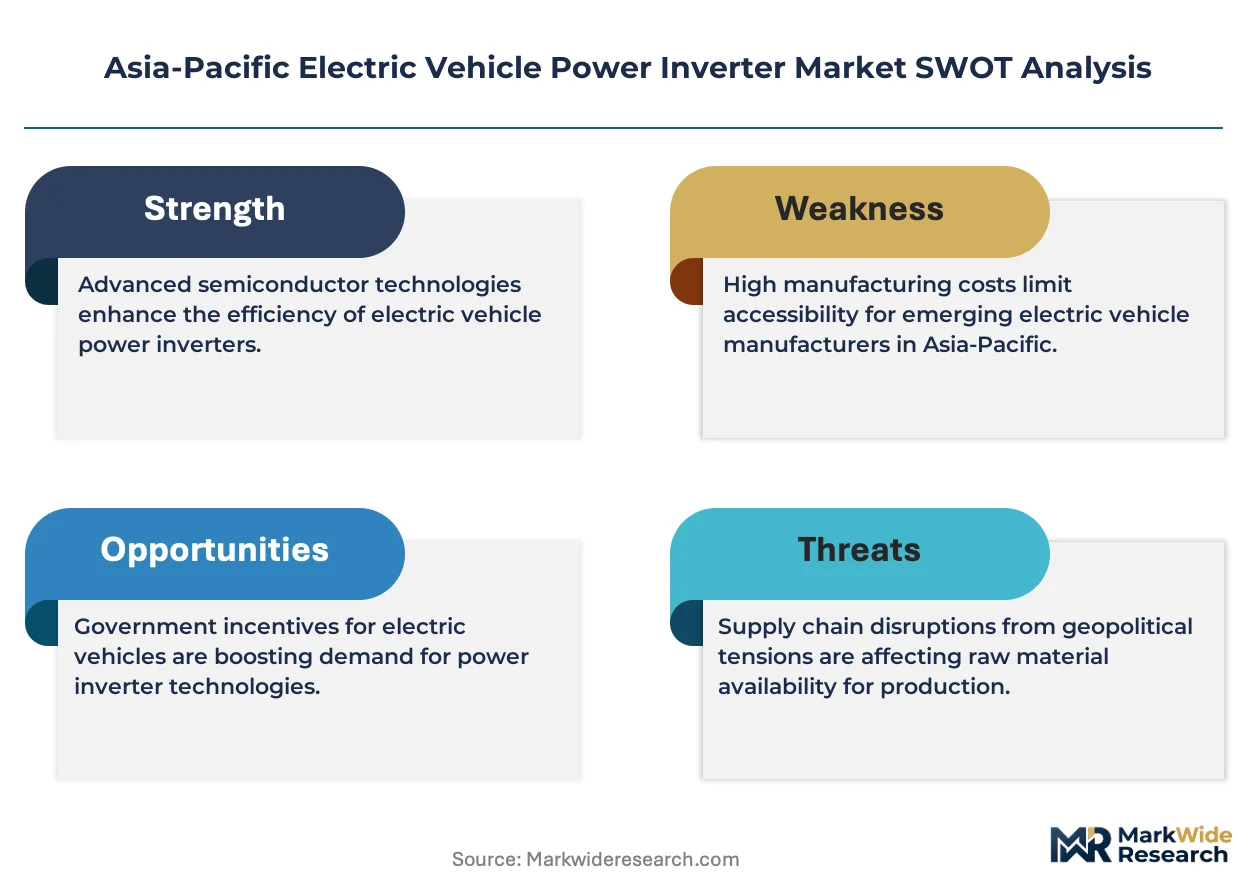
A capital-intensity divergence between silicon carbide foundry investments and legacy IGBT packaging lines is redrawing supplier tier structures in the Asia-Pacific Electric Vehicle Power Inverter Market. Mitsubishi Electric Corporation leverages captive wafer supply to sustain margin structures against commodity pressure. Denso Corporation anchors its position through integrated module-to-thermal-management architectures. BorgWarner Inc competes via high-volume manufacturing scale across Chinese joint-venture plants.
Asia-Pacific electric vehicle power inverters convert DC battery output into variable-frequency AC for traction motors, typically operating at switching frequencies above 10 kHz using silicon carbide or IGBT semiconductor bridges to minimize thermal losses during high-torque acceleration cycles. Conventional technology still occupies the majority unit volume in cost-sensitive two-wheeler and entry passenger segments, though bi-directional architectures for vehicle-to-grid integration are capturing the fastest-growing margin pools among charging station and fleet operator deployments. Medium power ratings dominate current OEM procurement specifications, while ultra high power systems for electric bus and heavy commercial platforms represent the concentration of forward engineering investment.
China's MIIT enforces GB standards for electromagnetic compatibility and efficiency testing that gate market access for imported inverter modules, while Japan's METI coordinates JIS certification pathways that shape product development timelines for Korean and Taiwanese suppliers. India's BIS adoption of harmonized test protocols under the PLI scheme is redirecting component sourcing toward domestic assembly joint ventures. Stakeholders must monitor how ASEAN national regulators align with Chinese versus Japanese technical standards before committing regional capacity expansion.
Market Dynamics
Silicon carbide foundry capacity concentration in Taiwan and South Korea is redrawing procurement hierarchies across the Asia-Pacific Electric Vehicle Power Inverter Market, as captive wafer supply becomes the primary determinant of margin sustainability against commodity IGBT pricing pressure.
Growth Catalysts
- MIIT GB Standards:China's electromagnetic compatibility and efficiency testing mandates are gating market access for imported inverter modules, forcing localization investments that deepen regional supply chain density.
- Municipal Bus Fleet Electrification:Mass transit procurement volumes across Chinese and Southeast Asian cities are accelerating demand for medium and ultra-high power inverter systems with bidirectional vehicle-to-grid architectures.
- Silicon Carbide Semiconductors:The material's superior thermal efficiency above 10 kHz switching frequencies is compressing thermal management footprints and enabling higher torque density in passenger EV platforms.
Market Restraints
- Wafer Supply Concentration:Taiwan Semiconductor Manufacturing and domestic Chinese foundries control over 80% of substrate supply, creating single-source vulnerability for Korean and Japanese module assemblers.
- Platinum Group Metal Volatility:Indium and gallium price swings in rare earth markets are destabilizing cost structures for wide-bandgap semiconductor packaging lines.
- JIS Certification Timelines:Japan's METI coordination of standards approval creates 12-18 month product development delays that disadvantage smaller Korean and Taiwanese suppliers.
Strategic Opportunities
- India's PLI Scheme:BIS harmonized test protocol adoption is redirecting component sourcing toward domestic assembly joint ventures in Tamil Nadu and Gujarat manufacturing corridors.
- Vehicle-to-Grid Integration:Bidirectional inverter architectures for charging station and fleet operator deployments are capturing the fastest-growing margin pools in commercial and utility-scale storage applications.
- ASEAN Regulatory Alignment:Thailand, Indonesia, and Vietnam are drafting national EV standards that will favor early movers with pre-certified Chinese or Japanese technical platforms.
Industry Challenges
- Power Electronics Talent Scarcity:The shortage of engineers proficient in wide-bandgap semiconductor design and thermal-mechanical integration is constraining R&D throughput across Korean and Taiwanese suppliers.
- Multi-Standard Certification Burden:Divergent GB, JIS, and emerging ASEAN test protocols are forcing parallel validation tracks that extend time-to-revenue by 6-9 months for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Electric Vehicle Power Inverter Market |
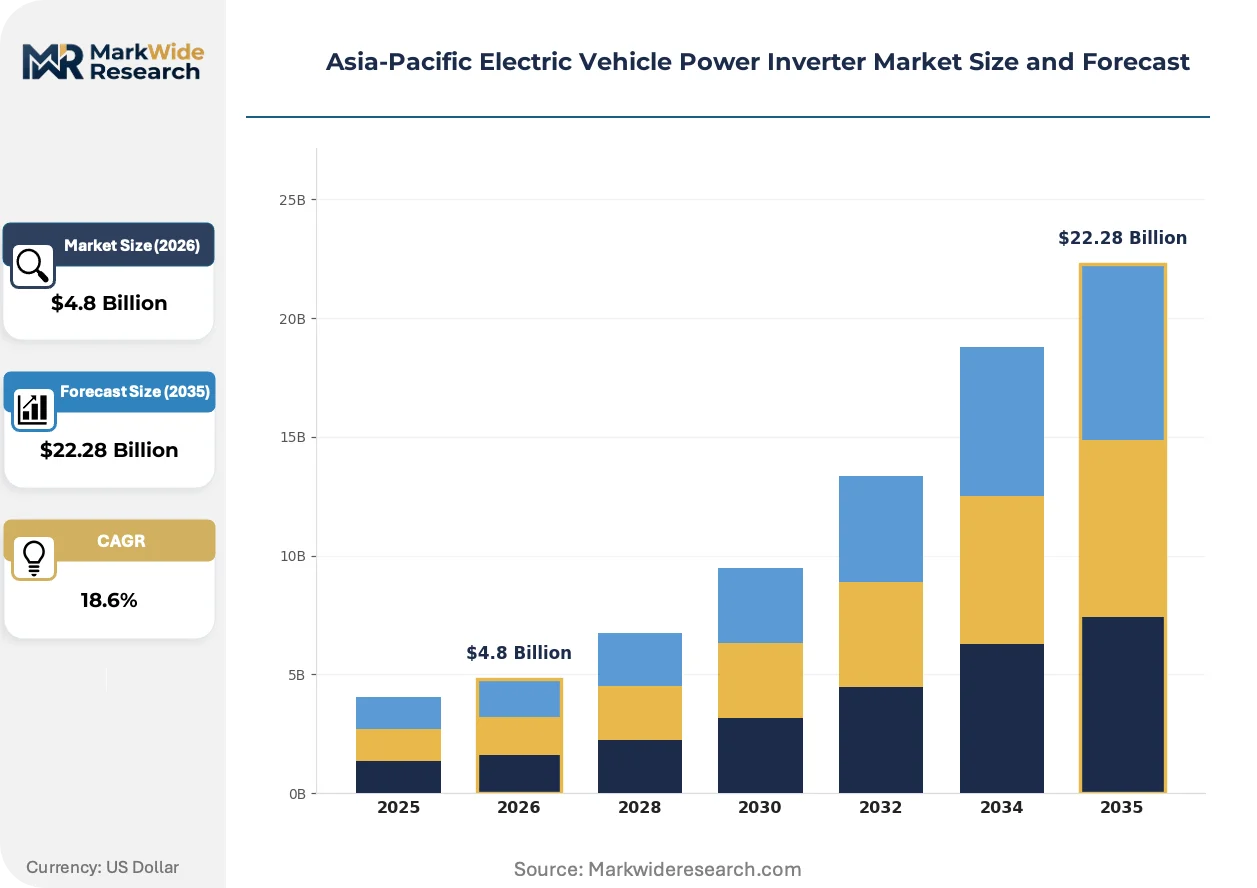
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Conventional, Bi-directional, Modular, Integrated Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Charging Stations Power Rating: Low Power, Medium Power, High Power, Ultra High Power End User: OEMs, Tier-1 Suppliers, Fleet Operators, Aftermarket Providers |
| Companies Covered | Robert Bosch GmbH, Siemens AG, Denso Corporation, Valeo SA, Aptiv PLC, Mitsubishi Electric Corporation, Continental AG, BorgWarner Inc, Toyota Industries Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Electric Vehicle Power Inverter Market Evolving Landscape
Power semiconductor architecture is fragmenting into competing material platforms while regulatory pressure on efficiency and electromagnetic compatibility tightens certification requirements across the Asia-Pacific Electric Vehicle Power Inverter Market.
Silicon carbide MOSFET technology converts DC battery output into variable-frequency AC for traction motors with switching losses below 50% of equivalent IGBT systems. Bus and heavy commercial OEMs in China and South Korea are adopting SiC traction inverters at twice the pace of passenger vehicle platforms. The technology is decomposing traditional thermal management supply chains by integrating cooling functions directly into power module substrates.
METI efficiency mandates and China's dual carbon goals are tightening semiconductor-grade standards that gate market access. Japanese certification pathways now require third-party validation of switching frequency stability under thermal cycling stress. Korean suppliers targeting both markets must maintain dual validation laboratories, compressing R&D efficiency and favoring larger competitors with captive testing infrastructure.
Fleet operators and charging station deployers are consolidating procurement around integrated module-to-thermal-management architectures rather than discrete component sourcing. This specification shift favors suppliers with in-house packaging and cooling system design capabilities. The pattern is most visible in South Korea's battery manufacturing corridor around Gwangju and Ulsan, where vertical integration between cell, module, and inverter production is becoming a standard procurement prerequisite.
Asia-Pacific Electric Vehicle Power Inverter Market Segmentation
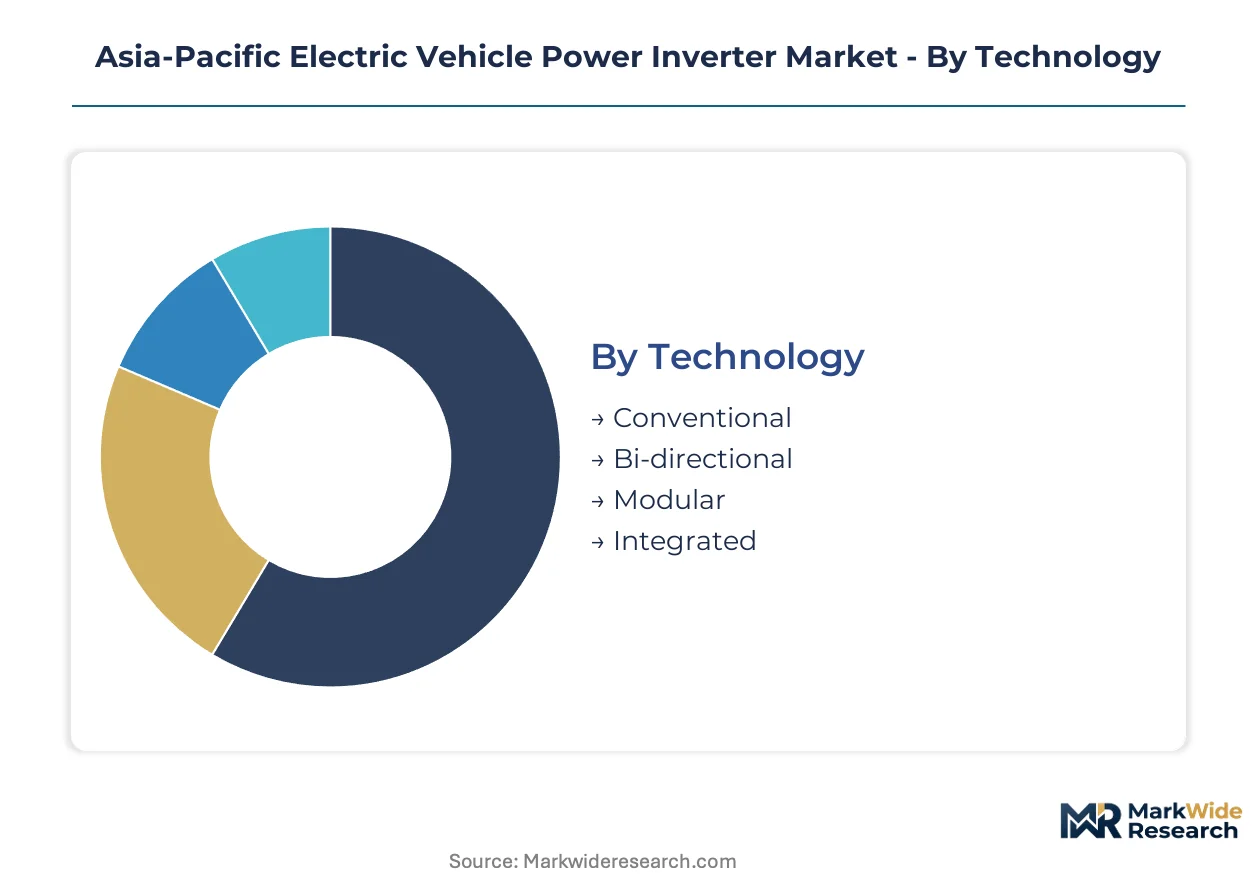
Technology, application, and power rating configurations determine procurement channel selection across the Asia-Pacific Electric Vehicle Power Inverter Market. OEMs and Tier-1 suppliers source through distinct qualification pathways, while fleet operators and aftermarket providers concentrate demand in specific technology tiers.
Technology:
Channel distribution varies sharply by technology maturity, with established platforms flowing through volume manufacturing partnerships and emerging architectures requiring direct technical collaboration.
- Conventional:Silicon IGBT-based architectures dominate procurement volumes through Chinese and Southeast Asian joint-venture assembly plants. Cost-sensitive two-wheeler and entry passenger segments in Indonesia and Vietnam source almost exclusively through this channel, with pricing pressure compressing margins for non-captive suppliers.
- Bi-directional:Vehicle-to-grid capable designs integrate DC-AC inversion with grid-synchronization controllers, capturing premium procurement from South Korean fleet operators and Japanese charging station deployers. METI efficiency mandates and China's dual carbon goals are accelerating certification requirements for this segment.
- Modular:Scalable power stages enable configuration flexibility across multiple vehicle platforms. Tier-1 suppliers in Taiwan and South Korea favor this architecture for reduced inventory complexity.
- Integrated:Combined power module and thermal management subsystems streamline OEM assembly lines. Japanese and Korean battery manufacturing corridors around Gwangju and Ulsan show strongest procurement concentration.
By volume, Conventional leads. By growth pace, Bi-directional is climbing the fastest.
Application:
End-use differentiation creates distinct margin structures, with commercial and infrastructure applications commanding premium pricing over mass-market passenger platforms.
- Passenger Vehicles:Medium power ratings dominate OEM specifications across Chinese domestic brands and Japanese premium manufacturers. MIIT GB standards for electromagnetic compatibility gate market access, forcing localization investments.
- Commercial Vehicles:Electric bus and heavy truck platforms drive ultra high power demand. Municipal procurement across Chinese cities and Bangkok's BRT electrification program specify bidirectional architectures with vehicle-to-grid capability.
- Two-Wheelers:Cost-optimized conventional inverters serve Southeast Asian last-mile delivery fleets. India's PLI scheme is redirecting component sourcing toward Tamil Nadu and Gujarat assembly joint ventures.
- Charging Stations:Grid-tied power conversion modules require harmonized certification across multiple national standards. Korean and Taiwanese suppliers face 12-18 month JIS approval timelines for Japanese market entry.
Passenger Vehicles generates the largest revenue base. Commercial Vehicles shows the steepest expansion trajectory.
Power Rating:
Manufacturing scale and semiconductor substrate requirements concentrate supply at opposite ends of the power spectrum.
- Low Power:Compact designs for two-wheeler and micro-mobility applications. High volume, commoditized pricing characterizes procurement from Vietnamese and Indonesian assemblers.
- Medium Power:Dominant rating for current passenger EV platforms across China, Japan, and South Korea. Silicon carbide MOSFET adoption is compressing thermal management footprints in this tier.
- High Power:Light commercial and premium passenger configurations. Taiwan Semiconductor Manufacturing and domestic Chinese foundries control substrate supply, creating sourcing vulnerability.
- Ultra High Power:Electric bus and heavy commercial systems represent the concentration of forward engineering investment. Municipal fleet electrification across Asia-Pacific cities accelerates procurement timelines.
Medium Power anchors current production volumes. Ultra High Power is gaining share fastest among ratings.
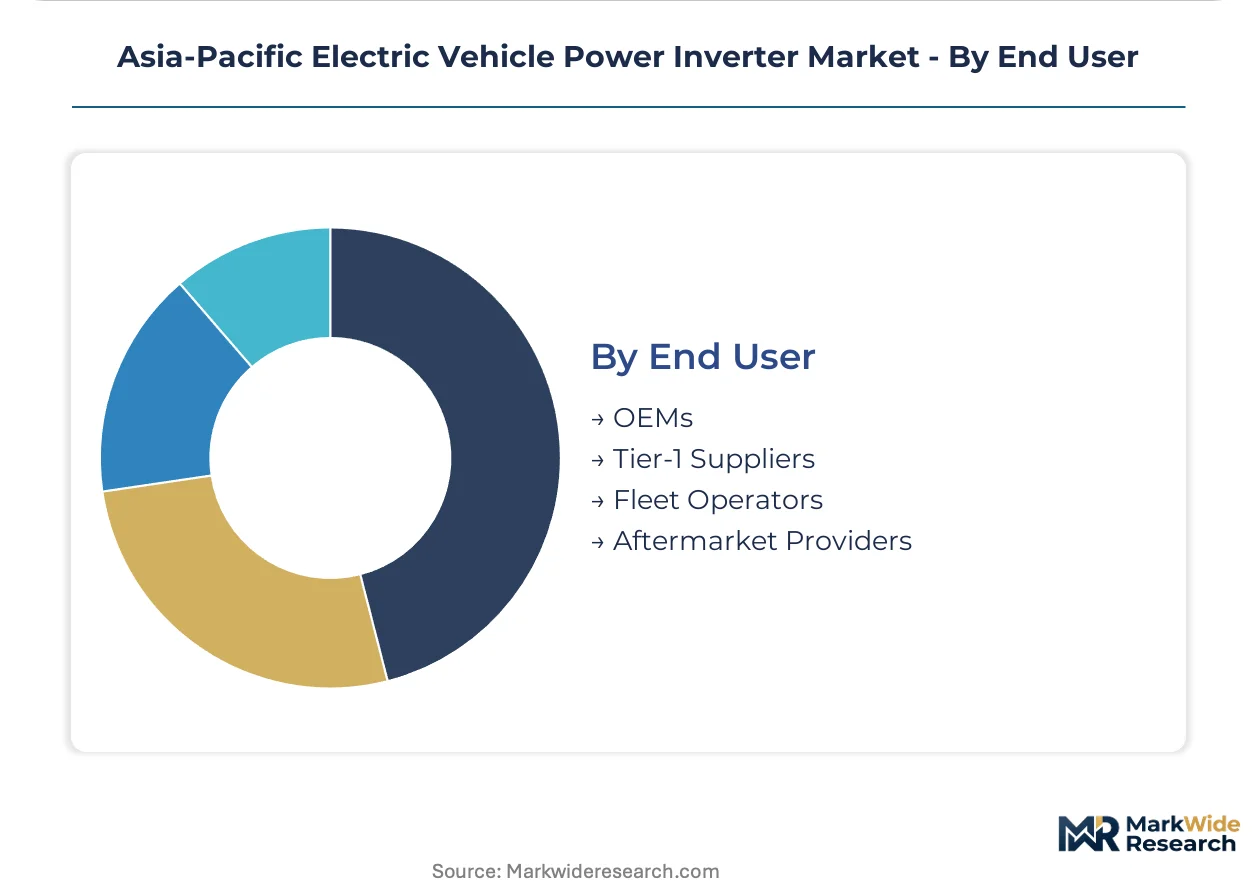
End User:
Customer type determines technical specification authority and supplier relationship intensity.
- OEMs:Direct procurement with full design authority. Chinese, Japanese, and Korean vehicle manufacturers specify integrated module-to-thermal-management architectures.
- Tier-1 Suppliers:Intermediate assembly role with module packaging expertise. South Korea's battery manufacturing corridor demands vertical integration between cell, module, and inverter production.
- Fleet Operators:Consolidated procurement around total cost of ownership metrics. Bidirectional vehicle-to-grid capability increasingly gates supplier selection.
- Aftermarket Providers:Replacement and retrofit demand concentrated in conventional technology tiers. India's BIS harmonized test protocols shape component eligibility.
OEMs command the largest procurement scale. Fleet Operators are expanding most quickly as a customer category.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in South Korea and Japan while Chinese suppliers compete on manufacturing scale. Taiwan's silicon carbide foundries command premium substrate margins. Regulatory divergence between MIIT GB standards and METI JIS certification creates distinct market access pathways.
China
Municipal bus fleet electrification drives procurement volumes across Beijing, Shenzhen, and Shanghai. MIIT enforces GB standards for electromagnetic compatibility and efficiency testing that gate market access for imported inverter modules. The Yangtze River Delta hosts dense concentrations of joint-venture assembly plants serving domestic EV brands.
Japan
Premium passenger vehicle manufacturers specify integrated module-to-thermal-management architectures with stringent performance requirements. METI coordinates JIS certification pathways that shape product development timelines for Korean and Taiwanese suppliers. The Kansai region around Osaka maintains specialized testing infrastructure for wide-bandgap semiconductor validation.
South Korea
Battery manufacturing corridors around Gwangju and Ulsan demand vertical integration between cell, module, and inverter production. Fleet operators consolidate procurement around bidirectional vehicle-to-grid capable systems. Domestic module assemblers face substrate supply vulnerability from Taiwan Semiconductor Manufacturing concentration.
India
Two-wheeler electrification and last-mile delivery fleets absorb cost-optimized conventional inverter volumes. BIS adoption of harmonized test protocols under the PLI scheme redirects component sourcing toward Tamil Nadu and Gujarat assembly joint ventures. State-level EV policies in Maharashtra and Karnataka accelerate local manufacturing commitments.
Thailand
Japanese automaker joint ventures anchor passenger vehicle inverter demand for export-oriented production. National EV standards under development favor early movers with pre-certified technical platforms. The Eastern Economic Corridor attracts module packaging investments serving ASEAN regional distribution.
Asia-Pacific Electric Vehicle Power Inverter Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific Electric Vehicle Power Inverter Market. Captive semiconductor foundry operators sustain margin structures against commodity IGBT pricing pressure, while high-volume manufacturers compete through Chinese joint-venture scale. The market structure fragments across three strategic archetypes: integrated module-to-thermal-management specialists, silicon carbide substrate controllers, and high-volume packaging operators. Dominant competitive moves include backward integration into wafer supply and strategic partnerships for JIS/GB dual certification.
Among diversified industrial conglomerates, Robert Bosch GmbH and Siemens AG exemplify archetypes with captive supply chain depth and systems integration capabilities. Denso Corporation and Mitsubishi Electric Corporation occupy positions within the Asia-Pacific supplier tier, representing Japanese manufacturers with established certification pathways and regional production footprints. BorgWarner Inc sits within the scale-driven competitive vector, reflecting North American-owned manufacturing presence across Chinese joint-venture facilities.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Siemens AG |
| Denso Corporation |
| Valeo SA |
| Aptiv PLC |
| Mitsubishi Electric Corporation |
| Continental AG |
| BorgWarner Inc |
| Toyota Industries Corporation |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between South Korean module assemblers and Taiwanese silicon carbide foundries lock in substrate supply and price visibility across the Asia-Pacific Electric Vehicle Power Inverter Market. These arrangements insulate Tier-1 suppliers from spot-market volatility in rare earth metals while committing buyers to minimum volume thresholds that shape inventory strategy.
Pricing Analysis
Configured-to-order pricing for integrated module-to-thermal-management systems commands substantial premiums over standard IGBT module quotations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with JIS-validated Japanese platforms pricing above GB-certified Chinese equivalents. Cost compression in conventional silicon IGBT tiers intensifies as Vietnamese and Indonesian assemblers consolidate procurement volumes. Two-wheeler OEMs in Southeast Asia exhibit highest price sensitivity, while South Korean fleet operators prioritize total cost of ownership metrics over unit pricing.
Supply Chain Analysis
Strategic stockpile preferences dominate among Japanese and Korean module assemblers buffering against Taiwan Semiconductor Manufacturing concentration, while Chinese joint-venture plants operate on leaner just-in-time inventories. Silicon carbide substrate supply draws from Taiwan, South Korea, and domestic Chinese foundries. Indium, gallium, and platinum group metals feed from concentrated rare earth processing corridors. Single-source vulnerability in wafer supply creates structural risk for Korean suppliers dependent on TSMC allocation. Distribution runs through battery manufacturing corridors around Gwangju and Ulsan into OEM final assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific Electric Vehicle Power Inverter Market sits in a cyclical recovery phase driven by municipal bus fleet electrification procurement waves across Chinese and Southeast Asian cities.
For Market Incumbents: Secure captive wafer supply through equity partnerships with Taiwanese or domestic Chinese foundries before allocation tightening accelerates. Deepen JIS and GB dual certification infrastructure to compress 12-18 month approval timelines that currently disadvantage smaller competitors. Threat from commodity IGBT pricing pressure demands backward integration into silicon carbide substrate production as a margin defense lever. For New Entrants and Emerging Players: Lead with bidirectional vehicle-to-grid architectures targeting South Korean fleet operators and Japanese charging station deployers where specification gaps remain. India's PLI scheme redirects component sourcing toward Tamil Nadu and Gujarat assembly joint ventures, creating the most penetrable geography for new manufacturing footprint. Go-to-market angle should emphasize integrated module-to-thermal-management designs that reduce OEM assembly complexity. For Investors and Strategic Acquirers: Silicon carbide packaging specialists with captive thermal management design capabilities represent the highest-conviction acquisition archetype for this market. Long-term viability hinges on sustained OEM consolidation around integrated architectures rather than discrete component sourcing. Watch for ASEAN regulatory alignment announcements with Chinese versus Japanese technical standards as the inflection indicator for regional capacity expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Foundry Partnership | Captive wafer supply from TSMC or domestic Chinese foundries secures margin structures against commodity IGBT pricing pressure. |
| Dual Certification Infrastructure Investment | Parallel JIS and GB validation laboratories compress approval timelines for Korean suppliers targeting both Japanese and Chinese markets. |
| Integrated Thermal Management Acquisition | In-house cooling system design capabilities meet South Korean battery corridor procurement prerequisites around Gwangju and Ulsan. |
| India PLI Manufacturing Joint Venture | Tamil Nadu and Gujarat assembly partnerships redirect component sourcing under BIS harmonized test protocols. |
| Vehicle-to-Grid Architecture Development | Bidirectional inverter designs capture premium procurement from South Korean fleet operators consolidating around total cost of ownership metrics. |
Research Methodology
A spread of perspectives from OEM platform engineers, Tier-1 supplier procurement leads, silicon carbide foundry operations managers, thermal management subsystem designers, and municipal fleet procurement officers converged on the working assumptions. Primary interview insights combined with secondary validation from MIIT GB standard filings, METI JIS certification registries, vehicle production databases, and customs trade data. Bottom-up and top-down triangulation anchored volume and value estimates.
Segmentation dimensions modeled span technology tier, application category, power rating band, and end-user type across the projection horizon. Analytical framework derived CAGRs from semiconductor substrate supply trajectories, OEM platform electrification roadmaps, and regulatory mandate implementation schedules. Forecast inputs incorporated silicon carbide MOSFET adoption curves and municipal bus fleet procurement pipelines.
The analysis sits within stated boundaries; outcomes outside sustained MIIT enforcement of GB standards and METI coordination of JIS pathways would require recalibration. Forecasts reflect assumptions on rare earth metal price stability and Taiwan foundry allocation continuity. Revision becomes warranted when ASEAN regulatory alignment crosses thresholds favoring one technical standard bloc over another.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
String Inverter Market
Power Systems
Global Rectifier Market
Power Systems
EV Power Module Market
Power Systems
Embedded Power Generation Market
Power Systems
Vacuum Pressure Impregnated (VPI) Transformer Market
Power Systems
Ultrafast Rectifiers Market
Power Systems
Germany Rechargeable Battery Market
Power Systems
Switch Mode Power Supply (SMPS) Market
Power Systems
Power Electronics Equipment Cooling System Market
Power Systems
Power Supply Isolation Equipment Market
Power Systems
Laptop Battery Market
Power Systems
Silicon-Controlled Rectifier (SCR) Market
Power Systems
Integrated UPS Market
Power Systems
Low Voltage AC Drive Market
Power Systems
Liquid Cooling Systems Market
Power Systems
Global Plasma Generators Market