
 Noise Suppression Components Market | 2026-2036
Noise Suppression Components Market Size, Share, and Industry Trends Forecast 2026-2036
Noise Suppression Components Market Foresight
Surface-mount miniaturization is rewriting how noise suppression components integrate into densely packed circuit boards. TDK Corporation leverages its ferrite material science leadership to anchor high-frequency filter portfolios across automotive and consumer electronics. Murata Manufacturing Co., Ltd. sustains manufacturing scale through vertically integrated ceramic capacitor and EMI filter production in Japan. Vishay Intertechnology, Inc. competes on thick-film and thin-film resistor-capacitor networks that absorb broadband noise in industrial power systems.
Noise suppression components encompass passive and active devices engineered to attenuate electromagnetic interference, acoustic vibration, or thermal-mechanical noise across specified frequency bands, typically operating from kilohertz to gigahertz ranges with insertion loss thresholds calibrated to IEC 60939 or MIL-STD-461 parameters. Their primary purpose is to ensure signal integrity, regulatory compliance, and human safety in electromechanical systems where spurious energy would otherwise degrade performance or violate emission limits. Passive filters currently dominate value capture in automotive electrification architectures, while acoustic panels and sound barriers represent the fastest-expanding material segment as construction codes tighten airborne noise isolation requirements. Foam-based absorption materials command margin pools in aerospace and precision manufacturing cleanrooms where outgassing specifications restrict supplier qualification.
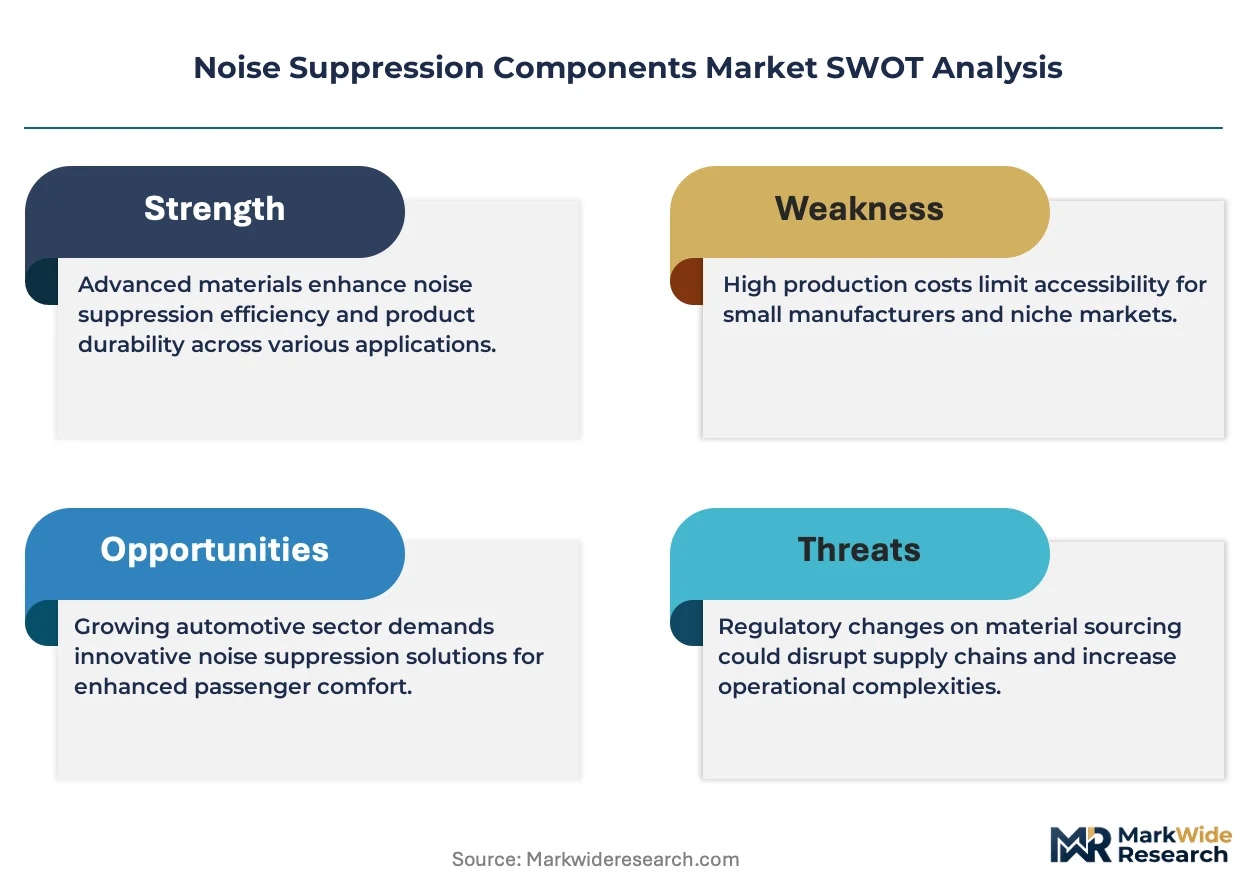
The EU F-Gas Regulation and REACH framework restrict fluorinated gas content and hazardous substance thresholds in acoustic foams sold across Europe, compelling reformulation of open-cell polyurethane and melamine products. The EPA and FCC in the United States enforce complementary emission limits through Title 47 CFR Part 15 and ambient noise standards that shape product certification roadmaps for cross-border suppliers. Stakeholders must monitor evolving material compliance deadlines and pre-qualify alternative chemistries before existing formulations lose market access.
Market Dynamics
Automotive electrification is compressing design cycles for electromagnetic interference mitigation as 800V architectures and silicon carbide inverters generate higher-frequency noise signatures requiring multi-stage filter topologies.
Growth Catalysts
- EU F-Gas Regulation:Tightening restrictions on fluorinated gas content in acoustic foams are accelerating reformulation investments, opening qualification windows for compliant material suppliers across European industrial corridors.
- Electric vehicle powertrain electrification:Battery management systems and onboard chargers require ferrite-based common-mode chokes operating above 10 MHz, pulling specialized filter architectures into high-volume automotive supply chains.
- Stuttgart-Munich industrial cluster concentration:Germany's precision manufacturing and aerospace engineering density sustains premium demand for low-outgassing melamine foams in cleanroom environments.
Market Restraints
- Raw material concentration in rare-earth ferrite supply:Neodymium and dysprosium processing dependence on Chinese refining capacity exposes filter manufacturers to price volatility and export control risks.
- REACH substance restriction complexity:ECHA's evolving candidate list for Substances of Very High Concern forces iterative reformulation of polyurethane foam catalysts and flame retardants, extending R&D timelines.
- Acoustic panel substitution by active noise cancellation:Software-defined cancellation algorithms in automotive cabins and consumer electronics threaten passive absorption material volumes in mid-tier applications.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Contract assembly incentives for smartphones and laptops are creating localized EMI filter demand requiring domestic qualification of ferrite and ceramic component suppliers.
- Convergence of thermal management and noise suppression:Phase-change materials and graphene composites that simultaneously damp vibration and conduct heat open dual-function product categories in data center and power electronics cooling.
- Japan's METI carbon neutrality roadmap:Green procurement mandates for public infrastructure projects are prioritizing bio-based acoustic materials, advantaging early movers in cellulose and lignin foam development.
Industry Challenges
- Multi-physics simulation talent scarcity:Electromagnetic-acoustic-thermal co-design requires engineers fluent in COMSOL and Ansys multiphysics suites, a skill set concentrated in aerospace and automotive OEMs rather than component suppliers.
- IEC 60939-3 certification timeline compression:Filter manufacturers face 18-24 month qualification cycles for automotive safety-critical applications, misaligned with 12-month vehicle platform development schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Noise Suppression Components Market |
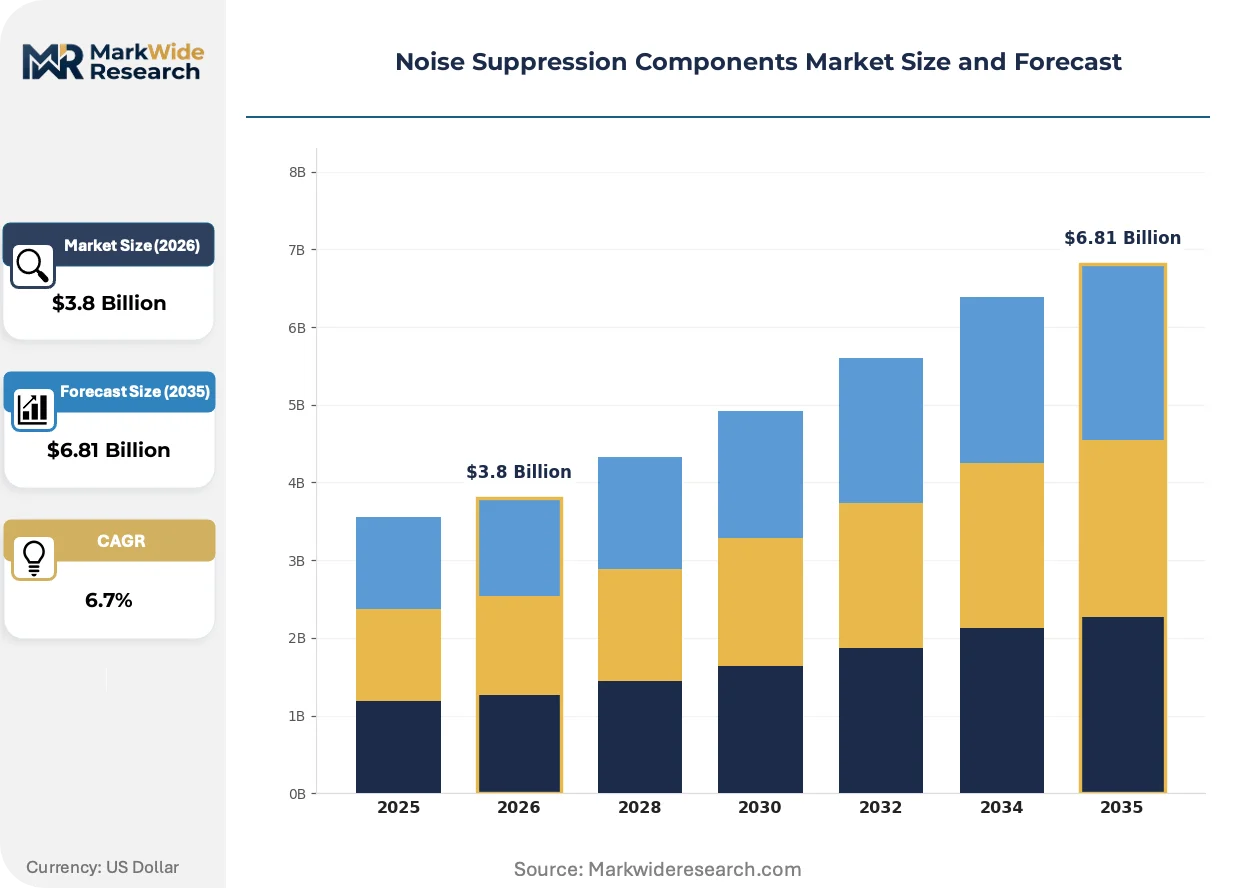
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Passive Filters, Active Filters, Sound Barriers, Acoustic Panels Application: Industrial Equipment, Consumer Electronics, Automotive, Construction Material: Foam, Metal, Fabric, Rubber End User: Manufacturers, Retailers, Contractors, Homeowners |
| Companies Covered | Murata Manufacturing Co., Ltd., TDK Corporation, Laird PLC, Panasonic Corporation, TE Connectivity Ltd., Vishay Intertechnology, Inc., KYOCERA AVX Components Corporation, Parker Chomerics, Taiyo Yuden Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Noise Suppression Components Market Shifts & Advancements
Component miniaturization and material science advances are converging to redefine how noise suppression integrates into densely packed electromechanical systems across transportation, industrial, and consumer applications.
Multilayer ferrite chip beads with embedded via structures are digitizing how high-frequency noise is managed in automotive ECUs and smartphone RF modules. Tier-1 automotive suppliers are specifying these devices for 5G telematics and ADAS sensor fusion boards where space constraints preclude discrete inductor-capacitor networks. This digitizing filter architecture is compressing the addressable market for conventional wire-wound ferrite components in sub-6 GHz applications.
REACH authorization procedures for diisocyanates in polyurethane foam production are forcing acoustic material suppliers to validate aliphatic and water-blown alternatives before 2025 sunset dates. Industrial consequence includes 30-40% raw material cost elevation for compliant formulations and accelerated consolidation among European foam converters lacking reformulation capabilities. Construction and rail interior segments in Germany, France, and the Netherlands are most affected, with project specifications already excluding non-authorized chemistries.
Buyer concentration among hyperscale data center operators is compressing supplier negotiation cycles and unbundling after-sales technical support from component pricing. Amazon Web Services, Microsoft Azure, and Google Cloud are deploying direct procurement teams to negotiate multi-year ferrite core and EMI gasket supply agreements, displacing traditional distribution channels. This concentration is most visible in Virginia's Data Center Alley and Singapore's Tuas industrial zone, where facility buildouts are synchronizing filter demand across thousands of server racks simultaneously.
Noise Suppression Components Market Segmentation
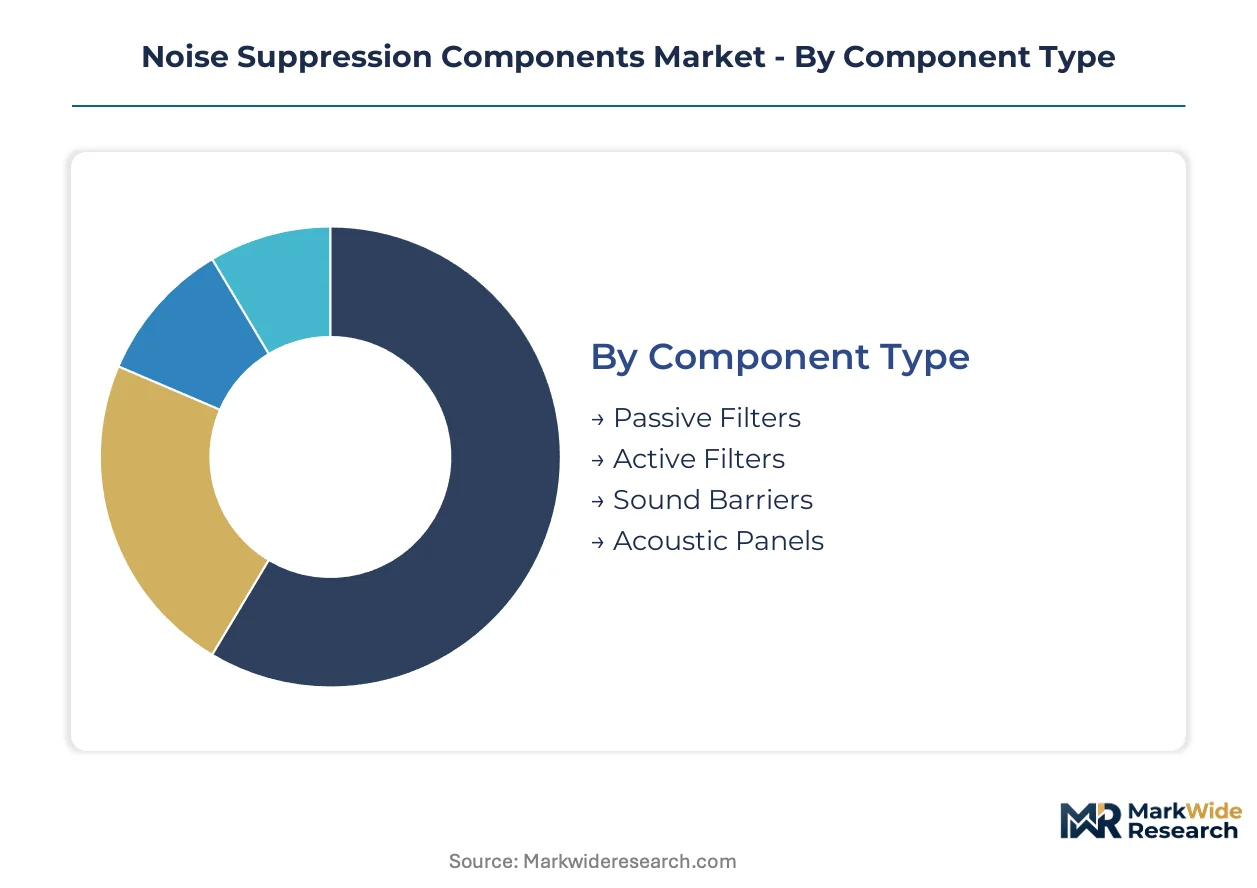
Noise suppression components serve divergent technical requirements across electromagnetic interference mitigation and acoustic vibration control. Segmentation reveals how material science, application intensity, and procurement authority reshape supplier strategies and margin structures.
Component Type:
Cost tier separates commodity passive devices from engineered active systems and material-based acoustic solutions.
- Passive Filters:Ferrite-based common-mode chokes and multilayer chip beads attenuate high-frequency noise without external power. Automotive electrification—particularly 800V architectures and silicon carbide inverters—pulls these components into multi-stage filter topologies across German and Japanese OEM supply chains.
- Active Filters:Powered cancellation circuits with real-time digital signal processing target low-frequency noise in precision manufacturing and medical imaging environments. Stuttgart-Munich industrial corridor demand concentrates here for semiconductor cleanroom compliance.
- Sound Barriers:Mass-loaded vinyl and composite panels block airborne transmission in rail and construction applications.
- Acoustic Panels:Porous absorption materials including melamine and open-cell polyurethane target reverberation control in commercial interiors and aerospace cabins.
Passive filters hold installed capacity. Acoustic panels are rotating up the share rankings.
Application:
Application intensity varies by electromagnetic noise severity, acoustic exposure limits, and regulatory enforcement stringency.
- Automotive:Battery management systems, onboard chargers, and 5G telematics modules demand ferrite components operating above 10 MHz. EU F-Gas Regulation and REACH framework compliance requirements are compressing supplier qualification timelines for acoustic interior materials.
- Industrial Equipment:Motor drives, power inverters, and CNC machinery generate broadband noise requiring thick-film resistor-capacitor networks. Virginia's Data Center Alley and Singapore's Tuas zone synchronize ferrite core demand across hyperscale server deployments.
- Consumer Electronics:Smartphone RF modules and laptop motherboards specify surface-mount miniaturized filters where space constraints preclude discrete inductor-capacitor networks.
- Construction:Airborne noise isolation requirements in Germany, France, and Netherlands project specifications are excluding non-authorized polyurethane chemistries ahead of diisocyanate sunset dates.
Industrial equipment maintains the steepest expansion trajectory. Consumer electronics is compressing average selling prices through procurement concentration.
Material:
Material selection hinges on frequency target, outgassing specifications, and reformulation compliance costs.
- Foam:Melamine and polyurethane formulations dominate aerospace cleanrooms and rail interiors. REACH authorization procedures for diisocyanates are elevating raw material costs for compliant formulations and consolidating European converter capacity.
- Metal:Rare-earth ferrite cores and permalloy shielding address electromagnetic interference in automotive and data center power electronics. Neodymium and dysprosium processing dependence on Chinese refining capacity exposes price volatility risks.
- Fabric:Composite textiles with conductive fibers serve lightweight shielding in wearable electronics and portable equipment.
- Rubber:Vibration-damping elastomers isolate mechanical noise in industrial machinery and HVAC systems.
Metal-based solutions command premium pricing. Foam is gaining share fastest through construction code tightening.
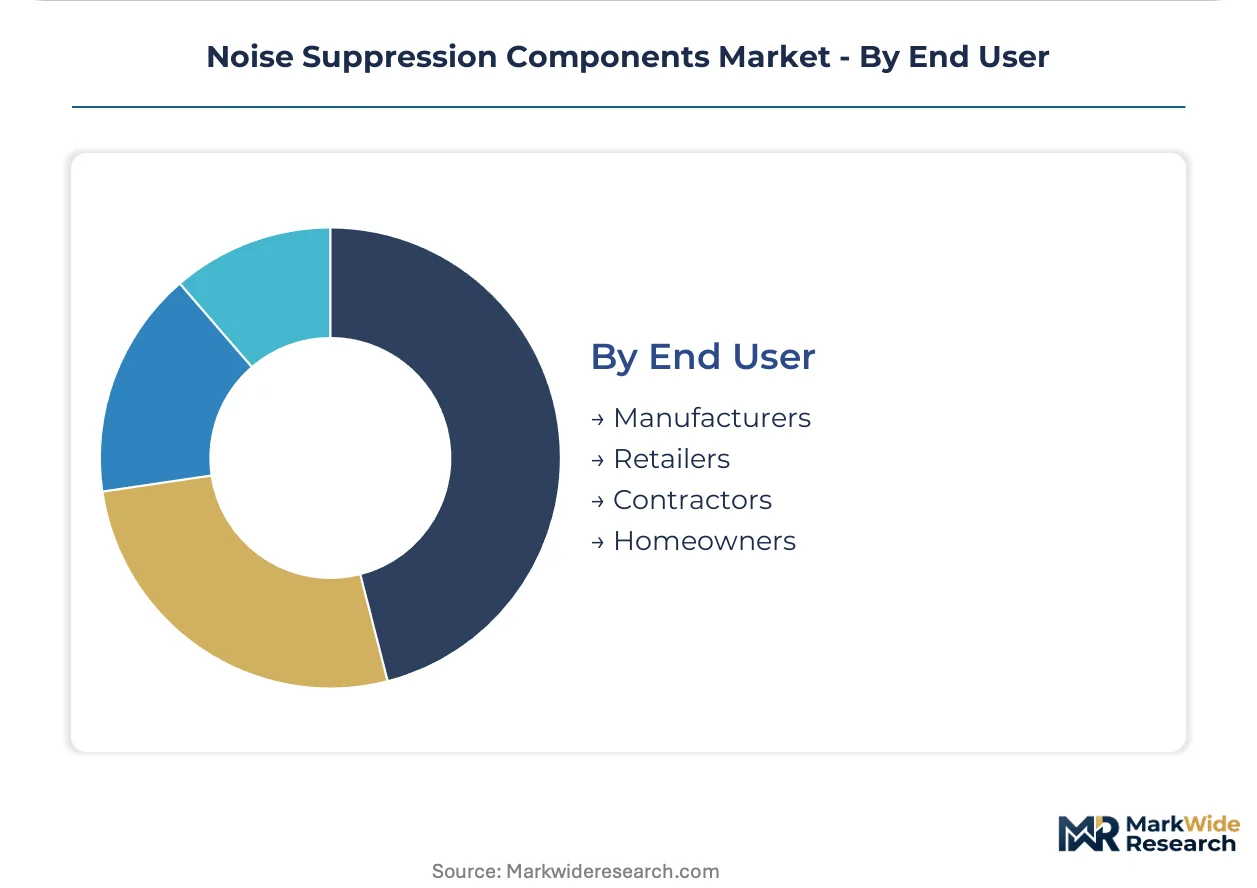
End User:
Procurement authority and technical specification control separate direct manufacturers from intermediated channels.
- Manufacturers:Tier-1 automotive suppliers and electronics OEMs specify component performance directly, compressing filter qualification cycles to align with 12-month vehicle platform schedules. Amazon Web Services, Microsoft Azure, and Google Cloud negotiate multi-year ferrite core supply agreements displacing traditional distribution.
- Contractors:Construction and rail project contractors face 30-40% raw material cost elevation for REACH-compliant acoustic foam formulations, accelerating consolidation among European converters lacking reformulation capabilities.
- Retailers:Consumer electronics distributors manage inventory for aftermarket replacement filters and DIY acoustic treatment kits.
- Homeowners:Residential renovation demand concentrates in premium melamine foam products for home studio and theater applications.
Manufacturers retain specification authority. Contractors are rotating up the share rankings through infrastructure buildout intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in ferrite cores and acoustic foams are redrawing procurement geography. China dominates rare-earth ferrite refining, while Germany and Japan concentrate high-value filter assembly. India's electronics manufacturing incentives are attracting component suppliers seeking tariff-advantaged production bases.
United States
Virginia's Data Center Alley and Texas hyperscale campuses synchronize ferrite core demand across thousands of server racks. The EPA enforces Title 47 CFR Part 15 emission limits that shape product certification roadmaps. Seattle's aerospace cluster sustains premium demand for low-outgassing melamine foams in cleanroom environments.
Germany
Stuttgart-Munich industrial corridor density sustains premium demand for precision-manufactured EMI filters and acoustic materials. The EU F-Gas Regulation and REACH framework restrict fluorinated gas content and hazardous substance thresholds in acoustic foams. Bavaria's automotive electrification ecosystem pulls ferrite-based common-mode chokes into 800V powertrain supply chains.
China
Rare-earth ferrite refining concentration in Inner Mongolia and Jiangxi exposes global filter manufacturers to price volatility and export control risks. MIIT's GB standards and dual carbon goals are tightening energy efficiency requirements for electromagnetic component production. Shenzhen's electronics manufacturing hub concentrates surface-mount filter assembly for consumer electronics and automotive telematics.
Japan
METI's carbon neutrality roadmap prioritizes bio-based acoustic materials in public infrastructure procurement. Tokyo-Osaka industrial corridors anchor vertically integrated ceramic capacitor and EMI filter production. Nagoya's automotive engineering density sustains qualification cycles for safety-critical filter applications in hybrid and electric powertrains.
India
The PLI scheme for electronics manufacturing is creating localized EMI filter demand for smartphone and laptop contract assembly. Karnataka and Tamil Nadu industrial corridors are attracting ferrite and ceramic component suppliers seeking domestic qualification. Delhi-NCR's data center buildouts are synchronizing demand for broadband noise suppression in server power distribution units.
Noise Suppression Components Market Competitive Landscape
On the supply side, the industry is consolidating around material science leaders with captive ferrite refining and ceramic formulation capabilities. Three strategic archetypes dominate: vertically integrated Japanese conglomerates controlling raw material-to-component pipelines; European specialists in REACH-compliant acoustic foams; and scale-driven contract manufacturers serving hyperscale data center procurement. Competitive moves center on M&A to secure rare-earth supply agreements and capacity expansion in India and Southeast Asia to capture PLI scheme benefits.
Within the vertically integrated tier, Murata Manufacturing Co., Ltd., TDK Corporation, and Taiyo Yuden Co., Ltd. represent archetypal Japanese conglomerates with in-house ceramic and ferrite material science. These entities exemplify supply-side concentration where backward integration into raw material processing creates defensible positioning against price volatility in rare-earth markets. Their geographic concentration in Japan's Kanto and Kansai industrial zones reflects historical clustering of electronics manufacturing infrastructure.
| Leading Market Players |
|---|
| Murata Manufacturing Co., Ltd. |
| TDK Corporation |
| Laird PLC |
| Panasonic Corporation |
| TE Connectivity Ltd. |
| Vishay Intertechnology, Inc. |
| KYOCERA AVX Components Corporation |
| Parker Chomerics |
| Taiyo Yuden Co., Ltd. |
| Others |
Supply & Pricing Matrix
Inner Mongolia's rare-earth ferrite refining concentration hands Chinese processors outsized leverage over global filter pricing, with downstream manufacturers absorbing volatility through long-term offtake contracts or captive supply investments. This geographic chokepoint compresses margin pools for European and Japanese assemblers while amplifying procurement power for hyperscale buyers consolidating server rack demand.
Pricing Analysis
Current-generation multilayer ferrite chip beads command substantial premiums over legacy wire-wound components, while next-gen embedded via structures are resetting price floors for automotive 5G telematics applications. Three-tier pricing structure across automotive-grade, industrial-grade, and consumer-grade certification levels separates qualified suppliers from commodity converters, with price erosion running through consumer electronics due to procurement concentration among smartphone OEMs. Automotive Tier 1 suppliers exhibit lowest price sensitivity given 18-24 month qualification lock-ins, while construction contractors face acute cost pressure from 30-40% REACH-compliant foam reformulation expenses.
Supply Chain Analysis
Neodymium and dysprosium feedstock dependence draws from Chinese refining capacity in Inner Mongolia and Jiangxi, Japanese ceramic formulation expertise in Kanto and Kansai industrial zones, and German precision assembly clustering around Stuttgart-Munich corridors. Raw material inputs hinge on rare-earth oxide supply, high-purity ferrite powders, and REACH-authorized polyurethane precursors. Single-source vulnerability concentrates in Chinese rare-earth export licensing, while distribution runs through direct procurement teams at hyperscale data center operators displacing traditional component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as automotive electrification and hyperscale data center buildouts create interoperability standards that favor component suppliers with modular, qualification-ready portfolios over custom-engineered legacy architectures.
For Market Incumbents: Insulate market position by deepening backward integration into rare-earth ferrite refining to offset Chinese supply volatility, and accelerate REACH-compliant acoustic foam reformulation ahead of diisocyanate sunset deadlines to consolidate European converter capacity. Active noise cancellation algorithms in automotive cabins threaten passive absorption volumes, making certification moats and automotive safety-critical filter qualifications the priority defensive levers. For New Entrants and Emerging Players: Pursue white-space opportunities in India's PLI scheme electronics manufacturing corridors, where localized EMI filter demand for smartphone and laptop contract assembly outpaces domestic supplier qualification. India's Karnataka and Tamil Nadu industrial zones offer the most penetrable geography, with go-to-market traction coming through partnership with Taiwanese contract manufacturers establishing Indian assembly capacity. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated material science specialists with captive ferrite processing and ceramic formulation capabilities over pure-play assemblers exposed to raw material volatility. Long-term viability over a multi-year window rests on supply security and automotive electrification content expansion, with acquisition targets clustering around Japanese and European mid-caps with in-house material science. The signal to watch is hyperscale data center direct procurement team formation, which indicates channel displacement velocity and margin compression timing for traditional distribution-dependent suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Refining | Captive neodymium supply from Inner Mongolia insulates TDK and Murata against Chinese export control volatility. |
| REACH-Compliant Foam Reformulation | Aliphatic polyurethane validation ahead of ECHA diisocyanate deadlines consolidates European converter market share. |
| India PLI Scheme Capacity Placement | Karnataka and Tamil Nadu ferrite core qualification captures tariff-advantaged smartphone assembly demand. |
| Hyperscale Direct Procurement Negotiation | Multi-year supply agreements with AWS and Microsoft Azure displace traditional EMI filter distribution channels. |
| Multilayer Chip Bead Architecture Transition | Embedded via structures for 5G automotive telematics compress wire-wound ferrite addressable markets. |
Research Methodology
A spread of perspectives from EMI filter procurement managers at Tier 1 automotive suppliers, acoustic foam technical directors at European converters, rare-earth trading specialists, and hyperscale data center infrastructure planners converged on the working assumptions driving this analysis. Primary fieldwork combined with secondary validation from SEC 10-K filings, customs and trade data, ECHA REACH authorization databases, and automotive production records. Bottom-up component demand modeling and top-down end-use market sizing were triangulated to constrain variance.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation modeling across component type, application intensity, material chemistry, and procurement authority dimensions. CAGRs were derived from installed base growth, content-per-unit expansion in 800V automotive architectures, and construction code tightening trajectories. Forecast inputs incorporated MIIT energy efficiency mandates, EU F-Gas Regulation compliance timelines, and METI carbon neutrality procurement preferences.
Macroeconomic conditions sit as an overlay; deviation in rare-earth oxide spot pricing, semiconductor capital expenditure cycles, or automotive platform development schedules would shift the trajectory materially. Cross-checking against IHS Markit vehicle production data and hyperscaler disclosed infrastructure spending is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Toroid Inductor Market
RF Components
RF Tester Market
RF Components
RF Gan Market
RF Components
RF Semiconductor Market
RF Components
Digital Phase Shifter Market
RF Components
RF Passive Component Market
RF Components
Japan Small Signal Transistor Market
RF Components
Global RF Transceiver Market
RF Components
Radio Frequency Integrated Circuit (RFIC) Market
RF Components
Multilayer Coupled Inductor Market
RF Components
Silicon Tuners Market
RF Components
Radio Frequency (RF) Signal Generators Market
RF Components
Coaxial Splitters Market
RF Components
RF Duplexer Market
RF Components
Latin America RFID Tags Market
RF Components
RF Antenna Market