
 Global Next Generation Power Semiconductors Market | 2026-2036
Global Next Generation Power Semiconductors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Next Generation Power Semiconductors Market Intelligence
The shift from silicon-based IGBTs to wide-bandgap materials like silicon carbide (SiC) is narrowing the performance gap between theoretical efficiency and real-world application. This technological transition creates distinct strategic lanes for key suppliers. Infineon Technologies AG leverages its vast manufacturing scale across multiple material platforms. Wolfspeed Inc. specializes in SiC and GaN-on-silicon, while STMicroelectronics NV competes with a broad portfolio including both next-generation and legacy silicon devices.
Next generation power semiconductors are devices built from wide-bandgap materials like silicon carbide (SiC) and gallium nitride (GaN). These materials allow for higher switching frequencies, lower energy loss, and operation at higher temperatures and voltages compared to conventional silicon. Within product types, Silicon Carbide MOSFETs are displacing older silicon IGBTs in new high-voltage designs. Demand from Electric Vehicle Drivetrains and Renewable Energy Systems represents the fastest-growing application segments, requiring maximum power density.
Regulatory frameworks like the EU's RoHS directive and US EPA vehicle emissions standards mandate higher energy efficiency, creating structural demand. China's dual carbon goals and associated GB standards further accelerate adoption in its domestic energy and transport sectors. Consequently, securing a stable supply of raw materials like high-purity SiC wafers is a primary focus for all major device manufacturers to support future growth.
Market Dynamics
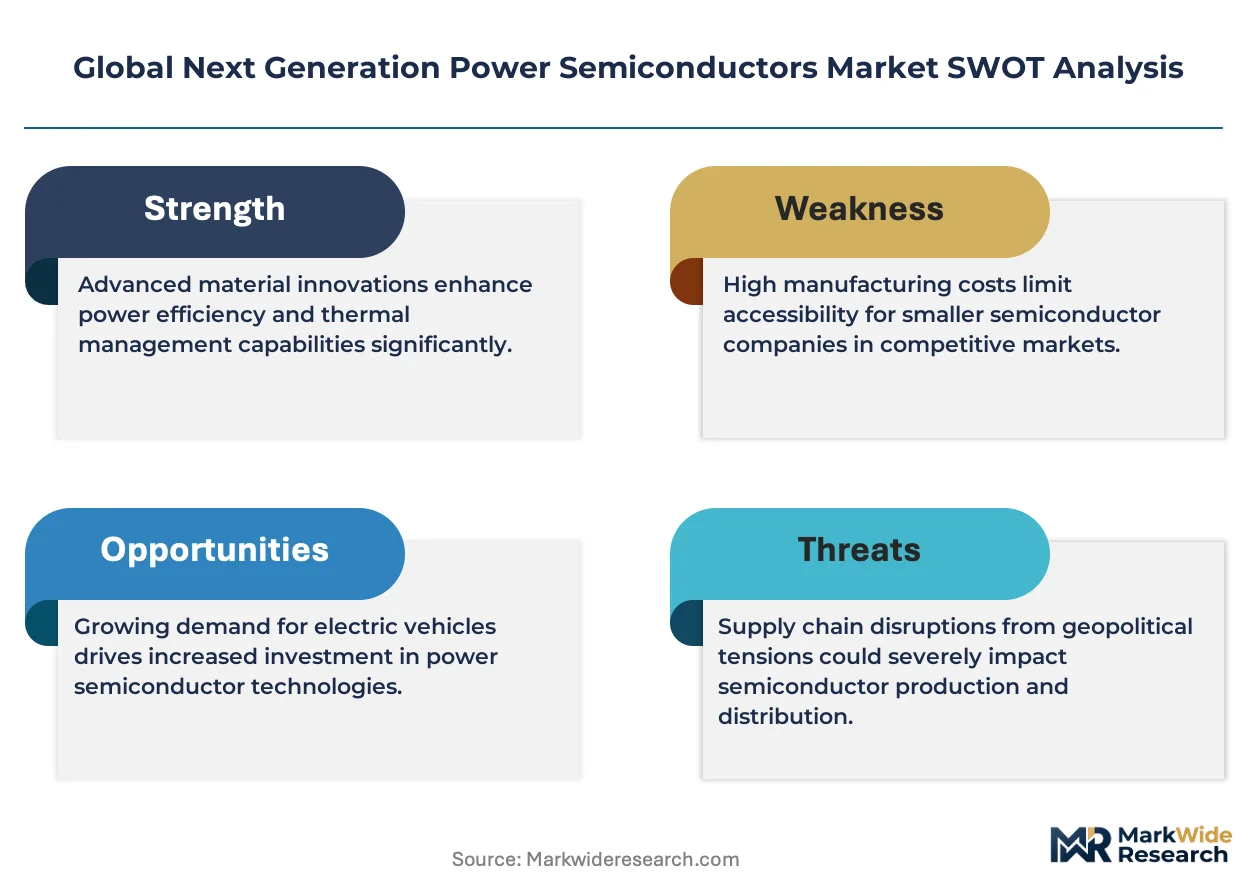
The market's central dynamic is the technological substitution of silicon with wide-bandgap materials like SiC and GaN. This shift is driven by urgent efficiency demands from the electric vehicle and renewable energy sectors, forcing a re-evaluation of power electronics design.
Growth Catalysts
- EV Drivetrain Adoption:Electric vehicle manufacturers require high-efficiency inverters to extend battery range and reduce vehicle weight, creating intense demand for SiC MOSFETs over traditional silicon IGBTs.
- EU Green Deal:Stringent emissions targets set by the EU Green Deal compel automotive and industrial sectors to adopt more energy-efficient power conversion technologies, directly benefiting next generation semiconductors.
- China's Energy Policies:China's dual carbon goals are accelerating the build-out of renewable energy infrastructure, such as solar and wind farms, which depend on high-voltage SiC and GaN devices for efficient power grid integration.
Market Restraints
- Substrate Cost and Availability:The high cost and limited supply of large-diameter, high-purity silicon carbide wafers compared to mature silicon substrates present a significant barrier to cost-competitive mass production.
- Manufacturing Complexity:Achieving low defect density and high yields in SiC and GaN crystal growth and device fabrication is technically challenging, constraining output and slowing the industry's ability to scale.
- Supply Chain Concentration:The global supply of raw SiC powder and boules is highly concentrated in a few key suppliers, creating potential bottlenecks and price volatility for device manufacturers.
Strategic Opportunities
- GaN in Consumer Electronics:Gallium nitride devices are creating new opportunities in high-frequency applications like compact fast chargers for laptops and smartphones, a segment where SiC is less competitive.
- Industrial Motor Drives:The vast, underpenetrated market for industrial motor drives offers a significant growth vector as factories upgrade equipment to meet higher energy efficiency standards mandated by governments.
- Grid Infrastructure Modernization:The expansion of smart grids and energy storage systems provides a long-term opportunity for high-voltage SiC devices in utility-scale applications beyond the automotive sector.
Industry Challenges
- Specialized Engineering Talent:A scarcity of power electronics engineers with deep expertise in wide-bandgap material physics and high-frequency circuit design hinders product development and application support for OEMs.
- System Integration Complexity:Integrating SiC and GaN devices requires a complete redesign of surrounding components, including gate drivers and magnetics, posing a significant challenge for teams accustomed to silicon-based systems.
- Reliability and Standardization:A lack of mature, industry-wide standards for testing and qualifying the long-term reliability of WBG devices can slow adoption cycles among risk-averse industrial and automotive customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Next Generation Power Semiconductors Market |
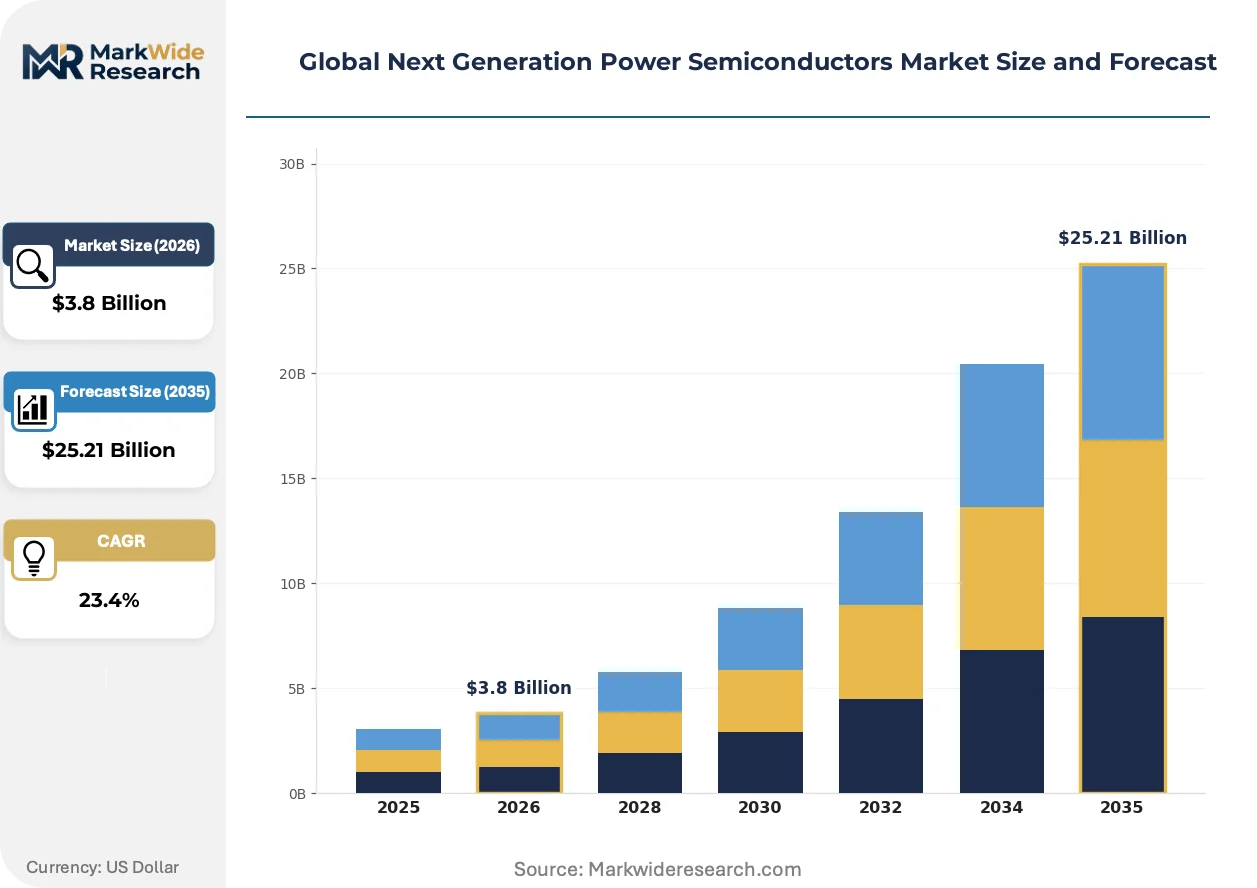
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $25.21 Billion |
| CAGR (2026 – 2036) | 23.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicon Carbide MOSFET, Gallium Nitride HEMT, Silicon IGBT, Silicon MOSFET, Thyristors Application: Renewable Energy Systems, Electric Vehicle Drivetrains, Industrial Motor Drives, Consumer Electronics, Power Supplies Technology: Wire Bonding, Flip Chip, Sputtering, Epitaxial Growth, Wafer Bonding End User: Utility Providers, Heavy Machinery Manufacturers, Consumer Appliance Producers, Aerospace Systems, Data Center Operators |
| Companies Covered | Infineon Technologies AG, Texas Instruments Inc., STMicroelectronics NV, NXP Semiconductors NV, Wolfspeed Inc., Qorvo Inc., Navitas Semiconductor, Power Integrations Inc., Renesas Electronics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Next Generation Power Semiconductors Market Strategic Shifts & Innovations
Material science advancements are enabling a fundamental shift in power electronics architecture. The transition to SiC and GaN is not merely a component swap but a catalyst for creating smaller, cooler, and more efficient power conversion systems across multiple industries.
Silicon Carbide (SiC) MOSFETs are semiconductor switches that offer superior performance in high-voltage, high-temperature environments compared to silicon. The automotive and industrial sectors are leading the adoption for new, power-dense applications. The entire design philosophy for power conversion is migrating from bulky, low-frequency silicon IGBT modules to highly compact, efficient, and high-frequency SiC-based architectures.
The US EPA’s stringent vehicle emissions and fuel economy standards create a powerful regulatory incentive for next generation power semiconductors. These rules compel automakers to maximize efficiency in electric and hybrid vehicle powertrains to meet fleet-wide compliance targets. The automotive segment is most affected, accelerating its transition to SiC-based traction inverters to extend EV range and minimize energy losses.
A key behavioral shift involves automotive OEMs forming deep co-design partnerships with semiconductor firms for critical power modules. This collaborative model is replacing the traditional transactional purchasing of standardized components from catalogs. The trend is most pronounced in the EV hubs of Germany and China, where tight integration between the inverter, motor, and battery system is essential for achieving competitive performance and range.
Global Next Generation Power Semiconductors Market Segmentation
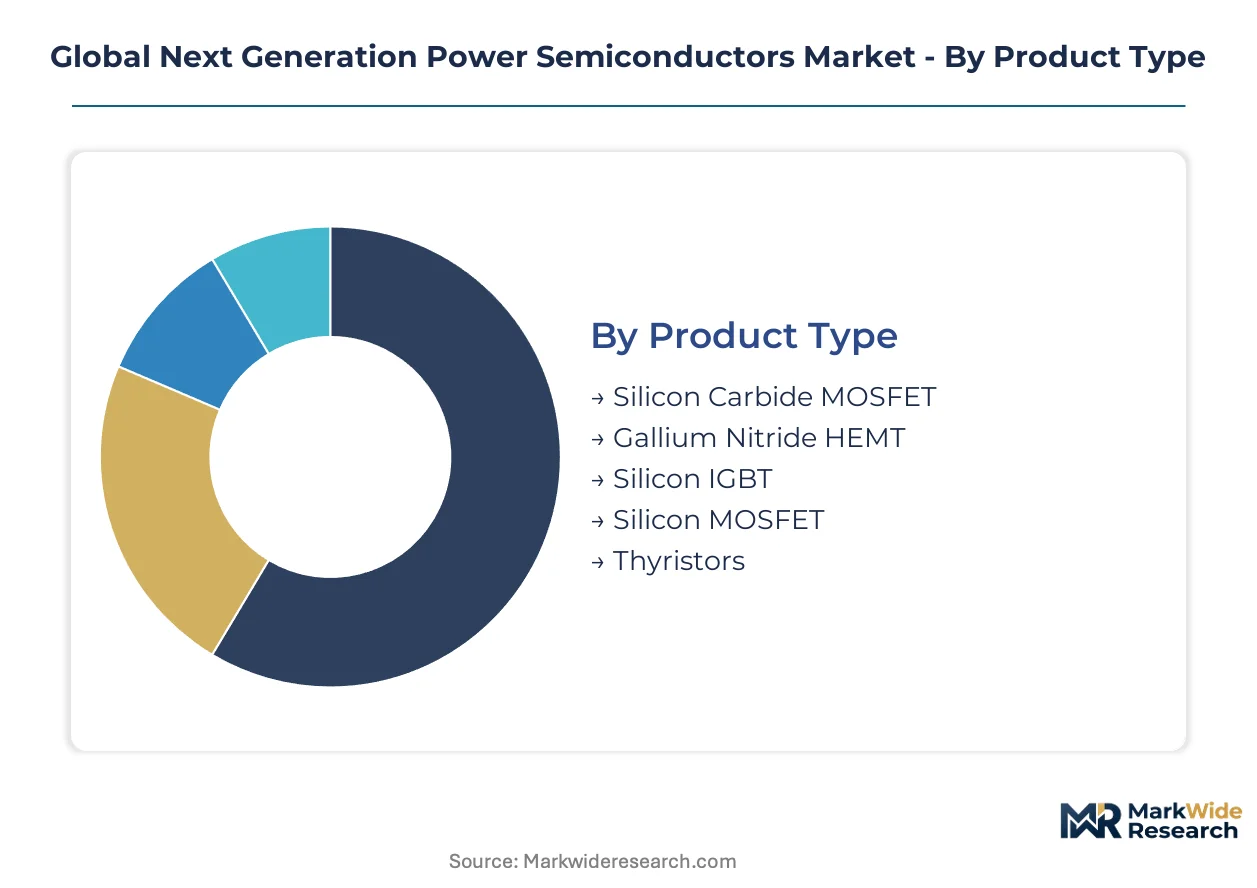
Market segmentation provides a critical framework for understanding the diverse forces shaping the next-generation power semiconductors industry. Analyzing these categories reveals the core technologies, applications, and end-user demands driving the rapid transition from conventional silicon to wide-bandgap materials.
Product Type:
The product type segmentation reveals a clear shift from mature silicon-based devices towards emerging wide-bandgap materials.
- Silicon Carbide MOSFET:This semiconductor switch offers superior performance in high-voltage and high-temperature environments compared to silicon. Demand from electric vehicle drivetrains and renewable energy systems requires maximum power density.
- Gallium Nitride HEMT:These devices enable higher switching frequencies and lower energy loss than traditional silicon components. Demand from consumer electronics, such as fast chargers, and certain power supplies utilizes GaN for compact designs.
- Silicon IGBT:These devices remain cost-effective for medium-power applications, though new high-voltage designs increasingly displace them.
- Silicon MOSFET:Widely used in lower-voltage power management, silicon MOSFETs offer a balance of cost and performance for many established applications.
- Thyristors:Primarily employed in high-power industrial applications, thyristors manage substantial current flows in grid infrastructure and motor controls.
Silicon IGBT handles the majority of throughput; Silicon Carbide MOSFET is the fastest mover on share.
Application:
Application segments highlight where the high-efficiency and power density benefits of next-generation semiconductors are most critically valued.
- Electric Vehicle Drivetrains:These systems require high-efficiency inverters to extend battery range and reduce vehicle weight. Automotive OEMs in China and Germany are driving this demand for SiC MOSFETs.
- Renewable Energy Systems:These systems demand high-voltage SiC and GaN devices for efficient power grid integration. China's dual carbon goals accelerate adoption in solar and wind farms.
- Industrial Motor Drives:This segment offers significant growth as factories upgrade equipment to meet higher energy efficiency standards mandated by governments.
- Consumer Electronics:Gallium nitride devices are creating new opportunities in compact fast chargers for laptops and smartphones.
- Power Supplies:High-frequency switching capabilities of next-gen devices reduce size and improve efficiency in various power conversion units.
Electric Vehicle Drivetrains and Renewable Energy Systems are pivotal for volume growth, while Consumer Electronics shows rapid expansion.
Technology:
The technology segmentation outlines the advanced manufacturing processes crucial for producing next-generation power semiconductor devices.
- Epitaxial Growth:This process involves depositing crystalline layers onto a substrate, essential for creating the active regions of SiC and GaN devices. Securing a stable supply of high-purity SiC wafers is a primary focus for device manufacturers.
- Flip Chip:This packaging technology connects semiconductor dies directly to a substrate via solder bumps, enabling higher performance and smaller form factors. Advanced power modules in electric vehicles benefit from its thermal and electrical advantages.
- Wire Bonding:A traditional packaging method, wire bonding remains a cost-effective solution for many standard power semiconductor applications.
- Sputtering:This physical vapor deposition technique is utilized for depositing thin films of various materials during device fabrication.
- Wafer Bonding:Essential for creating advanced substrates or 3D integrated structures, wafer bonding combines two or more wafers.
Epitaxial Growth remains foundational for material quality, while Flip Chip packaging enables denser, more efficient power modules.
End User:
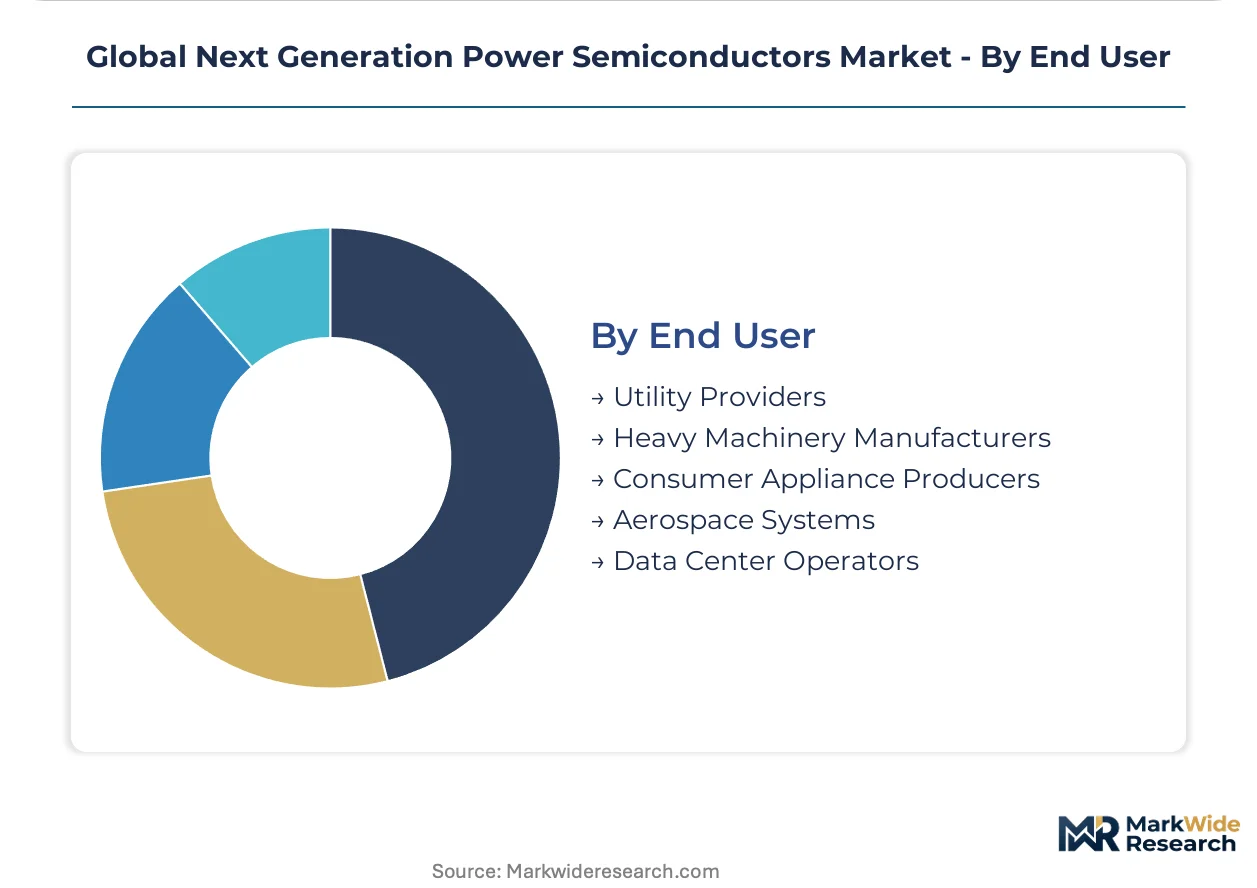
The end-user segmentation highlights the diverse clientele benefiting from the high-voltage, high-temperature, and high-frequency capabilities of next-generation power semiconductors.
- Utility Providers:These entities utilize high-voltage SiC devices for grid infrastructure modernization, including smart grids and energy storage systems. The expansion of renewable energy requires robust power management solutions for efficient integration.
- Data Center Operators:These operators seek higher efficiency and power density in power supplies and server infrastructure to reduce energy consumption and cooling costs. Stringent energy efficiency standards compel adoption of advanced power electronics.
- Heavy Machinery Manufacturers:These companies integrate advanced power electronics into industrial motor drives and power conversion systems for improved efficiency.
- Consumer Appliance Producers:GaN devices enable smaller, more efficient power solutions for a range of household electronics.
- Aerospace Systems:High-temperature operation and reduced weight are critical advantages for next-gen devices in demanding aerospace applications.
Utility Providers and Data Center Operators are driving significant efficiency gains through next-gen components, with Heavy Machinery Manufacturers also showing strong uptake.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The trade of advanced power semiconductor components from specialized manufacturing hubs to key automotive and industrial markets defines the global landscape. High-purity SiC wafers primarily flow from concentrated suppliers to device fabricators worldwide. This critical supply chain supports the rapid deployment of next-generation power electronics in major consuming regions.
United States
United States demand for SiC MOSFETs stems from electric vehicle drivetrains and grid infrastructure modernization. US EPA vehicle emissions standards and the IRA compel efficiency gains across energy sectors. North Carolina's research triangle and Silicon Valley continue to drive innovation in material science and device design.
China
China's significant uptake of next-generation power semiconductors is driven by its expansive electric vehicle market and renewable energy build-out. The nation's dual carbon goals and associated GB standards mandate high-efficiency power conversion. Manufacturing hubs like the Yangtze River Delta integrate advanced SiC devices into automotive and industrial applications.
Germany
German automotive OEMs and industrial manufacturers require high-efficiency power electronics for competitive advantage. The EU Green Deal's stringent emissions targets accelerate the transition to wide-bandgap materials. Bavaria's strong automotive and electronics cluster fosters collaborative design partnerships for SiC power modules.
Japan
Japanese industry utilizes next-generation power semiconductors in hybrid vehicles, industrial robotics, and energy-efficient infrastructure. METI's strategic initiatives promote domestic development and adoption of advanced power devices. The Kanto region's electronics firms are pioneering new packaging technologies for SiC and GaN solutions.
South Korea
South Korea's consumer electronics and electric vehicle sectors demand compact, high-efficiency power solutions. MOTIE initiatives support the development of next-generation semiconductor materials and applications. The Seoul Capital Area hosts numerous design houses focused on GaN-based fast chargers and EV power modules.
Global Next Generation Power Semiconductors Market Key Industry Players
Channel-controlling players compete with product-specialist players across the next-generation power semiconductors market. The industry exhibits a tiered structure, with integrated device manufacturers and material-focused specialists defining distinct competitive lanes. Strategic archetypes include large-scale diversified suppliers and focused wide-bandgap material innovators. Companies engage in strategic partnerships with automotive OEMs and invest heavily in capacity expansion for SiC wafer production.
Within the integrated device manufacturer archetype, Infineon Technologies AG and STMicroelectronics NV occupy significant positions, leveraging broad portfolios across multiple material platforms. Wolfspeed Inc., a US-based entity, exemplifies the specialized wide-bandgap material innovator, focusing on SiC and GaN-on-silicon solutions. These firms anchor various segments, from high-power automotive applications to compact consumer electronics, demonstrating distinct approaches to market penetration and technology leadership.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| Texas Instruments Inc. |
| STMicroelectronics NV |
| NXP Semiconductors NV |
| Wolfspeed Inc. |
| Qorvo Inc. |
| Navitas Semiconductor |
| Power Integrations Inc. |
| Renesas Electronics Corporation |
| Others |
Cost & Logistics Intelligence
North Carolina's specialized SiC wafer production capacity directly influences the cost structure of next-generation power semiconductors. This concentration of advanced material fabrication dictates pricing leverage for device manufacturers.
Pricing Analysis
The pricing gap between conventional silicon and wide-bandgap materials like SiC and GaN remains significant. Value-based pricing dominates for next-generation power semiconductors, driven by superior performance and stringent reliability qualification. Upward pricing pressure stems from the high cost of SiC wafers and complex manufacturing processes. Consumer electronics manufacturers exhibit higher price sensitivity compared to automotive OEMs and utility providers, who prioritize efficiency gains.
Supply Chain Analysis
Wolfspeed Inc.'s specialized manufacturing capacity for SiC wafers and devices dictates a significant portion of the next-generation power semiconductor supply. Geographic concentration centers on the United States, China, and Germany for material production and device fabrication. The supply chain relies on high-purity SiC wafers and raw SiC powder. Single-source vulnerability for key raw materials poses a structural risk. Distribution runs through direct sales channels and co-design partnerships with major automotive OEMs and industrial integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The next-generation power semiconductors market is positioned for a cyclical recovery, driven by sustained investment in electric vehicle production and renewable energy infrastructure build-out. This upswing reflects a broader industrial retooling towards energy efficiency.
For Market Incumbents: Build technological leadership and manufacturing scale to defend market share against specialized wide-bandgap innovators. Incumbents should invest heavily in expanding SiC wafer production capacity and deepen vertical integration for critical materials. Collaborative co-design partnerships with automotive OEMs also reinforce market position. This strategy mitigates the threat of supply chain concentration and ensures long-term cost competitiveness.
For New Entrants and Emerging Players: Pursue niche applications where wide-bandgap materials offer distinct performance advantages over silicon, such as GaN in compact consumer electronics fast chargers. Industrial motor drives also represent a significant underpenetrated market. The consumer electronics segment offers the most penetrable entry point due to less stringent reliability cycles. A go-to-market strategy emphasizing application-specific reference designs and simplified integration tools will accelerate adoption.
For Investors and Strategic Acquirers: Long-term, this sits as a foundational technology play because global energy transition mandates and electrification trends ensure sustained demand. Investors should seek specialized material science firms with proprietary crystal growth technologies as acquisition targets. These companies offer control over critical inputs and intellectual property. The primary signal to watch is the consistent reduction in SiC wafer manufacturing costs, indicating broader market scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| SiC Wafer Production Capacity Expansion | Securing high-purity SiC wafer supply is critical for scaling next-generation power semiconductor device output. |
| Deepen Automotive OEM Co-Design Partnerships | Tailored power module development with EV manufacturers like those in Germany ensures competitive performance and market penetration. |
| Invest in GaN-on-Silicon R&D | Cost-effective GaN-on-silicon technology will unlock new high-volume applications in consumer electronics and power supplies. |
| Drive Wide-Bandgap Reliability Standardization | Establishing industry-wide standards for WBG device testing will accelerate adoption among risk-averse industrial customers. |
| Expand Presence in China's EV and Renewable Sectors | Leveraging China's dual carbon goals and GB standards provides significant volume growth for SiC and GaN devices. |
Research Approach
Operator-level perspectives from power electronics engineers, automotive OEM procurement leads, and SiC wafer manufacturers anchored the qualitative base for this analysis. This primary research was validated against extensive secondary sources including US EPA vehicle emissions standards, EU Green Deal documents, and company financial disclosures. A rigorous bottom-up and top-down triangulation approach ensured data consistency across all market segments.
Scenario-bracketing informed the quantitative framework, modeling market behavior under various adoption rates and technological advancements across the analysis window. Segmentation dimensions included product type, application, technology, end user, and regional adoption patterns. Compound annual growth rates were derived from historical trends and projected technological shifts. Key industry-specific inputs included electric vehicle production volumes and global renewable energy capacity additions.
Sensitivities concentrate around raw material supply disruptions, regulatory changes, and unforeseen technological breakthroughs. Forecasts reflect assumptions regarding manufacturing yield improvements and continued market adoption. Quarterly review of SiC wafer pricing and EV adoption rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Global DC Power Supply Module Market
Power Systems
Middle East and Africa Low Voltage Drives Market
Power Systems
US Variable Frequency Drive Market
Power Systems
Power Supply Isolation Equipment Market
Power Systems
Linear Voltage Regulators Market
Power Systems
Power Electronics Market
Power Systems
Thermoelectric Generator (TEG) Market
Power Systems
MOSFET and IGBT Gate Driver Market
Power Systems
North America Variable Frequency Drive Market
Power Systems
Europe Micro Inverter Market
Power Systems
Saudi Arabia Vacuum Pressure Impregnated (VPI) Transformer Market
Power Systems
Asia-Pacific Automotive DC-DC Converters Market
Power Systems
Buck-Boost Controller Market
Power Systems
Train Auxiliary Rectifier Market
Power Systems
Solid State Transformer Market
Power Systems
Asia Pacific Solid State Transformers Market