
 China Switchgear Market | 2026-2036
China Switchgear Market Size, Share, and Industry Trends Forecast 2026-2036
China Switchgear Market Insights
Data center power infrastructure is realigning switchgear procurement toward higher-rated indoor assemblies with integrated digital monitoring. CHINT Group Co., Ltd. leverages its domestic manufacturing scale to dominate standard-voltage commercial segments. Siemens (China) Co., Ltd. sustains technology leadership in gas-insulated systems for urban substations. XD Electric anchors the state-backed utility channel through its ultra-high-voltage product line.
Switchgear comprises electrical disconnect, protection, and control apparatus rated from low-voltage residential panels to extra-high-voltage substation bays, typically employing SF6, vacuum, or air as interruption media with mechanical or solid-state actuation. Circuit breakers occupy the largest value pool given their fault-current interruption duty and contact-wear maintenance cycles. Smart technology segments are expanding fastest as utilities deploy IEC 61850-compatible intelligent electronic devices for condition-based monitoring. Protection relays retain concentrated margins due to firmware customization and certification barriers.
MIIT enforces GB standards for electromagnetic compatibility and arc-fault containment, while SAMR administers mandatory product certification that gates market access for imported assemblies. NMPA-aligned pressure-vessel rules govern SF6 gas management, pushing manufacturers toward vacuum interrupter designs. Stakeholders must weigh the capital trade-off between retrofitting analog installed bases and full digital replacement against grid modernization timelines.
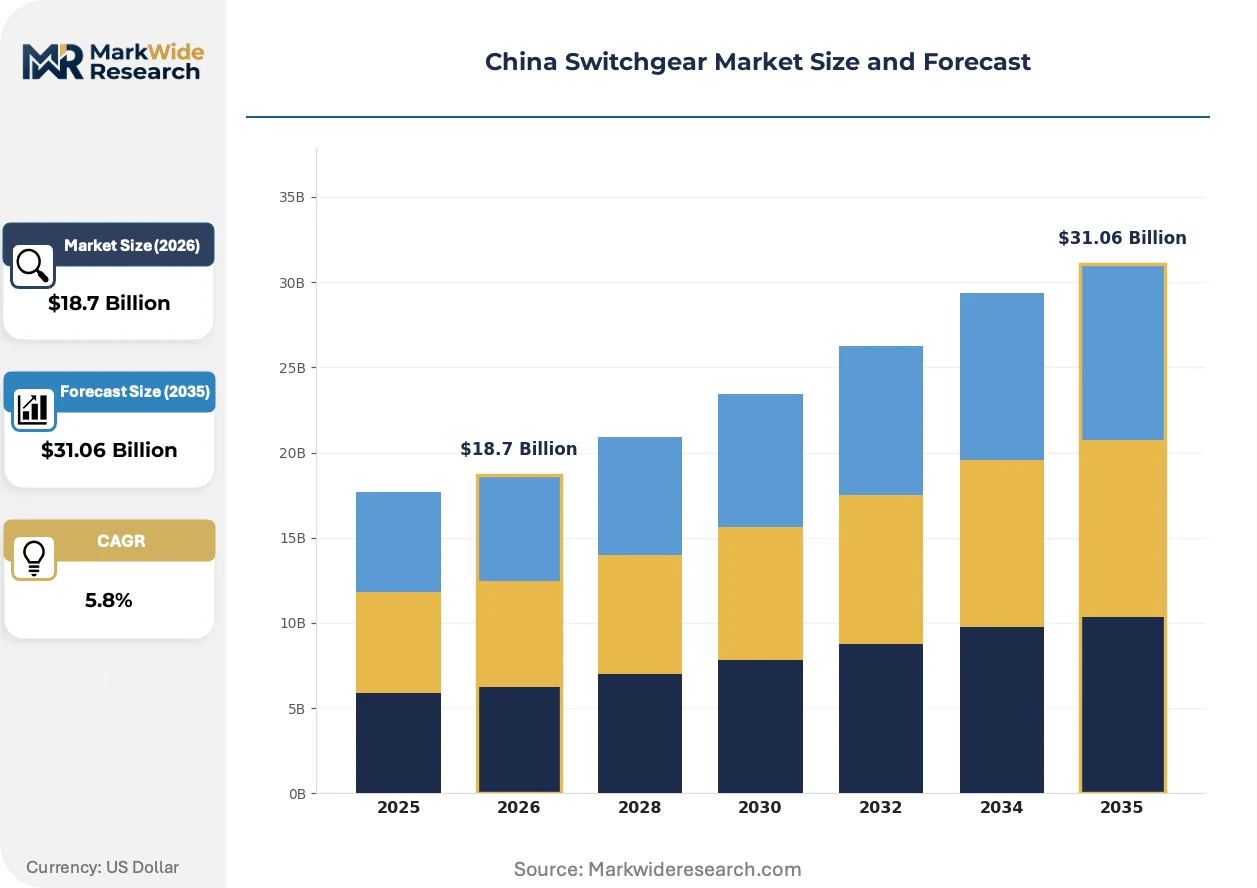
Market Dynamics
Data center operators in the Yangtze River Delta cluster are forcing voltage-tier upgrades across procurement specifications, compressing lead times for indoor gas-insulated assemblies while MIIT's GB standards mandate digital interoperability retrofits.
Growth Catalysts
- MIIT GB Standards for Smart Grid Interoperability:Mandatory digital protocol compliance accelerates replacement cycles for analog protection relays and circuit breakers across provincial utilities.
- SF6 Phase-Down Trajectories:NMPA-aligned pressure-vessel regulations and dual carbon goals drive vacuum interrupter adoption in new substation installations.
- Yangtze River Delta Data Center Buildouts:Hyperscale facility construction in Shanghai, Jiangsu, and Zhejiang concentrates demand for higher-rated indoor switchgear assemblies with integrated monitoring.
Market Restraints
- Copper and Rare Earth Input Volatility:Contact material costs swing with commodity markets, compressing margins on standard-voltage commercial panels.
- SF6 Gas Management Compliance Burden:NMPA pressure-vessel rules impose handling certification and reclamation infrastructure requirements that favor state-backed incumbents with captive service networks.
- Vacuum Interrupter Technical Ceiling:Current designs face dielectric stress limitations above 145kV, constraining substitution timelines in extra-high-voltage transmission corridors.
Strategic Opportunities
- Western Province Grid Modernization:Sichuan and Shaanxi provincial utilities lag coastal digitalization rates, creating retrofit demand for IEC 61850-compatible intelligent electronic devices.
- Integrated Solid-State Actuation:Convergence of power electronics with mechanical interruption enables arc-less switching for data center power distribution units.
- Dual Carbon Incentive Structures:Provincial green financing channels subsidize SF6-free substation upgrades, accelerating vacuum and dry-air technology penetration.
Industry Challenges
- IEC 61850 Firmware Customization Talent Scarcity:Protection relay engineering requires specialized protocol stack expertise concentrated at state research institutes.
- Legacy Analog Base Integration Complexity:Retrofitting intelligent electronic devices into 1990s-era substations demands site-specific engineering without standardized mounting or communication backplanes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Switchgear Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Circuit Breakers, Disconnector Switches, Fuse Gear, Protection Relays End User: Utilities, Industrial Sector, Commercial Buildings, Renewable Energy Installation Type: Indoor, Outdoor, Wall-mounted, Portable Technology: Digital, Analog, Hybrid, Smart |
| Companies Covered | SHANDONG KAICHUAN POWER EQUIPMENT COMPANY LTD, CHINT Group Co., Ltd., Pinggao Group Co., Ltd., ABB (China) Ltd., Siemens (China) Co., Ltd., Schneider Electric (China) Co., Ltd., Zhejiang Gangheng Electric Company Limited, XD Electric, Xuji Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Switchgear Market Trends and Innovations
Solid-state power electronics are compressing mechanical interruption cycles while regulatory pressure on SF6 intensifies material substitution timelines. Procurement specifications now embed digital condition-monitoring as standard rather than optional.
Distributed solid-state circuit protection is decentralizing fault-clearing authority from centralized substations to load-side power distribution units. Hyperscale data center operators in Jiangsu and Zhejiang provinces are specifying these modules for 10kV and 35kV indoor assemblies. The shift compresses arc-flash incident energy ratings while reducing maintenance cycles for mechanical contacts.
MIIT's electromagnetic compatibility and arc-fault containment GB standards are tightening type-test requirements for new switchgear certifications. Manufacturers must demonstrate digital protocol interoperability and thermal withstand under standardized fault conditions. Medium-voltage indoor assemblies face the steepest compliance redesign burden as provincial utilities align procurement with the updated framework.
Buyer specifications now unbundle hardware procurement from lifecycle service contracts, forcing manufacturers to compete on upfront capital cost while utilities self-perform or third-party maintenance. State Grid Corporation of China and Southern Power Grid are piloting this model in Guangdong and Shandong substation tenders. The compression of service revenue streams pressures margin structures for standard-voltage product lines.
China Switchgear Market Segmentation
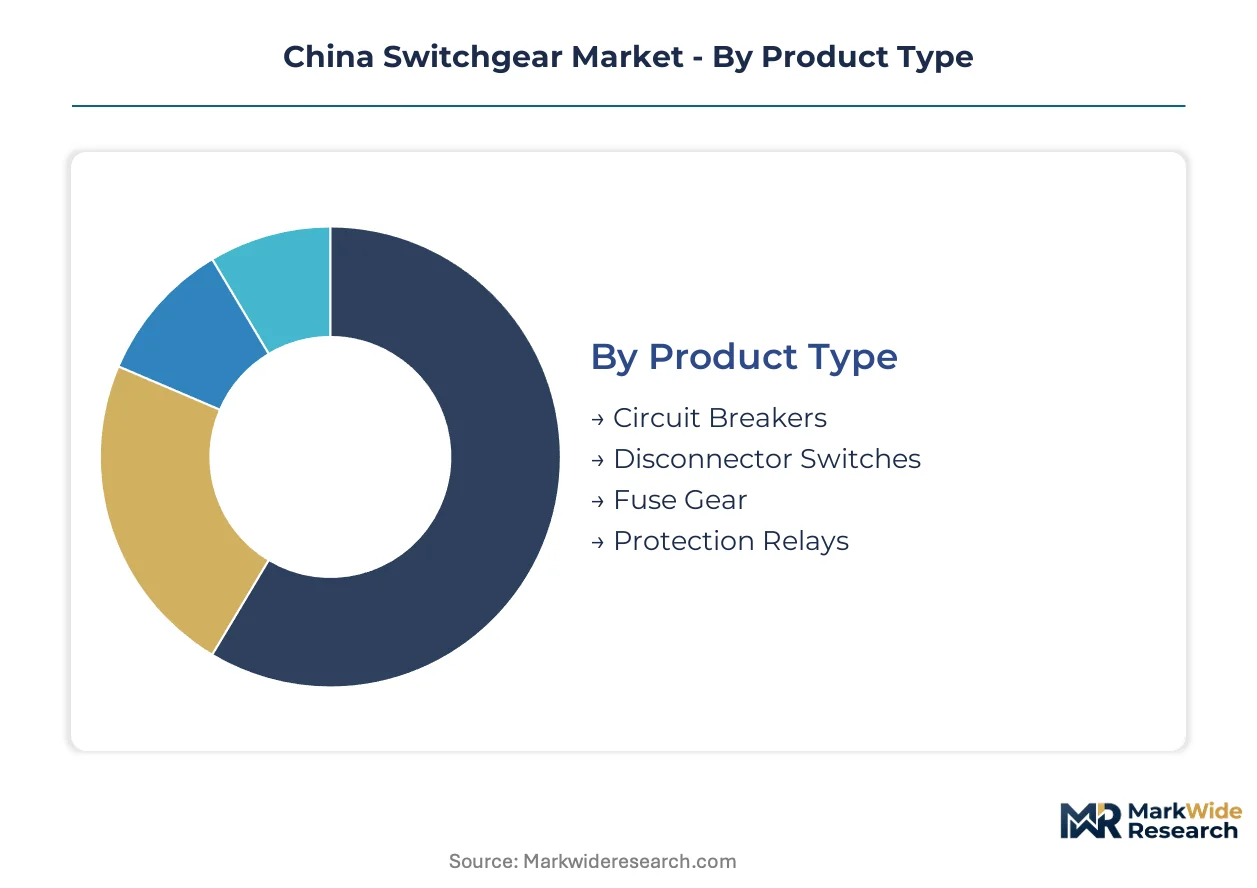
Segmentation in the China switchgear market reveals how procurement priorities diverge across voltage tiers, end-use applications, and technology readiness levels. Each dimension carries distinct upgrade-cycle timing and regulatory compliance burdens that reshape supplier positioning.
Product Type:
Replacement cycles for electromechanical components are compressing as MIIT's GB standards force digital interoperability upgrades across provincial utility fleets.
- Circuit Breakers:These fault-current interruption devices employ SF6, vacuum, or air as arc-quenching media, with contact-wear maintenance cycles driving recurring revenue. Demand concentrates in Yangtze River Delta data center substations where higher-rated indoor assemblies face compressed lead times.
- Protection Relays:Firmware-customized intelligent electronic devices with IEC 61850 protocol stacks command concentrated margins due to certification barriers and specialized engineering talent scarcity at state research institutes.
- Disconnector Switches:Mechanical isolators rated for visible-break safety in maintenance procedures.
- Fuse Gear:Overcurrent protection assemblies with sacrificial element replacement cycles.
Circuit breakers sit at the top of the volume ranking, with protection relays climbing the fastest.
End User:
Customer procurement sophistication varies sharply, with state-backed utilities demanding lifecycle service unbundling while commercial buyers prioritize upfront capital cost.
- Utilities:State Grid Corporation of China and Southern Power Grid pilot hardware-service separation in Guangdong and Shandong tenders, compressing manufacturer margin structures on standard-voltage lines.
- Industrial Sector:Heavy manufacturing facilities in Jiangsu and Zhejiang provinces specify integrated monitoring for predictive maintenance.
- Commercial Buildings:Standard-voltage panel procurement dominates this price-sensitive segment.
- Renewable Energy:Solar and wind farm interconnection demands vacuum interrupter designs to satisfy dual carbon compliance.
Utilities anchor the revenue base, with renewable energy expanding most quickly.
Installation Type:
Physical deployment constraints dictate material selection and environmental sealing requirements across China's climatic zones.
- Indoor:Gas-insulated assemblies with integrated digital monitoring face steep demand from hyperscale data center operators in Shanghai, Jiangsu, and Zhejiang provinces.
- Outdoor:Weather-resistant enclosures for transmission substations in western provinces.
- Wall-mounted:Space-constrained commercial and light industrial distribution panels.
- Portable:Temporary power infrastructure for construction and emergency response.
Indoor configurations dominate value capture, with outdoor installations gaining share in grid extension projects.
Technology:
Regulatory pressure on SF6 gas management and electromagnetic compatibility is accelerating material and protocol transitions.
- Digital:IEC 61850-compatible intelligent electronic devices with condition-based monitoring capabilities face mandatory adoption timelines under MIIT interoperability mandates.
- Smart:Converged power electronics with solid-state actuation enable arc-less switching for data center power distribution units in Jiangsu and Zhejiang.
- Analog:Legacy electromechanical protection facing replacement pressure from GB standard compliance deadlines.
- Hybrid:Transitional architectures blending mechanical interruption with digital monitoring overlays.
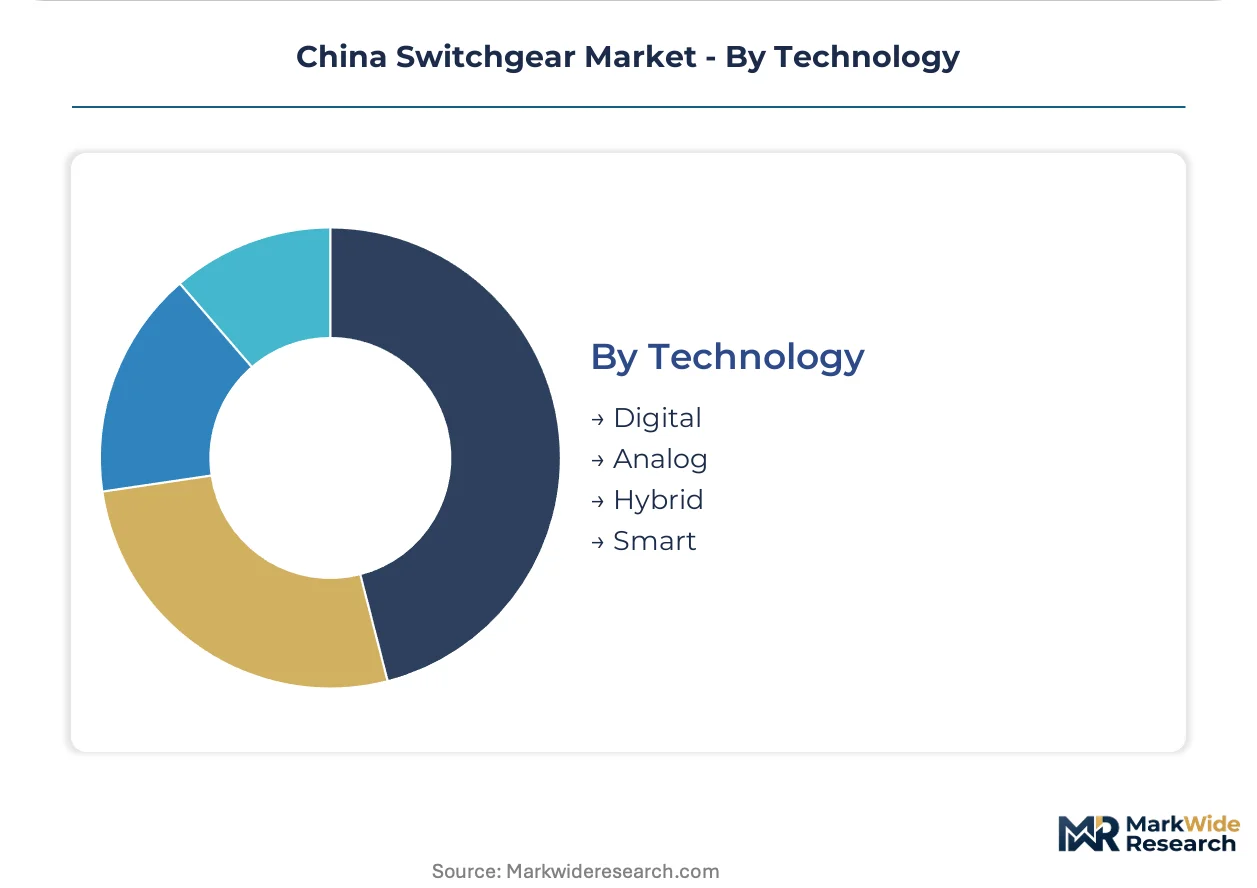
Digital technology holds the largest installed base, with smart systems showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration within China tracks the cost-of-compliance gap between coastal digital-mandate zones and western provinces with legacy analog fleets. Manufacturers relocate assembly capacity to exploit these regulatory arbitrage windows.
Yangtze River Delta
Shanghai, Jiangsu, and Zhejiang provinces concentrate hyperscale data center construction, forcing compressed lead times for higher-rated indoor gas-insulated assemblies. MIIT's GB electromagnetic compatibility standards mandate digital interoperability retrofits across provincial utility fleets. The Suzhou-Wuxi corridor anchors vacuum interrupter sourcing for 35kV indoor switchgear modules.
Pearl River Delta
Guangdong province pilots hardware-service unbundling in State Grid and Southern Power Grid tenders, compressing manufacturer margin structures. SAMR's mandatory product certification gates market access for imported assemblies through Shenzhen port-of-entry protocols. The Guangzhou-Dongguan manufacturing belt concentrates smart switchgear final assembly for Southeast Asian export.
Beijing-Tianjin-Hebei
State-backed utility procurement channels anchor ultra-high-voltage product demand through XD Electric's state-grid relationships. MEE-aligned dual carbon enforcement accelerates SF6 phase-down trajectories in new substation installations. The Tianjin Binhai New Area hosts gas-insulated system testing facilities serving northern corridor transmission projects.
Sichuan-Chongqing
Western grid modernization lags coastal digitalization rates, creating retrofit demand for IEC 61850-compatible intelligent electronic devices. Provincial green financing channels subsidize SF6-free substation upgrades in Chengdu metropolitan planning zones. The Chongqing Liangjiang New Area concentrates solid-state actuation prototyping for data center power distribution units.
Shandong Peninsula
Industrial heavy manufacturing facilities specify integrated monitoring for predictive maintenance across Jinan and Qingdao industrial parks. NMPA-aligned pressure-vessel rules impose handling certification requirements that favor state-backed incumbents with captive service networks. The Weifang-Yantai corridor hosts rare earth contact material processing for vacuum interrupter supply chains.
China Switchgear Market Competitive Landscape
Capacity expansion dominates the current landscape as domestic manufacturers scale vacuum interrupter foundries to capture SF6 substitution demand. The vendor base stratifies across three tiers: state-backed utility channel anchors, multinational technology licensors, and regional commercial panel specialists. Two strategic archetypes define positioning: scale-driven fabricators exploiting manufacturing cost advantages, and protocol-stack specialists capturing protection relay margins. Geographic expansion into western provinces and portfolio diversification toward solid-state modules represent the dominant competitive vectors.
Among domestic state-backed entities, XD Electric and CHINT Group Co., Ltd. exemplify divergent archetypes within the China switchgear competitive structure. XD Electric occupies a position anchoring ultra-high-voltage transmission relationships through state-grid procurement channels. CHINT Group Co., Ltd. represents scale-driven commercial segment penetration leveraging domestic manufacturing footprint. Siemens (China) Co., Ltd. sits within the multinational technology tier, exemplifying gas-insulated system positioning for urban substation applications. These three entities collectively illustrate the competitive tension between state-backed domestic consolidation and multinational technology licensing models.
| Leading Market Players |
|---|
| SHANDONG KAICHUAN POWER EQUIPMENT COMPANY LTD |
| CHINT Group Co., Ltd. |
| Pinggao Group Co., Ltd. |
| ABB (China) Ltd. |
| Siemens (China) Co., Ltd. |
| Schneider Electric (China) Co., Ltd. |
| Zhejiang Gangheng Electric Company Limited |
| XD Electric |
| Xuji Group |
| Others |
Pricing and Supply Chain Analysis
Dual carbon goals and NMPA-aligned pressure-vessel regulations gate qualified supply for SF6-free switchgear assemblies while segmenting pricing access across premium vacuum interrupter tiers and standard commercial panels. Procurement specifications from State Grid Corporation of China and Southern Power Grid unbundle hardware from lifecycle services, compressing channel margins and forcing manufacturers to compete on upfront capital cost.
Pricing Analysis
Distributor margins in the Yangtze River Delta cluster compress as hyperscale data center operators negotiate direct procurement contracts for higher-rated indoor gas-insulated assemblies. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under MIIT's GB electromagnetic compatibility standards and volume scale. Cost compression in standard-voltage commercial panels intensifies because copper and rare earth contact material volatility swings with commodity markets. Commercial building buyers exhibit the highest price sensitivity, while provincial utilities absorbing digital interoperability mandates show greater tolerance for premium-tier pricing.
Supply Chain Analysis
SAMR mandatory product certification gates component sourcing for imported assemblies through Shenzhen port-of-entry protocols, favoring domestic vacuum interrupter foundries. Manufacturing concentrates in China, with South Korea and Japan anchoring specialized solid-state power electronics feedstock for data center power distribution units. Raw material dependencies center on copper contact alloys, rare earth magnetic materials, and epoxy resin insulation systems. Single-source vulnerability in IEC 61850 firmware engineering talent concentrated at state research institutes threatens protection relay production scaling. Distribution runs through state-backed utility procurement channels and regional commercial panel distributors serving industrial facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's switchgear market reads as a late-cycle quality story as MIIT's GB standards force replacement cycles toward IEC 61850-compatible intelligent electronic devices with embedded condition-monitoring capabilities.
For Market Incumbents: Anchor ultra-high-voltage transmission relationships through state-grid procurement channels while accelerating vacuum interrupter foundry capacity to capture SF6 substitution demand. Threat from solid-state power electronics convergence demands R&D investment in arc-less switching modules for data center applications. Vertical integration into rare earth contact material processing secures margin control against commodity volatility. For New Entrants and Emerging Players: Enter via western province grid modernization in Sichuan and Shaanxi, where digitalization rates lag coastal benchmarks and retrofit demand for intelligent electronic devices remains underpenetrated. Target solid-state actuation prototyping for 10kV and 35kV data center power distribution units in the Chongqing Liangjiang New Area. Go-to-market leverage rests on IEC 61850 firmware customization partnerships with state research institutes. For Investors and Strategic Acquirers: Roll-up economics work for regional commercial panel specialists because SAMR certification barriers and NMPA pressure-vessel compliance favor scaled incumbents with captive service networks. Long-term viability centers on manufacturers with backward integration into vacuum interrupter production and demonstrated MIIT GB standard compliance. Signal to monitor: provincial green financing channel disbursement rates for SF6-free substation upgrades.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum Interrupter Production | Captive supply of SF6-free interruption media secures margin control against NMPA gas management compliance costs. |
| IEC 61850 Firmware Certification Investment | MIIT-mandated digital protocol interoperability creates barrier against analog relay competitors in provincial utility tenders. |
| Western Province Distribution Expansion | Sichuan and Shaanxi grid modernization lags coastal digitalization rates, creating retrofit demand arbitrage. |
| Solid-State Actuation R&D Partnership | Convergence with power electronics enables arc-less switching specifications from Jiangsu and Zhejiang data center operators. |
| Lifecycle Service Contract Unbundling | State Grid and Southern Power Grid pilot models compress manufacturer margins but open third-party maintenance revenue pools. |
Research Methodology
Multiple input streams — primary interviews with utility planning officers, switchgear procurement managers, and MIIT standardization committee members, alongside secondary validation — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged plant engineers at vacuum interrupter foundries, aftermarket service heads at state-backed incumbents, and EPC contractors for data center substation projects. Secondary sources included SAMR certification databases, MIIT GB standard publication records, State Grid Corporation tender disclosures, and provincial utility procurement bulletins.
Historical capacity utilization patterns were cross-referenced against panel input from utility procurement managers and hyperscale data center operators to construct demand trajectories across the projection horizon. Segmentation dimensions modeled encompass voltage tier, installation type, end-use application, and technology readiness level. CAGRs were derived from installed base replacement timing under MIIT compliance deadlines and green financing channel penetration rates for SF6-free upgrades.
Inputs from SAMR certification registries and provincial tender databases were available through the study window; gaps in solid-state actuation prototype commercialization timelines introduce uncertainty bands around smart technology adoption curves. Forecasts reflect assumptions regarding MIIT enforcement consistency and dual carbon policy continuity. A model refresh is warranted upon material change in NMPA pressure-vessel regulation stringency or rare earth export control regimes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Australia and New Zealand Medium Voltage Switchgear Market
Switches
Carrier Router Switch Market
Switches
Proximity Switches Market
Switches
Reed Switch Market
Switches
UAE Switchgear Market
Switches
Optical Switches Market
Switches
High-Voltage Disconnect Switch Market
Switches
Micro Switch Market
Switches
Pad-Mounted Switchgear Market
Switches
Oil Level Switches Market
Switches
Solid State Relay Market
Switches
Outdoor Boundary Vacuum Load Switch Market
Switches
Mexico Rocker Switch Market
Switches
Asia Pacific Transfer Switches Market
Switches
Global Safety Switches Market
Switches
Global High Voltage Switchgear Market