
 Smart Junction Box and Power Distribution Box Systems Market | 2026-2036
Smart Junction Box and Power Distribution Box Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Junction Box and Power Distribution Box Systems Market Insights
Project finance and long-term service leasing for grid infrastructure is rewriting competitive dynamics in power distribution hardware. Eaton leverages its integrated electrical portfolio to anchor utility-scale contracts across North America. Yazaki Corporation specializes in automotive-derived junction box architectures that it extends into industrial power distribution. Littelfuse competes through fuse and circuit protection expertise that it positions within smart monitoring ecosystems.
Smart junction box and power distribution box systems comprise enclosed electrical enclosures housing busbars, terminal blocks, protective devices, and communication modules rated typically from 600V to 38kV, designed to route, protect, and monitor electrical power flows across multiple downstream circuits. Their primary purpose centers on enabling centralized control, fault isolation, and real-time condition monitoring in complex electrical networks. IoT-enabled and smart sensor technologies are capturing the fastest expansion as utilities demand predictive maintenance capabilities, while junction boxes and power distribution boxes remain the volume foundation where margin pools concentrate in certified high-reliability variants. Residential automation and data center applications are outpacing industrial plant deployment in growth velocity.
The Federal Energy Regulatory Commission in the United States and the EU Green Deal framework in Europe are mandating grid resilience standards and carbon disclosure requirements that reshape product certification and procurement criteria for electrical infrastructure. China's National Energy Administration enforces smart grid integration protocols that dictate communication compatibility in distribution equipment. Stakeholders must monitor how evolving cybersecurity mandates for critical infrastructure intersect with hardware procurement decisions.
Market Dynamics
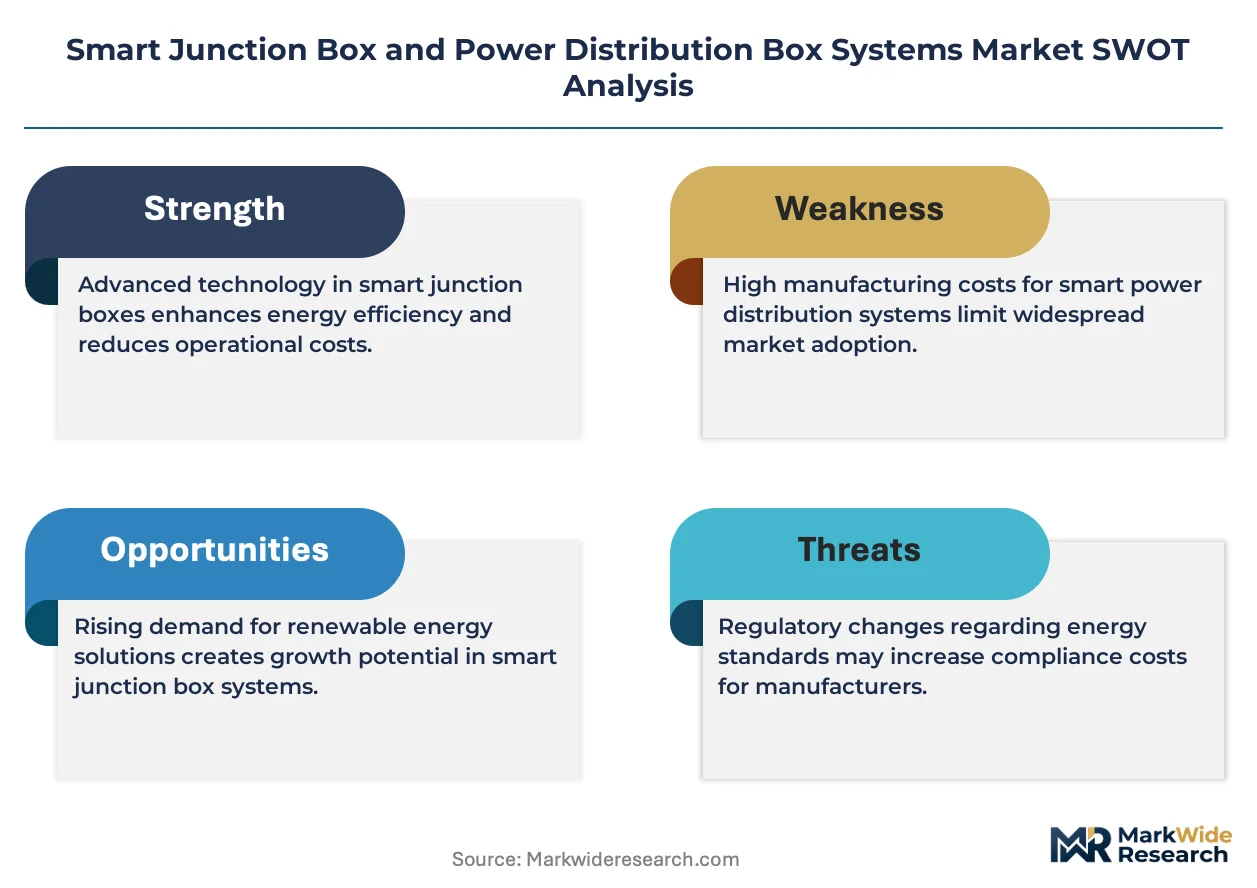
Grid digitization mandates are compressing replacement cycles for legacy distribution hardware as utilities face simultaneous pressure from renewable integration targets and cybersecurity hardening requirements.
Growth Catalysts
- EU Green Deal carbon disclosure:Germany and France enforce net-zero procurement standards that accelerate utility infrastructure refresh programs. Distribution operators must source certified low-carbon equipment for federal contracts.
- IoT sensor convergence:Predictive maintenance algorithms embedded in junction boxes reduce outage downtime. Electric utilities in China and India deploy these modules at scale across urban distribution networks.
- FERC resilience mandates:The Federal Energy Regulatory Commission requires fault isolation capabilities in critical infrastructure. US utilities upgrade substation and feeder-level distribution boxes to meet hardened grid standards.
Market Restraints
- Copper and aluminum price volatility:Busbar raw material costs swing with commodity markets. Manufacturers face margin compression when hedging strategies fail to anticipate LME price spikes.
- Semiconductor supply concentration:Communication module chipsets depend on concentrated East Asian foundry capacity. Lead times for industrial-grade microcontrollers extend procurement cycles unpredictably.
- Legacy IEC 61439 certification friction:Existing product lines require expensive retesting for smart variants. Smaller fabricators lack capital to maintain parallel certified and non-certified production lines.
Strategic Opportunities
- India rural electrification gaps:Unelectrified villages and agricultural feeders need modular, solar-compatible distribution boxes. State distribution companies tender for containerized smart junction units.
- Data center power density escalation:Hyperscale facilities demand 38kV-rated distribution with real-time thermal monitoring. Colocation operators in Virginia and Frankfurt specify these architectures.
- China dual carbon policy incentives:The National Energy Administration subsidizes smart grid equipment procurement. State Grid Corporation accelerates AMI-compatible distribution box deployment in coastal provinces.
Industry Challenges
- Cybersecurity certification bottlenecks:IEC 62443 industrial security standards require specialized testing labs. Hardware vendors queue months for accredited third-party validation.
- Legacy SCADA protocol fragmentation:Proprietary communication stacks in installed base impede seamless smart box integration. Utilities face costly middleware development or rip-and-replace decisions.
- Field engineering skill scarcity:Technicians trained in both high-voltage safety and network configuration remain scarce. Training programs at German and US technical institutes cannot scale to demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Junction Box and Power Distribution Box Systems Market |
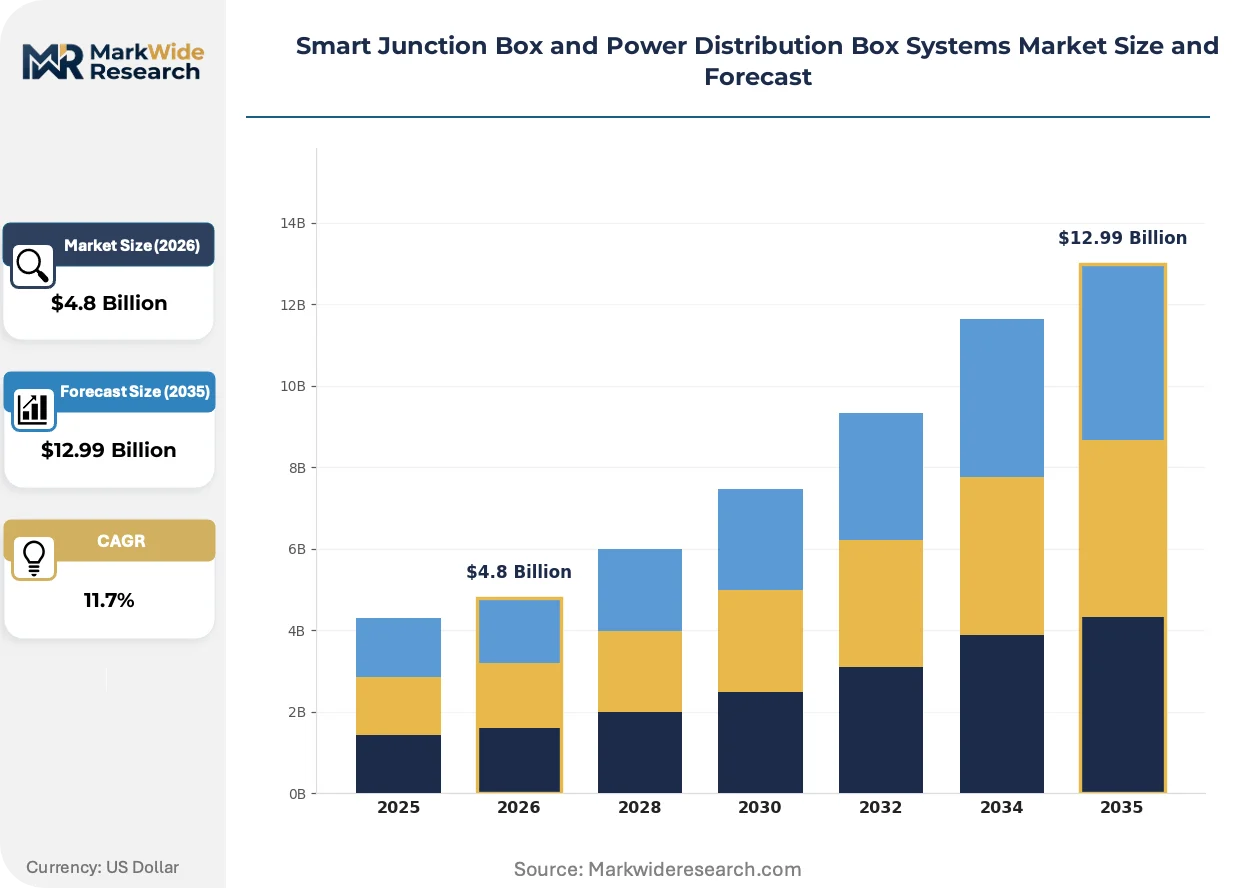
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
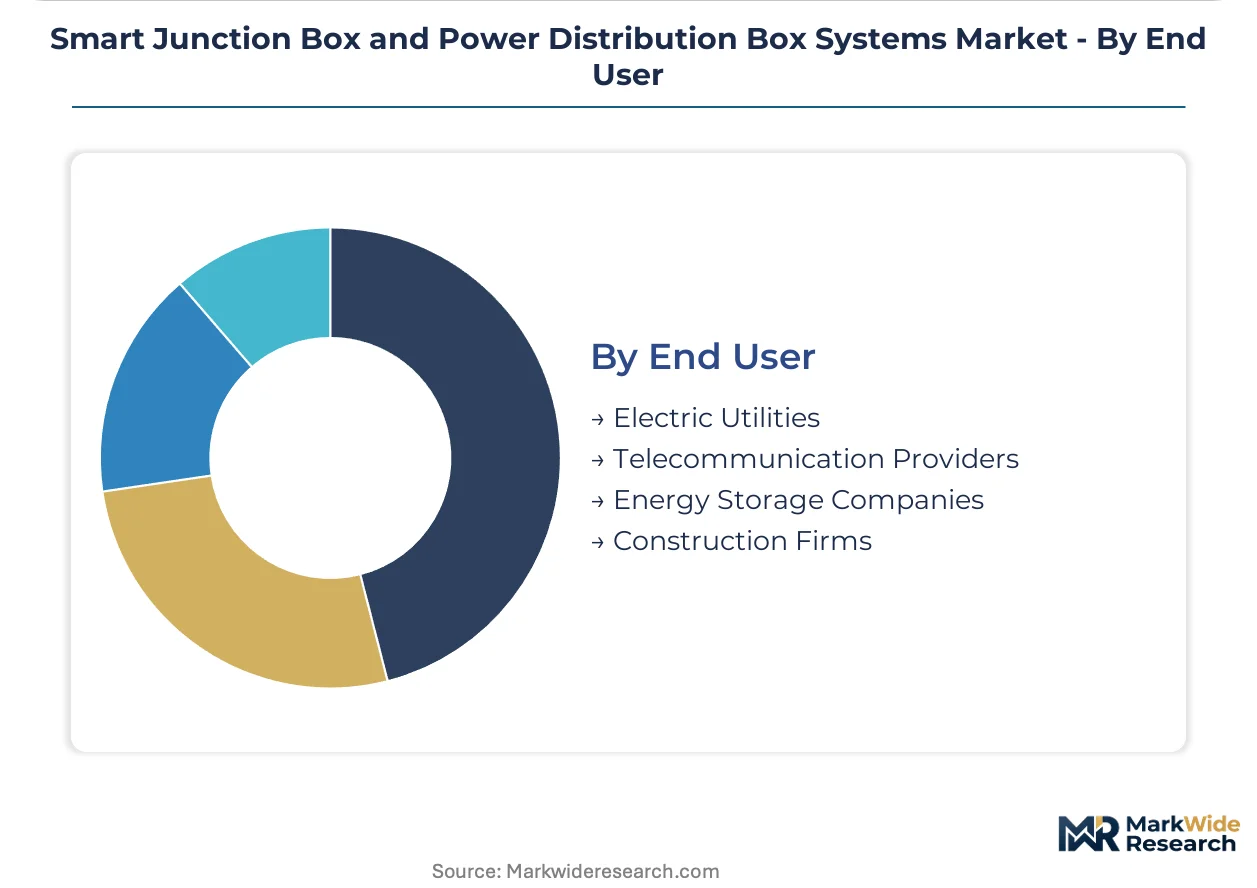
| Segmentation | Product Type: Junction Boxes, Power Distribution Boxes, Fuse Boxes, Circuit Protection Panels, Relay Boxes Technology: IoT Enabled, Wireless Communication, Overcurrent Protection, Smart Sensors, Remote Monitoring Application: Residential Automation, Data Centers, Commercial Buildings, Renewable Energy Systems, Industrial Plants End User: Electric Utilities, Telecommunication Providers, Energy Storage Companies, Construction Firms |
| Companies Covered | Aptiv, FORVIA HELLA, Littelfuse, Robert Bosch, TE Connectivity, Molex, Eaton, Lear Corporation, Yazaki Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Junction Box and Power Distribution Box Systems Market Trends and Innovations
Digital twin architectures and edge computing are collapsing the latency between grid event detection and protective action, redefining performance benchmarks for distribution hardware.
Silicon carbide power semiconductors are digitizing protection response times in medium-voltage distribution boxes. Data center operators and renewable interconnection projects specify these devices for sub-cycle fault clearing. The technology compresses arc flash incident energy exposure while enabling higher power density enclosures.
China's National Energy Administration enforces GB/T 36572 smart grid communication protocols that mandate interoperability testing for distribution equipment. Domestic manufacturers must certify against these standards for State Grid tenders. Foreign suppliers face extended homologation timelines to achieve protocol compliance.
Utility procurement departments now unbundle hardware purchase from decade-long service agreements. North American municipal utilities and European distribution system operators negotiate performance-based maintenance contracts separately from capital equipment acquisition. This bifurcation pressures traditional manufacturers to build service capabilities or cede margin to specialized integrators.
Smart Junction Box and Power Distribution Box Systems Market Segmentation
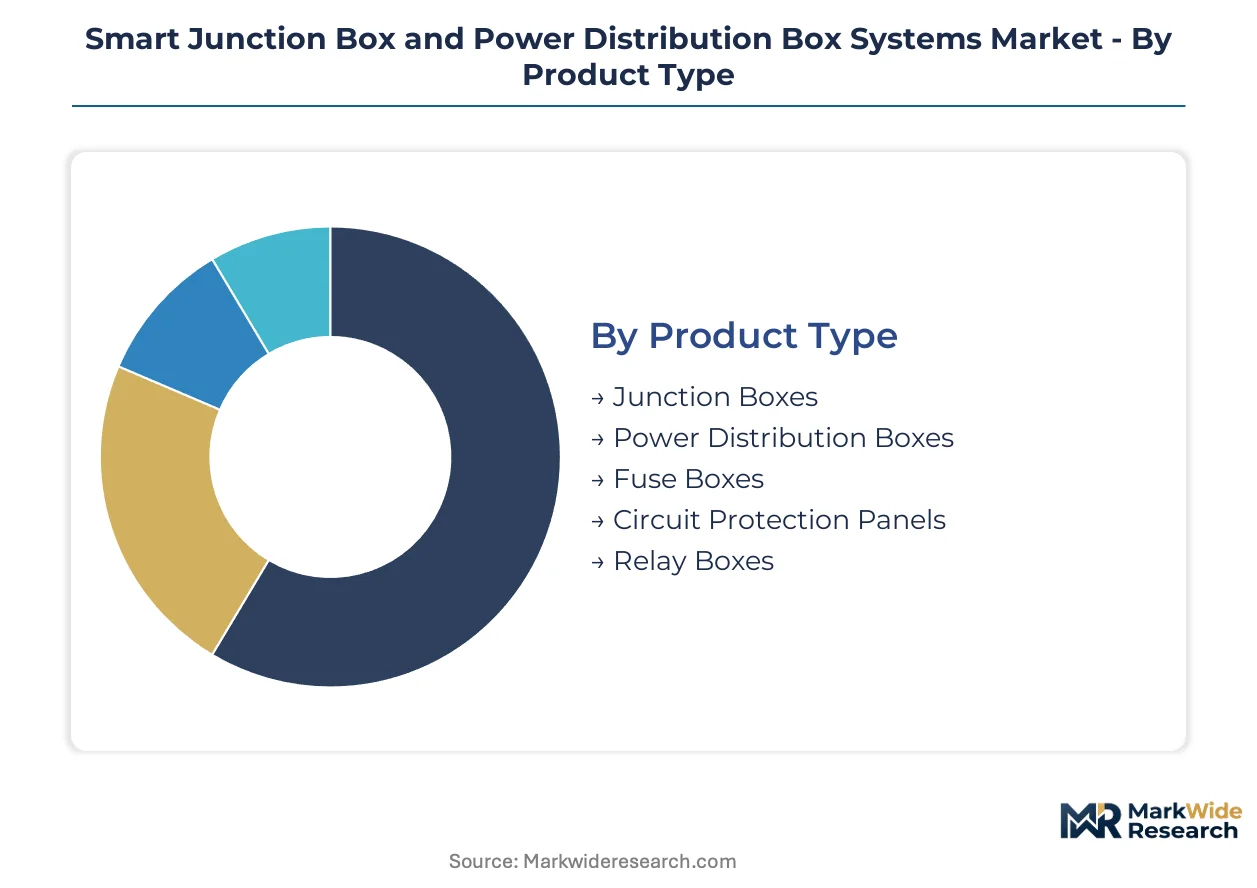
Segmentation in this market reveals how hardware specifications diverge across voltage classes, communication protocols, and environmental ratings. Procurement patterns differ sharply between utilities seeking hardened substation equipment and data center operators prioritizing thermal monitoring precision.
Product Type:
Mature fused enclosures dominate installed base volumes while smart variants with integrated monitoring reshape replacement economics.
- Junction Boxes:Enclosed housings rated 600V to 38kV route power through busbar assemblies and terminal blocks. Electric utilities in Germany and China specify these for urban distribution networks where space constraints demand compact form factors.
- Power Distribution Boxes:Modular enclosures with multiple feeder outputs and integrated protective devices. Data center operators in Virginia and Frankfurt procure 38kV-rated units with real-time thermal monitoring as power densities escalate beyond 50kW per rack.
- Fuse Boxes:Traditional overcurrent protection assemblies using fusible links. Agricultural electrification projects in India specify these for cost-sensitive rural feeder installations.
- Circuit Protection Panels:Molded case circuit breaker assemblies with selective coordination capabilities. Commercial building retrofit programs across France favor these for compliance with updated electrical safety codes.
- Relay Boxes:Electromechanical and solid-state switching enclosures for automated control sequences. Industrial plants in the United States deploy these for motor control center integration.
Junction boxes retain volume leadership; power distribution boxes hold the steepest expansion curve.
Technology:
Cost tiers separate basic protection functions from predictive maintenance capabilities that command premium pricing.
- IoT Enabled:Embedded communication modules supporting AMI and SCADA integration. State Grid Corporation in China mandates these for coastal province tenders under dual carbon policy incentives.
- Wireless Communication:Cellular and mesh radio protocols eliminating hardwired telemetry runs. Remote monitoring in Indian agricultural feeders relies on these where trenching costs prove prohibitive.
- Overcurrent Protection:Conventional thermal-magnetic and electronic trip units. Legacy infrastructure across the United States continues specifying these for FERC-mandated fault isolation upgrades.
- Smart Sensors:Temperature, humidity, and partial discharge monitors with edge analytics. Predictive maintenance algorithms embedded in these modules reduce outage downtime for urban utilities.
- Remote Monitoring:Cloud-connected diagnostic platforms with mobile operator interfaces. European distribution system operators unbundle these service capabilities from hardware procurement under performance-based contracts.
Overcurrent protection retains volume leadership; IoT-enabled architectures hold the steepest expansion curve.
Application:
Application patterns track electrification intensity, with digital infrastructure and building automation outpacing heavy industrial deployment.
- Residential Automation:Low-voltage distribution panels with smart home protocol gateways. New construction in Germany integrates these for EU Green Deal carbon disclosure compliance.
- Data Centers:High-density power distribution with silicon carbide protection and liquid cooling compatibility. Hyperscale facilities in Virginia specify 38kV-rated architectures with sub-cycle fault clearing.
- Commercial Buildings:Tenant submetering and load management panels. France enforces net-zero procurement standards that accelerate infrastructure refresh in federal buildings.
- Renewable Energy Systems:Solar and wind interconnection boxes with anti-islanding protection. China's National Energy Administration subsidizes smart grid equipment procurement for these installations.
- Industrial Plants:Motor control centers and process power distribution. Legacy SCADA protocol fragmentation impedes seamless smart box integration in these environments.
Industrial plants retain volume leadership; data centers hold the steepest expansion curve.
End User:
Customer type determines procurement sophistication, from standardized utility tenders to customized industrial specifications.
- Electric Utilities:Transmission and distribution operators with centralized procurement departments. FERC resilience mandates in the United States require fault isolation capabilities in critical infrastructure.
- Telecommunication Providers:Edge computing facilities and 5G base station power systems. These operators specify compact outdoor-rated distribution for network densification.
- Energy Storage Companies:Battery system integrators requiring bidirectional power flow management. Containerized smart junction units serve these applications in India rural electrification gaps.
- Construction Firms:General contractors and electrical subcontractors on commercial and residential projects. Field engineering skill scarcity constrains deployment velocity for these buyers.
Electric utilities retain volume leadership; energy storage companies hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal carbon disclosure requirements and China's dual carbon policy subsidies are redirecting procurement budgets toward certified smart grid equipment across major electrification markets.
United States
FERC resilience mandates and data center power density escalation drive demand for fault-isolation-capable distribution hardware. The Infrastructure Investment and Jobs Act channels federal funding toward grid modernization. Northern Virginia's hyperscale cluster specifies 38kV-rated units with sub-cycle fault clearing for colocation facilities.
Germany
Net-zero procurement standards and industrial automation retrofit cycles compress replacement timelines for distribution infrastructure. The country's national energy regulator enforces updated electrical safety codes for commercial building compliance. Bavaria's automotive supplier corridor deploys smart junction boxes for factory electrification upgrades.
China
State Grid Corporation's AMI-compatible tender requirements and coastal province smart grid subsidies accelerate IoT-enabled equipment deployment. The National Energy Administration mandates GB/T 36572 protocol compliance for distribution equipment certification. The Yangtze River Delta manufacturing belt concentrates domestic production capacity for export-grade units.
India
Rural electrification gaps and agricultural feeder modernization create demand for modular solar-compatible distribution boxes. The Central Electricity Authority promotes containerized smart junction units for state distribution company tenders. Maharashtra's industrial corridor and Gujarat's solar parks anchor deployment concentration for grid-tied installations.
France
Net-zero mandates for federal building infrastructure and commercial retrofit incentives reshape procurement criteria for electrical distribution hardware. The EU Green Deal framework imposes carbon disclosure requirements on public contracts. The Île-de-France data center cluster and Auvergne-Rhône-Alpes industrial belt specify certified low-carbon equipment for new installations.
Smart Junction Box and Power Distribution Box Systems Market Competitive Landscape
On the supply side, the industry is consolidating around integrated electrical portfolios and specialized protection expertise rather than pure-play hardware fabrication. Tiered competitive positioning separates full-system integrators from component specialists and regional fabricators. Strategic archetypes include diversified industrial conglomerates with captive utility relationships, automotive-derived electrical specialists extending into power distribution, and fuse-circuit protection pure-plays embedding monitoring capabilities. Dominant competitive moves encompass strategic partnerships for smart grid protocol certification and portfolio diversification into service-based revenue models.
Among diversified industrial players, Eaton anchors utility-scale contract positioning across North America through its integrated electrical portfolio. Yazaki Corporation represents the automotive-to-industrial extension archetype, leveraging junction box architectures developed for vehicle electrical systems. Littelfuse occupies the protection-specialist tier, embedding fuse and circuit expertise within broader monitoring ecosystems.
| Leading Market Players |
|---|
| Aptiv |
| FORVIA HELLA |
| Littelfuse |
| Robert Bosch |
| TE Connectivity |
| Molex |
| Eaton |
| Lear Corporation |
| Yazaki Corporation |
| Others |
Pricing and Supply Chain Analysis
Copper and aluminum commodity volatility determines both tier spreads and supply chain configuration for busbar-dependent manufacturers. Raw material hedging failures compress margins in standard-grade enclosures while certified high-reliability variants retain pricing power through captive sourcing agreements.
Pricing Analysis
Certification level creates the primary spread between IEC 61439-compliant premium units and uncertified economy alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects differential testing costs and smart sensor integration depth. Cost compression in standard enclosures intensifies because Chinese state grid tenders prioritize lowest-compliant-bid procurement. Agricultural electrification projects in India exhibit highest price sensitivity; data center operators in Virginia demonstrate lowest sensitivity due to uptime-value calculations.
Supply Chain Analysis
Export controls on industrial-grade microcontroller chipsets limit communication module flows from concentrated East Asian foundries. Manufacturing draws from China, Germany, and Mexico for enclosure fabrication. Raw material inputs center on copper busbar, aluminum extrusion, and silicon carbide semiconductors. Single-source vulnerability concentrates in semiconductor supply. Distribution runs through utility procurement departments, EPC contractors, and specialized electrical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Performance-based maintenance contracts now expand faster than hardware sales as European distribution system operators unbundle service capabilities from capital equipment acquisition.
For Market Incumbents: Pre-empt margin erosion in standard-grade enclosures by anchoring captive utility relationships through integrated electrical portfolios. Backward integration into busbar casting secures cost position against LME volatility. Certification investment in IEC 62443 cybersecurity standards defends premium tier access against automotive-derived entrants. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point given fragmented local supply and accelerating EU Green Deal-aligned retrofit mandates. Containerized solar-compatible distribution boxes for Indian agricultural feeders offer second white-space target. Channel partnership with state distribution companies provides lowest-friction go-to-market path. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors protection-specialist pure-plays with embedded monitoring capabilities. Five-to-ten year viability hinges on service revenue attachment rates exceeding hardware replacement cycles. Acquisition target archetype: fuse-circuit protection specialists with smart sensor integration roadmaps. Watch State Grid tender protocol shifts as inflection indicator for Chinese market access.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Grid Protocol Certification | GB/T 36572 compliance unlocks State Grid Corporation tenders in coastal provinces. |
| Performance-Based Service Contracting | Decade-long maintenance agreements separate revenue from hardware replacement cycles. |
| Silicon Carbide Protection Integration | Sub-cycle fault clearing meets hyperscale data center power density requirements. |
| Cybersecurity Certification Investment | IEC 62443 validation clears queue bottlenecks for critical infrastructure procurement. |
| Backward Integration into Busbars | Captive copper-aluminum supply hedges against commodity volatility in standard tiers. |
Research Methodology
Cross-validation between utility procurement officer interviews and FERC regulatory filing analysis anchors the qualitative findings. Primary fieldwork engaged grid planning directors, electrical distributor category managers, EPC contractor procurement leads, and smart grid integration specialists. Secondary sources encompassed EIA infrastructure investment data, IEC standard committee documentation, State Grid tender announcements, and customs records for electrical enclosure trade flows. Bottom-up unit economics triangulated against top-down utility capex projections.
Calibration against historical replacement cycle data and announced grid modernization budgets shaped the analytical framework across the analysis window. Segmentation dimensions modeled include voltage rating tier, communication protocol type, application environment, and end-user procurement sophistication. CAGRs derived from slope-intercept fitting of disclosed utility investment trajectories and equipment vendor revenue disclosures. Forecast inputs incorporated copper LME futures curves and semiconductor lead time indices.
Macroeconomic conditions sit as an overlay; deviation in utility borrowing costs and construction commodity indices would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and technology substitution elasticities. Material shifts in FERC resilience mandate implementation schedules or EU Green Deal procurement penalty structures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
BCD Power IC Market
Power Systems
Distribution Voltage Regulator Market
Power Systems
Power Electronics Market
Power Systems
PV Micro Inverters Market
Power Systems
Space DC-DC Converters Market
Power Systems
Saudi Arabia Vacuum Pressure Impregnated (VPI) Transformer Market
Power Systems
Solid-State Relay and Fuse Box Component Platforms Market
Power Systems
Thyristor Surge Protectors Market
Power Systems
Photovoltaic Inverters Market
Power Systems
Charge Controller System Market
Power Systems
Power Diode Market
Power Systems
Asia Pacific Battery Management System Market
Power Systems
Global Chip Power Inductor Market
Power Systems
String Inverter Market
Power Systems
MCR Based Static VAR Compensator Market
Power Systems
Switch Mode Power Supply (SMPS) Market