
 Low Code Development Platform Market | 2026-2036
Low Code Development Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Low Code Development Platform Market Intelligence
The citizen developer is collapsing the traditional distinction between IT departments and business units, accelerating digital transformation initiatives. Microsoft leverages its extensive Azure cloud infrastructure and Office 365 integration to promote its Power Platform. Salesforce dominates the ecosystem for customer-facing applications built on its core CRM. OutSystems specializes in high-performance applications for complex enterprise process automation.
A low code development platform provides a visual environment for creating software applications through graphical user interfaces and configuration instead of traditional hand-coding. These platforms abstract complex programming languages to accelerate the delivery of business applications. Cloud-based deployment models command the largest market share, offering scalability and reduced infrastructure overhead. Within solution types, process automation and core application development represent foundational use cases driving initial platform adoption.
Frameworks like the EU's GDPR and the US's HIPAA influence platform selection by requiring features that ensure data privacy and security by design. Compliance with these mandates drives demand for platforms that can rapidly update applications in response to changing rules. The central strategic decision for enterprises becomes how to balance centralized IT governance with the distributed innovation enabled by these tools.
Market Dynamics
The central dynamic is the push for business unit autonomy in application creation clashing with the need for centralized IT governance, a tension amplified by data privacy regulations like the EU's GDPR and the US's HIPAA.
Growth Catalysts
- Data Governance Mandates:Regulations like the EU's GDPR require that applications be adaptable to new privacy rules, driving demand for platforms that enable rapid, compliant updates without extensive recoding.
- Financial Services Agility:The banking, financial services, and insurance (BFSI) sector's need to accelerate digital product launches to compete with fintech startups propels adoption of low-code platforms for faster time-to-market.
- AI and ML Integration:The native integration of artificial intelligence and machine learning services into low-code platforms enables the creation of more sophisticated, data-driven business applications by non-specialist developers.
Market Restraints
- Vendor Lock-In Concerns:Deep investment in a single vendor's proprietary platform creates high switching costs and a dependency that can limit an enterprise's future architectural flexibility and negotiating power.
- Complex Pricing Models:Per-user, per-application, or consumption-based pricing structures can become prohibitively expensive at scale, creating budget uncertainty and hindering widespread adoption across large organizations.
- Threat of Substitution:Simple business use cases are increasingly served by more accessible no-code platforms, while highly complex, high-performance core systems still require traditional custom software development.
Strategic Opportunities
- SME Digitalization:Small and medium-sized enterprises in emerging economies, particularly in Southeast Asia, represent an underpenetrated segment for low-code tools as they pursue digital transformation initiatives.
- IoT Application Development:There is a significant opportunity in providing low-code tools specifically designed for building and managing Internet of Things (IoT) applications, bridging the gap between operational technology and business processes.
- Hyperautomation Convergence:Combining low-code platforms with Robotic Process Automation (RPA) and other intelligent automation technologies offers a path to creating comprehensive, end-to-end automated enterprise workflows.
Industry Challenges
- Fusion Team Skill Gaps:A scarcity of talent skilled in both business process knowledge and low-code platform capabilities inhibits the effectiveness of "fusion teams" intended to bridge IT and business units.
- Legacy System Integration:Integrating applications built on modern low-code platforms with decades-old legacy systems, such as mainframes in banking, presents significant technical and data synchronization challenges.
- Shadow IT Governance:The ease of creating applications by business users can lead to a proliferation of unmanaged "shadow IT," posing security, compliance, and data governance risks for the organization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Code Development Platform Market |
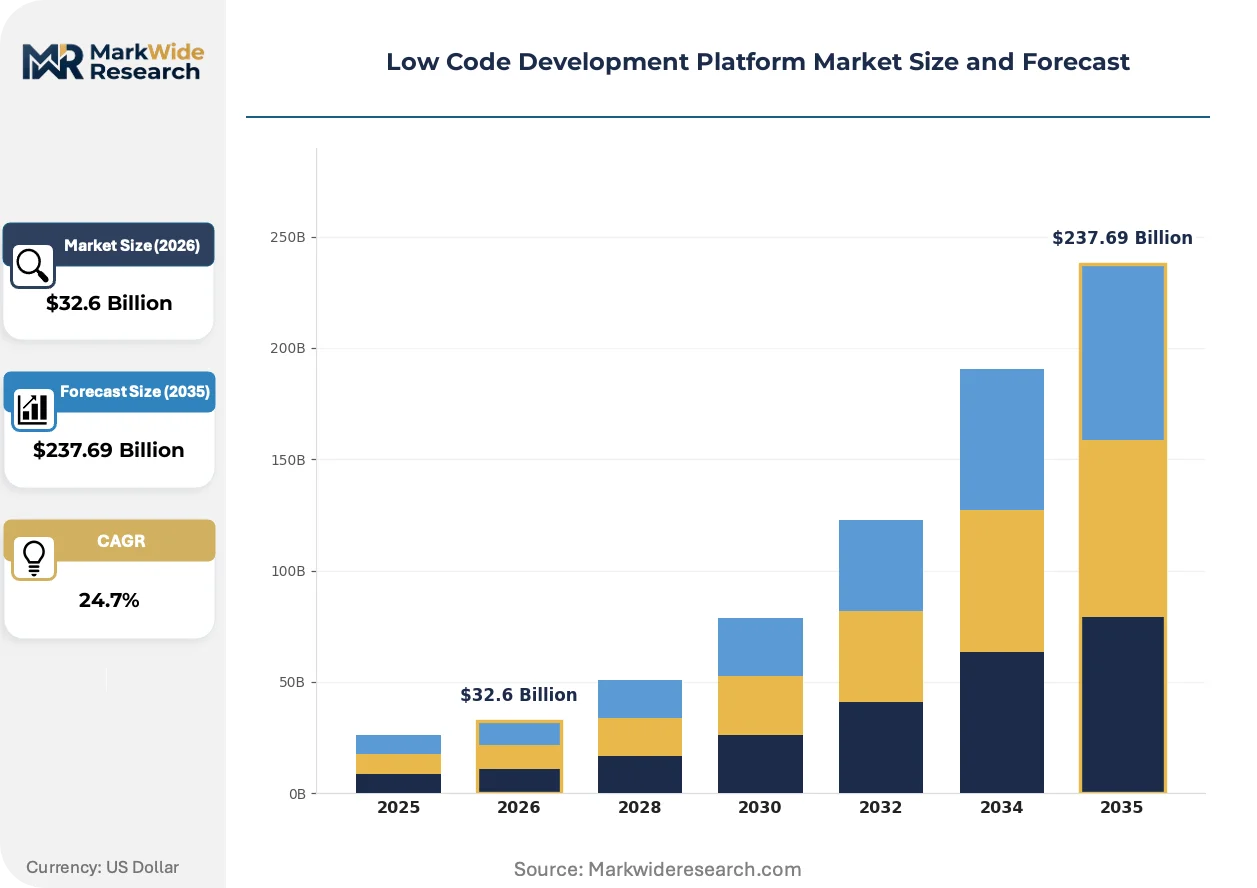
| Market Size in 2026 | $32.6 Billion |
| Market Size in 2035 | $237.69 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Virtual Private Cloud Solution Type: Process Automation, Application Development, Customer Experience, Integration Platform, Business Intelligence Application: Customer Relationship Management, Employee Onboarding, Supply Chain Automation, Financial Reporting, Human Capital Management End User Industry: Banking, Insurance, Telecommunications, Manufacturing, Government |
| Companies Covered | Microsoft Corporation, Salesforce.com Inc., OutSystems, Pegasystems Inc., Oracle Corporation, ServiceNow, Mendix Technology BV, Appian Corporation, Zoho Corporation Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Code Development Platform Market Strategic Shifts & Innovations
The industrialization of software development is the dominant theme, with platforms becoming standardized factories for producing business logic. This evolution prioritizes speed and accessibility while forcing new models for enterprise-wide governance and control over application portfolios.
Generative AI integration into low-code platforms enables creating application components from natural language prompts. Enterprise IT departments adopt these features to accelerate initial development cycles. This AI-assisted development is displacing the need for manual boilerplate coding and UI mockups, shortening the path from concept to prototype.
Regulations like India's Digital Personal Data Protection Bill (DPDPB) impose strict consent management and data fiduciary accountability requirements. This compels organizations to maintain auditable and rapidly modifiable applications to manage data processing. Platforms with embedded data governance features are becoming critical for regulated industries like healthcare and finance in the region.
A shift from monolithic platform acquisitions toward a composable enterprise approach is underway. Organizations now assemble a portfolio of specialized low-code tools for distinct tasks, rather than relying on a single vendor. This modular adoption strategy is most prominent within large North American enterprises aiming to mitigate vendor dependency.
Low Code Development Platform Market Segmentation
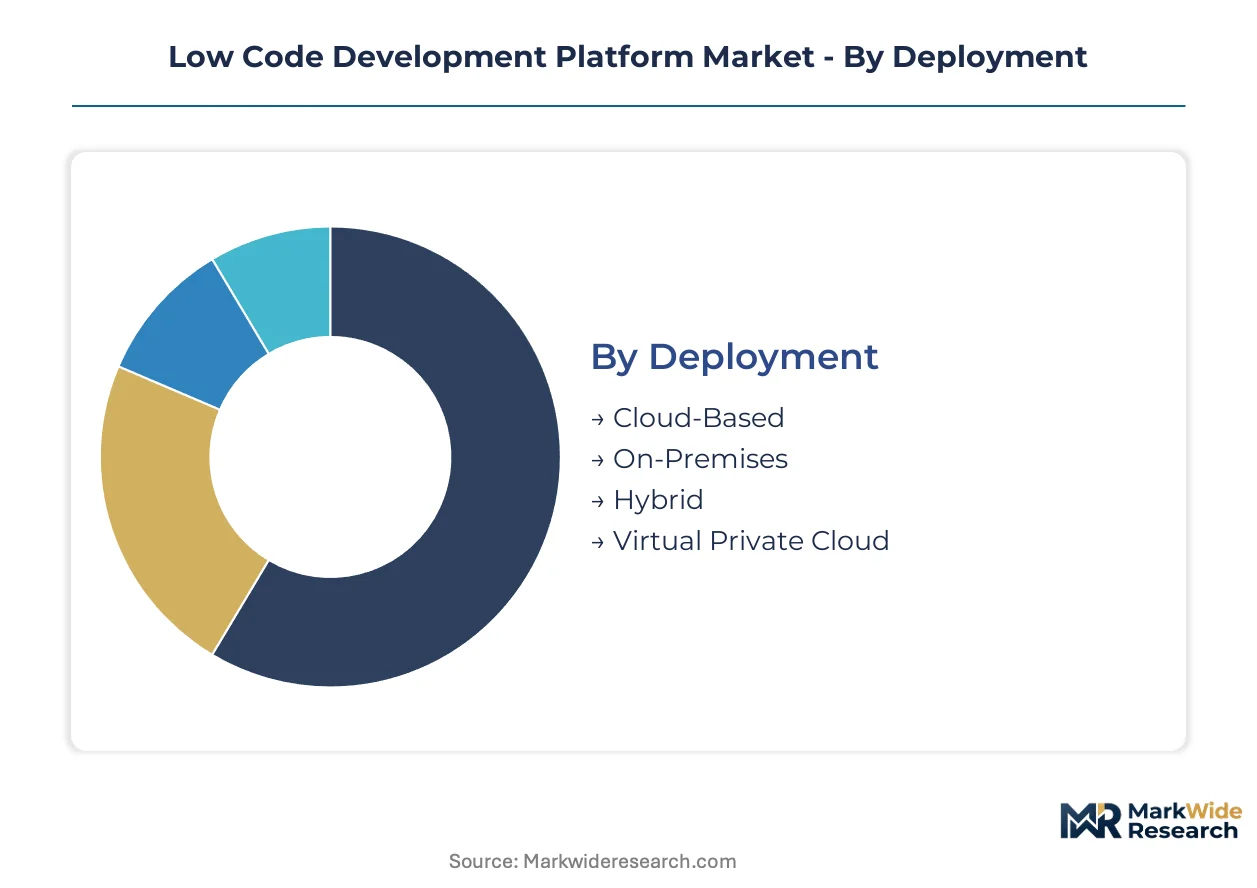
The Low Code Development Platform market segmentation reveals distinct value propositions across various operational and technological dimensions. Understanding these segments helps enterprises align platform capabilities with specific business objectives, optimizing resource allocation for digital transformation initiatives. Each category reflects unique adoption patterns and strategic investment areas for vendors.
Deployment:
Margin pools within the deployment category often reside in the flexibility and reduced infrastructure overhead offered by cloud-based and hybrid models.
- Cloud-Based:These platforms are hosted entirely on third-party cloud infrastructure, providing scalability, accessibility, and reduced upfront capital expenditure. Cloud-based deployments command the largest market share, driven by the need for agile development and rapid scaling across diverse user bases.
- Hybrid:Hybrid deployments combine elements of both cloud and on-premises infrastructure, allowing organizations to leverage cloud benefits while maintaining sensitive data on internal servers. This model appeals to regulated industries balancing innovation with strict data governance requirements like GDPR.
- On-Premises:On-premises solutions are installed and operated within an organization's own data centers, offering maximum control over data security and compliance. This deployment type is favored by highly regulated sectors with stringent data residency mandates.
- Virtual Private Cloud:A Virtual Private Cloud provides a logically isolated section of a public cloud, offering a secure and private cloud computing environment. Enterprises utilize this for enhanced security and network control within a public cloud framework.
The dominant share belongs to Cloud-Based, while Hybrid is closing the gap fastest.
Solution Type:
Application development and process automation solution types form the foundational use cases, attracting significant investment from enterprises seeking operational efficiencies.
- Application Development:This solution type focuses on building custom business applications from scratch using visual interfaces and pre-built components. Enterprises adopt these platforms to accelerate the delivery of line-of-business applications, reducing reliance on traditional coding.
- Process Automation:Low-code platforms enable the automation of repetitive business processes, streamlining workflows and improving operational efficiency. This includes tasks from data entry to complex multi-step approvals, driving significant productivity gains.
- Customer Experience:These solutions enhance customer interactions through the rapid development of portals, mobile apps, and personalized communication tools. Organizations leverage this to improve customer satisfaction and engagement.
- Integration Platform:Low-code integration platforms facilitate seamless connectivity between disparate systems and data sources without extensive coding. This addresses legacy system integration challenges for various industries.
- Business Intelligence:Solutions focused on business intelligence enable users to create dashboards and reports for data analysis and decision-making. These tools empower business users to gain insights from operational data.
Application Development solutions hold a substantial market presence, and Process Automation is experiencing rapid expansion.
Application:
Customer relationship management applications consistently drive demand for low-code platforms, followed by internal operational efficiencies.
- Customer Relationship Management:Low-code platforms facilitate the rapid customization and extension of CRM systems, enhancing customer-facing processes and data management. Salesforce's ecosystem exemplifies this demand for tailored customer applications.
- Supply Chain Automation:These applications streamline complex supply chain operations, from inventory management to logistics, improving efficiency and reducing operational costs. Organizations use low-code to build agile solutions for dynamic supply chain environments.
- Employee Onboarding:Low-code tools simplify and accelerate the employee onboarding process, automating tasks like document submission and access provisioning. This improves new hire experience and reduces administrative burden.
- Financial Reporting:Platforms assist in creating customized financial reporting tools, enabling businesses to generate accurate and timely financial statements. This supports compliance and internal decision-making.
- Human Capital Management:Low-code solutions support various HR functions, including performance management, talent acquisition, and employee self-service portals. These applications enhance HR operational effectiveness.
Customer Relationship Management applications capture a significant share, with Supply Chain Automation applications exhibiting strong growth.
End User Industry:
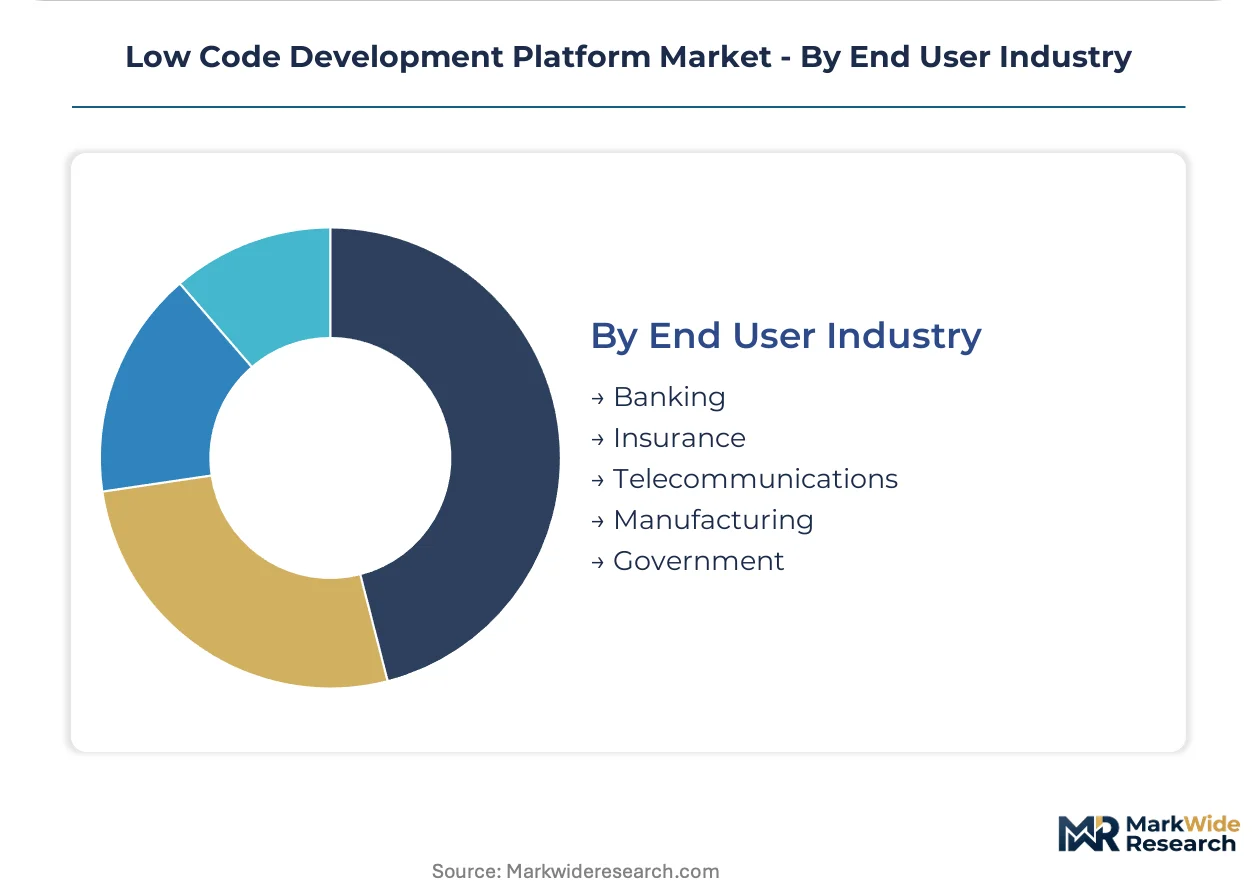
The banking, financial services, and insurance sector shows pronounced adoption due to its intense regulatory environment and need for digital product velocity.
- Banking:The banking sector leverages low-code platforms to accelerate digital product launches, modernize legacy systems, and enhance customer-facing applications. Financial services agility is a critical driver for platform adoption in this industry.
- Insurance:Insurance companies utilize low-code for developing new policy administration systems, automating claims processing, and improving agent and customer portals. Compliance with data governance mandates influences platform selection significantly.
- Telecommunications:Telecommunications firms employ low-code for developing customer service applications, network management tools, and billing system integrations. This supports rapid service deployment and customer engagement.
- Manufacturing:Manufacturers use low-code to build applications for production monitoring, quality control, and supply chain visibility. These tools enhance operational technology integration and efficiency.
- Government:Government agencies adopt low-code for public service delivery, internal process automation, and citizen engagement platforms. This facilitates digital transformation initiatives within public administration.
The Banking industry holds a substantial portion of the market, and the Insurance industry is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration for low-code platforms is evident across developed and emerging economies. Enterprises in Germany prioritize compliant application development within their robust software ecosystems. North American organizations focus on mitigating vendor dependency through composable enterprise strategies.
United States
United States enterprises prioritize rapid application delivery and integration with existing systems. HIPAA regulations significantly impact platform selection, demanding robust data privacy and security by design. Major tech hubs like Silicon Valley foster innovation, enabling the creation of advanced low-code tools for various sectors.
Germany
German businesses exhibit strong demand for low-code platforms to accelerate digital product launches. GDPR compliance is a primary driver, requiring adaptable applications for evolving privacy rules. Tech clusters in Munich and Berlin drive significant adoption within the automotive and financial services sectors.
India
Indian enterprises, especially SMEs, pursue digital transformation initiatives using low-code tools. The Digital Personal Data Protection Bill (DPDPB) mandates auditable and rapidly modifiable applications for data processing. Bengaluru and Hyderabad are key hubs for low-code innovation, supporting fintech and public sector applications.
Singapore
Singaporean organizations leverage low-code for comprehensive digitalization and smart nation projects. The Personal Data Protection Act (PDPA) guides platform selection, ensuring secure data handling and compliance. Singapore's urban innovation hubs actively integrate low-code tools for public services and IoT application development.
United Kingdom
United Kingdom businesses seek low-code platforms for financial services agility and public sector digital transformation. UK GDPR necessitates compliant and rapidly modifiable applications for data processing. London's financial technology ecosystem actively adopts low-code for developing innovative banking and insurance solutions.
Low Code Development Platform Market Key Industry Players
Player mix skews toward established enterprise software providers and specialized low-code platform vendors. The market exhibits a tiered structure, with a few dominant players alongside numerous niche solution providers addressing specific industry needs. Strategic archetypes include cloud infrastructure giants leveraging extensive ecosystems, CRM ecosystem leaders building on core platforms, and high-performance application specialists. Companies primarily engage in portfolio diversification and strategic partnerships to expand their market reach and integrate new technologies.
Cloud infrastructure giants like Microsoft Corporation leverage their extensive Azure cloud and Office 365 integration to promote their Power Platform, targeting broad enterprise adoption. Salesforce.com Inc. dominates the ecosystem for customer-facing applications, building on its core CRM capabilities and extending functionality through its AppExchange. Specialized high-performance application providers, exemplified by OutSystems, focus on complex enterprise process automation and mission-critical systems. These firms occupy distinct segments within the market, offering varied value propositions to enterprises seeking digital transformation tools and compliant application development.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Salesforce.com Inc. |
| OutSystems |
| Pegasystems Inc. |
| Oracle Corporation |
| ServiceNow |
| Mendix Technology BV |
| Appian Corporation |
| Zoho Corporation Pvt. Ltd. |
| Others |
Cost & Logistics Intelligence
GDPR and HIPAA compliance gates platform qualification, simultaneously influencing pricing models by demanding features that ensure data privacy and security by design.
Pricing Analysis
Cost-plus service contracts, often indexed to developer hours or project complexity, define a segment of low-code platform pricing. Subscription-based SaaS models with tiered features and per-user licensing dominate the market. Price differentiation stems from the level of customization, integration complexity with legacy systems, and the extent of after-sales support provided. Pricing softness reflects intense competition from no-code alternatives for simpler use cases. Small and medium-sized enterprises (SMEs) exhibit higher price sensitivity compared to large enterprises requiring mission-critical application development.
Supply Chain Analysis
The scarcity of specialized low-code development talent, particularly in fusion team capabilities, creates a significant chokepoint within the platform supply chain. Core dependencies include cloud infrastructure services from providers in the United States and Ireland, and advanced AI/ML models often sourced from innovation hubs in the US and Germany. Vendor lock-in represents a structural risk, limiting enterprise flexibility and increasing switching costs. Distribution channels primarily involve direct sales, strategic partnerships with system integrators, and cloud marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The low-code platform market presents a significant service-attach opportunity, with integration services and custom component development expanding faster than core platform subscriptions.
For Market Incumbents: Secure market share by deepening integration with generative AI capabilities and expanding cloud-native deployment options. Consolidate offerings to mitigate the threat of specialized no-code platforms encroaching on simpler business use cases. Invest in R&D for advanced data governance features to meet evolving regulatory demands. Enhance channel partner programs to extend reach into underpenetrated SME segments.
For New Entrants and Emerging Players: Lead with highly specialized low-code solutions targeting specific industry verticals or niche application types, such as IoT application development. Focus on providing simplified, transparent pricing models to attract price-sensitive small and medium-sized enterprises in emerging economies like Southeast Asia. Develop robust integration capabilities for legacy systems to address a persistent challenge for many organizations.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across core platform development, driven by the need for advanced AI integration and robust security features. Focus on acquiring specialized low-code platforms with strong vertical expertise or unique AI-driven development capabilities. The long-term viability hinges on platforms that can balance rapid innovation with stringent compliance requirements. A key signal to watch is the enterprise adoption rate of composable architecture models.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Seamless connectivity with enterprise systems enhances value proposition for large organizations. |
| Strategic Partnership | Collaborating with cloud providers expands market reach and leverages existing infrastructure ecosystems. |
| Acquisition of Specialist Firm | Gaining niche expertise accelerates time-to-market for targeted industry solutions. |
| Generative AI Product Launch | Introducing AI-assisted development features streamlines application creation for citizen developers. |
| Geographic Expansion | Entering emerging economies like India taps into growing demand for digital transformation tools. |
Research Approach
Initial hypotheses were tested against primary input from CTOs, IT procurement officers, and business unit leads, then refined through iterative processes. This involved extensive interviews with platform engineers and channel partners across diverse geographies. Secondary validation leveraged SEC filings, cloud provider reports, industry analyst publications, and academic research on software development trends. Bottom-up and top-down triangulation ensured data consistency and accuracy.
Variance-decomposition analysis disaggregated market growth drivers across deployment models, solution types, and end-user industries over the projection horizon. The analytical framework also modeled application dimensions, such as customer relationship management and supply chain automation, to capture granular market dynamics. Compound annual growth rates were derived from historical growth trends and projected market penetration rates. Key forecast inputs included enterprise IT spending trends and evolving regulatory compliance requirements.
Forecasts assume regulatory continuity in GDPR, HIPAA, and DPDPB regimes; material policy shifts would require re-modeling market trajectories. The analysis acknowledges potential disruptions from rapid advancements in generative AI capabilities and unforeseen global economic downturns. Practitioners should keep alternative scenarios live as enterprise digital transformation priorities and AI capabilities evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
On-Call Scheduling Software Market
Software & Services
Global Quantum Computing Software Market
Software & Services
Global Data Integration and Integrity Software Market
Software & Services
United Arab Emirates (UAE) Cloud Accounting Software Market
Software & Services
Global Online Form Builder Software Market
Software & Services
RIP Color Management Software Market
Software & Services
Open Source Bug Tracking Tool Market
Software & Services
Asia-Pacific Communication Platform-As-A-Service Market
Software & Services
E-Invoicing Software Market
Software & Services
Load Testing Software Market
Software & Services
Website Translation Software Market
Software & Services
Europe Saas-Based SCM Market
Software & Services
Graphical User Interface (GUI) Design Software Market
Software & Services
Collaborative Office Software Market
Software & Services
Online Project Management Software Market
Software & Services
Expense Management Software Market