
 Vehicle Embedded Software Market | 2026-2036
Vehicle Embedded Software Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Embedded Software Market Intelligence
Software-defined vehicle architectures is reconfiguring how automakers partition compute between centralized domains and edge controllers. Robert Bosch GmbH leverages its cross-domain software platform to anchor development across powertrain and chassis systems. Continental AG competes through its intensive R&D allocation toward automated driving middleware stacks. NXP Semiconductors specializes in automotive-grade processor ecosystems that sustain real-time deterministic performance for safety-critical functions.
Vehicle embedded software comprises the programmable instruction sets, real-time operating environments, and middleware layers that govern electronic control unit behavior across powertrain, chassis, body, and cockpit domains. These systems execute with deterministic latency thresholds, typically sub-millisecond for braking and steering functions, enabling closed-loop control of electromechanical actuators in production automobiles. Application software for driver assistance systems commands the dominant margin pool as Level 2+ automation proliferates across mass-market vehicle programs. Firmware layers governing functional safety loops represent the fastest-expanding segment, driven by ISO 26262 ASIL-D compliance requirements and over-the-air update architectures. End-user concentration among tier-1 suppliers persists, though OEMs are building captive software competencies to reduce dependency on external integration houses.
The EU AI Act, ISO 26262, and UNECE WP.29 cybersecurity regulations are reshaping embedded software validation protocols, mandating traceable development lifecycles and intrusion detection capabilities as market-access preconditions. NHTSA guidelines in the United States and MIIT standards in China impose parallel functional safety and data governance obligations on suppliers targeting those markets. Stakeholders must monitor regulatory divergence across jurisdictions to determine whether unified software platforms or region-specific compliance variants offer superior engineering economics.
Market Dynamics
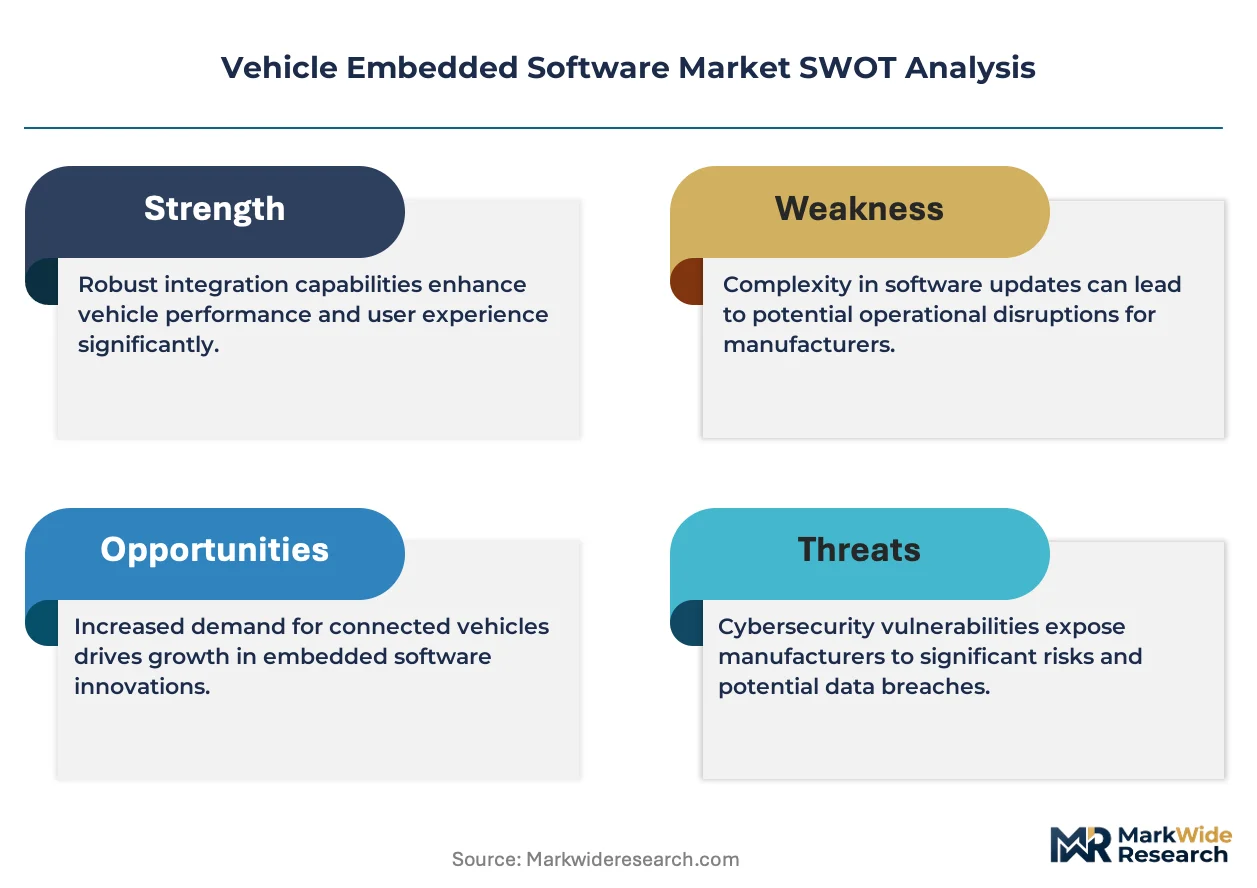
Centralized compute architectures are forcing tier-1 suppliers to restructure software delivery models around domain controllers rather than distributed ECU programming.
Growth Catalysts
- ISO 26262 ASIL-D mandates:Functional safety certification requirements across Europe and North America are expanding validation service demand.
- Over-the-air update penetration:Firmware refresh capabilities in electric vehicle platforms are creating recurring revenue streams for middleware providers.
- China's MIIT cybersecurity standards:Domestic OEMs are accelerating embedded security module procurement to meet type-approval requirements.
Market Restraints
- Silicon supply concentration:Automotive-grade microcontroller availability remains constrained by foundry capacity allocation in Taiwan.
- EU AI Act compliance costs:Conformity assessment procedures for autonomous driving algorithms are extending development timelines.
- Functional safety talent scarcity:Certified systems engineers command premium compensation that compresses supplier margins.
Strategic Opportunities
- Software-defined vehicle platforms:Unified operating environments spanning powertrain and cockpit domains enable cross-functional feature bundling.
- India's automotive PLI scheme:Domestic electronics manufacturing incentives are attracting embedded software development centers to Bangalore and Pune.
- Digital twin integration:Virtual ECU validation environments are compressing hardware-in-the-loop testing cycles before physical prototyping.
Industry Challenges
- Legacy powertrain code migration:Decades of proprietary engine control algorithms resist porting to zonal architectures without functional regression.
- Multi-standard certification stacking:Simultaneous ISO 26262, UNECE WP.29, and NHTSA compliance creates documentation burden.
- Real-time deterministic guarantees:Mixed-criticality workloads on shared processors require formal verification methods that extend release schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Embedded Software Market |
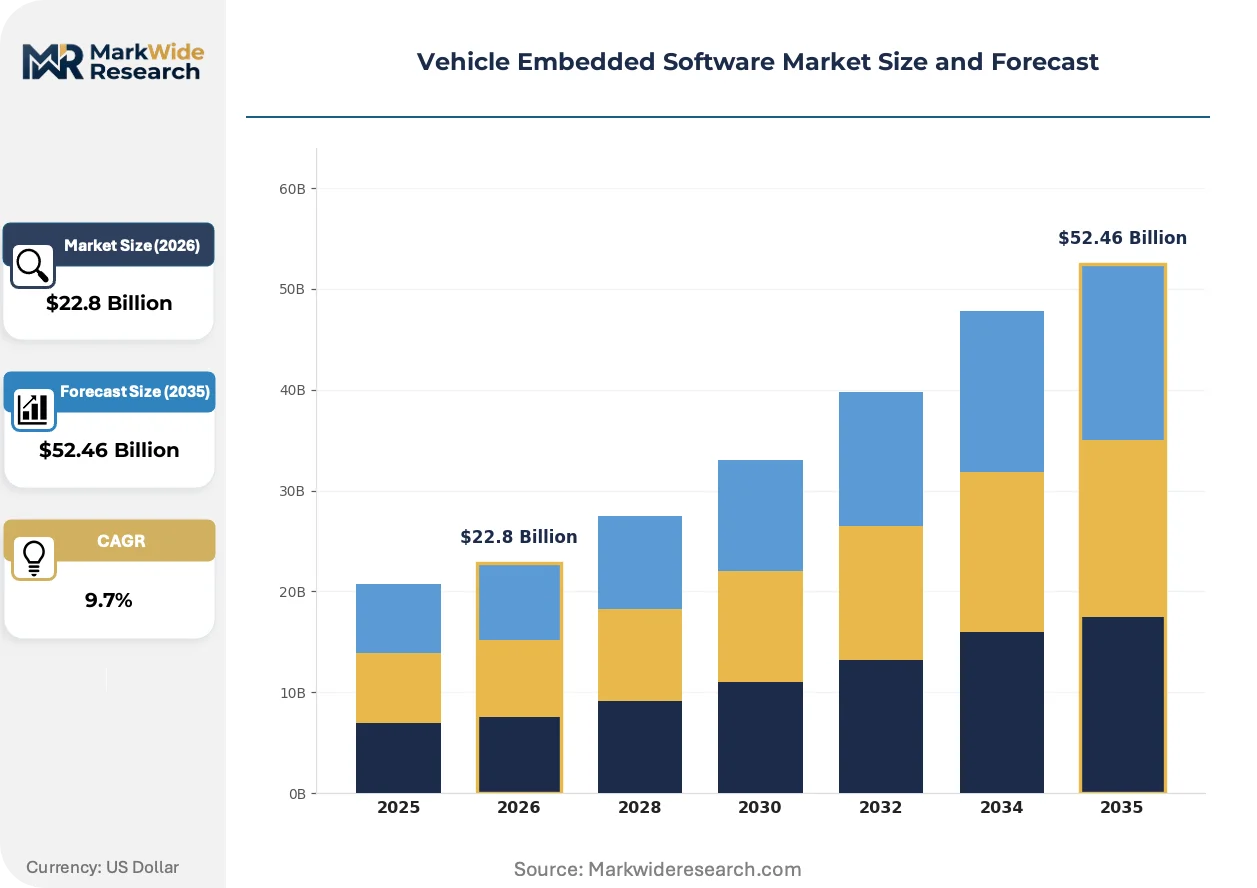
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $52.46 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Operating System, Middleware, Application Software, Firmware Technology: Embedded C, C++, Python, Real-Time Operating Systems End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Fleet Operators Application: Driver Assistance Systems, Infotainment, Telematics, Safety Features |
| Companies Covered | Robert Bosch GmbH, Continental AG, Denso Corporation, NXP Semiconductors, Renesas Electronics Corporation, Infineon Technologies AG, Harman International, Aptiv PLC, Texas Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Embedded Software Market Strategic Shifts & Innovations
Deterministic middleware stacks are displacing bespoke ECU firmware as automakers consolidate compute around high-performance system-on-chips.
Automotive-grade hypervisors are partitioning safety-critical and infotainment workloads onto shared multicore processors. Tier-1 suppliers are deploying these virtualization layers across domain controller programs to reduce hardware bill-of-materials. This consolidation is digitizing vehicle electrical architectures from federated ECU networks toward centralized compute pools.
UNECE WP.29 cybersecurity regulations are mandating intrusion detection systems and secure boot capabilities as market-access preconditions. Suppliers must demonstrate tamper-evident logging and over-the-air update authentication across entire vehicle fleets. European OEMs are responding fastest, embedding hardware security modules into gateway controllers ahead of North American and Asian competitors.
Long-term service contracts are displacing perpetual software licenses as OEMs seek predictable lifecycle costs. Tier-1 integrators are bundling middleware maintenance, cybersecurity patches, and feature updates into subscription structures. This shift is most advanced in Germany, where premium manufacturers negotiate decade-long software support agreements aligned with vehicle platform lifecycles.
Vehicle Embedded Software Market Segmentation
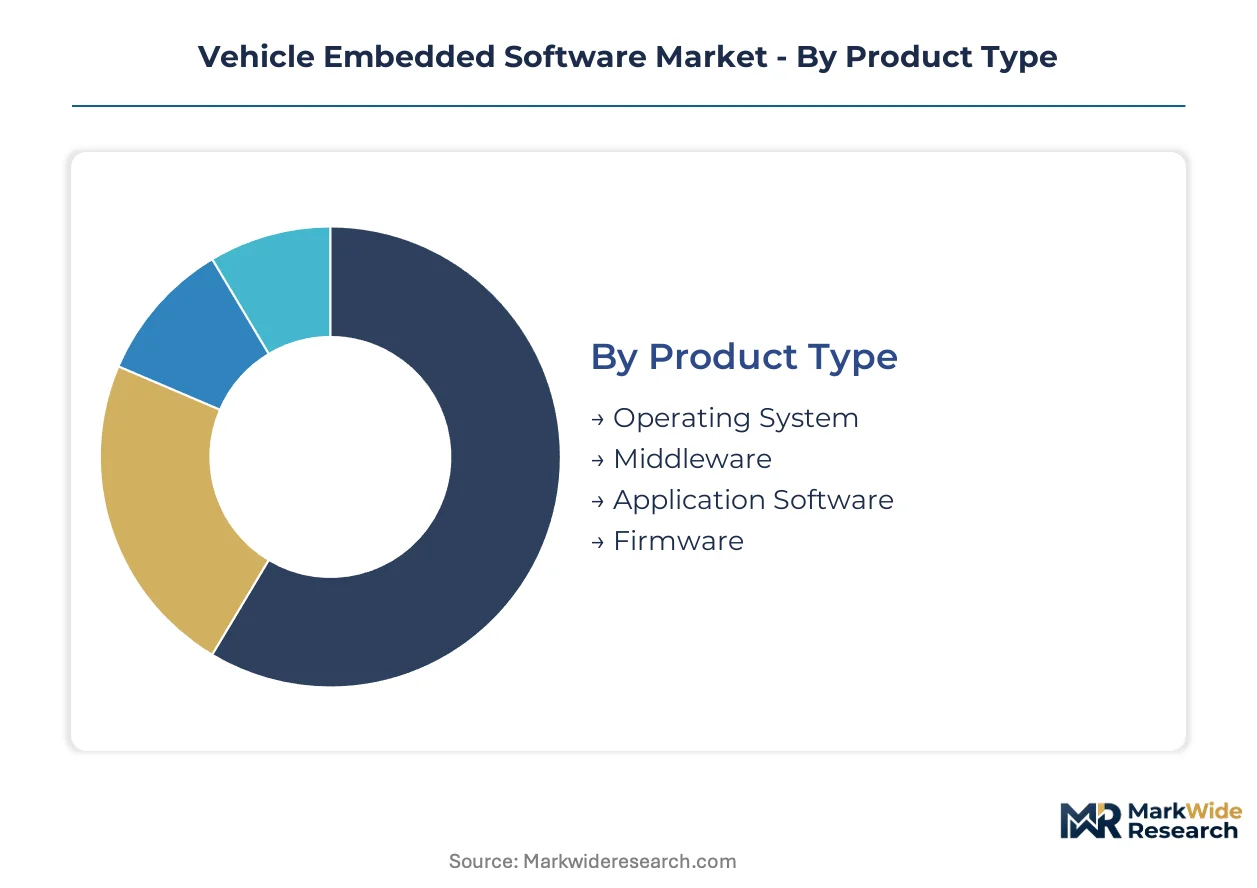
Vehicle embedded software segmentation reveals how architectural complexity fragments procurement decisions across automotive value chains. Each dimension—product layer, programming environment, customer type, and functional domain—carries distinct margin profiles and certification requirements that reshape supplier competitive positioning.
Product Type:
Cost tiers stratify sharply between foundational infrastructure and value-added application layers.
- Operating System:Automotive-grade OS kernels provide hardware abstraction and task scheduling for multicore processors. Real-time deterministic guarantees under ISO 26262 ASIL-D requirements concentrate procurement among German premium OEMs building zonal architectures. The dominant share belongs to Operating System, while Application Software is closing the gap fastest.
- Middleware:Communication stacks and data routing layers bridge heterogeneous ECU networks. Tier-1 suppliers in Stuttgart and Munich source these components to enable over-the-air update pipelines across electric vehicle fleets.
- Application Software:Feature-rich modules execute domain-specific functions from adaptive cruise control to battery thermal management.
- Firmware:Low-level instruction sets govern boot sequences and hardware initialization with minimal overhead.
Application Software captures the widest margin spread, though Firmware commands premium pricing for safety-critical certifications.
Technology:
Maturity gradients separate legacy codebases from modern development frameworks.
- Embedded C:Proven efficiency for resource-constrained microcontrollers with deterministic execution. Dominant in powertrain control modules where decades of validated algorithms resist migration. Embedded C maintains installed base leadership, while Python is climbing fastest among AI/ML validation workflows.
- C++:Object-oriented constructs enable complex state machines for automated driving stacks. German engineering centers favor this language for AUTOSAR Adaptive Platform implementations.
- Python:Rapid prototyping and machine learning integration accelerate algorithm development before hardware deployment.
- Real-Time Operating Systems:Deterministic scheduling kernels from vendors like QNX and Green Hills partition safety-critical workloads.
Embedded C still underpins the majority of production ECUs, though C++ is gaining fastest in new domain controller programs.
End User:
Supply chain position dictates software ownership models and integration depth.
- OEMs:Captive development centers in Germany and China are internalizing strategic software competencies. Volkswagen Group and BMW negotiate direct middleware licenses to reduce tier-1 dependency. OEMs control the largest procurement volume, while Fleet Operators are expanding fastest as mobility-as-a-service scales.
- Tier-1 Suppliers:Bosch, Continental, and ZF Friedrichshafen aggregate cross-OEM demand through reusable platform architectures.
- Aftermarket Providers:Diagnostic tools and retrofit modules serve vehicle aging populations outside warranty coverage.
- Fleet Operators:Commercial vehicle aggregators procure telematics and predictive maintenance software at enterprise scale.
Tier-1 Suppliers still intermediate the majority of embedded software transactions, though direct OEM procurement is accelerating most quickly.
Application:
Functional criticality determines certification burden and pricing power.
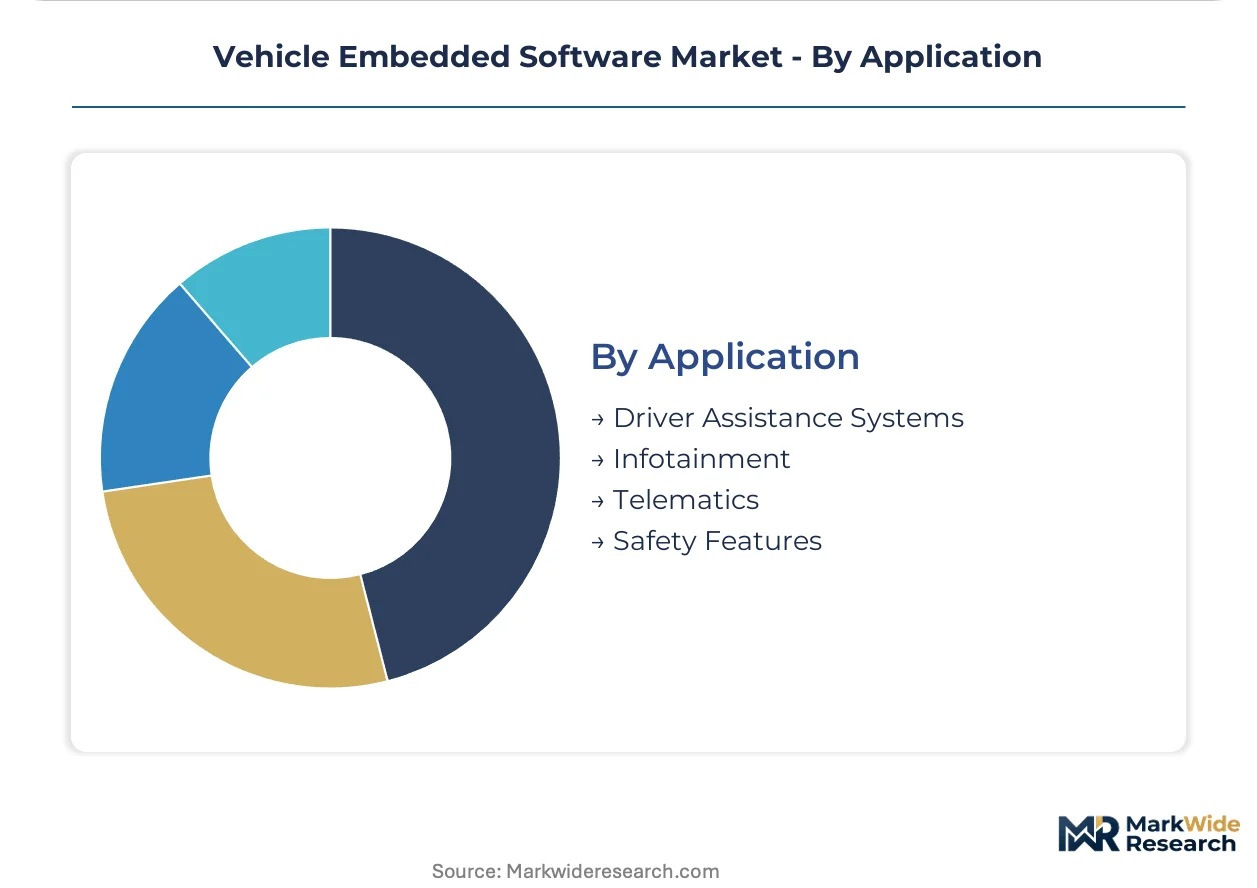
- Driver Assistance Systems:Sensor fusion algorithms and path planning modules execute Level 2+ automation. ASIL-D compliance requirements and neural network validation consume the largest engineering budgets across German premium programs. Driver Assistance Systems generates the highest revenue concentration, while Telematics is expanding most quickly.
- Safety Features:Airbag deployment, antilock braking, and electronic stability control demand sub-millisecond latency guarantees.
- Infotainment:Android Automotive and proprietary interfaces converge cockpit experiences with consumer electronics refresh cycles.
- Telematics:Cellular connectivity modules enable usage-based insurance, stolen vehicle tracking, and remote diagnostics.
Driver Assistance Systems commands the steepest investment trajectory, though Safety Features retains the most pricing inelasticity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German tier-1 suppliers export embedded software platforms to automotive engineering centers across China, Japan, and the United States. This trade corridor channels engineering services from Stuttgart and Munich to OEM captive development programs in Shanghai, Nagoya, and Detroit.
United States
NHTSA functional safety guidelines and IRA clean vehicle incentives accelerate embedded software procurement for electric powertrain controllers. Detroit-area engineering clusters source middleware stacks from German suppliers while building captive autonomous driving competencies in Silicon Valley satellite offices.
Germany
KBA type-approval requirements and EU AI Act conformity assessments tighten validation protocols for software-defined vehicle architectures. Engineering clusters in Stuttgart, Munich, and Wolfsburg concentrate cross-domain platform development across powertrain and chassis domains.
China
MIIT cybersecurity standards and dual carbon goals drive domestic OEMs toward embedded security module procurement. Automotive software development centers concentrate in Shanghai and Shenzhen, where BYD and NIO operate captive engineering programs for zonal controller architectures.
Japan
METI autonomous driving roadmaps and JIS functional safety standards shape tier-1 supplier R&D allocation. Nagoya and Tokyo engineering corridors host Denso and Renesas development centers specializing in real-time deterministic kernels for safety-critical applications.
South Korea
MFDS automotive software guidelines and government EV subsidies expand embedded platform deployment across Hyundai-Kia vehicle programs. Seoul Capital Area engineering clusters develop domain controller software for export to European and North American assembly plants.
Vehicle Embedded Software Market Key Industry Players
Channel-controlling players compete with product-specialist players across middleware, operating system, and firmware layers. The supplier base concentrates around tier-1 automotive integrators with captive software divisions and semiconductor vendors with automotive-grade processor ecosystems. Two strategic archetypes dominate: cross-domain platform providers spanning multiple vehicle functions, and safety-critical specialists delivering ASIL-D certified components. Competitive dynamics center on strategic partnerships for domain controller integration and technology licensing for hypervisor virtualization layers.
Within the cross-domain platform tier, Robert Bosch GmbH and Continental AG exemplify integrated engineering-to-manufacturing structures that span powertrain through cockpit domains. NXP Semiconductors occupies a position among semiconductor vendors supplying automotive-grade processor ecosystems to tier-1 integrators. Bosch represents the engineering conglomerate archetype with embedded software competencies distributed across multiple vehicle domains, while Continental AG sits within the tier-1 supplier category competing through middleware stack development.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Denso Corporation |
| NXP Semiconductors |
| Renesas Electronics Corporation |
| Infineon Technologies AG |
| Harman International |
| Aptiv PLC |
| Texas Instruments |
| Others |
Cost & Logistics Intelligence
Taiwan foundry concentration risk determines both tiered software licensing spreads and tier-1 supplier geographic diversification strategies. ASIL-D certification bottlenecks compress margins on safety-critical firmware while amplifying premium capture for automotive-grade middleware stacks.
Pricing Analysis
Current-generation hypervisor-enabled domain controllers command substantial premiums over legacy distributed ECU firmware and next-generation zonal architecture software. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified safety stacks from QM-grade middleware and unclassified application layers. Price differentiation hinges on ISO 26262 certification grade and volume scale commitments from OEM platform programs. Cost compression in economy-tier firmware is intensifying because Chinese domestic suppliers are undercutting European incumbents on non-safety-critical modules. Fleet operators exhibit the highest price sensitivity due to total-cost-of-ownership procurement models, while German premium OEMs remain least sensitive when purchasing ASIL-D components.
Supply Chain Analysis
Extended payment terms from German OEMs are squeezing working capital for tier-1 middleware providers and accelerating supply-chain finance facility adoption. Geographic supply concentration centers on Taiwan for automotive-grade microcontroller fabrication, Germany for AUTOSAR toolchain development, and China for electric vehicle platform software integration. Raw material dependencies include silicon wafers, automotive-grade packaging substrates, and rare earth elements for power management integrated circuits. Single-source vulnerability in 7nm automotive processor supply creates systemic exposure for domain controller programs. Distribution runs through tier-1 system integrators who bundle software with hardware platforms before OEM delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vehicle embedded software is approaching a platform-economics inflection where AUTOSAR Adaptive standardization and cross-OEM middleware interoperability are reshaping value capture. Ecosystem consolidation around unified operating environments favors scale players with certification depth.
For Market Incumbents: Build certification moats around ASIL-D functional safety competencies to defend against Chinese software entrants targeting non-safety-critical segments. Deepen vertical integration into hypervisor virtualization layers to control domain controller integration economics. Prioritize captive supply of real-time operating system kernels to reduce dependency on QNX and Green Hills licensing. Channel control through long-term service contracts with Volkswagen Group and BMW platform programs anchors recurring revenue against spot procurement pressure.
For New Entrants and Emerging Players: India's automotive PLI scheme incentives present underpenetrated white-space for embedded software development centers serving export markets. Target aftermarket telematics retrofit modules where certification burdens are lighter and price points more flexible. Pursue white-label middleware partnerships with tier-1 suppliers seeking to diversify beyond German engineering centers. Go-to-market execution should emphasize Python-based AI/ML validation tools that accelerate algorithm deployment before hardware commitment.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors safety-critical specialists with ISO 26262 ASIL-D track records and established tier-1 relationships. Long-term viability over the next decade hinges on positioning within zonal architecture transitions and over-the-air update infrastructure. Acquisition target archetypes include hypervisor virtualization specialists and cybersecurity module providers with UNECE WP.29 compliance capabilities. The signal to watch is tier-1 supplier captive software buildout rates, which would compress independent middleware vendor addressable market if accelerated.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | AUTOSAR Adaptive deployment across BMW and Volkswagen Group reduces integration fragmentation. |
| Battery Supply Agreement | Cell management system software contracts with CATL and BYD secure electric vehicle program access. |
| Software-Defined Vehicle Investment | Captive engineering centers in Bangalore and Pune leverage India's PLI scheme for cost arbitrage. |
| Geographic Manufacturing Footprint | Domain controller software development in Stuttgart and Munich maintains KBA type-approval proximity. |
| Charging Infrastructure Partnership | Telematics integration with Ionity and Electrify America networks enables usage-based feature activation. |
Research Approach
Initial hypotheses were tested against primary input from OEM platform engineers, tier-1 supplier procurement directors, semiconductor vendor automotive sales leads, and functional safety certification auditors and refined through secondary validation. Primary fieldwork encompassed structured interviews across Stuttgart, Munich, Shanghai, and Detroit engineering clusters. Secondary sources included UNECE WP.29 regulatory filings, MIIT cybersecurity standard drafts, ISO 26262 certification registry data, and IHS Markit vehicle production databases. Bottom-up segment sizing triangulated against top-down market aggregation to reconcile procurement volume estimates with supplier revenue disclosures.
Demand-supply balance modeling calibrated embedded software content per vehicle against electric and autonomous vehicle production trajectories across the analysis window. Segmentation dimensions encompassed product layer hierarchy, programming environment maturity, end-user supply chain position, and functional domain criticality. CAGRs were derived from S-curve penetration modeling of over-the-air update capabilities and zonal architecture adoption rates. Industry-specific forecast inputs included AUTOSAR platform deployment timelines and ASIL-D certification queue durations.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese domestic software vendors or accelerated tier-1 captive development would shift outcomes. Forecasts assume regulatory compliance timelines consistent with EU AI Act implementation schedules and MIIT cybersecurity phased requirements. Macroeconomic deviation in automotive production, regulatory acceleration of autonomous driving approval, or breakthroughs in formal verification automation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Test Automation Market
Software & Services
Calorie Metering Software Market
Software & Services
Expense Management Software Market
Software & Services
Configure Price and Quote (CPQ) Market
Software & Services
Programmable Automation Controller Software Market
Software & Services
Employee Engagement Solutions Market
Software & Services
Global Thermal Analysis Software Market
Software & Services
MRP Software Market
Software & Services
Global Retail Sourcing and Procurement Software Market
Software & Services
Search and Discovery Software Market
Software & Services
Global OEE Software Market
Software & Services
Production Optimization Software Market
Software & Services
Anti-Plagiarism for the Education Sector Market
Software & Services
User Interface Software Market
Software & Services
Enterprise Application Market
Software & Services
Load Balancing Software Market