
 On-Call Scheduling Software Market | 2026-2036
On-Call Scheduling Software Market Size, Share, and Industry Trends Forecast 2026-2036
On-Call Scheduling Software Market Intelligence
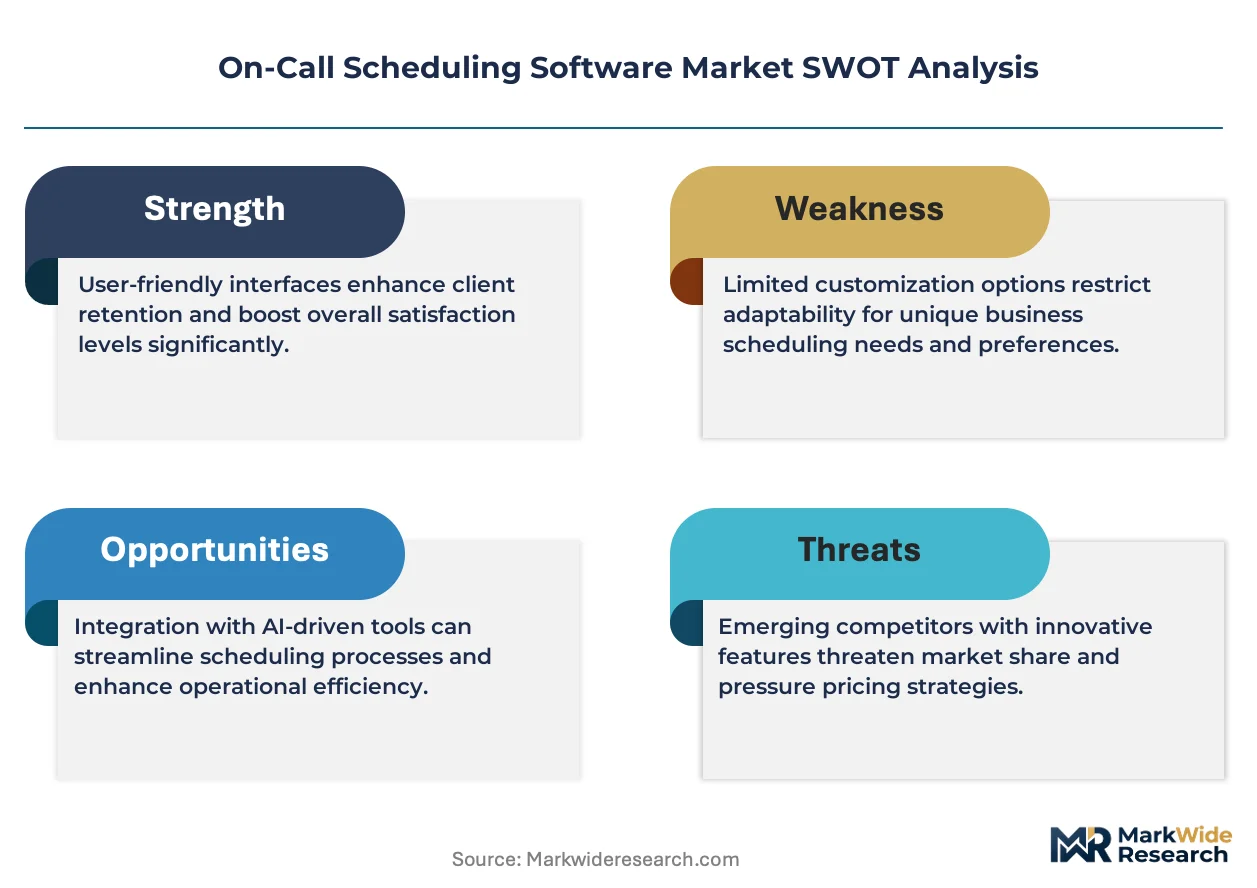
Nursing workforce attrition is unwinding traditional manual scheduling practices across acute care facilities. PagerDuty leverages real-time incident orchestration to sustain platform stickiness among enterprise IT departments. Atlassian anchors its competitive stance through deep Jira-ServiceNow integration pathways. xMatters differentiates via sophisticated multi-channel escalation protocols that reduce mean-time-to-response for critical infrastructure teams.
On-call scheduling software automates the assignment, notification, and rotation of personnel responsible for after-hours operational coverage, typically integrating with paging systems, calendaring infrastructure, and incident management APIs to ensure sub-minute alert delivery with acknowledgment tracking. Cloud-based deployment leads segment composition due to elastic scaling during mass-casualty events and distributed workforce coordination, while hybrid solutions capture margin pools from security-conscious buyers requiring on-premises data residency for patient records. Healthcare Providers represent the most penetrated end-user category, though IT Support divisions demonstrate the fastest expansion as DevOps teams adopt site-reliability-engineering practices.
FDA oversight of clinical decision-support tools intersects with HIPAA security rule enforcement to mandate encrypted alert transmission and granular access logging, compelling vendors to embed compliance-by-design architectures. The FCC regulates emergency communication priority routing under Part 90 rules, shaping product certification requirements for public-safety deployments. Buyers must evaluate vendor interoperability against emerging ISO 27001 extensions and determine whether native AI-driven shift-optimization modules justify premium positioning versus third-party bolt-on solutions.
Market Dynamics
Nursing workforce attrition across acute care facilities is forcing health systems to abandon manual scheduling practices. Cloud migration mandates from HIPAA compliance officers are accelerating procurement of automated physician rotation tools.
Growth Catalysts
- HIPAA Security Rule enforcement:Encrypted alert transmission requirements are compelling hospital networks to replace legacy paging infrastructure with compliant SaaS platforms.
- Site reliability engineering adoption:DevOps teams in enterprise IT departments are formalizing on-call rotations as operational maturity advances.
- Mass-casualty event protocols:Elastic cloud scaling during emergency surges is driving replacement of rigid on-premise scheduling systems.
Market Restraints
- On-premise data residency requirements:Security-conscious buyers in defense and classified research sectors block pure-cloud deployments.
- Legacy EHR integration complexity:Proprietary APIs from Cerner and Epic systems impose six-to-twelve-month implementation timelines.
- PSTN sunset uncertainty:FCC Phase II rules on copper network retirement create ambiguity for voice-based escalation pathways.
Strategic Opportunities
- ISO 27001 extension compliance:Vendors embedding native certification modules can capture premium positioning versus bolt-on security solutions.
- AI-driven shift optimization:Machine learning convergence with historical staffing data enables predictive absence coverage.
- India's hospital digitization:CDSCO-mandated clinical decision-support integration creates demand for compliant scheduling middleware.
Industry Challenges
- Multi-platform orchestration expertise:Shortage of engineers fluent in both ServiceNow and Jira API architectures delays enterprise deployments.
- FDA 510(k) documentation burden:Clinical decision-support classification debates extend regulatory timelines for patient-facing alert features.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | On-Call Scheduling Software Market |
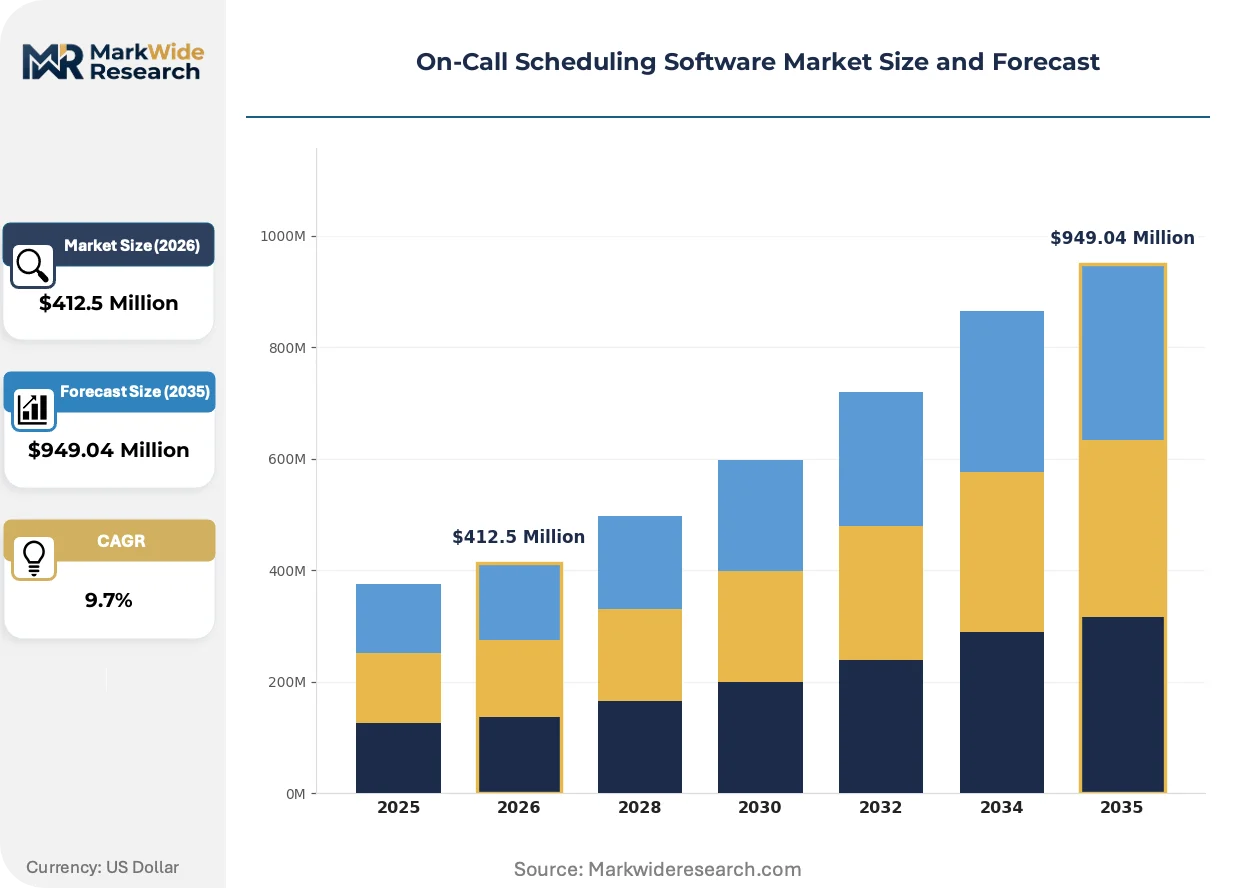
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $949.04 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based, On-premises, Mobile Applications, Hybrid Solutions End User: Healthcare Providers, Emergency Services, IT Support, Field Service Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Local Servers Feature: Automated Alerts, Shift Management, Reporting Tools, Integration Capabilities |
| Companies Covered | Spike, Atlassian, PagerDuty, Opsgenie, xMatters, Incident.io, Splunk OnCall, BigPanda, Rootly, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
On-Call Scheduling Software Market Strategic Shifts & Innovations
Real-time incident orchestration is compressing acceptable response windows from minutes to seconds. Vendors are racing to embed predictive analytics that anticipate staffing gaps before they trigger coverage failures.
Native AI scheduling engines are displacing rule-based rotation templates across enterprise healthcare deployments. Large integrated delivery networks in the United States are piloting machine learning models that ingest historical call volume, clinician fatigue scores, and seasonal admission patterns. This capability is displacing manual shift-swapping workflows that previously consumed 15-20 hours of administrative labor weekly per department.
The EU AI Act's risk classification framework is reshaping procurement criteria for algorithmic shift-allocation tools. High-risk system designations now mandate human-in-the-loop override capabilities and audit trail transparency. European hospital procurement committees are prioritizing vendors with pre-certified conformity assessments over faster but uncertified competitors.
Subscription pricing unbundling is fragmenting traditional all-in-one contracts into modular components. Buyers are separately evaluating alert delivery, calendar synchronization, and escalation management functions. This pattern is most visible among mid-market IT support divisions seeking to retain existing ticketing investments while upgrading on-call orchestration layers.
On-Call Scheduling Software Market Segmentation
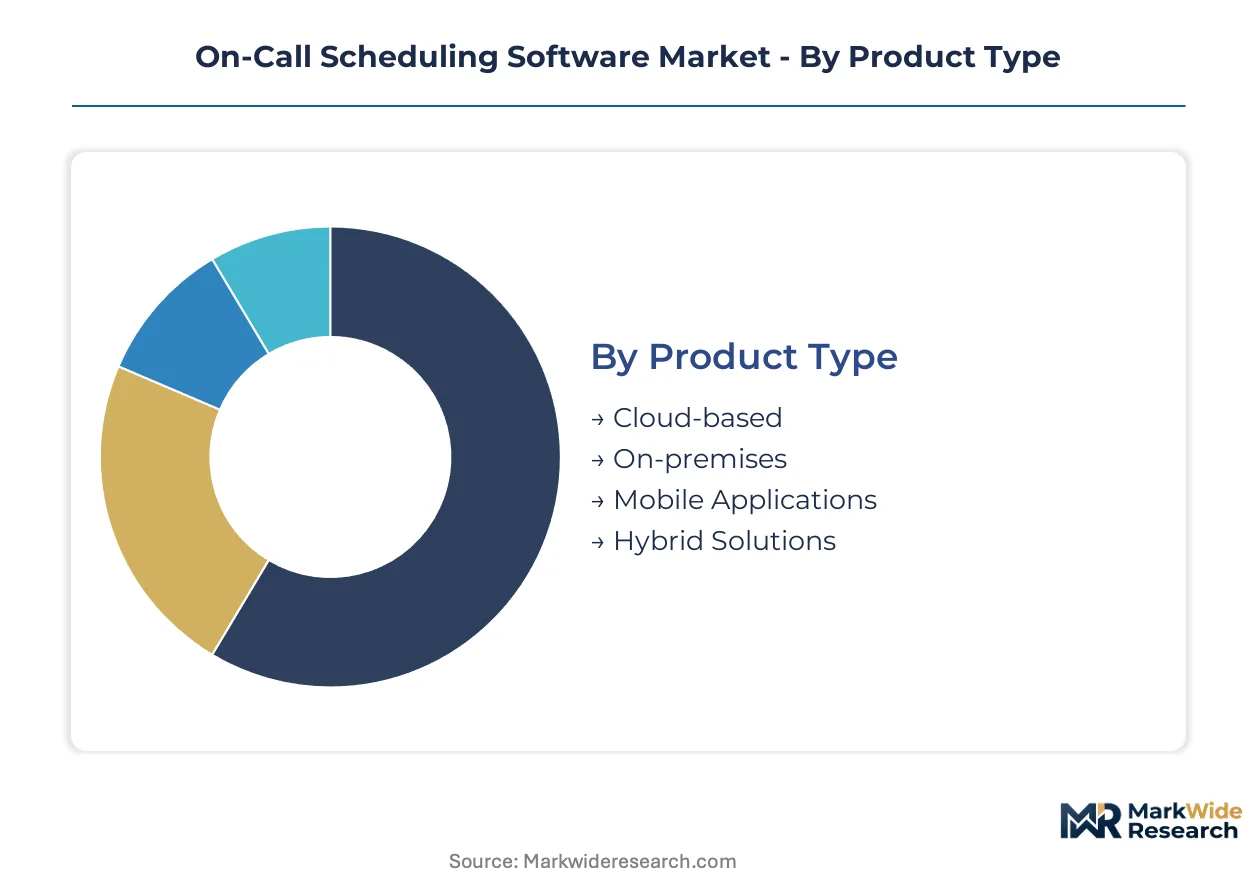
On-call scheduling software segments diverge sharply by infrastructure tolerance and regulatory exposure. Cloud-native buyers prioritize elastic scaling during surge events, while compliance-heavy sectors demand air-gapped deployments with granular audit trails.
Product Type:
Channel mix varies dramatically: direct enterprise sales dominate hybrid and on-premises deals, while cloud-based solutions flow through SaaS marketplaces and reseller networks.
- Cloud-based:Multi-tenant architectures enable instant provisioning across distributed hospital networks without capital expenditure. Large integrated delivery networks in the United States favor this model for mass-casualty surge capacity, though HIPAA business associate agreements lengthen procurement cycles.
- Hybrid Solutions:Split architectures keep patient data on-premises while routing alerts through cloud gateways. Security-conscious defense contractors and classified research facilities drive demand here, accepting premium pricing for data residency guarantees.
- On-premises:Air-gapped installations serve isolated critical infrastructure with zero external connectivity requirements.
- Mobile Applications:Native iOS and Android clients extend scheduling visibility to field personnel without full platform licensing.
Cloud-based systems dominate installed base. Hybrid Solutions are where expansion concentrates among regulated industries.
End User:
Cost tier stratification separates mission-critical deployments from cost-optimized implementations across vertical markets.
- Healthcare Providers:Hospital systems require FDA-aligned clinical decision-support integration with encrypted pager replacement and fatigue-aware rotation logic. Academic medical centers in Boston and Houston pilot AI-driven shift optimization to reduce administrative labor.
- IT Support:DevOps teams formalize site reliability engineering rotations with PagerDuty-style incident orchestration. Enterprise technology departments in Seattle and San Francisco represent the steepest expansion trajectory as SRE practices mature.
- Emergency Services:Public safety agencies need FCC Part 90 certified priority routing for 911 dispatch and ambulance coordination.
- Field Service:Utility and telecommunications crews use geofenced availability tracking for dispatch optimization.
Healthcare Providers anchor revenue concentration. IT Support is climbing the fastest as cloud-native operational practices spread.
Deployment:
Volume distribution tracks organizational scale: public cloud captures mid-market share, private deployments concentrate among Fortune 500 compliance officers.
- Public Cloud:Shared infrastructure delivers lowest per-seat economics for regional hospital networks without dedicated security staff. Cleveland Clinic and Kaiser Permanente leverage public cloud elasticity for seasonal census fluctuations.
- Private Cloud:Single-tenant virtualized environments satisfy HIPAA security rule mandates while retaining some operational flexibility. Mayo Clinic maintains private cloud scheduling for research hospital divisions with controlled substance oversight.
- Hybrid Cloud:Burst capacity models allow on-premises core systems to spill overflow traffic to public infrastructure during emergencies.
- Local Servers:Physical hardware in basement data centers persists where network connectivity is unreliable or prohibited.
Public Cloud holds the broadest installed base. Private Cloud is gaining share fastest among systems pursuing HIMSS Stage 7 certification.
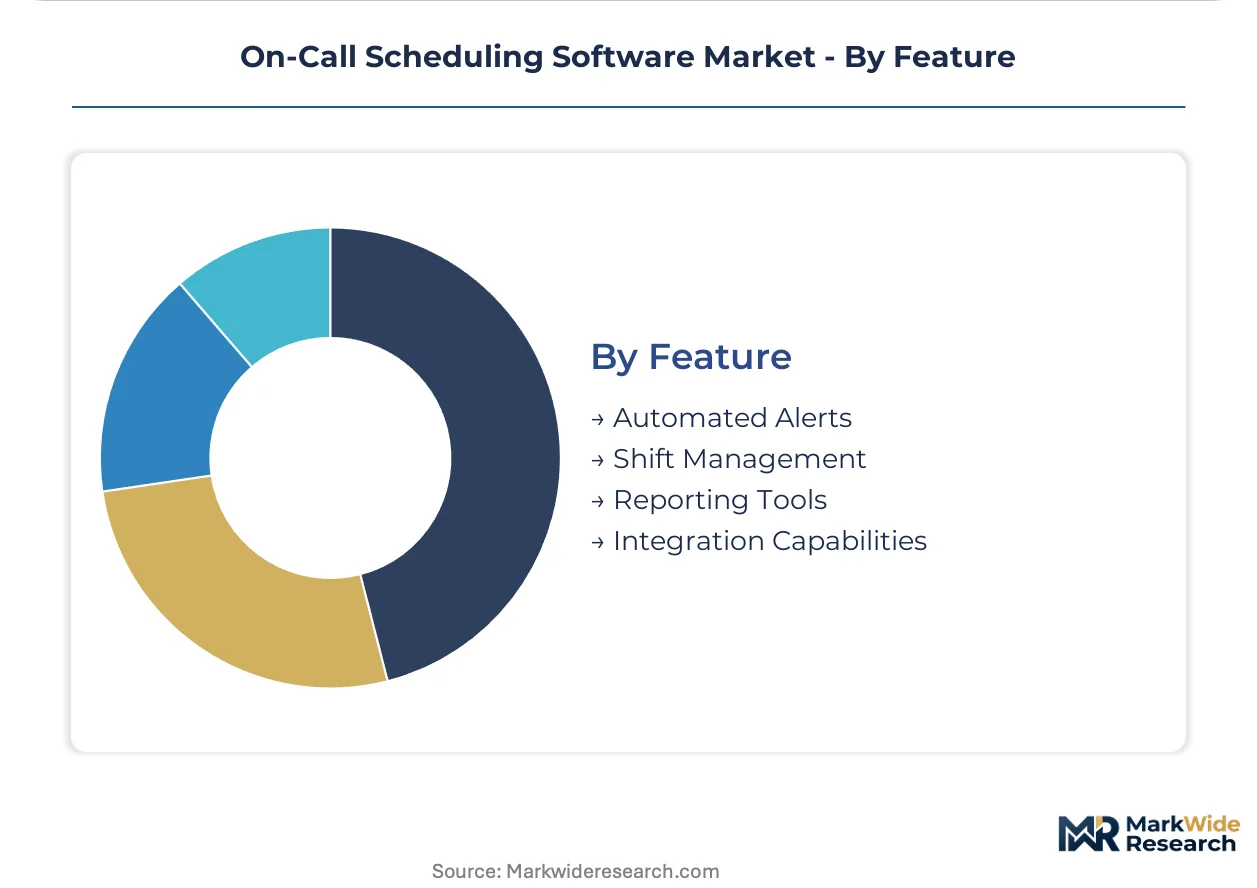
Feature:
Customer maturity determines module adoption: basic alerting saturates small deployments, advanced integration commands premium pricing.
- Automated Alerts:Sub-minute notification delivery with acknowledgment tracking and escalation chains forms the functional core. Multi-channel pathways spanning SMS, push, voice, and pager protocols reduce mean-time-to-response in critical care environments.
- Integration Capabilities:Native ServiceNow and Jira API connectivity enables incident-to-scheduler workflows that eliminate manual ticket routing. Enterprise IT departments prioritize this capability for DevOps toolchain consolidation.
- Shift Management:Rule-based and AI-driven rotation templates replace spreadsheet-based scheduling with conflict detection.
- Reporting Tools:Compliance dashboards and fatigue analytics satisfy Joint Commission documentation requirements.
Automated Alerts represent universal baseline functionality. Integration Capabilities is where vendor differentiation and pricing power concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC enforcement of HIPAA-aligned communication standards anchors procurement momentum in the United States. European hospital networks navigate EU AI Act compliance timelines. India's CDSCO mandates reshape clinical software integration requirements.
United States
Hospital systems in Boston and Houston pilot AI-driven shift optimization to reduce administrative labor burdens. FDA oversight of clinical decision-support tools intersects with HIPAA security rule enforcement to mandate encrypted alert transmission. Large integrated delivery networks concentrate procurement authority in these metropolitan clusters.
Germany
Academic medical centers demand ISO 27001-certified scheduling middleware for research hospital divisions. The EU AI Act's risk classification framework mandates human-in-the-loop override capabilities for algorithmic shift-allocation tools. Berlin and Munich anchor vendor certification efforts for continental European expansion.
United Kingdom
NHS trusts accelerate cloud migration for physician rotation tools amid workforce attrition pressures. GDPR compliance requirements lengthen procurement cycles for multi-tenant SaaS platforms. London-based health technology procurement committees prioritize vendors with pre-certified conformity assessments.
India
Private hospital chains in Maharashtra and Karnataka adopt automated scheduling to manage nursing workforce shortages. CDSCO-mandated clinical decision-support integration creates demand for compliant scheduling middleware. Bangalore and Mumbai represent the steepest adoption trajectory among APAC emerging markets.
Japan
Metropolitan hospital networks in Tokyo and Osaka integrate on-call systems with existing pager replacement infrastructure. METI digital health initiatives subsidize cloud adoption for regional medical associations. PMDA alignment with international software validation standards streamlines vendor market entry.
On-Call Scheduling Software Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the current market structure. Cloud-native platforms with native incident orchestration capabilities command premium positioning against rule-based rotation specialists. Three archetypes dominate: enterprise IT reliability platforms, healthcare-specific compliance engines, and modular alert-delivery specialists. Competitive moves concentrate on API ecosystem expansion and vertical workflow integration rather than pure pricing pressure.
Within the integrated platform tier, PagerDuty and Atlassian occupy positions defined by deep DevOps toolchain connectivity. xMatters exemplifies the multi-channel escalation specialist archetype with sophisticated protocol engineering. These three entities represent the competitive anchors against which mid-market buyers evaluate modular alternatives.
| Leading Market Players |
|---|
| Spike |
| Atlassian |
| PagerDuty |
| Opsgenie |
| xMatters |
| Incident.io |
| Splunk OnCall |
| BigPanda |
| Rootly |
| Others |
Cost & Logistics Intelligence
Capacity reservation contracts with cloud infrastructure providers lock in both compute access and subscription pricing visibility for SaaS vendors serving HIPAA-regulated hospital networks. These multi-year commitments insulate buyers from spot-market volatility in cloud egress fees while securing priority provisioning during mass-casualty surge events.
Pricing Analysis
Geographic price spreads between North American and South Asian deployments reach three-to-one ratios for equivalent seat counts. Three-tier pricing structure across premium, standard, and economy levels segments by integration complexity, with premium tiers commanding multiples for native ServiceNow and Jira API connectivity. Cost compression in mid-market cloud tiers intensifies as PagerDuty-style platforms consolidate incident orchestration bundles. Academic medical centers exhibit lowest price sensitivity due to grant-funded procurement, while regional hospital networks in India negotiate aggressively on per-seat economics.
Supply Chain Analysis
Strait of Malacca submarine cable transit underwrites latency-sensitive alert delivery for Asia-Pacific hospital networks. Cloud infrastructure concentrates in the United States, Ireland, and Singapore, with compute capacity expansion in Mumbai and São Paulo addressing data residency mandates. Raw material dependencies span semiconductor chips for mobile alert hardware, encryption modules for HIPAA-compliant transmission, and lithium-ion cells for pager replacement devices. Single-source vulnerability in AWS and Azure hyperscaler concentration threatens continuity for multi-tenant SaaS vendors. Distribution runs through direct enterprise sales for hybrid deployments and SaaS marketplaces for cloud-native subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as workforce attrition across acute care facilities splinters demand across specialized compliance engines, modular alert specialists, and integrated DevOps platforms. Subscription unbundling creates white-space for point-solution vendors.
For Market Incumbents: Fortify API ecosystem moats by embedding native AI-driven shift optimization before third-party bolt-ons capture premium positioning. Deepen certification investments in ISO 27001 extensions and EU AI Act conformity assessments to defend against emerging compliance-first entrants. Channel control through exclusive ServiceNow and Jira integration partnerships blocks modular competitors from enterprise IT procurement shortlists.
For New Entrants and Emerging Players: Lead with fatigue-aware rotation logic targeting academic medical centers in Boston and Houston, where administrative labor reduction justifies pilot budgets. India's CDSCO-mandated clinical decision-support integration represents the most penetrable geography, with Bangalore and Mumbai hospital chains seeking compliant middleware. Go-to-market through regional health technology distributors with pre-existing GPO relationships accelerates procurement committee access.
For Investors and Strategic Acquirers: Cloud-native platforms with dormant healthcare verticalization offer the strongest acquisition target archetype for private equity roll-up strategies. Long-term viability hinges on regulatory certification durability rather than feature velocity, favoring vendors with embedded HIPAA business associate agreements and FDA-aligned documentation. Watch for FCC Phase II PSTN sunset rulings as inflection indicator—voice-based escalation pathway disruption will compress valuations for pager-dependent legacy vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native ServiceNow and Jira API connectivity eliminates manual ticket routing for DevOps teams. |
| Acquisition of Specialist Firm | AI-driven shift optimization engines displace rule-based templates in academic medical centers. |
| Regulatory Certification Pathway | EU AI Act pre-certification unlocks procurement committees in Berlin and Munich hospital networks. |
| Geographic Expansion | CDSCO-compliant middleware addresses nursing workforce attrition in Maharashtra and Karnataka. |
| Strategic Partnership | Hyperscaler co-selling agreements accelerate HIPAA business associate agreement negotiations. |
Research Approach
The analysis maps cloud-native SaaS platforms, hybrid compliance engines, and modular alert specialists, each validated through hospital CIOs, DevOps platform engineers, GPO contracts managers, and health technology procurement committees. Primary interviews with these stakeholders combined with secondary validation against SEC filings, hospital procurement databases, hyperscaler capex disclosures, and CMS Medicare reimbursement data. Bottom-up seat-count modeling and top-down addressable market sizing underwent cross-referencing for triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include deployment architecture, organization scale, vertical regulatory exposure, integration complexity, and regional adoption pattern. CAGRs derived from historical penetration curves adjusted for HIPAA enforcement timelines and SRE practice maturation. Forecast inputs incorporated nursing workforce attrition rates and cloud migration mandate acceleration from compliance officers.
The analysis sits within stated boundaries; outcomes outside sustained HIPAA security rule enforcement or accelerated PSTN sunset timelines would require recalibration. Forecasts reflect documented assumptions about elastic scaling demand during mass-casualty protocols and AI shift-optimization adoption curves. Revision becomes warranted when FCC Phase II copper network retirement schedules cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Job Description Management Software Market
Software & Services
Load Balancing Software Market
Software & Services
Global Retail Execution Software Market
Software & Services
Home Design Software Market
Software & Services
Global Architect Software Market
Software & Services
Cricket Analysis Software Market
Software & Services
Global Catalog Management Systems Market
Software & Services
Parks and Playground Inspection Software Market
Software & Services
Global Application Release Automation Market
Software & Services
Global Performance Appraisal Software Market
Software & Services
Team Collaboration Tools Market
Software & Services
Talent Management Software Market
Software & Services
3D Printing Medical Device Software Market
Software & Services
Software-Defined Anything Market
Software & Services
Global Inspection Management Software Market
Software & Services
Ecommerce Software and Platform Market