
 Graphical User Interface (GUI) Design Software Market | 2026-2036
Graphical User Interface (GUI) Design Software Market Size, Share, and Industry Trends Forecast 2026-2036
Graphical User Interface (GUI) Design Software Market Foresight
Cloud infrastructure capacity in North America and Western Europe is shifting toward GPU-accelerated rendering farms that support real-time collaborative editing. Figma leverages browser-native architecture to sustain multi-user concurrency at scale. Adobe XD anchors professional creative workflows through deep integration with Creative Cloud. Sketch dominates macOS-native design environments with optimized vector performance.
Graphical User Interface design software encompasses vector-based editing environments, component libraries, and interactive prototyping engines that translate user experience specifications into production-ready interface assets. These systems employ constraint-based layout algorithms, design token architectures, and API-connected asset pipelines to bridge creative teams with frontend development workflows. Web Apps and Cloud-Based deployment models lead current adoption curves as distributed product teams demand synchronous collaboration without local installation overhead. Mobile Apps functionality is accelerating fastest as touchscreen-first interface specifications proliferate across enterprise software portfolios. Wireframing retains mature margin pools in agency contexts where rapid iteration cycles prioritize speed over fidelity.
FCC guidelines on digital accessibility and the EU Web Accessibility Directive shape interface compliance requirements that GUI platforms must embed natively. ISO 9241 ergonomic standards and W3C WCAG criteria further constrain acceptable interaction patterns, color contrast ratios, and keyboard navigation behaviors. Procurement teams should evaluate whether vendor roadmaps prioritize automated accessibility auditing and cross-border data residency controls before committing to multi-year platform contracts.
Market Dynamics
Browser-native rendering engines are compressing deployment cycles as distributed product teams abandon local installation requirements for synchronous cloud-based collaboration environments.
Growth Catalysts
- EU AI Act compliance mandates:Privacy-by-default architecture requirements are accelerating vendor investment in data residency controls and automated audit trails across European deployments.
- GPU-accelerated rendering farms:Cloud infrastructure providers in North America are scaling real-time collaborative editing capacity to serve enterprise software teams with multi-user concurrency demands.
- Touchscreen-first interface specifications:Mobile Apps functionality is pulling design tool development resources as enterprise software portfolios prioritize responsive, gesture-based interaction patterns.
Market Restraints
- Subscription cost escalation:Per-seat SaaS pricing for professional-grade vector editing environments is squeezing mid-market agency budgets and extending procurement cycles.
- Vector performance limitations:Browser-based rendering engines struggle with complex component libraries containing nested constraints and dynamic design tokens at scale.
- Cross-border data friction:GDPR residency requirements and divergent national cloud sovereignty rules are fragmenting vendor hosting architectures and complicating multi-region deployments.
Strategic Opportunities
- Automated accessibility auditing:FCC guidelines and the EU Web Accessibility Directive are creating procurement preference for platforms embedding WCAG compliance checking natively into design workflows.
- API-connected asset pipelines:Design token architectures that bridge creative teams with frontend development workflows are expanding into underpenetrated enterprise manufacturing and healthcare software verticals.
- Design system governance tools:Component library standardization across distributed product organizations is opening whitespace for versioning, permission, and approval workflow specialization.
Industry Challenges
- DesignOps talent scarcity:Organizations struggle to hire specialists capable of bridging design system architecture with DevOps pipeline integration and cross-functional workflow orchestration.
- Legacy tool migration friction:Creative teams entrenched in macOS-native vector environments resist retraining on browser-based platforms despite collaboration advantages.
- WCAG certification complexity:Third-party accessibility auditing timelines and remediation costs are extending enterprise procurement decisions and inflating implementation budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Graphical User Interface (GUI) Design Software Market |
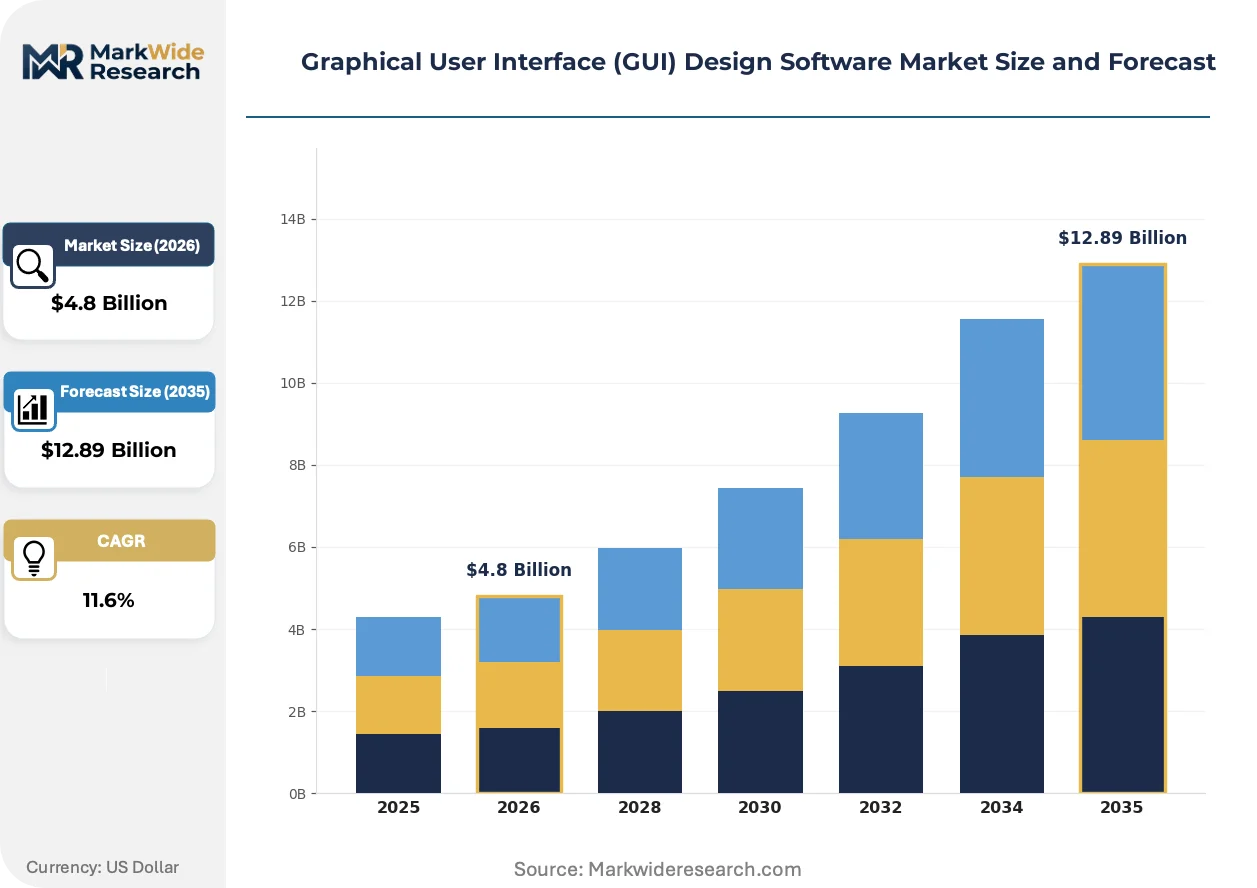
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.89 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Apps, Web Apps, Desktop Software, Prototyping Tools End User: Design Agencies, In-House Teams, Freelancers, Educational Institutions Deployment Model: Cloud-Based, On-Premise, Hybrid, SaaS Functionality: Wireframing, Mockup Creation, Collaboration, User Testing |
| Companies Covered | InVision Studio, UXPin, Figma, Justinmind, Proto.io, Adobe XD, Framer, Balsamiq, Sketch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Graphical User Interface (GUI) Design Software Market Shifts & Advancements
Generative capabilities are embedding into interface specification workflows, compressing the gap between natural language prompts and production-ready component libraries while reshaping creative team staffing models.
Constraint-based layout algorithms are expanding into automated responsive behavior generation, interpreting design intent across viewport dimensions without manual breakpoint specification. Enterprise SaaS product teams are adopting these systems fastest, reducing frontend handoff friction and compressing iteration cycles from days to hours. This capability is expanding into design system governance, enabling non-technical stakeholders to modify layouts without breaking component hierarchies.
The EU AI Act risk classification framework is mandating explainability features in design tools used for high-stakes interface decisions, particularly in financial services and healthcare software. Vendors must now document how automated layout suggestions are generated and provide audit trails for design choices affecting user outcomes. Platforms serving regulated European industries are prioritizing transparency dashboards and human-in-the-loop approval workflows to satisfy conformity assessment requirements.
Buyer concentration among SaaS-native product organizations is compressing vendor sales cycles and elevating procurement sophistication around API extensibility and security posture documentation. Traditional agency channel relationships are weakening as direct enterprise engagements dominate contract values. This pattern is most visible in the United States, where technology firms with mature design operations functions are consolidating spend with platforms offering deepest CI/CD integration and granular permission architectures.
Graphical User Interface (GUI) Design Software Market Segmentation
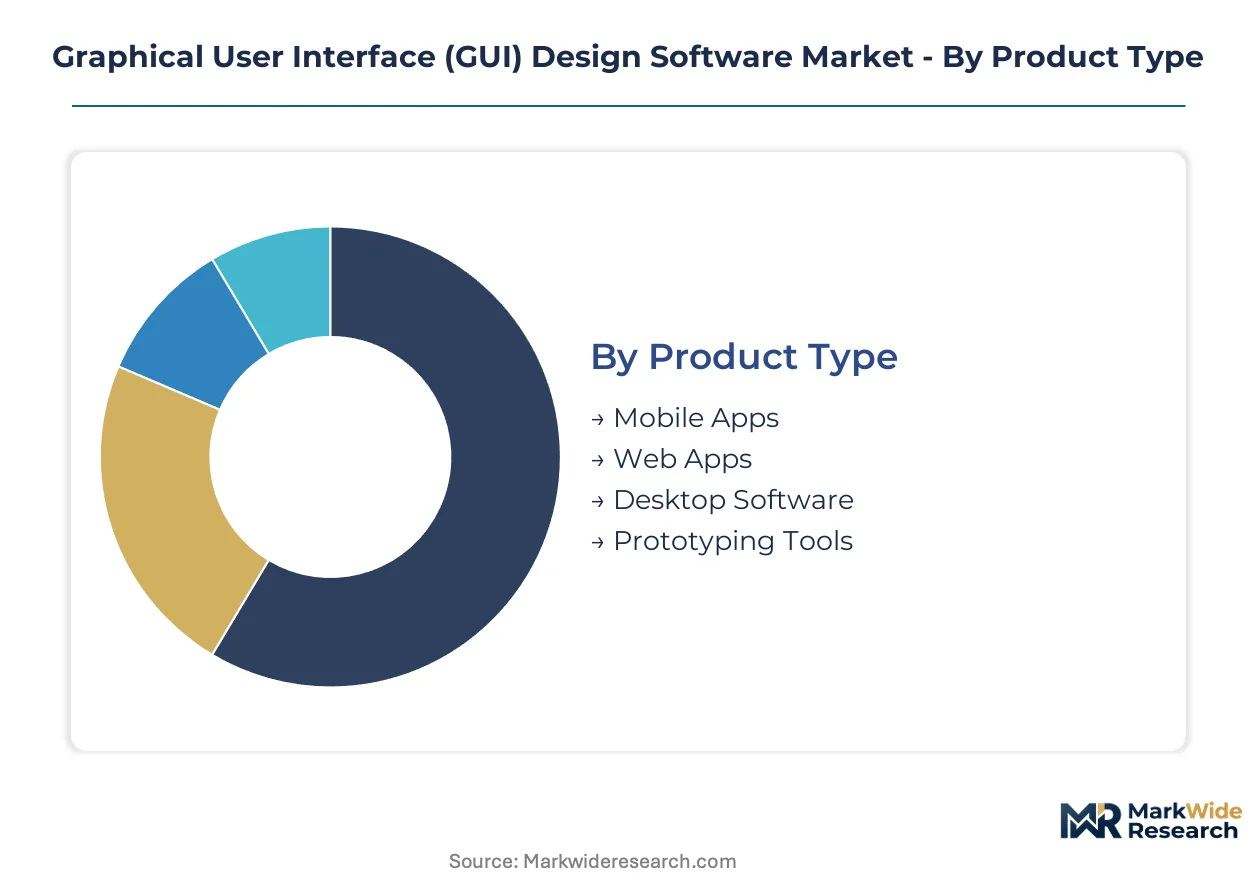
GUI design software segments reflect divergent technical requirements across creative workflows. Deployment preferences and collaboration intensity vary sharply between agency environments and enterprise product teams.
Product Type:
Technical sophistication and platform specificity separate buyer investment levels across interface specification tools.
- Web Apps:Browser-native rendering engines enable synchronous multi-user editing without local installation overhead. Enterprise SaaS product teams in the United States concentrate procurement here, driven by distributed workforce demands and CI/CD pipeline integration requirements.
- Mobile Apps:Touchscreen-first specification environments support gesture-based interaction prototyping and responsive breakpoint management. Demand clusters among fintech and healthcare software developers building cross-platform experiences, constrained by GPU-accelerated rendering farm capacity limitations.
- Desktop Software:macOS-native vector performance dominates professional creative workflows with optimized GPU utilization and offline capability.
- Prototyping Tools:Interactive behavior simulation engines bridge static mockups with clickable user experience validation.
Web Apps lead volumes today; Mobile Apps is gaining share fastest.
End User:
Organizational scale and procurement sophistication determine platform selection criteria and contract negotiation leverage.
- In-House Teams:Enterprise product organizations maintain dedicated design operations functions with formalized component library governance and DevOps integration mandates. Technology firms in California and New York drive premium platform adoption, prioritizing API-connected asset pipelines and granular permission architectures.
- Design Agencies:External creative services providers balance rapid iteration speed against client-mandated tool compatibility and export format flexibility. Mid-market agency budgets face squeeze from per-seat SaaS pricing escalation, extending procurement cycles and increasing open-source tool evaluation.
- Freelancers:Individual practitioners prioritize affordable subscription tiers and cross-platform portability for client project portability.
- Educational Institutions:University design programs and coding bootcamps negotiate volume licensing for curriculum-standardized tool training.
In-House Teams command the largest contract values; Design Agencies show the steepest expansion trajectory as external creative services outsourcing accelerates.
Deployment Model:
Data residency requirements and IT security postures fragment infrastructure preferences across regulated and unregulated industries.
- Cloud-Based:Fully managed SaaS delivery eliminates local server maintenance while enabling automatic feature updates and elastic collaboration scaling. GDPR compliance mandates and EU AI Act risk classification frameworks are accelerating European demand for privacy-by-default architecture with automated audit trails.
- SaaS:Subscription-native delivery models dominate procurement among SaaS-native product organizations with mature design operations functions.
- On-Premise:Self-hosted installations satisfy financial services and defense sector requirements for air-gapped environments and custom security hardening.
- Hybrid:Mixed infrastructure configurations balance sensitive asset local storage with cloud-based collaboration features for non-critical workflows.
Cloud-Based deployments anchor current adoption; Hybrid configurations are climbing the fastest as cross-border data friction intensifies.
Functionality:
Workflow stage and fidelity requirements determine feature prioritization and integration depth with adjacent creative tools.
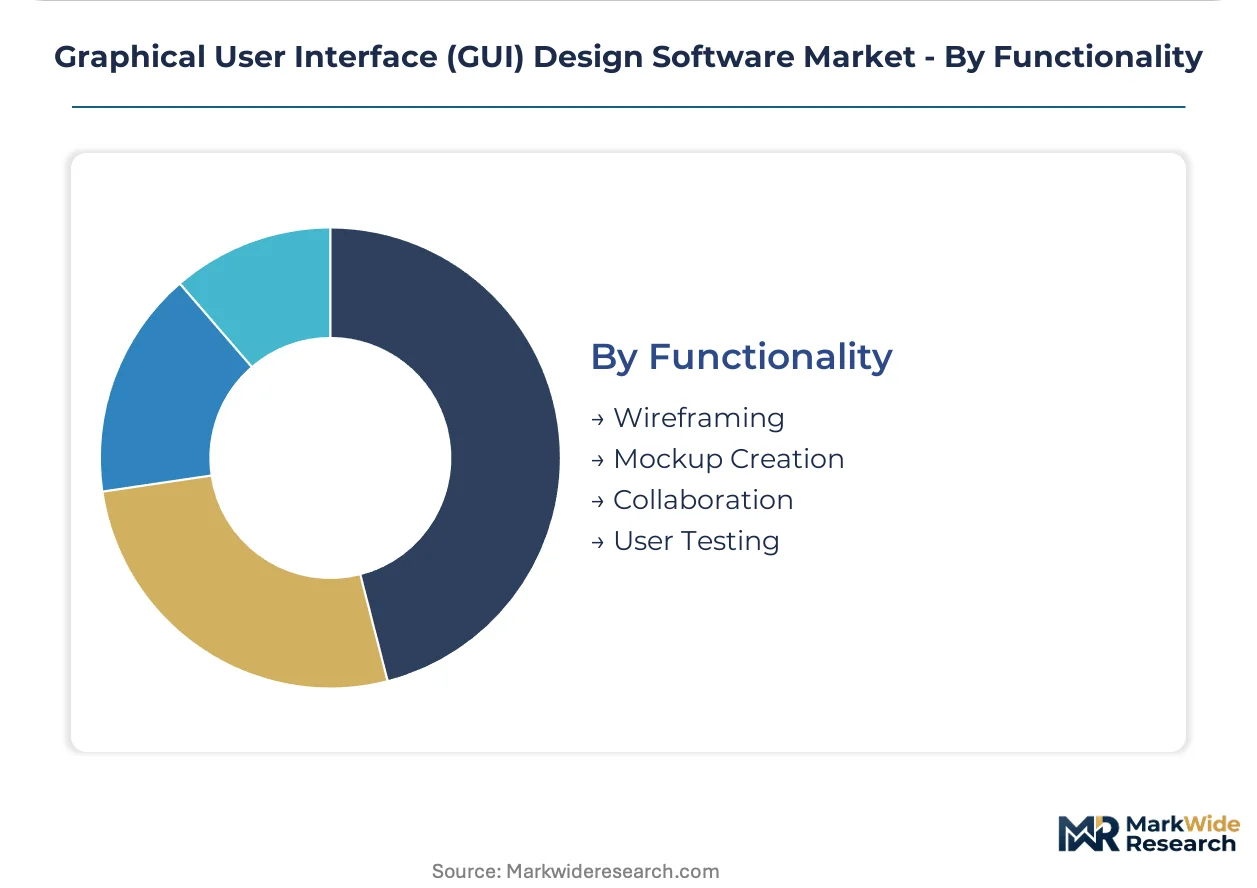
- Collaboration:Real-time concurrent editing, version control, and stakeholder comment threading compress feedback cycles from days to hours. FCC digital accessibility guidelines and EU Web Accessibility Directive compliance requirements are embedding automated WCAG auditing into collaborative review workflows.
- Wireframing:Low-fidelity rapid layout specification prioritizes speed over visual polish for early-stage concept validation.
- Mockup Creation:High-fidelity visual asset production with design token architecture and component library integration.
- User Testing:Interactive prototype distribution and behavioral analytics collection for usability validation before development handoff.
Collaboration functionality leads platform differentiation today; User Testing capabilities are expanding most quickly as outcome-based design validation gains procurement priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States technology firms outspend German counterparts on collaborative design platforms by substantial margins, yet GDPR compliance investments in Europe are narrowing the infrastructure gap. Cloud-native deployment preferences diverge sharply between these markets.
United States
Enterprise SaaS product teams in California and New York drive premium platform procurement, prioritizing API-connected asset pipelines and granular permission architectures. FCC digital accessibility guidelines shape procurement criteria for automated WCAG auditing features. Silicon Valley and Manhattan design operations clusters concentrate demand for real-time collaborative editing with CI/CD integration.
Germany
Industrial software manufacturers in Baden-Württemberg and Bavaria adopt design system governance tools for complex machinery interfaces. The EU AI Act risk classification framework mandates explainability features for high-stakes interface decisions. Stuttgart and Munich automotive software centers prioritize privacy-by-default architecture with automated audit trails.
United Kingdom
Fintech product organizations in London concentrate procurement of touchscreen-first prototyping capabilities for mobile banking experiences. GDPR residency requirements accelerate demand for regional cloud hosting with cross-border data friction mitigation. The City and Shoreditch tech corridors anchor design operations function maturation.
Japan
Consumer electronics manufacturers in Tokyo and Osaka prefectures maintain macOS-native vector workflows for hardware-software interface integration. METI standardization initiatives influence design tool evaluation criteria for export-ready products. The Kanto and Kansai industrial belts sustain specialized agency relationships for rapid iteration cycles.
India
Technology services firms in Karnataka and Telangana expand design operations headcount for global client delivery. The country's national data protection framework shapes vendor selection toward privacy-compliant hosting architectures. Bangalore and Hyderabad software export clusters drive mid-market SaaS subscription growth.
Graphical User Interface (GUI) Design Software Market Competitive Landscape
United States vendors anchor the browser-native tier; European specialists hold positions in privacy-compliant and macOS-native segments. Market structure consolidates around three platform archetypes: cloud-collaborative suites, desktop-native professional tools, and rapid-prototyping specialists. Competitive dynamics center on API ecosystem breadth and automated accessibility auditing capabilities. Strategic moves emphasize design system governance acquisitions and regional data residency infrastructure expansion.
Within the cloud-collaborative tier, Figma and InVision Studio represent the browser-native convergence archetype, while Sketch occupies a position in macOS-optimized vector performance. Adobe XD exemplifies the creative suite integration model. These anchors reflect the tripartite competitive structure: synchronous multi-user environments, native hardware optimization, and adjacent tool ecosystem leverage.
| Leading Market Players |
|---|
| InVision Studio |
| UXPin |
| Figma |
| Justinmind |
| Proto.io |
| Adobe XD |
| Framer |
| Balsamiq |
| Sketch |
| Others |
Supply & Pricing Matrix
Captive GPU rendering infrastructure in North America anchors both supply security and pricing power for real-time collaborative platforms, creating defensive moats that browser-native vendors exploit against macOS-dependent competitors. This vertical control over compute-intensive rendering pipelines lets cloud-collaborative suites maintain premium subscription tiers while mid-market agencies face escalating per-seat costs.
Pricing Analysis
Capacity additions in North America are reshaping price floors for GPU-accelerated rendering services that underpin synchronous editing environments. Three-tier pricing structure across premium, standard, and economy levels segments buyers by team size and DevOps integration depth. Cost compression in the agency tier intensifies because mid-market budgets cannot absorb enterprise-grade per-seat SaaS escalation. Freelancers and educational institutions show highest price sensitivity, while in-house enterprise product teams demonstrate lowest sensitivity due to design operations budget consolidation.
Supply Chain Analysis
Cloud infrastructure workforce availability in Virginia, Oregon, and Dublin feeds the scaling demands of real-time collaborative editing farms. GPU chip fabrication draws from Taiwan and South Korea, while data center construction materials source from China and domestic steel suppliers. Single-source vulnerability in advanced GPU supply creates procurement risk for vendors expanding European rendering capacity. Distribution runs through direct enterprise sales teams and self-service SaaS portals, bypassing traditional creative software retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
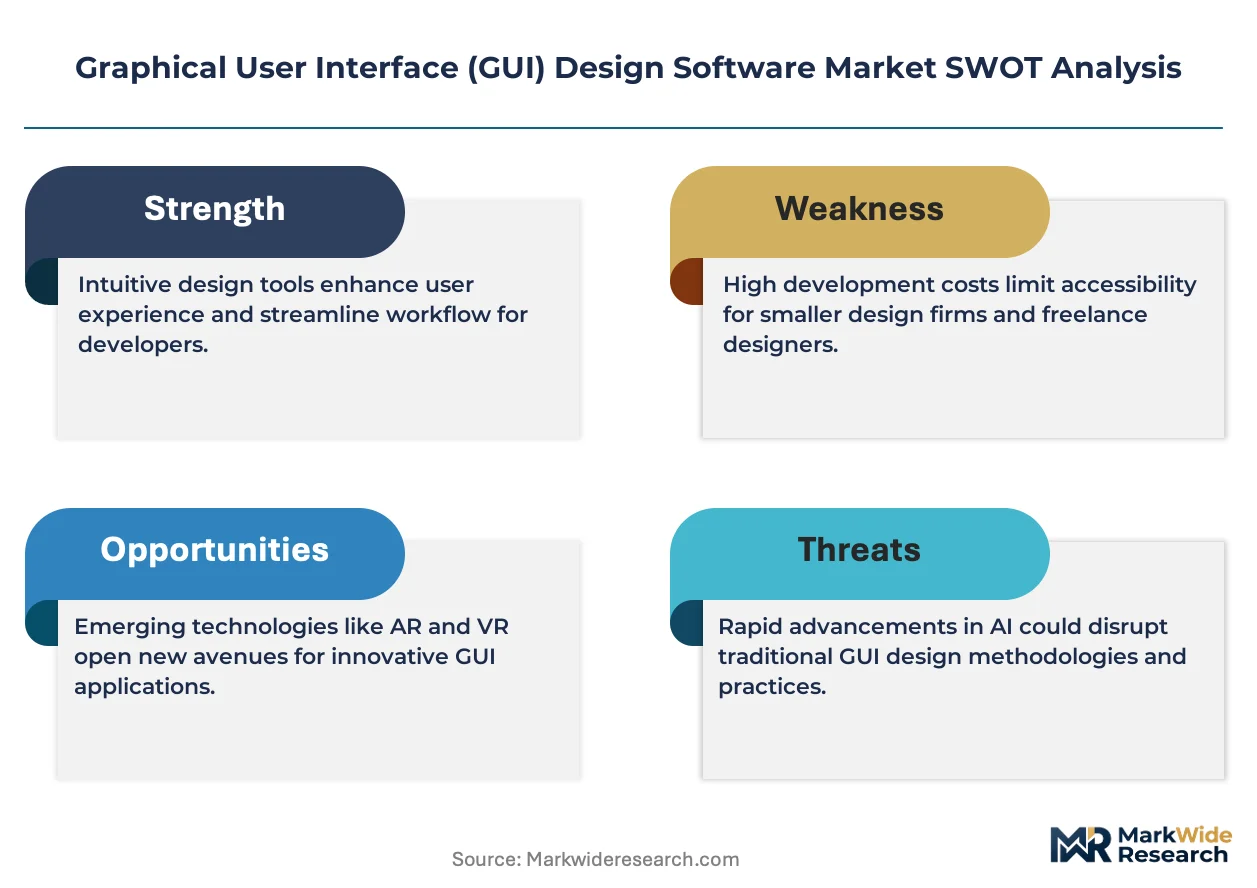
This market reads as a late-cycle quality story where procurement sophistication among SaaS-native product organizations elevates preference for API-connected asset pipelines and automated accessibility auditing over basic vector editing functionality.
For Market Incumbents: Deploy design system governance tooling as the primary defensive lever against emerging browser-native challengers. Incumbents should deepen CI/CD pipeline integration to raise switching costs for enterprise customers while acquiring specialized accessibility auditing firms to neutralize regulatory compliance as a differentiation vector. The threat of GPU-accelerated rendering farm commoditization demands accelerated investment in proprietary constraint-solving algorithms that browser engines cannot replicate at scale. For New Entrants and Emerging Players: Capture whitespace in healthcare and manufacturing software verticals where design token architectures remain underpenetrated. The most penetrable segment comprises mid-market industrial software teams in Baden-Württemberg and Bavaria seeking privacy-by-default alternatives to US-dominated cloud suites. A vertical-specific go-to-market angle emphasizing EU AI Act compliance documentation and automated audit trail generation unlocks procurement doors closed to generalist platforms. For Investors and Strategic Acquirers: Roll-up economics work for specialized accessibility auditing and design system governance tools because enterprise procurement is consolidating spend with platforms offering deepest compliance automation. The five-to-ten-year viability window favors acquisition targets with established WCAG certification workflows and regional data residency infrastructure already deployed. Watch for inflection when FCC enforcement actions on digital accessibility accelerate enterprise procurement mandates beyond voluntary adoption curves.| Strategic Initiative | Industry Significance |
|---|---|
| Design System Governance Acquisition | Consolidates component library standardization tooling for distributed enterprise product teams. |
| Regional Data Residency Infrastructure Expansion | Satisfies GDPR and EU AI Act automated audit trail requirements for Stuttgart and Munich automotive software centers. |
| Automated Accessibility Auditing Integration | Embeds WCAG compliance checking natively into Figma and Adobe XD competitor workflows for FCC guideline adherence. |
| API-Connected Asset Pipeline Development | Bridges creative teams with frontend development workflows in underpenetrated healthcare and manufacturing verticals. |
| GPU-Accelerated Rendering Farm Scale-Up | Supports real-time multi-user concurrency demands from Silicon Valley and Manhattan design operations clusters. |
Research Methodology
Bottom-up enterprise SaaS procurement modeling reconciled against top-down cloud infrastructure capacity tracking forms the analytical core of this study. Primary interviews with design operations leads, IT procurement officers, platform engineers, and regulatory compliance specialists at technology firms and creative agencies combined with secondary validation from SEC filings, hyperscaler capex disclosures, App Annie usage data, and EU regulatory documentation. Triangulation across these sources ensures segment-level precision without over-reliance on any single stakeholder perspective.
Historical trendline analysis of browser-native rendering engine adoption and per-seat SaaS pricing trajectories informed the projection framework across the analysis window. Segmentation dimensions modeled include deployment model, organization size, vertical industry, integration complexity with CI/CD pipelines, and regional regulatory cluster. CAGRs were derived from fitted growth curves adjusted for EU AI Act implementation timelines and FCC accessibility enforcement patterns. GPU farm capacity expansion schedules and design system governance tool penetration rates served as industry-specific forecast inputs.
Regulatory enforcement variance, cloud infrastructure cost volatility, and design operations talent availability are the dominant revision risks that could compress or extend modeled growth trajectories. Forecasts reflect assumptions about GDPR compliance investment continuity and enterprise SaaS procurement cycle stability. Material deviation in named triggers warrants pause and re-evaluation of segment-level projections and vendor competitive positioning assessments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Sales Dialer Software Market
Software & Services
North America Restaurant Management Software Market
Software & Services
UK Applicant Tracking System Market
Software & Services
Mobile Tracking Software Market
Software & Services
Software-Defined Machine Market
Software & Services
Programmable Automation Controller (PAC) Programming Software Market
Software & Services
Contract Abstraction Software Market
Software & Services
Interactive Digital Signage Software Market
Software & Services
Preschool Education Software Market
Software & Services
Mobile Application Stores Market
Software & Services
Desktop Publishing Software Market
Software & Services
Commissioning Software Market
Software & Services
Metal Recycling Software Market
Software & Services
Stock Media Software Market
Software & Services
Live Software Market
Software & Services
Document-Centric Collaboration Software Market