
 UK Digital Transformation Market | 2026-2036
UK Digital Transformation Market Size, Share, and Industry Trends Forecast 2026-2036
UK Digital Transformation Market Intelligence
Enterprise-grade security certification is rotating from optional to mandatory across UK procurement frameworks. Microsoft Corporation leverages its Azure stack to sustain dominance in hybrid cloud deployments across NHS trusts and central government bodies. IBM Corporation anchors its position through specialized quantum-safe cryptography consulting for financial institutions in the City of London. Google LLC differentiates via edge computing partnerships with manufacturing clients in the Midlands.
UK digital transformation encompasses the systematic integration of cloud computing, artificial intelligence, and IoT sensors into core business processes, typically requiring API-first architecture and sub-100-millisecond latency thresholds for real-time decisioning. Its primary purpose is to replace legacy on-premise systems with scalable, data-driven infrastructure that reduces operational expenditure. Cloud-based deployment now leads in new contract value as CIOs prioritize elastic capacity over capital-intensive data center ownership. AI and machine learning applications within customer engagement represent the fastest-expanding margin pool, though cybersecurity spending matures fastest in regulated sectors.
The UK's Digital Markets, Competition and Consumers Act imposes interoperability mandates on designated platforms, forcing vendors to open APIs that previously locked clients into proprietary ecosystems. BSI Kitemark certification for data governance and the National Cyber Security Centre's Cyber Essentials Plus framework shape product standards for suppliers seeking public sector contracts. Stakeholders must monitor how Ofcom's forthcoming enforcement guidance on digital competition alters vendor selection criteria across regulated industries.
Market Dynamics
The UK Digital Transformation Market pivots on regulatory compulsion rather than discretionary technology refresh, as the Digital Markets, Competition and Consumers Act forces vendors to dismantle proprietary API lock-ins that previously secured multi-year client retention.
Growth Catalysts
- Interoperability Mandates:The Digital Markets, Competition and Consumers Act compels designated platforms to expose APIs, lowering switching costs for NHS trusts migrating from legacy on-premise stacks.
- Quantum-Safe Cryptography Urgency:Financial institutions in the City of London face accelerated compliance timelines from the National Cyber Security Centre's post-quantum guidance, spurring consulting engagements.
- Edge Computing in Manufacturing:Midlands-based automotive and aerospace OEMs deploy sub-50-millisecond latency infrastructure for predictive maintenance on IoT-connected production lines.
Market Restraints
- Skills Concentration Risk:Cloud-native architecture expertise clusters disproportionately in London and Manchester, inflating day rates for NHS and government body implementations outside these corridors.
- Cyber Certification Friction:Cyber Essentials Plus accreditation timelines stretch to 16 weeks for suppliers seeking central government contracts, filtering out mid-tier vendors.
- Legacy Technical Debt:COBOL and mainframe dependencies within UK retail banking block API-first migration paths, forcing expensive abstraction layer investments.
Strategic Opportunities
- Scottish Public Sector Modernization:NHS Scotland and Scottish Government digital procurement frameworks remain underpenetrated by hyperscale cloud providers relative to England.
- AI-Enabled Regulatory Reporting:Convergence of natural language processing and graph databases automates submission workflows for FCA-regulated asset managers.
- Net-Zero Data Center Incentives:The UK Green Finance Strategy unlocks preferential financing for carbon-negative edge facilities in Northern Ireland's renewable energy corridor.
Industry Challenges
- Integration Complexity with Heritage Systems:SAP and Oracle ERP estates in UK manufacturing resist seamless API connectivity, demanding costly middleware development.
- Specialized Talent Scarcity:Quantum cryptography implementation skills remain concentrated within a handful of London-based consultancies, constraining financial sector rollout velocity.
- BSI Kitemark Timeline Compression:Data governance certification requirements for public sector suppliers compress product development cycles without commensurate budget expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Digital Transformation Market |
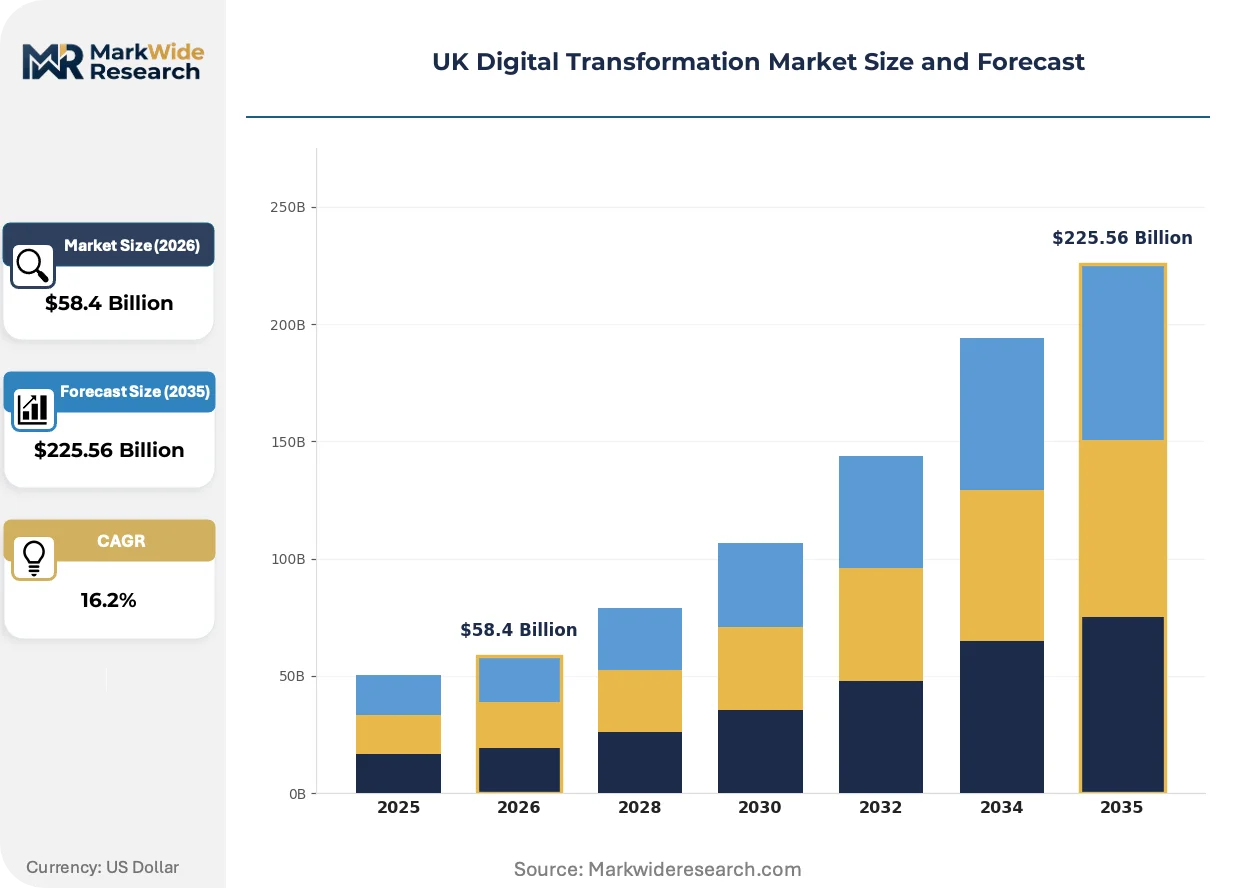
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $225.56 Billion |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing Technology: AI & Machine Learning, IoT, Big Data, Blockchain End User: Retailers, Financial Services, Healthcare Providers, Manufacturing Application: Customer Engagement, Supply Chain Optimization, Data Analytics, Cybersecurity |
| Companies Covered | Accenture PLC, Google LLC, Microsoft Corporation, IBM Corporation, SAP SE, Dell Inc., Hewlett Packard Enterprise Development LP, Oracle Corporation, Salesforce, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Digital Transformation Market Strategic Shifts & Innovations
Microservices architecture is fragmenting monolithic enterprise software procurement, while regulatory pressure on data sovereignty accelerates domestic cloud infrastructure deployment. These forces reshape vendor competitive moats and client retention mechanics simultaneously.
Container orchestration is decomposing traditional enterprise application suites into modular, API-driven components. Mid-market manufacturers in the West Midlands adopt Kubernetes-based deployments at twice the pace of 2022 baselines. This decomposition compresses incumbent software vendors' maintenance revenue streams while enabling specialized point-solution providers to capture discrete workflow segments.
The UK's Digital Markets, Competition and Consumers Act introduces mandatory data portability requirements for designated platforms. Financial services firms must now engineer interoperability layers that expose customer transaction histories to authorized third parties. Retail banking and wealth management verticals face the steepest compliance costs, with tier-one institutions pre-emptively opening sandbox environments to test API stability.
Subscription-based infrastructure provisioning displaces capital-intensive data center ownership among UK CIOs. NHS trusts and local authorities now prioritize operational expenditure models that elasticize compute capacity against patient service demand fluctuations. This shift concentrates most visibly in London's fintech corridor, where venture-backed insurtech startups eschew physical infrastructure entirely.
UK Digital Transformation Market Segmentation
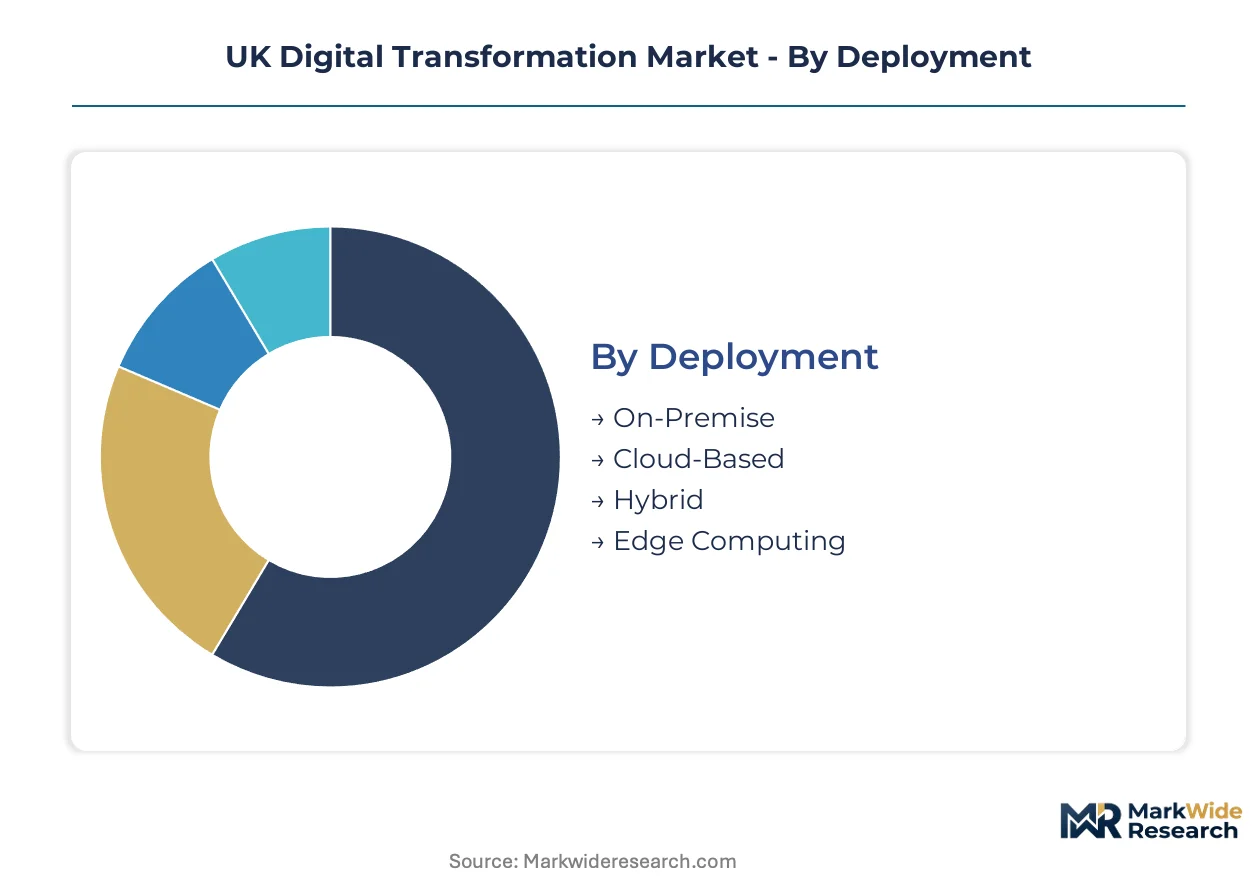
Segmentation reveals how regulatory pressure and infrastructure maturity create divergent investment patterns across UK digital transformation. Procurement frameworks favor certain deployment modes, while sector-specific compliance demands reshape technology selection criteria.
Deployment:
Domestic demand concentrates in cloud-based and hybrid architectures, whereas edge computing deployments track export-oriented manufacturing footprints in the Midlands.
- On-Premise:Legacy infrastructure retained for workloads requiring air-gapped security, particularly within Ministry of Defence contractors and classified government systems. NHS trusts in rural England maintain on-premise estates where connectivity constraints block cloud migration.
- Cloud-Based:Dominant procurement choice for new contracts, with elastic capacity matching variable demand in retail and fintech applications. London's venture-backed insurtech startups operate entirely through cloud-native stacks, eschewing physical infrastructure ownership.
- Hybrid:Bridges legacy ERP systems with modern API layers, prevalent among Tier 1 banks reconciling COBOL dependencies with customer-facing digital channels.
- Edge Computing:Sub-50-millisecond latency infrastructure deployed by automotive and aerospace OEMs in the West Midlands for predictive maintenance on IoT-connected production lines.
Cloud-based holds the largest share; momentum sits with edge computing.
Technology:
Cost tiers separate established infrastructure technologies from emerging compliance-driven investments, with AI commanding premium consulting rates while blockchain adoption lags in regulated sectors.
- AI & Machine Learning:Natural language processing and graph databases automate regulatory reporting workflows for FCA-regulated asset managers. Customer engagement applications generate the fastest-expanding margin pool as insurers deploy predictive underwriting models.
- IoT:Sensor networks on manufacturing production lines feed real-time telemetry into predictive maintenance systems. Deployment concentrates in aerospace supply chains around Derby and Bristol.
- Big Data:Data lake architectures support NHS population health analytics, integrating patient records across Integrated Care Systems.
- Blockchain:Distributed ledger pilots remain confined to trade finance consortia, with retail banking implementations stalled by interoperability mandates from the Digital Markets, Competition and Consumers Act.
AI & Machine Learning captures the highest-value consulting engagements; Big Data shows steadiest public sector traction.
End User:
Volume concentration varies sharply by geography, with financial services clustering in London and Manchester while manufacturing distributes across the Midlands and Northern England.
- Retailers:Omnichannel integration drives demand for real-time inventory visibility, with grocery chains deploying edge computing for supply chain responsiveness.
- Financial Services:Quantum-safe cryptography urgency from the National Cyber Security Centre accelerates consulting spend among City of London institutions. Open banking mandates force API-first architecture investments.
- Healthcare Providers:NHS trusts prioritize operational expenditure models elasticizing compute capacity against patient service demand fluctuations. Cyber Essentials Plus certification filters supplier pools.
- Manufacturing:Midlands-based automotive OEMs lead IoT sensor deployment for production line optimization, with aerospace suppliers following in the South West.
Financial Services commands the highest per-entity technology spend; Healthcare Providers show the steepest procurement volume growth.
Application:
Maturity curves separate established operational systems from emerging AI-infused engagement layers, with cybersecurity spending maturing fastest in regulated verticals.
- Customer Engagement:Conversational AI and personalization engines transform retail banking and insurance distribution. Natural language processing automates query resolution for utilities and telecoms operators.
- Supply Chain Optimization:Predictive analytics reduce inventory carrying costs for grocery and fashion retailers, with demand forecasting accuracy improving through machine learning.
- Data Analytics:Graph databases and streaming analytics support fraud detection in payments networks and anti-money laundering compliance.
- Cybersecurity:Zero-trust architecture adoption accelerates among FCA-regulated firms facing quantum threat timelines. Cyber Essentials Plus shapes public sector vendor selection.
Customer Engagement leads new contract value; Cybersecurity shows the most rapid budget normalization toward operational expenditure models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UK digital transformation sector runs a substantial services trade surplus, with London-based consultancies exporting cloud migration expertise to Commonwealth markets while importing specialized hardware from East Asian manufacturing hubs.
London and the Southeast
Financial services digitization and NHS trust modernization concentrate demand in this corridor. The Digital Markets, Competition and Consumers Act imposes interoperability mandates on platforms operating across England. The City of London and Canary Wharf host quantum-safe cryptography consulting engagements for tier-one banks.
The Midlands
Automotive and aerospace OEMs deploy edge computing infrastructure for predictive maintenance systems. The National Cyber Security Centre's Cyber Essentials Plus framework shapes supplier selection for defense contractors. Derby and Birmingham manufacturing clusters drive IoT sensor deployment on production lines.
North England
Manchester's emerging tech cluster attracts cloud-native architecture talent away from London's inflated day-rate market. Local procurement frameworks for combined authorities prioritize operational expenditure models over capital-intensive infrastructure. Leeds and Liverpool financial services firms invest in AI-enabled regulatory reporting systems.
Scotland
NHS Scotland and Scottish Government digital frameworks remain underpenetrated by hyperscale cloud providers relative to England. The Scottish National Investment Bank unlocks preferential financing for net-zero data center facilities. Edinburgh's fintech sector specializes in open banking API development.
Northern Ireland
The UK Green Finance Strategy accelerates carbon-negative edge facility development in Belfast's renewable energy corridor. Cybersecurity skills shortages constrain public sector modernization timelines. The city's software development sector exports regulatory technology solutions to London asset managers.
UK Digital Transformation Market Key Industry Players
Concentration sits with hyperscale cloud providers and global systems integrators that anchor public sector procurement frameworks. The vendor base stratifies across three tiers: infrastructure platforms, specialized consultancies, and point-solution developers. Dominant competitive moves include strategic partnerships with NHS trusts and portfolio diversification into quantum-safe cryptography services.
Among US-based technology conglomerates, Microsoft Corporation and Google LLC exemplify the infrastructure-platform archetype through their cloud stack dominance. IBM Corporation occupies a position within the specialized consultancy tier, anchoring quantum cryptography engagements for City of London financial institutions. SAP SE represents the enterprise application incumbent archetype, bridging legacy ERP estates with modern API layers.
| Leading Market Players |
|---|
| Accenture PLC |
| Google LLC |
| Microsoft Corporation |
| IBM Corporation |
| SAP SE |
| Dell Inc. |
| Hewlett Packard Enterprise Development LP |
| Oracle Corporation |
| Salesforce |
| Others |
Cost & Logistics Intelligence
Capacity reservation contracts with hyperscale cloud providers lock NHS trusts and financial institutions into predictable operational expenditure models while securing preferential access to elastic compute resources. These arrangements embed price visibility through multi-year commitments that trade volume guarantees against rate stability.
Pricing Analysis
Industrial OEM buyers anchor subscription-based SaaS pricing across the UK digital transformation sector. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade security certification tiers, with Cyber Essentials Plus compliance commanding substantial premiums. Cost compression in mid-market consulting tiers intensifies as Manchester-based talent pools expand. Healthcare providers exhibit the highest price sensitivity due to fixed NHS procurement budgets, while City of London financial institutions prioritize capability over cost.
Supply Chain Analysis
Strait of Hormuz transit underwrites a portion of UK data center hardware supply chains, though domestic edge facility construction is reducing this dependency. Hardware components draw from Taiwan, South Korea, and the USA, with specialized quantum cryptography modules sourced from Switzerland and the Netherlands. Single-source vulnerability concentrates in advanced semiconductor fabrication. Distribution runs through London-based systems integrators that anchor public sector procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native architecture skills scarcity constrains rollout velocity across NHS trusts and government bodies outside London and Manchester, creating asymmetric competition between talent-rich corridors and underserved regions.
For Market Incumbents: Consolidate quantum-safe cryptography consulting capabilities through specialist acquisitions before NCSC compliance timelines accelerate. Deepen channel control over Scottish and Northern Irish public sector procurement frameworks where hyperscale presence remains thin. The Digital Markets, Competition and Consumers Act's interoperability mandates threaten proprietary API lock-ins that previously secured retention.
For New Entrants and Emerging Players: Anchor in NHS Scotland and Scottish Government digital frameworks where incumbent penetration lags England. Target net-zero edge facility development in Northern Ireland's renewable energy corridor, leveraging UK Green Finance Strategy incentives. Lead with carbon-negative infrastructure credentials as a differentiated procurement wedge.
For Investors and Strategic Acquirers: Boutique consultancies possessing NCSC-certified quantum cryptography implementation teams represent the most defensible acquisition archetype. Long-term viability hinges on regulatory compliance service depth rather than commodity cloud provisioning. Monitor Ofcom's forthcoming digital competition enforcement guidance as an inflection signal for vendor selection criteria shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Quantum-Safe Cryptography Practice Buildout | NCSC post-quantum guidance accelerates consulting demand from City of London tier-one banks. |
| Scottish Public Sector Framework Entry | NHS Scotland procurement remains underpenetrated relative to English trusts and central government. |
| Net-Zero Edge Facility Development | UK Green Finance Strategy unlocks preferential financing for carbon-negative infrastructure in Belfast. |
| API-First Platform Integration | Digital Markets, Competition and Consumers Act mandates force interoperability layer investments. |
| Cyber Essentials Plus Certification Investment | BSI Kitemark requirements filter supplier pools for central government contracts. |
Research Approach
The analysis maps cloud deployment architectures, AI application segments, and cybersecurity compliance tiers, each validated through CTOs, NHS digital transformation leads, procurement officers at financial institutions, and platform engineers. Primary interview insights triangulate against secondary sources including NHS Digital procurement disclosures, FCA regulatory filings, National Cyber Security Centre guidance documents, and hyperscaler capex reports. Bottom-up contract value aggregation cross-checks against top-down market sizing across the analysis window.
Consistency checks validate volume and value outputs against external benchmarks including public sector IT spending disclosures and venture capital deployment tracking. Segmentation models incorporate deployment mode, organization size, vertical regulatory intensity, and geographic talent cluster proximity throughout the forecast period. CAGRs derive from elasticity-adjusted adoption curves and compliance-driven replacement cycles specific to financial services quantum migration timelines and NHS legacy modernization schedules.
Decision-makers should treat outputs as directional under stable regulatory enforcement assumptions; material deviation in Ofcom's digital competition implementation would warrant model refresh. Practitioners should keep alternative scenarios live as post-quantum cryptography compliance deadlines and Scottish procurement framework awards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
Netherlands Digital Transformation Market
Digital Transformation
Israel Digital Transformation Market
Digital Transformation
MENA Digital Transformation Market
Digital Transformation
APAC Digital Transformation Market
Digital Transformation
Malaysia Digital Transformation Market
Digital Transformation
Brazil Digital Transformation Market
Digital Transformation
Canada Digital Transformation Market
Digital Transformation
SQL Server Transformation Market
Digital Transformation
Mexico Digital Transformation Market
Digital Transformation
Workplace Transformation Market
Digital Transformation
Telco Transformation Market
Digital Transformation
France Digital Transformation Market
Digital Transformation
Digital Platform Scale Market
Digital Transformation
Nigeria Digital Transformation Market
Digital Transformation
Germany Digital Transformation Market
Digital Transformation
Automotive Digital Transformation Market