

RIP Color Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
RIP Color Management Software Market Insights
Modular bundling of color matching with workflow automation is rebalancing how print houses evaluate total cost of ownership. Electronics for Imaging leverages its installed base of wide-format printers to extend software attach rates. Onyx Graphics anchors its position in sign and display markets through specialized RIP modules for UV-cured inksets. Caldera competes by sustaining deep integration with textile printing hardware, particularly in dye-sublimation workflows.
RIP color management software comprises raster image processing engines that translate continuous-tone design files into halftoned, device-specific color separations using ICC profiles and spectral measurement data, ensuring delta-E accuracy typically below 2.0 across proofing and production stages. Its primary commercial purpose is to eliminate color variance between design intent and printed output across substrates ranging from uncoated paper to flexible packaging films. Cloud-based deployment is attracting mid-size print brokers seeking lower capital barriers, while on-premise systems still dominate high-security publishing environments where color data must remain air-gapped. Workflow automation as a solution type is capturing disproportionate margin pools as printers consolidate prepress steps into unified job ticketing systems.
FDA labeling requirements for pharmaceutical packaging, EU Green Deal waste-reduction mandates enforced through ECHA guidelines, and ISO 12647 color standard audits all shape product roadmaps and certification thresholds for RIP vendors. Germany's KBA and France's ANSM both reference color consistency in serialized packaging regulations, creating compliance-driven replacement cycles. Stakeholders must weigh whether to absorb rising certification costs internally or pass them through as premium-tier software modules.
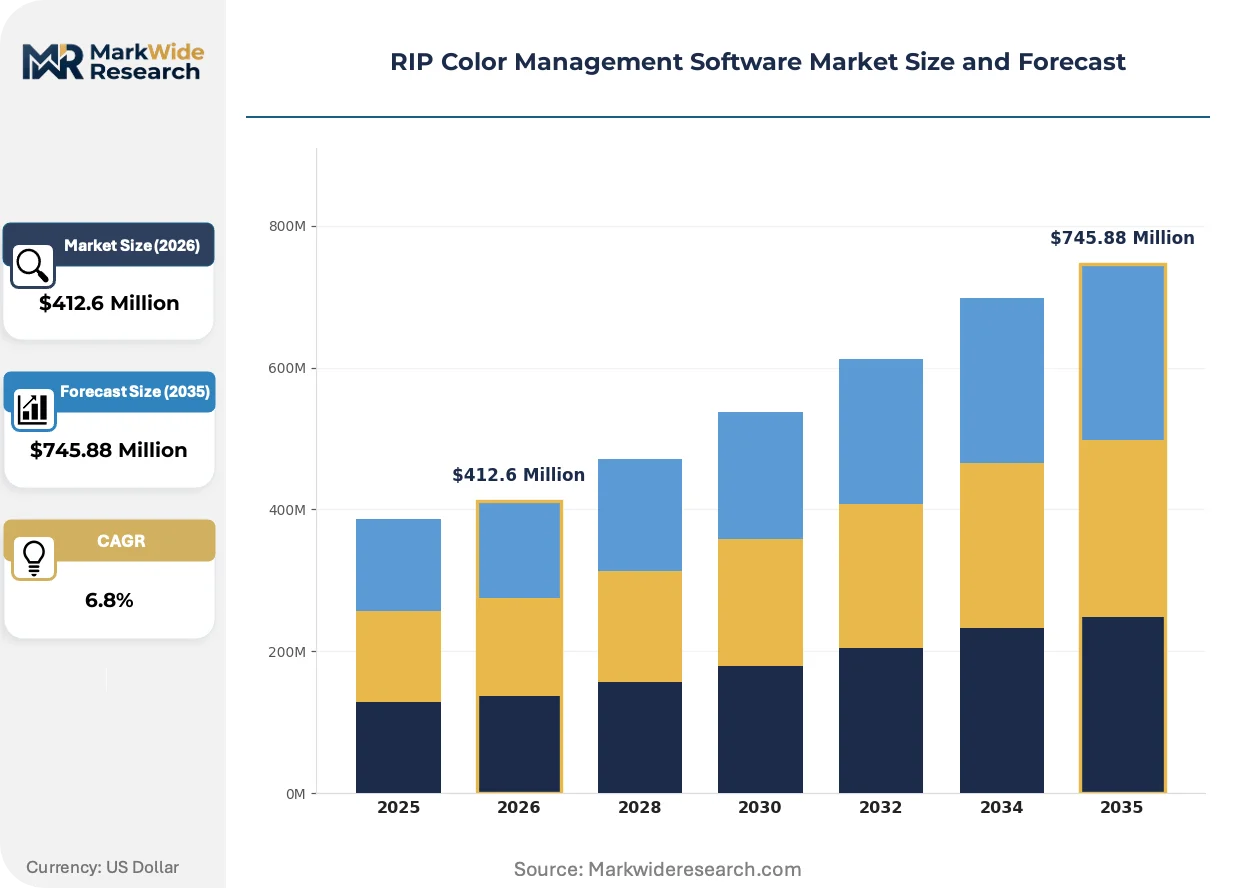
Market Dynamics
Cloud-based color calibration is compressing replacement cycles for legacy on-premise RIP installations across mid-market print houses, while EU Green Deal waste mandates force compliance-driven upgrades in pharmaceutical and food packaging workflows.
Growth Catalysts
- EU Green Deal waste-reduction mandates:ECHA-enforced guidelines requiring precise color proofing to minimize print waste are triggering system replacements among European packaging converters.
- Dye-sublimation textile printing:Specialized RIP modules for fabric decoration are capturing volume in fashion and home décor production clusters.
- Serialized pharmaceutical packaging:FDA labeling requirements and France's ANSM color consistency regulations are mandating delta-E accuracy below 2.0 for drug labels.
Market Restraints
- Spectral measurement hardware dependency:RIP software performance ties directly to spectrophotometer precision, creating input cost volatility when sensor suppliers raise prices.
- ICC profile fragmentation:Proprietary color science from dominant hardware vendors locks print houses into single-supplier ecosystems, raising switching costs.
- Legacy system entrenchment:High-security publishing environments in government and defense sectors resist cloud migration, capping addressable market expansion.
Strategic Opportunities
- Workflow automation convergence:Integration of job ticketing, color management, and production scheduling into unified platforms is electrifying margin pools for vendors with prepress software heritage.
- UV-cured inkset specialization:Dedicated RIP modules for rigid substrate printing in sign and display markets address unmet calibration needs.
- ISO 12647 certification services:Third-party audit preparation bundled with software subscriptions creates recurring revenue streams.
Industry Challenges
- Spectral color science expertise scarcity:Print houses struggle to hire technicians proficient in ICC profile generation and delta-E troubleshooting.
- Multi-vendor integration complexity:Harmonizing RIP outputs across mixed fleets of wide-format, offset, and digital presses demands custom middleware development.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RIP Color Management Software Market Trends and Innovations
Artificial intelligence is embedding into color prediction engines, shifting competitive advantage toward vendors with training data access. Regulatory pressure on packaging waste is accelerating software-led precision over hardware redundancy. Buyer expectations are compressing from annual calibration cycles to real-time cloud-based verification.
Machine learning-driven spectral prediction is electrifying prepress workflows by reducing physical proofing iterations. Large-format print houses in Germany's industrial corridor are adopting neural color engines that forecast substrate-ink interactions before press runs. This capability is compressing job turnaround times from days to hours while cutting consumable waste.
REACH chemical compliance is forcing reformulation of ink chemistries used in food-contact packaging, requiring RIP vendors to recalibrate separation tables for new pigment sets. Print service providers serving European consumer brands are rebuilding profile libraries to maintain color accuracy under stricter ECHA substance restrictions. Germany's KBA and France's ANSM both reference these color standards in pharmaceutical serialization audits.
Subscription-based color verification is displacing perpetual license models among mid-size print brokers seeking lower capital barriers. Cloud-native RIP deployments are capturing share in commercial print segments where job volumes fluctuate seasonally. North American packaging converters are piloting usage-based pricing for peak production periods, unbundling software access from hardware ownership.
RIP Color Management Software Market Segmentation
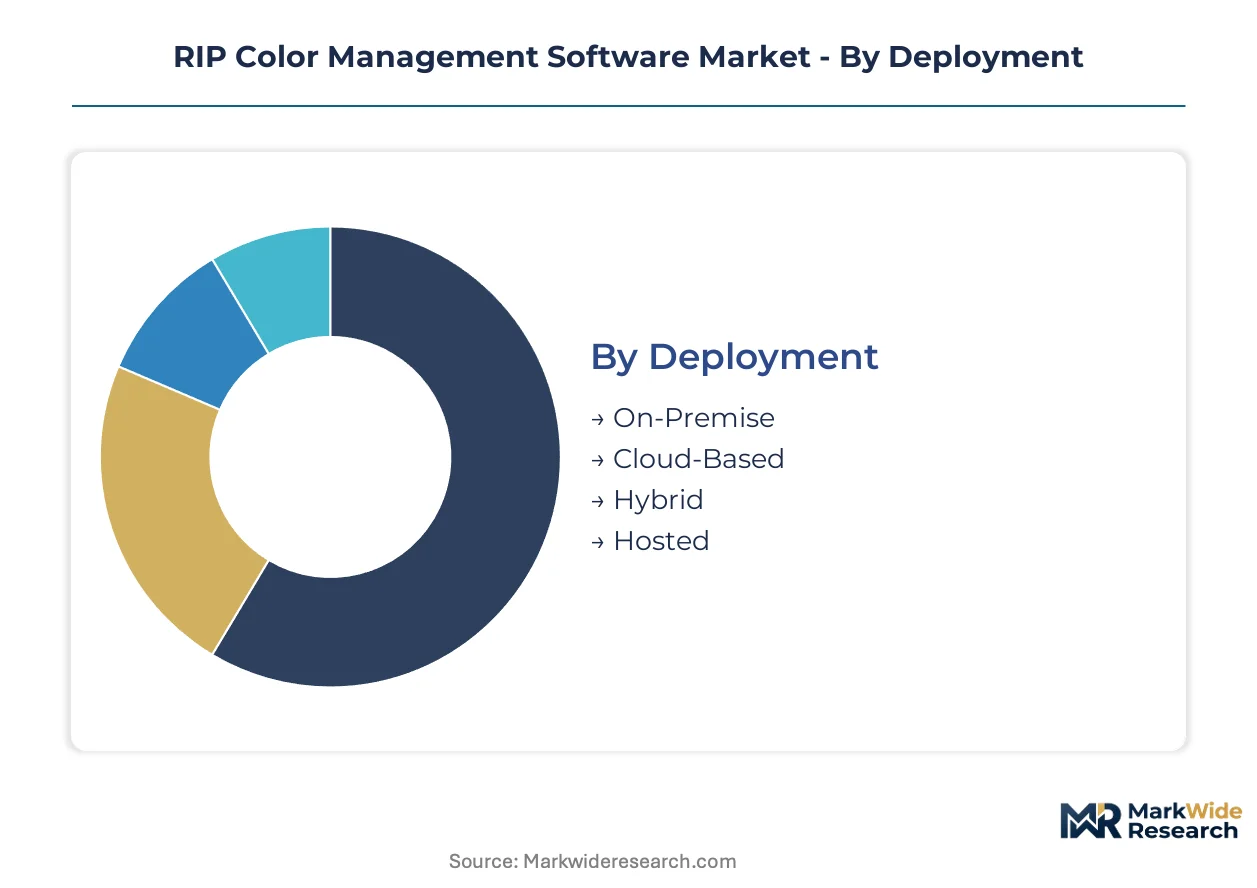
RIP color management software segments diverge sharply on certification burdens and compliance exposure. Deployment mode determines audit trail requirements under FDA and ECHA guidelines, while solution type dictates whether vendors must maintain ISO 12647 certification services.
Deployment:
FDA labeling requirements for pharmaceutical packaging and ECHA waste-reduction mandates impose distinct certification loads across deployment architectures.
- On-Premise:Air-gapped installations dominate defense publishing and high-security government environments where color data must remain physically isolated. Germany's KBA references these systems in serialized packaging audits for drug manufacturers.
- Cloud-Based: Mid-size print brokers in France and commercial houses in Italy are adopting subscription models to lower capital barriers. ECHA-compliant proofing workflows drive demand where waste reduction mandates require real-time color verification.
- Hybrid: Combines local RIP processing with cloud-based profile libraries, appealing to packaging converters facing seasonal volume spikes.
- Hosted:Managed service deployments concentrate among North American print brokers seeking outsourced IT overhead reduction.
On-Premise sits at the top of the volume ranking, with Cloud-Based climbing the fastest.
Solution Type:
Margin pools concentrate where prepress steps consolidate into unified platforms, reshaping how print houses evaluate total cost of ownership.
- Workflow Automation:Job ticketing systems that integrate color management with production scheduling capture disproportionate margin pools. Packaging houses in Germany's industrial corridor replace legacy RIP systems with these unified platforms to compress turnaround times.
- Color Matching: ICC profile generation engines ensure delta-E accuracy below 2.0 across proofing stages. Textile printers in dye-sublimation clusters demand specialized modules for fabric-ink interaction prediction.
- Proofing: Soft-proofing systems reduce physical iteration counts under EU Green Deal waste mandates.
- Calibration:Spectral measurement integration ties software performance to spectrophotometer precision.
- Image Enhancement:Prepress correction tools address substrate-specific color reproduction challenges.
Workflow Automation commands the dominant revenue share, though Color Matching shows the steepest expansion trajectory among specialized modules.
Application:
Regulatory pressure on packaging waste accelerates software-led precision over hardware redundancy across print categories.
- Packaging:Pharmaceutical and food-contact packaging face the strictest compliance loads. France's ANSM and Germany's KBA both reference color consistency in serialization regulations, forcing delta-E accuracy below 2.0.
- Digital Printing: Wide-format and commercial digital presses require substrate-specific separation tables. REACH chemical compliance forces recalibration for reformulated ink chemistries in European consumer brand supply chains.
- Textile Printing: Dye-sublimation workflows for fashion and home décor production clusters demand specialized RIP modules.
- Commercial Printing:General job production where cloud-native deployments gain share among volume-fluctuating operations.
- Labeling:Narrow-web applications with concentrated FDA labeling exposure for drug and medical device packaging.
Packaging leads absolute revenue contribution, while Digital Printing gains share fastest as cloud calibration tools compress replacement cycles.
End User Industry:
Procurement authority and technical sophistication vary sharply across buyer types, fragmenting sales motion requirements.
- Print Brokers:Mid-size intermediaries pilot usage-based pricing and cloud-native deployments to match seasonal demand fluctuations without hardware ownership.
- Publishing Houses:High-security government and defense publishers resist cloud migration, maintaining on-premise systems for air-gapped color data.
- Advertising Agencies:Creative shops prioritize soft-proofing speed over production calibration precision.
- Graphic Designers:Individual practitioners and small studios drive entry-tier subscription demand for color-accurate client presentations.
Print Brokers represent the fastest-expanding customer category, with Publishing Houses retaining the largest installed base of legacy perpetual licenses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Color management software originated in German prepress laboratories during the 1990s commercialization of ICC profiling standards. Heidelberg and Munich research institutes pioneered delta-E measurement protocols that migrated to North American wide-format printing clusters by the early 2000s.
Germany
Pharmaceutical serialization mandates from the KBA drive compliance-heavy RIP upgrades across Baden-Württemberg packaging houses. The EU Green Deal's waste-reduction framework tightens proofing accuracy requirements for food-contact substrates. Stuttgart's industrial print corridor hosts concentrated replacement cycles as converters abandon legacy perpetual licenses for subscription-based workflow automation.
United States
FDA labeling requirements for pharmaceutical packaging force delta-E accuracy below 2.0 across narrow-web label converters. Cloud-native deployments gain traction among mid-size print brokers in the Northeast seeking seasonal volume flexibility. Chicago's commercial printing cluster pilots usage-based pricing models that unbundle software access from hardware ownership.
France
ANSM color consistency regulations in pharmaceutical serialization audits trigger system replacements among Paris-region packaging specialists. REACH chemical compliance forces recalibration of separation tables for reformulated food-contact ink chemistries. Lyon and Grenoble textile production clusters demand specialized dye-sublimation RIP modules for fashion and home décor workflows.
United Kingdom
ISO 12647 certification services create recurring revenue opportunities as London-area print houses prepare for third-party audits. Publishing houses in the Southeast maintain air-gapped on-premise systems for high-security government color data. Manchester's commercial printing sector adopts hybrid deployments combining local RIP processing with cloud-based profile libraries.
Japan
METI standards for industrial printing precision shape product roadmaps for wide-format and textile RIP vendors. Osaka-Kobe manufacturing clusters integrate neural color engines that forecast substrate-ink interactions before press runs. Tokyo-area advertising agencies prioritize soft-proofing speed over production calibration precision in creative workflows.
RIP Color Management Software Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and workflow integration breadth. The vendor base stratifies into three tiers: integrated workflow automation platforms capturing disproportionate margin pools, specialized RIP module developers serving substrate-specific niches, and legacy perpetual-license maintainers defending installed bases. Consolidation pressure concentrates among mid-tier developers lacking cloud-native architectures or AI-enabled color prediction engines. Dominant competitive moves include strategic partnerships between RIP vendors and spectrophotometer manufacturers, plus portfolio diversification into subscription-based verification services.
Within the integrated platform tier, Electronics for Imaging and Onyx Graphics exemplify divergent specialization strategies. EFI leverages its wide-format printer installed base to extend software attach rates across commercial and packaging segments. Onyx Graphics anchors its competitive position through dedicated UV-cured inkset modules for rigid substrate applications in sign and display markets. Caldera occupies a distinct position among textile-focused specialists, sustaining deep hardware integration for dye-sublimation workflows in European and Asian fashion production clusters.
| Leading Market Players |
|---|
| Electronics for Imaging |
| Onyx Graphics |
| Caldera |
| Ergosoft AG |
| Mimaki Engineering |
| GMG Color |
| Wasatch Computer Technology |
| OneVision Software AG |
| Serendipity Software Pty |
| Others |
Pricing and Supply Chain Analysis
Spectrophotometer sensor costs cascade through RIP software tiers, with German precision hardware anchoring premium pricing while Asian-manufactured alternatives compress mid-market subscription rates for print brokers in France and Italy.
Pricing Analysis
Subscription-based SaaS tiers with usage-scaled access dominate the market structure. Pricing stratifies across ISO 12647-certified premium modules, standard workflow automation bundles, and economy-tier color matching tools. Cost compression in the economy tier intensifies because cloud-native entrants undercut legacy perpetual licenses. Mid-size print brokers exhibit the highest price sensitivity, while pharmaceutical packaging houses prioritize certification-grade accuracy over cost.
Supply Chain Analysis
EU Green Deal domestic-content mandates for sustainable manufacturing are reshaping sourcing patterns across the RIP ecosystem. Software development concentrates in Germany, the United States, and Japan, with spectral measurement hardware drawing from Swiss and Japanese sensor specialists. The supply chain rests on proprietary ICC profile libraries, spectrophotometer components, and cloud infrastructure services. Single-source vulnerability runs through dominant spectrophotometer suppliers. Distribution runs through direct vendor sales teams and specialized print equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between EU Green Deal compliance costs and FDA certification burdens creates geographic expansion opportunities for vendors with dual-continent certification capabilities.
For Market Incumbents: Lock in pharmaceutical packaging accounts by embedding ISO 12647 certification services into subscription renewals before cloud-native challengers achieve audit-ready accuracy. Prioritize backward integration into spectrophotometer partnerships to secure sensor supply against hardware vendor price volatility. Defend against AI-enabled color prediction entrants by acquiring training data reservoirs from textile and packaging production clusters. For New Entrants and Emerging Players: The mid-market gap between EFI's premium workflow platforms and entry-level color matching tools offers white-space entry through specialized dye-sublimation modules for Lyon and Grenoble textile clusters. Target hybrid deployment architectures for Manchester and Chicago commercial printers seeking seasonal flexibility without full cloud migration. Lead with API-first integration to bypass entrenched sales channel relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier developers lack cloud-native architectures or AI-enabled spectral engines. Long-term viability favors vendors with captive training data from multi-substrate production environments. Acquisition targets include textile-specialized RIP developers with deep Caldera-competitive integration and ISO 12647 audit preparation services. Watch for inflection when pharmaceutical serialization mandates expand beyond EU and US jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enabled Color Prediction Engine Launch | Neural spectral forecasting cuts physical proofing iterations for German packaging houses under ECHA waste mandates. |
| Strategic Partnership with Spectrophotometer Manufacturer | Sensor supply security locks in delta-E accuracy guarantees for FDA-compliant pharmaceutical label workflows. |
| ISO 12647 Certification Service Bundling | Third-party audit preparation creates recurring revenue from KBA and ANSM serialization compliance cycles. |
| Geographic Expansion into Textile Production Clusters | Dye-sublimation module deployment captures Lyon and Grenoble fashion décor volume from Caldera-specialized incumbents. |
| Acquisition of Cloud-Native Workflow Developer | Mid-market subscription architecture accelerates displacement of legacy perpetual-license installed bases. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with RIP software product managers, print house prepress directors, spectrophotometer manufacturer sales engineers, and packaging converter procurement leads informed demand-side dynamics. Secondary sources include SEC filings from listed print equipment vendors, ECHA regulatory guidance documents, FDA labeling compliance databases, and ISO certification body audit records. Bottom-up triangulation across deployment mode, solution type, and application segments reconciled with top-down market sizing.
Rate-of-change decomposition separates volume expansion from value migration across the projection horizon. Segmentation dimensions modeled include deployment architecture, solution type, application category, and end-user industry sophistication tier. CAGRs derive from fitted growth curves against historical replacement cycle data and regulatory mandate timelines. Industry-specific forecast inputs incorporate EU Green Deal waste-reduction enforcement schedules and pharmaceutical serialization rollout patterns.
The model assumes a particular technology adoption path; alternative pathways for AI-driven spectral prediction would alter the outlook if training data access concentrates among fewer vendors than projected. Forecasts reflect assumptions about cloud migration willingness in high-security publishing segments and spectrophotometer cost trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.