
 Database Monitoring Software Market | 2026-2036
Database Monitoring Software Market Size, Share, and Industry Trends Forecast 2026-2036
Database Monitoring Software Market Analysis
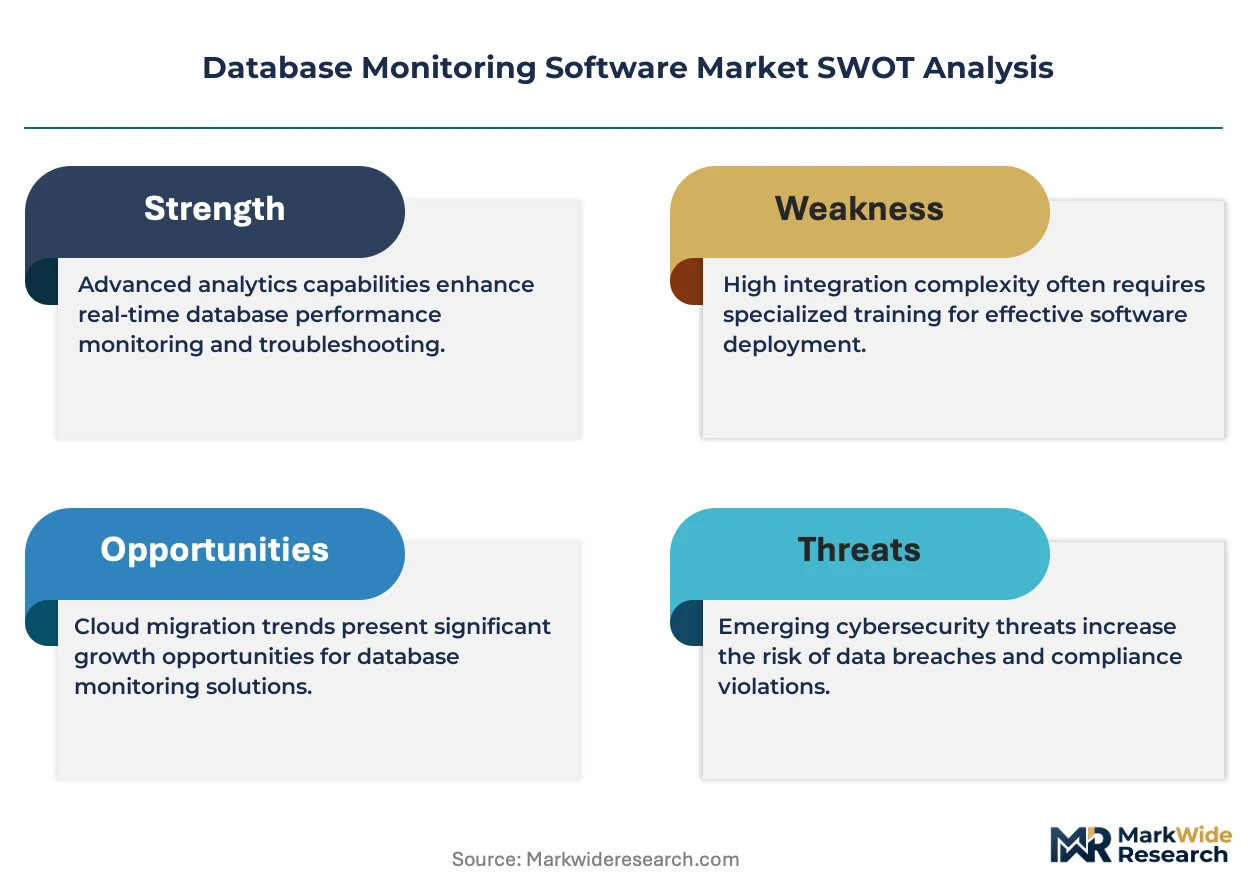
Modular subscription packaging is shifting buyer choice in database monitoring software as enterprises seek to unbundle all-in-one suites into component services. Datadog, Inc. leverages its cloud-native architecture to compete across multi-cloud environments. Dynatrace LLC anchors its position through AI-driven causal analysis capabilities. SolarWinds Worldwide, LLC sustains mid-market penetration with on-premise deployment flexibility.
Database monitoring software encompasses tools that track query performance, resource utilization, and availability metrics across relational and non-relational database management systems through agent-based or agentless collection methods. These systems serve the primary commercial purpose of preventing downtime, optimizing resource allocation, and ensuring data integrity for business-critical applications. Cloud-based deployment leads in new contract value while AI-driven technology segments capture expanding margin pools from predictive failure detection. Enterprise end users dominate current revenue but SMBs represent the fastest-growing adoption tier as managed service providers bundle monitoring into broader infrastructure offerings.
FDA 21 CFR Part 11 requirements shape validation protocols for pharmaceutical database systems while HIPAA Security Rule mandates drive healthcare provider investment in access-log monitoring. The EU AI Act introduces algorithmic transparency obligations that extend to database layers feeding automated decision systems. Stakeholders must evaluate how emerging cross-border data governance frameworks will alter deployment architecture requirements and vendor qualification criteria.
Market Dynamics
Real-time observability requirements from distributed cloud architectures are compressing traditional monitoring refresh cycles from minutes to sub-second intervals, forcing architectural redesign across vendor portfolios.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:Automated decision systems in financial services and healthcare must maintain auditable database query logs, expanding monitoring scope beyond performance to compliance verification.
- Connected manufacturing latency thresholds:German automotive clusters require sub-millisecond monitoring for industrial IoT data pipelines, pulling specialized tooling into operational technology budgets.
- Agentless collection architectures:Containerized microservices deployments favor passive network traffic analysis over traditional agent installation, reducing deployment friction in ephemeral environments.
Market Restraints
- Specialized talent scarcity:Shortage of engineers proficient in both database internals and cloud-native instrumentation limits enterprise self-deployment velocity.
- Input cost concentration:Cloud compute and egress fees from hyperscalers constitute 40-60% of delivered monitoring costs, constraining margin expansion for independent software vendors.
- Legacy relational persistence:Mainframe and on-premise Oracle estates resist full observability integration, fragmenting visibility across hybrid estates.
Strategic Opportunities
- NIS2 Directive procurement windows:European critical infrastructure operators face 2024-2025 compliance deadlines, creating concentrated demand for certified monitoring stacks.
- Edge database proliferation:SQLite and specialized time-series engines in retail and logistics IoT endpoints lack mature monitoring, representing greenfield attach opportunities.
- OpenTelemetry standardization:Vendor-neutral telemetry formats enable multi-tool data portability, lowering switching costs and opening mid-market consolidation paths.
Industry Challenges
- Cross-functional observability silos:Database, infrastructure, and application monitoring teams maintain separate tooling budgets and success metrics, complicating unified platform sales.
- FDA 21 CFR Part 11 validation overhead:Pharmaceutical deployments require documented installation qualification and operational qualification protocols, extending sales cycles by 6-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Database Monitoring Software Market |
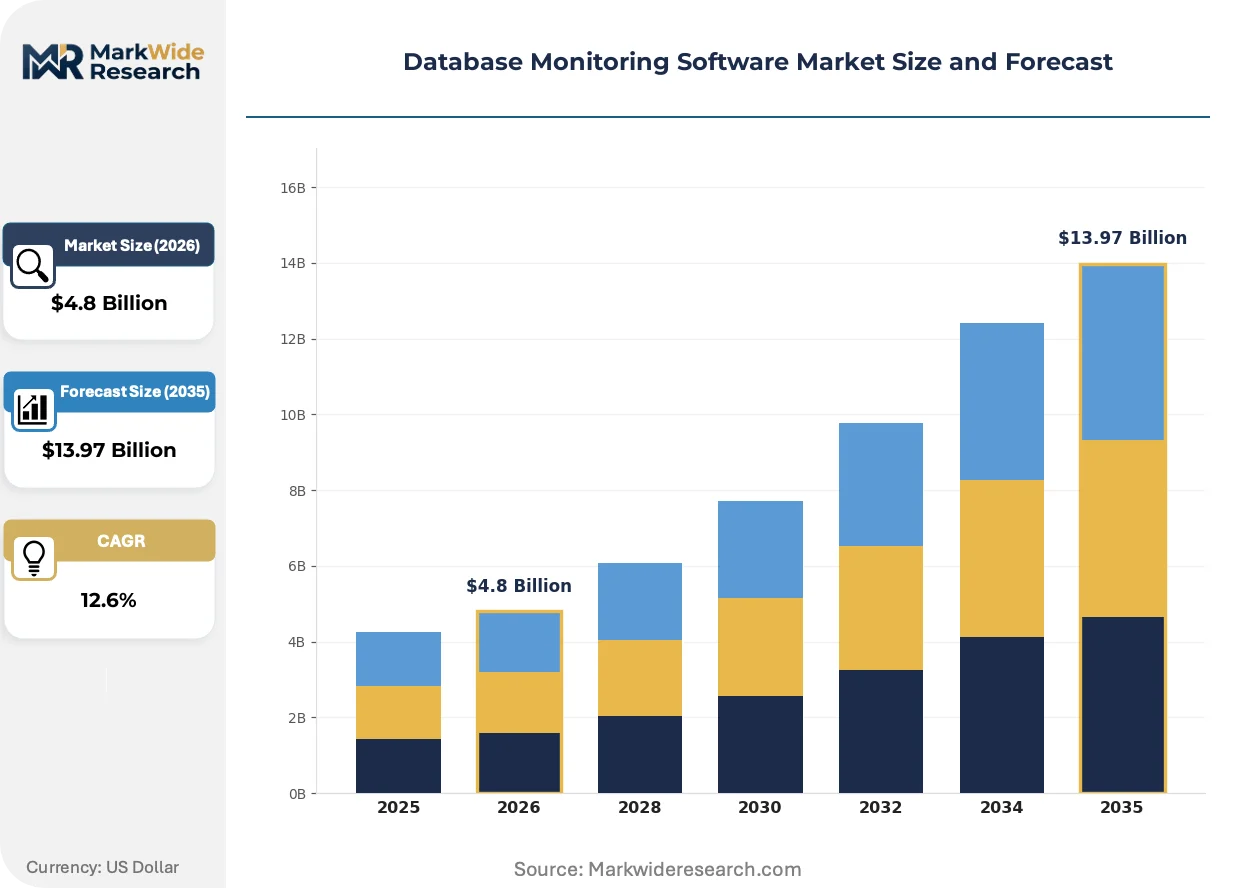
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based, On-premise, Hybrid, Open-source End User: Enterprise, SMBs, Government, Educational Institutions Deployment: Public Cloud, Private Cloud, Multi-cloud, Bare-metal Technology: AI-driven, Performance Metrics, Automated Alerts, Query Optimization |
| Companies Covered | Datadog, Inc., Dynatrace LLC, SolarWinds Worldwide, LLC, Quest Software Inc., Oracle Corporation, Paessler AG, Nagios Enterprises, LLC, eG Innovations, Heroix Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Database Monitoring Software Market Emerging Trajectories
Observability pipelines are absorbing adjacent security and cost-management functions, collapsing previously distinct software categories into unified data platforms.
eBPF kernel instrumentation is decentralizing collection architecture by enabling zero-overhead telemetry extraction without process modification. Financial services firms in Frankfurt and Singapore are deploying eBPF-based agents at scale for payment processing visibility. This kernel-level approach is decentralizing monitoring intelligence from centralized collectors to distributed edge nodes.
REACH chemical data management extensions are forcing pharmaceutical and materials companies to instrument R&D databases for audit trail completeness. The regulation mandates 10-year retention of substance safety data, expanding storage monitoring scope to archival systems. German chemical conglomerates are prioritizing validation-ready tools that pre-map to ECHA submission formats.
Enterprise buyers are unbundling monitoring from broader infrastructure contracts, creating direct procurement relationships with specialized vendors. Managed service providers previously reselling bundled suites now face disintermediation as end-users demand component-level pricing transparency. This disaggregation is most pronounced in US healthcare systems navigating HIPAA Security Rule vendor qualification requirements.
Database Monitoring Software Market Segmentation
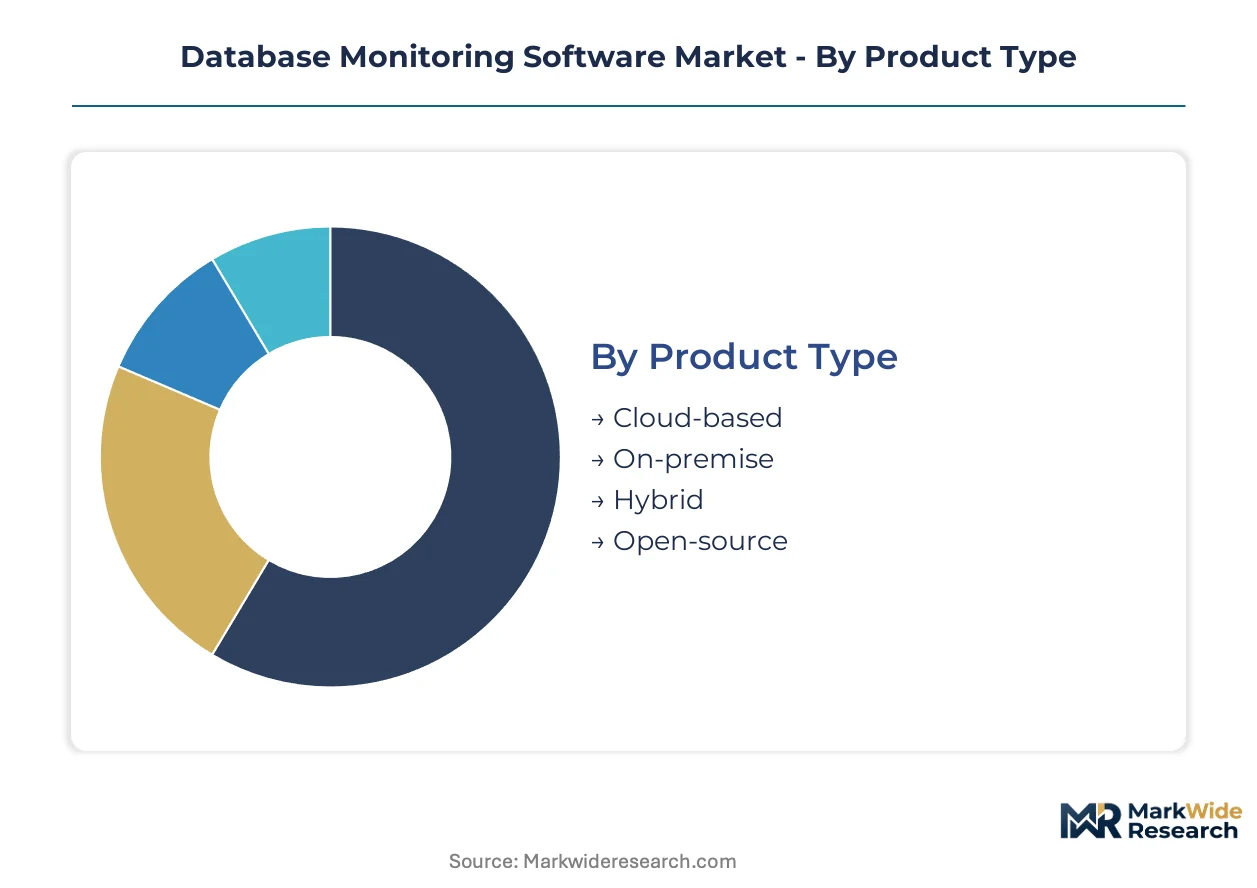
Database monitoring software segmentation reflects divergent infrastructure maturity and compliance requirements across buyer organizations. Procurement patterns split between cloud-native architectures and legacy persistence estates, while technology adoption varies sharply by data sensitivity and operational criticality.
Product Type:
Standardized SaaS delivery dominates new contract flow, yet customization demands persist in regulated verticals requiring data sovereignty controls.
- Cloud-based:Fully managed services with elastic compute scaling and API-native integration architectures. Financial services firms in Frankfurt and Singapore deploy these for payment processing visibility where sub-millisecond latency thresholds apply.
- On-premise:Licensed software deployed within customer-controlled data centers with full configuration autonomy. Pharmaceutical manufacturers under FDA 21 CFR Part 11 requirements favor these for documented installation qualification protocols.
- Hybrid:Split architectures synchronizing cloud analytics with on-premise data retention. German automotive clusters use these for connected manufacturing environments balancing edge processing with centralized compliance storage.
- Open-source:Community-developed tools with customizable telemetry pipelines and no licensing fees. Managed service providers bundle these into broader infrastructure offerings for cost-conscious SMBs.
Leading the category by volume: Cloud-based. Growing fastest: Hybrid.
End User:
Procurement authority concentrates with infrastructure teams, yet budget fragmentation across security and compliance functions shapes vendor selection.
- Enterprise:Multi-division organizations with dedicated database reliability engineering teams and formal vendor qualification processes. These buyers demand AI-driven predictive capabilities for distributed cloud architectures.
- SMBs:Resource-constrained organizations procuring through managed service providers or bundled infrastructure suites. This tier expands most quickly as channel partners unbundle monitoring into component services.
- Government:Public sector agencies with sovereign data requirements and extended procurement cycles. European critical infrastructure operators under NIS2 Directive deadlines drive certified stack demand.
- Educational Institutions:Universities and research organizations with episodic workload patterns and grant-funded technology refresh cycles. These buyers prioritize open-source tooling for budget flexibility.
Enterprise captures dominant revenue share. SMBs gain share fastest through MSP channel expansion.
Deployment:
Architecture choices track hyperscaler relationships and data residency mandates, with portability concerns rising as egress costs concentrate.
- Public Cloud:Single-tenant or multi-tenant services hosted on AWS, Azure, or GCP infrastructure. Containerized microservices deployments favor these for ephemeral environment compatibility.
- Private Cloud:Dedicated infrastructure with isolated network segments and custom security postures. Healthcare providers navigating HIPAA Security Rule requirements select these for access-log monitoring control.
- Multi-cloud:Orchestrated visibility across heterogeneous hyperscaler environments. These architectures address cloud migration mandates under EU AI Act algorithmic transparency obligations.
- Bare-metal:Direct hardware deployment without virtualization abstraction for maximum I/O performance. High-frequency trading operations in Frankfurt deploy these for kernel-level telemetry extraction.
Public Cloud leads contract value. Multi-cloud shows steepest expansion trajectory as buyers diversify vendor risk.
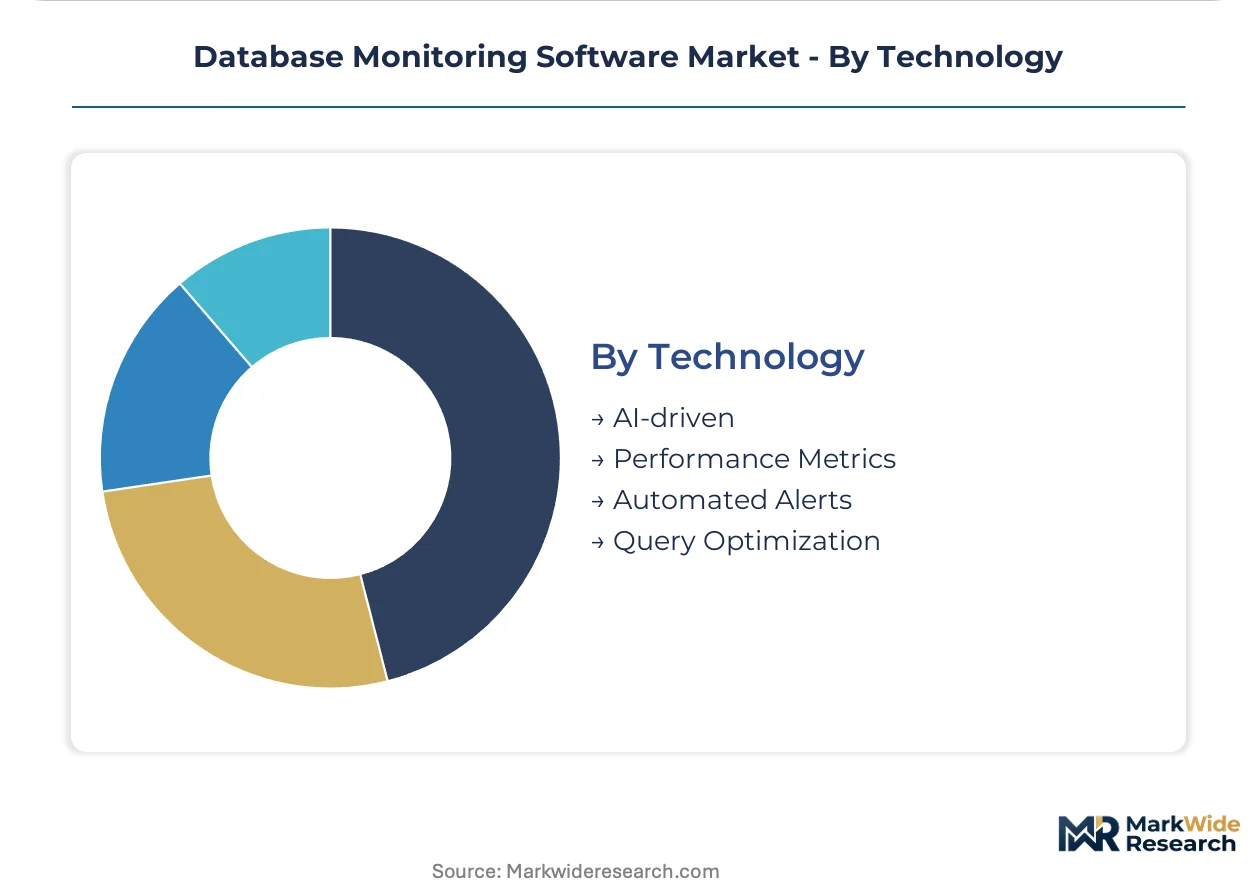
Technology:
Capability layering determines margin capture, with predictive functions commanding premium positioning over reactive monitoring.
- AI-driven:Machine learning models for anomaly detection, root cause analysis, and capacity forecasting. These systems capture expanding margin pools from predictive failure detection.
- Performance Metrics:Baseline telemetry collection for throughput, latency, and resource utilization tracking. Legacy relational persistence estates rely heavily on these for visibility into mainframe and Oracle systems.
- Automated Alerts:Threshold-based notification systems with escalation workflows and incident ticketing integration. REACH chemical data management extensions drive pharmaceutical investment in these for audit trail completeness.
- Query Optimization:Execution plan analysis and indexing recommendations for database performance tuning. Development teams in software clusters use these to prevent downtime for business-critical applications.
AI-driven commands premium pricing. Query Optimization climbs fastest as developer-centric tooling gains procurement influence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt's financial district concentration drives European procurement intensity for sub-millisecond latency monitoring. Singapore's data center tax incentives pull cloud-native deployment investment. Bangalore's software corridor anchors Asia-Pacific managed service provider expansion.
United States
Healthcare systems under HIPAA Security Rule mandates invest heavily in access-log monitoring for pharmaceutical database validation. FDA 21 CFR Part 11 requirements extend sales cycles for documented installation qualification protocols. Boston's biotech cluster demands predictive failure detection for distributed clinical trial data architectures.
Germany
Automotive industrial software clusters require sub-millisecond latency monitoring for connected manufacturing environments. EU AI Act algorithmic transparency obligations and NIS2 Directive compliance deadlines accelerate certified stack procurement. Baden-Württemberg's production facilities balance edge processing with centralized compliance storage through hybrid architectures.
Singapore
Payment processing visibility requirements from financial services firms deploy eBPF-based agents at scale for kernel-level telemetry extraction. Monetary Authority of Singapore operational resilience guidelines mandate real-time observability for critical banking infrastructure. The city-state's data center zone incentives concentrate multi-cloud orchestration investment.
India
Managed service providers bundle monitoring into broader infrastructure offerings for cost-conscious SMBs expanding fastest through channel partners. RBI's operational guidelines for payment systems drive database reliability engineering investment. Karnataka's software corridor anchors cloud-native tooling adoption for containerized microservices deployments.
United Kingdom
Financial services firms in the City of London expand real-time database monitoring to manage transactional integrity across distributed systems. FCA operational resilience requirements compress monitoring refresh cycles from minutes to sub-second intervals. The capital's fintech cluster favors agentless collection architectures for ephemeral environment compatibility.
Database Monitoring Software Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered pricing structures. Cloud-native specialists capture expanding margin pools through AI-driven predictive capabilities while legacy on-premise vendors defend mid-market penetration through deployment flexibility. Three archetypes dominate: hyperscaler-aligned platforms, AI-causal-analysis specialists, and infrastructure-flexibility providers. Consolidation pressure intensifies through strategic partnerships and geographic expansion moves.
Within the cloud-native platform tier, Datadog, Inc. and Dynatrace LLC exemplify architecture-agnostic positioning across multi-cloud environments. SolarWinds Worldwide, LLC occupies a distinct position emphasizing on-premise deployment autonomy for regulated verticals. These three anchors represent divergent bets on infrastructure abstraction versus operational control.
| Leading Market Players |
|---|
| Datadog, Inc. |
| Dynatrace LLC |
| SolarWinds Worldwide, LLC |
| Quest Software Inc. |
| Oracle Corporation |
| Paessler AG |
| Nagios Enterprises, LLC |
| eG Innovations |
| Heroix Corporation |
| Others |
Supply Flow & Price Mechanics
Cloud compute and egress fees from hyperscalers flow downstream through SaaS subscription tiers, compressing independent software vendor margins while concentrating pricing power with infrastructure-as-a-service providers serving enterprise buyers in Frankfurt and Singapore.
Pricing Analysis
Margin tightening in mid-market SaaS tiers reflects hyperscaler cost pass-through obligations and buyer procurement consolidation. Three-tier pricing structure across premium AI-driven, standard performance-monitoring, and economy open-source support levels dominates contract structures. Certification investment for FDA 21 CFR Part 11 validation and EU AI Act compliance commands substantial premiums over uncertified alternatives. SMB buyers through managed service provider channels exhibit highest price sensitivity, while pharmaceutical manufacturers under regulatory mandate show lowest elasticity.
Supply Chain Analysis
Engineer scarcity in Bangalore and Berlin constrains deployment velocity for cloud-native instrumentation architectures. Software development concentrates in India, Germany, and the United States, with kernel-level telemetry expertise clustering around Frankfurt's financial district and Singapore's data center zones. Critical dependencies include eBPF compiler frameworks, machine learning training infrastructure, and hyperscaler API ecosystems. Single-source vulnerability around AWS, Azure, and GCP egress pricing creates margin instability. Distribution runs through direct enterprise sales, managed service provider channels, and open-source community repositories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The database monitoring software market functions as a cost-of-compliance arena where EU AI Act algorithmic transparency mandates erect certification barriers that favor established vendors with documented validation protocols.
For Market Incumbents: Deploy AI-causal-analysis capability extensions to defend against hyperscaler-native monitoring tools encroaching on enterprise accounts. Deepen vertical integration into eBPF kernel instrumentation to reduce dependency on third-party collection agents. Capture NIS2 Directive procurement windows through pre-certified compliance stacks for European critical infrastructure operators. For New Entrants and Emerging Players: Edge database deployments in retail and logistics IoT endpoints represent underserved infrastructure lacking mature monitoring solutions. Target SQLite and time-series engine environments through lightweight agentless architectures. Pursue channel partnerships with industrial automation vendors to bypass direct competition with incumbent SaaS platforms. For Investors and Strategic Acquirers: Consolidation of open-source telemetry tooling into commercial platforms is the leading indicator that margin compression in pure-play monitoring will accelerate. Five-to-ten-year viability hinges on AI-driven predictive differentiation rather than reactive performance metrics. Monitor OpenTelemetry standardization adoption rates as the signal for multi-tool data portability enabling mid-market consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Causal Analysis Acquisition | Machine learning root-cause capabilities differentiate premium tiers from commodity monitoring in Frankfurt banking infrastructure. |
| eBPF Kernel Instrumentation Development | Zero-overhead telemetry extraction reduces deployment friction for containerized microservices in Singapore payment processing. |
| NIS2 Compliance Certification Investment | European critical infrastructure procurement deadlines create concentrated demand for validated monitoring stacks. |
| Edge Database Monitoring Product Launch | SQLite and time-series engine visibility addresses greenfield attach opportunities in German automotive IoT pipelines. |
| Managed Service Provider Channel Expansion | SMB adoption acceleration depends on bundling into broader infrastructure offerings through Bangalore software corridors. |
Methodological Framework
Document review covered SEC filings from publicly traded software vendors, EU regulatory impact assessments for AI Act and NIS2 implementation, and hyperscaler capex disclosures, complemented by interviews with database reliability engineering directors, IT procurement officers at financial services firms, channel partners in managed service provider networks, and integration specialists deploying observability pipelines. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, ECHA chemical data management protocols, and Monetary Authority of Singapore operational resilience guidelines. Bottom-up contract value analysis and top-down market sizing triangulated segment-level estimates.
Cross-referencing historical deployment patterns against panel input from infrastructure teams shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, organization size tier, vertical industry, integration complexity, and regional regulatory cluster. CAGRs derived from elasticity-adjusted adoption curves and compliance-driven procurement cycle analysis. Forecast inputs incorporated eBPF instrumentation penetration rates and EU AI Act implementation timeline assumptions.
Revisions become necessary when hyperscaler pricing restructuring, regulatory deadline postponements, or open-source standardization acceleration materialize beyond baseline assumptions. Forecasts reflect documented scenario parameters without claiming predictive certainty. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
ID Photo Software Market
Software & Services
Global Membership Management Software Market
Software & Services
Model Based Testing Tools Market
Software & Services
PCB Layout Software Market
Software & Services
Business Email Market
Software & Services
Software Publishers Market
Software & Services
Global Recreation Management Software Market
Software & Services
AI Powered Software Testing Tool Market
Software & Services
Global Apparel Management Software Market
Software & Services
Global Software Asset Management Market
Software & Services
Global Feed Software Market
Software & Services
Global Intranet Software Market
Software & Services
Global Quoting Software Market
Software & Services
Global Configuration Management Software Market
Software & Services
Information Technology Service Management (ITSM) Market
Software & Services
Global Disk Imaging Software Market