
 Asia-Pacific Communication Platform-As-A-Service Market | 2026-2036
Asia-Pacific Communication Platform-As-A-Service Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Communication Platform-As-A-Service Market Outlook
Enterprise buyer fragmentation across mid-market digital-native companies is realigning procurement patterns across the Asia-Pacific CPaaS landscape. Twilio Inc. leverages extensive API documentation and developer ecosystem investments to sustain engagement across fintech and e-commerce verticals. Infobip Ltd anchors regional delivery through localized data centers and direct carrier relationships in Indonesia and the Philippines. Tanla Platforms Limited dominates India-specific voice and messaging infrastructure with deep regulatory familiarity and telecom operator integration.
Asia-Pacific Communication Platform-As-A-Service denotes cloud-delivered software layers enabling programmable voice, messaging, video, and authentication workflows through REST APIs and SDKs, typically operating over SIP trunking and WebRTC protocols with sub-200ms latency targets for real-time interaction. The architecture serves enterprises seeking to embed communication capabilities into customer-facing applications without maintaining proprietary telecom infrastructure. Voice Platforms and Messaging Services command the majority of current revenue pools, though Video Conferencing exhibits the steepest trajectory as hybrid work norms persist across technology and professional services sectors. Public Cloud deployment retains volume leadership, yet Hybrid Cloud configurations are gaining structural importance among banking and healthcare end users managing multi-jurisdiction data sovereignty requirements.
TRAI in India enforces cloud telephony registration and data localization mandates that shape platform architecture decisions for vendors serving domestic enterprises. Australia's TGA and privacy frameworks influence healthcare segment procurement, while China's MIIT and cybersecurity regulations constrain foreign platform participation and redirect demand toward domestic alternatives. Stakeholders must monitor evolving cross-border data flow restrictions and carrier partnership licensing requirements as these determine operational scalability and competitive access across national markets.
Market Dynamics
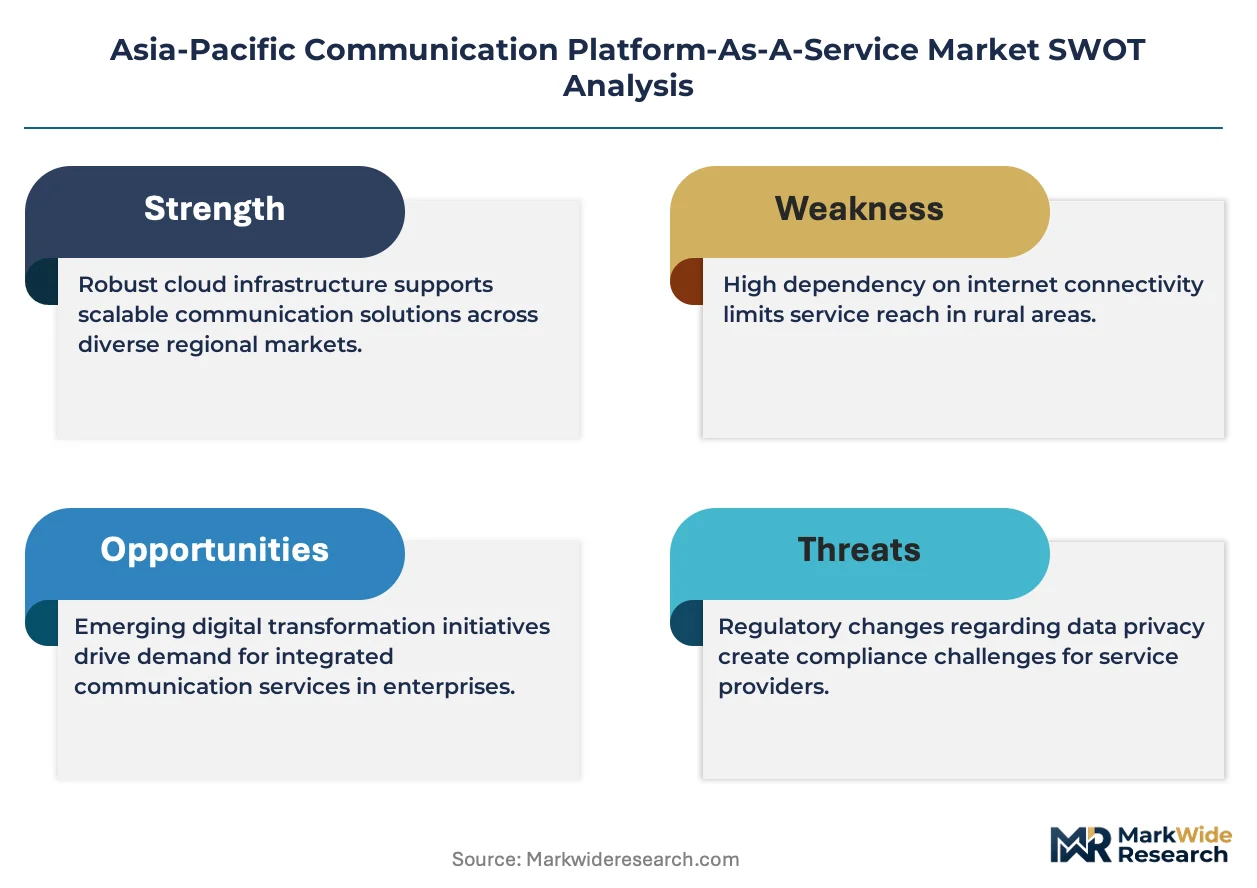
TRAI data localization mandates and cloud telephony registration requirements are forcing platform vendors to re-architect infrastructure for India-bound workloads, compressing deployment timelines and elevating compliance costs for regional expansion.
Growth Catalysts
- Digital Payment Ecosystems:Dense transaction volumes across India and Southeast Asia generate sustained demand for embedded authentication and fraud-alert messaging workflows.
- TRAI Cloud Telephony Mandates:Compliance-driven upgrades accelerate replacement of legacy on-premise systems with registered CPaaS platforms among Indian enterprises.
- Hybrid Work Normalization:Technology and professional services sectors in Australia and Singapore sustain elevated video conferencing consumption for distributed workforce coordination.
Market Restraints
- Carrier Partnership Licensing:Exclusive agreements between domestic telecom operators and select platform vendors in Indonesia and the Philippines restrict competitive access to numbering resources.
- Cross-Border Data Friction:Divergent data sovereignty requirements across India, China, and Australia fragment cloud architecture and inflate operational complexity.
- WebRTC Latency Constraints:Sub-200ms real-time interaction targets strain last-mile connectivity in tier-2 and tier-3 Indian cities, degrading user experience.
Strategic Opportunities
- Vietnam and Bangladesh:Underpenetrated banking and e-commerce verticals present first-mover expansion potential for voice and messaging infrastructure.
- AI-Native Conversation Orchestration:Convergence of large language models with programmable voice APIs enables automated customer service workflows for mid-market enterprises.
- Healthcare Communication Modernization:Australia's TGA privacy frameworks and telehealth reimbursement policies create procurement tailwinds for HIPAA-equivalent platforms.
Industry Challenges
- Legacy PBX Integration Complexity:Enterprises in Japan and South Korea face prolonged migration timelines due to entrenched on-premise telephony investments and custom configurations.
- Certification Timeline Compression:Multi-jurisdiction data residency audits for banking and healthcare segments extend sales cycles and strain pre-sales engineering capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Communication Platform-As-A-Service Market |
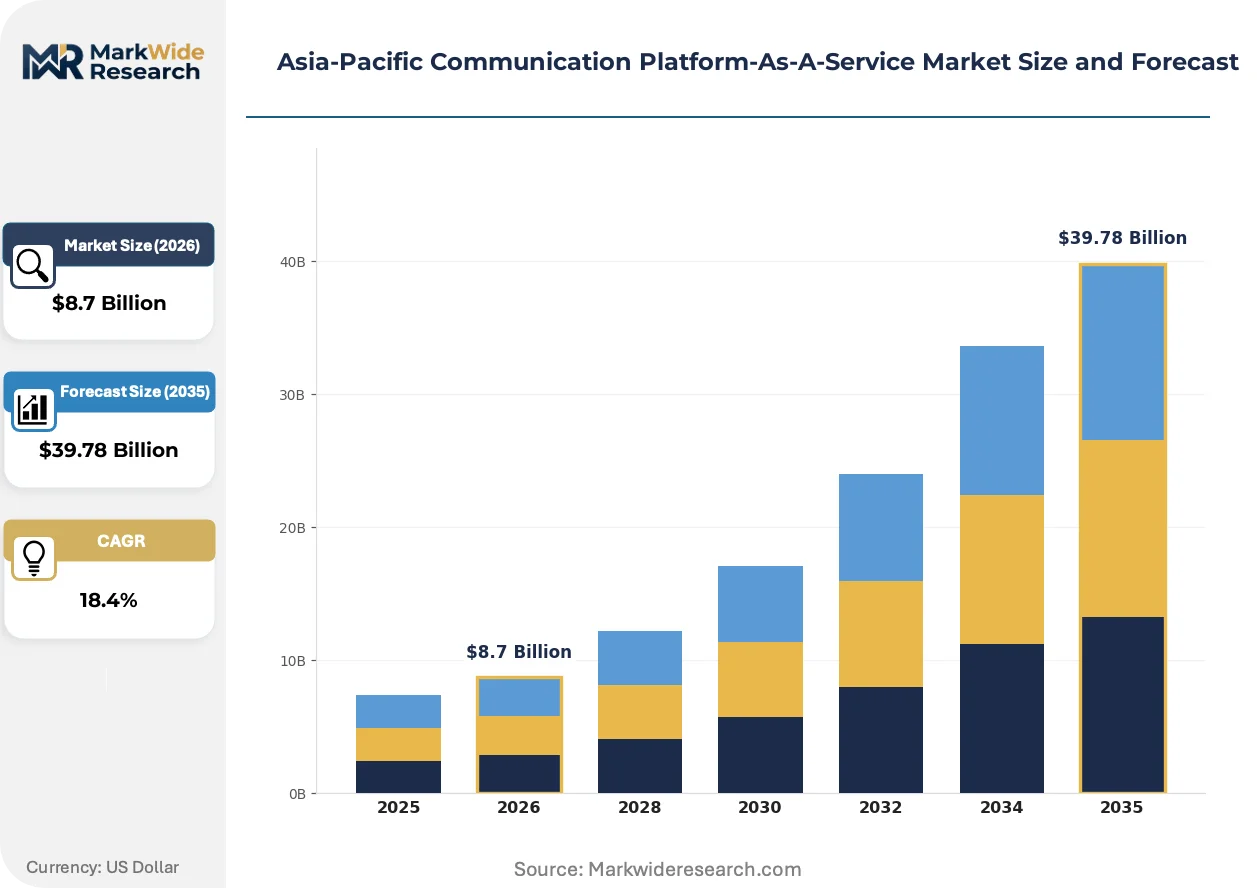
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Voice Platforms, Messaging Services, Video Conferencing, Unified Communication Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: SMEs, Large Enterprises, Healthcare, Education Service Type: Managed Services, Professional Services, Support Services, Consulting |
| Companies Covered | Twilio Inc., Vonage Holdings Corp, Tanla Platforms Limited, Route Mobile, VCloudX PTE Limited, Exotel, Plivo Inc., MessageBird, Infobip Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Communication Platform-As-A-Service Market Strategic Shifts
Programmable communication stacks are absorbing adjacent capabilities—AI orchestration, identity verification, and edge delivery—to transform from utility infrastructure into strategic customer engagement layers.
WebRTC is integrating serverless edge compute for media processing, collapsing latency for real-time video applications. Banking and telehealth providers in Singapore and Australia are piloting these architectures for high-stakes customer interactions. The technology is integrating fraud detection and biometric authentication directly into session negotiation, compressing the vendor stack for security-conscious buyers.
India's TRAI cloud telephony registration framework now requires real-time KYC verification for every virtual number provisioned. This industrializes compliance overhead into platform operations, favoring vendors with pre-integrated identity verification pipelines. Domestic Indian enterprises and multinational subsidiaries are restructuring procurement to prioritize registered platform providers, displacing unregistered offshore alternatives.
Mid-market digital-native companies across Southeast Asia are consolidating vendor relationships from point solutions toward unified communication platforms. E-commerce and fintech buyers in Indonesia and Vietnam now prioritize API breadth and regional data center presence over price-per-message. This concentration is visible most acutely in Jakarta and Ho Chi Minh City, where procurement teams are shortening evaluation cycles for full-stack providers.
Asia-Pacific Communication Platform-As-A-Service Market Segmentation
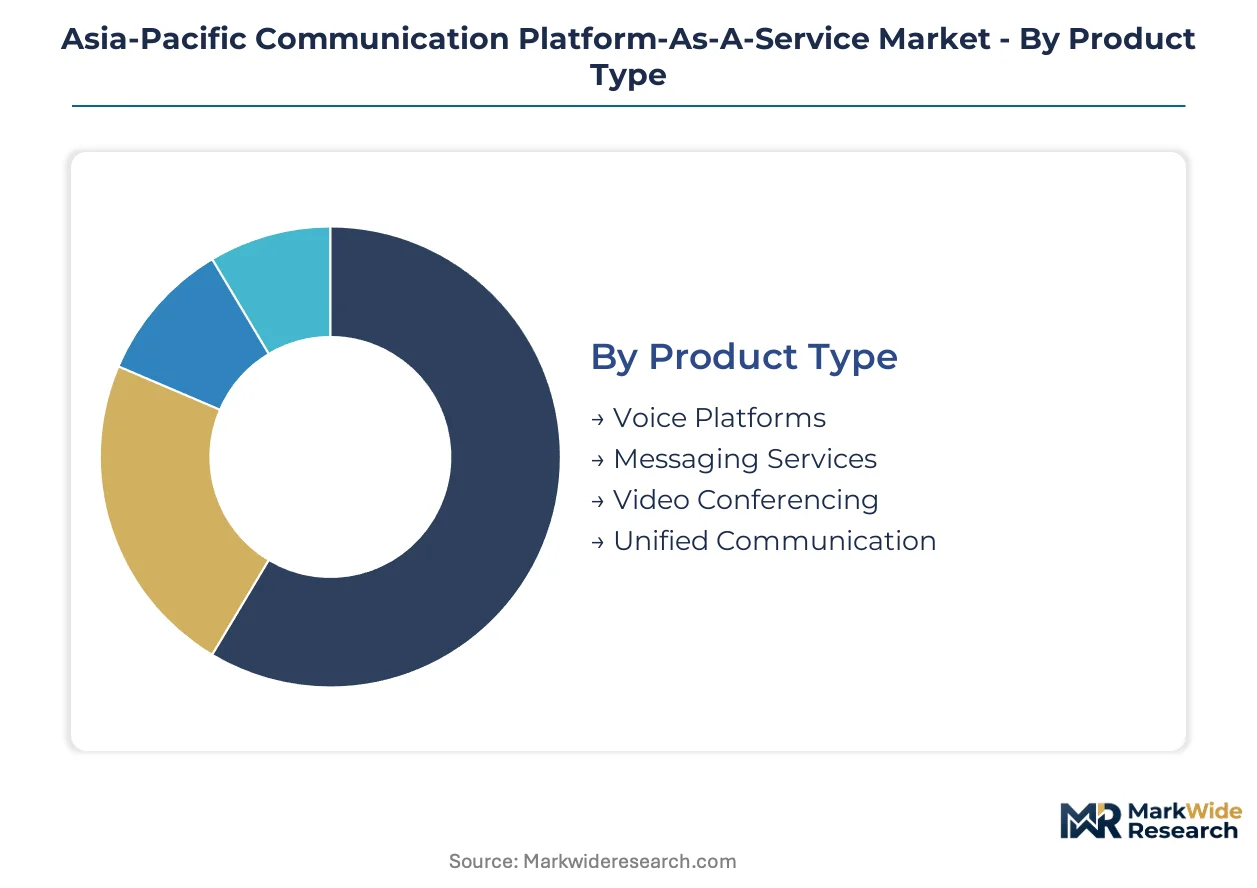
CPaaS architectures fragment across integration depths—from standalone voice stacks to embedded messaging layers woven directly into customer-facing applications. Procurement patterns diverge sharply based on whether enterprises seek utility infrastructure or strategic engagement orchestration.
Product Type:
Standalone voice and messaging platforms dominate transactional use cases, while embedded video and unified stacks serve deeper workflow integration across distributed workforces.
- Voice Platforms:SIP trunking and programmable voice APIs enable interactive voice response, click-to-call, and outbound notification workflows. Financial services firms in India and Singapore deploy these for payment authentication and fraud-alert systems, with TRAI registration mandates accelerating compliance-driven upgrades.
- Messaging Services:SMS, WhatsApp Business API, and RCS channels support one-time passwords, delivery tracking, and promotional campaigns. E-commerce platforms in Indonesia and Vietnam concentrate demand here, prioritizing regional data center presence over per-message cost.
- Video Conferencing:WebRTC-based real-time video with sub-200ms latency targets serves telehealth and hybrid work coordination.
- Unified Communication:Converged voice, messaging, and video stacks with single-pane administration reduce vendor fragmentation.
Voice Platforms lead volumes today; Video Conferencing is gaining share fastest.
Deployment:
Cost tiers separate volume buyers from compliance-sensitive segments, with hybrid configurations commanding premium positioning for multi-jurisdiction data sovereignty.
- Public Cloud:Multi-tenant infrastructure with pay-as-you-consume pricing enables rapid scaling for mid-market digital-native companies. Startups across Ho Chi Minh City and Jakarta favor this tier for speed-to-market without capital expenditure.
- Hybrid Cloud:Split architectures keep sensitive workloads on-premises while bursting transactional traffic to public infrastructure. Australian banks and Indian healthcare providers select this tier to satisfy TGA and TRAI data residency requirements without sacrificing elasticity.
- Private Cloud:Single-tenant dedicated environments with custom security policies serve defense and government contractors.
- On-Premises:Self-managed infrastructure with full operational control persists in Japan and South Korea due to entrenched legacy PBX investments.
Public Cloud retains the largest installed base; Hybrid Cloud configurations are climbing the fastest as banking and healthcare procurement tightens.
End User:
Customer maturity shapes adoption velocity, with digital-native SMEs outpacing regulated large enterprises on deployment speed despite smaller contract values.
- SMEs:Mid-market digital-native companies across Southeast Asia consolidate from point solutions toward full-stack platforms. Indonesian fintechs and Vietnamese e-commerce operators prioritize API breadth and localized support over enterprise-grade SLAs.
- Large Enterprises:Multi-divisional organizations with legacy telephony investments face prolonged migration timelines. Japanese and South Korean conglomerates exemplify this constraint, where custom PBX configurations and union negotiations extend procurement cycles.
- Healthcare:Telehealth providers and hospital networks require HIPAA-equivalent platforms with audit trails and patient consent management.
- Education:Universities and vocational institutes deploy virtual classrooms and administrative notification systems.
SMEs drive transaction volumes today; Healthcare represents the steepest expansion trajectory as Australia's TGA frameworks and telehealth reimbursement policies mature.
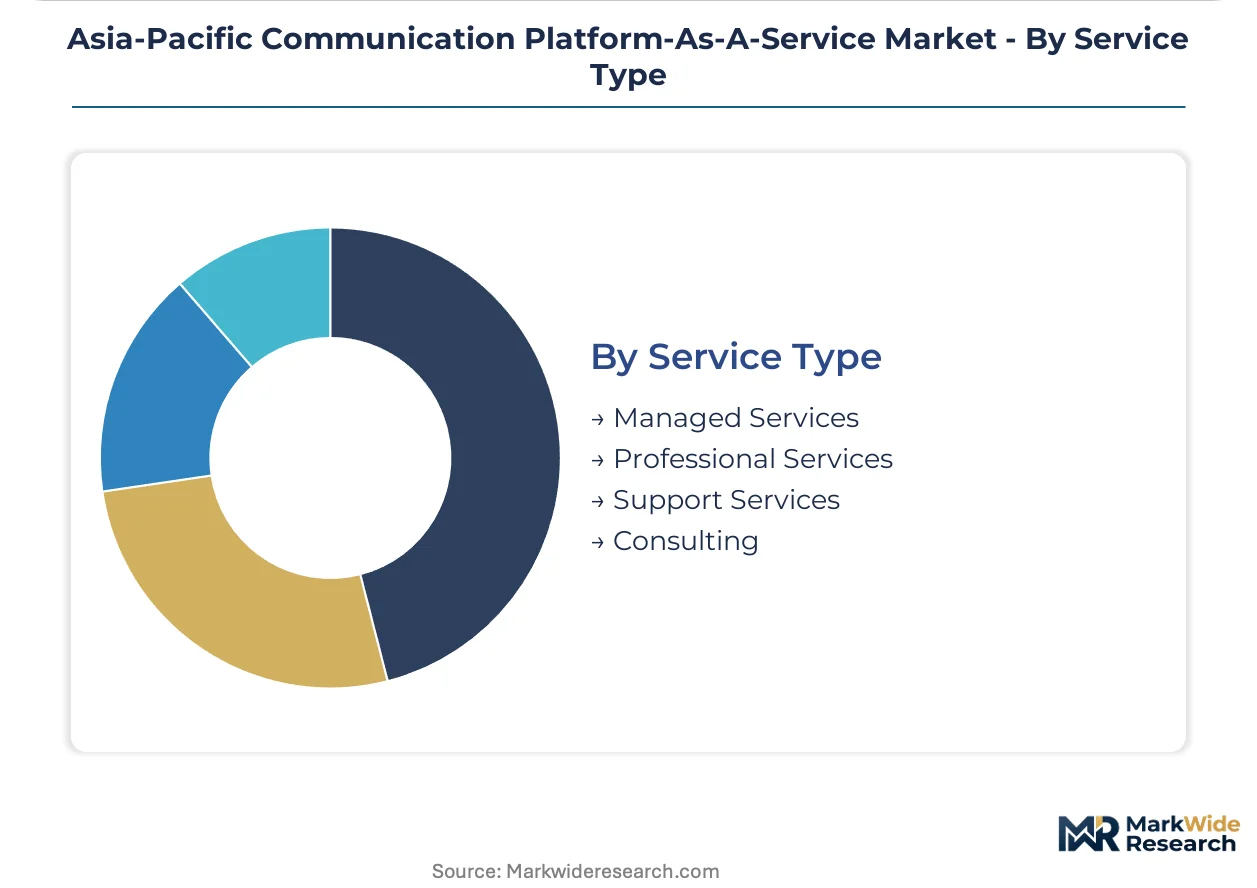
Service Type:
Margin structures favor recurring managed services over project-based professional engagements, though consulting retains pricing power for complex multi-cloud integrations.
- Managed Services:Ongoing platform operation, monitoring, and optimization delivered under multi-year contracts. Indian enterprises favor this model to satisfy TRAI cloud telephony registration without building internal telecom expertise.
- Professional Services:Custom implementation, system integration, and workflow design for specific enterprise requirements. Singaporean banks and Australian healthcare networks procure these for high-stakes customer interaction architectures.
- Support Services:Technical assistance, troubleshooting, and incident response with defined response-time commitments.
- Consulting:Strategic advisory on vendor selection, compliance roadmap development, and architecture planning.
Managed Services dominates recurring revenue pools; Professional Services commands the highest per-engagement margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Developer talent pools in Bangalore, Singapore, and Shenzhen anchor platform engineering capacity across the region. Cloud infrastructure specialists concentrate in these metros, driving API innovation and localization engineering for domestic compliance.
India
Digital payment volumes and government digitalization programs generate dense CPaaS deployment clusters. TRAI cloud telephony registration and data localization mandates force infrastructure re-architecture for domestic workloads. Mumbai and Bangalore host the highest concentration of voice and messaging infrastructure integration with telecom operators.
Singapore
Regional headquarters for multinational technology firms sustain demand for unified communication stacks. Monetary Authority of Singapore digital banking frameworks accelerate procurement of compliant messaging workflows. The city-state's data center ecosystem serves as the primary Southeast Asia hub for latency-sensitive video conferencing.
Indonesia
E-commerce transaction growth and fintech expansion drive embedded authentication messaging demand. Exclusive carrier partnership licensing restricts numbering resource access for non-incumbent platform vendors. Jakarta procurement teams consolidate vendor relationships toward full-stack providers with local data center presence.
Australia
Telehealth reimbursement policies and TGA privacy frameworks create procurement tailwinds for HIPAA-equivalent platforms. Hybrid work normalization sustains elevated video conferencing consumption across technology and professional services sectors. Sydney and Melbourne banking networks pilot serverless edge compute for high-stakes customer interactions.
Japan
Entrenched on-premise PBX investments and custom configurations prolong migration timelines for large enterprises. METI industrial digitalization incentives nudge conglomerates toward API-first communication architectures. Tokyo enterprise procurement cycles extend due to union negotiations and legacy system integration complexity.
Asia-Pacific Communication Platform-As-A-Service Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the Asia-Pacific CPaaS landscape. The vendor base stratifies into three tiers: global API-first platforms with extensive developer ecosystems, regional specialists leveraging localized carrier relationships, and domestic infrastructure providers with deep regulatory familiarity. Strategic moves concentrate on geographic expansion through data center localization and portfolio diversification into AI-native conversation orchestration.
Within the global API-first tier, Twilio Inc. and Plivo Inc. represent the archetype of developer-centric platform engineering with extensive documentation investments. Regional delivery specialists include Infobip Ltd and Tanla Platforms Limited, exemplifying vendors that anchor market position through direct carrier integration and compliance familiarity. Vonage Holdings Corp occupies a position bridging enterprise voice heritage with programmable API modernization.
| Leading Market Players |
|---|
| Twilio Inc. |
| Vonage Holdings Corp |
| Tanla Platforms Limited |
| Route Mobile |
| VCloudX PTE Limited |
| Exotel |
| Plivo Inc. |
| MessageBird |
| Infobip Ltd |
| Others |
Value Chain & Pricing Dynamics
TRAI cloud telephony registration mandates gate qualified supply access and premium-tier pricing power for vendors serving Indian enterprises, compressing deployment timelines for compliant platforms while elevating cost structures for unregistered alternatives. Data localization requirements across India, Australia, and Indonesia fragment cloud architecture and inflate operational complexity, forcing buyers to absorb compliance premiums or migrate to domestic infrastructure providers.
Pricing Analysis
The bundled-vs-unbundled service split defines competitive positioning across the Asia-Pacific CPaaS landscape, with full-stack unified communication platforms commanding 30-40% premiums over point-solution voice or messaging APIs. Price differentiation rests on data residency certification tier and regional data center presence, particularly for banking and healthcare segments navigating multi-jurisdiction sovereignty requirements. Cost compression in transactional messaging tiers is intensifying because Indonesian and Vietnamese e-commerce operators are consolidating vendor relationships toward API breadth over per-message economics. Mid-market digital-native companies in Ho Chi Minh City and Jakarta exhibit highest price sensitivity, while Australian banks and Singaporean fintechs prioritize compliance assurance and latency performance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with domestic telecom operators in Indonesia and the Philippines, where exclusive carrier partnership licensing restricts numbering resource access for non-incumbent platform vendors. Infrastructure supply concentrates in India, Singapore, and Australia, with cloud compute and edge delivery capacity anchored in Mumbai, Bangalore, and Sydney data center clusters. Raw material dependencies span SIP trunking capacity, WebRTC media processing licenses, and carrier-grade authentication hardware. Regulatory restriction risk escalates as cross-border data flow constraints multiply across the region. Distribution runs through direct enterprise sales teams for large banking and healthcare accounts, supplemented by self-serve developer portals and channel partners for mid-market digital-native adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in hybrid cloud configurations and AI-native conversation orchestration, where automation layers absorb adjacent capabilities and transform utility infrastructure into strategic customer engagement platforms with recurring revenue durability.
For Market Incumbents: Lock in carrier exclusivity extensions across Indonesia and the Philippines before regulatory frameworks open numbering resource access to foreign platform vendors. Deepen API documentation investments and developer ecosystem tooling to defend against emerging AI-native entrants targeting automated customer service workflows. Prioritize TRAI registration maintenance and real-time KYC pipeline integration as compliance capabilities become primary procurement filters for Indian enterprises. For New Entrants and Emerging Players: Serverless edge compute for media processing offers a technology-first wedge into Australian banking and telehealth segments piloting sub-100ms latency architectures for high-stakes customer interactions. Vietnam and Bangladesh present the most penetrable geography for voice and messaging infrastructure, with underpenetrated banking verticals and minimal incumbent carrier exclusivity. A channel partnership strategy with regional system integrators accelerates enterprise access without prolonged direct sales cycle investment. For Investors and Strategic Acquirers: Roll-up economics work for regional specialists with localized carrier relationships because data localization mandates are fragmenting cloud architecture and elevating compliance-driven switching costs for domestic infrastructure providers. The 5-10 year viability window favors vendors with pre-integrated identity verification pipelines and direct telecom operator integration. Acquisition target archetype: mid-scale CPaaS platforms with TRAI registration and established Indonesian or Philippine carrier partnerships. Watch for inflection when TRAI expands cloud telephony registration requirements to messaging infrastructure, triggering replacement demand for unregistered offshore alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Native Conversation Orchestration | Convergence of large language models with programmable voice APIs enables automated customer service workflows for mid-market enterprises. |
| Regional Data Center Localization | Compliance with TRAI data localization mandates and Australia's TGA privacy frameworks requires domestic infrastructure deployment. |
| Carrier Partnership Deepening | Exclusive agreements with Indonesian and Philippine telecom operators secure numbering resource access and competitive moats. |
| Hybrid Cloud Configuration Expansion | Split architectures satisfy multi-jurisdiction data sovereignty requirements for banking and healthcare procurement. |
| Serverless Edge Compute Integration | WebRTC media processing at the edge collapses latency for real-time video applications in Singapore and Australian banking networks. |
Study Parameters
Direct dialogue with platform engineering leads, enterprise IT procurement officers, telecom regulatory affairs specialists, and channel partner managers grounded qualitative assessment in operational reality across India, Singapore, Indonesia, and Australia. Secondary validation drew from TRAI regulatory filings, Monetary Authority of Singapore digital banking frameworks, Australian TGA privacy guidance, hyperscaler capex disclosures, and enterprise communication platform procurement databases. Bottom-up and top-down triangulation reconciled vendor-reported deployment metrics with end-user adoption patterns.
Bottom-up modeling anchored volume projections in segment-specific adoption curves across deployment models, organization sizes, and vertical compliance requirements, while top-down cross-checks validated aggregate market scale against regional cloud infrastructure investment flows. Segmentation dimensions spanned product type, deployment configuration, end-user category, and service model, with additional granularity on regulatory jurisdiction clusters. CAGRs were derived from fitted growth curves calibrated to historical penetration rates and policy-driven demand inflection points, incorporating WebRTC latency benchmarks and carrier partnership licensing timelines as industry-specific forecast inputs.
The model holds under stable regulatory enforcement intensity and sustained hybrid work normalization; deviation in cross-border data flow restrictions or carrier partnership licensing liberalization would shift competitive access and growth trajectory materially. Forecasts reflect documented assumptions about compliance timeline compression and enterprise migration velocity from legacy PBX systems. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Customer Advocacy Software Market
Software & Services
Global Product Management and Road Mapping Tool Market
Software & Services
Global Digital Experience Management Software Market
Software & Services
Global Lead Capture Software Market
Software & Services
RFP Software Market
Software & Services
Bankruptcy Software Market
Software & Services
Global Neural Network Software Market
Software & Services
Africa HR Payroll Software Market
Software & Services
Image Analysis Software Market
Software & Services
Global Remote Desktop Management Market
Software & Services
Global Roofing Software Market
Software & Services
Vlog Editing Software Market
Software & Services
Service Dispatch Software Market
Software & Services
Embedded Hypervisor Market
Software & Services
Digital Customer Onboarding Software Market
Software & Services
SRM Software Market