
 Infrastructure As Code (Iac) Market | 2026-2036
Infrastructure As Code (Iac) Market Size, Share, and Industry Trends Forecast 2026-2036
Infrastructure As Code (Iac) Market Intelligence
The EU Cybersecurity Act is consolidating enterprise preference for policy-as-code frameworks that embed compliance into automated pipelines. Amazon Web Services anchors the public cloud segment through CloudFormation's native integration with its service ecosystem. Microsoft competes by extending Azure Resource Manager across hybrid environments, while HashiCorp sustains its cross-cloud position through Terraform's provider-agnostic architecture.
Infrastructure as Code denotes the practice of managing and provisioning computing infrastructure through machine-readable definition files rather than manual configuration or interactive tools. These definitions typically use declarative languages such as YAML, JSON, or domain-specific syntax to specify desired state, enabling version control, automated testing, and repeatable deployments across development, staging, and production environments. The deployment model dimension shows hybrid cloud configurations capturing expanding margin pools as enterprises retain sensitive workloads on-premises while bursting to public resources. Within solution offerings, policy compliance modules are growing fastest as regulated industries demand automated guardrails that prevent configuration drift before resources reach production.
FCC guidelines on communications infrastructure resilience, combined with NIST SP 800-53 security controls and the EU Cybersecurity Act's certification schemes, are mandating auditable, automated infrastructure management across telecommunications and government sectors. ISO 27001 and SOC 2 frameworks further reinforce documentation requirements that IaC satisfies through immutable audit trails. Stakeholders must evaluate whether their current toolchain can enforce compliance policies across multi-cloud estates without creating vendor-specific skill silos that constrain future architecture decisions.
Market Dynamics
Federal cloud migration mandates and hyperscale data center buildouts are compressing deployment timelines, forcing enterprises to automate infrastructure provisioning through declarative configuration frameworks rather than manual processes.
Growth Catalysts
- NIST SP 800-53 security controls:US government agencies must maintain auditable infrastructure configurations, driving standardized IaC adoption across federal contractors and their supply chains.
- Financial services automation:Banks and insurers deploy policy-as-code modules to embed compliance checks directly into CI/CD pipelines, eliminating provisioning errors before production deployment.
- EU Cybersecurity Act certification schemes:European telecommunications providers must demonstrate automated, auditable infrastructure management to maintain operating licenses.
Market Restraints
- Specialized talent scarcity:Shortage of practitioners fluent in HCL, YAML, and domain-specific configuration languages limits enterprise rollout velocity.
- Legacy system integration friction:Mainframe and on-premises bare-metal environments resist API-driven provisioning, requiring costly middleware layers.
- Multi-cloud complexity tax:Managing state files and provider dependencies across AWS, Azure, and GCP estates demands redundant tooling investments.
Strategic Opportunities
- Edge infrastructure automation:5G network rollouts and IoT deployments require lightweight, declarative provisioning tools for distributed compute nodes.
- Regulatory tailwinds from CSRD:EU Corporate Sustainability Reporting Directive mandates auditable infrastructure carbon footprints, favoring IaC's immutable audit trails.
- AI-assisted configuration generation:Large language models trained on infrastructure patterns accelerate template authoring for underpenetrated mid-market enterprises.
Industry Challenges
- State management at scale:Terraform and CloudFormation state files become corruption risks when hundreds of engineers execute concurrent modifications.
- Drift detection latency:Production environments accumulate unauthorized manual changes that automated reconciliation jobs struggle to flag before security incidents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infrastructure As Code (Iac) Market |
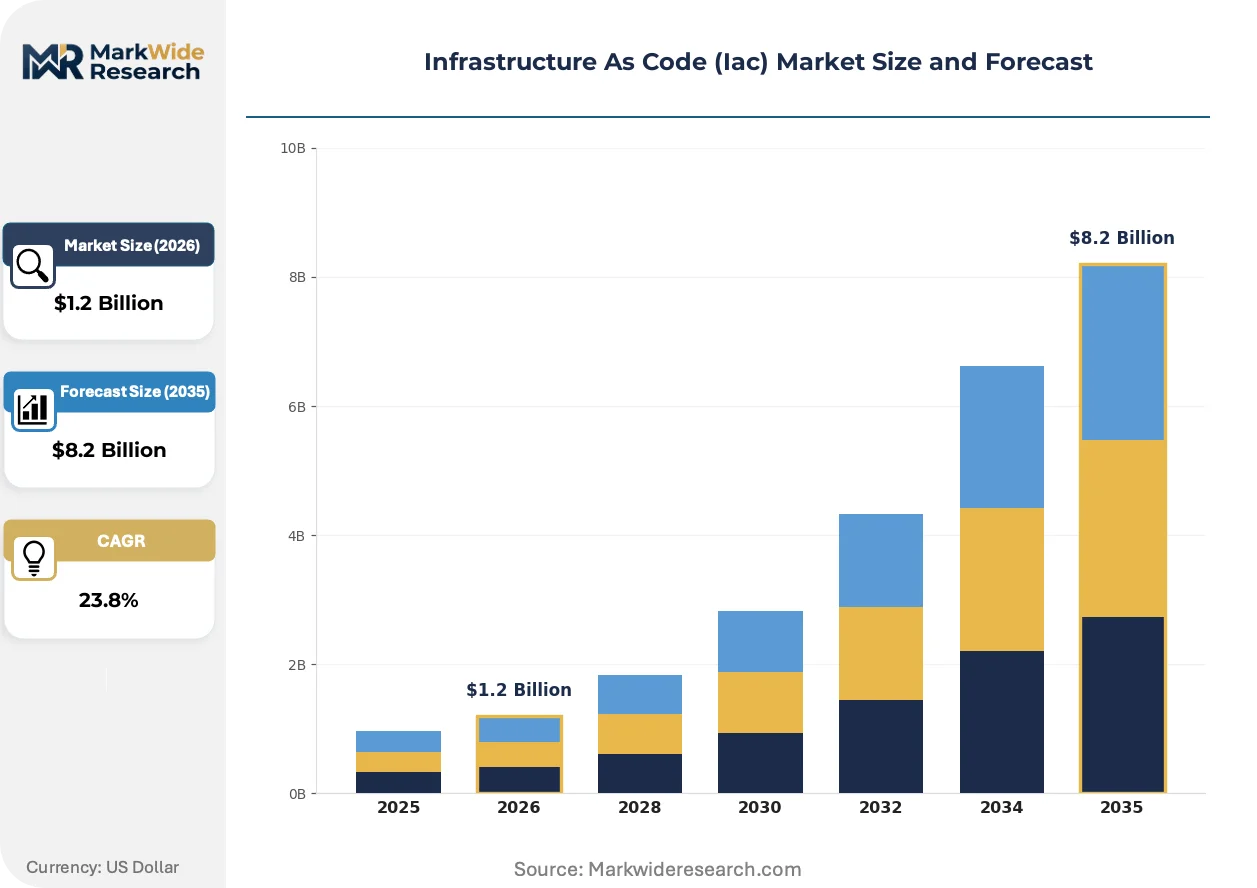
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $8.2 Billion |
| CAGR (2026 – 2036) | 23.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Solution Offering: Configuration Management, Provisioning Automation, Orchestration, Policy Compliance, Monitoring Use Case: Continuous Integration, Continuous Delivery, Disaster Recovery, Environment Provisioning, Security Automation End User Industry: Telecommunications, Financial Services, Education, Manufacturing, Government |
| Companies Covered | HashiCorp, Amazon Web Services, Microsoft, Google, IBM, Oracle, Pulumi, Red Hat, Hewlett Packard Enterprise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infrastructure As Code (Iac) Market Strategic Shifts & Innovations
Configuration management is fragmenting from monolithic platforms into composable, API-first modules that embed compliance and security guardrails directly at the provisioning layer.
Kubernetes Operators and custom resource definitions are modularizing infrastructure abstraction, allowing platform teams to package complex multi-service deployments into version-controlled, reusable components. Financial services and healthcare enterprises adopt these patterns fastest, compressing weeks of manual provisioning into minutes of automated orchestration.
The EU Cybersecurity Act's certification schemes are mandating automated compliance validation before infrastructure reaches production, forcing vendors to integrate policy engines directly into their core platforms. Telecommunications providers face the steepest compliance burdens, responding by hiring dedicated platform engineering teams to maintain certification-ready pipeline templates.
Enterprise buyers now demand consumption-based pricing for infrastructure tooling, displacing perpetual licenses with seat-agnostic models tied to managed resource counts. Channel partners and systems integrators in North America and Western Europe are restructuring compensation around outcome-based delivery metrics rather than upfront software sales.
Infrastructure As Code (Iac) Market Segmentation
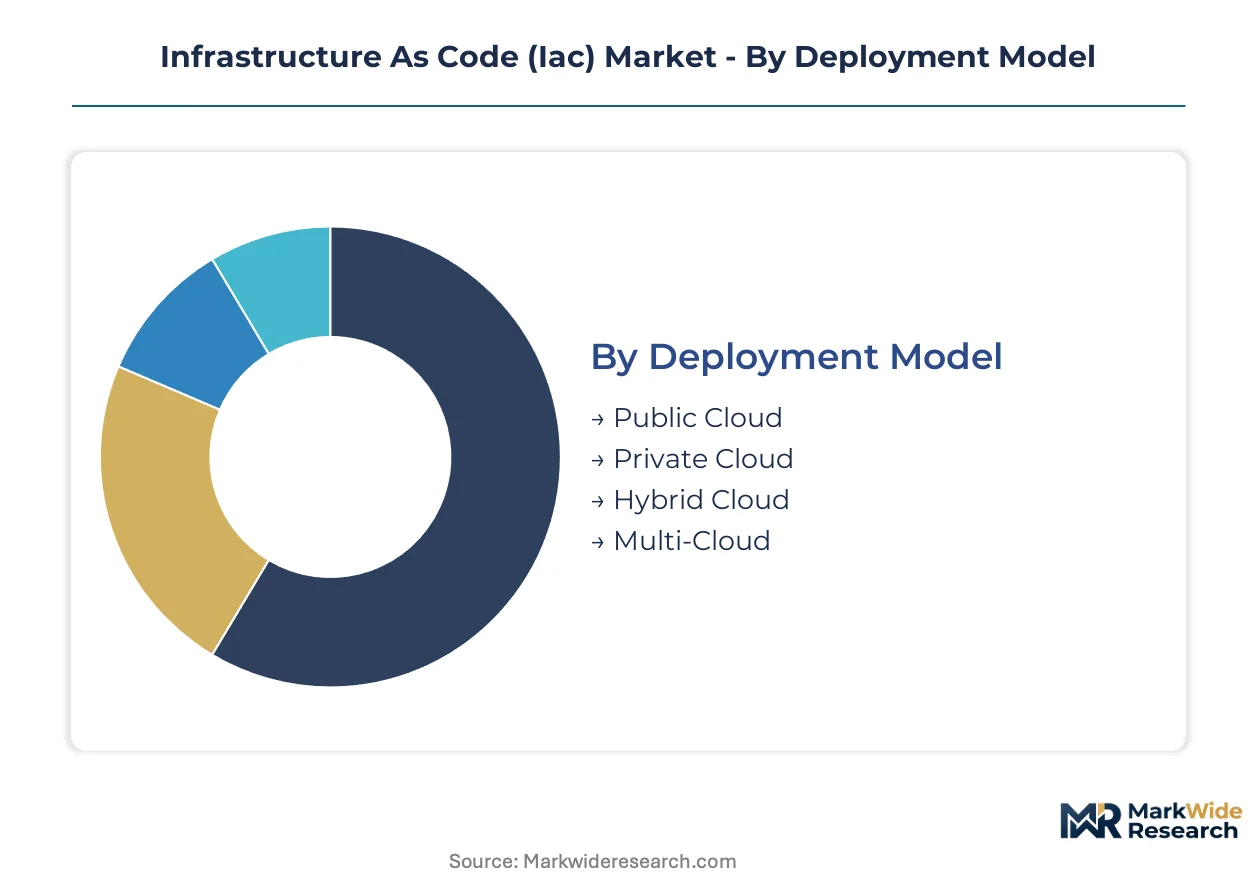
Infrastructure as Code procurement patterns diverge sharply across deployment architectures and regulatory contexts. Enterprises select frameworks based on workload sensitivity, compliance mandates, and existing cloud commitments rather than technical features alone.
Deployment Model:
Upgrade cycles for deployment infrastructure accelerate as organizations retire manual provisioning tools in favor of API-driven alternatives. The replacement wave concentrates where compliance automation has become non-negotiable.
- Public Cloud:Native tooling from hyperscale providers dominates this segment through deep service integration and managed state handling. Demand concentrates among United States federal contractors modernizing legacy systems under NIST SP 800-53 mandates, with procurement favoring CloudFormation and ARM templates that satisfy audit requirements without custom engineering.
- Hybrid Cloud:Bridging on-premises data centers with burst capacity to public resources, this architecture captures expanding margin pools as financial services firms retain sensitive transaction processing on sovereign infrastructure. German automotive manufacturers and United States healthcare providers drive specification requirements for consistent policy enforcement across estate boundaries.
- Private Cloud:Self-managed OpenStack and VMware environments serve classified workloads and regulated industries requiring air-gapped operations. Sovereign cloud initiatives in France and Saudi Arabia sustain investment in dedicated tooling stacks.
- Multi-Cloud:Provider-agnostic frameworks reduce vendor lock-in risk for enterprises operating across AWS, Azure, and GCP simultaneously. State synchronization complexity limits adoption to organizations with mature platform engineering functions.
Public Cloud sits at the top of the volume ranking, with Hybrid Cloud climbing the fastest.
Solution Offering:
Cost tier differentiation separates commodity provisioning tools from premium compliance-integrated platforms. Procurement teams evaluate total cost of ownership across licensing, skill acquisition, and audit preparation.
- Configuration Management:Established tools like Ansible and Chef maintain infrastructure state through imperative scripts, serving brownfield environments where incremental automation outweighs greenfield replacement. United Kingdom public sector bodies favor these approaches for legacy system coexistence.
- Provisioning Automation:Declarative frameworks including Terraform and Pulumi define desired end-states rather than execution steps, compressing deployment timelines from weeks to minutes. Japanese manufacturing conglomerates deploy these capabilities across distributed production facilities.
- Orchestration:Kubernetes-native controllers and Helm charts package multi-service deployments into version-controlled, reusable components. Telecommunications providers in South Korea leverage these patterns for 5G network function virtualization.
- Policy Compliance:Embedded guardrails validate configurations against regulatory frameworks before resource instantiation. This segment expands most quickly as EU Cybersecurity Act certification schemes mandate automated compliance validation for critical infrastructure operators.
- Monitoring:Drift detection and reconciliation engines identify unauthorized manual changes that violate declared infrastructure states. Australian financial institutions invest heavily here to satisfy APRA operational resilience requirements.
Provisioning Automation leads current spending, while Policy Compliance gains share fastest.
Use Case:
Application maturity determines which use cases absorb investment priority. Early adopters focus on velocity; regulated enterprises emphasize control and recoverability.
- Continuous Integration:Automated infrastructure spin-up for test environments accelerates developer feedback loops. Technology companies in Israel and India deploy these patterns at scale.
- Continuous Delivery:Pipeline-integrated provisioning pushes infrastructure changes through staged environments with automated validation. United States e-commerce platforms and European fintechs drive functional requirements.
- Disaster Recovery:Declarative recovery specifications enable infrastructure reconstruction in alternate regions within defined recovery time objectives. Canadian banks and Singaporean government agencies mandate these capabilities.
- Environment Provisioning:On-demand creation of development, staging, and production twins eliminates configuration skew. Brazilian software enterprises expanding internationally rely on this use case for operational consistency.
- Security Automation:Threat-driven infrastructure hardening and automated incident response isolation reduce mean time to containment. United States defense contractors and NATO member states prioritize this capability.
Environment Provisioning commands the largest deployment base, with Security Automation showing the steepest expansion trajectory.
End User Industry:
Customer type segmentation reveals divergent procurement authority and technical sophistication. Industries facing external compliance pressure invest earliest and most heavily.
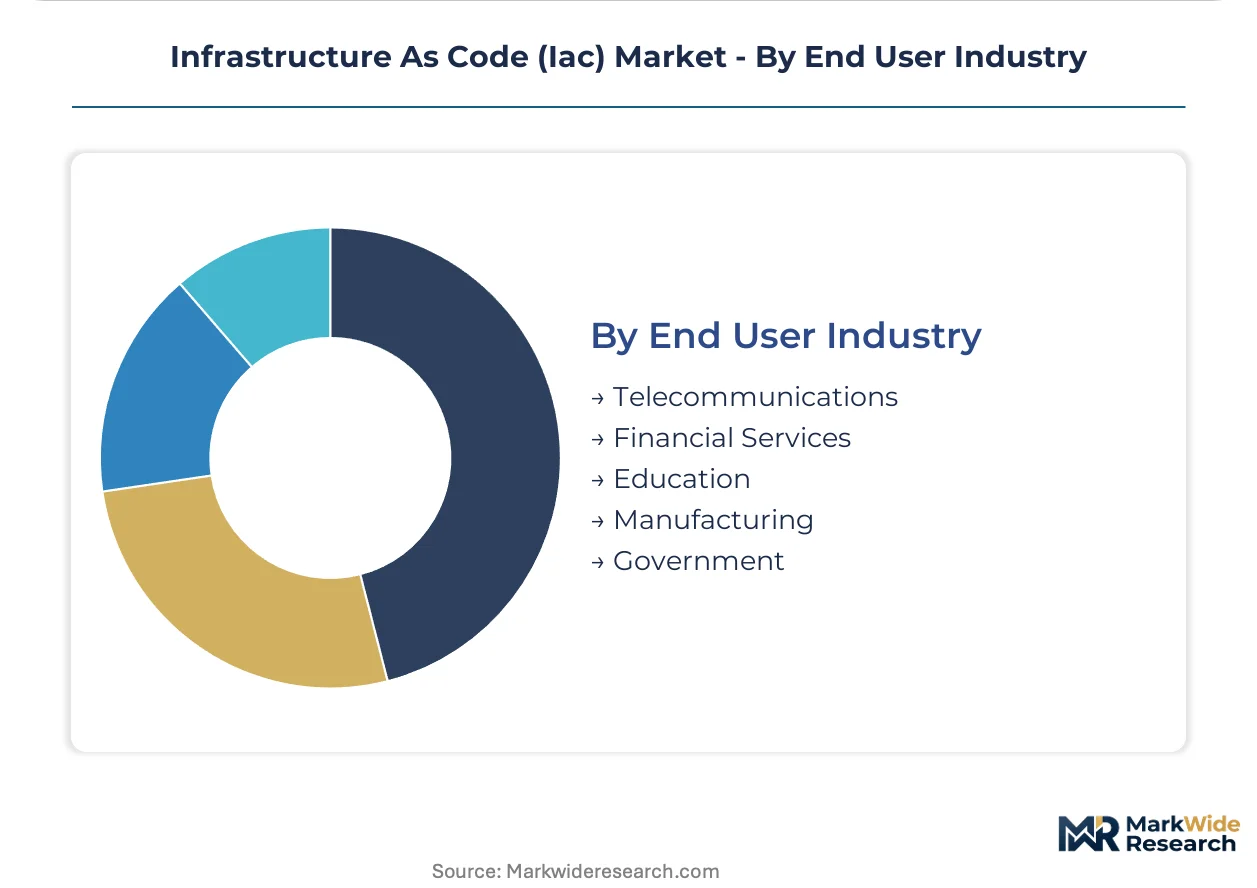
- Telecommunications:5G network rollouts and edge computing expansion demand lightweight, declarative provisioning for distributed compute nodes. EU Cybersecurity Act certification requirements reshape vendor selection criteria across European operators.
- Financial Services:Banks and insurers embed policy-as-code modules directly into CI/CD pipelines to eliminate provisioning errors before production deployment. Basel III operational resilience deadlines in Switzerland and Singapore accelerate procurement timelines.
- Government:Federal cloud migration mandates and hyperscale data center buildouts compress deployment timelines for public sector agencies. United States, United Kingdom, and Australian procurement frameworks increasingly specify IaC as a contract requirement.
- Manufacturing:Industrial IoT deployments and smart factory initiatives drive demand for edge-compatible provisioning tools. German Mittelstand enterprises and Japanese automotive suppliers lead adoption within this sector.
- Education:Research computing and campus IT modernization sustain steady demand for open-source tooling with minimal licensing overhead. University consortia in the Netherlands and Canada coordinate shared service architectures.
Financial Services dominates current revenue concentration, with Telecommunications expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Infrastructure as Code originated within United States hyperscale cloud operations before diffusing through financial centers and government procurement frameworks worldwide. Early standardization efforts at NIST and federal cloud migration mandates established the technical templates now adapted across jurisdictions.
United States
Federal cloud migration programs and hyperscale data center expansion drive enterprise procurement of declarative provisioning frameworks. NIST SP 800-53 security controls mandate auditable infrastructure configurations across federal contractors and their supply chains. Northern Virginia's data center corridor hosts the densest concentration of Terraform and CloudFormation deployments, serving intelligence community and defense contractor requirements.
Germany
Automotive manufacturers and Mittelstand enterprises demand consistent policy enforcement across sovereign on-premises infrastructure and burst capacity to public cloud. The EU Cybersecurity Act's certification schemes reshape vendor selection criteria for critical infrastructure operators. Stuttgart and Munich industrial clusters lead adoption of hybrid cloud configurations for connected vehicle platforms and smart factory initiatives.
United Kingdom
Public sector bodies favor incremental automation approaches for legacy system coexistence rather than greenfield replacement. Government procurement frameworks increasingly specify Infrastructure as Code as a contract requirement for IT modernization programs. London's financial services concentration drives demand for policy-as-code modules embedded directly into CI/CD pipelines.
Japan
Manufacturing conglomerates deploy declarative provisioning capabilities across distributed production facilities to compress deployment timelines. METI industrial digitization initiatives encourage standardization of infrastructure automation practices. Nagoya's automotive engineering corridor and Osaka's industrial machinery clusters represent the primary adoption centers.
Singapore
Financial institutions face Basel III operational resilience deadlines that accelerate procurement timelines for automated disaster recovery capabilities. The Monetary Authority of Singapore mandates auditable infrastructure management for systemically important banks. The city-state's regional headquarters concentration serves as the deployment hub for Southeast Asian operations of multinational banks.
Infrastructure As Code (Iac) Market Key Industry Players
Premium-margin players sit above commodity-margin players across the compliance-integrated versus basic-provisioning dimension. The market structure consolidates around three archetypes: hyperscale cloud providers with native tooling, cross-cloud platform specialists with provider-agnostic architectures, and open-source ecosystem orchestrators. Strategic moves concentrate on embedding policy engines directly into core platforms and restructuring partner compensation around outcome-based delivery metrics rather than upfront software sales.
Within the cross-cloud platform tier, HashiCorp exemplifies the provider-agnostic architecture archetype through its Terraform framework. Among hyperscale cloud operators, Amazon Web Services and Microsoft occupy positions representing native tooling integration strategies. These three entities anchor the competitive structure, with HashiCorp sustaining cross-cloud positioning while AWS and Microsoft leverage deep service integration within their respective ecosystems.
| Leading Market Players |
|---|
| HashiCorp |
| Amazon Web Services |
| Microsoft |
| IBM |
| Oracle |
| Pulumi |
| Red Hat |
| Hewlett Packard Enterprise |
| Others |
Cost & Logistics Intelligence
Horizontal integration through hyperscale cloud provider marketplaces anchors both supply positioning and pricing power for Infrastructure as Code vendors. AWS Marketplace and Azure Marketplace distribution creates captive demand channels that reinforce native tooling premiums while constraining third-party alternatives to price-competitive positioning.
Pricing Analysis
Consumption-based pricing tied to managed resource counts displaces perpetual licensing across the Infrastructure as Code landscape. Price differentiation hinges on compliance certification depth and multi-cloud orchestration breadth, with policy-as-code modules commanding premiums over basic provisioning tools. Cost compression in mid-market segments intensifies as open-source alternatives mature, though federal contractors exhibit minimal price sensitivity due to NIST-mandated audit trail requirements.
Supply Chain Analysis
Single-source vulnerability sits with United States-based hyperscale cloud infrastructure for state file storage and provider API dependencies. Supply concentration in the United States, Ireland, and Singapore shapes tooling distribution, with raw component dependencies spanning compute instances, object storage, and identity management services. Tariff exposure on cross-border data flows threatens margin stability for European deployments. Distribution runs through direct enterprise sales, cloud marketplaces, and systems integrator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Infrastructure as Code market represents a late-cycle quality story as regulated enterprises prioritize policy-embedded platforms over commodity provisioning tools. Demand is concentrating toward premium specifications that satisfy EU Cybersecurity Act certification schemes and NIST SP 800-53 audit mandates.
For Market Incumbents: Anticipate margin compression from open-source alternatives by deepening vertical integration into compliance validation engines and managed state services. HashiCorp and AWS should reinforce channel control through outcome-based partner compensation structures that displace upfront license revenue. The priority lever rests on embedding policy engines directly into core platforms before emerging platform engineering specialists capture mid-market share.
For New Entrants and Emerging Players: Systems integrators with federal contracting expertise represent the most accessible channel partner type for market penetration. White-space opportunities concentrate in Japanese manufacturing conglomerates and German Mittelstand enterprises seeking edge-compatible provisioning tools. Target environment provisioning use cases for Brazilian software enterprises expanding internationally, where operational consistency demands outpace incumbent service coverage.
For Investors and Strategic Acquirers: Roll-up economics work for cross-cloud platform specialists because state management complexity creates natural consolidation pressure as enterprises scale multi-cloud estates. Long-term viability favors providers with provider-agnostic architectures and embedded compliance engines. The signal to watch is federal procurement framework language that elevates IaC from preferred to mandatory contract requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Policy Engine Integration | Embedding compliance validation directly into provisioning pipelines satisfies EU Cybersecurity Act mandates for critical infrastructure operators. |
| Managed State Services | Centralized state file handling reduces corruption risks for Terraform deployments at federal contractor scale. |
| Channel Partner Restructuring | Outcome-based compensation aligns systems integrator incentives with customer deployment success metrics. |
| Edge Infrastructure Tooling | Lightweight provisioning agents address 5G network function virtualization requirements for telecommunications providers. |
| AI-Assisted Configuration | Large language model integration accelerates template authoring for mid-market enterprises lacking specialized HCL expertise. |
Research Approach
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with platform engineering directors, federal procurement officers, cloud architect leads, and systems integrator practice heads informed demand-side assessment. Secondary sources include SEC filings from hyperscale cloud providers, NIST SP 800-53 revision documentation, EU Cybersecurity Act implementing acts, and hyperscaler capital expenditure disclosures. Bottom-up deployment estimates triangulate against top-down market sizing.
Rate-of-change decomposition separates volume expansion from value migration across the analysis window. Segmentation dimensions modeled include deployment architecture, solution offering tier, end-user industry vertical, and regional regulatory cluster. CAGRs derive from installed base growth, replacement cycle acceleration, and premium module attach rates. Forecast inputs incorporate federal cloud migration program timelines and Basel III operational resilience deadline impacts.
Revisions become necessary when hyperscaler pricing restructuring, sovereign cloud mandate expansion, or generative AI disruption of configuration authoring materialize. Forecasts reflect documented assumptions about compliance automation adoption curves and multi-cloud state management complexity thresholds. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Cloud Based Manufacturing Market
Digital Solutions
Managed File Transfer (MFT) Market
Digital Solutions
Global Advanced Distribution Management System (ADMS) Market
Digital Solutions
Digital User Experience Solutions Market
Digital Solutions
Ticketing Solution Market
Digital Solutions
Digital Check Scanning Solutions Market
Digital Solutions
Multichannel Order Management Market
Digital Solutions
Remote Control Duplicators Market
Digital Solutions
North America Digital Signage Market
Digital Solutions
North America API Management Market
Digital Solutions
Data Labeling Solution and Services Market
Digital Solutions
Inventory Management Market
Digital Solutions
North America Enterprise Information Archiving (EIA) Market
Digital Solutions
Global Insight As a Service Market
Digital Solutions
Europe Digital Marketing Software Market
Digital Solutions
Kuwait ICT Market