
 Artificial Intelligence for IT Operations Platform Market | 2026-2036
Artificial Intelligence for IT Operations Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence for IT Operations Platform Market Intelligence
Healthcare IT infrastructure is broadening its reliance on AIOps platforms as hospitals integrate IoT medical devices and electronic health record systems. IBM leverages deep vertical expertise in hybrid cloud management to anchor large enterprise contracts. Microsoft competes through native Azure integration that extends AI-driven observability across multi-cloud estates. Dynatrace specializes in full-stack monitoring with automated root-cause analysis, occupying a premium position in application performance management.
Artificial Intelligence for IT Operations Platforms combine machine learning algorithms, streaming telemetry ingestion, and automated remediation workflows to predict infrastructure failures before service degradation occurs. These systems process log files, metrics, and trace data at sub-second latency to enable autonomous incident response in distributed computing environments. Machine Learning and Predictive Analytics segments lead current revenue generation as enterprises prioritize anomaly detection over manual threshold configuration. Cloud-Based deployment models represent the fastest-expanding category, while On-Premises installations retain margin concentration in regulated industries with strict data residency requirements.
The EU AI Act and GDPR impose algorithmic transparency and data governance requirements that shape platform architecture decisions for vendors serving European enterprises. In the United States, the SEC's cybersecurity disclosure rules and HIPAA technical safeguards drive demand for audit-ready AIOps documentation in financial and healthcare sectors. ISO 27001 and SOC 2 frameworks further constrain vendor qualification, filtering market access toward providers with certified security postures. Stakeholders must monitor evolving AI liability standards and cross-border data flow restrictions as procurement criteria harden across jurisdictions.
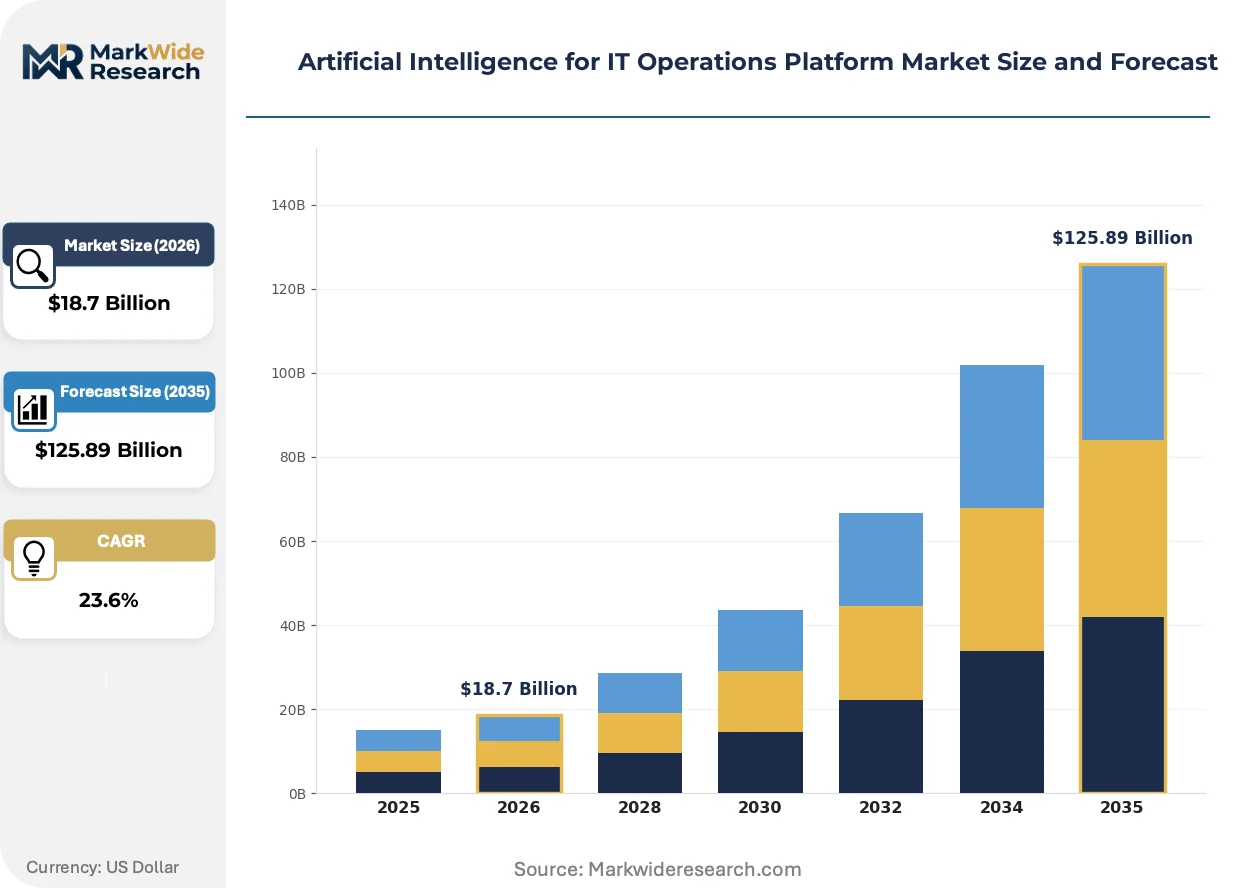
Market Dynamics
Cloud migration mandates under the EU AI Act and parallel governance frameworks in the United States are compressing procurement cycles while forcing architectural redesigns across vendor portfolios. Enterprises now prioritize platforms with built-in algorithmic transparency and cross-border data residency controls.
Growth Catalysts
- EU AI Act compliance deadlines:Financial services institutions in Germany and France are accelerating platform procurement to meet algorithmic transparency requirements for real-time fraud detection systems.
- IoT medical device integration:Healthcare IT infrastructure teams are deploying AIOps to manage telemetry from connected patient monitors and electronic health record synchronization workloads.
- Hybrid cloud complexity:Multi-cloud estates spanning AWS, Azure, and private data centers are generating observability gaps that machine learning-based anomaly detection fills.
Market Restraints
- Data residency compliance costs:Strict GDPR localization requirements force vendors to maintain separate infrastructure stacks for European enterprises, elevating operational overhead.
- Specialized talent scarcity:The shortage of Site Reliability Engineers with machine learning operations expertise constrains deployment velocity at mid-market enterprises.
- On-premises legacy lock-in:Regulated industries with ISO 27001 mandates face technical debt from decades-old monitoring tools that resist API-based integration.
Strategic Opportunities
- India's digital infrastructure buildout:Data center expansion in Mumbai and Bangalore creates demand for autonomous incident response platforms managing distributed computing estates.
- Edge computing convergence:AIOps platforms integrating 5G network slicing telemetry with container orchestration data unlock new manufacturing and logistics applications.
- SEC cybersecurity disclosure rules:Audit-ready documentation requirements for material incident reporting drive platform upgrades at US financial institutions.
Industry Challenges
- ML model explainability gaps:Black-box anomaly detection algorithms struggle to meet regulatory demands for transparent decision trails in healthcare and financial services.
- Fragmented observability data:Log files, metrics, and trace data residing in siloed tools complicate unified root-cause analysis across hybrid environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence for IT Operations Platform Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $125.89 Billion |
| CAGR (2026 – 2036) | 23.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monitoring Tools, Automation Solutions, Analytics Platforms, Incident Management Systems End User: Enterprises, Managed Service Providers, IT Departments, Cloud Service Providers Deployment: On-Premises, Cloud-Based, Hybrid, SaaS Technology: Machine Learning, Natural Language Processing, Predictive Analytics, Deep Learning |
| Companies Covered | IBM, Microsoft, ServiceNow, Splunk, Dynatrace, Broadcom, OpenText, BMC Software, Datadog, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence for IT Operations Platform Market Strategic Shifts & Innovations
Generative AI capabilities are embedding into IT operations platforms, shifting vendor competition from data ingestion scale toward natural language incident investigation and automated remediation scripting.
Large language models trained on operational data are rewriting how Site Reliability Engineers interact with monitoring systems. Healthcare IT teams at hospital networks are piloting conversational interfaces that translate natural language queries into complex PromQL or KQL searches. This compression of the investigation workflow is collapsing mean-time-to-resolution metrics from hours to minutes for common infrastructure failures.
The EU AI Act's risk-based classification system is forcing platform vendors to rearchitect feature sets for European deployment. High-risk applications in financial services now require human-in-the-loop validation for autonomous remediation actions. German and French enterprises are prioritizing vendors with pre-certified conformity assessment documentation to accelerate procurement timelines.
Enterprise buyers are consolidating vendor relationships around full-stack observability suites rather than point solutions for logs, metrics, or traces. Mid-market technology companies in the United States are replacing fragmented toolchains with unified platforms that correlate infrastructure health with business KPIs. This preference shift favors providers with native application performance management and digital experience monitoring integration.
Artificial Intelligence for IT Operations Platform Market Segmentation
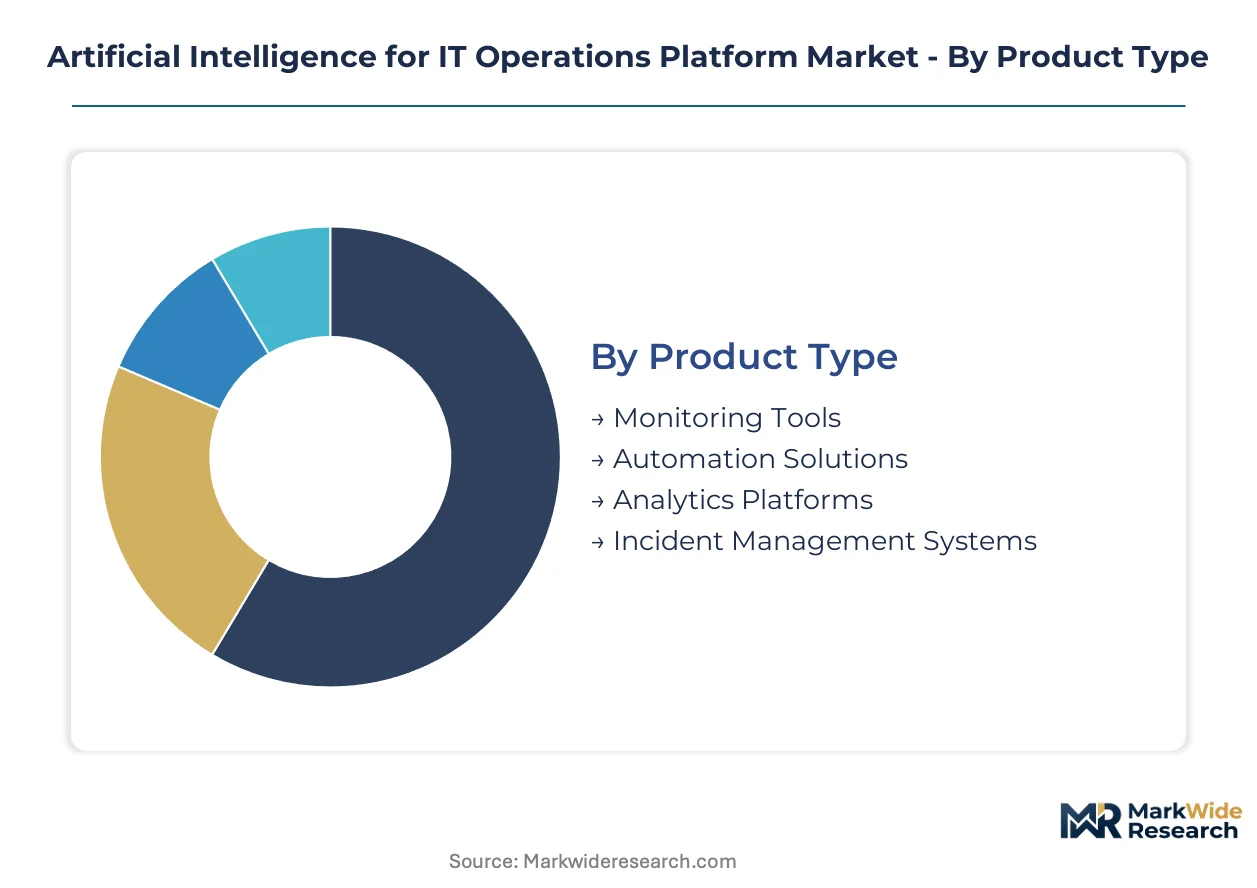
AIOps platforms fragment across multiple technical and commercial dimensions. Procurement patterns diverge sharply between organizations seeking standalone observability stacks versus those embedding intelligence into existing infrastructure management workflows.
Product Type:
Integration depth varies substantially — some segments operate as autonomous control planes while others embed as modular capabilities within broader IT service management suites.
- Monitoring Tools:Core infrastructure telemetry collection engines ingest metrics, logs, and traces at sub-second latency. Financial services institutions in Germany deploy these for real-time fraud detection pipeline observability under EU AI Act transparency mandates.
- Automation Solutions:Autonomous remediation engines execute predefined runbooks without human intervention. Healthcare IT teams at hospital networks prioritize these for patient monitor alert response where mean-time-to-resolution compression directly impacts clinical outcomes.
- Analytics Platforms:Correlation engines that unify siloed operational data into actionable intelligence.
- Incident Management Systems:Workflow orchestration tools bridging detection, escalation, and post-incident analysis.
Monitoring Tools lead volumes today; Automation Solutions are gaining share fastest.
End User:
Customer archetypes span internal IT functions, external service intermediaries, and infrastructure-as-a-service operators with divergent technical maturity and procurement authority.
- Enterprises:Large organizations operating hybrid multi-cloud estates with dedicated Site Reliability Engineering functions. German automotive manufacturers and US healthcare networks represent concentrated demand for full-stack observability with audit-ready documentation trails.
- Managed Service Providers:Third-party operators delivering infrastructure management across client portfolios. These entities prioritize multi-tenant architectures and standardized remediation playbooks that scale across heterogeneous customer environments.
- IT Departments:Internal technology functions with limited dedicated operations engineering resources.
- Cloud Service Providers:Hyperscale infrastructure operators integrating AIOps into native platform offerings.
Enterprises dominate current procurement; Managed Service Providers show the steepest expansion trajectory.
Deployment:
Architecture choices reflect data sovereignty requirements, latency constraints, and legacy system interdependencies rather than pure cost optimization.
- Cloud-Based:Fully managed SaaS delivery eliminating infrastructure overhead. Indian data center operators in Mumbai and Bangalore favor these models for rapid deployment during digital infrastructure buildout phases.
- On-Premises:Self-hosted installations maintaining physical control over telemetry data. US healthcare institutions subject to HIPAA technical safeguards and German financial institutions under GDPR strictures retain this model for sensitive workloads.
- Hybrid:Split architectures processing edge telemetry locally while aggregating analytics in cloud environments.
- SaaS:Subscription-delivered software abstracting underlying infrastructure complexity.
On-Premises retains margin concentration; Cloud-Based deployments are climbing the fastest.
Technology:
Algorithmic approaches differentiate on interpretability, training data requirements, and regulatory defensibility across high-stakes operational contexts.
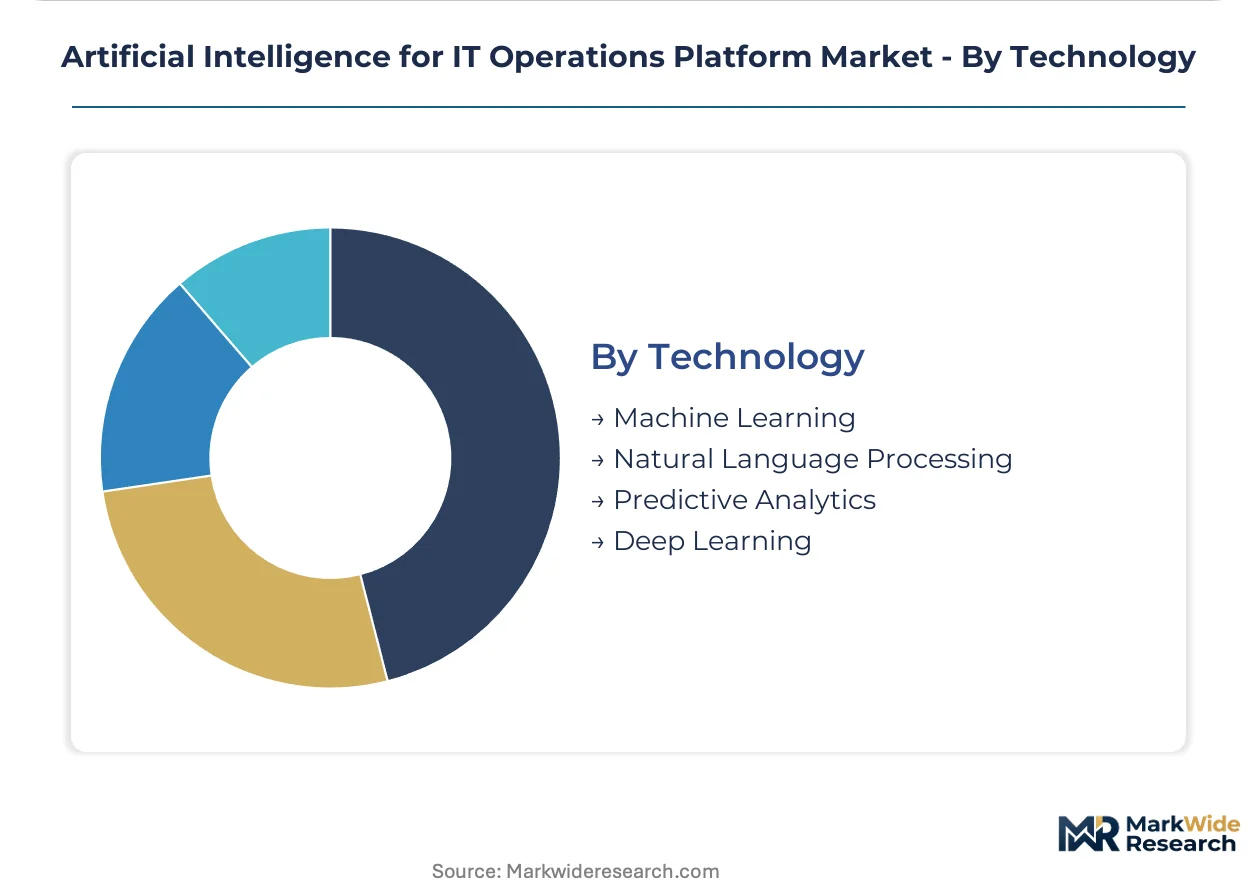
- Machine Learning:Supervised and unsupervised models detecting behavioral anomalies in infrastructure telemetry. These algorithms power the majority of current revenue generation as enterprises prioritize automated threshold configuration over manual baselining.
- Predictive Analytics:Time-series forecasting engines anticipating capacity exhaustion and failure propagation before service degradation manifests. French and German financial institutions under SEC cybersecurity disclosure rules and EU AI Act mandates demand these capabilities for audit-ready risk documentation.
- Natural Language Processing:Text analysis engines extracting operational signals from unstructured log data and conversational interfaces.
- Deep Learning:Neural network architectures processing high-dimensional telemetry patterns with limited feature engineering.
Machine Learning anchors present revenue; Predictive Analytics demonstrates the most rapid share expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping procurement patterns as vendors rearchitect platforms to satisfy divergent compliance costs across jurisdictions. Enterprises in high-regulation markets demand algorithmic transparency certifications, while operators in buildout phases prioritize rapid cloud deployment. This compliance-cost gradient concentrates vendor engineering resources and shapes regional competitive positioning.
United States
Financial services institutions and healthcare networks drive concentrated demand for audit-ready AIOps documentation. SEC cybersecurity disclosure rules and HIPAA technical safeguards mandate transparent incident reporting trails. Hospital networks in Greater Boston and financial services clusters in New York Metro prioritize platforms with native compliance tooling.
Germany
Automotive manufacturers and financial institutions under EU AI Act mandates accelerate procurement for algorithmic transparency. GDPR data residency requirements force vendors to maintain localized infrastructure stacks. Industrial automation hubs in Bavaria and banking centers in Frankfurt represent concentrated deployment sites for autonomous remediation platforms.
India
Data center operators in Mumbai and Bangalore favor cloud-based deployment models during digital infrastructure expansion. RBI guidelines on IT governance and SEBI cybersecurity frameworks shape procurement criteria for financial services. The Maharashtra-Gujarat corridor anchors demand for autonomous incident response managing distributed computing estates.
France
Banking and insurance sectors under EU AI Act high-risk application rules demand human-in-the-loop validation for autonomous actions. CNIL guidance on automated decision-making influences platform architecture choices. Paris-based financial institutions and Lyon healthcare clusters prioritize pre-certified conformity assessment documentation to compress procurement timelines.
United Kingdom
Post-Brexit regulatory divergence creates complexity for vendors serving both UK and EU enterprises. Financial services regulators in London maintain stringent operational resilience requirements. The Southeast technology corridor and Edinburgh financial centers represent concentrated demand for hybrid cloud observability with cross-border data flow controls.
Artificial Intelligence for IT Operations Platform Market Key Industry Players
Platform consolidation through strategic partnerships dominates the current landscape as vendors bundle observability capabilities into unified suites. The vendor base organizes around three tiers: hyperscale cloud operators with native integration advantages, specialized monitoring pure-plays with deep algorithmic expertise, and legacy IT service management incumbents extending into AI-driven automation. M&A activity and technology licensing agreements represent the primary competitive vectors as firms acquire machine learning capabilities and geographic compliance certifications.
Within the hyperscale tier, Microsoft and IBM anchor positions through cloud-native integration and hybrid management expertise respectively. Dynatrace occupies a specialized position exemplifying the premium pure-play archetype focused on full-stack application performance management. These three entities represent divergent strategic approaches: native platform extension, vertical solution bundling, and best-of-breed depth.
| Leading Market Players |
|---|
| IBM |
| Microsoft |
| ServiceNow |
| Splunk |
| Dynatrace |
| Broadcom |
| OpenText |
| BMC Software |
| Datadog |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up monitoring specialists now dominate the AIOps vendor landscape, compressing channel margins while enforcing pricing discipline through unified platform bundling. Their ownership structure concentrates supply-side negotiation leverage against hyperscale cloud providers, creating tiered cost pass-through dynamics that reshape procurement economics for enterprise buyers.
Pricing Analysis
Distributor margin compression in the enterprise software channel is accelerating direct-to-customer SaaS transitions. Subscription tiers stratify across premium full-stack observability, standard monitoring-only modules, and economy alert-management entry points. Price differentiation hinges on ISO 27001 certification grade and multi-cloud integration depth. Cost compression in the mid-market tier is intensifying because managed service providers aggregate demand across heterogeneous client portfolios. Healthcare networks exhibit the lowest price sensitivity due to HIPAA-mandated audit trail requirements, while Indian data center operators show acute sensitivity during infrastructure buildout phases.
Supply Chain Analysis
EU AI Act domestic-content mandates for algorithmic transparency documentation are reshaping vendor sourcing toward localized engineering centers in Germany and France. Core platform development concentrates in the United States, India, and Germany. The supply chain draws from specialized machine learning operations talent pools, GPU compute infrastructure, and compliance certification services. Single-source vulnerability in cloud infrastructure APIs poses structural risk for multi-tenant platform architectures. Distribution runs through direct enterprise sales teams, hyperscaler marketplaces, and regional systems integrators serving regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AIOps market functions as a stable compounder anchored by persistent cloud migration mandates and regulatory compliance deadlines that sustain procurement velocity regardless of macroeconomic cycles.
For Market Incumbents: Anticipate margin pressure from generative AI-native entrants by accelerating full-stack observability bundling and deepening vertical integration into automated remediation engines. Defensive consolidation through acquisition of specialized NLP startups preserves algorithmic differentiation. Channel control via certified partner ecosystems counters hyperscaler marketplace disintermediation threats. For New Entrants and Emerging Players: Enter via India's digital infrastructure buildout, where cloud-based deployment demand outpaces established vendor capacity. Target mid-market managed service providers in Mumbai and Bangalore with lightweight, API-first automation solutions. A consumption-based pricing model with rapid time-to-value demonstration unlocks procurement decisions compressed by SEBI cybersecurity framework deadlines. For Investors and Strategic Acquirers: Hyperscale cloud operators are the most active acquirers in this space, seeking to fill observability gaps in native platform offerings. The long-term viability window favors targets with pre-certified EU AI Act conformity documentation and established healthcare vertical penetration. Watch for inflection signals in SEC cybersecurity disclosure enforcement intensity, which accelerates platform upgrade cycles at US financial institutions.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified observability suites displace fragmented point solutions at German automotive manufacturers. |
| Acquisition of Specialist Firm | Generative AI startups with NLP expertise compress investigation workflows for US hospital networks. |
| Geographic Expansion | Localized infrastructure stacks in France satisfy CNIL guidance on automated decision-making transparency. |
| Strategic Partnership | Hyperscaler alliances accelerate multi-cloud telemetry ingestion for Indian data center operators. |
| Product Launch | Human-in-the-loop validation features address EU AI Act high-risk application requirements in banking. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with platform engineering directors, IT procurement officers at financial institutions, healthcare CIOs, and Site Reliability Engineering leads with secondary validation. SEC 10-K filings, hyperscaler capex disclosures, EU regulatory impact assessments, and healthcare GPO contract databases anchored the data foundation. Bottom-up deployment estimates and top-down market sizing triangulated across independent analytical paths.
Historical reference periods spanning pre-pandemic baseline through cloud acceleration phases anchored the forecast window. The analytical framework modeled deployment architecture, organization size tier, vertical industry, integration complexity depth, and regional regulatory cluster across the projection horizon. CAGRs derived from segment-level trajectory analysis incorporating EU AI Act compliance deadline impacts and SEC cybersecurity disclosure rule adoption curves.
Inputs from vendor financial disclosures and regulatory filing databases were available through the study window; gaps in private mid-market transaction data introduce uncertainty bands around emerging geography estimates. Forecasts reflect documented assumptions regarding compliance timeline adherence and cloud migration velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Commercial Artificial Intelligence Market
Artificial Intelligence (AI)
Synthetic Data Generation Market
Artificial Intelligence (AI)
Edge AI Hardware Market
Artificial Intelligence (AI)
AI-Ready Enterprise Knowledge Graph Market
Artificial Intelligence (AI)
Global Artificial Intelligence Chip Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Accelerator Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
Asia-Pacific AI Orchestration Market
Artificial Intelligence (AI)
Latin America Artificial Intelligence Market
Artificial Intelligence (AI)
Global AI Training Dataset Market
Artificial Intelligence (AI)
Automated Data Annotation Tool Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Life Science Market
Artificial Intelligence (AI)
AI in Retail Market
Artificial Intelligence (AI)
Artificial Intelligence in Logistics Market
Artificial Intelligence (AI)
Artificial Neural Network Market
Artificial Intelligence (AI)
Image Recognition Market