
 Global Data Integration and Integrity Software Market | 2026-2036
Global Data Integration and Integrity Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Data Integration and Integrity Software Market Foresight
Cloud-native architecture is repositioning on-premises middleware economics across enterprise data stacks. Informatica leverages extensive connector libraries to sustain hybrid deployment leadership. Fivetran anchors cloud-native ETL automation for high-velocity analytics workloads. Dell Boomi competes through unified platform integration spanning API management and data orchestration.
Data integration and integrity software encompasses tools that extract, transform, load, validate, and govern information across heterogeneous systems using schema mapping, lineage tracking, and real-time synchronization protocols. These platforms ensure consistency, accuracy, and accessibility for operational reporting and machine learning pipelines. Cloud-based deployment leads in new bookings as enterprises exit fixed-capital data centers, while data governance solutions capture expanding margin pools from regulated industries. Customer analytics applications within BFSI institutions represent the fastest-growing demand segment as banks unify transactional and behavioral data.
The EU AI Act, GDPR, and SEC climate disclosure rules in the United States are mandating auditable data lineage and quality controls, directly expanding procurement of governance and metadata management modules. Japan's METI and South Korea's MFDS are implementing similar data reliability frameworks for cross-border digital trade. Stakeholders must evaluate whether their integration architectures can satisfy emerging algorithmic accountability requirements without sacrificing throughput performance.
Market Dynamics
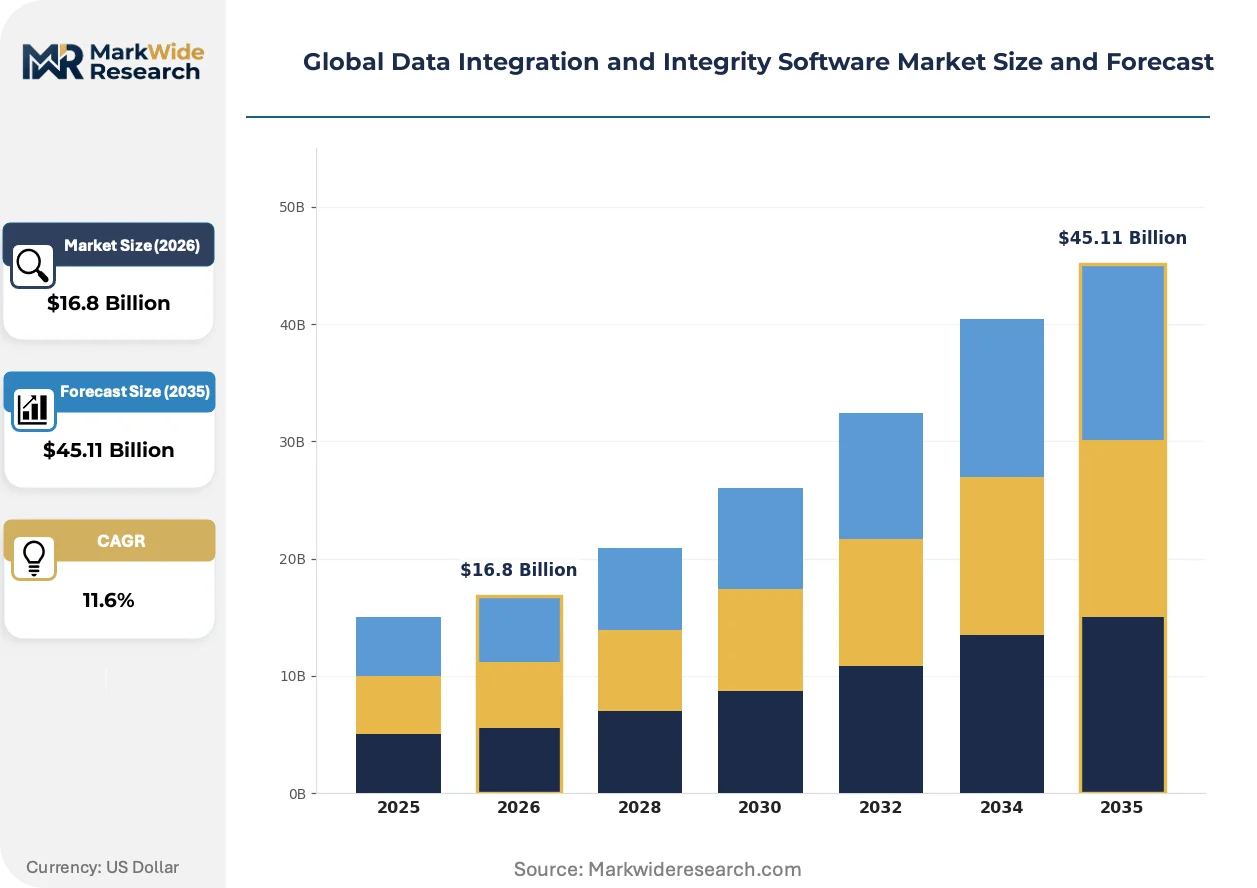
Cloud-native data pipelines are compressing middleware replacement cycles as enterprises abandon fixed-capital data centers for consumption-based architectures. This structural shift is redrawing competitive boundaries between legacy integration vendors and API-native challengers.
Growth Catalysts
- EU AI Act compliance mandates:Auditable data lineage requirements are accelerating procurement of governance modules across European financial services and healthcare institutions.
- Real-time risk analytics:BFSI institutions in the United States, Germany, and India are expanding investments in streaming data infrastructure for operational decision-making.
- Schema mapping automation:Machine learning-powered data preparation tools are reducing manual integration labor in enterprise analytics workloads.
Market Restraints
- Specialized engineering talent scarcity:Shortages of data engineers with distributed systems expertise are inflating implementation timelines and professional services costs.
- Hybrid complexity premiums:Enterprises maintaining on-premises data gravity face 40-60% higher total cost of ownership for dual-environment orchestration.
- Vendor lock-in risks:Proprietary transformation languages and metastore dependencies create switching friction for cloud-committed workloads.
Strategic Opportunities
- India's digital public infrastructure:Account Aggregator framework and Open Credit Enablement Network are creating governed data exchange requirements for fintech integration.
- Edge-to-cloud synchronization:Convergence of 5G latency thresholds and containerized data pipelines is opening manufacturing and logistics use cases.
- SEC climate disclosure rules:Scope 3 emissions tracking mandates are forcing supply chain data unification investments across North American enterprises.
Industry Challenges
- Mainframe connectivity expertise:COBOL-era systems integration knowledge is aging out of the workforce faster than replacement training programs can replenish.
- Cross-border data residency:Fragmented sovereignty requirements between GDPR, China's PIPL, and emerging national frameworks are complicating global architecture design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Data Integration and Integrity Software Market |
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $45.11 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Edge, Private Cloud Solution/Offering: Data Quality Management, Master Data Management, Data Governance, Metadata Management, Data Profiling Application: Customer Analytics, Risk Management, Supply Chain Optimization, Compliance Monitoring, Fraud Detection End User: BFSI Institutions, Telecommunications, Government Agencies, Manufacturing Firms, Technology Providers |
| Companies Covered | MuleSoft, SnapLogic, Informatica, IBM, Workato, Fivetran, Dell Boomi, Adverity, Talend, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Data Integration and Integrity Software Market Shifts & Advancements
Active metadata management is repositioning data catalogs from passive documentation to operational control planes. This evolution is compressing the gap between discovery and enforcement in enterprise data architectures.
Data contracts with programmatic quality enforcement are electrifying the handoff between data producers and consumers. Financial services institutions in London and Singapore are embedding these interfaces into CI/CD pipelines. The technology is compressing incident resolution timelines from days to minutes while reducing downstream analytics corruption.
The EU AI Act's risk classification framework is mandating technical documentation standards for training data provenance. High-risk AI system deployers must maintain immutable lineage records spanning preprocessing, augmentation, and model versioning. German automotive manufacturers and French healthcare AI developers are restructuring data governance workflows to satisfy conformity assessment requirements.
Consumption-based pricing for data pipeline infrastructure is displacing perpetual licensing in enterprise procurement. Buyers in the United States are unbundling professional services from software subscriptions, preferring outcome-guaranteed managed service arrangements. This shift is visible most acutely in mid-market technology companies modernizing from batch-oriented ETL tools.
Global Data Integration and Integrity Software Market Segmentation
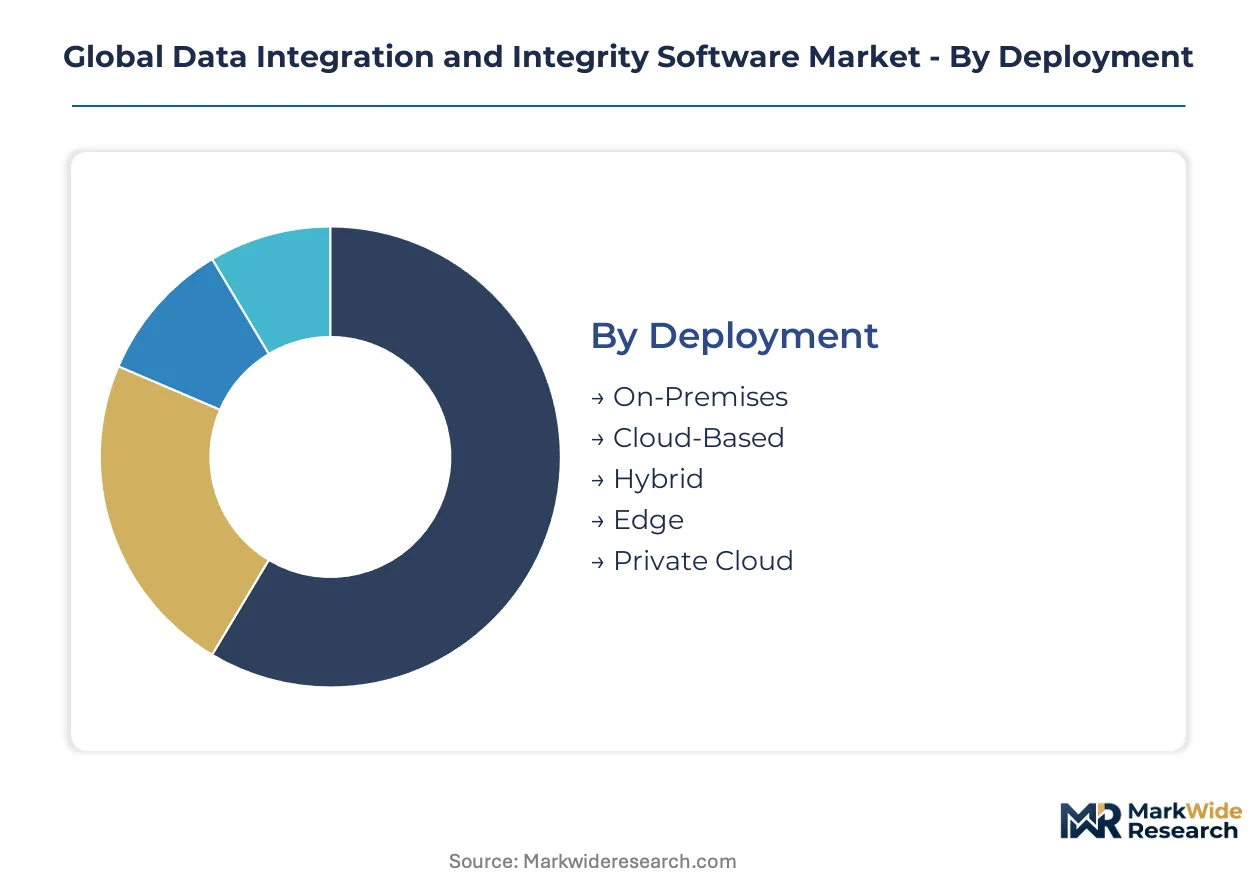
Segmentation in data integration software reveals how procurement decisions split between architectural philosophy and functional priority. Buyers weigh deployment risk tolerance against specific governance mandates that vary sharply by industry.
Deployment:
Capital commitment horizons and data gravity constraints determine infrastructure selection across enterprise buyers.
- Cloud-Based:Consumption-metered infrastructure eliminates fixed-capital data center commitments. United States mid-market technology companies favor this model for analytics modernization, driven by preference for outcome-guaranteed managed service arrangements over perpetual licensing.
- Hybrid:Dual-environment orchestration preserves on-premises data gravity while enabling cloud burst capacity. German automotive manufacturers and French healthcare AI developers deploy this architecture to satisfy EU AI Act conformity assessment requirements without sacrificing throughput performance.
- On-Premises:Fixed-capital installations persist in regulated BFSI institutions with legacy mainframe dependencies.
- Edge:Containerized pipelines synchronize manufacturing floor data with central repositories under 5G latency thresholds.
- Private Cloud:Sovereign infrastructure deployments address China's PIPL and fragmented cross-border residency requirements.
Cloud-Based leads on scale; Edge leads on momentum.
Solution/Offering:
Module selection tracks directly to regulatory pressure intensity and data estate complexity.
- Data Governance:Platforms enforce policy across lineage, access control, and retention with programmatic audit trails. European financial services institutions accelerate procurement here to satisfy GDPR and EU AI Act technical documentation standards for training data provenance.
- Master Data Management:Golden record creation unifies customer, product, and supplier identifiers across heterogeneous systems. BFSI institutions in India leverage MDM to operationalize Account Aggregator framework data exchange for fintech integration.
- Data Quality Management:Validation engines profile completeness, consistency, and timeliness for operational reporting.
- Metadata Management:Active catalogs reposition from passive documentation to operational control planes.
- Data Profiling:Automated discovery tools map schema relationships and anomaly patterns in legacy warehouses.
Data Governance captures expanding margin pools from regulated industries; Master Data Management climbs fastest in emerging market digital infrastructure buildouts.
Application:
Use case priority reflects industry-specific risk exposure and revenue protection requirements.
- Risk Management:Real-time streaming infrastructure enables operational decision-making under volatility. United States and German BFSI institutions expand investments here as interest rate sensitivity and counterparty exposure intensify.
- Customer Analytics:Transactional and behavioral data unification supports personalization at scale. This segment within BFSI institutions shows steepest expansion trajectory as banks compete on experience differentiation.
- Compliance Monitoring:Automated controls track SEC climate disclosure rules and EU CSRD sustainability reporting mandates.
- Supply Chain Optimization:Scope 3 emissions tracking forces data unification across North American enterprise supplier networks.
- Fraud Detection:Anomaly detection pipelines correlate cross-channel signals for real-time intervention.
Risk Management leads on scale; Customer Analytics leads on momentum.
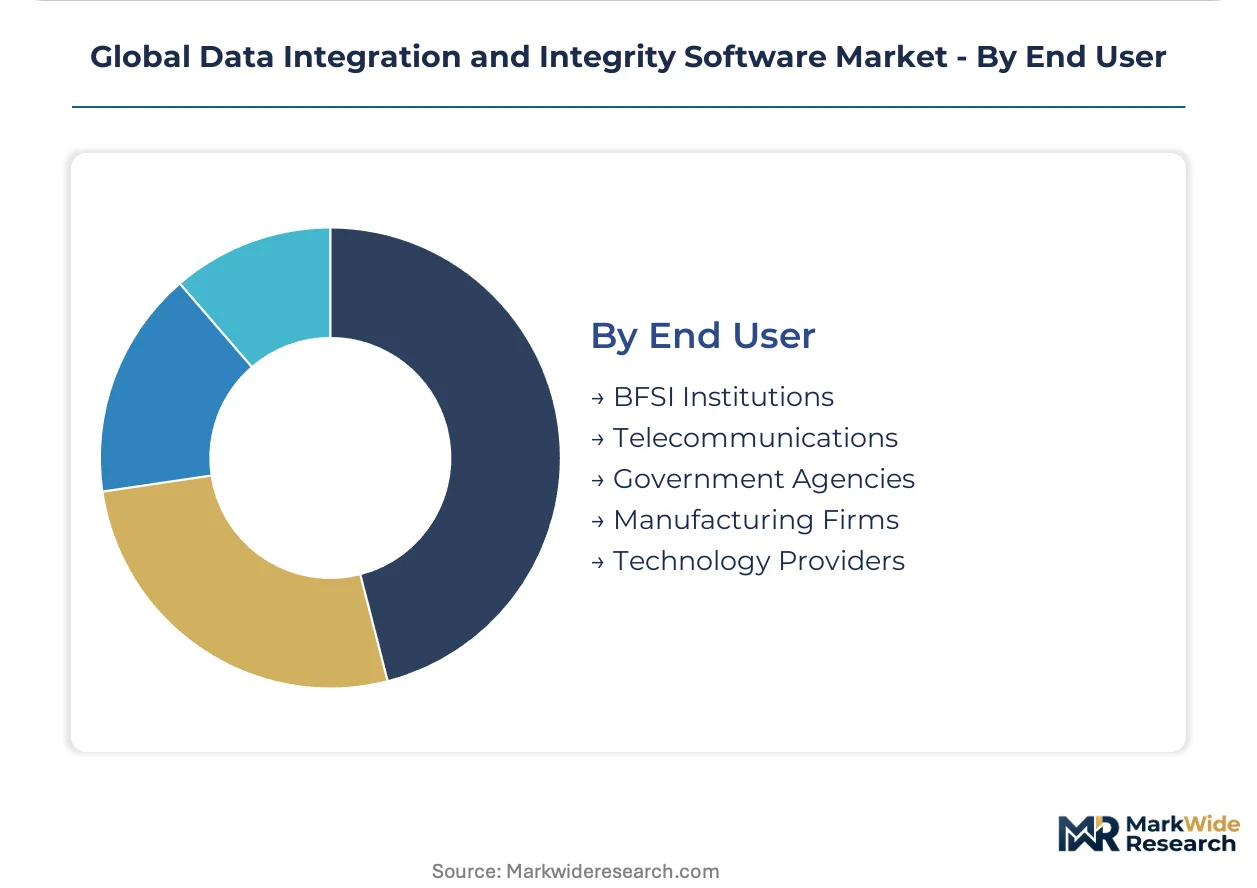
End User:
Sector digital maturity and regulatory burden shape solution sophistication requirements.
- BFSI Institutions:Unified platforms span API management, data orchestration, and governed analytics. These buyers concentrate demand in the United States, Germany, and India as they modernize legacy integration stacks for real-time risk analytics.
- Government Agencies:Sovereign data architectures prioritize residency compliance and inter-agency interoperability. Japan's METI and South Korea's MFDS procurement reflects data reliability frameworks for cross-border digital trade.
- Telecommunications:Subscriber data platforms support 5G network optimization and edge service delivery.
- Manufacturing Firms:Industrial IoT integration demands edge-to-cloud synchronization for predictive maintenance.
- Technology Providers:Embedded integration capabilities differentiate platform-as-a-service offerings.
BFSI Institutions lead on scale; Government Agencies lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's concentration of cloud-native software vendors anchors North American innovation in data pipeline architectures. Enterprise procurement across the United States, Germany, and India is compressing replacement cycles for legacy middleware stacks. Regulatory fragmentation between GDPR, EU AI Act, and China's PIPL is forcing multinational enterprises into sovereign data architecture investments.
United States
Mid-market technology companies in San Francisco and Seattle are unbundling professional services from software subscriptions, preferring outcome-guaranteed managed service arrangements for analytics modernization. SEC climate disclosure rules are mandating auditable supply chain data lineage across North American enterprises. Financial services institutions in New York and Chicago are expanding real-time streaming infrastructure for operational risk decision-making.
Germany
Automotive manufacturers in Stuttgart and Munich are restructuring data governance workflows to satisfy EU AI Act conformity assessment requirements for high-risk AI system deployers. The country's national data protection authority enforces GDPR technical documentation standards for training data provenance. Industrial clusters in Baden-Württemberg are deploying hybrid architectures that preserve on-premises data gravity while enabling cloud burst capacity.
India
Fintech integration demand concentrates in Mumbai and Bangalore as the Account Aggregator framework and Open Credit Enablement Network create governed data exchange requirements. The central bank's digital payment infrastructure mandates are accelerating procurement of master data management solutions. BFSI institutions in Hyderabad and Pune are modernizing legacy integration stacks to unify transactional and behavioral data for customer analytics.
Japan
Manufacturing firms in Nagoya and Osaka are implementing edge-to-cloud synchronization for predictive maintenance under 5G latency thresholds. METI data reliability frameworks for cross-border digital trade are expanding procurement of metadata management modules. Technology providers in Tokyo are embedding data contracts with programmatic quality enforcement into CI/CD pipelines.
United Kingdom
Financial services institutions in London are embedding data contracts into operational workflows, compressing incident resolution timelines from days to minutes. The Information Commissioner's Office enforces GDPR compliance mandates that accelerate investment in governed data architectures. Fintech clusters in Manchester and Edinburgh are procuring cloud-native ETL automation for high-velocity analytics workloads.
Global Data Integration and Integrity Software Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors race to embed integration capabilities into broader platform ecosystems. The vendor base splits between legacy integration suites with extensive connector libraries and API-native challengers with consumption-metered pricing. Three archetypes define competitive positioning: hybrid deployment specialists, cloud-native ETL pure-plays, and unified platform integrators spanning API management and data orchestration. M&A activity and technology licensing agreements represent the dominant competitive moves as incumbents acquire ML-powered data preparation capabilities.
Within the hybrid deployment tier, Informatica and Dell Boomi exemplify the unified platform approach, while Fivetran occupies a position as the cloud-native ETL anchor for high-velocity analytics workloads. IBM represents the legacy enterprise systems integrator archetype with mainframe connectivity expertise. These three companies sit within distinct competitive vectors—on-premises-to-cloud orchestration, consumption-based cloud automation, and enterprise-grade governance suites—without overlapping strategic positioning.
| Leading Market Players |
|---|
| MuleSoft |
| SnapLogic |
| Informatica |
| IBM |
| Workato |
| Fivetran |
| Dell Boomi |
| Adverity |
| Talend |
| Others |
Supply & Pricing Matrix
Consumption-metered cloud infrastructure is redrawing cost economics for enterprise data integration while simultaneously concentrating supplier leverage among hyperscale platform operators. This shift compresses margin pools for traditional perpetual-license vendors and redirects pricing power toward API-native challengers with automated provisioning capabilities.
Pricing Analysis
Input-cost pass-through from cloud compute and storage underpins subscription pricing for cloud-native ETL vendors, with consumption spikes in data-intensive workloads translating directly to customer bills. Three-tier pricing structure across enterprise, mid-market, and developer tiers differentiates by governance depth and connector library breadth, with European buyers exhibiting highest sensitivity due to GDPR compliance overhead. Pricing pressure stems from unbundling of professional services as United States mid-market technology companies demand outcome-guaranteed managed service arrangements. Volume scale drives least price sensitivity among BFSI institutions modernizing legacy mainframe stacks, where switching costs override procurement negotiation leverage.
Supply Chain Analysis
Freight costs for edge hardware deployments exert marginal pressure on hybrid architecture total cost of ownership, though software supply chains remain predominantly weightless. Engineering talent concentrates in the United States, India, and Germany, with distributed systems expertise scarcity inflating implementation timelines across all deployment models. Raw material dependencies center on semiconductor components for edge gateways, cloud compute instances from hyperscale providers, and proprietary transformation language IP locked in vendor metastores. Single-source vulnerability sits with mainframe connectivity expertise as COBOL-era systems integration knowledge ages out faster than replacement training programs replenish. Distribution runs through direct enterprise sales for large BFSI contracts, hyperscaler marketplaces for cloud-native adoption, and systems integrator channels for hybrid complexity premiums.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
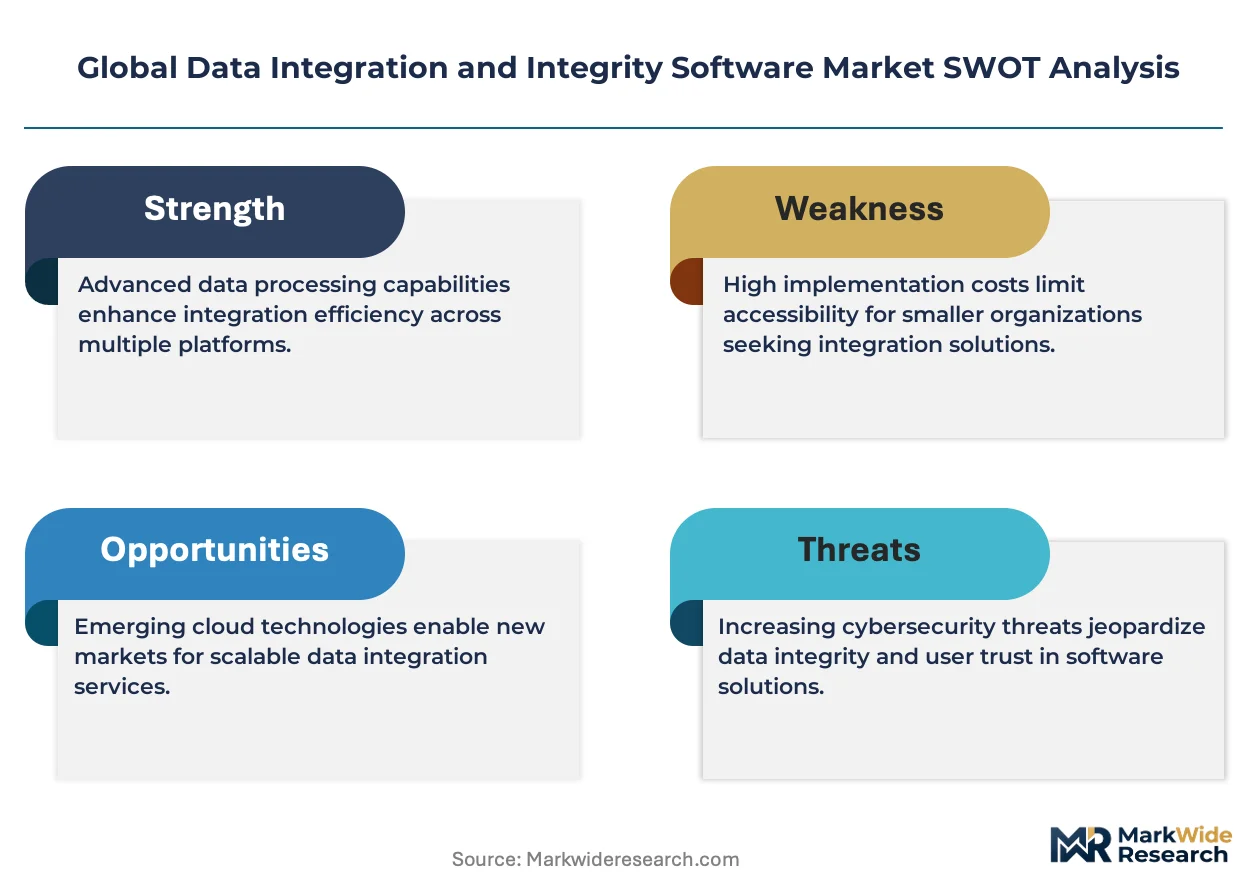
Margin expansion in data integration software rests on automation-driven cost compression in schema mapping and lineage tracking, alongside premium-tier capture from EU AI Act compliance mandates forcing governed architecture upgrades.
For Market Incumbents: Extend connector library coverage into India's Account Aggregator framework and Open Credit Enablement Network protocols before API-native challengers capture fintech integration share. Defend hybrid deployment leadership through embedded data contracts with programmatic quality enforcement, neutralizing cloud-native ETL automation threats in European financial services procurement cycles. Prioritize certification investment for EU AI Act conformity assessment workflows to maintain premium pricing in German automotive and French healthcare AI developer segments.
For New Entrants and Emerging Players: Launch via hyperscaler marketplace distribution to bypass incumbent direct sales infrastructure and capture United States mid-market technology company demand for consumption-metered analytics modernization. Target edge-to-cloud synchronization use cases in Japanese manufacturing and South Korean logistics where 5G latency thresholds create technical moats against batch-oriented legacy tools. Penetrate India's digital public infrastructure buildout through master data management solutions operationalizing central bank payment mandates.
For Investors and Strategic Acquirers: Valuations sit cheapest among hybrid deployment specialists with mainframe connectivity expertise but lagging cloud-native automation capabilities, presenting consolidation targets for platform integrators seeking unified API management and data orchestration breadth. Long-term viability favors vendors with immutable lineage record architectures satisfying emerging algorithmic accountability requirements without throughput sacrifice. Watch for inflection in SEC climate disclosure rule enforcement triggering supply chain data unification investment acceleration across North American enterprise networks.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies API management with data orchestration for BFSI modernization in Germany and India. |
| Acquisition of Specialist Firm | Captures ML-powered schema mapping automation to compress manual integration labor timelines. |
| Strategic Partnership | Embeds data contracts into CI/CD pipelines for London financial services incident resolution. |
| Geographic Expansion | Addresses India's Account Aggregator framework governed data exchange requirements for fintech. |
| Product Launch | Delivers active metadata management repositioning catalogs from passive documentation to control planes. |
Research Methodology
Multiple input streams — primary interviews with data platform engineers, IT procurement officers, and integration specialists; secondary validation through SEC filings, hyperscaler capex disclosures, and EU regulatory documentation; plus customs records for edge hardware trade flows — were reconciled through bottom-up and top-down triangulation. Conversations with CTOs at United States mid-market technology companies, governance leads at German automotive manufacturers, and fintech architects in Mumbai informed deployment model and pricing sensitivity assumptions. Secondary sources included EMA submissions for healthcare AI data provenance standards, METI framework publications for Japanese cross-border digital trade reliability requirements, and RBI circulars on India's digital payment infrastructure mandates.
Data-stream reconciliation across deployment model, organization size, vertical regulatory intensity, integration complexity, and regional adoption pattern segmentation anchored the analytical framework. CAGRs were derived from elasticity modeling of cloud-native migration velocity against legacy middleware replacement cycles, with inputs from schema mapping automation adoption curves and EU AI Act compliance procurement timelines across the analysis window. Industry-specific forecast inputs incorporated edge-to-cloud synchronization uptake in 5G-enabled manufacturing and Scope 3 emissions tracking data unification investment response to SEC climate disclosure rules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated GDPR enforcement fragmentation or hyperscaler pricing volatility. Model outputs reflect assumptions on distributed systems engineering talent replenishment rates and mainframe connectivity expertise retirement curves. A model refresh is warranted upon material change in EU AI Act high-risk system classification scope or India's digital public infrastructure rollout acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Neural Network Software Market
Software & Services
Performing Arts Software Market
Software & Services
Global Automation Software Market
Software & Services
Employee Engagement Solutions Market
Software & Services
Global Automotive Software Market
Software & Services
Decision Support System (DSS) Software Market
Software & Services
Business Activity Monitoring Software (BAM) Market
Software & Services
Global App Store Optimization Tools Software Market
Software & Services
Warranty Management Software Market
Software & Services
Global Back Testing Software Market
Software & Services
Compositing Software Market
Software & Services
Test Automation Market
Software & Services
Global Product Management Software Market
Software & Services
Recruitment Software Market
Software & Services
Global Ad Server Software Market
Software & Services
Online Paint Editor App Market