
 Global Online Form Builder Software Market | 2026-2036
Global Online Form Builder Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Online Form Builder Software Market Foresight
Healthcare intake and patient data collection is rebalancing toward automated, compliance-ready digital workflows. Jotform leverages HIPAA-aligned form infrastructure to anchor its position in regulated verticals. Typeform competes through conversational interface design that sustains premium positioning in customer experience-led segments. Zoho Forms extends its distribution through tight integration with the broader Zoho ecosystem, occupying mid-market share across Asia-Pacific and Latin America.
Online form builder software comprises cloud-native and on-premises applications that enable non-technical users to design, deploy, and manage data collection interfaces through drag-and-drop visual editors, conditional logic engines, and API-driven backend integrations. These tools serve commercial and institutional users by replacing paper-based or coded-form processes with configurable digital workflows that feed directly into CRM, ERP, and analytics systems. Cloud-based deployment leads absolute revenue contribution due to zero-infrastructure onboarding and automatic compliance patching, while automation tools within solution offerings capture the fastest expansion as enterprises demand trigger-based routing and real-time data synchronization. Small businesses dominate customer type volume, though enterprises concentrate margin pools through multi-tenant administration and SSO-enabled security modules.
The US FDA enforces HIPAA requirements that shape healthcare form builder procurement, while the EU AI Act and GDPR impose algorithmic transparency and cross-border data handling standards on vendors serving European enterprises. India's TRAI and emerging data protection frameworks under the Digital Personal Data Protection Act are tightening consent-layer specifications for SaaS tools processing citizen information. Stakeholders must monitor how fragmented national data localization rules reshape vendor architecture decisions and partner ecosystem requirements.
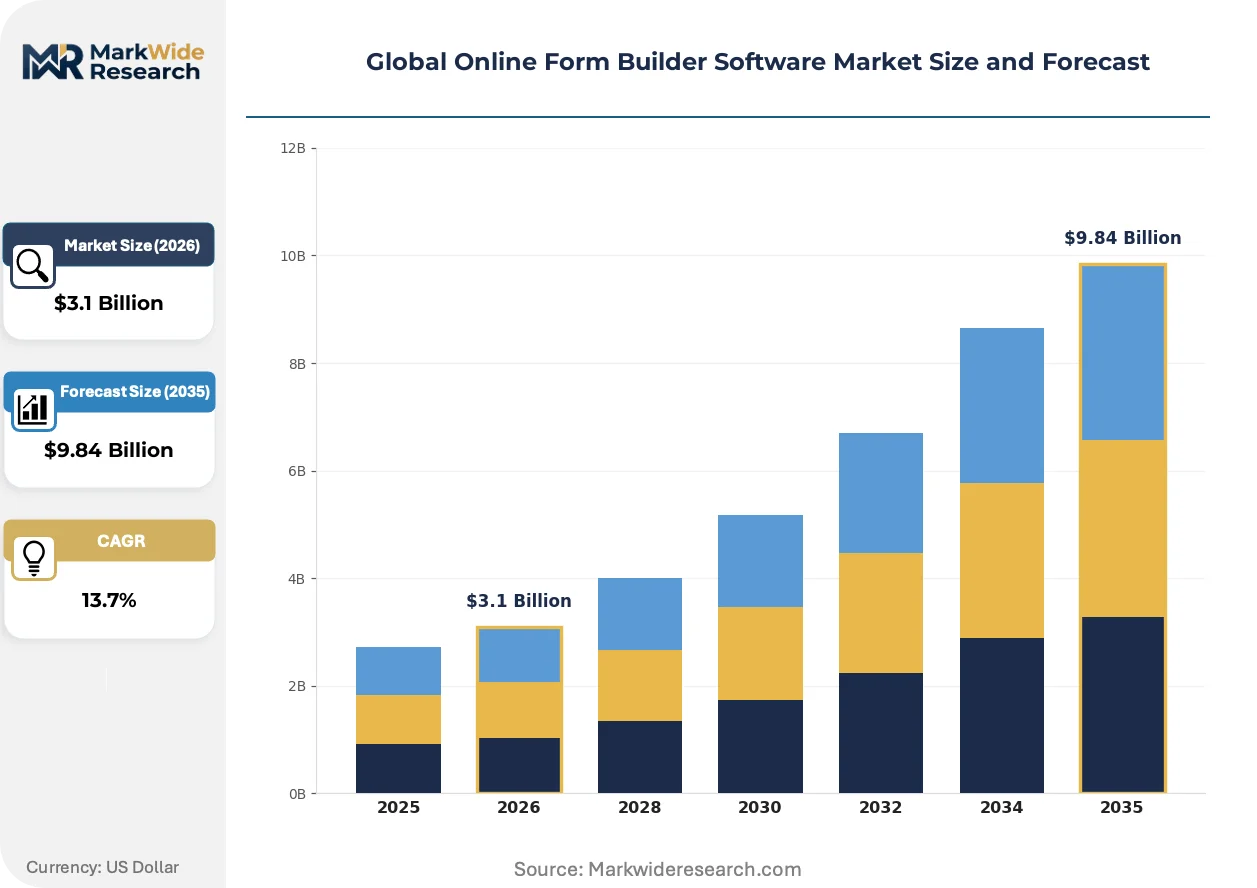
Market Dynamics
Cloud migration mandates under the EU AI Act and India's Digital Personal Data Protection Act are forcing vendors to rearchitect data residency layers, while healthcare procurement teams prioritize HIPAA-aligned intake workflows that compress vendor evaluation cycles.
Growth Catalysts
- EU AI Act compliance deadlines:European enterprises accelerate replacement of legacy paper processes with auditable digital workflows, expanding addressable market for cloud-native form infrastructure.
- Healthcare digitization:US hospitals and clinics deploy automated patient intake to satisfy FDA-enforced HIPAA audit trails, creating sustained demand for compliant form builders.
- API-first architecture:Real-time synchronization with CRM and ERP systems is automating data routing, reducing manual entry errors in enterprise deployments.
Market Restraints
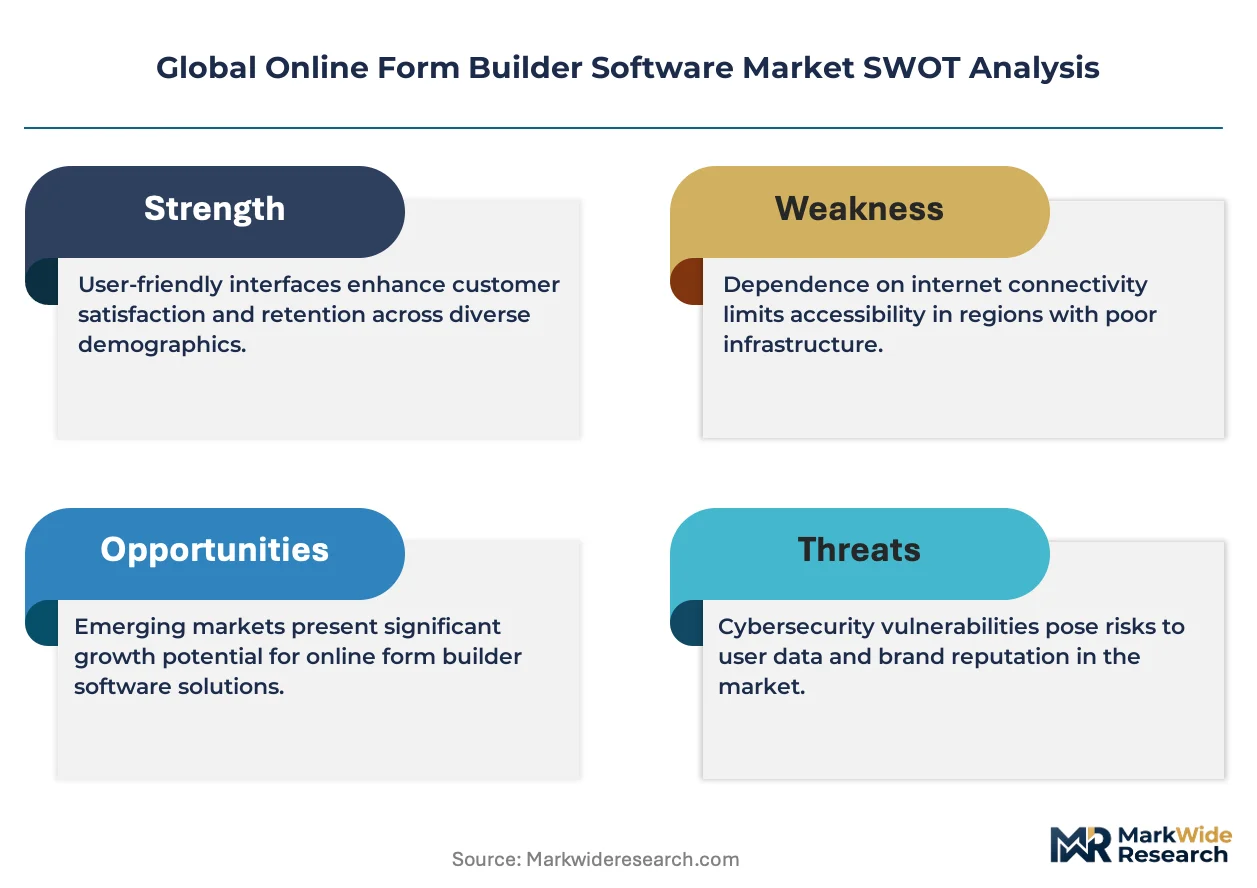
- Data localization fragmentation:Divergent national requirements for citizen data storage increase engineering overhead and limit vendor operational leverage.
- Subscription cost compression:Mid-market buyers resist tiered pricing escalations for advanced conditional logic and SSO modules, squeezing average revenue per user.
- Legacy system entrenchment:On-premises ERP installations in industrial sectors create integration friction that delays cloud form builder adoption.
Strategic Opportunities
- India's SME digitization wave:TRAI-mandated digital service standards and BIS certification pathways open distribution channels for localized SaaS form tools.
- Conversational interface convergence:Natural language processing embedded within form flows is capturing preference in customer experience-led verticals.
- Embedded finance workflows:KYC and payment collection modules integrated directly into form builders unlock new revenue streams in fintech and insurance applications.
Industry Challenges
- Cross-border compliance engineering:Vendors must maintain parallel infrastructure stacks to satisfy simultaneous GDPR, HIPAA, and emerging data protection act requirements.
- Enterprise sales cycle elongation:Security review committees demand extensive penetration testing and SOC 2 documentation, stretching vendor cash conversion timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Online Form Builder Software Market |
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $9.84 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS Solution Offering: Basic Builder, Advanced Designer, Data Integration, Automation Tools, Analytics Dashboard Use Case: Lead Generation, Customer Feedback, Event Registration, Order Management, Survey Collection Customer Type: Small Businesses, Enterprises, Educational Institutions, Non-Profit Organizations, Freelancers |
| Companies Covered | HubSpot, Microsoft Forms, Jotform, involve.me, Fillout, Typeform, Zoho Forms, Heyflow, Google Forms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Online Form Builder Software Market Shifts & Advancements
Form builder functionality is converging with adjacent automation layers, compressing the boundary between data collection and downstream workflow execution. Three developments are restructuring competitive positioning.
Conditional logic engines with branching pathways are automating complex multi-step approvals that previously required manual routing. Healthcare administrators and government agencies are deploying these tools at scale to reduce intake processing bottlenecks. The technology is automating role-based access controls that previously demanded custom development.
The EU AI Act's algorithmic transparency requirements impose documentation burdens on vendors deploying automated decision-making within form workflows. European procurement teams now mandate explainability features that trace how submitted data triggers downstream actions. Healthcare and financial services segments are responding by demanding built-in audit logging that satisfies both GDPR and sector-specific regulators.
Self-service deployment models are displacing traditional vendor-assisted implementations as IT departments shrink and line-of-business buyers gain procurement authority. Mid-market enterprises are adopting no-code configuration tools that bypass technical review committees. This pattern is most visible in Germany and the United States, where SaaS procurement centralization is fragmenting across departmental budgets.
Global Online Form Builder Software Market Segmentation
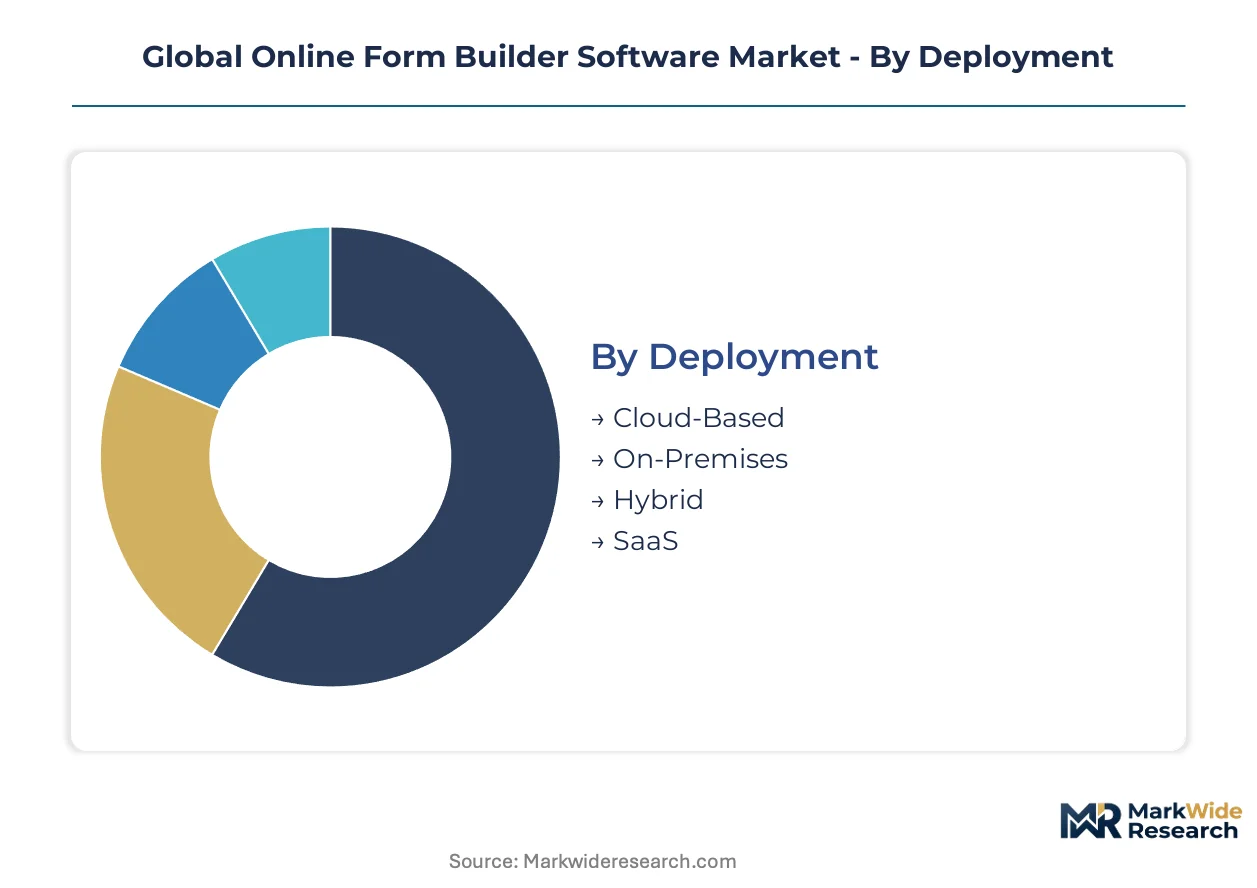
Form builder software segments diverge sharply in infrastructure requirements and compliance burdens. Deployment architecture determines data residency obligations, while customer scale dictates security module sophistication and pricing tolerance.
Deployment:
Cloud-native architectures demand minimal capital expenditure compared to self-hosted alternatives requiring server procurement and dedicated DevOps staffing.
- Cloud-Based:Multi-tenant SaaS infrastructure with automatic patching and elastic scaling. US healthcare systems and German automotive suppliers concentrate procurement here to satisfy HIPAA and GDPR audit requirements without on-site hardware.
- On-Premises:Single-tenant installations on customer-managed servers with full source code control. India's defense contractors and Saudi government agencies mandate this for air-gapped environments under national security directives.
- Hybrid:Split workloads with sensitive data on-premises and public-facing forms in cloud zones. Japanese financial institutions favor this for METI-aligned data classification schemes.
- SaaS:Fully managed subscription tiers with zero configuration onboarding. Freelancers and US small businesses drive volume through self-service procurement portals.
Most installed capacity flows through Cloud-Based deployments. Expansion is steepest in Hybrid configurations as regulated verticals seek compromise architectures.
Solution Offering:
Feature depth correlates directly with integration complexity and professional services attachment rates.
- Basic Builder:Drag-and-drop interfaces with standard field types and limited conditional logic. Indian micro-enterprises and US sole proprietors adopt this for invoice collection and simple contact forms.
- Advanced Designer:Custom CSS injection, white-label domains, and granular permission matrices. German marketing agencies and UK professional services firms pay premium pricing for brand control.
- Data Integration:Pre-built connectors to Salesforce, HubSpot, and SAP ecosystems. Enterprise procurement teams in the United States require this for CRM synchronization without middleware.
- Automation Tools:Trigger-based routing, approval chains, and real-time webhook execution. Healthcare administrators in Australia deploy these for patient intake workflows under TGA documentation standards.
- Analytics Dashboard:Conversion funnel visualization and abandonment pattern detection. E-commerce operators in Brazil and Mexico prioritize this for cart recovery optimization.
Revenue concentrates in Data Integration modules. Automation Tools are gaining share fastest as enterprises replace manual routing with event-driven architectures.
Use Case:
Functional application determines form complexity, field volume, and downstream system connectivity requirements.
- Lead Generation:Progressive profiling forms with CRM enrichment and scoring algorithms. US B2B SaaS vendors and Indian IT services firms deploy these for pipeline acceleration.
- Customer Feedback:NPS and CSAT instruments with sentiment analysis integration. German automotive OEMs and Japanese electronics manufacturers mandate this for quality assurance loops.
- Event Registration:Multi-session scheduling with payment processing and badge generation. Conference organizers in Singapore and UAE rely on this for TRAI and MOHAP-compliant attendee tracking.
- Order Management:Configurable product selectors with inventory validation and tax calculation. UK retailers and Australian distributors require real-time ERP synchronization.
- Survey Collection:Academic research instruments with branching logic and statistical export. Educational institutions in Canada and South Korea favor this for peer-review compliance.
Lead Generation commands the largest deployment base. Order Management is expanding most quickly as B2B procurement digitizes.
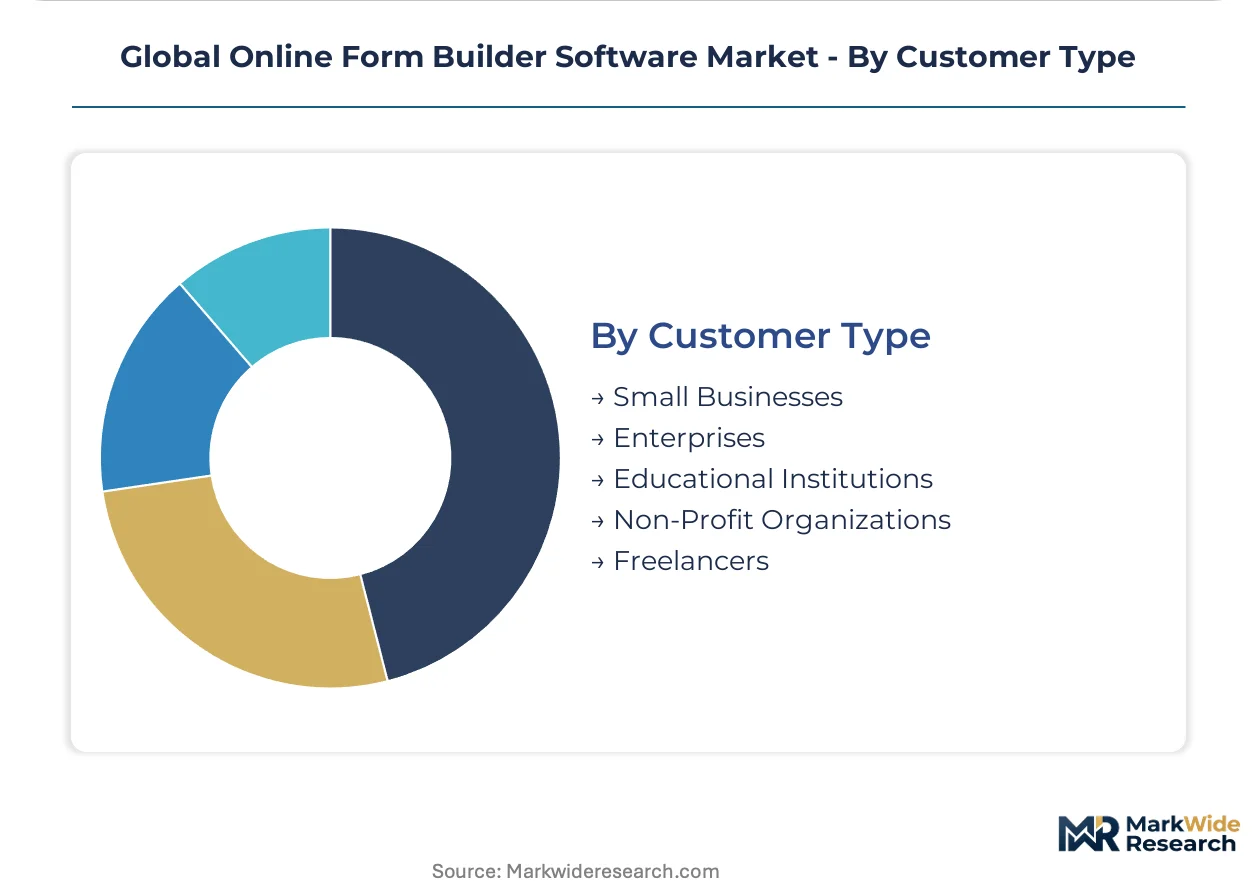
Customer Type:
Organizational scale dictates administrative overhead, security certification requirements, and contract negotiation complexity.
- Small Businesses:Teams under 50 employees with single-admin setups and credit-card billing. This segment dominates unit volume across India, Brazil, and Southeast Asia.
- Enterprises:Multi-tenant deployments with SSO, SCIM provisioning, and custom SLA terms. Fortune 500 procurement in the United States and EU member states drives margin concentration.
- Educational Institutions:FERPA-compliant student data handling with semester-based licensing. US universities and Australian TAFE systems represent dedicated vertical sales motions.
- Non-Profit Organizations:Discounted pricing tiers with donor management integration and grant reporting exports. NGOs in Germany and the UK leverage this for CSRD-aligned impact documentation.
- Freelancers:Individual contractors with pay-as-you-go billing and lightweight embedding options. Creative professionals in Italy and Spain constitute a price-sensitive expansion segment.
Small Businesses account for the majority of active accounts. Enterprises generate disproportionate revenue per seat through security module upsells.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing vendor engineering resources toward jurisdictions with harmonized compliance frameworks, compressing operational leverage in fragmented data-localization environments.
United States
Enterprise SaaS procurement concentrates in healthcare and financial services verticals demanding HIPAA-aligned audit trails. FDA enforcement of patient data handling standards accelerates replacement of legacy paper intake systems with cloud-native form infrastructure. Hospital networks in the Boston-Cambridge corridor and Texas Medical Center drive concentrated demand for compliant workflow automation.
Germany
Automotive suppliers and industrial manufacturers prioritize GDPR-auditable form workflows for supplier onboarding and quality assurance documentation. EU AI Act algorithmic transparency mandates reshape procurement criteria for automated decision-making tools. Manufacturing clusters in Baden-Württemberg and Bavaria deploy conditional logic engines for multi-step approval chains.
India
SME digitization waves across IT services and e-commerce sectors expand addressable market for self-service form builders. TRAI-mandated digital service standards and emerging Digital Personal Data Protection Act requirements tighten consent-layer specifications. Technology parks in Bangalore and Hyderabad anchor enterprise SaaS adoption for customer intake and lead generation workflows.
Japan
Financial institutions and pharmaceutical distributors favor hybrid deployment architectures under METI-aligned data classification schemes. Cross-border data handling restrictions necessitate parallel infrastructure stacks for domestic and international operations. Tokyo-Osaka corridor enterprises invest in automation tools for real-time ERP synchronization and regulatory reporting.
United Kingdom
Professional services firms and marketing agencies demand white-label form infrastructure with granular permission matrices for client-facing data collection. Post-Brexit regulatory divergence from EU frameworks creates compliance engineering overhead for vendors serving both markets. London-based fintech clusters drive embedded finance workflow adoption for KYC and payment collection modules.
Global Online Form Builder Software Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with cloud-native SaaS vendors capturing volume in self-service tiers while enterprise-focused platforms concentrate margin through security module upsells. Market structure tilts toward moderate fragmentation as vertical-specific compliance requirements prevent pure commoditization. Three archetypes dominate: horizontal platforms with broad integration ecosystems, vertical specialists targeting regulated industries, and ecosystem-embedded tools leveraging distribution through adjacent software suites. Competitive moves center on API-first architecture investments and geographic data residency expansion.
Within the horizontal platform tier, Jotform and Typeform occupy positions exemplifying divergent interface philosophies—transactional efficiency versus conversational experience design. Zoho Forms anchors the ecosystem-embedded archetype through tight integration with broader business software suites. Microsoft Forms and Google Forms represent infrastructure-layer entrants leveraging existing productivity suite distribution to capture price-sensitive volume segments.
| Leading Market Players |
|---|
| HubSpot |
| Microsoft Forms |
| Jotform |
| involve.me |
| Fillout |
| Typeform |
| Zoho Forms |
| Heyflow |
| Google Forms |
| Others |
Supply & Pricing Matrix
Enterprise healthcare procurement teams in the United States and Germany concentrate purchasing power for HIPAA and GDPR-aligned form infrastructure, anchoring vendor pricing models to subscription tiers with security module upsells rather than per-transaction fees. This buyer concentration compresses margin pools for mid-market SaaS vendors while rewarding platforms that bundle compliance certification into base pricing.
Pricing Analysis
Distributor margins in the enterprise channel typically range from fifteen to twenty-five percent, though direct-to-enterprise sales bypass this layer entirely through vendor field sales teams. Pricing stratifies across premium, standard, and economy tiers, with differentiation driven by SSO provisioning depth and conditional logic sophistication. Cost compression in the mid-market stems from buyer resistance to tiered escalations for advanced automation modules. Small businesses and freelancers exhibit highest price sensitivity, while Fortune 500 procurement teams prioritize audit-ready security stacks over per-seat cost.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and India anchor cloud infrastructure provisioning for form builder platforms, with hyperscaler partnerships determining latency and data residency capabilities. Engineering talent pools draw from Bangalore, Berlin, and Boston metropolitan clusters. Single-source vulnerability concentrates in hyperscaler compute dependencies, particularly AWS and Azure dominance in healthcare-compliant hosting. Distribution runs through API-first integration marketplaces and direct self-service portals, with professional services layered for enterprise implementations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Online Form Builder Software Market functions as a stable compounder, with regulatory compliance mandates across healthcare and financial services verticals generating recurring replacement demand for legacy paper workflows.
For Market Incumbents: Anticipate margin compression from conversational interface specialists by deepening vertical integration into healthcare-specific compliance documentation and audit logging. Prioritize capacity addition in Indian and German data center zones to satisfy TRAI and GDPR localization requirements. Defensive positioning requires embedding form infrastructure into broader automation suites before low-code competitors capture workflow orchestration layers. For New Entrants and Emerging Players: Launch via API-first integration marketplaces targeting Indian SME digitization waves and UK professional services white-label demand. The most penetrable segment sits in mid-market German automotive supplier networks seeking GDPR-auditable quality assurance documentation without enterprise pricing tiers. A compliance-forward go-to-market angle emphasizing EU AI Act explainability features accelerates procurement committee traction. For Investors and Strategic Acquirers: Vertical software platforms serving healthcare and financial services are the most active acquirer in this space, seeking to embed form infrastructure into existing workflow suites. Over the medium-term horizon, acquisition targets should display HIPAA or GDPR certification depth alongside established API integration ecosystems. The signal to watch is enterprise procurement committee consolidation around bundled automation platforms rather than standalone form tools.| Strategic Initiative | Industry Significance |
|---|---|
| Geographic Data Residency Expansion | HIPAA and GDPR audit requirements in the United States and Germany drive infrastructure localization investments. |
| Platform Integration Partnership | Salesforce and HubSpot connector ecosystems concentrate enterprise procurement preference for CRM-synchronized form tools. |
| Acquisition of Specialist Firm | Conversational interface capabilities from Typeform-class competitors capture premium positioning in customer experience verticals. |
| Compliance Certification Program | FDA-enforced HIPAA audit trails and EU AI Act transparency mandates reshape vendor evaluation criteria. |
| Product Launch | Embedded finance workflows with KYC modules unlock fintech and insurance application revenue streams. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CTOs, IT procurement officers, platform engineers, and healthcare compliance leads with secondary validation against SEC filings, hyperscaler capex disclosures, and hospital procurement databases. Bottom-up deployment estimates across cloud-native, on-premises, and hybrid architectures were triangulated against top-down SaaS spending projections.
Historical reference periods anchored the projection horizon to observed adoption curves in healthcare digitization and EU regulatory compliance waves. Segmentation dimensions modeled include deployment architecture, organization size, vertical industry, integration complexity, and regional adoption pattern. CAGRs derived from fitted growth curves incorporating API penetration rates and conditional logic module attachment trends.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated data localization mandates or hyperscaler pricing shocks. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Artwork Management Software Market
Software & Services
Talent Acquisition Software Market
Software & Services
United Arab Emirates (UAE) Cloud Accounting Software Market
Software & Services
Global Reference Check Software Market
Software & Services
Procure to Pay Software Market
Software & Services
Paraphrasing Tools Market
Software & Services
Case Management Software (CMS) Market
Software & Services
Embedded Software Market
Software & Services
Mining Simulation Software Market
Software & Services
Asia Pacific Human Capital Management Software (HCM) Market
Software & Services
Global PPC Software Market
Software & Services
Lead-To-Account Matching and Routing Software Market
Software & Services
North America Saas-Based Expense Management Market
Software & Services
Automotive Customization Software Market
Software & Services
Global Electronic Design Automation Tools (EDA) Market
Software & Services
Non-Profit Software Market