
 Online Project Management Software Market | 2026-2036
Online Project Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Online Project Management Software Market Intelligence
Market Context
The subscription tiering layer is pivoting from seat-based licenses toward outcome-based consumption models that bundle analytics, storage, and API access into unified contracts. Microsoft Corporation leverages its enterprise distribution channel to embed project management within broader productivity suites. Atlassian Corporation Plc anchors its position through deep integration with developer tooling and IT service management workflows. monday.com Ltd. differentiates through verticalized templates that accelerate deployment in marketing and professional services segments.
Technical Definition and Structural Segments
Online project management software comprises cloud-hosted or on-premise applications that orchestrate task allocation, resource scheduling, milestone tracking, and cross-functional collaboration through centralized digital workspaces accessible via web browsers and mobile endpoints. The primary commercial purpose is to reduce project overruns by replacing fragmented spreadsheets and email chains with real-time visibility into dependencies, bottlenecks, and capacity utilization. Cloud-Based deployment captures the dominant share of new implementations as enterprises prioritize remote accessibility and reduced infrastructure overhead, while Resource Scheduling within Solution Type commands premium pricing due to its direct linkage to labor cost optimization in professional services and construction. Agile Project Management under Use Case is expanding fastest as software development methodologies diffuse into non-IT sectors including financial services and telecommunications.
Regulatory Frame and Outlook
The EU AI Act and GDPR impose algorithmic accountability and data residency requirements that shape feature roadmaps for vendors serving European enterprises, particularly around automated resource allocation and predictive deadline forecasting. In the United States, HIPAA and SEC disclosure rules extend compliance obligations to project management platforms processing healthcare research timelines and financial audit workflows. Stakeholders must evaluate whether their vendor's certification portfolio aligns with sector-specific mandates before committing to multi-year deployment contracts.
Market Dynamics
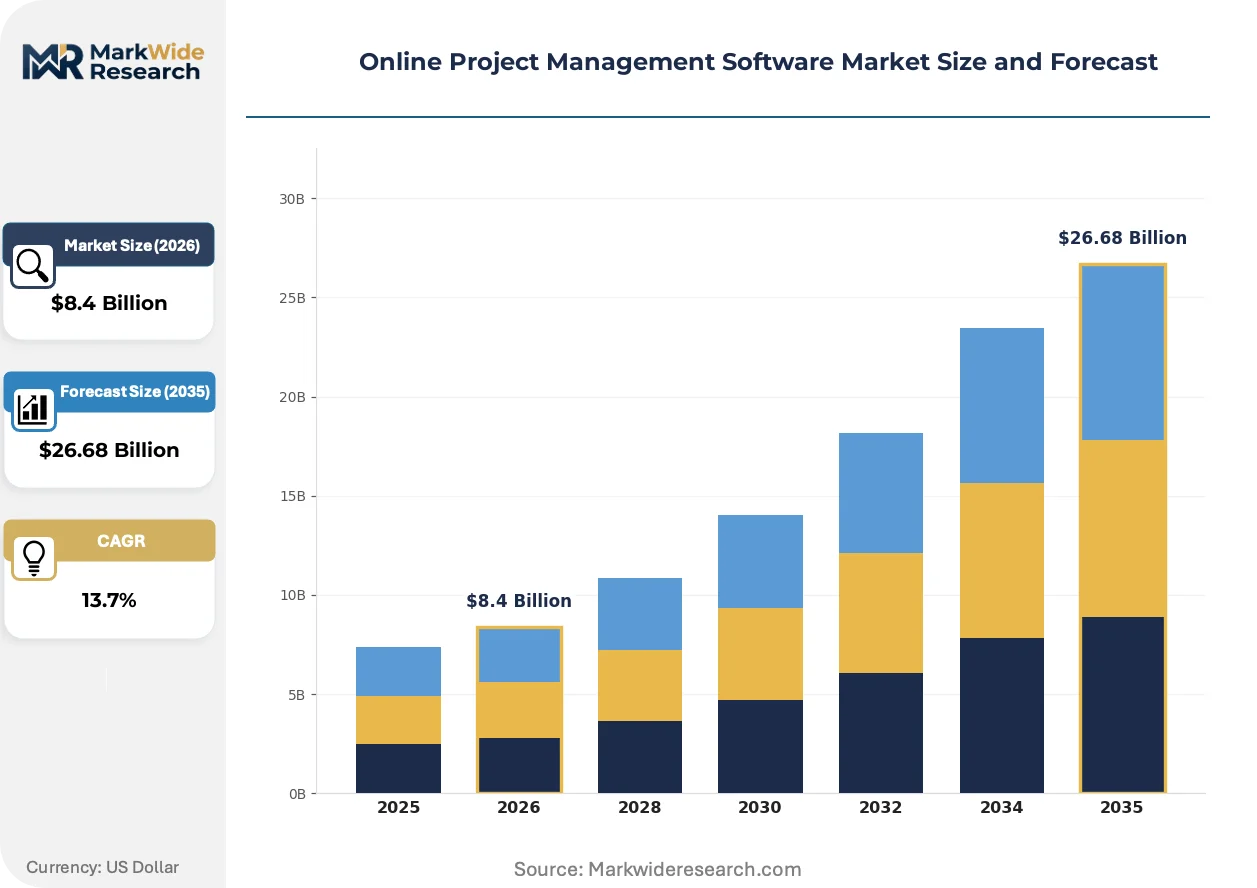
Outcome-based consumption models are compressing traditional seat-based licensing as enterprise buyers demand unified contracts bundling analytics, storage, and API access into measurable productivity metrics rather than per-user fees.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic transparency requirements in workflow automation are prompting vendors to embed explainable AI features, expanding addressable market among European enterprises subject to automated decision-making audits.
- Construction sector digitization:Cloud-based coordination tools are displacing fragmented spreadsheets and email chains as general contractors modernize legacy project tracking systems to reduce cost overruns.
- Agile methodology diffusion:Financial services and telecommunications firms are importing software development workflows into non-IT project portfolios, expanding the addressable user base beyond traditional technology teams.
Market Restraints
- Data residency fragmentation:GDPR localization requirements and divergent national cloud sovereignty laws are forcing vendors to maintain redundant infrastructure across European member states, elevating operational complexity.
- Legacy system entrenchment:Federal contractors in the United States face multi-year modernization timelines due to entrenched on-premise systems and stringent security clearance requirements for cloud migration.
- Skills concentration:Shortage of certified project management professionals capable of configuring advanced resource scheduling modules limits adoption velocity in mid-market professional services firms.
Strategic Opportunities
- HIPAA-compliant healthcare vertical:Research institutions and hospital systems require certified platforms for clinical trial timeline management, creating whitespace for vendors with healthcare-specific compliance portfolios.
- SEC disclosure automation:Financial audit workflow modules that integrate directly with disclosure management systems represent an underdeveloped segment among publicly traded enterprises.
- Edge-mobile convergence:Construction field teams and distributed professional services workers are driving demand for offline-capable mobile endpoints synchronized with cloud master schedules.
Industry Challenges
- Integration architecture complexity:Enterprise IT departments struggle to reconcile API-driven project management platforms with entrenched ERP and HRIS systems, extending deployment timelines.
- Certification timeline compression:Vendors must maintain parallel compliance tracks for ISO 27001, SOC 2 Type II, and sector-specific mandates simultaneously, diverting engineering resources from feature development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Project Management Software Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $26.68 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS, Private Cloud Solution Type: Task Management, Resource Scheduling, Time Tracking, Collaboration Tools, Reporting & Analytics Use Case: Agile Project Management, Waterfall Methodology, Kanban, Scrum, Lean Project Management End User Industry: Information Technology, Telecommunications, Construction, Education, Financial Services |
| Companies Covered | Microsoft Corporation, monday.com Ltd., Asana Inc., Atlassian Corporation Plc, Smartsheet Inc., Zoho Corporation Pvt Ltd., Wrike Inc., Basecamp LLC, Adobe Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Project Management Software Market Strategic Shifts & Innovations
Generative AI capabilities are penetrating workflow automation layers, compressing the gap between raw project data and executive decision support while regulatory pressure on algorithmic accountability intensifies across major economies.
Embedded predictive analytics engines are automating resource allocation recommendations by analyzing historical velocity patterns and capacity utilization across distributed teams. Mid-market professional services firms are adopting these capabilities fastest, replacing manual spreadsheet-based forecasting. This compression of planning cycles is forcing vendors to retrain user interfaces around exception handling rather than data entry.
The EU AI Act's risk classification framework is mandating human-in-the-loop safeguards for automated deadline forecasting modules processing high-stakes infrastructure timelines. Vendors serving European construction and energy sectors must now document algorithmic decision pathways and maintain audit trails. German and French regulators are conducting the first wave of compliance inspections, establishing precedent for enforcement intensity.
Enterprise procurement teams are consolidating vendor relationships by demanding unified contracts spanning productivity suites, developer tooling, and project coordination platforms. IT departments in United States federal contracting and healthcare research segments are rejecting point solutions in favor of integrated stacks. This concentration pressure is most visible among Fortune 500 technology and financial services buyers with mature vendor management functions.
Online Project Management Software Market Segmentation
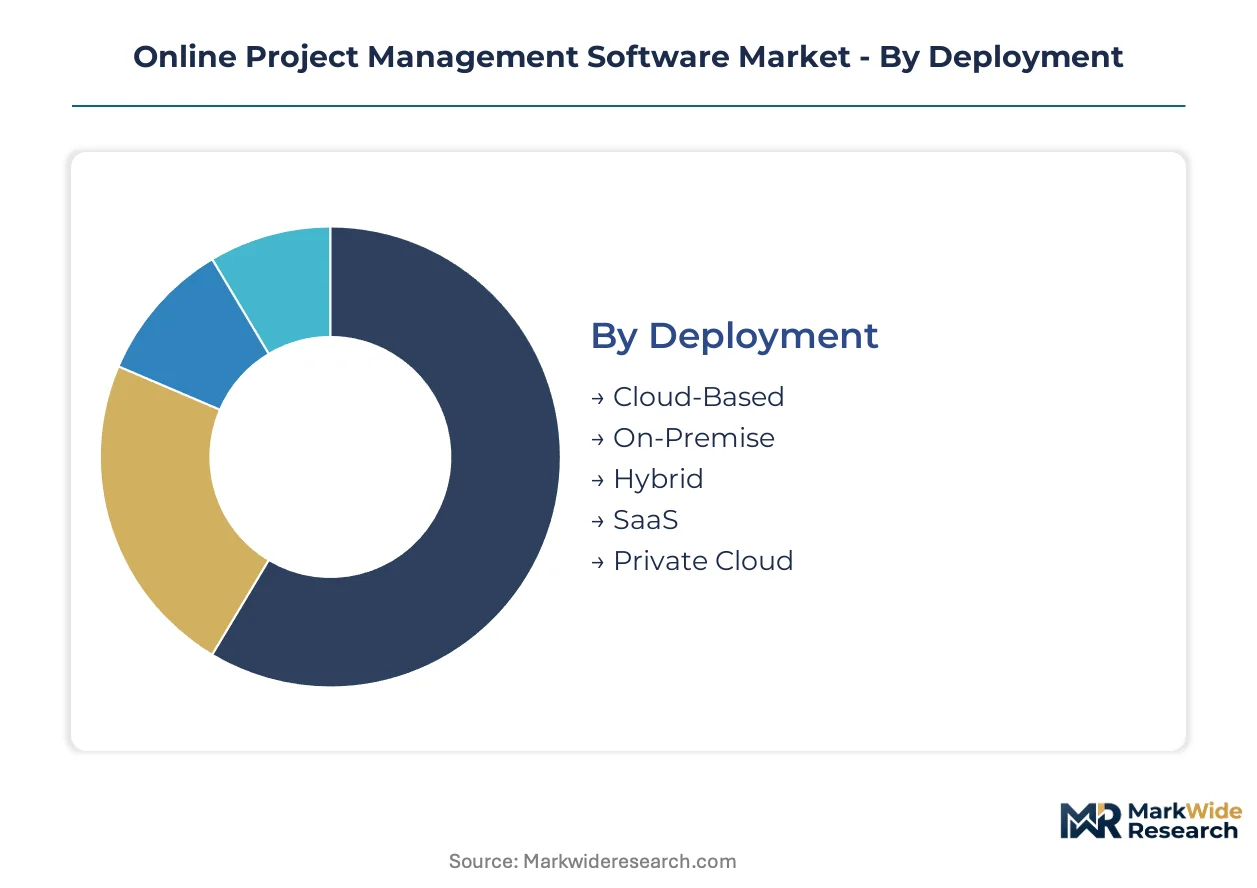
Segmentation in online project management software reveals how deployment architecture, functional modules, methodological workflows, and vertical specialization create distinct commercial battlegrounds. Buyers prioritize integration depth over standalone capability, compressing vendor margins in fragmented segments while rewarding unified platforms.
Deployment:
Integration depth varies sharply across deployment modes, with embedded systems dominating enterprise procurement while standalone configurations persist in regulated niches requiring air-gapped environments.
- Cloud-Based:Multi-tenant architectures with automatic scaling and zero local infrastructure requirements. Demand concentrates among mid-market professional services firms in the United States seeking remote accessibility without capital expenditure. Federal contractors face extended security authorization timelines that slow migration velocity.
- SaaS:Subscription-native delivery with API-first design patterns enabling ecosystem connectivity. European enterprises subject to GDPR data residency mandates drive procurement through vendors with EU sovereign cloud options. Algorithmic transparency requirements under the EU AI Act shape feature roadmaps for automated workflow modules.
- On-Premise:Self-hosted installations maintaining full data custody behind corporate firewalls. Defense contractors and classified research facilities require these configurations for compliance with security clearance protocols.
- Hybrid:Split architectures synchronizing sensitive on-premise data with cloud collaboration layers. Healthcare systems processing HIPAA-regulated clinical trial timelines favor this model for patient data protection.
- Private Cloud:Single-tenant dedicated infrastructure combining cloud elasticity with isolation guarantees. Financial services firms under SEC disclosure rules deploy these for audit trail integrity.
Cloud-Based leads volumes today; SaaS is gaining share fastest.
Solution Type:
Cost tier stratification separates premium resource optimization modules from commoditized task tracking, with pricing power concentrating in segments directly measurable against labor cost reduction.
- Resource Scheduling:Capacity planning engines with predictive load balancing and skill-based assignment algorithms. Construction general contractors in the United States deploy these to compress project overruns and optimize subcontractor coordination. Premium pricing reflects direct linkage to labor cost containment.
- Task Management:Hierarchical work breakdown structures with dependency mapping and critical path visualization. Marketing agencies and professional services firms standardize on these capabilities for client deliverable tracking.
- Time Tracking:Automated capture of billable hours against project codes with integration to payroll systems. Legal and consulting practices require granular audit trails for client invoicing accuracy.
- Collaboration Tools:Real-time document co-editing, threaded discussions, and notification routing across distributed teams. Telecommunications field deployment teams leverage mobile-optimized versions for tower installation coordination.
- Reporting & Analytics:Executive dashboards aggregating milestone velocity, budget burn rates, and risk indicators. Financial services portfolio managers use these for regulatory disclosure preparation.
Resource Scheduling commands premium pricing; Task Management shows steepest expansion trajectory among mid-market adopters.
Use Case:
Application maturity varies by sector, with software development methodologies now diffusing into non-IT workflows and reshaping functional requirements across legacy industries.
- Agile Project Management:Sprint-based iteration with backlog grooming, velocity tracking, and retrospective analytics. Financial services product teams in insurance and retail banking import these workflows from technology departments. Regulatory scrutiny of algorithmic decision-making under the EU AI Act affects automated sprint planning tools.
- Scrum:Time-boxed ceremonies with defined roles and artifact standards. Telecommunications network rollout teams adopt these for infrastructure deployment predictability.
- Waterfall Methodology:Sequential phase-gate progression with formal sign-off requirements. Construction and energy sector projects maintain these for contract compliance and milestone-based payment terms.
- Kanban:Visual workflow management with work-in-progress limits and pull-based replenishment. Manufacturing and logistics operations adapt these for maintenance scheduling.
- Lean Project Management:Waste elimination frameworks targeting process efficiency and value stream optimization. Healthcare administrative operations deploy these for patient flow improvement initiatives.
Agile Project Management leads volumes today; Scrum is climbing the fastest among telecommunications infrastructure teams.
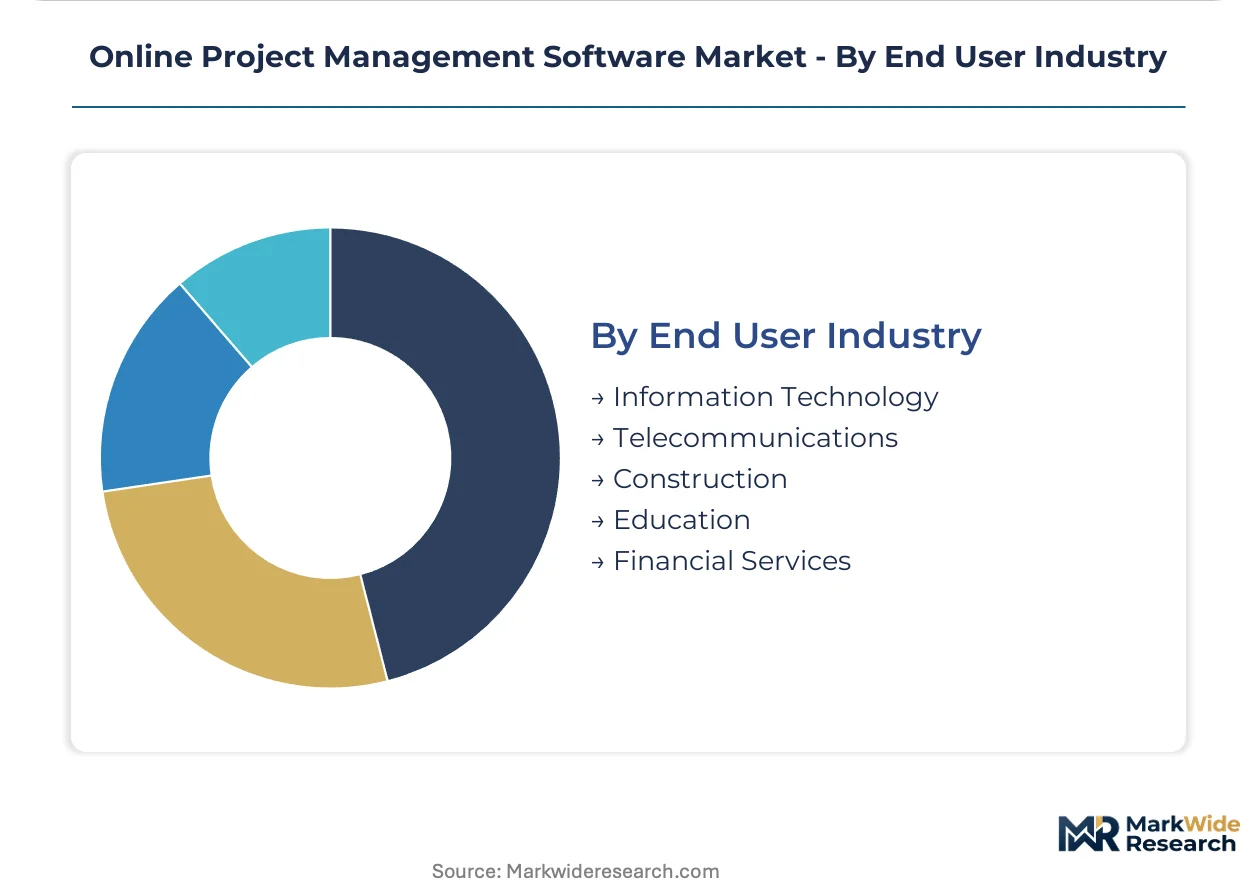
End User Industry:
Customer type concentration drives vertical specialization, with compliance requirements and workflow complexity creating distinct procurement patterns across regulated and unregulated sectors.
- Construction:Field-to-office coordination with subcontractor management, permit tracking, and equipment scheduling. General contractors in the United States modernize legacy spreadsheet systems to reduce cost overruns and improve milestone predictability.
- Information Technology:DevOps-integrated pipelines connecting code repositories, CI/CD automation, and incident response. Software vendors embed project management within broader developer tooling stacks.
- Financial Services:Audit workflow management with SEC disclosure integration and risk control documentation. Publicly traded enterprises require certified platforms for financial reporting timeline coordination.
- Telecommunications:Network infrastructure deployment with tower construction tracking, spectrum coordination, and regulatory filing management. Field technician mobility requirements drive demand for offline-capable endpoints.
- Education:Research grant administration, curriculum development workflows, and institutional accreditation tracking. University systems deploy these for multi-investigator collaboration on federally funded projects.
Construction leads volumes today; Financial Services is expanding most quickly under regulatory disclosure automation pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates federal contractor demand for cloud migration, while Germany enforces algorithmic transparency mandates that reshape vendor feature roadmaps. These divergent regulatory pressures create distinct procurement patterns across major economies.
United States
Federal contractors modernizing legacy on-premise systems drive cloud adoption, though security clearance requirements extend migration timelines. HIPAA and SEC disclosure rules extend compliance obligations to platforms processing healthcare research timelines and financial audit workflows. Demand clusters in Washington D.C. metro and Northern Virginia among defense and intelligence contractors.
Germany
Industrial manufacturing and automotive sectors import Agile methodologies into non-IT project portfolios, expanding the addressable user base. The EU AI Act's risk classification framework mandates human-in-the-loop safeguards for automated resource allocation modules. The Rhine-Ruhr industrial corridor hosts concentrated deployment among engineering and construction firms modernizing project coordination.
United Kingdom
Professional services firms in London and Southeast England adopt outcome-based consumption models bundling analytics and API access into unified contracts. GDPR data residency requirements shape vendor selection criteria for enterprises processing client-confidential project data. The financial services cluster in the City of London drives demand for SEC disclosure-integrated audit workflow modules.
France
Public sector procurement mandates accelerate SaaS adoption among government agencies and state-owned enterprises. CNIL enforcement of GDPR algorithmic accountability requirements affects automated deadline forecasting tools. The Paris-Saclay research cluster generates specialized demand for clinical trial timeline management platforms compliant with healthcare data regulations.
Japan
Telecommunications infrastructure deployment teams adopt Scrum methodologies for network rollout predictability. METI industrial digitization programs subsidize cloud migration among mid-market manufacturers. The Kanto region around Tokyo concentrates demand for DevOps-integrated project management within enterprise software development teams.
Online Project Management Software Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with enterprise productivity suite vendors capturing consolidated procurement decisions while standalone platforms defend niche verticals. The vendor base organizes into three tiers: integrated productivity suite providers, developer-tooling-anchored platforms, and vertical-specialist challengers. M&A activity concentrates on API-first startups enabling ecosystem connectivity, while geographic expansion targets EU sovereign cloud deployments.
Within the integrated productivity tier, Microsoft Corporation exemplifies enterprise distribution scale. Among vertical-specialist challengers, monday.com Ltd. and Asana Inc. occupy positions emphasizing template-driven rapid deployment. These three entities represent divergent strategic archetypes: suite embedding versus vertical acceleration versus workflow-native design. Their collective positioning illustrates how procurement consolidation favors unified contracts while specialized use cases sustain standalone platform viability.
| Leading Market Players |
|---|
| Microsoft Corporation |
| monday.com Ltd. |
| Asana Inc. |
| Atlassian Corporation Plc |
| Smartsheet Inc. |
| Zoho Corporation Pvt Ltd. |
| Wrike Inc. |
| Basecamp LLC |
| Adobe Inc. |
| Others |
Cost & Logistics Intelligence
Certified project management professionals concentrated in the United States and Western Europe command wage premiums that compress pricing-tier spreads between entry-level SaaS subscriptions and enterprise resource-scheduling modules. Labor-cost differentials between these regions and Eastern European delivery centers enable vendors to maintain three-tier pricing structures across premium, standard, and economy levels while preserving margin integrity in high-compliance segments.
Pricing Analysis
Capacity additions in India and Poland are reshaping price floors for implementation and configuration services, compressing margins on mid-market deployments. Subscription-native SaaS delivery dominates, with price differentiation driven by API access depth and vertical certification grade. Cost compression in the standard tier is intensifying because hyperscale buyers negotiate unified contracts bundling analytics and storage. Federal contractors show least price sensitivity due to security clearance requirements, while mid-market professional services firms exhibit highest sensitivity to per-seat fees.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale buyer demand, while value-added resellers and systems integrators serve mid-market implementations requiring customization. Engineering talent concentrates in the United States, India, and Germany, with cloud infrastructure provision drawing from hyperscaler data centers across these markets. The supply chain rests on specialized API development, compliance certification labor, and mobile endpoint hardware. Single-source vulnerability in EU sovereign cloud infrastructure elevates operational risk for vendors serving GDPR-mandated deployments. Distribution runs through vendor-direct sales for Fortune 500 accounts and partner-led channels for regional mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: EU AI Act compliance costs in Germany and France run substantially higher than equivalent certification investments in the United States, creating margin expansion opportunities for vendors with modular algorithmic transparency architectures.
For Market Incumbents: Anchor platform stickiness through deep integration with entrenched ERP and HRIS systems that extend switching costs. Invest in ISO 27001 and SOC 2 Type II certification pipelines to defend against emerging API-first challengers targeting compliance-sensitive healthcare and financial services verticals. Capacity additions in Eastern European delivery centers offer labor-cost leverage for implementation services without compromising data residency requirements. For New Entrants and Emerging Players: Self-service onboarding portals targeting mid-market professional services firms bypass incumbent sales cycles and compress customer acquisition costs. The most penetrable whitespace sits in HIPAA-compliant healthcare verticals where research institutions require clinical trial timeline management with audit trail integrity. A vertical-specialist positioning emphasizing template-driven rapid deployment in construction subcontractor coordination offers defensible beachhead expansion. For Investors and Strategic Acquirers: Valuations sit cheapest among API-first workflow automation startups enabling ecosystem connectivity rather than full-stack platform vendors. Long-term viability across the projection horizon hinges on regulatory certification moats rather than feature velocity alone. Watch EU AI Act enforcement intensity in Germany and France as the primary inflection indicator for compliance-premium pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding project management within Microsoft productivity suites captures consolidated procurement decisions. |
| Acquisition of Specialist Firm | API-first startups with healthcare compliance portfolios address HIPAA-regulated clinical trial whitespace. |
| Geographic Expansion | EU sovereign cloud deployments in Germany and France satisfy GDPR data residency mandates. |
| Strategic Partnership | Systems integrator alliances accelerate mid-market implementations requiring ERP reconciliation. |
| Product Launch | Offline-capable mobile endpoints synchronized with cloud master schedules serve construction field teams. |
Research Approach
Coverage spans the United States, Germany, United Kingdom, France, and Japan, with primary inputs from each market triangulated against secondary validation. Interviews with CTOs, IT procurement officers, platform engineers, and integration specialists informed deployment-model and integration-complexity segmentation. Secondary sources include SEC filings, hyperscaler capex disclosures, EU regulatory filings, and healthcare procurement databases. Bottom-up sizing of vendor-reported subscription revenue and top-down cross-check against enterprise software spending aggregates anchored volume and value estimates.
Granularity-level modeling disaggregated the analysis window by deployment architecture, organization size, vertical specialization, integration complexity, and regional adoption pattern. CAGRs were derived from segment-specific growth trajectories weighted by addressable base expansion. Forecast inputs incorporated construction sector digitization velocity, EU AI Act compliance timeline assumptions, and Agile methodology diffusion rates into non-IT sectors.
The model assumes a particular technology adoption path; alternative pathways for generative AI workflow automation would alter the outlook if regulatory enforcement intensity diverges from base-case assumptions. Forecasts reflect documented assumptions regarding cloud migration timelines among federal contractors and certification pipeline completion rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Avionics Software Market
Software & Services
Compensation Software Market
Software & Services
User Research Repositories Software Market
Software & Services
Asia-Pacific Text to Speech (TTS) Software Market
Software & Services
Global Manufacturing Operations Management (MOM) Software Market
Software & Services
Content Creation Software Market
Software & Services
Europe Contract Lifecycle Management Software Market
Software & Services
Global Call Center Software Market
Software & Services
Visitor Identification Software Market
Software & Services
Global Photogrammetry Software Market
Software & Services
Labor Management Software Market
Software & Services
3D Printing Medical Device Software Market
Software & Services
Global Handyman Software Market
Software & Services
Global Database Software Market
Software & Services
Italy HR Payroll Software Market
Software & Services
Towing Software Market