
 United Arab Emirates (UAE) Cloud Accounting Software Market | 2026-2036
United Arab Emirates (UAE) Cloud Accounting Software Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates (UAE) Cloud Accounting Software Market Insights
Market Context
Modular unbundling of core accounting functions into standalone microservices is hardening buyer expectations across the UAE. Intuit Inc. leverages its QuickBooks ecosystem to anchor SME penetration in Dubai's free zones. Sage Group plc competes through localized VAT compliance engines tailored to UAE Federal Tax Authority requirements. Oracle Corporation dominates large-enterprise deployments with multi-entity consolidation tools for Abu Dhabi sovereign wealth-linked conglomerates.
Technical Definition and Segment Structure
Cloud accounting software delivers browser-accessible financial management through multi-tenant architectures with automated ledger posting, real-time bank reconciliation, and API-native tax reporting. The technology eliminates on-premise server dependency while enforcing role-based access controls and encrypted audit trails for commercial bookkeeping. SaaS deployment captures the dominant margin pool due to zero-install onboarding and continuous regulatory update propagation. Automated invoicing and payroll processing command premium pricing among customer type segments, while hybrid cloud configurations gain traction among UAE banks and insurance entities with data sovereignty constraints.
Regulatory Frame and Outlook
MOHAP's health-sector digital transformation mandates intersect with UAE Central Bank open banking directives to create dual compliance pressure on financial software vendors. SAMR cloud data classification rules and Federal Tax Authority real-time reporting requirements shape product roadmaps and localization investments. Stakeholders must monitor evolving VAT e-invoicing mandates and cross-border data flow restrictions as determinants of vendor viability.
Market Dynamics
Modular unbundling of accounting functions into standalone microservices is compressing vendor margins while elevating buyer expectations for API-native interoperability across Dubai and Abu Dhabi financial centers.
Growth Catalysts
- UAE Central Bank open banking framework:Real-time data sharing mandates are forcing legacy ERP users toward cloud-native reconciliation tools. Dubai fintech clusters are accelerating migration timelines.
- SME digitalization wave:Automated payroll and e-invoicing modules are penetrating Dubai free zones at unprecedented velocity. Federal Tax Authority real-time reporting requirements eliminate paper-based alternatives.
- SAMR cloud data residency rules:Sovereign data classification standards are creating compliant hosting infrastructure. Abu Dhabi sovereign wealth-linked conglomerates are consolidating multi-entity ledgers onto approved platforms.
Market Restraints
- Specialized cloud talent scarcity:UAE-based implementation partners command premium rates for Federal Tax Authority certification. Vendor margins compress during deployment phases.
- Hybrid infrastructure complexity:Banks and insurers with legacy core systems face integration friction. SAMR compliance adds architectural layers that slow rollout velocity.
- Cross-border data flow restrictions:Regional data localization requirements fragment vendor R&D investment. Multi-tenant architectures require jurisdiction-specific instance isolation.
Strategic Opportunities
- Ras Al Khaimah and Sharjah SME corridors:Underpenetrated emirates outside Dubai-Abu Dhabi axis present greenfield acquisition targets. Localized Arabic-language interfaces unlock wallet-share expansion.
- Health sector digital mandates:MOHAP interoperability requirements intersect with financial reporting needs. Specialized vertical modules for hospital networks command pricing premiums.
- AI-native audit automation:Machine learning anomaly detection converges with blockchain immutable ledgers. Early movers capture compliance-averse enterprise segments.
Industry Challenges
- Federal Tax Authority certification timelines:VAT e-invoicing module approval cycles extend 8-14 months. Product roadmaps stall awaiting regulatory sign-off.
- Legacy ERP integration complexity:On-premise Oracle and SAP instances resist API-native connectivity. Custom middleware development consumes professional services capacity.
Report Scope
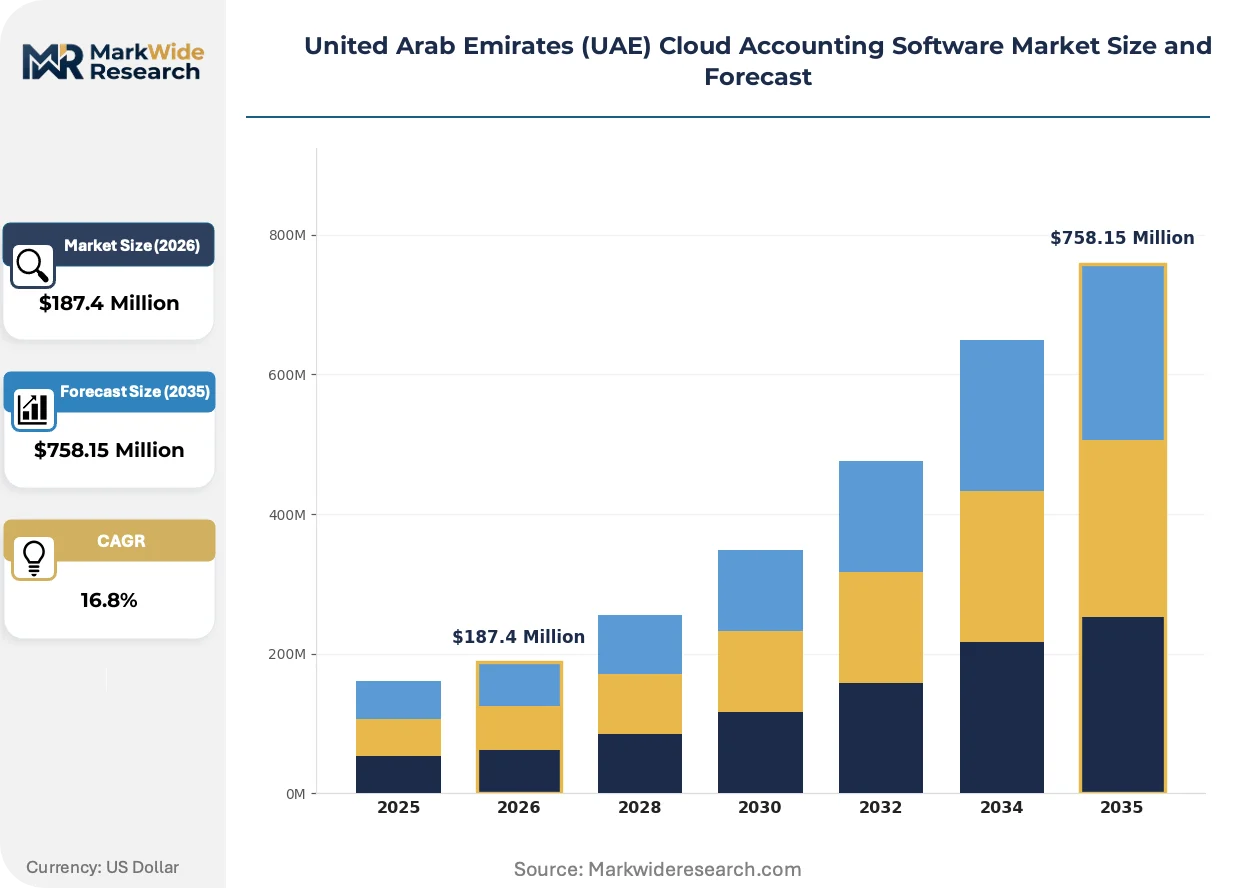
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates (UAE) Cloud Accounting Software Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $758.15 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, SaaS Service Type: Automated Invoicing, Payroll Processing, Financial Reporting, Budgeting Customer Type: SMEs, Large Enterprises, Startups, Freelancers Pricing Model: Subscription-Based, Pay-As-You-Go, Tiered Pricing, One-Time License |
| Companies Covered | Intuit Inc., Sage Group plc, Oracle Corporation, Odoo S.A., Xero Limited, Microsoft Dynamics 365, Zoho Books, Wafeq, Tally Solutions, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates (UAE) Cloud Accounting Software Market Trends and Innovations
Distributed ledger architectures and embedded finance protocols are fragmenting traditional accounting software value chains. Vendor differentiation now hinges on real-time data interoperability rather than feature breadth.
Blockchain-based immutable audit trails are decentralizing trust mechanisms in financial record-keeping. Dubai International Financial Centre institutions are piloting smart-contract reconciliation for cross-border trade finance. This architecture is decentralizing the role of centralized ledger authorities, compressing settlement cycles from days to minutes.
SAMR cloud data classification rules and UAE Central Bank open banking directives are mandating API-first compliance architectures. Vendors must reengineer multi-tenant platforms for sovereign data isolation without sacrificing interoperability. Abu Dhabi-based banks with sovereign wealth fund linkages are driving demand for hybrid configurations that satisfy both frameworks.
Subscription fatigue among mid-market enterprises is fragmenting procurement patterns toward modular best-of-breed stacks. Buyers in Dubai's technology free zones are unbundling core accounting from payroll and tax modules, selecting point solutions over integrated suites. This behavior is most visible among Series B-stage fintechs prioritizing speed-to-compliance over vendor consolidation.
United Arab Emirates (UAE) Cloud Accounting Software Market Segmentation
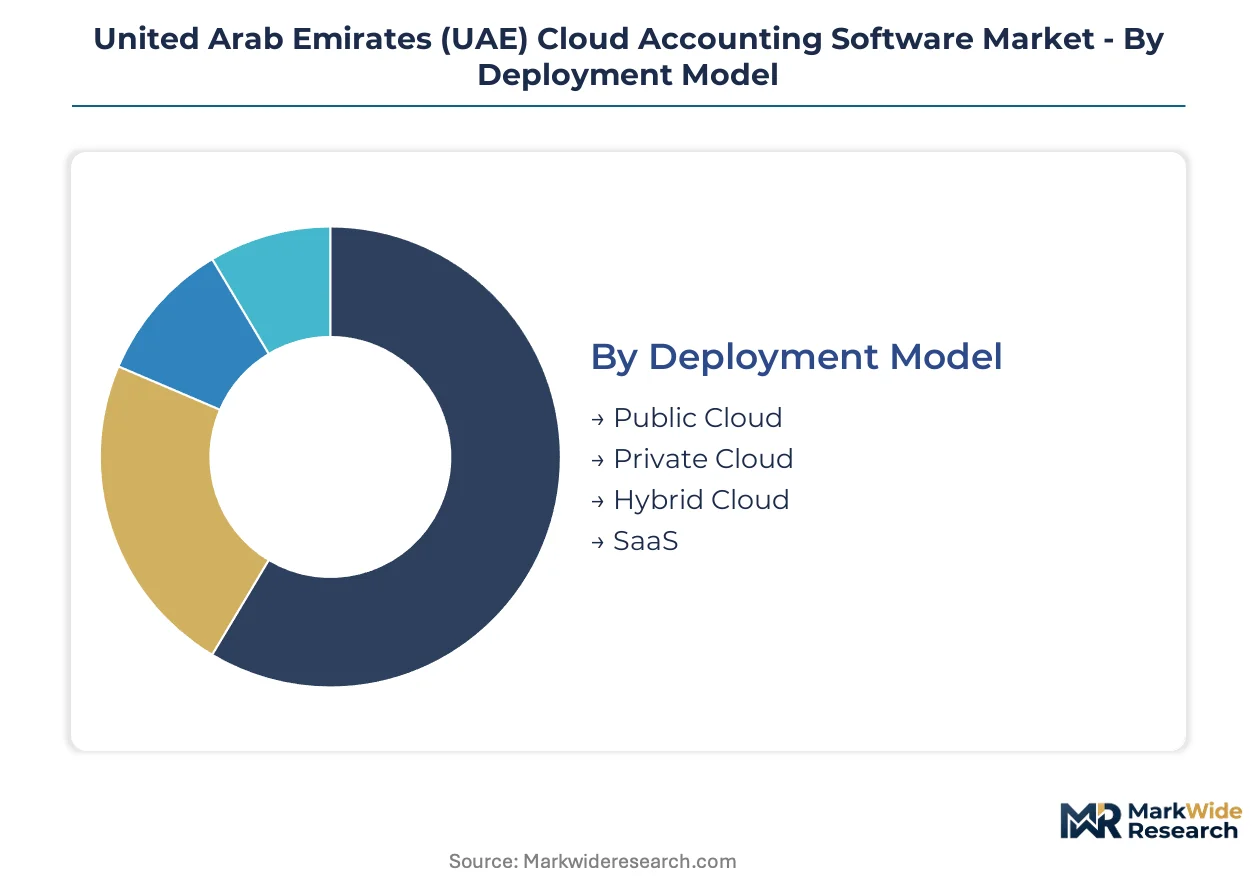
Deployment architecture and customer scale create divergent compliance burdens across the UAE cloud accounting landscape. SAMR data residency rules and Federal Tax Authority reporting mandates fragment procurement patterns by segment.
Deployment Model:
Buyer risk tolerance toward data sovereignty dictates infrastructure selection across Dubai and Abu Dhabi financial centers.
- SaaS:Multi-tenant browser delivery eliminates server maintenance overhead while propagating regulatory updates automatically. Dubai free zone SMEs favor zero-install onboarding for Federal Tax Authority real-time reporting compliance. Volume sits with SaaS; growth tilts toward Hybrid Cloud.
- Hybrid Cloud:Split architectures isolate sensitive ledger data on-premise while routing transactional workflows through compliant cloud nodes. Abu Dhabi sovereign wealth-linked conglomerates demand this configuration for SAMR classification adherence. Procurement concentrates among banks and insurers with legacy core system dependencies.
- Public Cloud:Shared infrastructure delivers cost efficiency for standardized bookkeeping workloads without jurisdiction-specific customization.
- Private Cloud:Single-tenant dedicated environments satisfy the strictest data isolation requirements for healthcare and government entities.
SaaS dominates transaction volume; hybrid configurations expand most quickly under regulatory pressure.
Service Type:
Module selection correlates with customer digital maturity and payroll complexity across emirate-level labor markets.
- Automated Invoicing:API-native e-invoice generation integrates directly with UAE Federal Tax Authority portals for real-time VAT submission. Dubai fintech clusters deploy this module first to accelerate compliance velocity. Demand concentrates among Series B-stage enterprises unbundling from legacy ERP suites.
- Payroll Processing:WPS-compliant salary disbursement automation handles gratuity accruals and end-of-service calculations per UAE Labor Law. Abu Dhabi construction and logistics conglomerates with multi-national workforces drive premium pricing acceptance. Wage Protection System integration mandates elevate this to mission-critical status.
- Financial Reporting:Consolidated multi-entity dashboards serve holding company structures with cross-emirate operations.
- Budgeting:Scenario-planning tools attract project-based industries with volatile contract pipelines.
Payroll commands the steepest pricing premiums; automated invoicing gains share fastest among compliance-averse entrants.
Customer Type:
Organizational scale determines integration complexity and customization depth requirements across the UAE commercial landscape.
- SMEs:Modular procurement patterns favor best-of-breed point solutions over integrated suites. Dubai technology free zone startups prioritize speed-to-deployment over vendor consolidation. This segment drives API-native interoperability expectations.
- Large Enterprises:Multi-entity consolidation tools manage complex ownership structures spanning sovereign wealth-linked portfolios. Abu Dhabi headquarters operations demand Arabic-localized interfaces and dedicated implementation support. Procurement cycles extend 12-18 months with extensive Federal Tax Authority certification requirements.
- Startups:Pre-revenue ventures select freemium tiers with upgrade pathways toward Series A scalability.
- Freelancers:Solo practitioners require mobile-first expense capture and simplified tax filing workflows.
Large enterprises anchor revenue concentration; SMEs expand most rapidly through free zone digitization mandates.
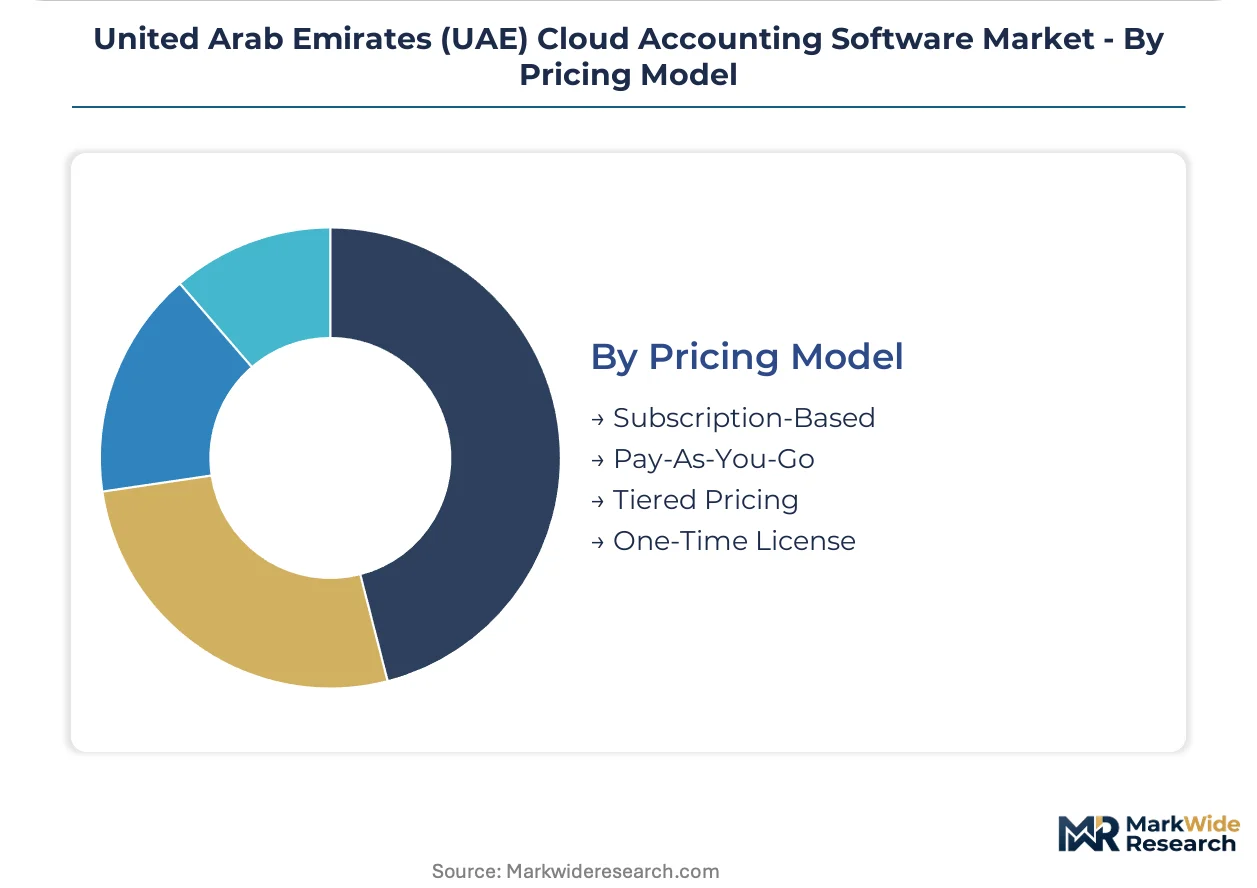
Pricing Model:
Contract structure preference signals customer cash flow predictability and commitment horizon across UAE business cycles.
- Subscription-Based:Recurring annual or monthly fees align vendor revenue with customer operational continuity. Dubai SME corridors favor this model for predictable budgeting against seasonal revenue fluctuations. Volume concentrates here due to vendor preference for recurring revenue visibility.
- Tiered Pricing:Feature-banded packages separate basic bookkeeping from advanced analytics and multi-currency support. Abu Dhabi mid-market enterprises self-select into appropriate tiers without sales intervention. This structure reduces procurement friction for procurement teams with limited technical evaluation capacity.
- Pay-As-You-Go:Transaction-volume billing suits project-based consultancies with irregular invoice cycles.
- One-Time License:Perpetual purchase with maintenance contracts persists among legacy-dependent public sector entities.
Subscription models capture dominant wallet share; tiered pricing climbs fastest among self-serve digital buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's free zones concentrate cloud accounting demand through tax incentives and digitization mandates that accelerate SME software procurement. Federal regulations cascade across emirate-level implementations.
Dubai
Dubai Multi Commodities Centre and Dubai Internet City host fintech clusters driving automated invoicing adoption. UAE Central Bank open banking directives force real-time reconciliation tool deployment. Dubai International Financial Centre institutions pilot blockchain-based audit trails for cross-border trade finance.
Abu Dhabi
Sovereign wealth-linked conglomerates demand multi-entity consolidation tools for complex holding structures. SAMR cloud data residency rules mandate compliant hosting infrastructure for financial data. Abu Dhabi Global Market anchors large-enterprise procurement with Arabic-localized implementation support.
Sharjah
Industrial zones and logistics corridors generate payroll processing demand from multi-national workforces. Federal Tax Authority real-time reporting requirements eliminate paper-based alternatives. Sharjah Research Technology and Innovation Park incubates mid-market enterprises seeking modular best-of-breed solutions.
Ras Al Khaimah
Underpenetrated SME corridors present greenfield acquisition targets for vendors with Arabic-language interfaces. MOHAP health-sector digital transformation mandates intersect with financial reporting needs. Ras Al Khaimah Economic Zone attracts cost-conscious enterprises escaping Dubai-Abu Dhabi pricing premiums.
Northern Emirates
Ajman and Fujairah construction sectors drive WPS-compliant payroll automation for transient labor pools. UAE Labor Law gratuity accrual calculations elevate payroll modules to mission-critical status. Fujairah's port and logistics clusters require basic bookkeeping solutions with upgrade pathways toward enterprise scalability.
United Arab Emirates (UAE) Cloud Accounting Software Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across deployment architectures and customer scales. The vendor base separates into three tiers: global ERP incumbents with multi-entity tools, regional specialists with VAT compliance engines, and API-native challengers unbundling core functions. Competitive moves concentrate on M&A for compliance certification and strategic partnerships with UAE-based implementation partners.
Within the global ERP tier, Oracle Corporation anchors large-enterprise positioning through sovereign wealth fund relationships. Sage Group plc exemplifies the regional specialist archetype with localized Federal Tax Authority compliance engines. Intuit Inc. occupies the SME-focused position through QuickBooks ecosystem penetration in Dubai free zones.
| Leading Market Players |
|---|
| Intuit Inc. |
| Sage Group plc |
| Oracle Corporation |
| Odoo S.A. |
| Xero Limited |
| Microsoft Dynamics 365 |
| Zoho Books |
| Wafeq |
| Tally Solutions |
| Others |
Pricing and Supply Chain Analysis
Abu Dhabi sovereign wealth-linked conglomerates anchor pricing power through multi-year subscription commitments that subsidize SaaS onboarding costs for Dubai free zone SMEs. Federal Tax Authority certification timelines compress vendor margins while elevating buyer willingness to pay for pre-approved modules.
Pricing Analysis
Short lead-time premiums apply to Federal Tax Authority-certified deployments with sub-90-day implementation windows, while spot inventory discounts emerge for non-compliant legacy migration tools. Subscription-based recurring fees dominate wallet share, with price differentiation hinging on WPS payroll integration depth and Arabic localization completeness. Pricing pressure stems from SAMR compliance infrastructure investments that vendors cannot fully pass through to mid-market buyers. Dubai technology free zone startups exhibit highest price sensitivity; Abu Dhabi holding companies with sovereign fund linkages demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with UAE-based implementation partners holding Federal Tax Authority certification, creating bottleneck risk during deployment surges. Cloud infrastructure supply concentrates in UAE, Saudi Arabia, and India for compliant hosting nodes, while API middleware components draw from Ireland, Singapore, and the United States. Supply chain risk centers on cross-border data flow restrictions fragmenting multi-tenant architecture development. Distribution runs through Dubai-based systems integrators with SAMR audit credentials, channeling software licenses to emirate-level procurement clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
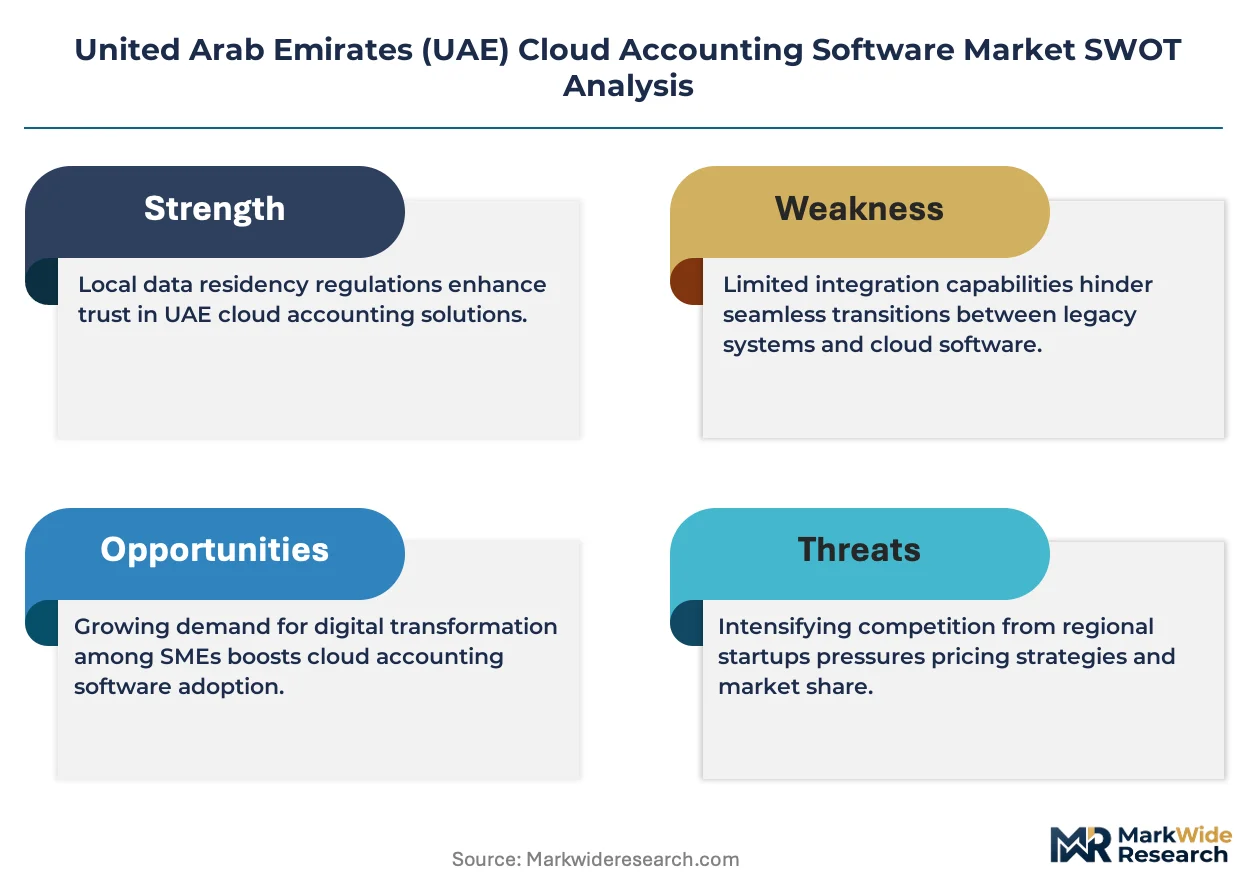
This market reads as a cost-of-compliance story where SAMR cloud data residency rules and Federal Tax Authority certification requirements erect barrier-to-entry moats favoring vendors with sunk localization investments.
For Market Incumbents: Deepen vertical integration into UAE-based implementation partner networks to capture professional services margin pools eroded by certification complexity. Fortify multi-entity consolidation tools against API-native challengers unbundling core accounting functions. Priority lever: acquire Federal Tax Authority pre-certified modules to compress rival deployment timelines. For New Entrants and Emerging Players: Launch via modular best-of-breed positioning targeting Ras Al Khaimah and Sharjah SME corridors outside Dubai-Abu Dhabi saturation. White-space concentration sits with Arabic-localized payroll automation for industrial zone workforces. Go-to-market angle: WPS-compliant rapid deployment with gratuity accrual calculators pre-configured to UAE Labor Law. For Investors and Strategic Acquirers: The window for entry favors vendors with existing SAMR-compliant hosting infrastructure and Federal Tax Authority module approvals. Long-term viability hinges on regulatory certification velocity rather than feature innovation alone. Acquisition target archetype: regional specialists with VAT compliance engines and sovereign wealth fund relationships. Signal to watch: MOHAP health-sector interoperability mandates expanding financial software procurement beyond traditional buyers.| Strategic Initiative | Industry Significance |
|---|---|
| Federal Tax Authority Certification Investment | Pre-approval compresses rival deployment timelines and anchors premium pricing power. |
| SAMR-Compliant Hosting Infrastructure Buildout | Data residency adherence unlocks Abu Dhabi sovereign wealth-linked conglomerate procurement. |
| API-Native Modular Unbundling | Microservices architecture captures Dubai fintech cluster demand for interoperability-first solutions. |
| Arabic Localization and WPS Integration | UAE Labor Law compliance elevates payroll modules to mission-critical status for construction and logistics verticals. |
| Strategic Partnership with UAE Systems Integrators | Certified implementation capacity channels software licenses through Dubai-Abu Dhabi procurement clusters. |
Research Methodology
Independent corroboration across cloud software vendor executives, Federal Tax Authority compliance officers, and Dubai free zone IT procurement leads underwrites the qualitative findings. Primary interviews with SAMR audit specialists, UAE-based systems integrators, and Abu Dhabi sovereign wealth fund technology advisors combined with secondary validation from SEC filings of listed software vendors, UAE Central Bank open banking directives, and Federal Tax Authority regulatory updates. Bottom-up deployment volume estimates and top-down market sizing triangulate to bound forecast uncertainty.
Comparable-period anchoring to historical SaaS adoption curves in GCC financial centers structured the projection horizon. Segmentation dimensions modeled span deployment architecture, organization scale, service type module, and emirate-level regulatory adoption pattern. CAGRs derive from vendor revenue disclosures, customer procurement cycle analysis, and compliance mandate implementation timelines. Industry-specific inputs include SAMR cloud data classification rule evolution and Federal Tax Authority real-time reporting mandate penetration rates.
Regulatory enforcement variance, certification timeline delays, and sovereign wealth fund technology procurement shifts are the dominant revision risks. Forecasts reflect assumptions around compliance mandate adherence velocity and cross-emirate data localization interpretation consistency. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Europe Pharmacy POS Software Market
Software & Services
Global Cloud Enterprise Resource Planning Market
Software & Services
Global Legal Case Management Software Market
Software & Services
Virtual Client Computing Software Market
Software & Services
Over the Air (OTA) Updates Market
Software & Services
Mobile Enterprise Application Development Platform Market
Software & Services
Global CMDB Software Market
Software & Services
Asia Pacific Human Capital Management Software (HCM) Market
Software & Services
Waterway Transportation Software Solutions Market
Software & Services
Germany HR Payroll Software Market
Software & Services
Europe Servicenow Store Apps Market
Software & Services
Enterprise Content Management Software Market
Software & Services
Braking Systems Software Market
Software & Services
Test Automation Market
Software & Services
Global Furniture Manufacturing Software Market
Software & Services
Global Application Platform Market