
 Expense Management Software Market | 2026-2036
Expense Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Expense Management Software Market Analysis
API-first architecture is recalibrating how enterprises evaluate expense platforms against legacy ERP modules. SAP Concur leverages deep ERP integration to sustain dominance among Fortune 500 accounts. Brex competes on corporate card-linked spend automation, while Ramp anchors its position with software-centric procurement controls for mid-market technology firms.
Expense management software automates the capture, validation, reimbursement, and analysis of business expenditures through rule-based workflows and real-time policy enforcement. Cloud-based deployment leads the market as enterprises prioritize remote accessibility and reduced infrastructure overhead. Expense reporting solutions dominate solution-level revenue, though invoice management is gaining traction among organizations seeking unified accounts-payable automation. API integration levels are expanding fastest as finance teams demand seamless data flow into ERP, CRM, and payroll systems.
SOX compliance requirements in the United States, GDPR data residency rules in Europe, and India's RBI guidelines on digital payment records are shaping product roadmaps and market access conditions. ISO 27001 certification has become a baseline procurement filter for enterprise buyers evaluating vendor security postures. Stakeholders must weigh interoperability investments against the risk of vendor lock-in as platform consolidation accelerates.
Market Dynamics
API-first architecture is dismantling the integration moats that once protected legacy ERP modules, forcing vendors to compete on data fluidity rather than proprietary lock-in. Finance teams now evaluate platforms by their webhook density and schema flexibility, not by feature checklists alone.
Growth Catalysts
- SOX Compliance Mandates:United States public companies face auditor scrutiny over expense trail integrity. Automated policy enforcement and immutable audit logs reduce control deficiency findings.
- Remote Workforce Normalization:Distributed teams require mobile-first capture and real-time reimbursement workflows. Cloud-native platforms displace paper-based processes that collapsed under hybrid work models.
- Real-Time Payment Rails:India's UPI infrastructure and Brazil's Pix network enable instant employee reimbursement. Finance teams in these markets bypass traditional ACH latency that previously delayed settlement.
Market Restraints
- Data Residency Friction:GDPR's territorial processing requirements force vendors to maintain EU-isolated infrastructure. This fragments development roadmaps and elevates operational overhead.
- Banking Partner Concentration:Corporate card issuance depends on a narrow tier of licensed issuers. Fintech platforms face margin compression when negotiating interchange revenue splits.
- Legacy ERP Entrenchment:SAP and Oracle installations carry decade-long depreciation schedules. Finance leaders delay SaaS migration to avoid write-off penalties.
Strategic Opportunities
- Embedded Finance Convergence:Expense platforms integrate lending, insurance, and FX hedging through banking-as-a-service APIs. This transforms software vendors into full-stack financial operating systems.
- Mid-Market Underservice:Companies with 200-2,000 employees lack dedicated procurement teams. Automated spend controls address compliance gaps without headcount expansion.
- CSRD Reporting Alignment:Europe's Corporate Sustainability Reporting Directive mandates granular Scope 3 emissions tracking. Expense data becomes foundational for supplier carbon accounting.
Industry Challenges
- ISO 27001 Certification Bottlenecks:Enterprise procurement requires current security attestations. Vendors face 6-12 month audit cycles that stall deal velocity.
- Interoperability Tax:Each ERP connector demands bespoke schema mapping. Engineering teams divert resources from core product development to integration maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Expense Management Software Market |
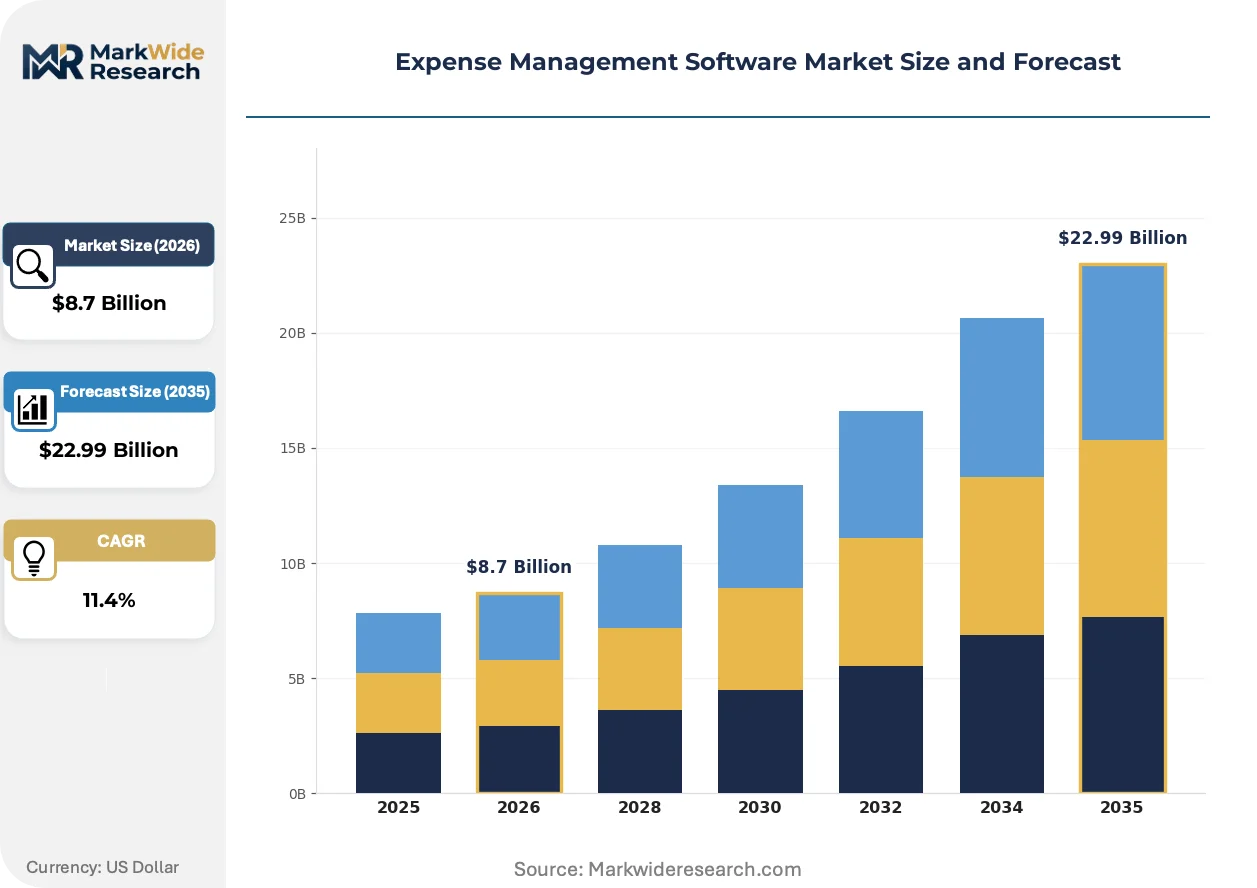
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Mobile End User: Corporates, Small Enterprises, Non-Profits, Government Agencies Solution: Expense Reporting, Invoice Management, Travel Management, Budgeting Integration Level: API, ERP, CRM, Payroll |
| Companies Covered | SAP Concur, Coupa Software, Expensify, Zoho Corporation, Oracle NetSuite, Brex, Ramp, Navan, Spendesk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Expense Management Software Market Emerging Trajectories
Machine learning is compressing the exception-handling burden that previously consumed finance operations headcount. Vendors now compete on model accuracy in receipt parsing and policy violation prediction.
Blockchain-based receipt verification is decentralizing audit trail custody across distributed ledger networks. Large enterprises with multi-jurisdiction operations pilot these systems to eliminate notarization costs. The technology removes intermediary reliance in cross-border expense validation, collapsing reconciliation timelines from weeks to hours.
GDPR's data portability mandates are forcing vendors to implement standardized export formats. European finance teams now demand machine-readable transaction histories that migrate across platforms. This regulatory pressure erodes switching costs and intensifies churn risk for incumbent providers.
Subscription fatigue among software buyers is shortening evaluation cycles and compressing pilot-to-contract timelines. Mid-market technology firms now demand 30-day proof-of-concept deployments with pre-built ERP connectors. United States SaaS procurement teams prioritize time-to-value metrics over feature depth in vendor selection.
Expense Management Software Market Segmentation
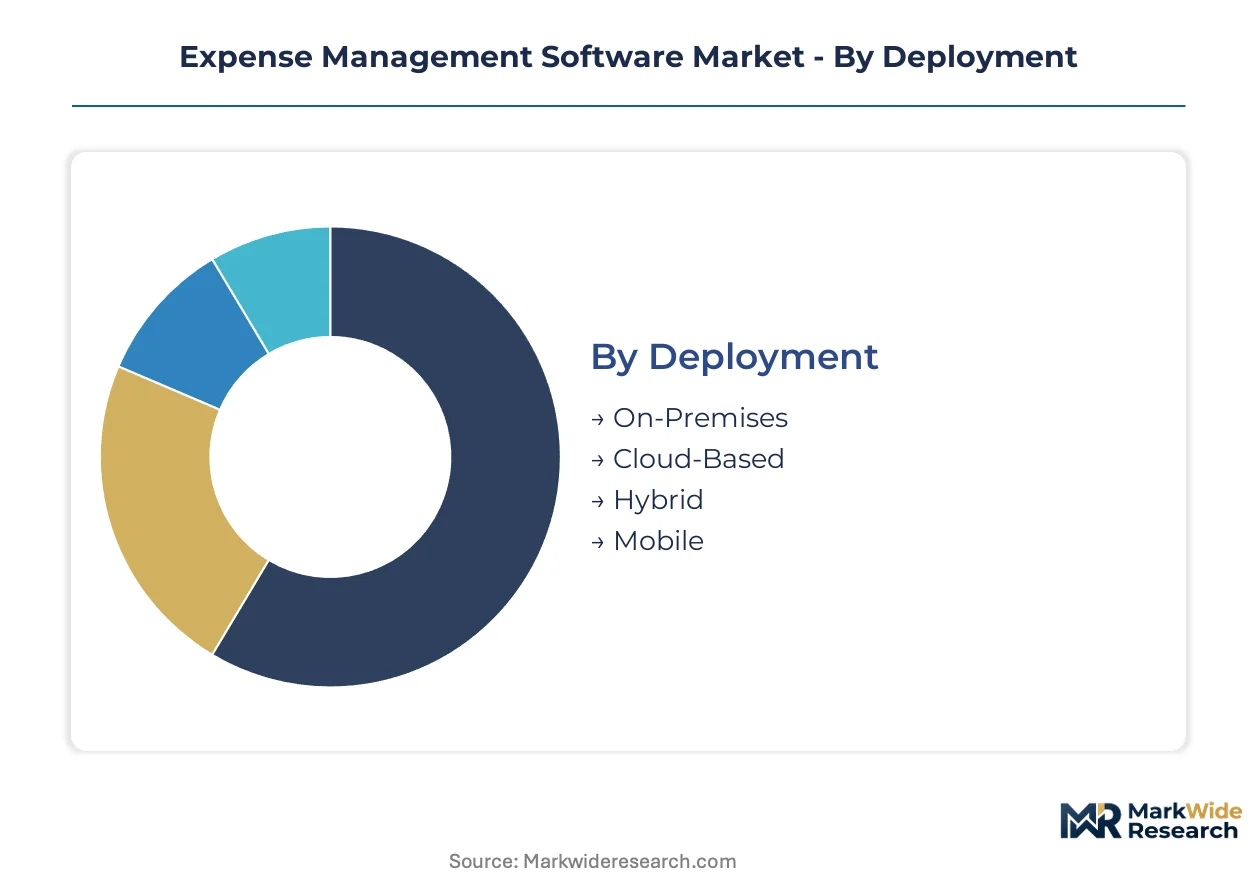
Segmentation in expense management software reveals how deployment preferences, user complexity, and integration requirements fragment procurement patterns. Finance teams select configurations based on audit trail mandates, workforce distribution, and existing ERP investments.
Deployment:
ISO 27001 certification burdens vary sharply across deployment modes, with cloud and hybrid configurations demanding continuous compliance attestations while on-premises installations shift liability to internal IT teams.
- Cloud-Based:Multi-tenant SaaS architectures eliminate infrastructure ownership while delivering automatic policy updates and mobile accessibility. United States enterprises with distributed workforces prioritize this mode to satisfy SOX auditor demands for immutable audit logs without capital expenditure. Remote workforce normalization accelerates displacement of legacy installations.
- On-Premises:Single-tenant deployments behind corporate firewalls retain full data custody for defense contractors and regulated financial institutions. European organizations with strict GDPR territorial processing requirements maintain this mode despite higher total cost of ownership. Depreciation schedules and sunk infrastructure costs delay migration timelines.
- Hybrid:Split architectures isolate sensitive transaction data on-premises while routing routine workflows through cloud interfaces. Mid-market manufacturing firms with mixed compliance obligations adopt this compromise to balance accessibility with control.
- Mobile:Native iOS and Android applications enable receipt capture, mileage tracking, and approval routing without desktop dependency. Field sales organizations and construction supervisors require offline functionality with synchronization upon network restoration.
Cloud-Based sits at the top of the volume ranking, with Mobile climbing the fastest as frontline workforce digitization accelerates.
End User:
Procurement complexity scales with organizational size, separating self-serve implementations from enterprise sales cycles requiring procurement, legal, and information security sign-offs.
- Corporates:Multi-entity conglomerates with 10,000-plus employees demand role-based access controls, multi-currency support, and subsidiary-level policy differentiation. Fortune 500 procurement teams evaluate vendors through formal RFP processes with dedicated evaluation committees.
- Small Enterprises:Companies with under 200 employees prioritize rapid deployment and pre-configured workflows over customization. QuickBooks and Xero integration availability often determines vendor selection in this price-sensitive segment.
- Non-Profits:Grant-funded organizations require fund-specific expense allocation and donor-restricted budget enforcement. Specialized compliance reporting for 501(c)(3) entities and government grantors shapes product requirements.
- Government Agencies:Federal, state, and municipal entities mandate FedRAMP or equivalent security authorizations with classified data handling protocols. Procurement runs through formal government contracting vehicles with extended sales cycles.
Corporates command the highest absolute spending, though Small Enterprises are expanding most quickly as vertical SaaS vendors target previously underserved mid-market accounts.
Solution:
Feature bundling decisions reflect finance team maturity, with sophisticated organizations unifying previously siloed spend management functions.
- Expense Reporting:Core functionality encompassing receipt capture, policy enforcement, approval routing, and reimbursement processing. Corporate card integration and automated general ledger coding reduce manual reconciliation burden for high-transaction-volume organizations.
- Invoice Management:Accounts-payable automation with purchase order matching, three-way validation, and vendor payment scheduling. Organizations seeking unified procure-to-pay workflows adopt this module to eliminate duplicate data entry.
- Travel Management:Booking integration, itinerary management, and negotiated rate compliance for business travel programs. TMC partnerships and direct airline/hotel API connections differentiate vendor capabilities.
- Budgeting:Real-time spend tracking against departmental forecasts with variance alerts and reallocation workflows. Rolling forecast capabilities and scenario modeling attract organizations implementing zero-based budgeting methodologies.
Expense Reporting maintains dominant share, while Invoice Management gains ground fastest as finance leaders consolidate vendor relationships.
Integration Level:
Engineering resource allocation for connector maintenance directly impacts vendor margin structure and product velocity.
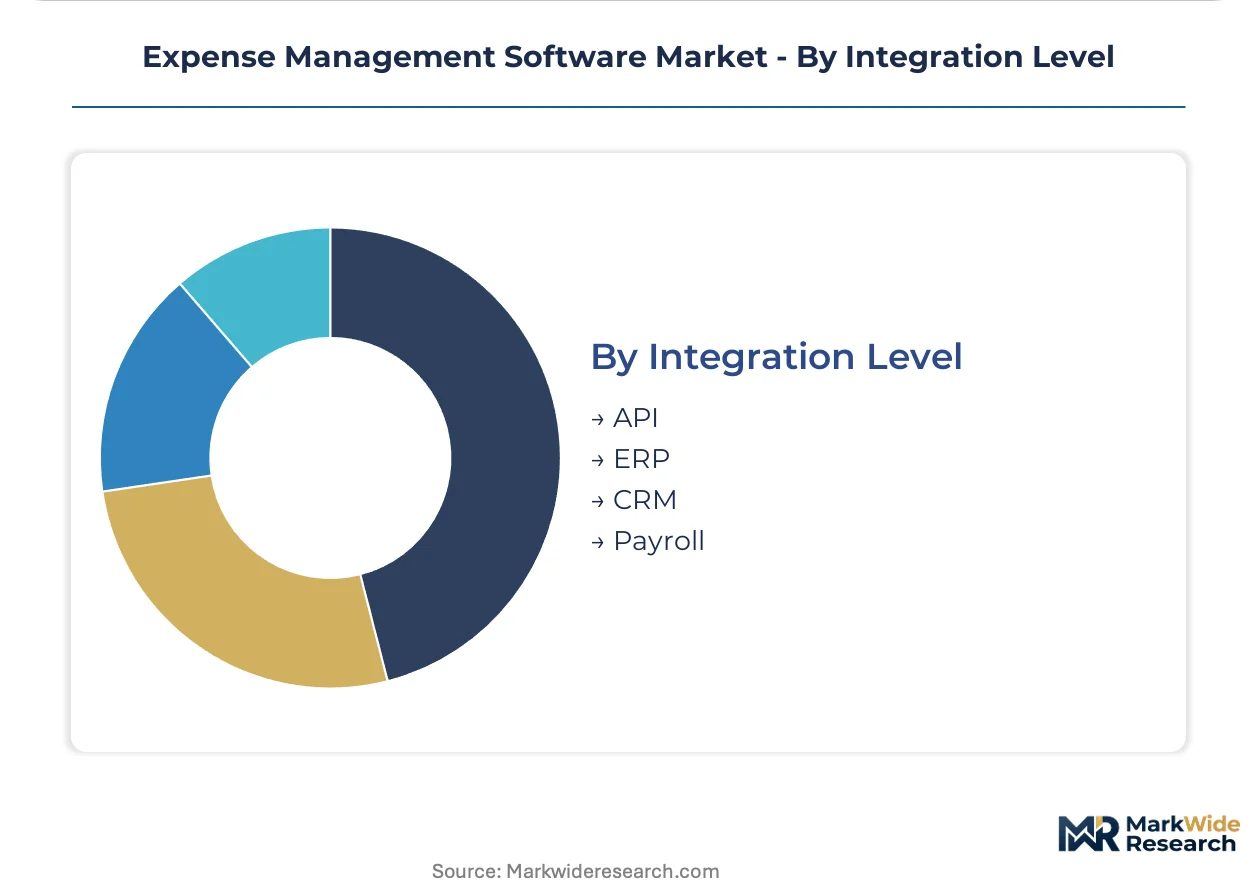
- API:Webhook-based real-time data exchange enabling custom workflow automation and third-party application embedding. Technology firms with internal development capacity favor this flexibility for bespoke integrations.
- ERP:Pre-built connectors for SAP, Oracle, NetSuite, and Microsoft Dynamics with standardized chart-of-accounts mapping. Manufacturing and retail enterprises with complex inventory costing requirements prioritize deep ERP synchronization.
- CRM:Salesforce and HubSpot integrations linking customer-facing spend to opportunity records and account profitability analysis. Professional services firms with project-based billing models require this connectivity.
- Payroll:Direct deposit and expense reimbursement synchronization with ADP, Workday, and Paylocity systems. Organizations with high employee turnover and frequent reimbursement cycles value automated payroll posting.
ERP connectors handle the greatest transaction volume, though API adoption is accelerating most steeply as platform ecosystems expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley enterprise SaaS procurement clusters anchor global expense management software deployment velocity, with finance technology adoption radiating from North American headquarters operations into distributed regional implementations.
United States
Fortune 500 corporate card programs and SOX compliance mandates drive replacement of legacy on-premises systems. SEC auditor scrutiny over expense trail integrity accelerates automated policy enforcement procurement. New York financial services and San Francisco technology headquarters concentrate vendor sales activity.
Germany
Mittelstand manufacturing firms demand ERP-native expense modules with deep SAP integration. GDPR territorial processing requirements sustain hybrid deployment preferences despite cloud migration pressure. Munich and Stuttgart industrial clusters prioritize on-premises data custody for supplier payment workflows.
United Kingdom
Professional services firms with project-based billing models require CRM-linked spend tracking capabilities. FCA regulatory expectations for financial controls documentation shape procurement criteria. London's consulting and legal services density supports premium-tier platform adoption.
India
UPI real-time payment infrastructure enables instant employee reimbursement bypassing traditional ACH latency. RBI guidelines on digital payment records mandate granular transaction documentation. Bangalore and Hyderabad technology campuses anchor mid-market SaaS procurement growth.
Japan
Keiretsu corporate networks demand multi-entity expense consolidation with subsidiary-level policy differentiation. METI digital transformation incentives accelerate paper-based process displacement. Tokyo headquarters operations maintain conservative deployment timelines despite cloud-native platform availability.
Expense Management Software Market Vendor Landscape
API-first integration investments dominate the current landscape as vendors dismantle legacy ERP moats through webhook density and schema flexibility. The vendor base concentrates around three strategic tiers: enterprise ERP-integrated suites, corporate card-linked fintech platforms, and vertical SaaS specialists. Consolidation pressures intensify as platform ecosystems expand, with M&A activity and strategic partnership formation representing the primary competitive vectors for capability expansion.
Within the enterprise-integrated tier, SAP Concur and Oracle NetSuite exemplify deep ERP synchronization strategies that sustain Fortune 500 retention. Brex occupies a position among card-anchored fintech disruptors competing on spend automation rather than software licensing alone. These archetypes represent divergent bets on whether finance teams prioritize data fluidity or proprietary ecosystem lock-in as the decisive procurement criterion.
| Leading Market Players |
|---|
| SAP Concur |
| Coupa Software |
| Expensify |
| Zoho Corporation |
| Oracle NetSuite |
| Brex |
| Ramp |
| Navan |
| Spendesk |
| Others |
Supply Flow & Price Mechanics
Fortune 500 finance procurement committees concentrate purchasing power across multi-year SaaS contracts, anchoring the dominant subscription-tiered pricing model with annual pre-payment discounts and seat-based scaling.
Pricing Analysis
Input-cost pass-through from cloud infrastructure providers and banking-as-a-service partners compresses margins for mid-tier vendors. Pricing stratifies across enterprise, professional, and self-serve tiers with differentiation driven by API call volume allowances and ISO 27001 certification status. Cost compression in the self-serve tier intensifies as freemium acquisition costs rise. Small enterprises exhibit highest price sensitivity, while Fortune 500 accounts prioritize integration depth over per-seat economics.
Supply Chain Analysis
Freight and data transit costs factor minimally as software delivery runs through cloud regions operated by hyperscale providers in the United States, Ireland, and Singapore. The supply chain draws from banking partners in the United States, card networks in Europe, and engineering talent pools in India and Poland. Single-source vulnerability concentrates in corporate card issuance partnerships with licensed banking entities. Distribution runs through direct enterprise sales teams, self-serve web platforms, and systems integrator channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as SOX compliance mandates perpetuate replacement cycles for legacy on-premises installations across United States public companies.
For Market Incumbents: Deepen ERP connector density to defend against API-first challengers dismantling integration moats through webhook architectures. Prioritize SAP and Oracle NetSuite synchronization investments. Fortify ISO 27001 certification maintenance to sustain enterprise procurement filter compliance. For New Entrants and Emerging Players: Launch via product-led growth motions targeting mid-market technology firms with 200-2,000 employees lacking dedicated procurement teams. Penetrate the underserviced manufacturing vertical with pre-built three-way matching workflows. Anchor go-to-market strategy on 30-day proof-of-value deployments with instant UPI reimbursement capabilities. For Investors and Strategic Acquirers: Corporate card issuers and vertical SaaS consolidators represent the most active acquirer categories in this space. Position holdings for five-to-ten year holding periods as platform consolidation accelerates. Monitor API-first vendors achieving webhook density parity with legacy ERP modules as the inflection signal for competitive equilibrium shifts.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Webhook density expansion dismantles legacy ERP integration moats for SAP Concur and Oracle NetSuite accounts. |
| Embedded Finance Convergence | Banking-as-a-service APIs transform expense platforms into full-stack financial operating systems with lending and FX hedging. |
| Mid-Market Vertical Expansion | Pre-built manufacturing connectors address compliance gaps for 200-2,000 employee firms without procurement headcount. |
| CSRD Reporting Alignment | Scope 3 emissions tracking modules satisfy Europe's Corporate Sustainability Reporting Directive for supplier carbon accounting. |
| Real-Time Payment Infrastructure | UPI and Pix network integration enables instant reimbursement bypassing ACH latency in India and Brazil. |
Methodological Framework
Bottom-up corporate deployment modeling reconciled against top-down SaaS vendor revenue tracking forms the analytical core. Primary interviews with CFOs, IT procurement officers, platform engineers, and integration specialists combine with secondary validation from SEC filings, App Annie mobility data, hyperscaler capex disclosures, and ISO certification registries. Triangulation across stakeholder perspectives and data sources ensures methodological rigor.
Input-output matrices map deployment mode adoption rates against end-user segmentation dimensions including organization size, vertical industry, and integration complexity across the projection horizon. CAGRs derive from regression analysis of historical SaaS procurement velocity and policy enforcement automation penetration. Forecast inputs incorporate SOX compliance audit deficiency rates and remote workforce normalization trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory fragmentation scenarios or banking partner consolidation shocks. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Towing Software Market
Software & Services
Entity Management Software Market
Software & Services
Camera Tracking Software Market
Software & Services
Europe Enterprise Resource Planning (ERP) Software Market
Software & Services
North America Automotive Software Market
Software & Services
Web Scraping Software Market
Software & Services
Russian IT Software and Services Market
Software & Services
Global Application Release Automation Market
Software & Services
Hadoop Market
Software & Services
Global Voting Software Market
Software & Services
Global Data Discovery Software Market
Software & Services
Global Retail Execution Software Market
Software & Services
Global Mobile User Interface Services Market
Software & Services
Tech Support Services Market
Software & Services
Apache Spark Market
Software & Services
Programming Language Market