
 Europe Saas-Based SCM Market | 2026-2036
Europe Saas-Based SCM Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Saas-Based SCM Market Insights
Direct software distribution between SaaS vendors and large European manufacturers is rewriting how supply chain technology reaches end users. SAP SE leverages its deep ERP integration to anchor procurement workflows inside German automotive and chemical plants. Oracle Corporation competes through database-layer connectivity that sustains real-time visibility across multi-tier supplier networks. Manhattan Associates specializes in warehouse-centric execution systems that dominate third-party logistics operators in the Netherlands and Belgium.
Europe SaaS-Based SCM encompasses cloud-delivered applications that orchestrate procurement, inventory, transportation, and supplier coordination through multi-tenant architectures with API-first integration protocols and sub-second latency requirements. These platforms centralize demand signals, inventory positions, and logistics events to reduce working capital buffers and shorten order-to-cash cycles. Public Cloud deployments now capture the majority of new subscriptions as manufacturers prioritize elastic compute for seasonal demand spikes. Among end user types, E-commerce platforms represent the fastest-expanding category as fulfillment networks require continuous reconfiguration across borders. Supplier Collaboration functionality commands premium pricing due to its direct impact on procurement cost reduction and risk mitigation.
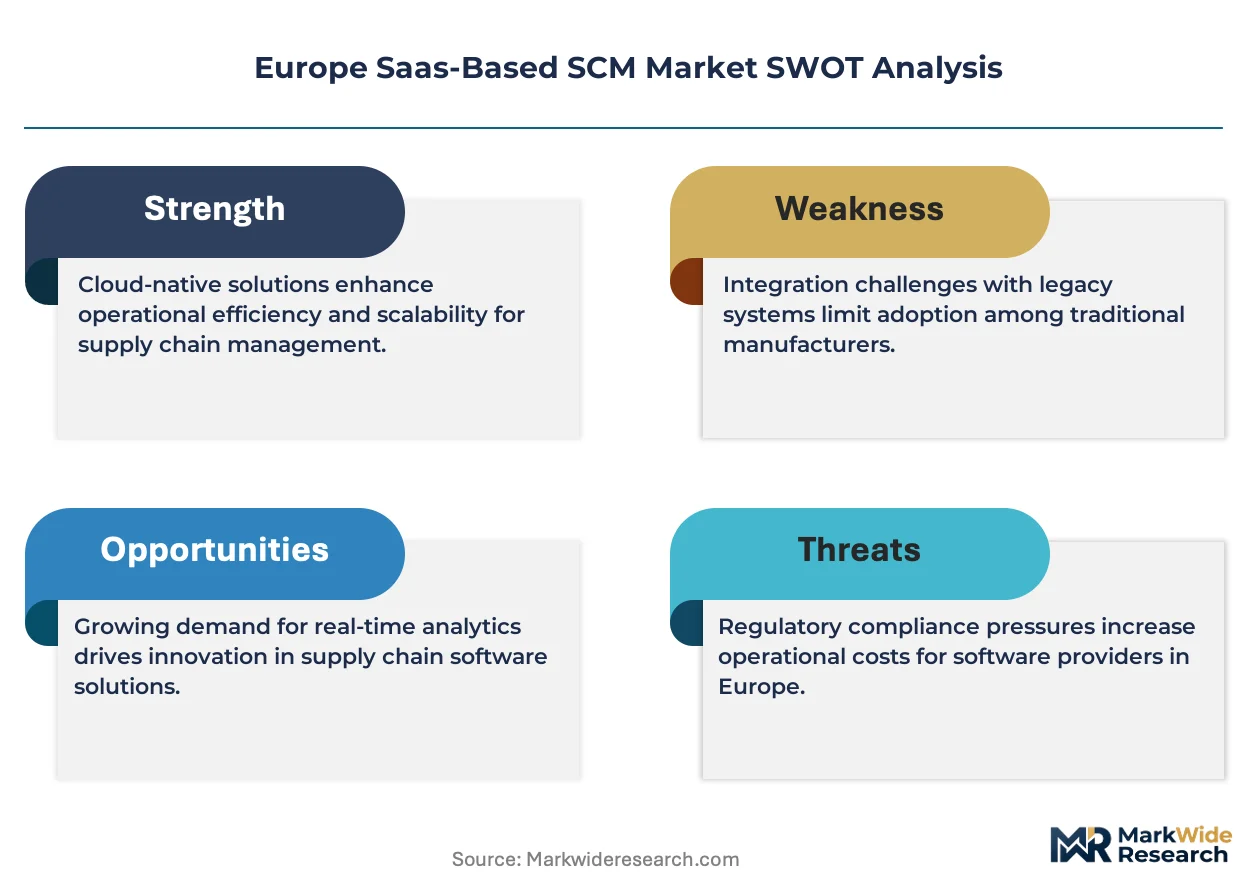
GDPR data residency rules, the EU AI Act's risk classification framework, and CSRD supply chain due diligence requirements collectively shape product roadmaps and vendor qualification processes across the continent. EMA documentation standards and REACH chemical tracking obligations further extend compliance functionality into pharmaceutical and industrial supply chains. Stakeholders must monitor how the EU Green Deal's embedded carbon reporting mandates will force SCM platforms to integrate emissions data at the purchase-order line level.
Market Dynamics
The EU AI Act's risk classification framework and CSRD supply chain due diligence mandates are forcing SaaS vendors to embed compliance logic directly into procurement workflows, compressing vendor qualification timelines and reshaping competitive differentiation.
Growth Catalysts
- CSRD Reporting Mandates:Large European manufacturers must disclose Scope 3 emissions across supplier tiers, driving demand for cloud-native platforms that automate carbon data collection at the purchase-order line level.
- Germany's Mittelstand Digitization:Mid-sized industrial firms in Baden-Württemberg and Bavaria are consolidating fragmented supplier portals into unified SaaS environments to reduce working capital buffers.
- API-First Integration Protocols:Real-time data exchange between ERP systems and logistics networks now operates at sub-second latency, enabling continuous inventory rebalancing across multi-country fulfillment networks.
Market Restraints
- GDPR Data Residency Costs:Strict localization requirements force vendors to maintain separate cloud instances per member state, inflating infrastructure overhead and complicating multi-tenant architectures.
- Legacy ERP Lock-In:Deep integration with on-premise SAP deployments creates switching friction that extends sales cycles and inflates implementation consulting fees.
- REACH Chemical Tracking Complexity:Pharmaceutical and industrial supply chains face escalating documentation burdens that strain platform configurability and user adoption rates.
Strategic Opportunities
- Poland's Manufacturing Corridor:Underpenetrated automotive supplier networks in Silesia and Greater Poland present first-mover advantages for warehouse-centric execution platforms.
- EU Green Deal Embedded Carbon Reporting:Upcoming mandates will require emissions tracking at the SKU level, creating premium pricing potential for compliance-augmented modules.
- Edge-to-Cloud Convergence:Combining IoT sensor streams with centralized analytics enables predictive inventory positioning for seasonal demand spikes in Nordic markets.
Industry Challenges
- SCM-DevOps Talent Scarcity:European firms struggle to hire engineers who bridge supply chain domain expertise with cloud-native architecture skills, delaying platform rollouts.
- Multi-Tier Supplier Onboarding:Extending SaaS connectivity beyond direct suppliers to third and fourth tiers requires contractual renegotiation that stretches implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Saas-Based SCM Market |
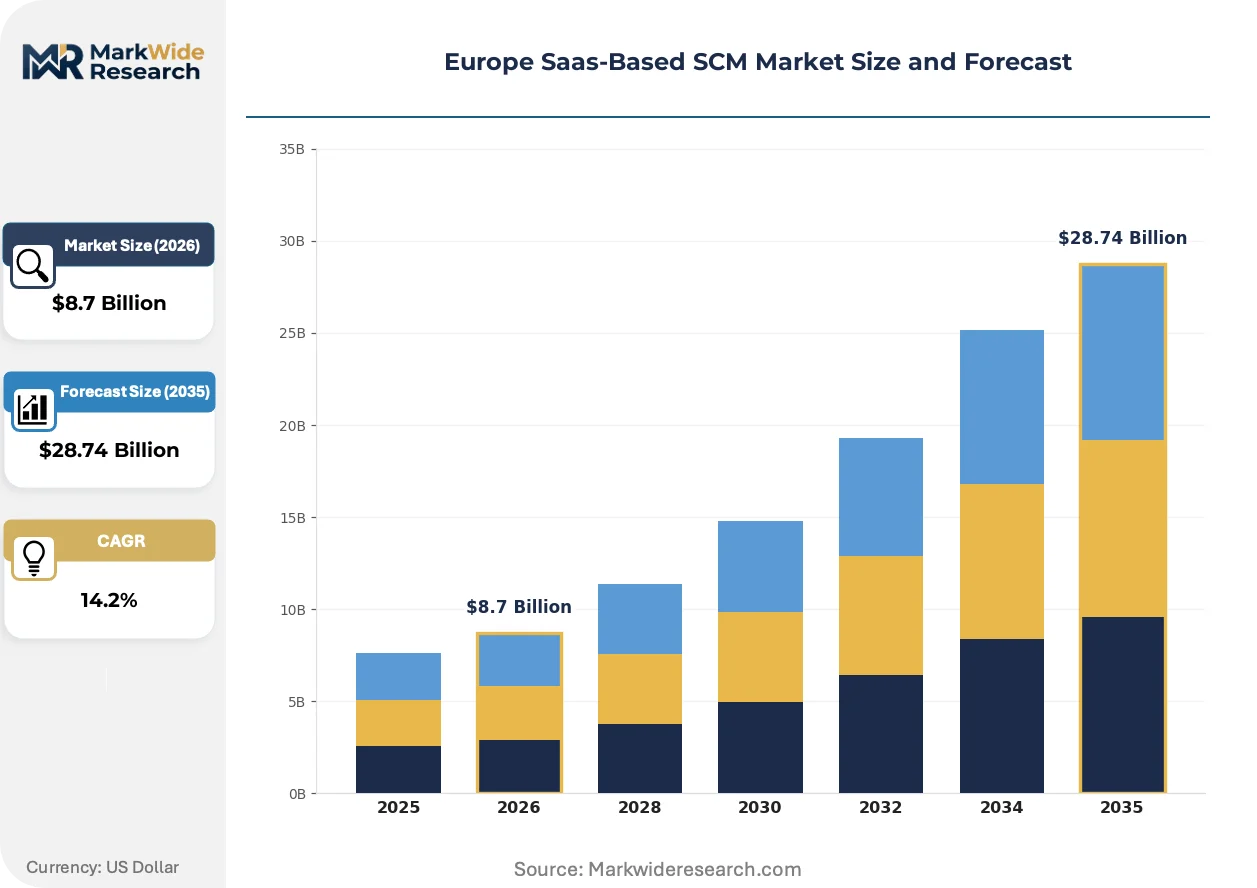
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User Type: Manufacturers, Distributors, Retailers, E-commerce Functionality: Inventory Management, Order Processing, Supplier Collaboration, Demand Planning Pricing Model: Subscription-Based, Pay-As-You-Go, Freemium, License Fee |
| Companies Covered | SAP SE, Oracle Corporation, IBM Corporation, Manhattan Associates, Korber AG, Kinaxis, Logility, Descartes Systems Group, Blue Yonder, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Saas-Based SCM Market Trends and Innovations
Cloud-native supply chain platforms are absorbing AI-driven forecasting and blockchain-based provenance tracking into unified architectures, compressing the gap between planning and execution layers.
Digital twin technology is hybridizing physical and virtual supply chain representations. German automotive manufacturers deploy these replicas to simulate supplier disruptions before they propagate. The technology is compressing scenario planning cycles from weeks to hours.
REACH documentation standards and EMA batch tracking requirements are extending compliance functionality into pharmaceutical supply chains. Vendors must now embed chemical substance databases and serialization protocols directly into core platforms. French and Italian drug manufacturers face the steepest adaptation curves.
Buying committees at European manufacturers now mandate carbon-adjusted total cost of ownership metrics in vendor selection. Procurement teams weight emissions data alongside price and service levels. Dutch chemical distributors and Belgian third-party logistics operators have moved fastest to align supplier scorecards with EU Green Deal benchmarks.
Europe Saas-Based SCM Market Segmentation
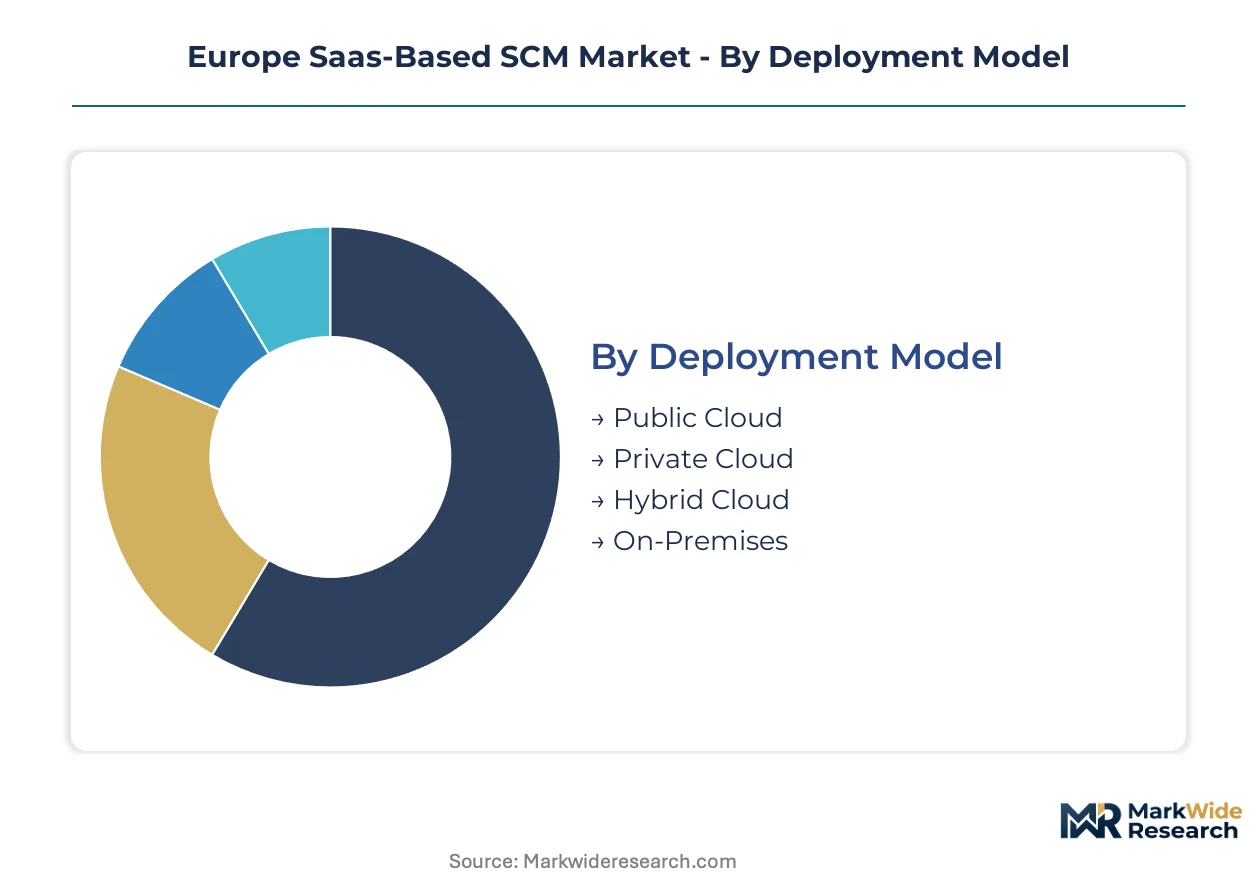
European SaaS SCM segmentation reveals how deployment architecture, end-user complexity, and functional depth create distinct commercial battlegrounds. Each dimension carries unique compliance burdens and integration requirements that reshape vendor positioning across the continent.
Deployment Model:
Use-case spectrum spans elastic seasonal scaling to sovereign data control.
- Public Cloud:Multi-tenant architectures deliver elastic compute for automotive manufacturers managing seasonal demand spikes. German automotive OEMs in Stuttgart and Munich prioritize this model for supplier network orchestration, though GDPR data residency rules force regional instance fragmentation.
- Private Cloud:Single-tenant environments isolate pharmaceutical batch data for EMA compliance. French drug manufacturers in the Île-de-France cluster favor this deployment for REACH documentation workflows, accepting higher infrastructure overhead for audit trail sovereignty.
- Hybrid Cloud:Split architectures run sensitive procurement data on-premises while pushing analytics to public infrastructure. Dutch chemical distributors deploy this model to balance CSRD carbon reporting with legacy ERP connectivity.
- On-Premises:Localized installations persist in Bavarian Mittelstand firms with deep SAP integration and limited IT modernization budgets.
Established volume favors Public Cloud; emerging adoption favors Hybrid Cloud.
End User Type:
Cost tier differentiation separates enterprise complexity from fulfillment velocity.
- E-commerce:Continuous network reconfiguration demands sub-second latency for cross-border fulfillment. Nordic platforms and Benelux marketplaces drive this segment, prioritizing warehouse-centric execution systems that compress order-to-cash cycles.
- Manufacturers:Multi-tier supplier coordination requires API-first integration at the purchase-order line level. German industrial firms in Baden-Württemberg dominate demand, embedding EU AI Act risk classification into procurement workflows.
- Distributors:Inventory positioning across heterogeneous supplier bases demands demand signal centralization. Belgian third-party logistics operators represent concentrated demand for carbon-adjusted total cost of ownership metrics.
- Retailers:Seasonal assortment planning drives need for predictive inventory positioning, with French hypermarket chains adopting digital twin simulation for scenario compression.
Volume concentration sits with Manufacturers; steepest expansion trajectory belongs to E-commerce.
Functionality:
Application criticality determines module pricing power and implementation complexity.
- Supplier Collaboration:Direct procurement cost reduction and risk mitigation command premium pricing. German automotive networks leverage this functionality for Scope 3 emissions disclosure under CSRD mandates, automating carbon data collection across tiered suppliers.
- Demand Planning:AI-driven forecasting absorbs external signals for inventory rebalancing. Pharmaceutical manufacturers in Italy and Spain deploy these capabilities to synchronize batch production with EMA documentation timelines.
- Inventory Management:Real-time position visibility reduces working capital buffers for Polish automotive suppliers in Silesia.
- Order Processing:Execution layer automation streamlines fulfillment workflows for Netherlands-based third-party logistics operators.
Margin premium concentrates in Supplier Collaboration; fastest feature adoption occurs in Demand Planning.
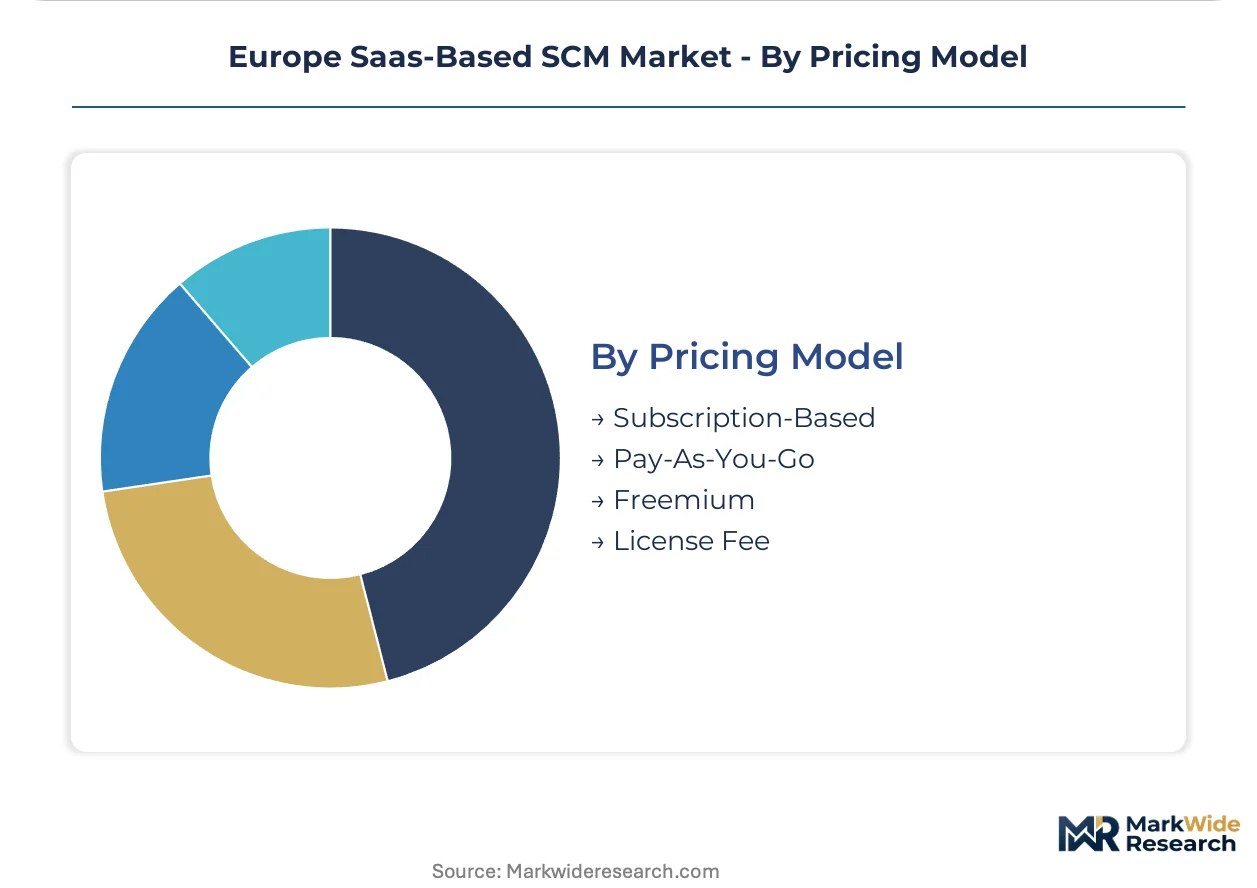
Pricing Model:
Customer maturity and procurement sophistication shape contract structures.
- Subscription-Based:Predictable annual or monthly fees align with enterprise budgeting cycles. Large French and German manufacturers prefer this structure for multi-year ERP integration roadmaps.
- Pay-As-You-Go:Consumption metering matches variable fulfillment volumes. E-commerce platforms in seasonal markets favor this flexibility for peak demand absorption.
- Freemium:Tiered feature access enables pilot adoption among mid-sized Mittelstand firms testing cloud migration.
- License Fee:Perpetual arrangements persist in legacy on-premises deployments with deep customization requirements.
Revenue stability favors Subscription-Based; customer acquisition velocity favors Freemium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine corridor's freight rail network underwrites continental supply chain density, channeling containerized goods between Rotterdam's port complex and Milan's manufacturing basin. This infrastructure backbone concentrates SaaS procurement authority in corridor-adjacent industrial clusters.
Germany
Baden-Württemberg's automotive supplier networks and Bavaria's Mittelstand machinery firms drive cloud-native procurement adoption. The EU AI Act's risk classification framework forces procurement platforms to embed algorithmic audit trails. Stuttgart-based OEMs now mandate sub-second latency for multi-tier supplier coordination.
France
Île-de-France's pharmaceutical manufacturers and Auvergne-Rhône-Alpes's chemical processors generate concentrated demand for REACH-compliant batch tracking. EMA documentation standards extend platform functionality into serialization workflows. Lyon-based drug manufacturers face steep adaptation curves for supply chain due diligence mandates.
Netherlands
Rotterdam's port-centric logistics operators and Amsterdam's e-commerce fulfillment networks prioritize warehouse execution systems. CSRD carbon reporting requirements push Dutch chemical distributors toward emissions-adjusted procurement metrics. Third-party logistics providers in the Randstad cluster lead supplier scorecard alignment with EU Green Deal benchmarks.
Poland
Silesia's automotive supplier networks and Greater Poland's manufacturing expansion create first-mover opportunities for warehouse-centric platforms. GDPR data residency rules force regional cloud instance deployment. Wrocław-based electronics contract manufacturers digitize supplier onboarding to compress working capital cycles.
Belgium
Antwerp's petrochemical corridor and Brussels' EU institutional procurement shape compliance-heavy platform requirements. REACH chemical tracking obligations strain platform configurability for industrial distributors. Belgian third-party logistics operators in the Flanders region adopt carbon-adjusted total cost of ownership metrics fastest.
Europe Saas-Based SCM Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower functional scope. The vendor base organizes around three archetypes: ERP-native suite providers with deep workflow integration, best-of-breed execution specialists with warehouse-centric capabilities, and planning-centric vendors with AI-driven forecasting modules. Consolidation pressure intensifies as procurement teams demand unified data models across procurement, inventory, and logistics layers. Strategic moves center on API-first partnership ecosystems and vertical compliance module development.
Within the ERP-native tier, SAP SE anchors procurement workflow integration for German automotive and chemical manufacturers. Oracle Corporation occupies a position emphasizing database-layer connectivity for real-time multi-tier visibility. Manhattan Associates exemplifies the execution-specialist archetype, serving third-party logistics operators in the Netherlands and Belgium with warehouse-centric systems. These three represent distinct competitive vectors: suite depth, data infrastructure, and operational execution.
| Leading Market Players |
|---|
| SAP SE |
| Oracle Corporation |
| IBM Corporation |
| Manhattan Associates |
| Korber AG |
| Kinaxis |
| Logility |
| Descartes Systems Group |
| Blue Yonder |
| Others |
Pricing and Supply Chain Analysis
Cloud infrastructure concentration in Ireland and Germany's Frankfurt-Rhine-Main corridor anchors margin capture for SaaS vendors serving European manufacturers, with data residency compliance costs flowing downstream as tiered subscription premiums.
Pricing Analysis
Volume-discount tiering structures dominate European SaaS SCM contracts, with enterprise manufacturers securing 15-30% reductions at 1000+ user thresholds. Price differentiation hinges on CSRD compliance module depth and sub-second latency guarantees for automotive networks. Cost compression in the mid-market segment intensifies as Polish and Romanian manufacturers demand freemium-to-paid conversion paths. E-commerce platforms exhibit highest price sensitivity due to seasonal volume volatility, while pharmaceutical manufacturers prioritize audit-trail sovereignty over cost.
Supply Chain Analysis
Supply-chain finance facilities extended by major cloud hyperscalers reduce working capital friction for SaaS vendors provisioning multi-tenant infrastructure across EU member states. Geographic supply concentration centers on Ireland, Germany, and the Netherlands for primary data center capacity, with secondary compute nodes in Poland and Sweden. Platform development draws from specialized labor pools in Estonia and Portugal for API engineering talent. Single-source vulnerability persists in AI/ML accelerator hardware dependent on Asian foundries. Distribution runs through direct enterprise sales teams supplemented by SAP-certified implementation partners in Stuttgart, Munich, and Paris.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's SaaS SCM market represents a high-growth disruption as CSRD mandates and EU AI Act compliance requirements force wholesale replacement of on-premise procurement systems with cloud-native architectures.
For Market Incumbents: Harden API-first integration capabilities against emerging best-of-breed challengers attacking the warehouse execution layer. Deepen vertical integration into carbon accounting data providers to secure CSRD module differentiation. Acquire specialized compliance boutiques in France and Germany before regulatory deadlines compress buyer decision windows.
For New Entrants and Emerging Players: Poland's Silesian automotive supplier corridor offers the most penetrable geography for warehouse-centric execution platforms, with GDPR-compliant regional cloud instances already mandated. Target mid-sized Mittelstand firms in Bavaria's machinery belt with freemium supplier collaboration modules. Pursue partnership-first go-to-market strategies through SAP integration marketplaces rather than direct enterprise sales.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed supply chain planning specialists lacking CSRD compliance functionality. Five-to-ten year viability favors vendors with embedded carbon tracking and multi-tier supplier onboarding automation. Watch for EU Green Deal enforcement intensity as the inflection signal determining platform consolidation pace.
| Strategic Initiative | Industry Significance |
|---|---|
| CSRD Compliance Module Development | Embedded carbon tracking at purchase-order line level satisfies German automotive disclosure mandates. |
| API-First Platform Integration | Sub-second latency protocols enable real-time inventory rebalancing across Rhine-Alpine corridor networks. |
| Geographic Cloud Expansion | Polish and Swedish data center deployment addresses GDPR residency requirements for Nordic manufacturers. |
| Acquisition of Compliance Specialists | REACH documentation boutiques extend platform functionality into French pharmaceutical supply chains. |
| Strategic Partnership with ERP Vendors | SAP-certified integration accelerates procurement workflow embedding in Baden-Württemberg industrial clusters. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with CTOs at German automotive OEMs, procurement directors in French pharmaceutical networks, cloud infrastructure architects at Benelux logistics operators, and integration specialists serving Mittelstand firms. Secondary validation drew from EMA documentation filings, CSRD regulatory drafts, EU AI Act implementation guidance, hyperscaler capex disclosures, and customs data on enterprise software imports. Bottom-up subscription volume estimates triangulated against top-down IT spending surveys across the analysis window.
Calibration against historical adoption curves in adjacent cloud software categories shaped the projection framework. Segmentation dimensions modeled encompass deployment architecture, end-user complexity tier, functional module depth, and regional regulatory intensity. CAGRs derived from logistic diffusion curves applied to compliance-mandated replacement cycles. Forecast inputs included EU Green Deal enforcement timelines and REACH documentation burden escalation trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive platform consolidation moves by ERP-native suite providers would shift outcomes. Macroeconomic contraction in German manufacturing, delayed CSRD enforcement, or breakthrough generative AI capabilities disrupting planning workflows would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Disclosure Management Software Market
Software & Services
Global Home Inspection Software Market
Software & Services
Remote Desktop Software Market
Software & Services
Open Stack Service Market
Software & Services
GCC Human Capital Management Software Market
Software & Services
Africa Financial Services Software Market
Software & Services
Saas for Spa Management Market
Software & Services
Global Offshore Software Development Market
Software & Services
File Analysis Software Market
Software & Services
Global Electronic Data Capture Software Market
Software & Services
Global Text to Speech (TTS) Software Market
Software & Services
Game Development Software Market
Software & Services
Non-Profit Donation Software Market
Software & Services
Electromagnetic Simulation Software Market
Software & Services
Enterprise MLC (Emlc) Market
Software & Services
Relational Database Management System Market