
 Load Testing Software Market | 2026-2036
Load Testing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Load Testing Software Market Analysis
Usage-based SaaS financing and outcome-aligned subscription models is reconfiguring competitive entry barriers for load testing vendors. Datadog leverages its integrated observability stack to bundle performance testing with infrastructure monitoring. SmartBear anchors its position through specialized API testing capabilities that extend into enterprise quality assurance workflows. Tricentis competes via AI-augmented test automation that reduces manual scripting overhead for complex enterprise applications.
Load testing software simulates concurrent user traffic against applications, APIs, and infrastructure components to measure response times, throughput thresholds, and failure points under controlled stress conditions. The technology validates system reliability before production deployment, preventing revenue loss from performance degradation during traffic spikes. Cloud-based deployment dominates commercial adoption as elastic infrastructure eliminates capital expenditure on dedicated load generator hardware. API and microservices testing segments expand fastest as service-oriented architectures proliferate across enterprise modernization programs. On-premise installations persist in regulated sectors where data residency requirements restrict cloud migration timelines.
FDA validation requirements for healthcare software systems shape product development roadmaps for vendors serving pharmaceutical and medical device clients. EMA's cybersecurity guidelines for connected health applications add compliance layers to European deployment specifications. ISO 25010 software quality standards and IEC 62304 medical device software frameworks create baseline certification thresholds that filter market access. Stakeholders must monitor how evolving AI governance mandates from the EU AI Act reshape automated test generation capabilities and audit trail requirements across regulated industries.
Market Dynamics
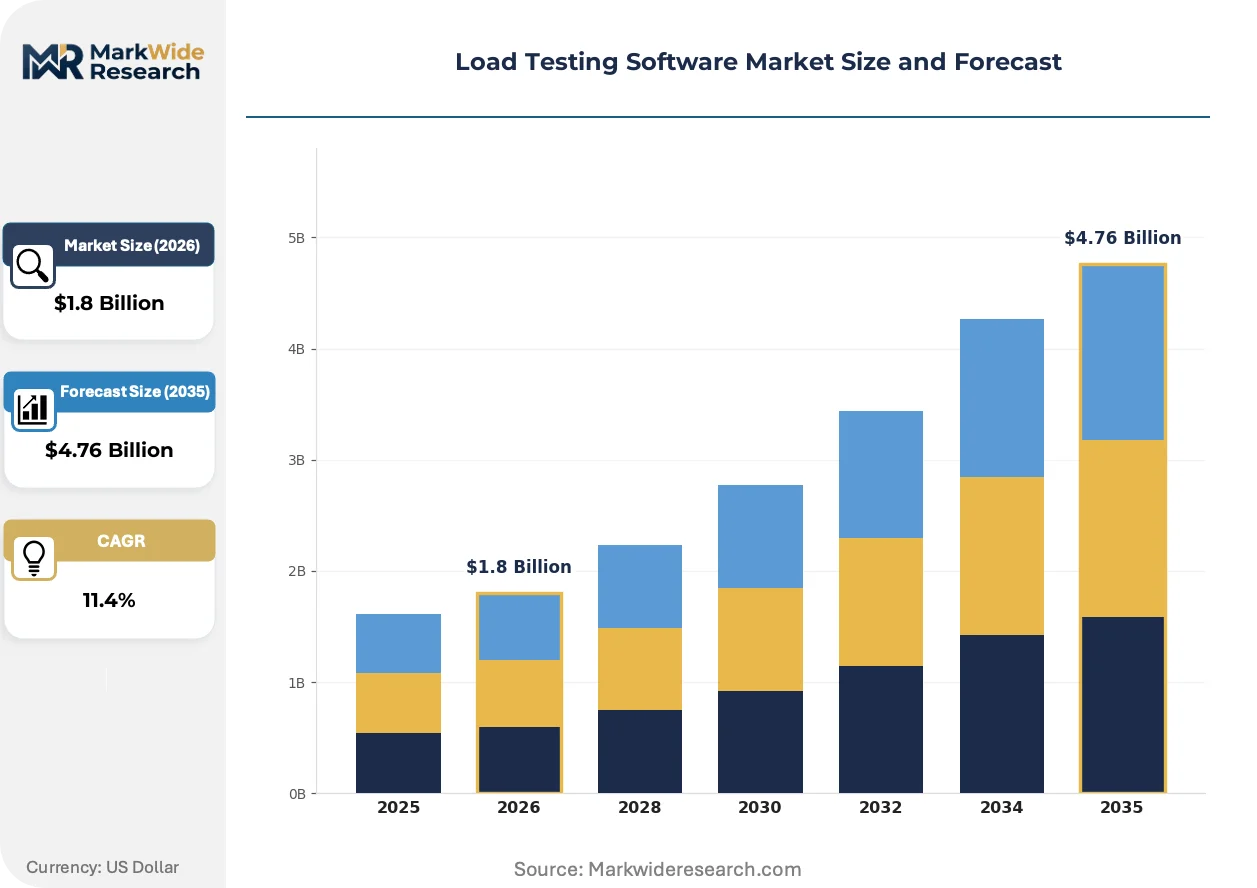
Cloud-native SaaS deployment is compressing capital barriers for load testing adoption while EU AI Act compliance mandates are forcing automated validation into regulated software pipelines. These twin pressures are restructuring vendor business models and customer procurement patterns simultaneously.
Growth Catalysts
- GDPR Article 32:EU data protection mandates require documented resilience testing for personal data processing systems, creating procurement pull from financial services and healthcare verticals.
- Microservices architecture proliferation:Container orchestration platforms are expanding API testing demand as service mesh complexity outpaces manual test coverage capacity.
- India:RBI's digital payment infrastructure guidelines and SEBI's trading system uptime requirements are accelerating load testing adoption among fintech and capital market participants.
Market Restraints
- Cloud infrastructure concentration:Hyperscaler dependency creates vendor lock-in risk as elastic load generation requires continuous compute procurement from AWS, Azure, or GCP.
- Specialized SRE talent scarcity:Site reliability engineering expertise for test script development and bottleneck analysis commands premium compensation, inflating implementation costs.
- On-premise hardware depreciation:Regulated sectors maintaining physical load generators face stranded asset risk as cloud migration timelines extend beyond equipment lifecycles.
Strategic Opportunities
- EMA cybersecurity guidelines:Connected health application mandates in Europe create compliance-driven demand for validated performance testing documentation.
- AI-augmented test generation:Large language model integration with synthetic traffic scripting is reducing manual correlation effort for complex user journey simulation.
- Outcome-aligned pricing:Usage-based SaaS models tied to detected performance defects are displacing seat-based subscriptions in mid-market DevOps procurement.
Industry Challenges
- ISO 25010 certification complexity:Software quality standard compliance requires extensive documentation of test coverage metrics, extending sales cycles for regulated industry accounts.
- Legacy monolith integration:Mainframe and COBOL system performance validation demands specialized protocol adapters that fragment engineering resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Load Testing Software Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS Technology: Web Applications, Mobile Applications, APIs, Microservices End User: IT Departments, Software Vendors, Enterprises, Service Providers Application: Performance Testing, Stress Testing, Scalability Testing, Load Testing |
| Companies Covered | Datadog, New Relic, Tricentis, BlazeMeter, OpenText, Postman, SmartBear, BrowserStack, Gatling, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Load Testing Software Market Emerging Trajectories
Agent-based observability integration is collapsing the boundary between production monitoring and pre-deployment validation. Vendors are racing to embed load testing within continuous deployment pipelines before competitors lock in platform consolidation.
Container-native load generation is virtualizing traffic simulation infrastructure through Kubernetes-native test orchestration. DevOps teams at SaaS providers are replacing dedicated load generator clusters with ephemeral pod-based traffic engines. This architecture is virtualizing capital expenditure models while enabling per-pull-request performance regression detection.
EU AI Act risk classification requirements are mandating documented stress testing for high-risk automated decision systems. Healthcare and financial services deployers must validate algorithmic performance under adversarial load conditions. German automotive and French banking regulators are issuing supplementary guidance on acceptable latency thresholds for AI-inferred outputs.
Platform engineering teams are consolidating vendor relationships around integrated observability stacks rather than standalone testing tools. Procurement evaluation criteria now weight APM integration depth above specialized load testing feature breadth. This preference shift is most pronounced among Series C and public SaaS companies in the United States and United Kingdom.
Load Testing Software Market Segmentation
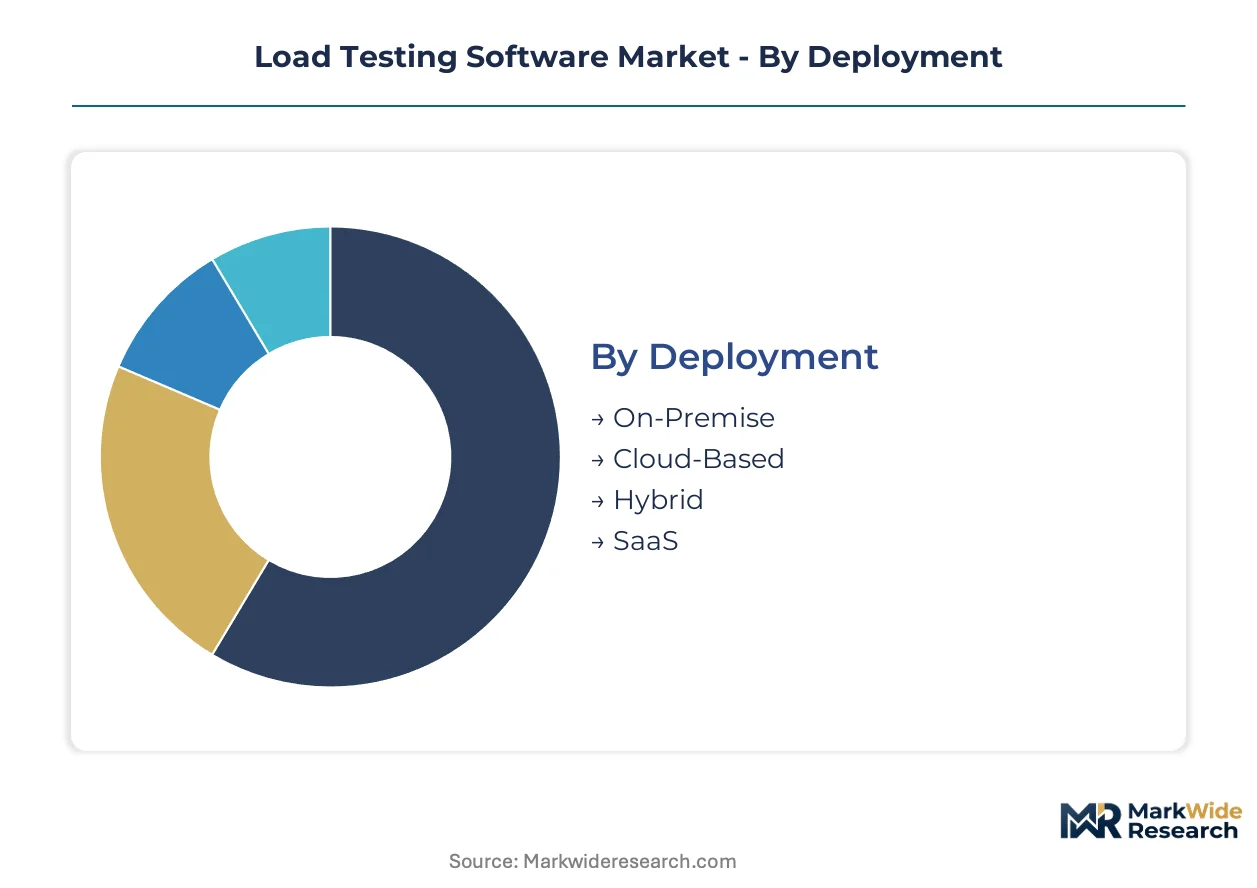
Segmentation reveals how procurement patterns fragment across infrastructure maturity levels and compliance postures. Cloud-native teams cycle through tools faster than regulated enterprises maintaining validated on-premise stacks.
Deployment:
SaaS and cloud-based deployments turn over fastest as DevOps teams iterate continuously, while on-premise installations persist longest where validation documentation anchors procurement cycles.
- On-Premise:Physical load generator clusters deployed within customer data centers demand dedicated hardware maintenance and specialized protocol adapters. Financial services firms in Germany and healthcare systems under FDA jurisdiction retain these installations where data residency requirements block cloud migration timelines.
- Cloud-Based:Elastic compute provisioning from hyperscalers eliminates capital expenditure on dedicated infrastructure while enabling burst capacity for seasonal traffic validation. Indian fintechs scaling under RBI digital payment guidelines and US SaaS providers dominate procurement as they prioritize per-pull-request performance regression detection.
- Hybrid:Split deployments route sensitive test data through on-premise infrastructure while leveraging cloud elasticity for non-regulated workloads. European automotive manufacturers under KBA oversight and Japanese industrial conglomerates favor this architecture to balance compliance with cost efficiency.
- SaaS:Fully managed subscription services embed load testing within continuous deployment pipelines through API-first architectures. Mid-market DevOps teams in the United Kingdom and Australian cloud-native startups drive adoption of usage-based pricing tied to detected performance defects.
On-premise dominates installed base. SaaS is where expansion concentrates.
Technology:
Cost tier stratification separates enterprise-grade microservices platforms from budget-conscious web application tools, with API testing commanding premium pricing due to specialized protocol expertise requirements.
- Web Applications:Browser-based traffic simulation validates response times and rendering performance across desktop and mobile client environments. Legacy enterprise IT departments in France and established B2B software vendors maintain these tools for monolithic application stacks.
- Mobile Applications:Device farm integration and network condition emulation test native iOS and Android binaries under variable connectivity scenarios. Consumer-facing service providers in South Korea and Brazilian e-commerce platforms prioritize these capabilities as mobile traffic share climbs.
- APIs:Protocol-level validation of REST, GraphQL, and gRPC endpoints measures latency distributions and error rate thresholds under synthetic request loads. German automotive suppliers integrating with connected vehicle platforms and Indian payment processors under SEBI uptime mandates represent the steepest expansion trajectory.
- Microservices:Container-orchestrated test generation simulates traffic across service mesh architectures with distributed tracing correlation. Platform engineering teams at Series C SaaS companies in the United States and cloud-native enterprises in Singapore deploy these tools to manage inter-service dependency complexity.
Web applications anchor legacy revenue. Microservices is climbing the fastest.
End User:
Volume concentration skews toward enterprises with multi-application portfolios, while margin capture favors software vendors embedding testing capabilities within commercial product offerings.
- IT Departments:Internal technology organizations validate pre-production systems against corporate SLA thresholds before external release. Canadian banking IT groups and Australian government agencies maintain centralized testing centers of excellence with standardized tool procurement.
- Software Vendors:Independent software companies integrate load testing within quality assurance workflows for commercial product releases. Healthcare software developers under FDA validation requirements and European medical device manufacturers facing EMA cybersecurity guidelines demand extensive documentation capabilities.
- Enterprises:Large organizations with diverse application portfolios deploy testing across business units with varying infrastructure maturity levels. German automotive OEMs and US pharmaceutical conglomerates operate the most complex multi-vendor environments.
- Service Providers:Managed testing services and quality engineering consultancies deliver performance validation as outsourced functions. Indian IT services exporters and Polish nearshore development shops compete on script development velocity and bottleneck analysis expertise.
Enterprises dominate installed base. Software vendors is gaining share fastest.
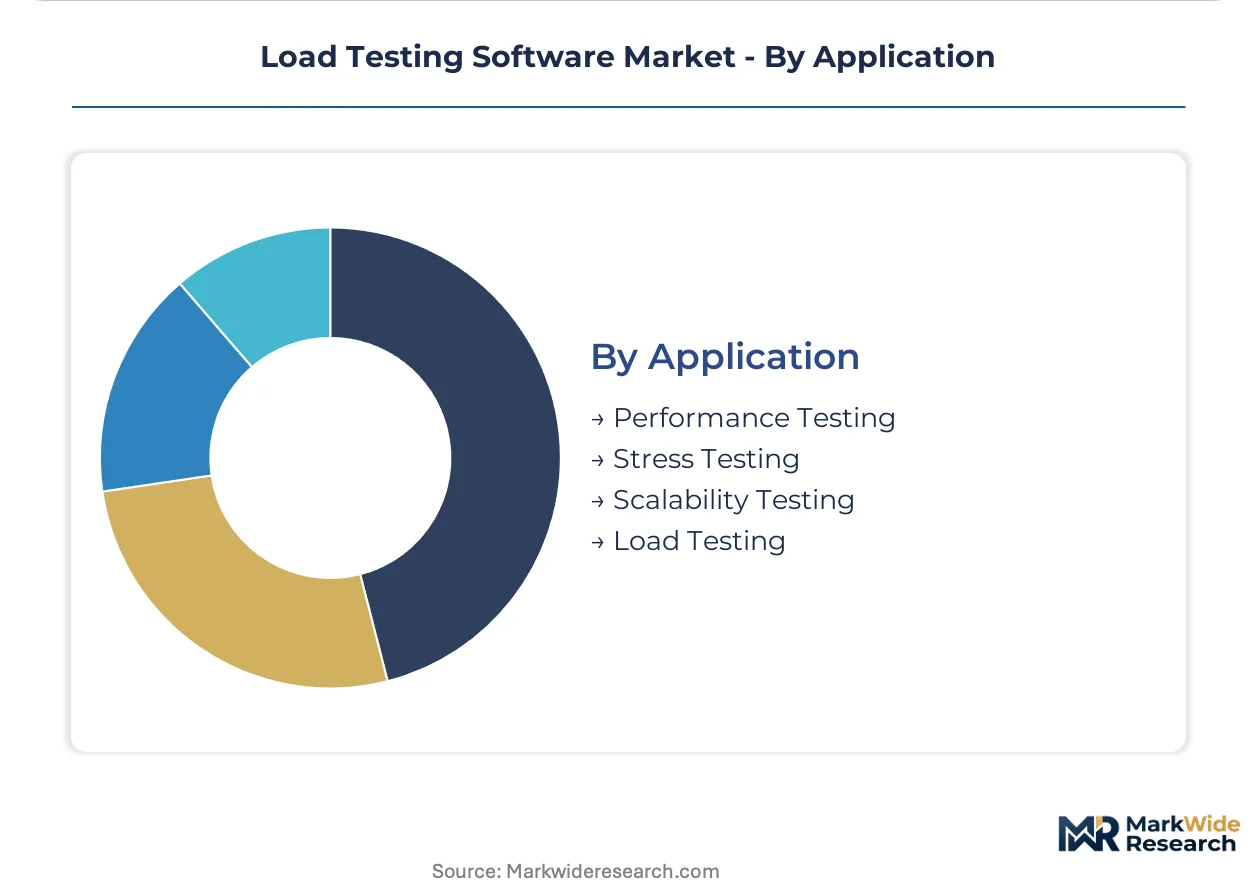
Application:
Customer type differentiation separates specialized stress testing for regulated uptime mandates from generalist performance validation, with scalability testing commanding premium engagement due to architectural consulting components.
- Performance Testing:Baseline measurement of response time distributions and throughput ceilings under expected production load profiles. Standard practice across all end-user segments, with French retail banks and Japanese telecommunications operators maintaining the most rigorous measurement protocols.
- Stress Testing:Deliberate overload conditions identify failure thresholds and recovery behavior beyond normal operating parameters. Mandatory for Indian trading systems under SEBI guidelines and US healthcare platforms facing HIPAA availability requirements.
- Scalability Testing:Incremental load ramping validates horizontal and vertical scaling behavior across infrastructure expansion scenarios. Cloud-native SaaS providers in the United Kingdom and German Industry 4.0 manufacturing platforms invest heavily as they architect for unpredictable demand spikes.
- Load Testing:General-purpose concurrent user simulation encompassing functional validation under multi-user contention. Small and mid-market IT departments in Brazil and Southeast Asian e-commerce operations deploy these as entry-level capabilities before graduating to specialized test types.
Performance testing dominates installed base. Scalability testing is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Load testing software trade flows reflect concentrated production in established SaaS hubs against distributed consumption across modernization programs. The United States generates substantial export value through integrated observability platforms, while Germany and India represent the fastest-growing import demand centers as regulatory mandates accelerate procurement.
United States
Platform engineering teams at Series C SaaS companies and public cloud providers drive enterprise-grade adoption. SEC disclosure requirements for operational resilience and HIPAA availability mandates for healthcare systems create compliance pull. The San Francisco Bay Area and Seattle metropolitan clusters host the densest concentration of observability-integrated load testing deployments.
Germany
Automotive OEMs and industrial machinery manufacturers under KBA oversight demand validated performance documentation for connected systems. The EU AI Act risk classification requirements force stress testing protocols for automated decision systems. Bavarian automotive suppliers and Frankfurt financial institutions represent the steepest procurement trajectory.
India
RBI digital payment infrastructure guidelines and SEBI trading system uptime mandates accelerate fintech and capital market adoption. The country's IT services exporters deliver managed testing capabilities to global clients. Mumbai's financial district and Bangalore's SaaS corridor concentrate domestic demand expansion.
United Kingdom
Mid-market DevOps teams prioritize usage-based SaaS models tied to detected performance defects. Platform consolidation preferences favor vendors with deep APM integration. London's fintech cluster and Manchester's enterprise software base anchor procurement concentration.
Japan
Telecommunications operators and industrial conglomerates maintain rigorous measurement protocols for legacy system modernization. METI guidelines on operational resilience shape enterprise procurement criteria. Tokyo's corporate headquarters and Osaka's manufacturing technology centers sustain specialized demand.
Load Testing Software Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in protocol-specific niches. The vendor base stratifies between consolidated observability stacks and fragmented point solutions. Three archetypes dominate: full-stack monitoring platforms extending into testing, API-centric quality tools, and open-source load generation engines. Competitive maneuvering concentrates on API-first architecture investments and outcome-aligned pricing model deployment.
Within the observability-integrated tier, Datadog exemplifies platform consolidation strategy, while Tricentis occupies a position representing AI-augmented automation archetypes. SmartBear anchors the specialized API testing segment. These three entities collectively illustrate how vendor positioning diverges between bundled infrastructure monitoring and dedicated quality engineering workflows.
| Leading Market Players |
|---|
| Datadog |
| New Relic |
| Tricentis |
| BlazeMeter |
| OpenText |
| Postman |
| SmartBear |
| BrowserStack |
| Gatling |
| Others |
Supply Flow & Price Mechanics
San Francisco Bay Area hyperscaler infrastructure anchors elastic compute provisioning for load generation workloads, concentrating downstream pricing power among vendors with captive cloud capacity agreements. Cloud-native SaaS deployment models compress capital barriers while creating tiered subscription structures that reflect infrastructure cost passthrough dynamics.
Pricing Analysis
Enterprise DevOps buyers anchor value-based pricing structures across the load testing software landscape. Three-tier pricing separates enterprise-grade observability bundles from mid-market per-test consumption models and open-source supported tiers. Price differentiation hinges on API protocol breadth and ISO 25010 certification documentation depth. Cost compression in the mid-market tier intensifies as usage-based SaaS financing displaces seat-based subscriptions. Small and mid-market IT departments exhibit highest price sensitivity, while regulated healthcare software vendors under FDA validation requirements demonstrate lowest sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Hyperscaler dependency between United States cloud providers and European data residency requirements dominates supply chain risk architecture for load testing infrastructure. Geographic supply concentration centers on United States, Germany, and India as primary demand nodes driving elastic compute provisioning. Raw material dependencies draw from semiconductor fabrication for load generator hardware, submarine cable capacity for transatlantic traffic simulation, and specialized protocol adapter manufacturing. Single-source vulnerability concentrates around AWS, Azure, and GCP as the sole viable elastic compute sources for burst testing capacity. Distribution runs through direct SaaS subscription channels for cloud-native deployments and systems integrator partnerships for regulated on-premise installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where regulatory entrenchment creates durable switching costs. Validation documentation requirements under FDA, EMA, and EU AI Act frameworks cement incumbent positions through compliance friction that new entrants cannot easily replicate.
For Market Incumbents: Pre-empt platform consolidation momentum by embedding load testing capabilities within broader observability stacks before competitors lock in DevOps toolchain relationships. Deepen API-first architecture investments to capture microservices testing expansion. Defend against open-source load generation engines by accelerating AI-augmented test automation differentiation that reduces manual scripting overhead.
For New Entrants and Emerging Players: Southeast Asian e-commerce operations and Brazilian fintech infrastructure represent underpenetrated demand centers where legacy tool replacement cycles create white-space opportunity. Target mid-market DevOps teams in United Kingdom and Australia with outcome-aligned pricing models tied to detected performance defects. Pursue channel partnerships with systems integrators serving regulated European automotive manufacturers under KBA oversight.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized API testing capabilities over generalist web application tools as service-oriented architectures proliferate. Long-term viability rests on vendors demonstrating sustained R&D investment in container-native test orchestration and EU AI Act compliance automation. Acquisition target archetypes include microservices-focused testing specialists with Kubernetes-native architectures. Monitor SEBI and RBI regulatory enforcement intensity in India as inflection indicator for emerging market demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding load testing within Datadog-style observability stacks captures DevOps toolchain consolidation momentum. |
| AI-Augmented Test Generation | Large language model integration reduces manual correlation effort for complex user journey simulation. |
| Regulatory Compliance Automation | EU AI Act stress testing documentation capabilities differentiate vendors serving healthcare and financial services. |
| Container-Native Orchestration | Kubernetes-native traffic engines virtualize capital expenditure models for cloud-native SaaS providers. |
| Outcome-Aligned Pricing Deployment | Usage-based models tied to detected defects displace seat-based subscriptions in mid-market procurement. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with platform engineering directors, DevOps team leads, IT procurement officers, and quality assurance managers; and secondary validation through SEC filings of publicly traded observability vendors, hyperscaler capex disclosures, regulatory guidance documents from FDA and EMA, and EU AI Act implementation texts. Bottom-up triangulation across deployment model, technology segment, end-user category, and application type combined with top-down macroeconomic overlay analysis.
Forecast inputs considered cloud migration timelines across regulated industries, microservices architecture adoption curves, and EU AI Act enforcement phasing across the analysis window. Segmentation dimensions modeled include deployment model, organization size, vertical industry, integration complexity with existing observability stacks, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand projections and vendor pricing trajectory analysis. Industry-specific inputs encompass SEBI trading system uptime mandate compliance rates and FDA software validation documentation requirements.
Macroeconomic conditions sit as an overlay; deviation in cloud infrastructure pricing, enterprise software procurement cycles, or regulatory enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions regarding technology adoption curves and compliance timeline adherence. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Data Extraction Software Market
Software & Services
Customer Revenue Optimization Software Market
Software & Services
Meditation Management Apps Market
Software & Services
Visitor Identification Software Market
Software & Services
Global Note Taking App Market
Software & Services
Productivity Software Publishing Market
Software & Services
LTFS Copy Software Market
Software & Services
Global Cloud Accounting Technology Market
Software & Services
Search and Discovery Software Market
Software & Services
Global Award Management Software Market
Software & Services
Global Construction Management Software Market
Software & Services
Library Management Software Market
Software & Services
Mobile Tracking Software Market
Software & Services
Europe Saas-Based SCM Market
Software & Services
Gym Motion Tracking Software Market
Software & Services
Collaborative Authoring Tools Market