
 Global Quantum Computing Software Market | 2026-2036
Global Quantum Computing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Quantum Computing Software Market Foresight
Project finance through quantum-as-a-service subscription models is narrowing the capital barrier for mid-sized enterprises to access quantum algorithms. IBM leverages its Qiskit ecosystem to sustain developer loyalty across academic and commercial users. Google anchors its competitive position through Sycamore processor integration with its quantum software stack. Microsoft differentiates via Azure Quantum's multi-hardware orchestration layer that spans trapped-ion and superconducting qubit systems.
Quantum computing software encompasses programming frameworks, error correction protocols, and algorithm libraries that translate abstract quantum circuits into executable instructions for hardware backends operating at millikelvin temperatures. These tools enable computational acceleration for problems intractable to classical silicon, including prime factorization, combinatorial optimization, and quantum chemistry simulation. Cloud-based deployment leads current adoption as hyperscalers absorb cryogenic infrastructure costs, while quantum machine learning represents the fastest-expanding solution type as financial institutions pilot portfolio optimization. On-premise installations retain premium pricing among defense contractors and intelligence agencies with data sovereignty requirements.
FDA guidelines on computational validation for drug discovery, EU AI Act risk classifications for autonomous decision systems, and NIST post-quantum cryptography standards collectively shape product roadmaps and procurement criteria. The EU Green Deal's datacenter efficiency mandates additionally pressure cloud providers to disclose quantum cooling energy intensity. Stakeholders must monitor which regulatory jurisdiction achieves primacy in certifying quantum algorithm safety for critical infrastructure applications.
Market Dynamics
Federal research funding in the United States and EU AI Act compliance mandates are compressing cloud platform architectures while accelerating on-premise deployment among defense contractors with strict data sovereignty requirements.
Growth Catalysts
- NIST Post-Quantum Cryptography Standards:Federal procurement guidelines in the United States are mandating quantum-resistant algorithm migration across critical infrastructure sectors, forcing software vendors to prioritize cryptographic library development.
- Pharmaceutical molecular modeling:Drug discovery pipelines at European and American pharmaceutical firms are integrating variational quantum eigensolvers to accelerate protein folding simulations previously intractable on classical clusters.
- Japan's quantum technology roadmap:METI funding allocations for quantum software startups are concentrating algorithm development talent in Tokyo-Osaka corridors, creating regional innovation density unmatched elsewhere in Asia-Pacific.
Market Restraints
- Cryogenic infrastructure costs:Dilution refrigerator maintenance and helium-3 supply volatility constrain cloud provider expansion, limiting access for mid-sized enterprises outside major metropolitan zones.
- Decoherence time limitations:Current superconducting qubit coherence periods cap circuit depth, preventing execution of commercially valuable algorithms requiring thousands of gate operations.
- EU AI Act risk classification friction:Autonomous decision system categorization creates compliance uncertainty for quantum machine learning deployments in financial services, slowing procurement cycles.
Strategic Opportunities
- Germany's industrial quantum computing initiative:Federal Ministry funding for manufacturing optimization algorithms creates white space for software vendors targeting automotive and chemical process simulation.
- Quantum machine learning convergence:Tensor network compression techniques combined with quantum kernel methods are opening predictive maintenance applications in aerospace supply chains previously unreachable by either technology alone.
- Edge-to-cloud orchestration channels:Hybrid deployment models allowing on-premise pre-processing with cloud-based quantum execution are emerging as preferred procurement pathways for healthcare systems managing patient data.
Industry Challenges
- Quantum software engineering talent scarcity:The intersection of quantum physics, linear algebra, and high-performance computing expertise remains concentrated at fewer than two dozen academic institutions globally, constraining vendor hiring pipelines.
- Legacy system integration complexity:Enterprise resource planning connectors and classical HPC workflow adapters require substantial customization, extending deployment timelines and inflating professional services costs.
- Algorithm certification timelines:Absence of standardized validation frameworks for quantum advantage claims leaves procurement officers without objective criteria to evaluate vendor performance assertions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Quantum Computing Software Market |
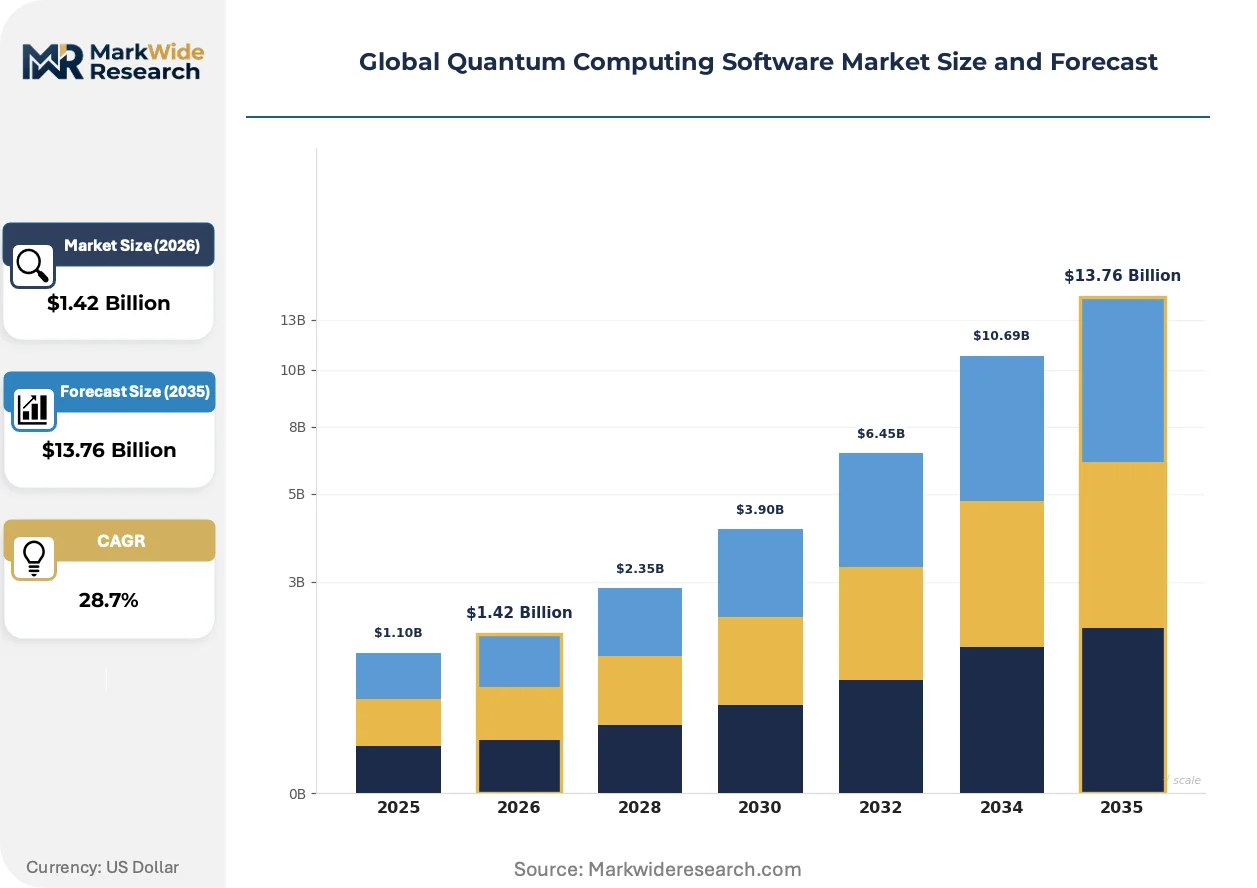
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $13.76 Billion |
| CAGR (2026 – 2036) | 28.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
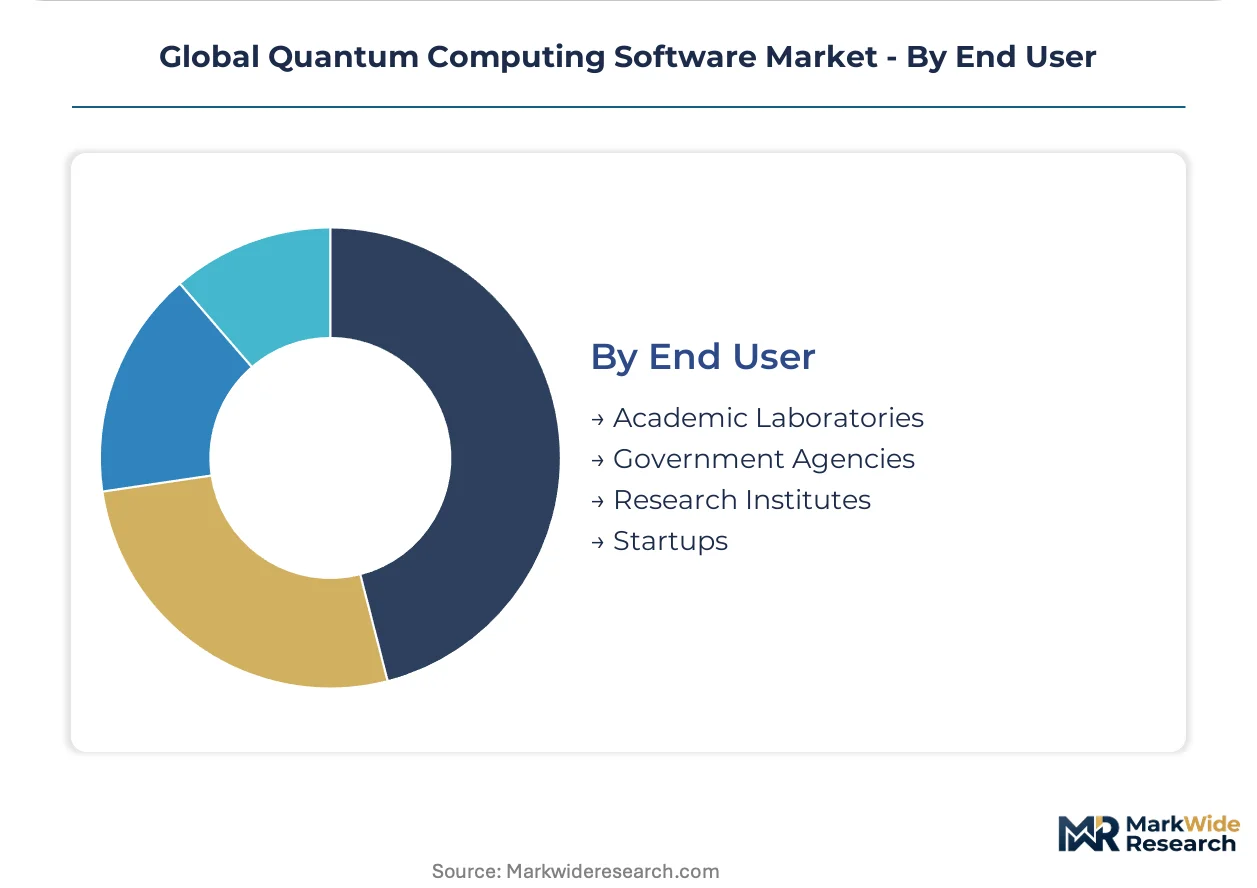
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Edge Computing Solution Type: Quantum Programming Frameworks, Quantum Error Correction, Quantum Simulation, Quantum Machine Learning Application: Cryptography, Drug Discovery, Financial Modeling, Optimization, Logistics End User: Academic Laboratories, Government Agencies, Research Institutes, Startups |
| Companies Covered | D-Wave Systems, Rigetti Computing, IBM, Google, Classiq, Microsoft, IonQ, BlueQubit, Amazon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Quantum Computing Software Market Shifts & Advancements
Quantum error correction protocols and hybrid classical-quantum compilers are compressing the gap between hardware capability and commercial utility, while regulatory jurisdictions compete to establish certification primacy for safety-critical deployments.
Error mitigation through probabilistic error cancellation is collapsing the effective noise floor for near-term intermediate-scale quantum devices. Financial services firms in London and New York are piloting these techniques for derivative pricing models, compressing the timeline for quantum advantage in risk analysis from decade-scale projections to current hardware generations.
The EU AI Act's risk-based classification system for autonomous decision-making is forcing quantum machine learning vendors to rearchitect model interpretability features. High-risk system categorization triggers conformity assessment obligations that favor European-headquartered providers with established notified body relationships, tilting competitive dynamics in regulated sectors.
Subscription-based quantum-as-a-service procurement is displacing capital-intensive on-premise installations among mid-market pharmaceutical and materials science firms. Germany's chemical conglomerates and South Korean battery manufacturers are driving this shift, unbundling hardware ownership from algorithm access and compressing payback periods for exploratory quantum computing investments.
Global Quantum Computing Software Market Segmentation
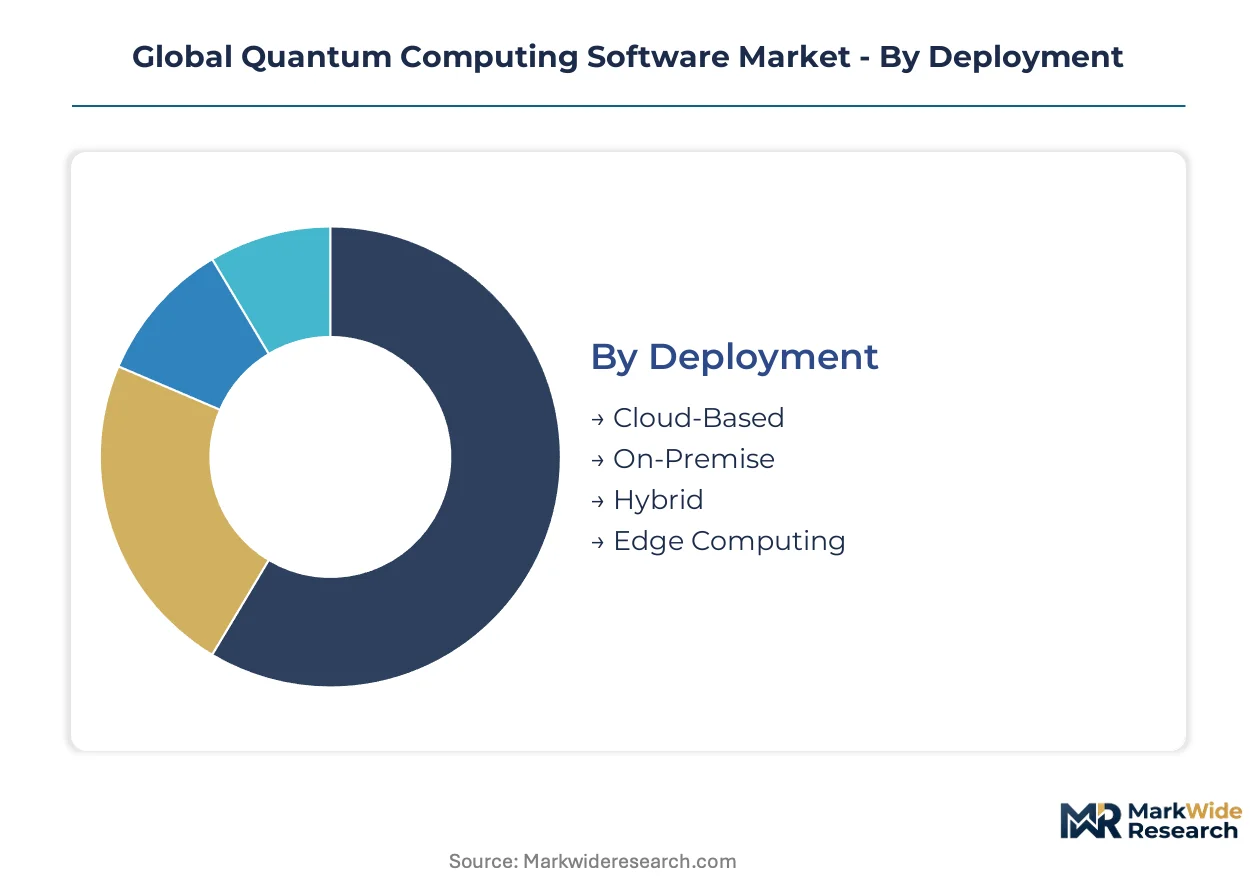
Quantum computing software segments reflect divergent commercial maturity across deployment infrastructure and solution architectures. Vendor positioning and procurement patterns vary sharply between cloud-native platforms and sovereign on-premise installations.
Deployment:
Cost tier determines accessibility thresholds across the deployment spectrum, separating hyperscaler-absorbed infrastructure from capital-intensive captive systems.
- Cloud-Based:Hyperscalers absorb dilution refrigerator and helium-3 logistics costs, delivering API-accessible quantum circuits to enterprises without cryogenic capital expenditure. Pharmaceutical firms in Germany and financial institutions in the United States concentrate procurement here, driven by FDA computational validation requirements and EU AI Act compliance uncertainty that favors operational flexibility over fixed infrastructure.
- On-Premise:Captive installations command premium pricing for defense contractors and intelligence agencies with strict data sovereignty mandates. The United Kingdom's Government Communications Headquarters and France's national cyber defense agency anchor demand, prioritizing air-gapped execution environments over cloud accessibility.
- Hybrid:Orchestration layers route pre-processing to classical clusters and quantum execution to cloud backends. Healthcare systems in the Netherlands pilot this architecture for patient data workflows requiring local de-identification before remote algorithm execution.
- Edge Computing:Compact cryogenic units deployed at manufacturing sites for real-time process optimization. Japan's METI-funded automotive suppliers in the Nagoya corridor test edge-to-cloud quantum pipelines for supply chain resilience.
Cloud-Based deployments command the established base. The steepest expansion runs through Hybrid configurations.
Solution Type:
Application maturity separates algorithm libraries with immediate commercial utility from foundational layers still resolving hardware constraints.
- Quantum Machine Learning:Tensor network compression combined with quantum kernel methods accelerates predictive maintenance for aerospace supply chains. Financial services firms in London and Singapore drive procurement, though EU AI Act high-risk system classifications slow procurement cycles for autonomous decision deployments.
- Quantum Simulation:Variational quantum eigensolvers model protein folding and molecular interactions previously intractable on classical clusters. Roche and Bristol Myers Squibb anchor demand in Basel and New Jersey, integrating simulation into FDA-guided drug discovery pipelines.
- Quantum Programming Frameworks:Python-based circuit composers and hardware abstraction layers enable algorithm portability across superconducting and trapped-ion backends. Academic institutions in Zurich and Waterloo concentrate adoption.
- Quantum Error Correction:Probabilistic error cancellation and surface code implementations compress effective noise floors for near-term devices. IBM and Google internal development teams dominate current deployment.
Quantum Simulation commands the established base. Quantum Machine Learning climbs the fastest as financial institutions pilot portfolio optimization.
Application:
Regulatory pressure intensity shapes adoption velocity across use cases, with cryptography mandates outpacing exploratory domains.
- Cryptography:NIST post-quantum standards force migration across United States federal infrastructure, creating immediate procurement demand for quantum-resistant algorithm libraries. Banking regulators in Switzerland and Singapore have issued parallel guidance, compressing vendor development timelines.
- Drug Discovery:Molecular modeling pipelines at Sanofi and Merck integrate quantum chemistry simulation, though FDA computational validation frameworks remain under development for quantum-generated submissions.
- Financial Modeling:Derivative pricing and risk analysis applications pilot probabilistic error cancellation techniques in London and New York, collapsing quantum advantage timelines from decade-scale projections.
- Optimization:Combinatorial solvers address logistics network design for Deutsche Post and manufacturing scheduling for Siemens.
- Logistics:Last-mile routing and inventory positioning algorithms remain exploratory, with limited commercial deployment outside pilot programs.
Cryptography commands the established base. Drug Discovery gains share fastest as protein folding validation matures.
End User:
Customer type determines procurement authority and budget scale, separating sovereign-funded installations from venture-backed experimentation.
- Government Agencies:National laboratory partnerships and defense procurement channels concentrate demand in the United States, United Kingdom, and Australia. NIST, Oak Ridge National Laboratory, and the Australian Defence Science and Technology Group anchor funding flows with multi-year algorithm development contracts.
- Academic Laboratories:ETH Zurich, MIT, and the University of Tokyo train quantum software engineering talent while hosting hyperscaler hardware partnerships. These institutions constrain vendor hiring pipelines given concentration at fewer than two dozen global centers.
- Research Institutes:Germany's Fraunhofer Society and Japan's RIKEN bridge foundational research and commercial application, often co-funding algorithm development with industrial partners.
- Startups:Venture-backed quantum software firms in the Tokyo-Osaka corridor and Boston-Cambridge cluster concentrate on narrow application verticals, frequently licensing through cloud marketplaces rather than direct enterprise sales.
Government Agencies command the established base. Startups show the steepest expansion trajectory as cloud marketplaces lower capital barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net export positions in quantum software concentrate where federal research funding and hyperscaler infrastructure overlap, creating trade asymmetries favoring the United States and Japan against net-importing European pharmaceutical and financial services sectors.
United States
NIST post-quantum cryptography procurement mandates and Department of Energy national laboratory partnerships anchor domestic demand. FDA computational validation frameworks for drug discovery software shape vendor development timelines. Boston-Cambridge and Silicon Valley clusters concentrate venture-backed quantum machine learning startups licensing through cloud marketplaces.
Germany
Federal Ministry funding for industrial quantum computing applications drives automotive and chemical process simulation procurement. EU AI Act high-risk system classifications create compliance friction for autonomous financial decision systems. Fraunhofer Society institutes in Munich and Stuttgart bridge foundational research with industrial algorithm co-development.
Japan
METI quantum technology roadmap allocations concentrate algorithm development talent in the Tokyo-Osaka corridor. National cyber defense requirements favor domestic cloud platform procurement over foreign hyperscalers. RIKEN research institutes in Kobe and Tsukuba host hardware-software integration partnerships with automotive suppliers testing edge-to-cloud pipelines.
United Kingdom
Government Communications Headquarters data sovereignty mandates sustain premium on-premise installation demand among intelligence agencies. National Quantum Programme funding supports academic-commercial spinouts from Oxford and Cambridge. London financial services firms pilot probabilistic error cancellation for derivative pricing under Bank of England supervisory frameworks.
Switzerland
Swissmedic and FINMA regulatory guidance on quantum-generated submissions compresses pharmaceutical and banking software validation timelines. ETH Zurich trains quantum software engineering talent constraining global vendor hiring pipelines. Basel-based Roche anchors molecular modeling demand integrating variational quantum eigensolvers into FDA-guided pipelines.
Global Quantum Computing Software Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in error correction and algorithm libraries. The vendor base organizes around three strategic archetypes: hyperscalers absorbing cryogenic infrastructure costs, pure-play quantum software firms licensing narrow vertical applications, and legacy enterprise IT vendors extending classical stacks into quantum orchestration layers. Dominant competitive moves include strategic partnerships between hardware manufacturers and cloud platforms, plus technology licensing agreements that unbundle algorithm access from captive hardware ownership.
Within the hyperscaler tier, IBM, Google, and Microsoft represent contrasting architectural bets on developer ecosystem control versus multi-hardware abstraction. IBM anchors the open-source framework archetype through its Qiskit ecosystem. Google exemplifies vertical integration between processor hardware and proprietary software stacks. Microsoft occupies a position emphasizing cloud-native orchestration across disparate qubit modalities. These three firms collectively shape procurement standards that mid-sized enterprise adopters follow.
| Leading Market Players |
|---|
| D-Wave Systems |
| Rigetti Computing |
| IBM |
| Classiq |
| Microsoft |
| IonQ |
| BlueQubit |
| Amazon |
| Others |
Supply & Pricing Matrix
Helium-3 supply volatility and single-source dilution refrigerator dependency determine both cloud subscription tier spreads and captive on-premise hardware ownership patterns. This input concentration compresses mid-market accessibility while amplifying premium pricing for sovereign installations.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. Premium tiers bundle dedicated cryogenic infrastructure with algorithm customization for defense contractors; standard tiers offer API-accessible quantum circuits through hyperscaler subscriptions; economy tiers limit gate operations and queue priority. Price differentiation hinges on certification level—NIST post-quantum cryptographic validation commands substantial premiums—and volume scale, with pharmaceutical consortiums extracting tiered discounts. Cost compression in standard tiers is intensifying because hyperscalers absorb helium logistics to capture developer ecosystem loyalty. Mid-sized financial services firms exhibit highest price sensitivity, deferring procurement until error mitigation techniques mature.
Supply Chain Analysis
Extended payment terms from cloud providers to dilution refrigerator manufacturers stabilize working capital for cryogenic hardware vendors. Supply concentrates in the United States, Finland, and Japan for superconducting qubit fabrication; helium-3 extraction feeds from Russia and the United States. Raw material dependencies encompass niobium superconducting films, printed circuit boards with millikelvin-rated components, and specialized microwave cabling. Single-source vulnerability persists for dilution refrigerator compressors, where Bluefors and Oxford Instruments control captive production. Distribution runs through hyperscaler cloud marketplaces for software licensing, with direct hardware sales to national laboratories and defense agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as EU AI Act risk classifications splinter procurement standards, creating specialized niches for compliance-native vendors alongside performance-optimized alternatives.
For Market Incumbents: Harden cloud platform architectures against data sovereignty requirements by deploying regional edge nodes in Germany, Japan, and Switzerland. Invest in NIST post-quantum cryptographic certification to preempt federal procurement lockout. Acquire trapped-ion hardware partnerships to neutralize Google's superconducting integration advantage. For New Entrants and Emerging Players: Build out quantum error correction software stacks for near-term intermediate-scale devices, targeting pharmaceutical firms in Basel and New Jersey with variational quantum eigensolver applications. White space concentrates in automotive process optimization for Germany's chemical conglomerates. Go-to-market leverage rests on cloud marketplace listings with pay-per-circuit consumption models. For Investors and Strategic Acquirers: NIST post-quantum cryptography standard finalization reshapes the acquisition landscape by elevating cryptographic library vendors to strategic infrastructure status. Long-term viability favors firms with hybrid classical-quantum compiler intellectual property and established hyperscaler distribution. Target acquisition archetype: pure-play quantum software firms with vertical applications in drug discovery or financial risk modeling. Monitor FDA computational validation framework development for quantum-generated submissions as inflection indicator for pharmaceutical segment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure Quantum's multi-hardware orchestration spans trapped-ion and superconducting modalities. |
| Strategic Partnership | IBM's Qiskit ecosystem sustains developer loyalty across academic and commercial user bases. |
| Acquisition of Specialist Firm | Error correction startups with probabilistic cancellation IP address near-term device constraints. |
| Product Launch | Quantum machine learning modules target portfolio optimization for London and Singapore financial institutions. |
| Geographic Expansion | Tokyo-Osaka corridor concentration captures METI-funded algorithm development talent. |
Research Methodology
Desk research of hyperscaler capex disclosures, NIST standard drafts, and EU regulatory filings preceded structured interviews with quantum software engineering leads, pharmaceutical computational chemistry directors, financial services risk technology officers, and cloud platform procurement managers. Secondary validation drew from SEC filings of publicly traded quantum hardware vendors, academic partnership announcements from ETH Zurich and MIT, and national laboratory funding allocations. Bottom-up estimates of cloud API consumption and top-down triangulation against federal research budgets converged on segment-level projections.
Assumptions held fixed include NIST post-quantum cryptography migration timelines, EU AI Act enforcement sequencing, and helium-3 supply continuity; varied assumptions encompassed error correction breakthrough timing and quantum advantage demonstration in financial derivative pricing. The analytical framework modeled deployment mode, solution type, application vertical, and end-user category across the projection horizon. CAGR derivation weighted hardware roadmap announcements against historical cloud service adoption curves. Industry-specific inputs comprised FDA computational validation framework development status and METI funding allocation trajectories.
Practitioners should monitor NIST standard finalization dates, EU AI Act conformity assessment body designations, and helium-3 export restriction signals for early signals of forecast revision triggers. Forecasts reflect documented assumptions regarding cryogenic infrastructure cost trajectories and quantum machine learning algorithm maturity. Macroeconomic contraction in federal research budgets, regulatory jurisdiction competition for certification primacy, or superconducting qubit coherence period stagnation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Vlog Editing Software Market
Software & Services
Global Java Web Frameworks Software Market
Software & Services
EDA Tools Market
Software & Services
Global Childcare Management Software Market
Software & Services
Mobile Device Management (MDM) Market
Software & Services
SRM Software Market
Software & Services
Global Disk Imaging Software Market
Software & Services
France HR Payroll Software Market
Software & Services
Screen and Video Capture Software Market
Software & Services
Latin America Cloud Workforce Management Software Market
Software & Services
Telecom Billing Software Market
Software & Services
Global Log Management Software Market
Software & Services
Acoustic Simulation Software Market
Software & Services
Smartphone Applications Market
Software & Services
Avionics Software Market
Software & Services
Global Mobile User Interface Services Market