
 LED and OLED Display Market | 2026-2036
LED and OLED Display Market Size, Share, and Industry Trends Forecast 2026-2036
LED and OLED Display Market Outlook
Subscription-based display-as-a-service models for commercial digital signage is realigning how panel vendors monetize hardware lifecycles. Samsung Display leverages captive OLED capacity to dominate smartphone panel supply. LG Display anchors large-format OLED production for premium television applications. BOE Technology extends Gen 10.5 LCD and emerging OLED lines to compete across multiple application tiers.
LED and OLED displays are electroluminescent visual output devices comprising semiconductor diodes or organic thin-film stacks that emit light when current passes through emissive layers, with OLED achieving sub-millisecond response times and near-perfect black levels through pixel-level light control. Their primary commercial purpose spans information presentation, entertainment consumption, and human-machine interface visualization across consumer and professional contexts. OLED product types command premium positioning in smartphone and television applications where contrast ratio and form factor flexibility justify higher unit economics. Mini-LED and MicroLED segments represent the fastest-expanding technology categories as manufacturers resolve transfer yield and cost barriers for mass production. Digital signage applications concentrate margin pools in commercial end-user deployments where brightness durability and remote manageability drive replacement cycles.
EPA energy conservation standards and the EU Ecodesign Directive constrain standby power and luminous efficacy thresholds for displays sold in the United States and European markets, directly shaping panel architecture and driver IC selection. China's MIIT enforces GB standards for display energy efficiency while SAMR oversees market access certification, creating multi-jurisdictional compliance burdens for multinational suppliers. REACH and RoHS frameworks in Europe restrict hazardous substance use in organic emitter materials and phosphor compositions, elevating R&D costs for compliant chemistries. Stakeholders must monitor regulatory divergence between energy efficiency mandates and material restriction regimes to anticipate where certification investments will determine market access.
Market Dynamics
Automotive infotainment integration is pulling advanced OLED and Mini-LED architectures into vehicle cabins faster than display fabs can qualify new panel grades for temperature cycling and vibration tolerance.
Growth Catalysts
- Automotive cabin digitization:Tier-1 suppliers specify flexible OLED for curved instrument clusters and passenger entertainment screens.
- China's dual carbon goals:MIIT energy efficiency mandates accelerate factory retrofits and Gen 8.6 OLED line investments.
- MicroLED transfer yield improvements:Laser-induced forward transfer methods resolve die placement precision for commercial signage pilot production.
Market Restraints
- Organic emitter material concentration:UDC and Merck dominate phosphorescent host and dopant supply, creating single-source exposure for OLED panel makers.
- Fine metal mask bottleneck:Japanese and South Korean suppliers control FMM tensioning equipment needed for sub-6-inch RGB OLED deposition.
- EU RoHS and REACH material restrictions:Cadmium-free quantum dot and lead-free solder requirements elevate R&D costs for compliant chemistries.
Strategic Opportunities
- India display manufacturing:PLI scheme incentives attract module assembly and testing investments for domestic smartphone and television brands.
- Transparent OLED retail installations:Department stores and automotive showrooms pilot see-through display walls for augmented product visualization.
- IT OLED penetration:Laptop and monitor brands specify hybrid OLED and tandem stack architectures for high-refresh productivity panels.
Industry Challenges
- Vacuum thermal evaporation technician shortage:OLED deposition engineers with 200mm and 300mm tool experience command premium compensation in South Korea and China.
- Multi-jurisdictional certification timelines:Separate EPA, EU Ecodesign, and China GB efficiency testing extends product launch windows by 8-14 months.
- Legacy LCD fab repurposing costs:Converting amorphous silicon lines to oxide backplane or hybrid OLED requires $2-4 billion per Gen 8.5 site.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LED and OLED Display Market |
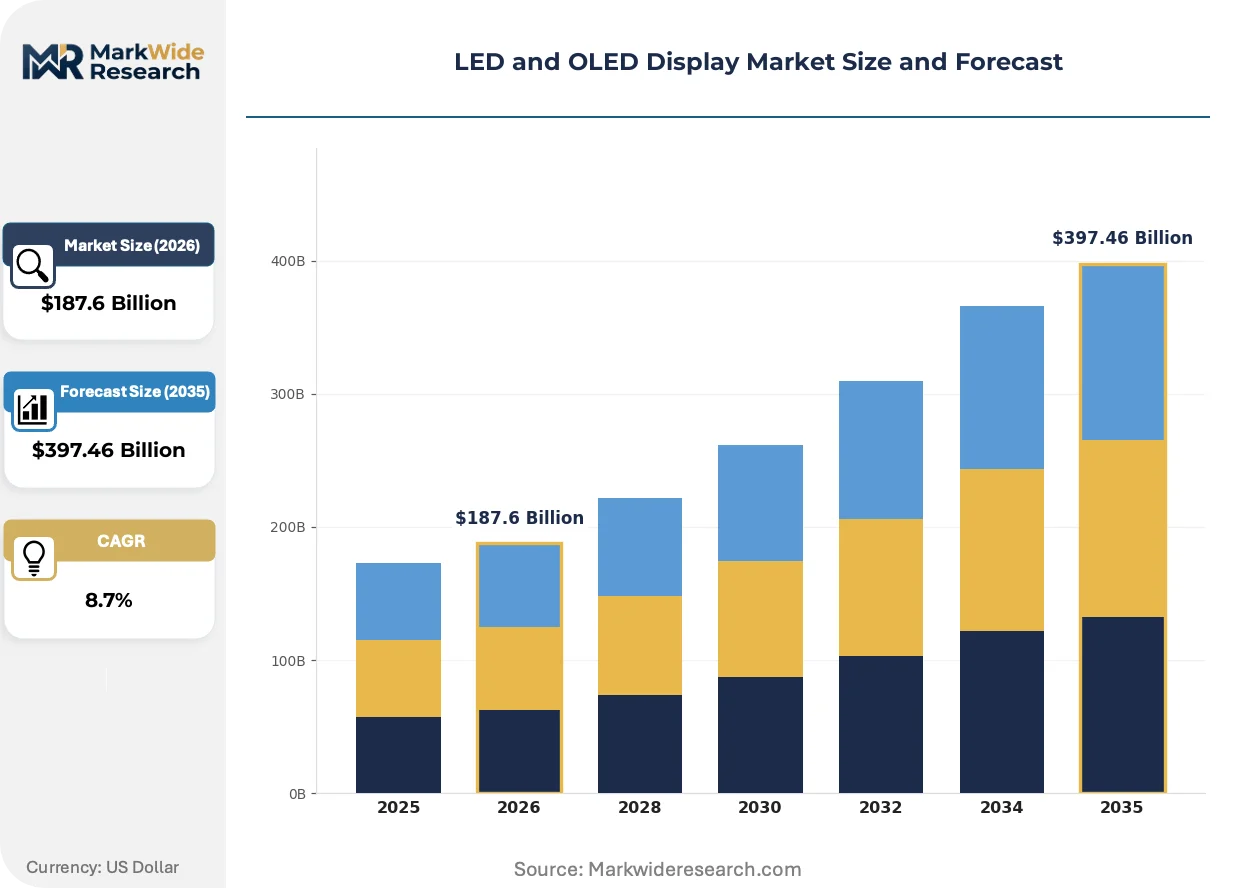
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $397.46 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, OLED, Mini-LED, MicroLED Application: Television, Smartphone, Computer Monitor, Digital Signage End User: Residential, Commercial, Industrial, Government Technology: Active Matrix, Passive Matrix, Quantum Dot, Edge-Lit |
| Companies Covered | Samsung Display, LG Display, BOE Technology, AU Optronics, Sony Corporation, Universal Display Corporation, ams-OSRAM, Nichia, Signify, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LED and OLED Display Market Strategic Shifts
Display technology trajectories are diverging across application tiers as manufacturers place competing bets on deposition methods, substrate materials, and driver integration approaches.
Tandem stack OLED architectures combine two electroluminescent units in series to double luminance efficiency and extend operational lifetime. Automotive HUD and transparent display developers specify these structures for 10,000-nit peak brightness requirements. Tandem OLED is rewriting performance benchmarks for head-mounted displays and aircraft cockpit instrumentation.
EPA energy conservation standards and the EU Ecodesign Directive impose tightening standby power limits and minimum luminous efficacy thresholds for displays sold in North America and Europe. Panel designers eliminate discrete power bricks and integrate GaN driver ICs to meet sub-0.5-watt standby requirements. Television and monitor segments face the steepest compliance cost escalation as regulations phase in through 2027.
Commercial signage buyers are unbundling hardware ownership from content management and field service through subscription-based display-as-a-service contracts. System integrators assume capital risk and refresh cycles while end-users pay per square meter per month. North American retail and quick-service restaurant chains lead this procurement model transition.
LED and OLED Display Market Segmentation
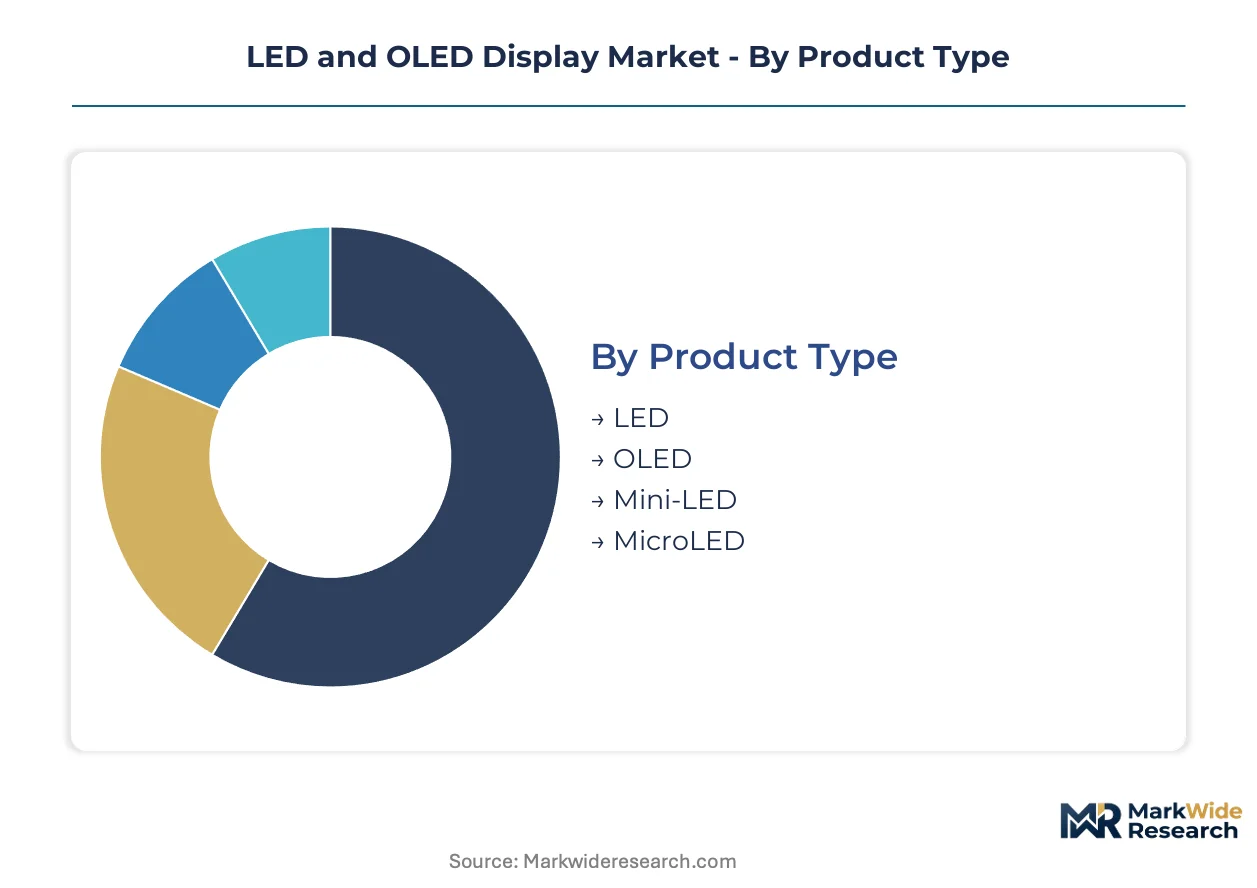
Display technology fragmentation creates distinct margin pools and qualification barriers across product architectures. Panel vendors configure deposition tools, driver ICs, and substrate handling systems differently for each segment, locking in specialization advantages.
Product Type:
Supply concentration in OLED emitter materials and LED epitaxy equipment shapes competitive positioning across the four technology branches.
- OLED:Organic thin-film stacks using vacuum thermal evaporation achieve sub-millisecond response times through pixel-level light control. Smartphone and television brands in South Korea specify these panels where contrast ratio justifies premium unit economics against LCD alternatives.
- LED:Gallium nitride semiconductor diodes on sapphire or silicon carbide substrates deliver high-brightness output for backlighting and direct-view applications. China's display cluster around Shenzhen and Hefei concentrates packaging capacity for commercial signage and residential television backlights.
- Mini-LED:Chip-scale devices below 200 micrometers enable thousands of local dimming zones. Automotive infotainment systems pull these architectures into vehicle cabins faster than fabs can qualify new panel grades for temperature cycling tolerance.
- MicroLED:Sub-50 micrometer dies require laser-induced forward transfer for precise placement. Pilot production lines in Taiwan and the United States focus on commercial signage where brightness durability commands replacement cycle premiums.
Today's leader: OLED. Tomorrow's challenger: MicroLED.
Application:
End-use volume distribution and replacement cycle length determine fab loading and depreciation recovery schedules.
- Television:Large-format panels exceeding 55 inches anchor Gen 8.5 and Gen 10.5 LCD fab utilization, with OLED penetrating premium price tiers through white-OLED and quantum dot-OLED hybrid architectures.
- Smartphone:Flexible and foldable OLED dominates flagship device specifications, with South Korean panel makers supplying Apple and Samsung Electronics from Gumi and Tangjeong cluster capacity.
- Computer Monitor:Gaming and professional productivity segments specify high-refresh OLED and Mini-LED backlighting for color-critical workflows.
- Digital Signage:Commercial deployments prioritize brightness durability and remote manageability, with subscription-based display-as-a-service models realigning hardware lifecycle monetization.
Smartphone panels generate the highest revenue per substrate; television drives the greatest absolute volume.
End User:
Procurement sophistication and total cost of ownership calculation methods diverge sharply across buyer categories.
- Residential:Consumer electronics retailers and e-commerce platforms move inventory through seasonal promotional cycles, with replacement driven by form factor upgrades rather than failure rates.
- Commercial:Quick-service restaurant chains, retail department stores, and corporate campuses specify managed service contracts with 5-7 year refresh commitments.
- Industrial:Factory automation and process control applications demand wide-temperature operation and sunlight readability, favoring high-brightness LED over emissive OLED.
- Government:Public information displays and transportation signage procurement incorporates domestic content requirements and extended warranty terms.
Commercial buyers concentrate margin pools; residential volume enables scale economies.
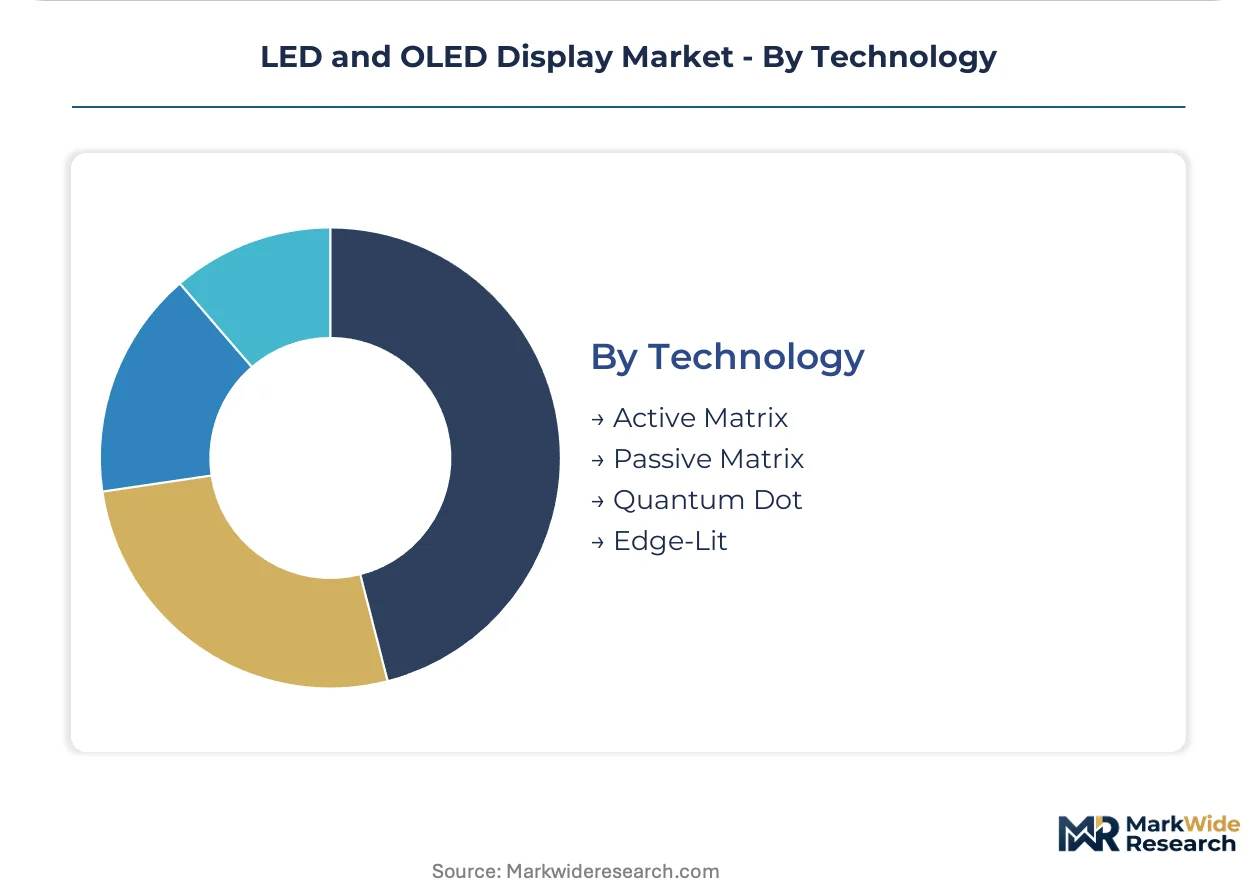
Technology:
Backplane architecture and light management approach define manufacturing equipment requirements and yield learning curves.
- Active Matrix:Thin-film transistor arrays enable individual pixel addressing for high-resolution formats. Oxide semiconductor backplanes from Japan Display and LG Display support OLED and advanced LCD architectures.
- Passive Matrix:Simpler row-column addressing suits low-information-content applications including simple indicators and basic signage where cost minimization dominates.
- Quantum Dot:Cadmium-free or indium phosphide nanocrystal photoluminescent layers enhance color gamut in LCD backlights. Samsung Display and TCL CSOT deploy these in premium television tiers.
- Edge-Lit:LED arrays along panel borders with light-guide plates enable slim form factors in mainstream television and monitor segments where thickness reduction drives consumer preference.
Active Matrix commands the technology investment priority; Quantum Dot represents the steepest expansion trajectory in premium LCD enhancement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting display manufacturing toward jurisdictions with lower compliance costs and stronger subsidy regimes. South Korea and China maintain cost advantages in OLED deposition, while India and Vietnam attract module assembly through production-linked incentives.
China
MIIT energy efficiency mandates under dual carbon goals are accelerating factory retrofits in Hefei and Shenzhen. GB standards for display power consumption now exceed EU Ecodesign thresholds in stringency. BOE Technology and TCL CSOT anchor Gen 10.5 LCD and emerging OLED capacity in the Yangtze River Delta cluster.
South Korea
Samsung Electronics and Apple procurement contracts sustain premium OLED fab utilization in Gumi and Tangjeong. The Ministry of Trade, Industry and Energy (METI) coordinates domestic supply chain security for phosphorescent emitter materials. Display panel exports dominate the country's high-tech manufacturing trade balance.
United States
EPA energy conservation standards and FCC electromagnetic compatibility rules impose 8-14 month certification timelines for television and monitor imports. MicroLED pilot production concentrates in California and Texas near defense and aerospace HUD developers. Commercial signage buyers in Texas and Florida are adopting subscription-based display-as-a-service contracts.
Japan
Fine metal mask tensioning equipment suppliers in Nagoya and Osaka control critical OLED deposition tooling. METI industrial policy supports domestic semiconductor display material production. Japanese equipment makers command premium pricing for vacuum thermal evaporation systems exported to Chinese and South Korean fabs.
India
PLI scheme incentives attract module assembly investments from smartphone and television brands targeting domestic consumption. BIS certification requirements for display energy efficiency are tightening parallel to EU and US trajectories. Tamil Nadu and Uttar Pradesh are emerging as testing and integration hubs for South Asian market supply.
LED and OLED Display Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with captive OLED suppliers commanding premium smartphone panel economics while open-cell LCD vendors compete on scale. The market structures around three tiers: integrated display conglomerates with in-house emitter material development, pure-play panel fabricators dependent on external chemical supply, and equipment-focused technology licensors. Consolidation pressure is mounting as tandem stack OLED and MicroLED architectures demand capital commitments exceeding $4 billion per Gen 8.5 fab conversion. Strategic partnerships between panel makers and automotive Tier-1 suppliers are accelerating cabin display qualification timelines.
Among integrated Korean conglomerates, Samsung Display and LG Display occupy positions as archetypes of captive supply chain control, with the former leveraging oxide backplane expertise and the latter anchoring large-format white-OLED television production. BOE Technology represents the scale-driven Chinese competitor extending Gen 10.5 LCD dominance into emerging OLED lines. These three entities exemplify how geographic clustering around Gumi, Tangjeong, and Hefei creates divergent cost structures for premium versus mainstream panel tiers.
| Leading Market Players |
|---|
| Samsung Display |
| LG Display |
| BOE Technology |
| AU Optronics |
| Sony Corporation |
| Universal Display Corporation |
| ams-OSRAM |
| Nichia |
| Signify |
| Others |
Value Chain & Pricing Dynamics
Tandem stack OLED deposition and laser-induced forward transfer for MicroLED placement are simultaneously rewriting cost economics and concentrating supply among fabs with capital reserves for Gen 8.5 conversions. Panel vendors with captive emitter material development command pricing power as organic phosphorescent host supply tightens under REACH compliance costs.
Pricing Analysis
Distributor margins on commercial digital signage compress as subscription-based display-as-a-service models shift capital risk to system integrators. Three-tier pricing structure across premium, standard, and economy levels separates automotive-grade panels with temperature cycling certification from consumer television SKUs. Cost compression in mainstream LCD tiers intensifies because BOE Technology and TCL CSOT load Gen 10.5 fabs for depreciation recovery. Commercial buyers with managed service contracts show least price sensitivity; residential consumers through e-commerce platforms show most.
Supply Chain Analysis
Phosphorescent emitter material supply rests on Universal Display Corporation and Merck AG concentration in the United States and Germany. Fine metal mask tensioning equipment draws from Japanese suppliers in Nagoya and Osaka. Gallium nitride epitaxy wafers and oxide semiconductor backplanes source from South Korean and Taiwanese foundries. Single-source vulnerability in FMM equipment creates qualification bottlenecks for RGB OLED deposition. Distribution runs through branded panel vendors to Tier 1 automotive suppliers and television OEMs, with open-cell LCD flowing through Shenzhen trading hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LED and OLED Display Market functions as a stable compounder anchored by automotive cabin digitization pulling advanced panel architectures through decade-long vehicle platform cycles.
For Market Incumbents: Cement oxide backplane expertise and tandem stack OLED capacity in South Korea's Gumi and Tangjeong clusters to defend against Chinese Gen 8.6 OLED investments. Deepen captive supply of phosphorescent emitter materials to offset UDC and Merck pricing power. Priority lever sits with qualifying flexible OLED for curved instrument clusters before 2027 EU Ecodesign standby power mandates phase in. For New Entrants and Emerging Players: Quick-service restaurant chains with 5-7 year refresh commitments represent an underserved buyer archetype open to display-as-a-service procurement. Target India PLI scheme module assembly incentives for domestic smartphone brand supply. Pilot transparent OLED retail installations in automotive showrooms offer lowest competitive density. Go-to-market angle: bundle content management software with hardware subscription to assume capital risk. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play panel fabricators without in-house emitter material development. Long-term viability favors integrated conglomerates with backward integration into organic chemistry and vacuum deposition tooling. Acquisition target archetype: equipment-focused technology licensors with laser-induced forward transfer IP. Signal to watch: MicroLED transfer yield crossing commercial signage viability thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Tandem Stack OLED Capacity Expansion | Automotive HUD developers specify these structures for 10,000-nit peak brightness requirements. |
| Backward Integration into Emitter Materials | Captive phosphorescent host production reduces UDC and Merck single-source exposure. |
| Gen 8.5 Fab Conversion to Hybrid OLED | MIIT energy efficiency mandates accelerate oxide backplane retrofits in Hefei and Shenzhen. |
| Display-as-a-Service Platform Launch | North American retail chains unbundle hardware ownership from content management contracts. |
| MicroLED Pilot Production Scale-Up | Taiwan and United States facilities target commercial signage brightness durability premiums. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured deposition tool engineers, automotive Tier 1 procurement leads, commercial signage system integrators, and display fab operations directors. Secondary validation drew from EPA energy conservation standard filings, EU Ecodesign Directive implementation guidance, China MIIT GB standard updates, and SEC 10-K disclosures from panel vendors. Bottom-up substrate throughput estimates and top-down end-use demand aggregation were cross-referenced for triangulation.
Historical reference periods anchored the projection horizon to qualified fab capacity expansions and automotive platform cycle commitments. Segmentation dimensions modeled include display technology, application tier, backplane architecture, and regional regulatory cluster. CAGRs were derived from substrate loading schedules and depreciation recovery assumptions. Forecast inputs incorporated phosphorescent emitter material supply constraints and FMM equipment lead times.
Underlying measurement precision varies by segment; automotive and commercial signage carry tighter precision than residential television given longer replacement cycle visibility. Forecasts reflect assumptions about tandem stack OLED yield learning and MicroLED transfer placement accuracy. Regulatory divergence between EPA, EU Ecodesign, and China GB efficiency mandates, plus organic emitter material supply concentration, warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
UK Outdoor LED Lighting Market
LED
Africa LED Lighting Market
LED
LED Modular Display Market
LED
Brazil LED Market
LED
Global Outdoor LED Lighting Market
LED
Europe LED Lighting Market
LED
Single-Digit 7 Segment LED Displays Market
LED
Japan Outdoor LED Lighting Market
LED
Dot-Matrix LED Displays Market
LED
Surface Mount PLCC Leds Market
LED
Pixel Pitch LED Market
LED
LED Panel Market
LED
Middle East LED Lights Market
LED
Asia Pacific LED Lighting Market
LED
Architectural LED Products Market
LED
Mini LED Market