
 Single-Digit 7 Segment LED Displays Market | 2026-2036
Single-Digit 7 Segment LED Displays Market Size, Share, and Industry Trends Forecast 2026-2036
Single-Digit 7 Segment LED Displays Market Analytics
Buyer concentration among industrial equipment OEMs is realigning procurement volumes toward vendors with certified supply chains. Kingbright leverages vertical integration in LED chip packaging to sustain margin stability across volatile substrate costs. Broadcom anchors its position through proprietary driver IC designs that reduce external component counts. Lite-On Technology Corporation competes on manufacturing scale, operating high-volume SMD lines that service consumer electronics brands across Taiwan and mainland China.
Single-digit 7 segment LED displays are electroluminescent numeric indicators built from seven individually addressable LED bars arranged in a rectangular pattern, typically measuring 0.28 to 2.3 inches in digit height and requiring 5-20 mA per segment for standard brightness. These devices translate binary-coded decimal or serial input signals into visible numerals for human-machine interfaces in equipment where alphanumeric complexity is unnecessary. Common cathode configurations lead unit shipments due to simpler logic-level interfacing with microcontrollers, while automotive dashboard applications represent the fastest-growing end-use as electrified vehicle architectures multiply display nodes. Color type segmentation shows white and red dominant in industrial and automotive qualified products, with blue and green variants occupying premium positions in consumer-facing devices where aesthetic differentiation commands price premiums.
EPA energy efficiency guidelines and EU RoHS substance restrictions constrain phosphor and substrate material selections, forcing reformulation of high-brightness red chips. CE marking and ECHA REACH compliance create dual certification burdens for suppliers accessing European industrial and automotive channels. FDA oversight of medical device displays adds a third regulatory layer for manufacturers targeting patient monitoring instrumentation. Stakeholders must monitor evolving automotive functional safety standards and decide whether to absorb certification costs internally or cede that market to established tier-one display integrators.
Market Dynamics
Industrial equipment OEM procurement consolidation is concentrating order volumes among qualified suppliers with certified supply chains, compressing vendor margins while raising barriers for unqualified competitors.
Growth Catalysts
- Electrified vehicle architectures:Battery-electric and hybrid platforms multiply dashboard display nodes, expanding qualified supplier demand for automotive-grade single-digit indicators.
- REACH compliance differentiation:European material sourcing rules tighten, favoring vendors with pre-certified supply chains over competitors facing reformulation costs.
- Surface-mount device automation:High-volume SMD packaging lines reduce per-unit labor content, enabling cost-competitive scaling for appliance instrumentation clusters.
Market Restraints
- Phosphor cost volatility:Rare-earth phosphor price swings constrain high-brightness red chip formulations, squeezing margins on qualified industrial products.
- Substrate supply concentration:Sapphire and silicon carbide wafer sourcing clusters in East Asian foundries create geographic vulnerability for LED chip fabricators.
- OLED substitution in premium automotive:Flexible organic emitters capture share in luxury electrified vehicle interiors, limiting single-digit LED expansion in high-margin segments.
Strategic Opportunities
- Medical device certification gap:FDA-qualified display suppliers remain scarce for patient monitoring instrumentation, creating premium positioning for compliant vendors.
- EU Green Deal procurement mandates:Public sector industrial equipment tenders increasingly specify energy-efficient display technologies, favoring qualified LED suppliers.
- IoT-enabled predictive maintenance:Smart industrial equipment requires distributed numeric readouts for sensor data visualization, expanding addressable unit demand.
Industry Challenges
- Functional safety certification timelines:Automotive ISO 26262 qualification cycles extend 18-24 months, delaying revenue recognition for new product variants.
- Legacy microcontroller interfacing:Common cathode designs must maintain backward compatibility with installed 8-bit controller architectures, constraining protocol innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single-Digit 7 Segment LED Displays Market |
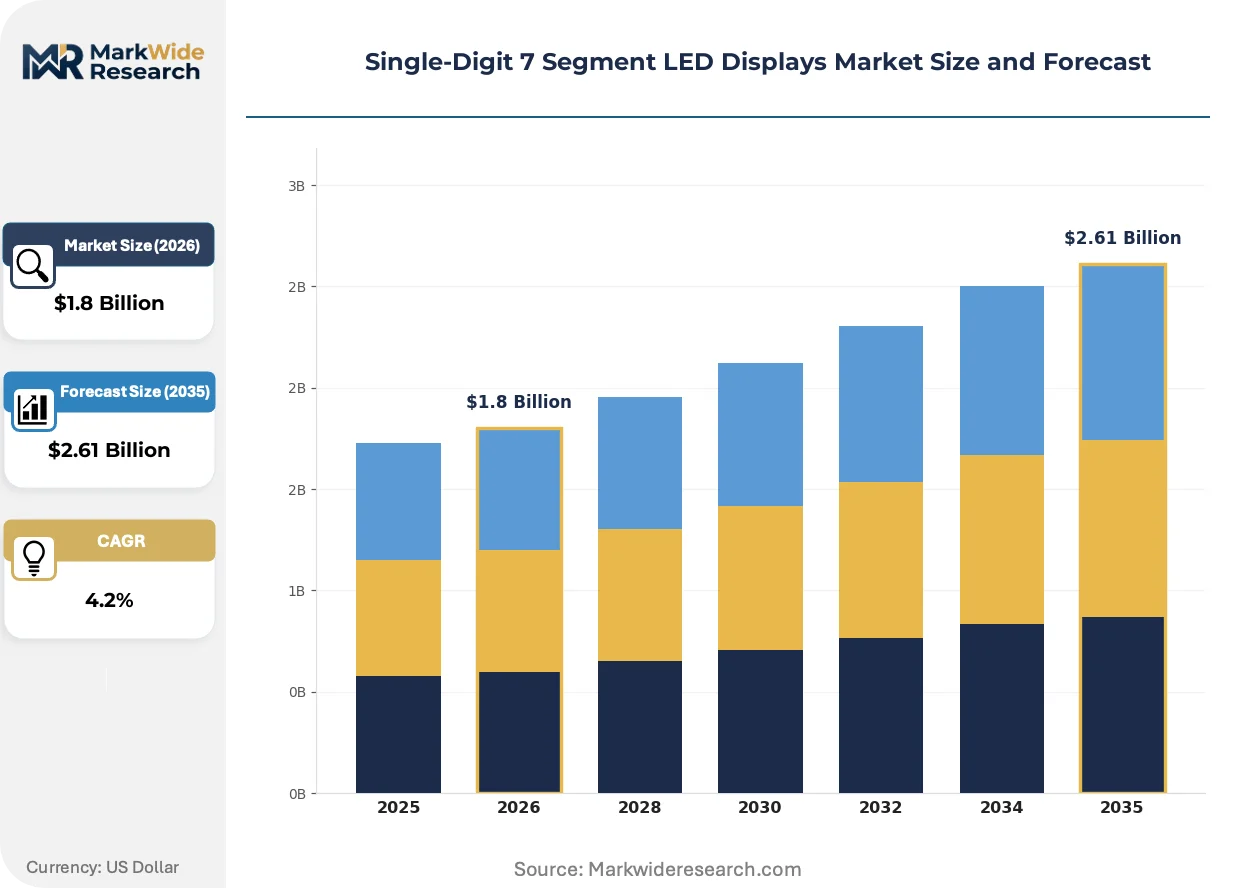
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Common Anode, Common Cathode, Digit Size, Color Type End User: Consumer Electronics, Industrial Equipment, Telecommunication, Automotive Application: Advertising Displays, Measurement Instruments, Consumer Products, Automotive Dashboards Technology: Digital, Analog, Hybrid, Display Technology |
| Companies Covered | Kingbright, Broadcom, Lumex, Visual Communications Company, Lite-On Technology Corporation, Visha, Opteq, Futaba Corporation, Foshan NationStar Optoelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single-Digit 7 Segment LED Displays Market Evolving Landscape
Component miniaturization and regulatory material restrictions are forcing simultaneous redesign of packaging formats and phosphor chemistries across the supplier base.
Chip-on-board (COB) packaging is overtaking traditional lead-frame construction in sub-0.5 inch digit heights, eliminating wire bonds and reducing failure modes in high-vibration automotive environments. Tier-one dashboard integrators in Germany and Japan are specifying COB exclusively for new electrified vehicle platforms. This shift is compressing demand for conventional plastic leaded chip carrier formats among second-tier suppliers.
EU RoHS substance restrictions now cover four additional heavy metals in display phosphor formulations, forcing reformulation of high-brightness red and amber chips. Manufacturers serving European industrial and automotive channels must dual-source compliant phosphor blends or risk channel exclusion. Medical device suppliers face compounded certification burdens as FDA 21 CFR Part 820 quality system requirements layer atop material compliance.
Buyer consolidation among industrial automation OEMs is compressing supplier counts per category, with procurement teams reducing qualified vendor lists from twelve to four participants. Long-term framework agreements now lock in volume commitments and technical roadmaps, displacing spot-market purchasing. This concentration is most visible in German and Japanese factory automation equipment supply chains, where Siemens and Fanuc procurement organizations have completed vendor rationalization programs.
Single-Digit 7 Segment LED Displays Market Segmentation
Segmentation in single-digit 7 segment LED displays reveals how technical configuration choices cascade into divergent supply chain requirements. Procurement teams select segments based on interfacing complexity, regulatory qualification burden, and end-use environmental tolerances.
Product Type:
Integration depth varies sharply across product types, with common cathode designs dominating standalone instrumentation while common anode variants embed more readily into complex multi-digit arrays.
- Common Anode:All segment anodes connect to a shared positive supply, requiring active-low driver logic. This configuration suits multiplexed display arrays in industrial control panels where multiple digits share driver ICs, though microcontroller interfacing demands more complex firmware. Demand concentrates in German factory automation OEMs consolidating procurement around qualified suppliers.
- Common Cathode:Shared negative return path enables direct sourcing from standard microcontroller GPIO pins without external driver components. Simpler logic-level interfacing drives preference in consumer appliance instrumentation clusters across China, where cost minimization overrides driver complexity concerns. REACH-compliant phosphor sourcing tightens for red variants in European automotive qualified products.
- Digit Size:Heights from 0.28 to 2.3 inches span handheld medical devices through factory-floor readouts, with sub-0.5 inch COB packaging displacing lead-frame construction in vibration-critical automotive applications.
- Color Type:White and red dominate industrial and automotive qualified products; blue and green command price premiums in consumer-facing devices where aesthetic differentiation justifies higher BOM costs.
Common cathode leads volumes today; common anode is gaining share fastest in multiplexed industrial systems.
End User:
Cost tier stratification separates premium-qualified automotive and medical applications from price-sensitive consumer electronics procurement.
- Consumer Electronics:High-volume appliance instrumentation in China and Taiwan absorbs standard-grade displays with minimal certification overhead. Lite-On Technology Corporation's SMD lines service this segment through manufacturing scale rather than technical differentiation.
- Industrial Equipment:Factory automation OEMs in Germany and Japan have reduced qualified vendor lists from twelve to four participants, locking in long-term framework agreements with volume commitments. Siemens and Fanuc procurement organizations completed rationalization programs that favor suppliers with certified supply chains and REACH compliance documentation.
- Telecommunication:Network equipment requires extended temperature-range operation, narrowing qualified supplier pools for outdoor infrastructure deployments.
- Automotive:Battery-electric and hybrid platforms multiply dashboard display nodes, with ISO 26262 functional safety qualification cycles extending 18-24 months. Tier-one German and Japanese integrators specify COB packaging exclusively for new electrified vehicle platforms.
Industrial equipment leads volumes today; automotive is expanding most quickly as electrified architectures proliferate.
Application:
Application maturity determines whether segments compete on price or certification-based differentiation.
- Advertising Displays:High-brightness outdoor installations in commercial signage drive demand for amber and red variants with enhanced thermal management.
- Measurement Instruments:Laboratory and field equipment demands precision optical matching across digit uniformity, favoring suppliers with in-house phosphor blending capabilities. FDA 21 CFR Part 820 quality system requirements layer atop material compliance for patient monitoring instrumentation, creating scarce qualified supplier positions.
- Consumer Products:Appliance interfaces prioritize cost minimization over optical performance, sourcing through high-volume SMD lines with minimal customization.
- Automotive Dashboards:Functional safety requirements and vibration tolerance specifications exclude unqualified competitors, with OLED substitution capturing share in luxury vehicle interiors.
Consumer products leads volumes today; measurement instruments is climbing the fastest on medical device certification scarcity.
Technology:
Technology segments reflect supply concentration in driver IC design and packaging automation.
- Digital:Binary-coded decimal and serial input protocols dominate new designs, with proprietary driver ICs from Broadcom reducing external component counts in qualified automotive applications.
- Analog:Legacy voltage-level interfacing persists in retrofit industrial installations where microcontroller replacement is uneconomical.
- Hybrid:Mixed-signal approaches bridge analog sensor outputs to digital display inputs in process control instrumentation.
- Display Technology:COB packaging overtakes lead-frame construction in sub-0.5 inch heights, eliminating wire bonds for high-vibration automotive environments.
Digital leads volumes today; display technology is gaining share fastest on COB adoption in electrified vehicles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Germany, Japan, and Taiwan anchor display driver IC design and packaging automation expertise for this electroluminescent component category.
Germany
Siemens and Fanuc procurement organizations drive demand consolidation for factory automation instrumentation. ECHA REACH compliance documentation requirements filter supplier participation in industrial channels. Bavaria's automotive tier-one cluster around Munich specifies chip-on-board packaging for electrified vehicle dashboard programs.
China
Domestic appliance manufacturing in Guangdong and Zhejiang provinces absorbs high volumes of common cathode displays for cost-sensitive interfaces. MIIT GB standards and dual carbon goals reshape phosphor sourcing rules for export-qualified production. Shenzhen's SMD packaging ecosystem services consumer electronics brands with compressed lead times.
Japan
Tier-one automotive integrators in Nagoya and Tokyo metropolitan areas multiply display nodes for battery-electric platforms. METI industrial standards and JIS certification protocols extend qualification timelines for new product variants. Kyushu's semiconductor packaging corridor specializes in high-reliability COB construction for vibration-critical applications.
United States
FDA 21 CFR Part 820 quality system requirements create scarce supplier positions for patient monitoring instrumentation. EPA energy efficiency guidelines constrain phosphor formulations in high-brightness red chips. Texas and California medical device clusters source qualified displays through validated supply chain documentation.
Taiwan
Lite-On Technology Corporation's manufacturing scale anchors SMD line capacity for consumer electronics brands. The island's semiconductor packaging ecosystem supports backward integration into LED chip fabrication. Hsinchu Science Park concentrates driver IC design talent serving multiplexed industrial display arrays.
Single-Digit 7 Segment LED Displays Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across three discernible tiers. The vendor base compresses around qualified suppliers with certified supply chains as industrial OEM procurement rationalization proceeds. Strategic archetypes include vertical integrators controlling substrate-to-package workflows, driver IC designers reducing external component counts, and high-volume SMD fabricators competing on manufacturing scale. Dominant competitive moves encompass long-term framework agreements locking in volume commitments and COB packaging transitions displacing legacy lead-frame formats.
Among the named participants, Kingbright exemplifies vertical integration through captive LED chip packaging capabilities. Broadcom occupies a position anchored in proprietary semiconductor designs that streamline system-level integration. Lite-On Technology Corporation represents scale-driven manufacturing archetypes operating high-volume surface-mount device lines.
| Leading Market Players |
|---|
| Kingbright |
| Broadcom |
| Lumex |
| Visual Communications Company |
| Lite-On Technology Corporation |
| Visha |
| Opteq |
| Futaba Corporation |
| Foshan NationStar Optoelectronics |
| Others |
Value Network & Pricing Analysis
Semiconductor packaging specialists concentrated in Taiwan and Japan create labor-cost differentials that widen spreads between premium automotive-qualified displays and economy-grade consumer electronics units. These workforce clusters anchor tiered pricing structures where certification burden and phosphor sourcing transparency separate contract values.
Pricing Analysis
Bundled driver IC and display module offerings command premiums against unbundled component sourcing common in high-volume appliance manufacturing. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 26262 qualification status and REACH phosphor documentation completeness. Cost compression in standard-grade industrial tiers intensifies as Chinese SMD fabricators absorb excess capacity. Consumer electronics OEMs in Guangdong exhibit highest price sensitivity, while German automotive tier-ones prioritize qualification reliability over unit economics.
Supply Chain Analysis
Workforce availability constraints in Kyushu's semiconductor packaging corridor and Shenzhen's SMD ecosystem concentrate high-reliability COB production in Japan while consumer-grade volume manufacturing clusters in China. Sapphire and silicon carbide wafer supply draws from Taiwanese and Korean foundries, with rare-earth phosphor blending anchored in Chinese processing facilities. Single-source vulnerability in automotive-qualified COB substrates creates geographic concentration risk. Distribution runs through authorized component distributors serving qualified industrial channels alongside direct OEM contracts for high-volume consumer appliance programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where procurement consolidation among industrial OEMs shifts demand toward premium-certified suppliers with documented REACH compliance and functional safety qualifications.
For Market Incumbents: Anticipate OLED substitution pressure in luxury automotive interiors by deepening COB packaging capabilities for electrified vehicle platforms. Accelerate FDA 21 CFR Part 820 quality system certification to capture scarce supplier positions in patient monitoring instrumentation. Lock in multi-year phosphor supply agreements before rare-earth price volatility squeezes qualified product margins.
For New Entrants and Emerging Players: Capture the medical device certification gap where qualified display suppliers remain scarce for patient monitoring applications. Penetrate EU Green Deal procurement mandates by positioning energy-efficient LED technologies for public sector industrial equipment tenders. Pursue partnership-based go-to-market models with established tier-one dashboard integrators rather than direct OEM qualification.
For Investors and Strategic Acquirers: Automotive tier-one electronics suppliers are the most active acquirer in this space, seeking captive display capabilities for electrified platform integration. Five-to-ten year viability hinges on functional safety certification depth and backward integration into phosphor formulation. Monitor ISO 26262 qualification cycle completion rates as inflection indicator for revenue recognition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| COB Packaging Transition | Eliminates wire bond failure modes in high-vibration automotive environments per German tier-one specifications. |
| REACH Phosphor Reformulation | Secures European industrial channel access as ECHA tightens heavy metal restrictions in display formulations. |
| FDA Quality System Certification | Creates scarce supplier positioning for patient monitoring instrumentation in Texas and California medical clusters. |
| Long-Term Framework Agreements | Locks volume commitments with Siemens and Fanuc procurement organizations completing vendor rationalization. |
| Driver IC Proprietary Development | Reduces external component counts in qualified automotive applications per Broadcom's established approach. |
Research Methodology
Bottom-up appliance and automotive instrumentation modeling reconciled against top-down LED chip and driver IC supply tracking forms the analytical core of this study. Primary interviews with display procurement managers at industrial automation OEMs, Tier 1 automotive electronics integrators, and medical device quality assurance directors combined with secondary validation from ECHA substance restriction databases, FDA 510(k) filing records, and MIIT GB standard publications. Triangulation across these sources calibrated segment-level volume estimates.
Input-output matrices mapped common cathode and common anode configurations against digit height, color type, and end-use qualification tiers across the projection horizon. Segmentation dimensions encompassed product type integration depth, end-user cost tier stratification, application maturity, and display technology packaging format. CAGRs derived from regression analysis of historical procurement volume patterns and forward-looking OEM platform roadmaps, with automotive electrification adoption curves and medical device certification timelines as industry-specific forecast inputs.
Rare-earth phosphor price volatility, automotive functional safety certification delays, and OLED substitution acceleration in premium vehicle interiors are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding procurement consolidation trajectories and regulatory enforcement intensity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Thailand LED Market
LED
UK Outdoor LED Lighting Market
LED
Superluminescent Diodes Market
LED
LED Light Bar Market
LED
Japan LED Market
LED
Chip on Board LED Market
LED
LED Panel Market
LED
Dual-Digit 7 Segment LED Displays Market
LED
UV LED Market
LED
Mini LED Market
LED
Europe Outdoor LED Lighting Market
LED
Led Video Walls Market
LED
North America LED Packaging Market
LED
Small Pitch LED Display Market
LED
Saudi Arabia LED Lights Market
LED
Japan Indoor LED Lighting Market