
 Africa LED Lighting Market | 2026-2036
Africa LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Africa LED Lighting Market Outlook
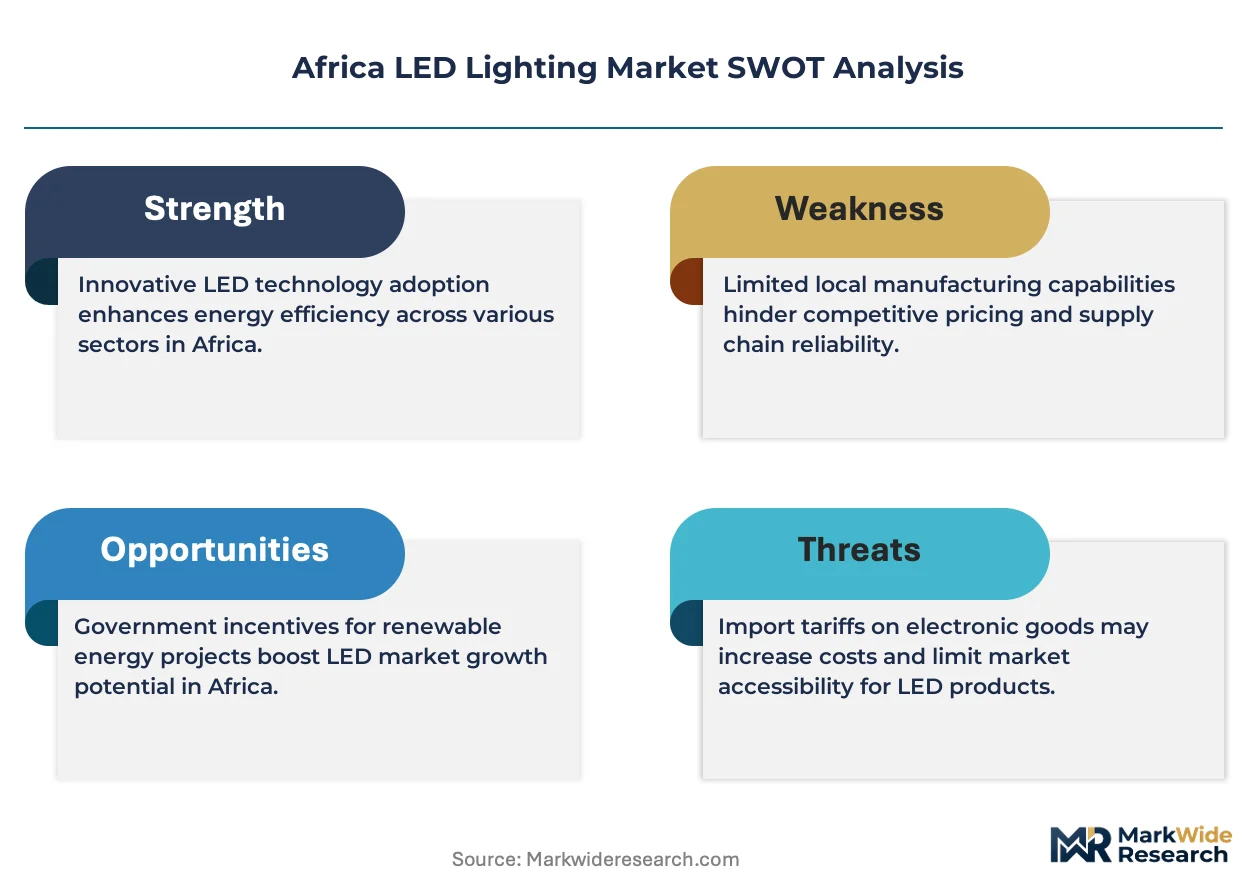
High-efficacy tier certification above 130 lumens per watt is collapsing the cost barrier between premium imports and local assembly. Signify N.V. leverages its Cape Town distribution hub to sustain last-mile coverage across Southern Africa. ams-OSRAM AG anchors component supply for regional fixture assemblers. Unilumin competes on project scale in Nigeria's federal road lighting tenders.
Africa LED Lighting comprises solid-state illumination devices using gallium nitride semiconductors that convert electrical current into visible light at efficiencies exceeding traditional fluorescent and incandescent technologies, typically operating at color temperatures between 2700K and 6500K with rated lifespans of 25,000 to 50,000 hours. These systems serve commercial, industrial, and public infrastructure applications where grid reliability varies and operational cost minimization drives procurement decisions. Solar LED technology leads technology segment growth where grid extension proves uneconomical, while smart lighting remains concentrated in South African commercial property retrofits. Bulbs dominate product type volume through mass-market retail channels, though panels capture disproportionate margin in corporate fit-out specifications.
South Africa's SABS enforces compulsory energy performance standards that restrict import of non-compliant luminaires, while Nigeria's SON certification requirements create procedural friction for unregistered suppliers. Kenya's EPRA regulates off-grid solar-integrated products through quality verification protocols that shape distributor inventory decisions. Stakeholders must weigh certification cost recovery against margin compression from informal channel competition.
Market Dynamics
Falling lithium-ion battery costs are compressing the payback period for solar-LED hybrid installations, redirecting procurement volumes from grid-dependent fixtures toward autonomous systems across Nigeria's commercial corridor and Kenya's agricultural processing zones.
Growth Catalysts
- SABS energy efficiency labeling:South Africa's compulsory standards restrict non-compliant luminaire imports, forcing quality upgrades across distributor inventories and accelerating local assembly investments.
- Street lighting retrofits:Municipal procurement volumes in Lagos, Nairobi, and Cairo are consolidating demand for high-efficacy fixtures above 130 lumens per watt.
- Gallium nitride semiconductors:These materials enable solid-state illumination efficiencies that collapse operational cost barriers between premium imports and regional assembly operations.
Market Restraints
- SON certification friction:Nigeria's Standards Organisation registration requirements create procedural delays that disadvantage unregistered suppliers and compress margins for formal channel participants.
- Informal channel competition:Unregulated imports through cross-border trading posts in West Africa undercut certified product pricing and erode warranty-backed service models.
- Grid reliability variance:Erratic power supply in secondary cities forces buyers toward higher-cost solar-hybrid configurations despite lower upfront budgets.
Strategic Opportunities
- EPRA quality verification:Kenya's Energy and Petroleum Regulatory Authority protocols for off-grid solar-integrated products create first-mover advantages for compliant distributors.
- Smart lighting convergence:IoT-enabled controls and LED fixtures are merging in South African commercial property retrofits, opening recurring revenue streams through managed service contracts.
- Agricultural processing zones:Post-harvest facilities in Kenya's Rift Valley and Nigeria's Kaduna corridor remain underpenetrated for task-optimized LED installations.
Industry Challenges
- Certification timeline compression:Multiple national standards bodies across the continent require parallel testing regimes that extend product launch cycles and strain quality assurance budgets.
- Technical integration complexity:Legacy fluorescent infrastructure in existing commercial buildings demands specialized retrofit engineering that qualified installation contractors struggle to supply at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa LED Lighting Market |
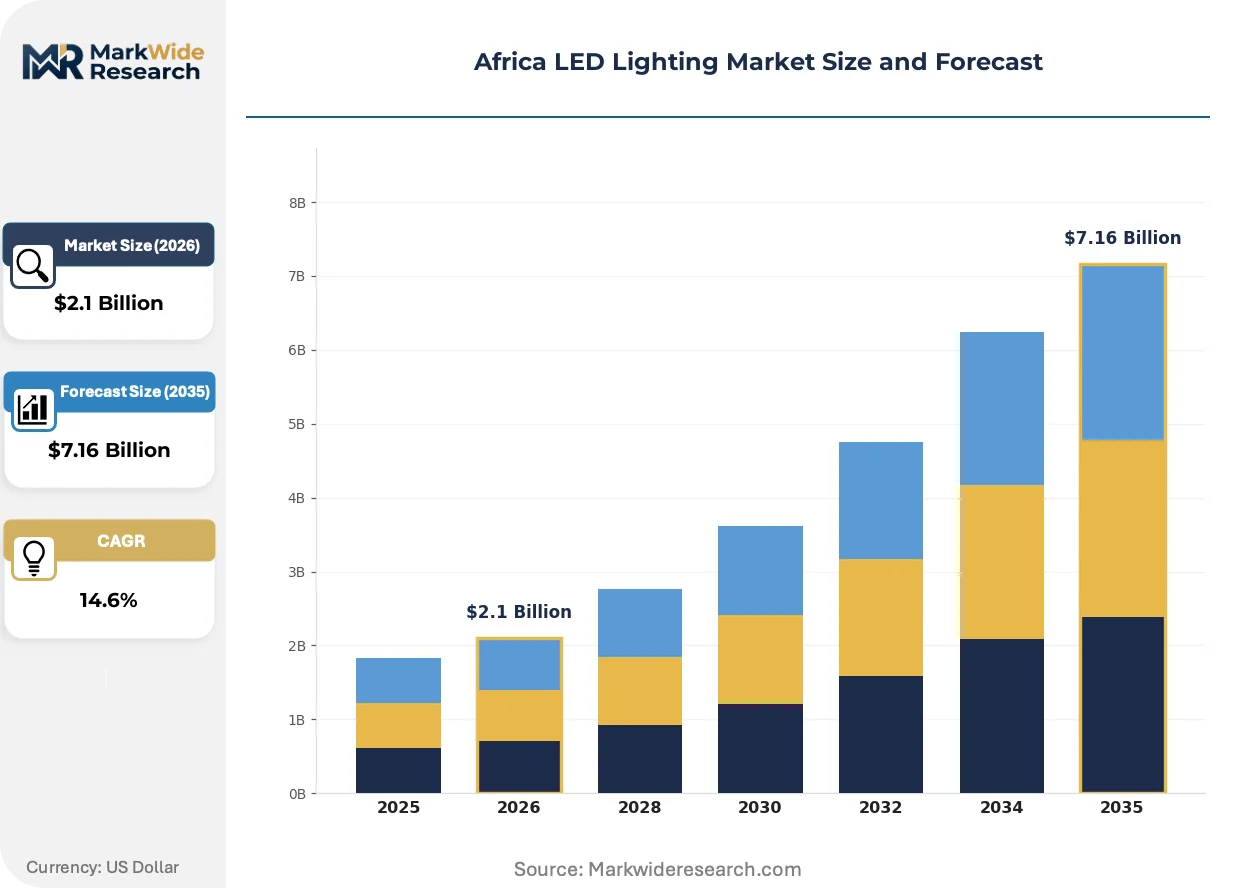
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $7.16 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulbs, Fixtures, Strips, Panels Application: Residential, Commercial, Industrial, Outdoor Technology: Smart Lighting, Solar LED, Linear LED, RGB LED End User: Retailers, Manufacturers, Government, Contractors |
| Companies Covered | Eaton Corporation plc, Panasonic Holdings Corp, Signify N.V., Cree, Inc., GE Lighting, ams-OSRAM AG, Zumtobel Group AG, Unilumin, Acuity Brands, Inc., Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa LED Lighting Market Strategic Shifts
Driver electronics and optical components are compressing into smaller form factors while maintaining thermal performance, enabling fixture designs that reduce material costs and expand application flexibility across constrained installation environments.
Chip-on-board LED arrays are miniaturizing the thermal management footprint for high-output street luminaires. Municipal engineers in Cairo and Lagos are specifying these compact engines for retrofit housings that cannot accommodate conventional heat-sink geometries. The reduced mechanical complexity is lowering landed costs for containerized shipments and accelerating deployment timelines on federal road tenders.
South Africa's SABS has tightened efficacy thresholds for imported luminaires, effectively delisting products below 90 lumens per watt from formal distribution channels. Regional assemblers are responding by sourcing higher-grade LED engines from compliant component suppliers and establishing captive testing laboratories to accelerate pre-shipment verification. This regulatory escalation is concentrating procurement authority among distributors with established certification relationships.
Buyer preference is hardening around total-cost-of-ownership metrics rather than upfront fixture pricing. Facility managers in Nairobi's commercial districts are demanding rated lifespan documentation and lumen maintenance curves before tender submission. This specification discipline is displacing low-bid procurement models and rewarding suppliers with verified performance data and local service presence.
Africa LED Lighting Market Segmentation
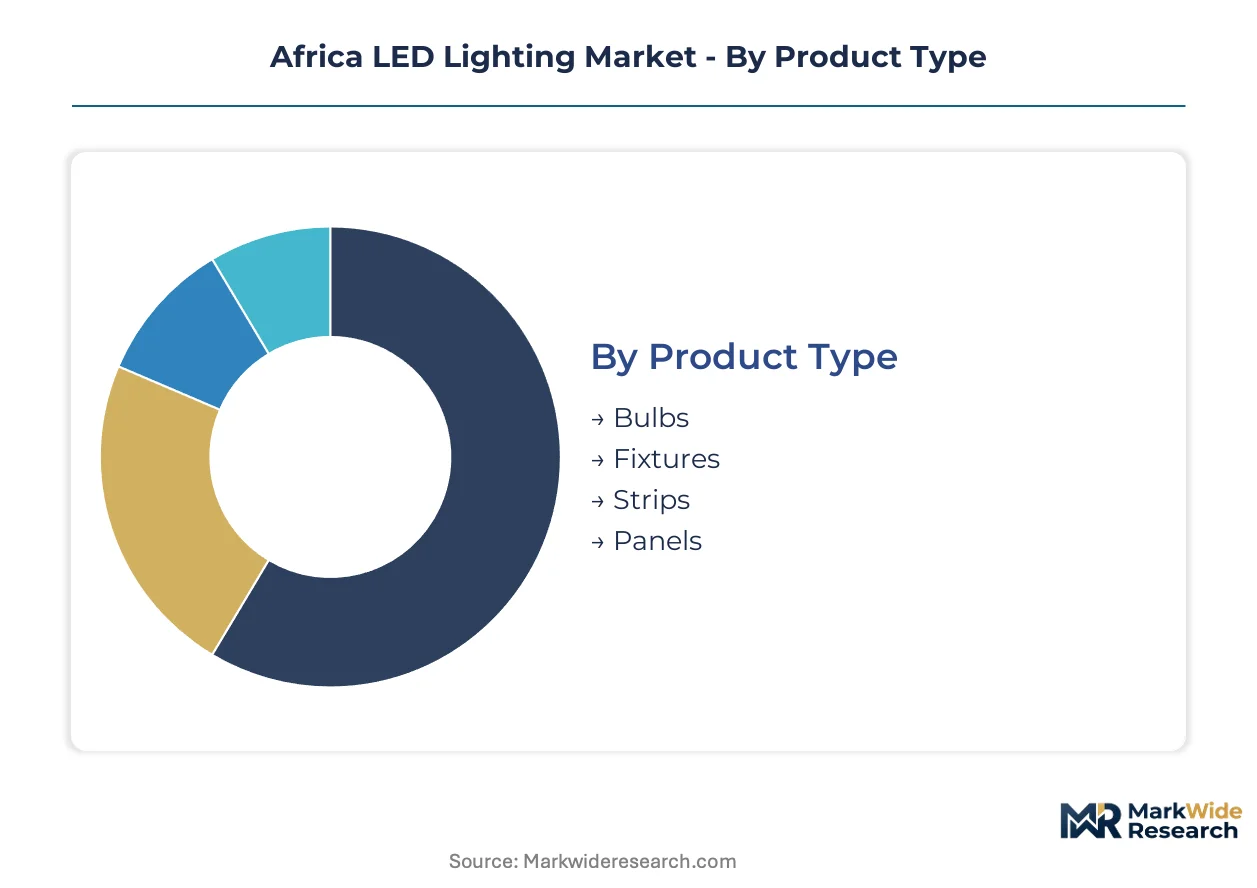
Segmentation in the Africa LED Lighting Market reveals how procurement authority fragments across formal tender channels, informal retail networks, and direct contractor relationships. Each dimension exposes distinct margin structures and certification requirements that shape supplier strategy.
Product Type:
Channel mix varies sharply by product form factor, with mass-market retail driving high-volume bulb sales while specification-grade panels flow through project engineering firms.
- Bulbs:Standard A19 and E27 base configurations dominate unit volume through hardware retailers and electrical wholesalers across Lagos, Nairobi, and Johannesburg. SON certification requirements in Nigeria and SABS labeling in South Africa filter informal imports, compressing margins for unregistered distributors.
- Fixtures:Downlights, high-bays, and floodlight housings command project-based procurement through lighting design consultants and MEP contractors. Municipal street lighting retrofits in Cairo and federal road tenders in Nigeria concentrate demand for IP65-rated outdoor housings.
- Strips:Flexible linear arrays serve architectural accent and cove lighting applications through specialist lighting dealers.
- Panels:Recessed and surface-mounted flat panels capture corporate fit-out specifications in Nairobi's commercial districts and Cape Town office retrofits.
By volume, Bulbs leads. By growth pace, Panels is ahead.
Application:
Cost tier stratification separates premium specification-grade installations from economy replacements, with solar-hybrid configurations commanding price premiums in off-grid contexts.
- Residential:Grid-connected household replacements and off-grid solar home systems drive divergent product requirements. Kenya's Rift Valley agricultural communities favor pay-as-you-go solar LED kits distributed through rural agent networks.
- Commercial:Office retrofits, retail fit-outs, and hospitality lighting demand efficacy documentation and lumen maintenance guarantees. South African property managers specify smart controls alongside LED fixtures to capture demand-response tariffs.
- Industrial:High-bay warehouses and processing facilities require 50,000-hour rated lifespans and high color rendering indices for quality control environments.
- Outdoor:Street lighting, perimeter security, and area illumination face harsh thermal and moisture conditions that accelerate driver electronics failure.
Commercial captures the highest absolute spend. Residential is expanding most quickly.
Technology:
Volume concentration favors mature linear and basic LED configurations, while emerging segments reshape competitive positioning through integrated system sales.
- Smart Lighting:IoT-enabled fixtures with occupancy sensing and daylight harvesting concentrate in South African commercial property retrofits. Managed service contracts create recurring revenue streams for systems integrators.
- Solar LED:Autonomous off-grid systems with lithium-ion battery storage are displacing grid-dependent fixtures across Nigeria's commercial corridor and Kenya's agricultural processing zones. EPRA quality verification protocols in Kenya shape distributor inventory decisions.
- Linear LED:T8 and T5 tube replacements dominate retrofit volume in existing fluorescent infrastructure.
- RGB LED:Color-tunable systems serve architectural and entertainment applications through specialist specification channels.
Linear LED leads by installed base. Solar LED shows the steepest expansion trajectory.
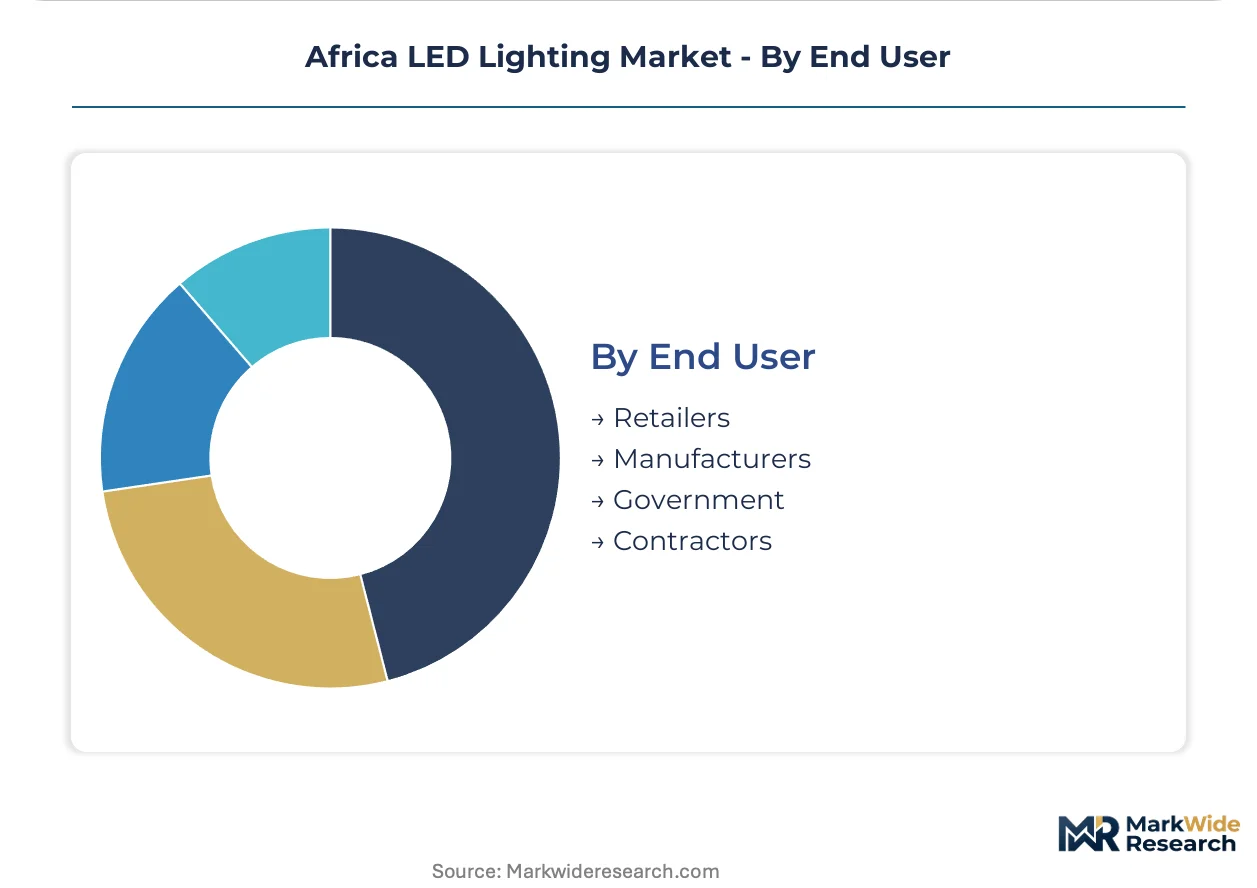
End User:
Customer type determines procurement discipline, with government tenders enforcing strict certification compliance while contractor channels prioritize availability and credit terms.
- Government:Municipal procurement offices in Lagos, Nairobi, and Cairo consolidate street lighting demand through competitive bidding with efficacy thresholds above 130 lumens per watt. Registration requirements with national standards bodies extend vendor qualification timelines.
- Contractors:Electrical installation firms serving commercial and industrial projects demand local inventory availability and technical support. Cape Town and Johannesburg distribution hubs sustain last-mile coverage for Southern African project sites.
- Retailers:Hardware chains and electrical wholesalers manage high-volume bulb inventories with thin margins.
- Manufacturers:Regional fixture assemblers source LED engines and driver components from compliant component suppliers.
Contractors move the highest product volume. Government is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component supply and distribution infrastructure concentrate in Southern Africa, with assembly operations radiating toward East and West African demand clusters. National certification regimes fragment procurement channels and reshape inventory positioning across the continent.
South Africa
Commercial property retrofits in Cape Town and Johannesburg drive specification-grade panel demand. The country's national standards body enforces compulsory energy efficiency labeling that restricts non-compliant luminaire imports. Regional assemblers source LED engines through compliant component suppliers and establish captive testing laboratories to accelerate verification timelines.
Nigeria
Federal road lighting tenders and off-grid commercial corridor installations consolidate procurement volumes. The Standards Organisation registration requirements create procedural friction that disadvantages unregistered suppliers. Lagos municipal procurement offices enforce efficacy thresholds above 130 lumens per watt for street lighting retrofits.
Kenya
Agricultural processing zones in the Rift Valley and pay-as-you-go solar home systems drive divergent product requirements. The Energy and Petroleum Regulatory Authority regulates off-grid solar-integrated products through quality verification protocols. Nairobi commercial districts exhibit hardened buyer preference around total-cost-of-ownership metrics and lumen maintenance documentation.
Egypt
Municipal street lighting retrofits in Cairo consolidate demand for compact chip-on-board LED arrays in legacy retrofit housings. Federal tender specifications emphasize reduced mechanical complexity to lower landed costs for containerized shipments. Nile Delta industrial zones remain underpenetrated for task-optimized LED installations in processing facilities.
Ghana
Grid extension projects and commercial building stock retrofits shape fixture demand patterns. National electrification programs channel procurement toward high-efficacy configurations that minimize operational cost burdens. Accra-Tema metropolitan corridor concentrates distribution infrastructure for last-mile coverage to secondary cities.
Africa LED Lighting Market Competitive Environment
Concentration sits with diversified electronics conglomerates and specialized lighting manufacturers that maintain regional distribution hubs and certification relationships. The competitive structure tiers across premium specification-grade suppliers, mid-market regional assemblers, and economy-oriented import channels. Three archetypes dominate: multinational lighting specialists with captive distribution networks, component suppliers anchoring regional fixture assembly, and project-scale specialists competing on tender volume. Dominant competitive moves include strategic partnerships with national standards bodies to accelerate certification timelines, and geographic expansion through distribution hub establishment in secondary cities.
Among diversified electronics conglomerates, Eaton Corporation plc and Panasonic Holdings Corp occupy positions that span electrical infrastructure and consumer lighting portfolios. Signify N.V. and ams-OSRAM AG represent contrasting archetypes within the lighting value chain—one anchored in downstream distribution and fixture integration, the other in upstream component supply for regional assemblers. Unilumin exemplifies the project-scale specialist competing on federal road tender volume in West African markets.
| Leading Market Players |
|---|
| Eaton Corporation plc |
| Panasonic Holdings Corp |
| Signify N.V. |
| Cree, Inc. |
| GE Lighting |
| ams-OSRAM AG |
| Zumtobel Group AG |
| Unilumin |
| Acuity Brands, Inc. |
| Others |
Value Chain & Pricing Dynamics
Ninety-day container lead times from Asian component hubs to Lagos and Mombasa concentrate inventory carrying costs among distributors with established SABS and EPRA certification relationships, compressing margin buffers for unregistered competitors and amplifying pricing power for compliant channel captains.
Pricing Analysis
SABS energy efficiency labeling dictates the pricing tier structure across Southern African distribution channels. Three-tier pricing structure across premium, standard, and economy levels separates specification-grade panels with lumen maintenance guarantees from basic bulb replacements and uncertified informal imports. Price differentiation rests on certification grade and volume scale, with municipal tender volumes commanding contract-based long-term offtake terms. Cost compression in the economy tier is intensifying because cross-border trading posts in West Africa undercut formal channel pricing. Retailers serving residential replacements exhibit highest price sensitivity, while government procurement offices demonstrate lowest sensitivity due to total-cost-of-ownership mandates.
Supply Chain Analysis
China and South Korea anchor gallium nitride semiconductor wafer fabrication and LED engine production for African-bound shipments. The regional supply chain draws from lithium-ion battery cell manufacturing in China and driver electronics assembly in Malaysia and Vietnam. Single-source vulnerability concentrates in gallium nitride substrate supply, where limited qualified suppliers extend qualification timelines for regional assemblers. Distribution runs through Cape Town and Johannesburg hubs for Southern Africa, with Lagos and Nairobi serving as secondary consolidation points for West and East African corridors respectively.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where national standards body relationships create certification barriers that compound over successive product launch cycles and concentrate procurement authority among established distributors.
For Market Incumbents: Fortify certification moats by deepening captive testing laboratory investments in Cape Town and Lagos to compress pre-shipment verification timelines below competitor thresholds. Channel control through exclusive distributor agreements in Kenya's Rift Valley agricultural processing zones limits emerging entrant access to high-growth solar-LED segments. Capacity addition in Nairobi and Accra distribution hubs reinforces last-mile coverage against project-scale specialists competing on federal tender volume. For New Entrants and Emerging Players: Anchor in Kenya's pay-as-you-go solar home system channel, where EPRA quality verification protocols have displaced informal competitors and created compliant distributor acquisition opportunities. Agricultural processing zones in Nigeria's Kaduna corridor and Egypt's Nile Delta remain underpenetrated for task-optimized LED installations with lumen maintenance guarantees. Direct contractor relationships with MEP firms bypass incumbent distributor margin capture and accelerate specification-grade panel penetration in Nairobi commercial fit-outs. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electronics conglomerates with underperforming lighting divisions lacking Africa-specific certification infrastructure and distribution relationships. Long-term viability centers on regulatory entrenchment depth rather than manufacturing scale, favoring targets with established SABS, SON, and EPRA registration portfolios. The signal to watch is municipal tender specification hardening around total-cost-of-ownership metrics and lumen maintenance documentation requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Laboratory Investment | Captive SABS and SON testing capabilities compress product launch cycles versus outsourced verification. |
| Distribution Hub Expansion | Secondary city presence in Accra and Dar es Salaam captures agricultural processing zone procurement volumes. |
| Solar-LED System Integration | Lithium-ion battery supply agreements with Chinese cell manufacturers secure hybrid system cost positions. |
| Smart Lighting Platform Partnership | IoT control integration with South African property managers opens recurring managed service revenue streams. |
| Regional Fixture Assembly Joint Venture | Local content requirements in Nigerian federal tenders favor assembly operations over pure import models. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with municipal procurement officers, lighting design consultants, MEP contractors, and regional distributor inventory managers; and secondary validation through SABS efficacy threshold documentation, EPRA quality verification protocols, SON registration filings, and customs trade data on LED engine and driver electronics imports. Bottom-up triangulation across segment-level procurement volumes and top-down reconciliation with national electrification program disclosures anchored market sizing.
Across the analysis window, the forecasting framework modeled product type segmentation by channel margin structure, technology segmentation by grid reliability variance, and application segmentation by buyer procurement discipline. CAGRs were derived from municipal tender pipeline analysis and solar-LED hybrid payback period compression trajectories. Key inputs included lithium-ion battery cost curves, national standards body regulatory escalation timelines, and informal channel import volume estimates through cross-border trading post monitoring.
Underlying assumptions cover continued SABS efficacy threshold tightening and EPRA quality verification protocol expansion, with deviation risk concentrated in abrupt tariff shifts on Chinese LED engine imports and accelerated informal channel penetration through unmonitored border crossings. Recalibration cycles align with material shifts in national standards body regulatory schedules and municipal tender award patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
China LED Lighting Market
LED
LED Encapsulation Market
LED
Middle East LED Lights Market
LED
Outdoor LED Display Market
LED
LED Modular Display Market
LED
Microled Market
LED
North America LED Lighting Market
LED
Mini LED Display Market
LED
High-Intensity LED Logo and Livery Lighting Systems Market
LED
Germany Outdoor LED Lighting Market
LED
Thailand LED Market
LED
North America Commercial LED Lighting Market
LED
US LED Downlight Market
LED
India LED Lighting Market
LED
Bluetooth LED Bulb Market
LED
North America LED Packaging Market