
 Global Display Panel Market | 2026-2036
Global Display Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Global Display Panel Market Analysis
South Korea is rewriting capacity dynamics across the Global Display Panel Market as domestic fabs expand Gen 8.5 and Gen 10.5 OLED lines. Samsung Display leverages vertical integration into organic emitter deposition to sustain technology leadership in mobile OLED panels. BOE Technology Group anchors Chinese supply through massive Gen 10.5 LCD and emerging OLED investments in Hefei and Wuhan. LG Display competes via differentiated white-OLED architectures for television and premium monitor applications.
Display panels are optoelectronic devices comprising thin-film transistor backplanes, color filter arrays, and emissive or liquid-crystal layers engineered to render visual information at resolutions spanning HD to 8K, serving as human-machine interfaces across consumer, automotive, and industrial systems. LCD retains volume dominance in cost-sensitive television and monitor segments where manufacturing scale and mature supply chains preserve margin pools. OLED captures premium value in smartphones and emerging automotive applications where flexible form factors and superior contrast ratios command pricing power. QLED and Mini LED technologies occupy intermediate positioning by enhancing LCD performance through quantum dot emission layers and dense local dimming zones.
The EU Ecodesign Framework and REACH chemical restrictions shape material selection and recyclability requirements for panels sold across Europe, while South Korea's Ministry of Trade, Industry and Energy enforces domestic content rules and R&D tax incentives that steer capital allocation. China's Ministry of Ecology Environment implements dual carbon targets that elevate energy efficiency standards for fab operations and supplier qualification. Stakeholders must monitor how regulatory divergence between these jurisdictions fragments certification requirements and influences site selection for next-generation manufacturing capacity.
Market Dynamics
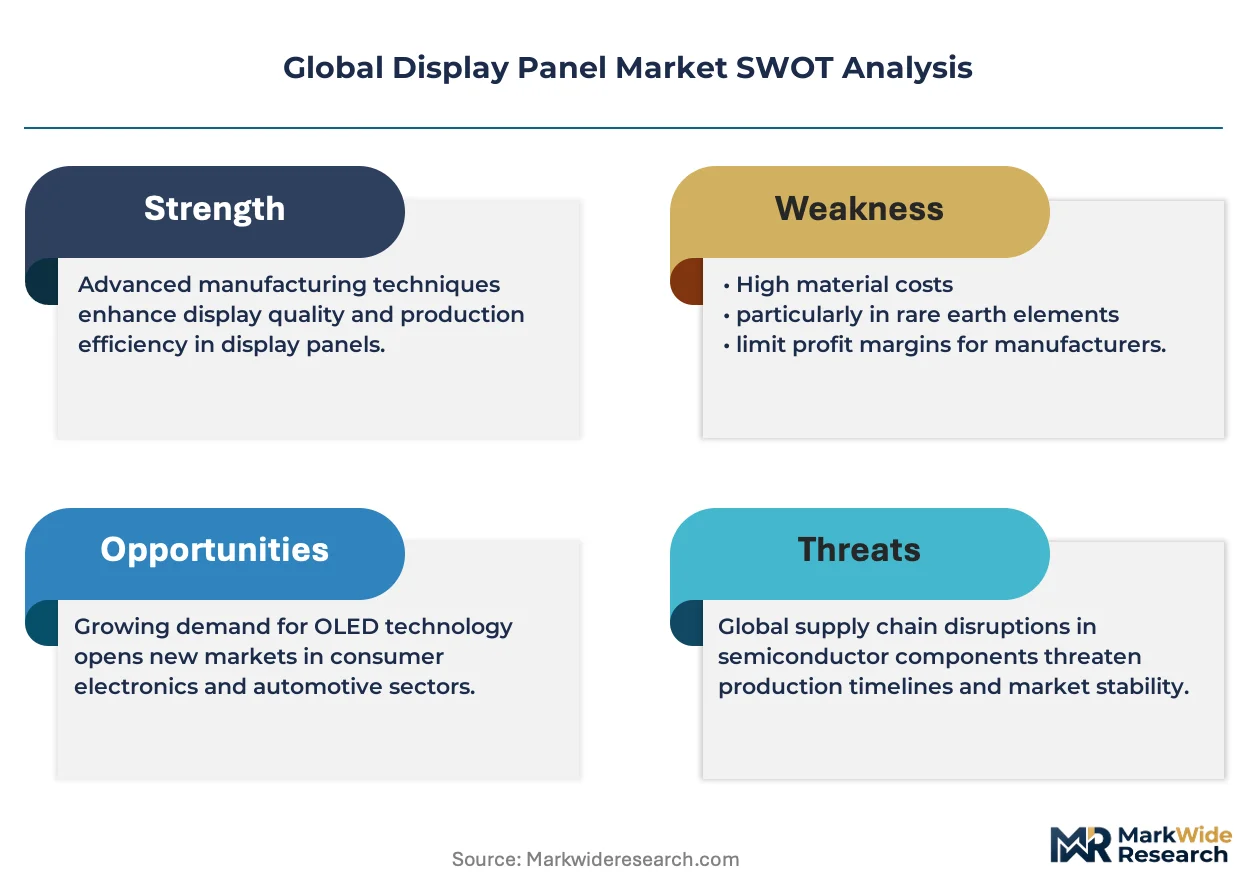
Gen 10.5 OLED fab investments by South Korean and Chinese manufacturers are compressing LCD capacity economics while automotive cockpit digitization creates bifurcated demand pools for rigid and flexible panel architectures.
Growth Catalysts
- Automotive cockpit digitization:Infotainment and instrument cluster displays are expanding procurement volumes as OEMs eliminate mechanical gauges. Tier-1 suppliers in Germany and Japan are qualifying flexible OLED for curved dashboard integration.
- EU Ecodesign Framework:Energy efficiency mandates for television panels sold across Europe are accelerating mini LED backlight adoption as manufacturers redesign thermal management systems to meet standby power limits.
- Dual carbon targets:China's Ministry of Ecology Environment is enforcing fab energy intensity standards that favor OLED over LCD due to lower backlight power requirements in finished consumer products.
Market Restraints
- Organic emitter material cost volatility:Iridium and platinum complex precursors for OLED deposition face concentrated supply from specialty chemical producers in Japan and Germany, creating input price instability.
- Gen 8.5+ equipment lead times:Vapor deposition chamber and photolithography tool availability from Japanese and Dutch suppliers stretches 18-24 months, constraining capacity expansion velocity.
- Technical limitation in blue emitter lifetime:Tandem blue OLED architectures remain below commercial durability thresholds for television applications, forcing continued reliance on LCD for large-format premium segments.
Strategic Opportunities
- Underpenetrated Indian television replacement cycle:Panel manufacturers can establish local module assembly partnerships as import duties on finished sets rise and domestic content rules tighten under the PLI scheme.
- Micro LED transfer technology convergence:Laser lift-off and stamp-based mass transfer methods are maturing simultaneously, enabling new entrants to bypass OLED patent thickets in premium television.
- Automotive transparent display applications:Windshield-integrated augmented reality HUDs represent an emerging specification segment where electroluminescent and transparent OLED technologies compete for OEM qualification.
Industry Challenges
- Cleanroom engineering talent scarcity:Gen 10.5 fab operations require specialized expertise in particle control and chemical handling that outstrips vocational training pipeline output in Vietnam and Indonesia expansion sites.
- Multi-jurisdiction chemical compliance:REACH restrictions in Europe, TSCA in the United States, and China's MEE chemical catalog create fragmented substance approval timelines that delay new emitter material commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Display Panel Market |
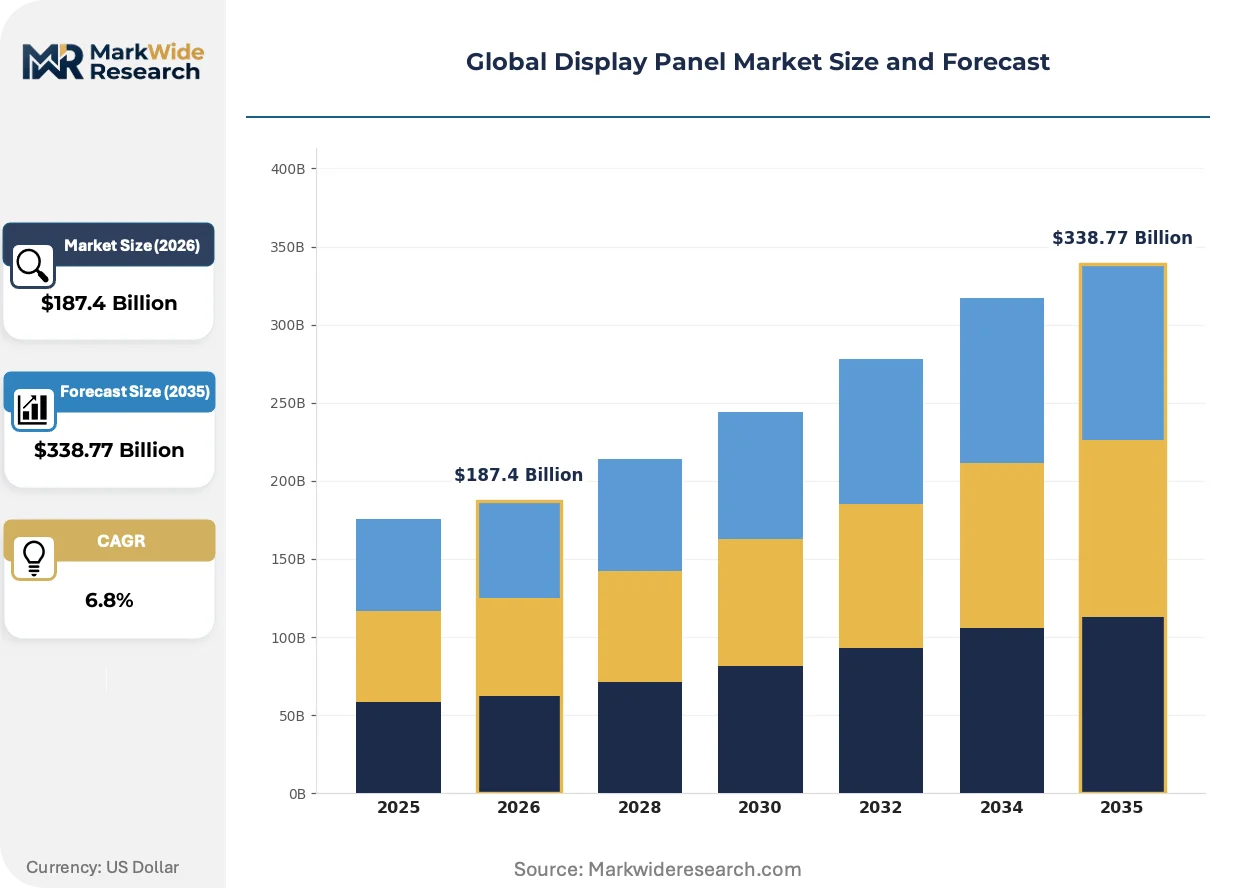
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD, OLED, QLED, Mini LED Technology: Touchscreen, Transparent, Flexible, 3D End User: Consumer Electronics, Automotive, Industrial, Commercial Installation: Wall-mounted, Freestanding, Embedded, Portable |
| Companies Covered | Samsung Display Co., Ltd., LG Display Co., Ltd., BOE Technology Group Co., Ltd., AU Optronics Corp., Innolux Corporation, Sharp Corporation, Japan Display Inc., TCL China Star Optoelectronics Technology Co., Ltd., Tianma Microelectronics Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Display Panel Market Emerging Trajectories
Panel technology trajectories are diverging between cost-optimized LCD enhancement and emissive OLED scaling, while regulatory pressure on embodied carbon reshapes material selection and manufacturing location decisions.
Mini LED backlighting with dense local dimming zones is hybridizing television and monitor product positioning. Premium consumer electronics brands in South Korea and Taiwan are adopting 2,000+ zone configurations to bridge performance gaps with OLED at lower manufacturing cost. This architecture is compressing the price-performance window where quantum dot LCD competes directly with white-OLED television panels.
China's dual carbon implementation rules issued by MEE are tightening energy efficiency disclosure requirements for panel imports. Manufacturers must now submit third-verified fab carbon intensity data to qualify for government procurement and state-owned enterprise supply contracts. South Korean exporters are responding by relocating final module assembly to Chinese free-trade zones to satisfy domestic content thresholds.
Fleet procurement by hospitality and corporate display deployers is shortening replacement cycles from seven to five years as 4K specification becomes baseline for new commercial installations. Systems integrators in North America and Western Europe are bundling installation and content management subscriptions, displacing traditional distributor inventory-holding models. This pattern is most visible in United States healthcare and education verticals where facility renovation budgets are consolidating AV spending under single-vendor contracts.
Global Display Panel Market Segmentation
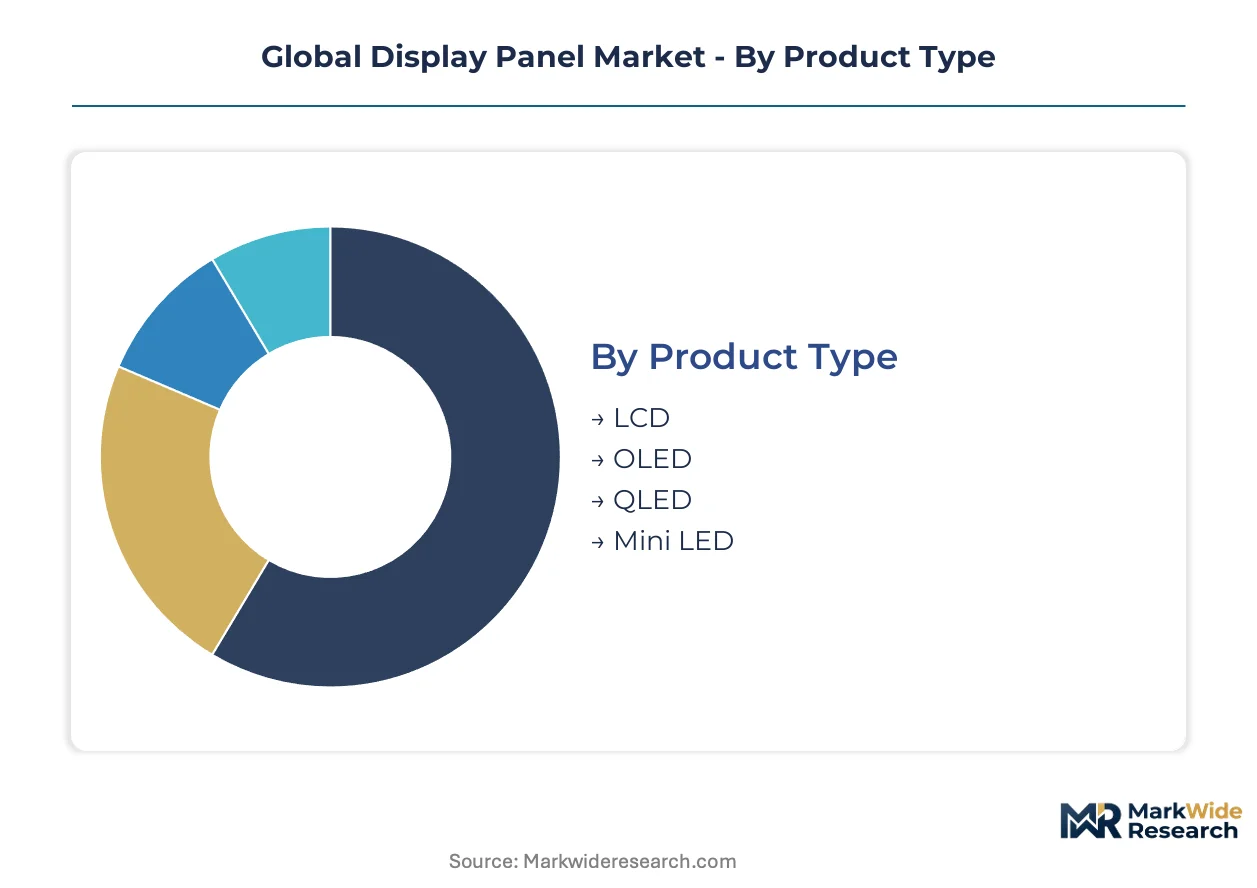
Display panel segmentation reveals how technology maturity, application requirements, and physical integration constraints create distinct competitive arenas with divergent margin profiles and capital intensity thresholds. Manufacturers must align fab investments and material sourcing to the specific performance and cost specifications demanded by each segment cluster.
Product Type:
Cost tier differentiation separates volume manufacturing from premium positioning, with each technology occupying distinct price-performance coordinates shaped by capital requirements and yield complexity.
- LCD:Liquid-crystal displays employ thin-film transistor backplanes with LED edge or direct backlighting to modulate light transmission through liquid-crystal orientation. Television procurement in India and Southeast Asia concentrates demand where import duty structures and domestic content rules under the PLI scheme reshape local assembly economics.
- OLED:Organic light-emitting diode panels stack emissive organic layers on flexible substrates, eliminating backlight systems through pixel-level illumination. Samsung Display and LG Display anchor supply from South Korean Gen 8.5 and Gen 10.5 fabs, with automotive cockpit applications in Germany and Japan driving flexible substrate qualification.
- QLED:Quantum dot enhancement layers integrated with LCD backplanes extend color gamut through photoluminescent nanocrystal emission. Samsung Electronics television product lines in North America represent primary demand concentration.
- Mini LED:Dense arrays of sub-millimeter LEDs enable thousands of local dimming zones behind LCD panels, bridging contrast performance toward OLED levels. Premium monitor procurement from Taiwanese and South Korean electronics brands sustains niche positioning.
LCD holds installed capacity across Gen 10.5 fabs in China and South Korea. OLED is rotating up the share rankings in smartphone and automotive qualification pipelines.
Technology:
Application-specific functional requirements determine which enabling technologies command design-in priority across end-use verticals with divergent interface specifications.
- Touchscreen:Capacitive and resistive sensing layers integrated atop display substrates enable direct manipulation interfaces. Industrial HMI deployments in Germany and Japan sustain demand for projected capacitive multi-touch with glove-compatible sensitivity specifications.
- Transparent:Partially transmissive panel architectures permit overlay of digital content on physical backgrounds. Retail fixture installations in Dubai and Singapore represent emerging commercial demand concentration.
- Flexible:Polyimide substrate and barrier film engineering enable bendable and foldable form factors. Samsung Display mobile panel shipments and emerging automotive curved dashboard specifications in Germany drive technology development priorities.
- 3D:Autostereoscopic or glasses-required depth rendering through lenticular lenses or directional backlighting. Medical imaging workstations in the United States and Japan sustain specialized demand for volumetric visualization without eyewear.
Touchscreen dominates installed base across consumer and industrial applications. Flexible is climbing the fastest in capital allocation priority among South Korean and Chinese manufacturers.
End User:
Customer type segmentation maps how volume scale, specification tolerance, and procurement authority distribute across organizational buyers with distinct technical competencies and contract structures.
- Consumer Electronics:Smartphones, televisions, monitors, and wearables represent volume concentration with rapid replacement cycles. South Korean and Chinese OEM procurement patterns concentrate demand for mobile OLED and television LCD with 4K/8K resolution specifications.
- Automotive:Infotainment systems, instrument clusters, and head-up displays require temperature-extended operating ranges and vibration resistance. German Tier-1 suppliers in Stuttgart and Munich are qualifying flexible OLED for curved cockpit integration alongside Japanese manufacturers in Nagoya.
- Industrial:HMI panels, process control displays, and ruggedized field units demand extended temperature ratings and ingress protection. Manufacturing automation deployments in Germany's Ruhr region and Japan's Aichi prefecture sustain specialized procurement.
- Commercial:Digital signage, hospitality television, and corporate collaboration displays operate under continuous-duty cycles with remote management requirements. Healthcare and education facility renovation budgets in the United States are consolidating AV procurement under single-vendor contracts with five-year replacement cycles.
Consumer Electronics commands manufacturing scale economies. Automotive is gaining share fastest as cockpit digitization eliminates mechanical gauges across OEM lineups.
Installation:
Physical integration constraints determine thermal management, structural reinforcement, and connectivity requirements that differentiate panel module specifications.
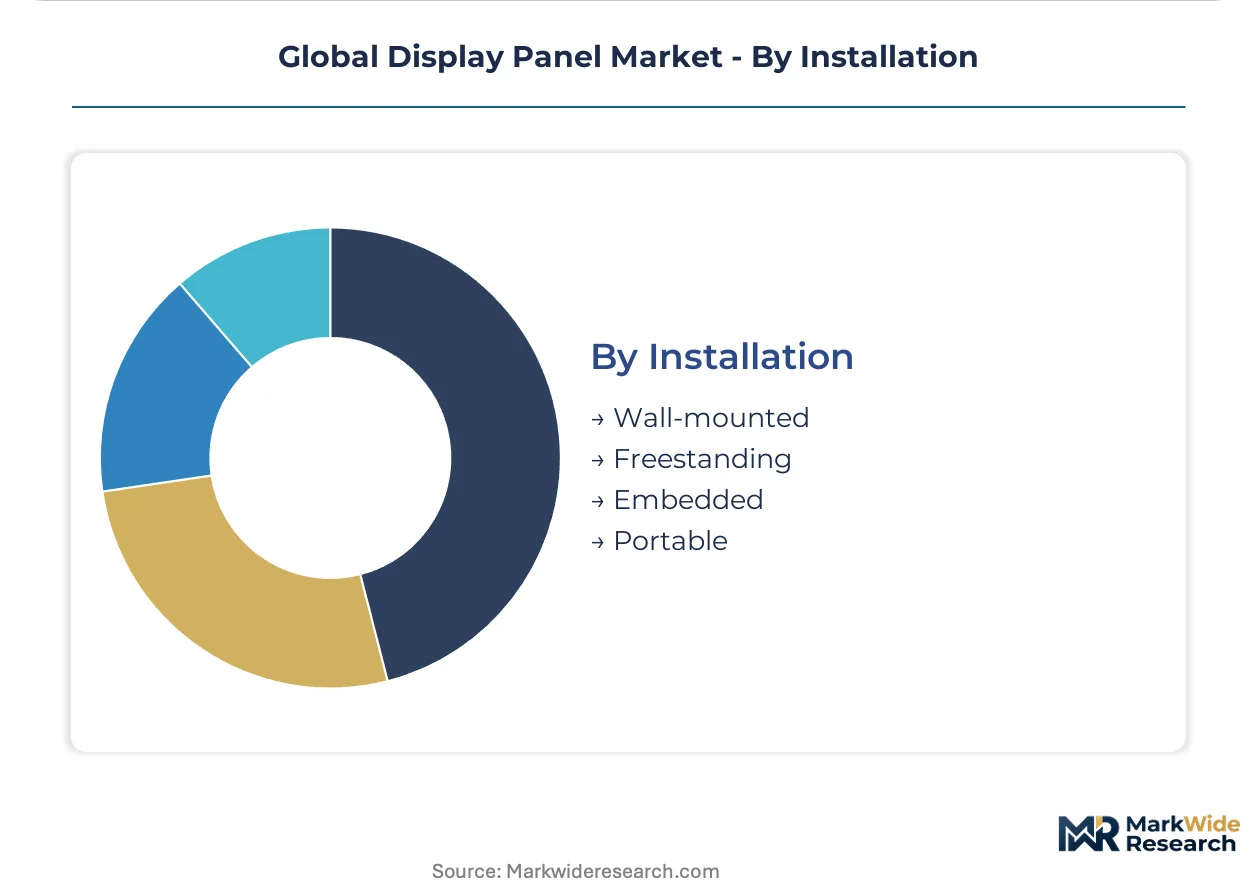
- Wall-mounted:Fixed bracket installation for residential television and commercial signage applications dominates volume. Indian market import duty structures on finished sets favor local module assembly partnerships for this configuration.
- Freestanding:Integrated chassis and base structures for kiosks, information terminals, and retail displays. Shopping mall and airport deployments in Dubai and Singapore concentrate demand.
- Embedded:Custom-fit integration into appliance front panels, automotive dashboards, and industrial equipment housings. Automotive OEM specifications in Germany and Japan require embedded module qualification for curved surface integration.
- Portable:Battery-powered operation with weight-optimized enclosures for tablets, laptops, and field-service devices. South Korean and Chinese consumer electronics OEMs drive specification requirements for thin-film substrate and low-power driver IC integration.
Wall-mounted holds installed capacity across residential and commercial base. Embedded is rotating up the share rankings as automotive cockpit digitization accelerates module integration complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Panel consumption patterns diverge sharply across major economies. South Korea and China absorb premium OLED for mobile and television applications. Germany and Japan concentrate automotive cockpit procurement. India represents a volume growth frontier where import substitution policies reshape assembly economics.
South Korea
Smartphone OEM procurement and television replacement cycles concentrate demand for mobile OLED and white-OLED panels. The Ministry of Trade, Industry and Energy enforces domestic content rules and R&D tax incentives that steer capital toward Gen 8.5 and Gen 10.5 fab expansions. The Gyeonggi-do manufacturing corridor anchored by Samsung Display and LG Display sustains global supply leadership through vertical control over organic emitter deposition.
China
Massive domestic television procurement and state-backed automotive electrification programs drive LCD and emerging OLED demand. The Ministry of Ecology Environment implements dual carbon targets that elevate energy efficiency standards for fab operations and supplier qualification. Hefei and Wuhan host BOE Technology Group's Gen 10.5 LCD and OLED investments, with module assembly shifting to free-trade zones to satisfy domestic content thresholds.
Germany
Automotive OEM cockpit digitization and industrial HMI deployments sustain specialized demand for flexible OLED and ruggedized panel specifications. The EU Ecodesign Framework mandates standby power limits and recyclability requirements that accelerate mini LED adoption in premium television. Stuttgart and Munich-based Tier-1 suppliers qualify flexible OLED for curved dashboard integration alongside instrument cluster elimination programs.
Japan
Medical imaging workstations and industrial automation displays sustain specialized demand for high-resolution panels with extended temperature ratings. METI enforces JIS standards and domestic procurement preferences that preserve local module assembly capabilities. Nagoya and Aichi prefecture manufacturing clusters anchor automotive display qualification programs for curved cockpit integration.
India
Television replacement cycles and smartphone volume growth concentrate demand for cost-optimized LCD and entry-level OLED panels. The PLI scheme and rising import duties on finished sets favor local module assembly partnerships over direct panel imports. Maharashtra and Tamil Nadu assembly corridors attract Chinese and South Korean manufacturers establishing knock-down kit operations to satisfy domestic content rules.
Global Display Panel Market Vendor Landscape
Capability concentration sits with South Korean specialists commanding organic emitter deposition expertise; scale advantage sits with Chinese manufacturers leveraging Gen 10.5 fab capacity. The market structures around three archetypes: vertically integrated material-to-panel producers, pure-play fab operators, and module assembly specialists. Competitive moves center on backward integration into precursor chemicals and geographic relocation of final assembly to satisfy domestic content thresholds.
Within the South Korean tier, Samsung Display Co., Ltd. and LG Display Co., Ltd. exemplify vertically integrated specialists with captive control over organic emitter supply chains. BOE Technology Group Co., Ltd. anchors Chinese scale positioning through massive Gen 10.5 investments. These three entities represent the dominant competitive anchors shaping technology trajectories and capacity allocation decisions across mobile, television, and emerging automotive applications.
| Leading Market Players |
|---|
| Samsung Display Co., Ltd. |
| LG Display Co., Ltd. |
| BOE Technology Group Co., Ltd. |
| AU Optronics Corp. |
| Innolux Corporation |
| Sharp Corporation |
| Japan Display Inc. |
| TCL China Star Optoelectronics Technology Co., Ltd. |
| Tianma Microelectronics Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Japanese and German specialty chemical producers anchor organic emitter precursor supply, concentrating margin capture upstream while South Korean panel manufacturers defend downstream pricing power through captive deposition capabilities. This feedstock concentration shapes contract structures and procurement risk allocation across the value chain.
Pricing Analysis
Long-term offtake agreements dominate strategic procurement between display manufacturers and emitter material suppliers, insulating against iridium and platinum complex volatility. Pricing stratifies across premium OLED, mid-tier Mini LED, and economy LCD tiers based on resolution grade and automotive qualification status. Cost compression in television LCD intensifies as Chinese Gen 10.5 capacity expansion outpaces demand absorption. Automotive OEMs exhibit lowest price sensitivity due to stringent reliability certification requirements, while Indian television assemblers face acute margin pressure from import duty structures.
Supply Chain Analysis
Organic emitter precursors draw from concentrated Japanese and German chemical synthesis clusters, tethering panel cost structures to specialty metal complex availability. Vapor deposition chambers and photolithography tools hinge on Dutch and Japanese equipment suppliers with extended fulfillment cycles. Single-source vulnerability runs through extreme ultraviolet lithography systems for advanced backplane patterning. Distribution runs through South Korean and Chinese module assembly hubs serving regional OEM clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat: REACH chemical restrictions and China's dual carbon mandates create compliance barriers that favor incumbent scale and captive supply chain investments.
For Market Incumbents: Build technology-lock moats through backward integration into organic emitter precursor synthesis, neutralizing Japanese and German chemical supplier pricing leverage. Secure Gen 8.5+ equipment slots with Dutch and Japanese toolmakers before lead time extensions constrain capacity additions. Prioritize automotive qualification pipelines in Stuttgart and Nagoya to capture cockpit digitization premiums ahead of flexible OLED standardization. For New Entrants and Emerging Players: India's underpenetrated television replacement cycle offers module assembly partnerships under PLI domestic content rules, bypassing direct fab investment requirements. Target transparent display specifications for retail fixture deployments in Dubai and Singapore where electroluminescent and transparent OLED technologies compete without established incumbent lock-in. Pursue micro LED transfer technology licensing to circumvent South Korean OLED patent thickets. For Investors and Strategic Acquirers: Secondary-cycle assets sit with Chinese state-backed fab operators facing margin compression from LCD oversupply and dual carbon compliance costs. Long-term viability centers on OLED technology leadership and automotive qualification depth rather than scale alone. Monitor blue emitter lifetime breakthroughs as the inflection signal for television OLED displacement of premium LCD segments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Emitters | Samsung Display's captive precursor production insulates against Japanese chemical supplier price volatility. |
| Gen 10.5 OLED Capacity Expansion | BOE Technology Group's Hefei investments capture scale economies for television panel cost reduction. |
| Automotive Flexible OLED Qualification | LG Display's curved dashboard integration programs with German Tier-1 suppliers secure premium positioning. |
| Micro LED Mass Transfer Development | Laser lift-off technology maturation enables new entrants to bypass established OLED patent portfolios. |
| Free-Trade Zone Module Relocation | South Korean exporters' Chinese assembly shifts satisfy MEE domestic content thresholds under dual carbon rules. |
Methodological Framework
Two parallel data streams informed the analysis: structured interviews with fab operations directors, automotive Tier-1 procurement managers, and display equipment supplier technical leads; and secondary validation through SEC filings, customs trade records, and MEE energy disclosure databases. Bottom-up capacity modeling triangulated against top-down OEM procurement forecasts across smartphone, television, and automotive verticals.
Forecast inputs span technology generation transitions, regional regulatory divergence under REACH and dual carbon implementation, and automotive cockpit digitization penetration curves. Segmentation dimensions include panel technology, substrate flexibility, end-use application, and geographic manufacturing cluster. CAGRs derive from installed base replacement cycles and content-per-vehicle expansion trajectories.
Practitioners should monitor blue OLED emitter lifetime breakthroughs and MEE carbon intensity enforcement strictness for early signals of technology substitution acceleration. Forecasts reflect assumptions about equipment lead time stability and automotive qualification timeline continuity. Material shifts in EU Ecodesign standby power limits or Japanese precursor export restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Next Generation 3D Display Market
Display Technologies
Flexible Display Market
Display Technologies
Multimedia Projectors Market
Display Technologies
Low Power Display Market
Display Technologies
Field Emission Display Market
Display Technologies
Display Material Market
Display Technologies
Visual Computing Market
Display Technologies
AMOLED Display Market
Display Technologies
Global Smartphone Display Panel Market
Display Technologies
Digital Holographic Display Market
Display Technologies
Cathode Ray Tube Display Market
Display Technologies
Touch Screen Film Market
Display Technologies
Foldable Display Market
Display Technologies
Wireless Display Market
Display Technologies
Smart Privacy Glass Market
Display Technologies
Backlit Displays Market