
 Global Outdoor LED Lighting Market | 2026-2036
Global Outdoor LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Global Outdoor LED Lighting Market Foresight
Chinese chip-on-board packaging capacity is decoupling from legacy phosphor-converted white LED supply chains. Signify N.V. leverages its Interact City platform to anchor large-scale municipal retrofits across European capitals. Cree Inc. dominates high-efficacy chip production for roadway applications where thermal management determines operating life. Osram Licht AG extends its portfolio into horticultural and human-centric spectral variants beyond standard outdoor white points.
Outdoor LED lighting encompasses solid-state luminaires engineered from gallium nitride epitaxy on sapphire or silicon carbide substrates, emitting directional photons through precision secondary optics for exterior illumination tasks. These systems achieve luminous efficacies exceeding 150 lumens per watt while operating across temperature extremes from -40°C to +50°C, enabling replacement of high-pressure sodium and metal halide infrastructure in public and commercial exterior environments. Street lights command the largest installed base among product categories, though solar LED technology grows fastest where grid extension costs exceed standalone photovoltaic-battery system economics. Smart LED architectures with embedded dimming and occupancy sensing capture premium margin pools as municipalities shift from hardware procurement to performance-contracting service models.
FCC Part 15 governs radio-frequency emissions from connected outdoor luminaires in the United States, while the EU F-Gas Regulation and Ecodesign Directive constrain embodied carbon and hazardous substance thresholds for luminaires sold across member states. China's MIIT enforces GB standards for LED module interchangeability and electromagnetic compatibility, creating compliance complexity for multinational fixture suppliers. Stakeholders must monitor evolving interoperability protocols between lighting networks and urban Internet-of-Things platforms as procurement criteria shift from lumen-dollar metrics toward data-enabled service value.
Market Dynamics
The outdoor LED lighting sector is reconfiguring around sensor-integrated infrastructure where luminaires function as data collection nodes rather than standalone illumination devices. Municipal procurement offices now evaluate connected pole architectures on telemetry value, compressing margins for hardware-only suppliers while elevating platform providers.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of high-global-warming-potential refrigerants in outdoor fixtures accelerates adoption of passive thermal management designs in roadway luminaires across German and French infrastructure programs.
- Silicon carbide substrates:Wider bandgap semiconductors enable junction temperatures above 175°C, extending operational life in desert climates where sapphire-based chips degrade prematurely.
- Brazilian municipal retrofits:Grid-connected LED deployments in São Paulo and Rio de Janeiro prioritize theft-resistant housing designs following copper extraction vandalism patterns.
Market Restraints
- Gallium supply concentration:Primary gallium refining capacity clusters in Chinese smelters, exposing fixture manufacturers to export quota volatility and price spikes.
- Legacy sodium vapor persistence:Existing HPS installations with 20,000-hour remaining life delay replacement cycles in budget-constrained Indian municipal corporations.
- Interoperability fragmentation:Competing mesh protocols from TALQ, Zhaga, and proprietary vendor stacks create integration friction for multi-supplier deployments.
Strategic Opportunities
- Indonesian archipelago electrification:Solar-LED hybrid systems bypass submarine cable economics across 17,000 islands where diesel generator maintenance costs exceed photovoltaic lifecycle expenditure.
- LiDAR convergence:Integration of automotive-grade ranging sensors into roadway poles creates traffic flow data products sellable to mapping services and insurers.
- India PLI scheme:Production-linked incentives for LED component manufacturing attract chip packaging investments previously concentrated in East Asian facilities.
Industry Challenges
- Thermal simulation expertise:Computational fluid dynamics competency for passive cooling design resides in a narrow pool of semiconductor packaging engineers, constraining product development velocity.
- Legacy DALI integration:Retrofit installations must bridge 20-year-old digital addressable lighting interface installations with IP-native control architectures, multiplying commissioning complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Outdoor LED Lighting Market |
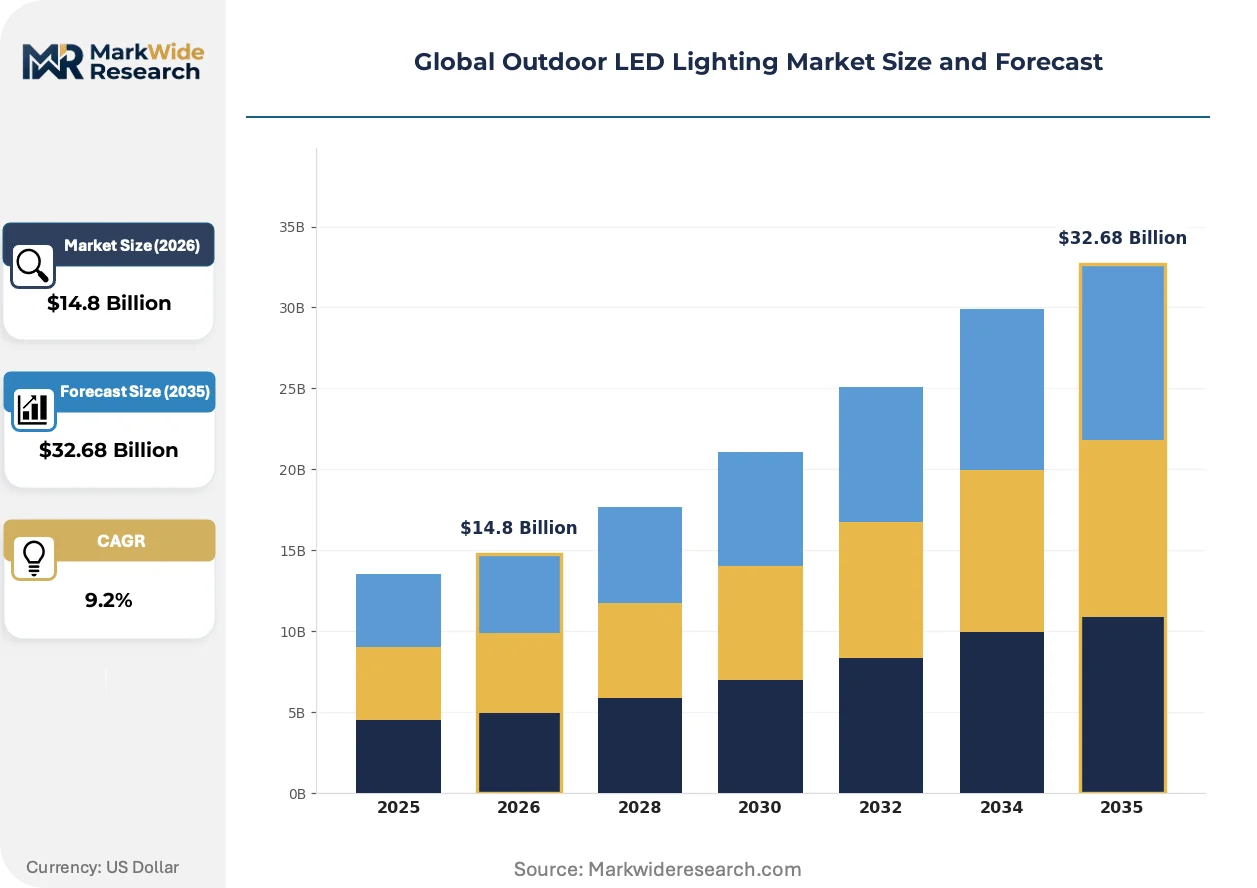
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Street Lights, Flood Lights, Garden Lights, Wall Lights Technology: Smart LED, Solar LED, Conventional LED, RGB LED Application: Public Spaces, Parks, Roadways, Parking Lots End User: Municipalities, Commercial Properties, Residential Areas, Industrial Sites |
| Companies Covered | Cree Inc., Panasonic Corporation, Signify N.V., Schreder Group, Samsung Electronics Co. Ltd., Acuity Brands Lighting Inc., General Electric Co. Ltd., Cooper Lighting Solutions, Osram Licht AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Outdoor LED Lighting Market Shifts & Advancements
Photonic engineering is migrating from efficacy maximization toward spectral programmability, enabling single luminaire platforms to serve circadian, horticultural, and public safety functions sequentially. This redefinition of hardware utility is compressing product lifecycles and expanding addressable service revenue pools.
Chip-on-board LED architectures are overtaking discrete SMD packages in high-lumen roadway applications. COB designs eliminate individual lens arrays, reducing optical loss from 12% to 4% while simplifying thermal path engineering. German Autobahn lighting tenders now specify COB minimums, forcing retrofit suppliers to redesign within 18-month procurement windows.
China's GB standards for LED module interchangeability are tightening electromagnetic compatibility testing protocols for connected outdoor fixtures. MIIT enforcement actions against non-compliant imports are blocking European and North American suppliers lacking in-country certification laboratories. Manufacturers are establishing captive testing facilities in Shenzhen to maintain mainland market access.
Performance contracting is displacing capital expenditure procurement in North American municipal markets. Chicago, Los Angeles, and Toronto street lighting departments now contract for guaranteed lumen-hours rather than fixture ownership, transferring operational risk to infrastructure service providers. This model demands 15-year system reliability warranties that reshape supplier balance sheet structures.
Global Outdoor LED Lighting Market Segmentation
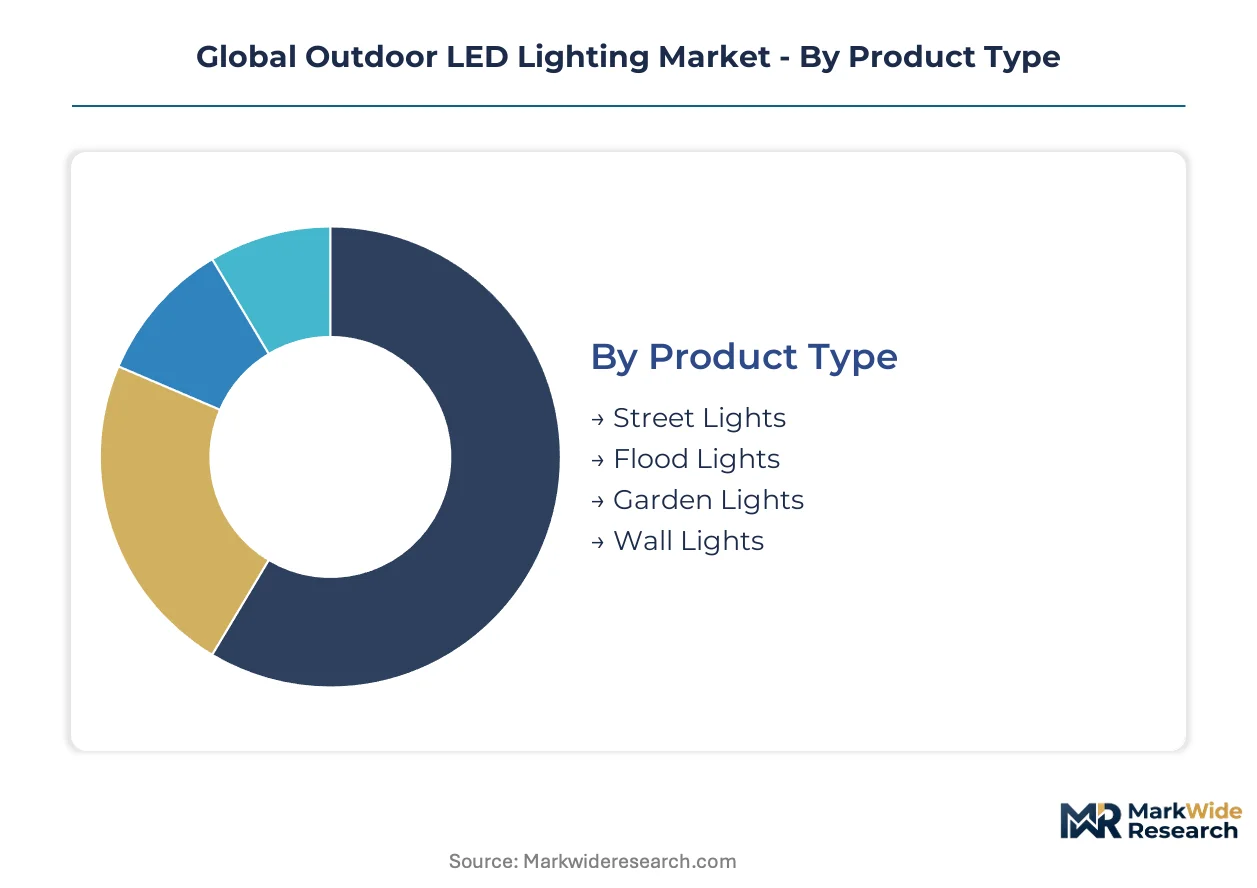
Segmentation in outdoor LED lighting reveals divergent technology requirements across deployment contexts. Municipal procurement cycles, thermal engineering specifications, and connectivity architectures create distinct margin profiles that reshape supplier positioning.
Product Type:
Volume concentrates in standardized roadway luminaires where economies of scale dominate supplier economics. Premium capture sits with specialized architectural fixtures commanding specification-based selection.
- Street Lights:COB architectures with 150+ lm/W efficacy dominate German Autobahn and São Paulo municipal tenders. Passive thermal management designs extend operating life in desert climates where junction temperatures exceed 175°C.
- Flood Lights:High-lumen output fixtures serve Brazilian mining operations and Indian industrial zones. Theft-resistant housing designs address copper extraction vandalism patterns in grid-connected deployments.
- Garden Lights:Low-voltage landscape luminaires integrate solar-battery systems for Indonesian island electrification bypassing submarine cable economics.
- Wall Lights:Architectural facade illumination employs precision secondary optics for directional photon delivery in European heritage district retrofits.
Mature deployment sits with Street Lights. Newer deployment is concentrated in Garden Lights.
Technology:
Smart connectivity commands procurement priority as municipalities shift from hardware ownership to performance-contracting service models. Solar-battery hybrids gain traction where grid extension costs exceed standalone photovoltaic lifecycle expenditure.
- Smart LED:Sensor-integrated poles with embedded dimming and occupancy sensing capture telemetry value in Chicago, Los Angeles, and Toronto street lighting departments. FCC Part 15 and EU F-Gas Regulation compliance complexity elevates platform providers over hardware-only suppliers.
- Solar LED:Photovoltaic-battery standalone systems address 17,000 Indonesian islands where diesel generator maintenance costs exceed renewable lifecycle economics. MIIT GB standards for electromagnetic compatibility constrain import pathways.
- Conventional LED:Non-connected luminaires persist in budget-constrained Indian municipal corporations with 20,000-hour remaining life on legacy sodium vapor infrastructure.
- RGB LED:Spectrally programmable architectures enable sequential circadian, horticultural, and public safety functions from single luminaire platforms.
Established procurement favors Conventional LED. Steepest expansion trajectory belongs to Smart LED.
Application:
Public infrastructure absorbs capital deployment at scale while commercial parking optimization drives sensor integration adoption. Geographic concentration varies by electrification density and retrofit cycle timing.
- Public Spaces:City square and plaza illumination in European capitals leverages Signify's Interact City platform for centralized telemetry management. EU Ecodesign Directive efficacy minimums phase out mercury-containing luminaires.
- Parks:Recreational area lighting employs human-centric spectral variants extending Osram's portfolio beyond standard outdoor white points. Circadian programming supports evening athletic activity safety.
- Roadways:German Autobahn tenders now specify COB minimums forcing 18-month supplier redesign windows. Cree's high-efficacy chip production dominates thermal-critical applications.
- Parking Lots:Commercial facility illumination integrates automotive-grade LiDAR sensors creating traffic flow data products sellable to mapping services and insurers.
Volume concentration rests with Roadways. Emerging specification intensity centers on Parking Lots.
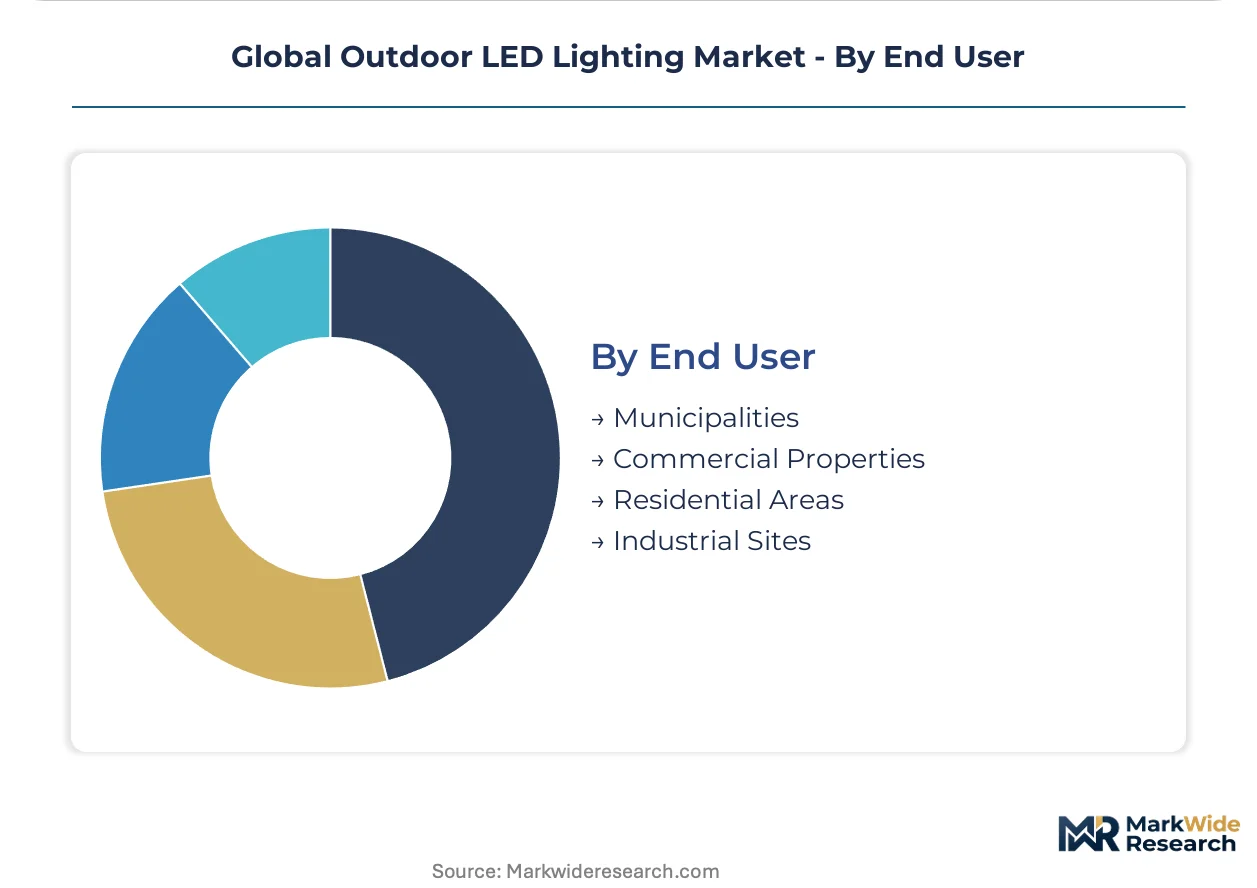
End User:
Municipal procurement offices now evaluate connected pole architectures on data-enabled service value rather than lumen-dollar metrics. Industrial site requirements prioritize thermal management in extreme operating temperature ranges.
- Municipalities:German, Indian, and Brazilian local governments replace sodium vapor installations with connected LED architectures. India's PLI scheme attracts chip packaging investments previously concentrated in East Asian facilities.
- Commercial Properties:Retail and office campus lighting demands 15-year system reliability warranties under performance-contracting models transferring operational risk to infrastructure service providers.
- Residential Areas:Subdivision and gated community deployment favors standardized fixture interchangeability under China's MIIT GB standards for LED module compatibility.
- Industrial Sites:Mining, port, and logistics facility illumination requires -40°C to +50°C operating range certification. Silicon carbide substrates enable junction temperatures above 175°C in desert climate installations.
Procurement maturity concentrates with Municipalities. Specification evolution is accelerating fastest among Commercial Properties.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gallium refining capacity clusters in Chinese smelters, exposing fixture manufacturers to export quota volatility. Municipal retrofit cycles and smart infrastructure mandates vary sharply by jurisdiction, reshaping procurement patterns across major economies.
China
MIIT enforces GB standards for LED module interchangeability and electromagnetic compatibility, blocking non-compliant imports. The dual carbon goals accelerate phaseout of mercury-containing luminaires. Shenzhen hosts captive certification laboratories established by European suppliers seeking mainland market access.
Germany
Autobahn lighting tenders now specify chip-on-board minimums, forcing 18-month supplier redesign windows. The EU F-Gas Regulation and Ecodesign Directive tighten efficacy minimums for roadway infrastructure. Bavaria and North Rhine-Westphalia concentrate municipal retrofit programs replacing sodium vapor installations.
United States
FCC Part 15 governs radio-frequency emissions from connected outdoor luminaires, elevating compliance costs for platform providers. Performance contracting displaces capital expenditure procurement in Chicago, Los Angeles, and Toronto street lighting departments. Thermal management expertise concentrates in semiconductor packaging engineers serving desert climate installations.
India
The PLI scheme attracts chip packaging investments previously concentrated in East Asian facilities. Legacy sodium vapor installations with 20,000-hour remaining life delay replacement cycles in budget-constrained municipal corporations. Maharashtra and Gujarat anchor domestic manufacturing expansion for roadway and industrial applications.
Brazil
Grid-connected LED deployments in São Paulo and Rio de Janeiro prioritize theft-resistant housing designs following copper extraction vandalism patterns. ANVISA regulates electromagnetic compatibility for imported fixtures. Mining operations in Minas Gerais drive demand for high-lumen flood lighting with extreme temperature certification.
Global Outdoor LED Lighting Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue sensor-integrated platforms and performance-contracting service models. The vendor base stratifies across three tiers: multinational platform providers with city-scale deployment capabilities, regional fixture specialists capturing municipal retrofit cycles, and component-level suppliers controlling thermal management intellectual property. Consolidation pressure intensifies as procurement offices evaluate telemetry value over hardware specifications. Dominant competitive moves include backward integration into chip packaging and strategic partnerships with urban Internet-of-Things platform operators.
Among Netherlands-based platform providers, Signify N.V. exemplifies the connected infrastructure archetype. Cree Inc. and Osram Licht AG occupy positions within the high-efficacy component tier, representing divergent substrate strategies for thermal-critical applications. These three entities anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Cree Inc. |
| Panasonic Corporation |
| Signify N.V. |
| Schreder Group |
| Samsung Electronics Co. Ltd. |
| Acuity Brands Lighting Inc. |
| General Electric Co. Ltd. |
| Cooper Lighting Solutions |
| Osram Licht AG |
| Others |
Supply & Pricing Matrix
Municipal performance-contracting mandates in Chicago, Los Angeles, and Toronto are forcing suppliers to bundle 15-year system reliability warranties with hardware sales, compressing margins for unbundled fixture vendors while elevating platform providers with balance sheet capacity to absorb long-term operational risk.
Pricing Analysis
Warranty and telemetry service bundling now separates premium platform providers from hardware-only suppliers in North American municipal procurement. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by certification tier, after-sales service depth, and smart connectivity integration. Pricing pressure stems from India's PLI scheme attracting domestic chip packaging investments that undercut import-dependent fixture costs. Budget-constrained Indian municipal corporations exhibit highest price sensitivity, while German Autobahn authorities prioritize thermal performance specifications over unit cost.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Rotterdam, and Dallas anchor hub-and-spoke patterns for fixture assembly and certification testing. Primary gallium refining capacity clusters in Chinese smelters, exposing manufacturers to export quota volatility. Raw material dependencies span sapphire and silicon carbide substrates, phosphor-converted white LED packages, and copper thermal management components. Single-source vulnerability concentrates in Chinese gallium supply, with tariff exposure running through US-China trade corridors. Distribution runs through municipal procurement offices, electrical contractors, and infrastructure service providers under performance-contracting arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation and Ecodesign Directive create a cost-of-compliance moat that favors incumbent platform providers with captive certification laboratories and established in-country testing infrastructure, while blocking non-compliant imports from price-competitive entrants lacking European market access.
For Market Incumbents: Extend platform ecosystem dominance by integrating LiDAR and automotive-grade sensors into roadway pole architectures, creating proprietary traffic flow data products that lock municipalities into long-term service contracts. Backward integration into silicon carbide chip packaging mitigates gallium supply concentration risk from Chinese smelter quotas. Reinforce thermal simulation expertise scarcity by acquiring computational fluid dynamics engineering teams from semiconductor packaging specialists. For New Entrants and Emerging Players: The price-point gap between premium smart LED platforms and economy conventional fixtures creates white-space opportunity for mid-tier suppliers offering modular upgrade pathways. Target Indonesian archipelago solar-LED hybrid deployments where submarine cable economics and diesel generator maintenance costs exclude grid-connected incumbents. Pursue Brazilian municipal retrofits with theft-resistant housing designs as entry wedge against established European suppliers unfamiliar with copper extraction vandalism patterns. For Investors and Strategic Acquirers: The window for entry favors component-level specialists controlling thermal management intellectual property and captive gallium sourcing arrangements. Long-term viability hinges on 5-10 year infrastructure replacement cycles in budget-constrained municipalities transitioning from sodium vapor. Watch India's PLI scheme disbursement velocity as inflection indicator for East Asian chip packaging investment relocation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chip Packaging | Mitigates gallium supply concentration from Chinese smelter export quotas. |
| Performance-Contracting Service Model | Transfers 15-year operational risk to infrastructure providers in Chicago and Toronto. |
| LiDAR Sensor Integration | Creates traffic flow data products sellable to mapping services and insurers. |
| Captive Certification Laboratory Establishment | Maintains mainland China market access under tightening MIIT GB standards. |
| Solar-LED Hybrid System Deployment | Bypasses submarine cable economics across 17,000 Indonesian islands. |
Research Methodology
Document review covered EU F-Gas Regulation filings, MIIT GB standard enforcement actions, and municipal procurement databases from Chicago, São Paulo, and Mumbai, complemented by interviews with street lighting department procurement officers, thermal management engineers at Cree and Osram, and distribution channel partners in European electrical supply. Secondary validation drew from SEC 10-K disclosures, customs trade data for gallium and sapphire substrates, and infrastructure project development trackers. Bottom-up fixture shipment estimates triangulated against top-down municipal capital expenditure budgets.
Segment-level projections across product type, technology, application, and end user dimensions were generated through the analytical framework, with CAGRs derived from retrofit cycle timing and smart infrastructure penetration curves. Industry-specific inputs included junction temperature degradation models for silicon carbide substrates, theft-resistant housing cost premiums for Brazilian deployments, and performance-contracting warranty liability structures.
Inputs from municipal procurement databases and chip packaging facility investment announcements were available through the study window; gaps in real-time gallium smelter export quota data introduce uncertainty bands around cost assumptions. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and infrastructure budget allocation patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
High-Brightness LED Market
LED
Surface Mount PLCC Leds Market
LED
East Africa LED Lighting Market
LED
GCC LED Lighting Market
LED
LED Tube Drivers Market
LED
LED Modules and Light Engines Market
LED
France Indoor LED Lighting Market
LED
LED Driver Market
LED
Dot-Matrix LED Displays Market
LED
Germany LED Lighting Market
LED
China LED Market
LED
LED Panel Market
LED
Mini LED Display Market
LED
High-Intensity LED Logo and Livery Lighting Systems Market
LED
South America LED Lighting Market
LED
Europe Indoor LED Lighting Market