
 Flexible OLED Market | 2026-2036
Flexible OLED Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible OLED Market Analysis
Project finance tied to display fab build-outs is tilting competitive dynamics toward capital-heavy conglomerates. Samsung Electronics leverages captive AMOLED capacity to dominate premium smartphone panel supply. BOE Technology Group sustains aggressive capacity expansion through state-backed credit facilities. LG Display anchors its position in automotive-grade flexible displays through dedicated production lines.
Flexible OLED denotes organic light-emitting diode displays fabricated on polyimide or ultra-thin glass substrates enabling bend radii below 5 millimeters, primarily serving device form-factor innovation in portable electronics. AMOLED technology leads volume shipments while transparent OLED occupies nascent architectural and automotive glazing applications. Consumer Electronics application segments concentrate margin pools in flagship smartphone launches, whereas Automotive Displays represents the fastest-growing demand vector as curved cockpit screens proliferate.
REACH chemical restrictions in Europe constrain fluorinated encapsulant formulations, while China's GB standards govern electromagnetic emissions from foldable devices. The US FCC certifies radio-integrated flexible modules for 5G mmWave compatibility. Stakeholders must monitor how Korea's Ministry of Trade, Industry and Energy calibrates export credit terms amid subsidy investigations by trading partners.
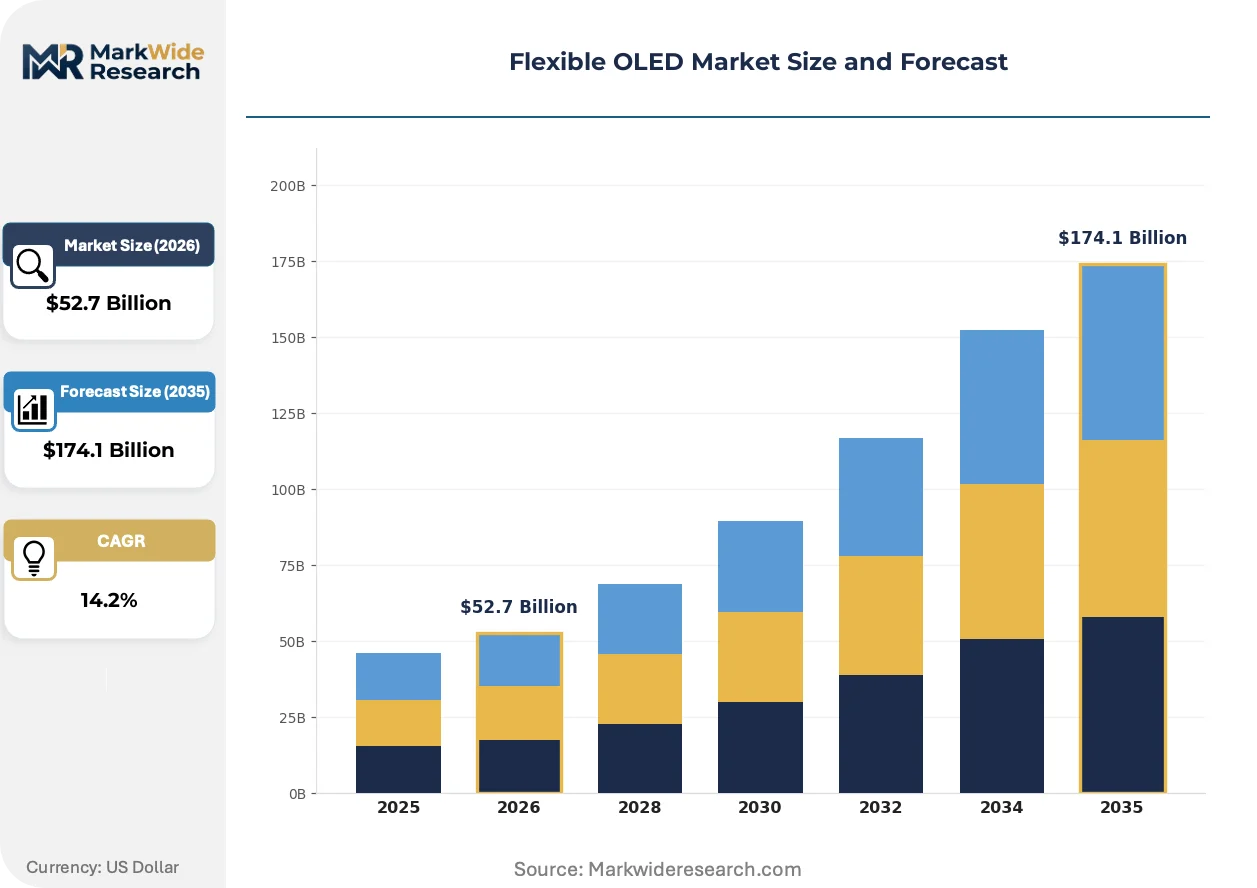
Market Dynamics
Capital concentration in display fabrication is locking out mid-tier entrants as Samsung Electronics and BOE Technology Group scale captive AMOLED capacity through project finance tied to multi-billion-dollar fab build-outs.
Growth Catalysts
- EU Ecodesign for Sustainable Products Regulation:Mandates for material recovery in display panels are accelerating closed-loop recycling infrastructure investments across European manufacturing corridors.
- Automotive cockpit digitization:Curved instrument clusters and pillar-to-pillar displays are pulling flexible OLED into tier-one supplier roadmaps faster than anticipated.
- Guangdong Province cluster density:Proximity of panel makers to component suppliers compresses logistics costs and prototype iteration cycles for foldable device launches.
Market Restraints
- Fluorinated encapsulant chemistry constraints:REACH restrictions in Europe limit barrier layer formulations, forcing reformulation of high-performance moisture seals.
- Polyimide substrate supply concentration:Three Japanese chemical conglomerates control over 80% of optical-grade PI resin capacity, creating input vulnerability.
- Yield drag from laser lift-off processing:Thermal stress during substrate separation destroys 15-20% of panels at Gen 6 scale, elevating effective unit costs.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Component-level incentives are drawing display module assembly away from traditional East Asian hubs.
- Transparent OLED architectural glazing:Commercial building retrofits in Middle Eastern commercial districts are testing switchable transparency for solar heat management.
- 5G mmWave antenna integration:Radio-transparent flexible substrates enable antenna-in-display architectures that rigid alternatives cannot match.
Industry Challenges
- Cleanroom construction lead times:Gen 8.5 fab builds require 36-48 months from groundbreaking to qualified production, locking capital without revenue.
- Cross-border IP licensing friction:OLED deposition equipment patents held by Korean and Japanese toolmakers create royalty stacking for new entrants.
- Fold reliability certification timelines:200,000-cycle bend testing protocols add 6-9 months to smartphone OEM qualification schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible OLED Market |
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $174.1 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Tablets, Wearables, TV Displays Application: Consumer Electronics, Automotive Displays, Industrial Equipment, Medical Devices Technology: AMOLED, PMOLED, Transparent OLED, Micro OLED End User: Retail, Home Automation, Education, Entertainment |
| Companies Covered | Samsung Electronics, LG Display, BOE Technology Group, AU Optronics, Universal Display Corporation, Visionox Technology, Royole Corporation, Tianma Microelectronics, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible OLED Market Emerging Trajectories
Display technology trajectories are compressing form-factor constraints while regulatory chemistry mandates and procurement concentration are rewriting competitive entry requirements across the value chain.
Hybrid organic-inorganic thin-film encapsulation is collapsing the thickness-performance tradeoff that previously forced device designers to choose between durability and bend radius. Automotive tier-one suppliers are adopting these stacks for curved cockpit displays ahead of consumer electronics refresh cycles. The technology is collapsing the barrier between premium smartphone and mass-market automotive specifications.
China's GB standards for electromagnetic emissions from foldable devices are tightening test protocols for 5G-integrated flexible modules. MIIT certification timelines have extended by 4-6 weeks as radiated spurious emission limits compress. Domestic OEMs are responding by pre-qualifying antenna-display integration designs before final industrial design lock.
Smartphone OEM procurement is consolidating panel allocation around dual-source strategies that split volume between Korean and Chinese suppliers. Flagship launch programs now require qualified second sources before volume commitments, displacing sole-source arrangements that dominated 2019-2022 procurement patterns. This pattern is most pronounced in Guangdong-based device assembly operations serving European and Middle Eastern distribution channels.
Flexible OLED Market Segmentation
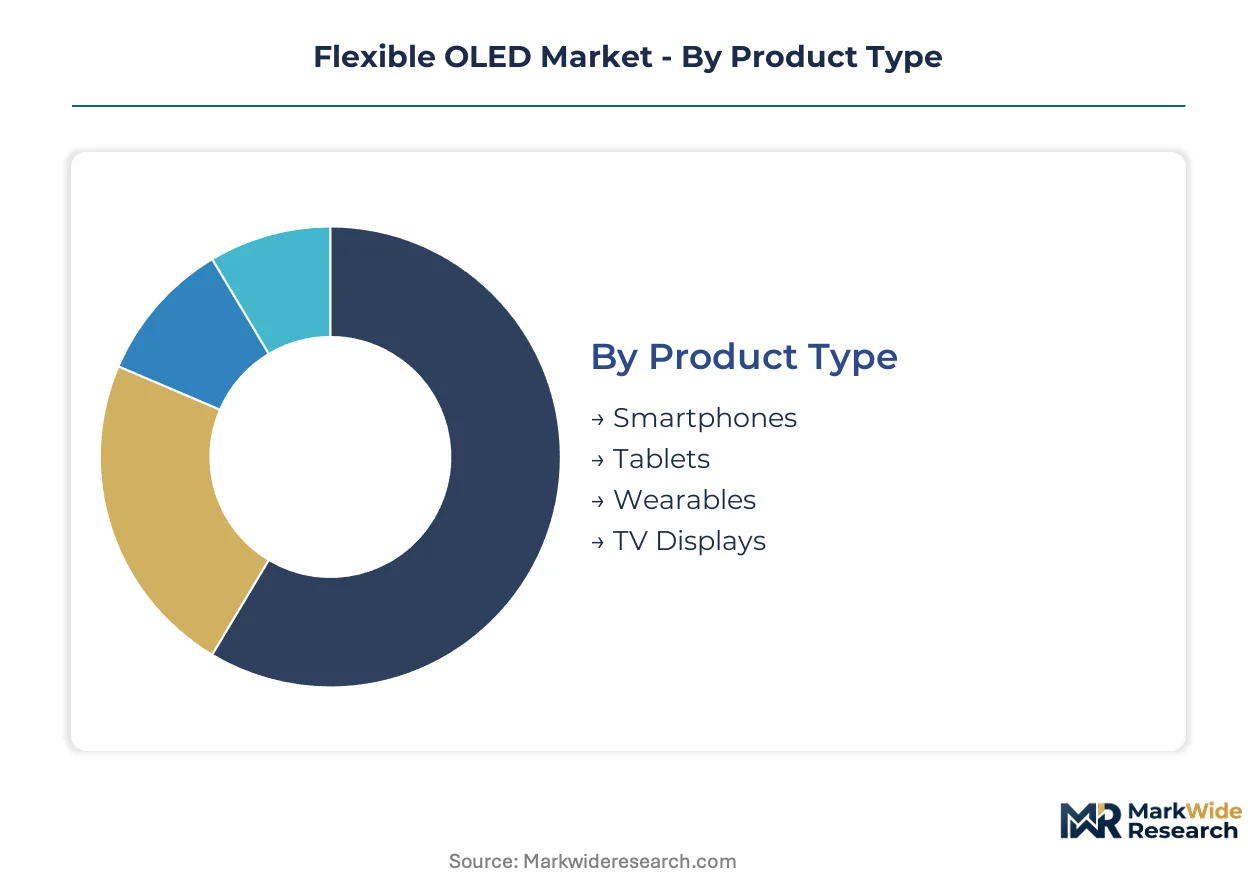
Flexible OLED segmentation reveals how substrate engineering and deposition chemistry align with distinct performance requirements across device categories. Understanding these divisions exposes where margin pools concentrate and which technology transitions will reshape procurement patterns.
Product Type:
The use-case spectrum spans pocket-scale foldables to wall-scale installations, each imposing unique mechanical and optical specifications on panel architecture.
- Smartphones:Displays fabricated on polyimide substrates achieve sub-5mm bend radii for clamshell and book-style foldables. Samsung Electronics and Chinese OEMs in Guangdong Province drive procurement concentration for flagship launches requiring 200,000-cycle mechanical certification.
- Wearables:Ultra-thin glass hybrid stacks balance scratch resistance with wrist-conforming curvature. Apple Watch and fitness tracker demand in Shenzhen's manufacturing corridor sustains dedicated Gen 4.5 fab capacity.
- Tablets:Larger active areas amplify stress concentration at fold hinges, slowing adoption relative to smartphone form factors.
- TV Displays:Rollable demonstrators remain exhibition-grade due to yield penalties from laser lift-off processing at Gen 8.5 scale.
The dominant share belongs to Smartphones, while Wearables is closing the gap fastest.
Application:
Cost tier stratification separates premium consumer devices from regulated industrial and medical certifications.
- Consumer Electronics:Flagship smartphone and tablet launches concentrate volume shipments and margin extraction. South Korean panel makers leverage captive AMOLED capacity to secure design wins for foldable refreshes.
- Automotive Displays:Curved instrument clusters and pillar-to-pillar screens impose thermal cycling and vibration specifications beyond consumer-grade reliability. LG Display has dedicated production lines for tier-one supplier qualification.
- Industrial Equipment:Ruggedized flexible panels for field-service tablets require enhanced moisture barrier performance under REACH chemical restrictions.
- Medical Devices:Sterilization-compatible encapsulation and biocompatibility certification extend development timelines for surgical display applications.
Consumer Electronics commands the volume base, though Automotive Displays is expanding most quickly as cockpit digitization accelerates.
Technology:
Volume concentration tilts toward active-matrix architectures while emissive-layer innovations unlock specialized applications.
- AMOLED:Thin-film transistor backplanes enable high refresh rates and variable refresh for power management. Samsung Display and BOE Technology Group have scaled Gen 6 capacity for smartphone and tablet production.
- Transparent OLED:Partially transparent cathode architectures enable architectural glazing and head-up display applications. Commercial building retrofits in Dubai and Riyadh are testing switchable transparency for solar heat management.
- PMOLED:Passive-matrix addressing suits low-information-content applications with limited pixel counts and simpler driver requirements.
- Micro OLED:Silicon backplane integration delivers pixel densities for augmented reality headsets, though wafer-scale processing constrains panel dimensions.
AMOLED holds the installed capacity advantage, yet Transparent OLED is gaining share fastest as building-integrated photovoltaics converge with display functionality.
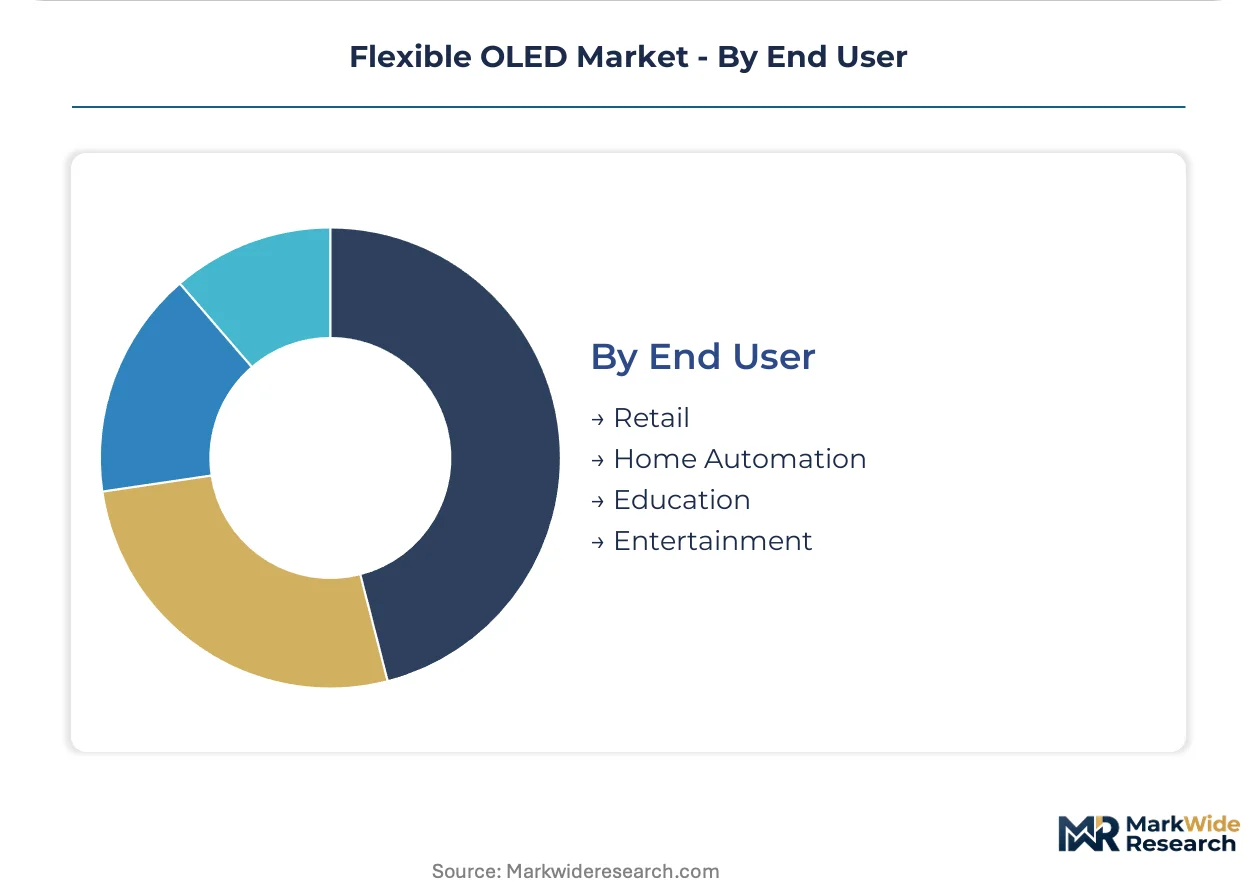
End User:
Customer-type differentiation separates mass-market volume from specialized integration requirements.
- Retail:Curved signage and interactive fitting-room mirrors deploy flexible panels for spatial design flexibility. Guangdong-based integrators serve European luxury retail rollouts.
- Home Automation:Concealed control surfaces and rollable television concepts test consumer willingness to pay premium pricing for form-factor novelty.
- Education:Foldable whiteboard and portable presentation displays remain pilot-stage due to durability concerns in high-touch environments.
- Entertainment:Immersive exhibition installations and concert stage backdrops exploit flexible OLED's weight reduction versus LED walls.
Retail captures the current deployment lead, while Home Automation is climbing the fastest as smart home ecosystems integrate display surfaces.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's export credit terms for display equipment and China's state-backed fab financing are redrawing manufacturing maps faster than demand shifts alone would predict.
South Korea
Seoul's Ministry of Trade, Industry and Energy calibrates export credit support for OLED deposition equipment shipments to Vietnam and India. Samsung Display and LG Display anchor the Gyeonggi-do cluster where Gen 6 flexible lines achieve qualified yields ahead of regional competitors. The Korea Development Bank extends project finance terms that compress payback periods for captive AMOLED capacity additions.
China
MIIT certification timelines for 5G-integrated flexible modules have extended 4-6 weeks under tightened GB electromagnetic emission standards. BOE Technology Group and Visionox Technology scale Gen 6 capacity in the Chengdu-Chongqing corridor where polyimide substrate logistics costs run below coastal alternatives. The country's dual carbon goals are accelerating laser lift-off processing efficiency investments to curb energy intensity per panel.
Japan
METI industrial technology grants support thin-film encapsulation research at consortiums linking chemical conglomerates to display toolmakers. Three optical-grade polyimide resin suppliers concentrate capacity in the Kansai region, creating input vulnerability for downstream panel fabrication. Osaka-based material specialists are reformulating fluorinated barrier chemistries to anticipate REACH restriction expansions.
Germany
ECHA REACH restrictions on perfluorinated encapsulant precursors are forcing reformulation of moisture barrier layers for automotive-grade flexible displays. Stuttgart-area tier-one suppliers qualify curved cockpit screens from Asian panel makers under KBA automotive safety protocols. The EU Ecodesign for Sustainable Products Regulation is accelerating closed-loop recycling infrastructure investments across Bavarian manufacturing corridors.
United States
FCC certification of radio-integrated flexible modules for 5G mmWave compatibility shapes antenna-in-display architectures for flagship smartphone launches. Apple procurement teams in Cupertino dual-source panel allocation between Korean and Chinese suppliers under post-2022 qualification protocols. The Inflation Reduction Act's advanced manufacturing credits have not yet extended to display fabrication, leaving module assembly cost-competitive only for Mexico-proximate logistics.
Flexible OLED Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a market structure consolidating around capital-heavy conglomerates with captive AMOLED capacity. Samsung Electronics and BOE Technology Group exemplify the scale-driven archetype leveraging project finance for multi-billion-dollar fab build-outs. LG Display and AU Optronics occupy the application-specialist tier targeting automotive and industrial certifications respectively. Competitive moves center on capacity expansion timing and strategic partnerships for deposition equipment access rather than price-based rivalry.
Among Korean and Chinese conglomerates, Samsung Electronics, BOE Technology Group, and LG Display exemplify three distinct competitive archetypes. Samsung Electronics represents the vertically integrated device-maker model where captive panel supply secures flagship smartphone design wins. BOE Technology Group occupies the state-backed capacity scaler position with credit facilities enabling aggressive Gen 6 expansion timelines. LG Display exemplifies the application-diversification archetype through dedicated automotive-grade production lines that anchor tier-one supplier relationships. Universal Display Corporation and Visionox Technology sit within the technology-licensing and regional-specialist tiers respectively, though their strategic positioning remains contingent on patent access and domestic procurement patterns.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Display |
| BOE Technology Group |
| AU Optronics |
| Universal Display Corporation |
| Visionox Technology |
| Royole Corporation |
| Tianma Microelectronics |
| Panasonic Corporation |
| Others |
Supply Flow & Price Mechanics
Japanese optical-grade polyimide resin concentration in the Kansai region funnels margin capture toward substrate suppliers, leaving panel makers to absorb yield-driven cost volatility from laser lift-off processing.
Pricing Analysis
Certification level creates the primary spread, with automotive-grade panels commanding substantial premiums over consumer electronics specifications due to KBA thermal cycling protocols. Three-tier pricing structure across premium, standard, and economy levels segments by bend radius tolerance and encapsulant barrier performance. Pricing pressure stems from yield drag at Gen 6 scale, where thermal stress destroys panels during substrate separation. Tier-one automotive suppliers exhibit lowest price sensitivity due to long-term qualification timelines, while Guangdong-based smartphone OEMs drive hardest bargain on volume commitments.
Supply Chain Analysis
Export controls on OLED deposition equipment constrain capacity expansion outside Korea and China, limiting tool availability for new entrants. Manufacturing gravity centers on South Korea, China, and Japan, with polyimide substrate supply anchored in Japanese chemical conglomerates. The value chain draws from fluorinated precursors, ultra-thin glass, and thin-film transistor backplanes as critical inputs. Single-source vulnerability concentrates in optical-grade PI resin, where three suppliers control over four-fifths of capacity. Distribution runs through tier-one automotive suppliers and flagship smartphone OEMs with qualified vendor lists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flexible OLED is approaching a platform-economics inflection where antenna-in-display architectures and foldable form factors create interoperability lock-in comparable to early smartphone ecosystem consolidation.
For Market Incumbents: Pre-empt transparent OLED architectural glazing deployment in Middle Eastern commercial districts before specialty glass competitors establish specification control. Secure dedicated production lines for automotive-grade curved cockpit displays, as tier-one supplier relationships harden around qualified sources. Vertical integration into thin-film encapsulation materials buffers REACH restriction volatility on fluorinated chemistry.
For New Entrants and Emerging Players: India's PLI scheme for electronics manufacturing offers component-level assembly incentives that reduce capital barriers versus Gen 6 fab builds. Target medical device sterilization-compatible encapsulation, where biocompatibility certification extends development timelines but limits incumbent response speed. Pursue white-label partnerships with Guangdong-based integrators serving European luxury retail signage rollouts.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with state-backed Chinese panel makers facing subsidy investigation headwinds from trading partners. Long-term viability hinges on deposition equipment patent access and qualified yield trajectories at Gen 8.5 scale. Watch Korea's Ministry of Trade, Industry and Energy export credit recalibration as early signal of competitive financing asymmetry shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Automotive-Grade Production Line Qualification | LG Display's dedicated lines anchor tier-one supplier relationships under KBA protocols. |
| Thin-Film Encapsulation Material Backward Integration | Hybrid organic-inorganic stacks collapse thickness-performance tradeoffs for curved cockpit screens. |
| Transparent OLED Architectural Glazing Pilot | Dubai and Riyadh commercial retrofits test switchable transparency for solar heat management. |
| Antenna-in-Display 5G mmWave Certification | FCC certification shapes radio-transparent substrate architectures that rigid alternatives cannot match. |
| Closed-Loop Recycling Infrastructure Investment | EU Ecodesign Regulation accelerates material recovery mandates across Bavarian manufacturing corridors. |
Methodological Framework
A standing panel of display fab operations directors, tier-one automotive supplier procurement leads, smartphone OEM panel sourcing managers, and thin-film encapsulation R&D directors provided ongoing calibration. Primary fieldwork combined structured interviews with deposition equipment toolmakers and polyimide resin specialists, validated against SEC filings from Samsung Electronics and BOE Technology Group, MIIT certification disclosure databases, and ECHA REACH restriction amendment notices. Bottom-up capacity build-out tracking and top-down demand segmentation by device category were triangulated against customs trade data for OLED panel shipments.
Scenario bracketing anchored volume projections across technology adoption curves for foldable smartphones, curved automotive displays, and transparent architectural glazing. Segmentation dimensions modeled include substrate type, application tier, end-use industry, and regional manufacturing cluster. CAGRs were derived from qualified yield trajectories at Gen 6 and Gen 8.5 scale, laser lift-off processing efficiency improvements, and procurement concentration shifts in Guangdong Province. Forecast inputs incorporated REACH chemical restriction expansion timelines and Korea Development Bank export credit term adjustments.
Practitioners should monitor yield breakthroughs at Gen 8.5 scale and automotive cockpit digitization acceleration for early signals of demand inflection. Forecasts reflect assumptions around polyimide substrate supply continuity and deposition equipment patent licensing friction. Material shifts in EU fluorinated encapsulant restriction scope or Japan-South Korea trade control escalations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
North America Head-Up Display Market
Display Technologies
1440p Gaming Monitors Market
Display Technologies
Global Portable Monitor Market
Display Technologies
Display Fingerprint Technology Market
Display Technologies
4K Drawing Tablet with Screen Market
Display Technologies
Multi-Touch Screen Market
Display Technologies
Global 4K Display Resolution Market
Display Technologies
Surface-Conduction Electron-Emitter Display (SED) Market
Display Technologies
Digital Kiosk Display Market
Display Technologies
Digital Holographic Display Market
Display Technologies
Asia-Pacific Industrial Display Market
Display Technologies
United States Microdisplay Market
Display Technologies
IGZO Display Market
Display Technologies
Visual Computing Market
Display Technologies
Thin Display Technology Market
Display Technologies
Europe Transparent Conductive Films Market