
 Architectural LED Products Market | 2026-2036
Architectural LED Products Market Size, Share, and Industry Trends Forecast 2026-2036
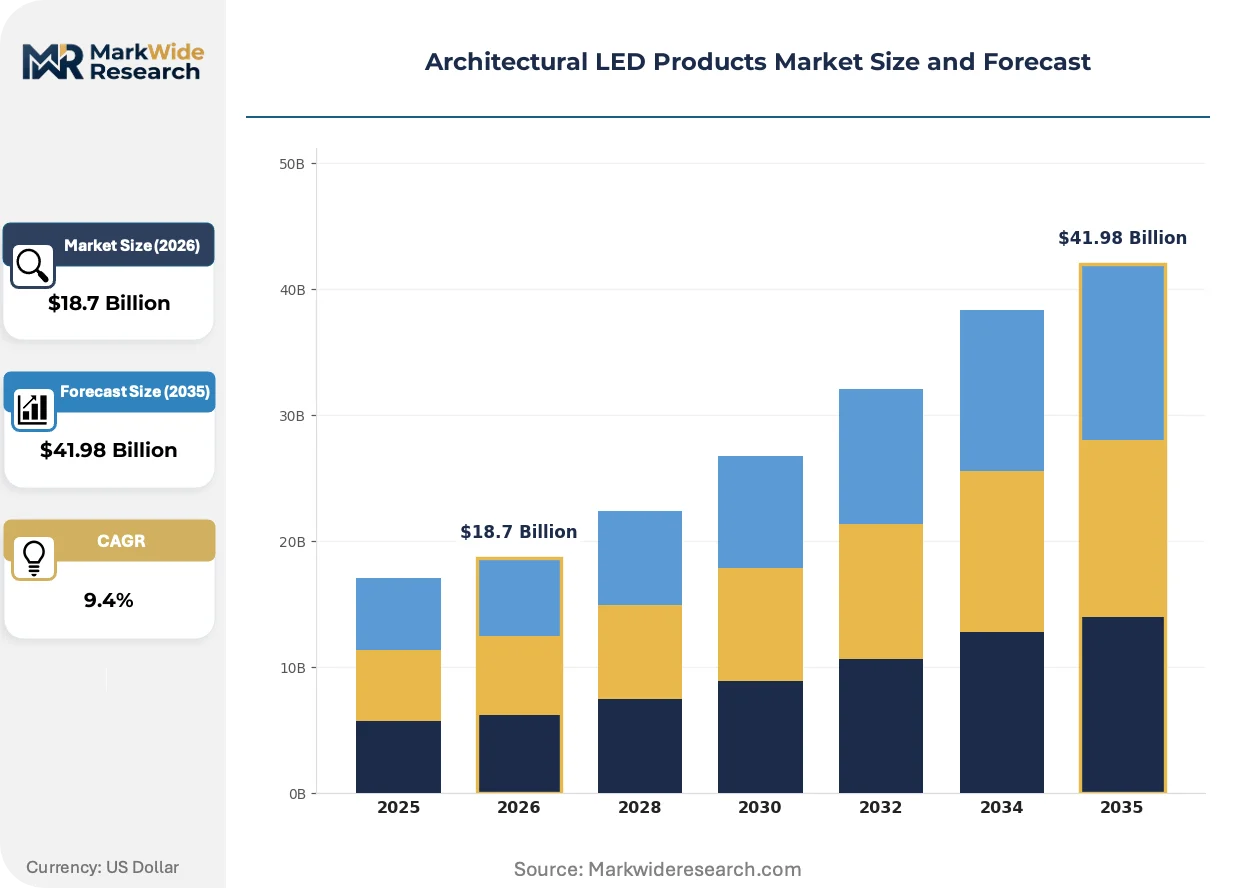
Architectural LED Products Market Outlook
Multi-source component procurement for driver ICs and optical assemblies is consolidating around vertically integrated domestic suppliers. Signify leverages captive semiconductor sourcing to control bill-of-material volatility. Acuity Brands anchors North American specification channels through deep agent relationships with electrical contractors. Fagerhult competes in Nordic healthcare and education segments with circadian-rhythm-optimized product families.
Architectural LED products are solid-state luminaires employing gallium nitride emitters, aluminum or polymer heat sinks, and constant-current drivers to deliver directional or ambient illumination for built environments. Thermal management design determines lumen maintenance over fifty-thousand-hour operational life, while optical engineering shapes beam angles for facade grazing or cove washing. Recessed lights dominate volume in commercial new construction where ceiling plenum depth constraints favor low-profile housings. Strip lights represent the fastest-expanding category as linear coves and millwork integration displace fluorescent T5 systems in hospitality and retail fit-outs. Smart lighting technology commands premium positioning where BACnet and DALI-2 integration enables daylight harvesting and occupancy-based dimming.
The US Department of Energy enforces ENERGY STAR and DLC Premium qualification criteria that filter non-compliant imports from utility rebate programs. Europe's Ecodesign Directive and CE marking under the Low Voltage Directive mandate electromagnetic compatibility and photobiological safety testing for market access. China's GB standards and CCC certification require domestic testing laboratory validation for products sold through state-owned procurement channels. Stakeholders must monitor evolving interoperability standards between proprietary smart lighting ecosystems and open-protocol building management systems.
Market Dynamics
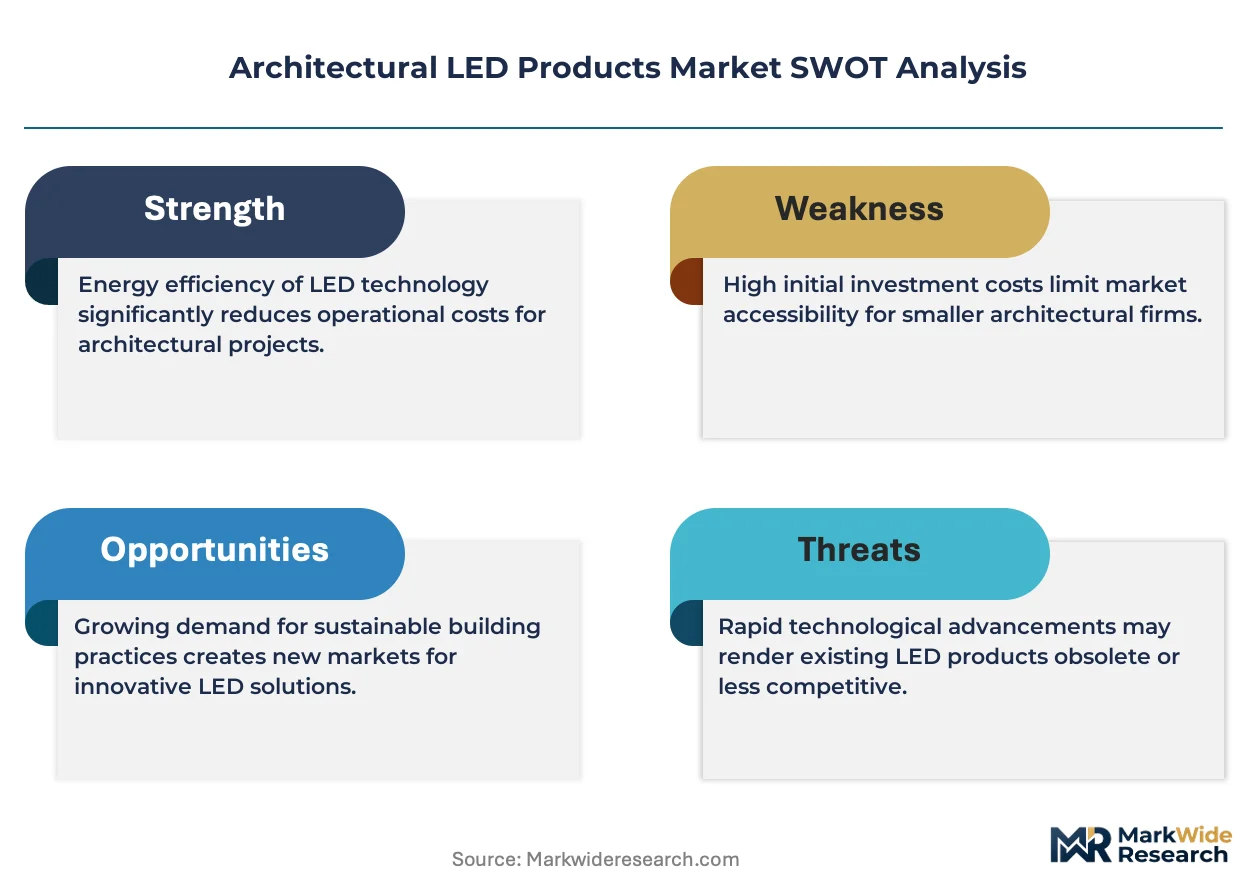
Europe's Ecodesign Directive is compressing product lifecycles by mandating minimum efficacy thresholds that obsolete legacy luminaire designs before natural replacement cycles conclude.
Growth Catalysts
- Healthcare Circadian Lighting:Nordic hospital systems specify tunable-white systems for patient recovery optimization. Fagerhult's rhythm-optimized families demonstrate clinical efficacy in Stockholm and Copenhagen facilities.
- China Infrastructure Renewal:State-owned procurement channels favor LED retrofits for municipal building stock under GB standards compliance mandates.
- Smart Building Integration:BACnet and DALI-2 protocols enable daylight harvesting in commercial new construction. Specifiers bundle lighting controls with HVAC management for unified building automation.
Market Restraints
- Driver IC Supply Concentration:Semiconductor fabrication for constant-current drivers concentrates in Taiwan and South Korea foundries. Geopolitical friction threatens bill-of-material stability for luminaire assemblers.
- Thermal Management Cost Structure:Aluminum heat sink extrusions face energy-intensive production penalties under EU carbon border adjustments. Polymer alternatives trade thermal conductivity for weight reduction.
- Fluorescent T5 Substitution Lag:Budget-constrained hospitality operators in secondary markets delay LED strip retrofits despite T5 phase-out schedules.
Strategic Opportunities
- German Deep Retrofit Programs:Federal building efficiency mandates create specification volume for recessed downlight replacements in Berlin and Munich commercial cores.
- Li-Fi Convergence:Visible light communication integration transforms luminaires into data transmission nodes. Early deployments target electromagnetic-sensitive healthcare environments.
- Utility Rebate Channel Expansion:US Department of Energy ENERGY STAR qualification opens DLC Premium access for rebate-eligible specification in California and New York utility territories.
Industry Challenges
- Optical Engineering Talent Scarcity:Beam angle design for facade grazing applications requires specialized photometric simulation expertise. Universities produce fewer illumination engineers than market demand absorbs.
- CCC Certification Timelines:China's mandatory product certification requires domestic laboratory validation cycles that delay market entry for European and North American manufacturers.
- Legacy Fluorescent Ballast Integration:Retrofit projects encounter incompatible ceiling plenum depths and wiring configurations that complicate LED module installation in 1980s commercial stock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Architectural LED Products Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recessed Lights, Wall Sconces, Strip Lights, Floodlights Application: Commercial Buildings, Residential Areas, Outdoor Spaces, Exhibition Halls Installation Type: New Construction, Retrofits, Remodels, Pre-Engineered Technology: Smart Lighting, Solar-Powered, Dimmable, RGB |
| Companies Covered | Artemide, Trilux, Acuity Brands, Regent, IGuzzini, Signify, Flos, DMF Lighting, Fagerhult, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Architectural LED Products Market Strategic Shifts
Human-centric lighting specifications are migrating from healthcare niches into mainstream commercial development, rewiring how architects program circadian effects through tunable spectral output.
Mini-LED chip-scale packaging is rewriting optical density limits for linear cove applications. Hospitality designers in Dubai and Singapore specify sub-5mm pitch strips for millwork integration without visible diode patterning. The technology compresses fixture profile depths by sixty percent versus conventional SMD arrays.
Europe's Ecodesign Directive tightens minimum efficacy thresholds for directional lamps and luminaires. Manufacturers must redesign optical assemblies and driver electronics to maintain lumen output while reducing wattage. German specification channels filter non-compliant imports from project shortlists.
Electrical contractor specification influence is consolidating around agent relationships with national distribution. Contractors in Texas and Florida markets bundle lighting packages with broader electrical infrastructure bids. This compresses direct manufacturer engagement with end-user architects.
Architectural LED Products Market Segmentation
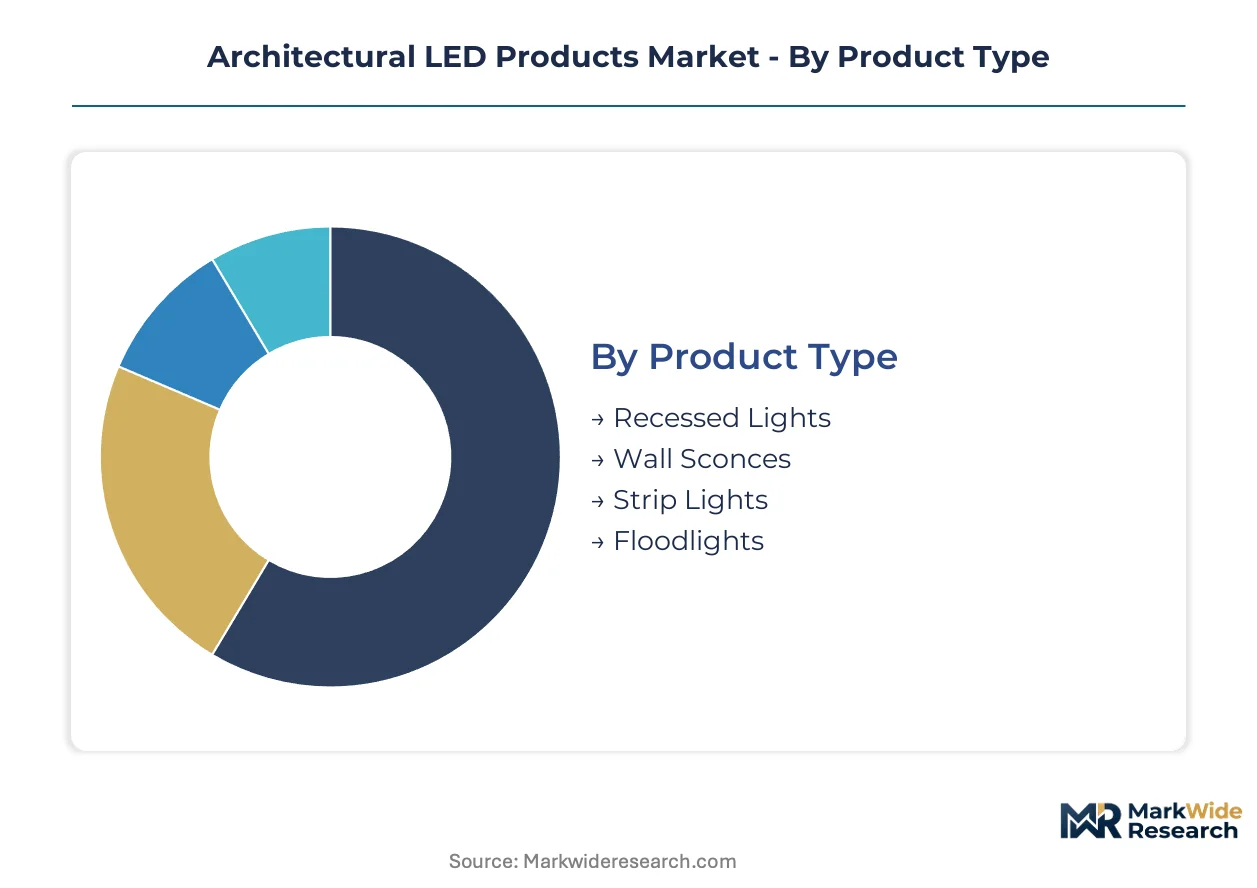
Architectural LED product segmentation reveals how specification channels, installation constraints, and control protocols fragment demand across built environment verticals. Understanding these axes illuminates where procurement authority concentrates and which technology investments command premium positioning.
Product Type:
Optical form factor and thermal envelope specifications differentiate how luminaires integrate into ceiling, wall, and facade assemblies.
- Recessed Lights:Low-profile housings with die-cast aluminum heat sinks dominate commercial new construction where plenum depth constraints limit fixture height. Germany and the United States specification channels filter for ENERGY STAR and DLC Premium compliance in federal and municipal retrofit programs.
- Strip Lights:Linear cove systems with mini-LED chip-scale packaging achieve sub-5mm pitch for millwork integration without visible diode patterning. Hospitality designers in Dubai and Singapore specify these for bar fronts and ceiling reveals, displacing fluorescent T5 systems fastest.
- Wall Sconces:Directional grazing fixtures for facade illumination and corridor ambient lighting.
- Floodlights:High-output arrays for exterior facade washing and landscape accent applications.
Recessed lights lead on specification volume; strip lights lead on momentum.
Application:
End-use environments impose distinct photometric, control, and durability requirements that reshape product configuration.
- Commercial Buildings:Tunable-white systems with BACnet and DALI-2 integration enable daylight harvesting and occupancy-based dimming in office and retail cores. Nordic hospital systems specify circadian-optimized families for patient recovery, expanding from healthcare niches into mainstream wellness-focused development.
- Outdoor Spaces:IP-rated enclosures with polymer heat sinks face EU carbon border adjustment penalties on aluminum alternatives, shifting procurement toward domestic European extruders.
- Residential Areas:Smart home ecosystem compatibility drives specification in high-end single-family and multi-family developments.
- Exhibition Halls:High-CRI track and flood systems for artifact and artwork illumination with precise beam control.
Commercial buildings concentrate specification authority; outdoor spaces face the steepest regulatory compliance burden.
Installation Type:
Project delivery mode determines whether luminaire selection occurs during design development or post-occupancy retrofit.
- New Construction:Early-stage specification through electrical contractor agent relationships bundles lighting with broader infrastructure bids, compressing direct manufacturer engagement with architects.
- Retrofits:LED module replacement of legacy fluorescent systems dominates China state-owned procurement under GB standards compliance mandates for municipal building stock renewal.
- Remodels:Tenant improvement projects with accelerated timelines favor pre-configured luminaire packages.
- Pre-Engineered:Modular assemblies for rapid deployment in standardized commercial building prototypes.
New construction captures the deepest specification influence; retrofits expand fastest where infrastructure renewal programs prioritize LED conversion.
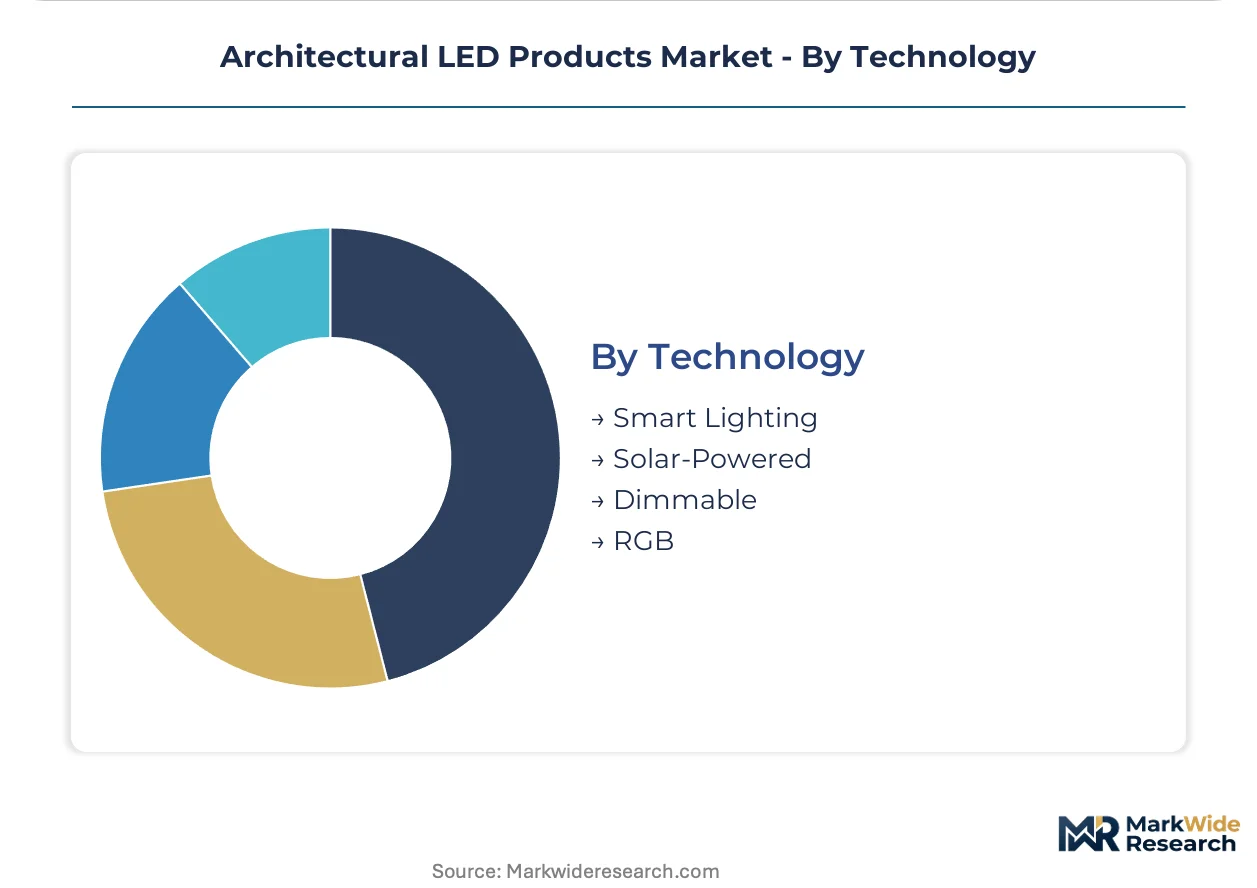
Technology:
Control protocol and power architecture differentiation separates premium specification from commodity replacement.
- Smart Lighting:BACnet and DALI-2 protocol integration enables unified building automation with HVAC management systems, commanding premium positioning in California and New York utility rebate territories.
- Dimmable:Phase-cut and 0-10V control compatibility remains baseline for commercial specification where energy codes mandate automatic daylight responsiveness.
- Solar-Powered:Off-grid autonomous systems for remote exterior applications with integrated battery storage.
- RGB:Color-mixing arrays for dynamic facade illumination and experiential retail environments.
Smart lighting leads on margin expansion; dimmable maintains the broadest specification base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's specification channels anchor architectural LED procurement through federal building efficiency mandates and deep retrofit programs in Berlin and Munich commercial cores.
Germany
The Ecodesign Directive compresses product lifecycles by tightening minimum efficacy thresholds for directional lamps. Federal building efficiency mandates create specification volume for recessed downlight replacements. Berlin and Munich commercial cores concentrate procurement authority through electrical contractor agent relationships.
China
State-owned procurement channels favor LED retrofits for municipal building stock under GB standards compliance mandates. CCC certification requires domestic testing laboratory validation for products sold through state procurement. Yangtze River Delta manufacturing clusters supply optical assemblies and driver components to domestic luminaire assemblers.
United States
Commercial building developers accelerate specification of tunable-white systems for wellness-focused interiors. The Department of Energy enforces ENERGY STAR and DLC Premium qualification criteria that filter non-compliant imports from utility rebate programs. California and New York utility territories command premium positioning for smart lighting with BACnet integration.
Sweden
Nordic hospital systems specify tunable-white systems for patient recovery optimization. Fagerhult's rhythm-optimized families demonstrate clinical efficacy in Stockholm facilities. The country's healthcare procurement channels filter for circadian-rhythm-optimized product families in education and hospital segments.
United Arab Emirates
Hospitality designers in Dubai specify mini-LED chip-scale packaging strips for millwork integration without visible diode patterning. MOHAP regulates electromagnetic compatibility for healthcare environment deployments. Dubai and Abu Dhabi commercial fit-outs displace fluorescent T5 systems fastest in luxury retail and hotel sectors.
Architectural LED Products Market Competitive Environment
Global majors compete with regional champions across specification channels and control protocol integration. The vendor base separates into three tiers: vertically integrated semiconductor owners, specification-channel specialists with deep electrical contractor relationships, and component assemblers serving price-sensitive retrofit markets. Dominant competitive moves include backward integration into driver IC sourcing and geographic expansion through agent relationship networks with national distribution.
Among European lighting specialists, Signify, Fagerhult, and IGuzzini occupy distinct archetype positions. Signify exemplifies the vertically integrated model through captive semiconductor sourcing that controls bill-of-material volatility. Fagerhult anchors the healthcare and education specification segment with circadian-rhythm-optimized positioning. IGuzzini represents Italian design-forward fabrication serving facade grazing and architectural accent applications.
| Leading Market Players |
|---|
| Artemide |
| Trilux |
| Acuity Brands |
| Regent |
| IGuzzini |
| Signify |
| Flos |
| DMF Lighting |
| Fagerhult |
| Others |
Value Chain & Pricing Dynamics
Gallium nitride wafer costs transmit directly from Taiwanese foundries through driver IC assemblies to luminaire pricing tiers, with premium smart-lighting configurations absorbing volatility through captive semiconductor sourcing while standard retrofit modules face margin compression from spot-market component exposure.
Pricing Analysis
Input-cost pass-through from aluminum heat sink extrusions and constant-current driver ICs stratifies luminaire pricing across three tiers. Premium positioning commands differentiation through ENERGY STAR and DLC Premium certification bundling with BACnet integration, while economy retrofit modules compete on per-lumen cost in municipal procurement channels. Pricing pressure stems from EU carbon border adjustments on aluminum-intensive thermal management components. Commercial contractors demonstrate lowest price sensitivity where utility rebates offset first cost, whereas budget-constrained hospitality operators in secondary markets delay specification.
Supply Chain Analysis
Photoresist and specialty chemical supply for gallium nitride epitaxy rests on Japanese and South Korean producers, with wafer fabrication concentrating in Taiwan and driver IC packaging in Malaysia and China. Aluminum extrusions for heat sinks draw from domestic European and North American mills facing energy cost penalties, while optical-grade polymers source from German and US specialty compounders. Single-source vulnerability concentrates in 200mm gallium nitride wafer supply from two foundry operators. Distribution runs through electrical contractor agent relationships with national distribution houses, compressing direct manufacturer access to end-user architects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Architectural LED Products Market functions as a stable compounder, with infrastructure renewal mandates across Germany, China, and the United States delivering replacement-cycle visibility that insulates revenue streams from cyclical construction volatility.
For Market Incumbents: Deploy backward integration into driver IC sourcing to insulate bill-of-material volatility from Taiwan foundry concentration. Deepen specification channel control through exclusive agent relationships with electrical contractors in Texas and Florida markets, where bundled infrastructure bids compress competitor access. Counter Fagerhult's circadian-rhythm positioning with tunable-white product family investments targeting Nordic healthcare procurement channels. For New Entrants and Emerging Players: Enter via Li-Fi convergence applications in electromagnetic-sensitive healthcare environments, where early deployment partnerships with Dubai and Abu Dhabi hospital systems bypass entrenched specification channels. Target German deep retrofit programs for recessed downlight replacements, where federal building efficiency mandates create volume without requiring established electrical contractor relationships. Pursue white-label manufacturing for state-owned procurement channels in China under GB standards compliance. For Investors and Strategic Acquirers: Consolidation pressure builds where optical engineering talent scarcity constrains product development velocity for mid-tier assemblers. Long-term viability favors vertically integrated players with captive semiconductor sourcing and established specification channel relationships over component assemblers serving price-sensitive retrofit markets. Acquisition target archetypes include circadian-optimization specialists with clinical validation in Nordic healthcare systems and mini-LED packaging technology holders. Watch for inflection where Ecodesign Directive efficacy threshold revisions accelerate legacy luminaire obsolescence beyond natural replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Driver IC Sourcing | Captive semiconductor supply insulates Signify and Acuity Brands from Taiwan foundry volatility and geopolitical friction. |
| Circadian-Rhythm Product Family Launch | Fagerhult's clinical validation in Stockholm facilities creates specification preference in Nordic healthcare procurement channels. |
| Li-Fi Technology Integration | Visible light communication transforms luminaires into data nodes for electromagnetic-sensitive Dubai healthcare deployments. |
| Deep Retrofit Program Participation | Berlin and Munich federal building mandates create volume for ENERGY STAR-compliant recessed downlight replacements. |
| Smart Lighting Protocol Certification | DALI-2 and BACnet integration unlocks California and New York utility rebate territories for premium positioning. |
Study Parameters
Coverage spans Germany, China, the United States, Sweden, and the United Arab Emirates, with primary inputs from each market's specification channels. The analysis combines structured interviews with electrical contractor agents, lighting specification engineers, and procurement officers at hospital systems and commercial developers with secondary validation from ENERGY STAR qualification databases, Ecodesign Directive regulatory filings, and China GB standards documentation. Bottom-up luminaire shipment data triangulates against top-down construction spending and retrofit program allocations.
Rate-of-change decomposition separates volume effects from value-mix shifts across the projection horizon. The analytical framework models segmentation by product type, application environment, installation mode, and control protocol complexity, with cross-cutting analysis of regional regulatory cluster effects. CAGRs derive from fitted growth curves against historical replacement-cycle data and announced infrastructure renewal program timelines. Industry-specific forecast inputs include Ecodesign Directive efficacy threshold implementation schedules and China state-owned procurement channel LED conversion mandates.
Inputs from electrical contractor agents and hospital procurement officers were available through the study window; gaps in real-time inventory data from Taiwan foundry operators introduce uncertainty bands around driver IC cost assumptions. Forecasts reflect documented assumptions regarding regulatory implementation timelines and infrastructure program funding continuity. A small set of triggers warrants ongoing watch: Ecodesign Directive threshold acceleration, Taiwan semiconductor export restrictions, and China CCC certification timeline extensions for European and North American manufacturers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Smart LED Indoor Signage Market
LED
France LED Lighting Market
LED
North America LED Packaging Market
LED
Middle East LED Lights Market
LED
Surface Mount PLCC Leds Market
LED
Superluminescent Diodes Market
LED
Europe Indoor LED Lighting Market
LED
GCC LED Lighting Market
LED
Gan Micro LED Market
LED
Germany Automotive LED Lighting Market
LED
LED Control Unit Market
LED
UV-C LED Market
LED
Germany LED Lighting Market
LED
LED Light Bar Market
LED
7 Segment LED Displays Market
LED
LED Panel Market