
 Europe LED Lighting Market | 2026-2036
Europe LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Europe LED Lighting Market Analysis
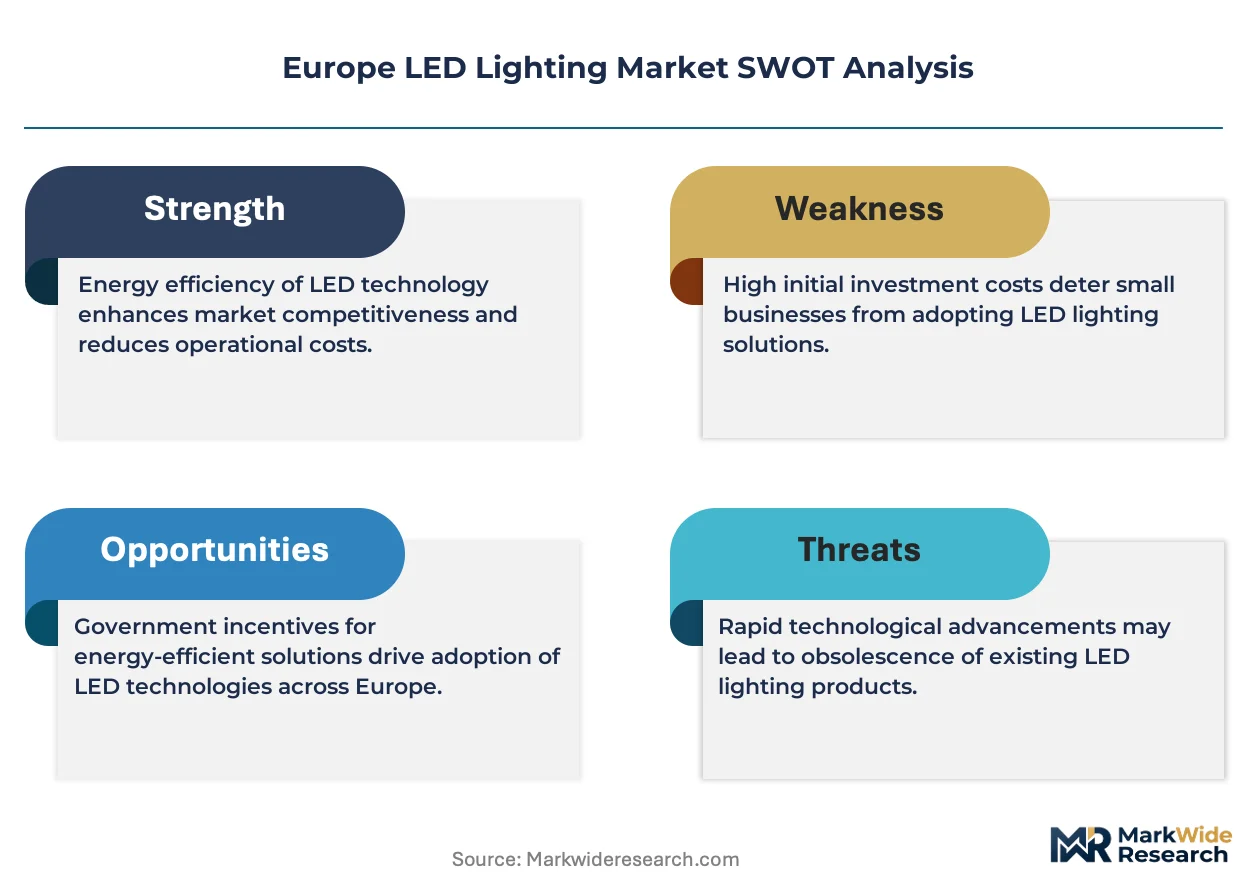
Electrical engineering talent scarcity across Central Europe is bifurcating the competitive landscape between capital-rich incumbents and specialized mid-tier firms. Signify leverages its in-house semiconductor packaging capabilities to control chip-to-fixture cost curves. Zumtobel Group anchors its position through architectural specification relationships with premium commercial developers. ams-OSRAM sustains technology leadership in tunable white and human-centric spectral outputs for healthcare and education environments.
Europe LED Lighting comprises solid-state luminaires using gallium nitride or indium gallium nitride semiconductor junctions, typically operating at 80-150 lumens per watt with correlated color temperatures from 2700K to 6500K, designed to replace legacy fluorescent and high-intensity discharge sources in commercial, industrial, and municipal settings. Residential bulb replacement has matured into a low-margin volume category, while smart lighting systems with embedded sensors and wireless controls capture disproportionate margin pools in commercial new-build and deep retrofit projects. Outdoor solar-LED hybrid installations are expanding fastest in peri-urban French and Spanish municipalities seeking to reduce grid-connection costs for street furniture.
The EU Green Deal and Ecodesign Directive, enforced by national market surveillance authorities, are phasing out non-LED sources and mandating minimum luminous efficacy thresholds that reshape product portfolios. ECHA REACH restrictions on hazardous substances in electronics and the EU AI Act's emerging requirements for autonomous lighting control systems add compliance layers that favor firms with established regulatory affairs functions. Stakeholders must monitor how the EU's expanding carbon border adjustment mechanisms affect imported component economics and whether national recovery funds redirect toward building efficiency rather than new construction.
Market Dynamics
The EU Green Deal's building renovation targets are compressing replacement cycles for installed luminaires while Ecodesign Directive enforcement eliminates legacy fluorescent stock from distribution channels.
Growth Catalysts
- EU Green Deal renovation mandates:Mandatory minimum efficiency thresholds for commercial and residential buildings are accelerating fixture replacement timelines across member states.
- Gallium nitride semiconductor advances:Higher efficacy chips operating above 150 lumens per watt are reducing wattage requirements for equivalent lumen output in street and roadway applications.
- French ESG-linked financing structures:Deep energy renovation loans tied to environmental performance criteria are prioritizing LED retrofits in commercial real estate portfolios.
Market Restraints
- Rare earth element supply concentration:Dependence on phosphor materials sourced through concentrated Asian supply chains creates input cost volatility for white LED production.
- CE marking compliance burden:Ecodesign Directive verification procedures and national market surveillance authority testing protocols extend product launch timelines.
- Electrical engineering talent scarcity:Central European universities are producing insufficient graduates to meet demand for solid-state lighting design and controls integration.
Strategic Opportunities
- Spanish peri-urban solar-LED hybrids:Municipalities seeking grid-independence for street furniture are deploying off-grid luminaires with integrated photovoltaic panels and battery storage.
- Human-centric spectral tuning:Healthcare and education facilities in Germany and Austria are specifying tunable white systems for circadian rhythm optimization.
- EU AI Act autonomous controls:Wireless sensor networks with embedded machine learning for occupancy detection and daylight harvesting will face emerging compliance requirements favoring established regulatory affairs functions.
Industry Challenges
- Embedded systems firmware integration:Smart luminaires require interoperability across proprietary wireless protocols and building management system architectures.
- REACH substance restriction timelines:ECHA evaluations of electronics hazardous substance limits force rapid reformulation of solder alloys and encapsulant materials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe LED Lighting Market |
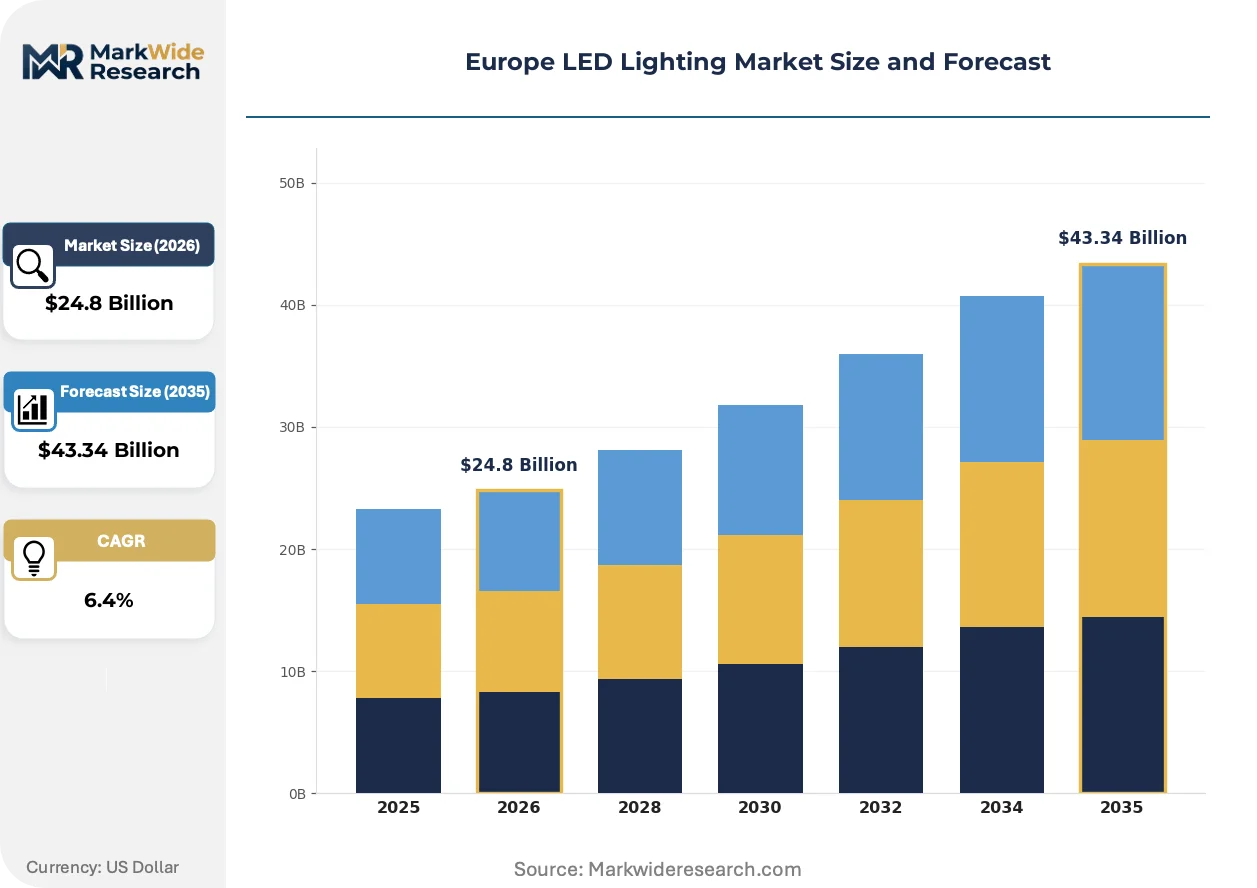
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulbs, Fixtures, Strips, Panels Application: Residential, Commercial, Industrial, Outdoor Technology: Smart Lighting, Solar LED, RGB, Traditional End User: Consumers, Contractors, Retailers, Wholesalers |
| Companies Covered | Signify, Zumtobel Group, ams-OSRAM, Schréder, Fagerhult Group, LEDVANCE GmbH, Legrand, Schneider Electric, ERCO, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe LED Lighting Market Emerging Trajectories
LED driver electronics and optical components are undergoing dimensional compression that enables fixture form factors previously unattainable with conventional thermal management.
Chip-on-board LED arrays are miniaturizing thermal interface requirements while maintaining lumen density. Healthcare facility designers in the Netherlands and Belgium are specifying these compact modules for surgical task lighting and examination luminaires. The reduction in heat sink mass is enabling pendant fixtures with suspended cable rather than rigid conduit mounting systems.
Ecodesign Directive 2019/2020 and its accompanying single lighting regulation are phasing out T8 fluorescent tubes and compact fluorescent lamps from EU distribution. German and Italian electrical wholesalers are clearing remaining legacy stock through discount channels ahead of enforcement deadlines. Commercial retrofit contractors are responding by accelerating specification of integrated LED troffers and linear systems.
Building owners are unbundling lighting system procurement from general electrical contracts and engaging directly with specialized lighting design consultants. French and Swedish commercial developers are separating fixture supply from installation labor through split-package tendering. This disintermediation is most pronounced in Paris and Stockholm office renovation projects where energy performance contracting guarantees require independent verification of installed efficacy.
Europe LED Lighting Market Segmentation
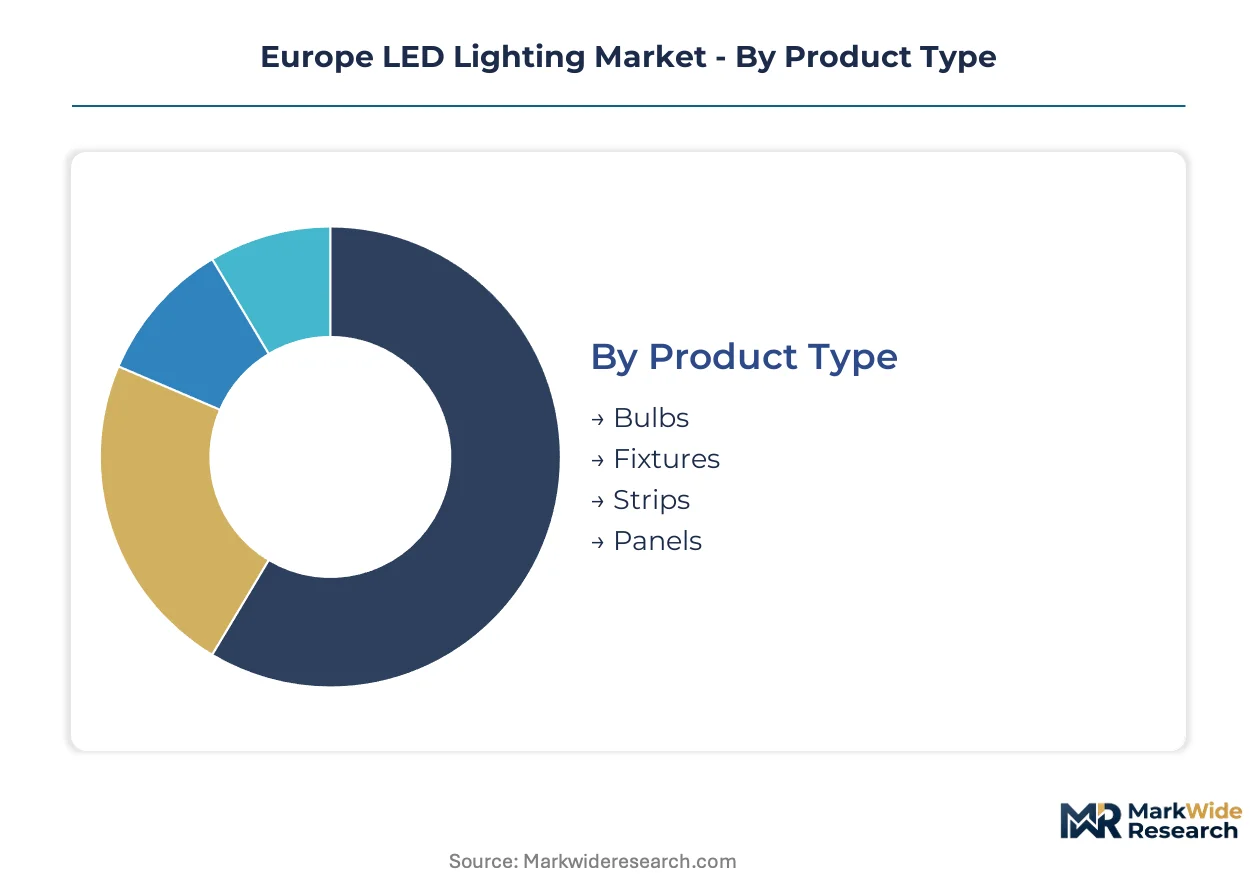
Margin pools in Europe LED Lighting concentrate where specification complexity meets regulatory compliance—architectural fixtures and smart systems command premium positioning, while commoditized bulbs compete on procurement scale. Understanding segment boundaries reveals where technology leadership translates into pricing power versus where volume efficiency determines survival.
Product Type:
Margin concentration follows thermal management sophistication and optical engineering intensity, with architectural fixtures capturing disproportionate value against standardized replacement lamps.
- Fixtures:Integrated luminaires incorporating heat sinks, drivers, and optics into unified housings typically specified for commercial new-build and deep retrofit projects. German and French municipalities prioritize these for street and roadway infrastructure upgrades where Ecodesign Directive minimum efficacy thresholds eliminate legacy fluorescent alternatives. Contractors unbundle fixture procurement from installation labor to secure independent verification of lumen output claims.
- Panels:Recessed or surface-mounted flat-form luminaires using edge-lit or direct-backlit LED arrays for uniform illumination in office and healthcare environments. Demand concentrates in France's commercial real estate retrofit sector where ESG-linked financing structures favor deep energy renovations with guaranteed performance outcomes. The Netherlands and Belgium specify compact chip-on-board variants for surgical task lighting where heat sink mass reduction enables suspended cable mounting.
- Bulbs:Retrofit replacement lamps for existing sockets, now a low-margin volume category with mature penetration across residential channels.
- Strips:Flexible linear LED arrays for cove lighting, signage, and architectural accent applications, typically sold through electrical wholesalers to contractors.
The dominant share belongs to fixtures, while panels are closing the gap fastest.
Application:
Replacement cycle velocity varies sharply across installation contexts, with regulatory pressure accelerating commercial and outdoor segments while residential demand stabilizes.
- Commercial:Office, retail, and hospitality installations where building renovation mandates and energy performance contracting drive specification of tunable white and sensor-integrated systems. Paris and Stockholm developers split-package tendering separates fixture supply from installation labor to meet ESG verification requirements. The EU Green Deal's building renovation targets compress replacement timelines for installed luminaires in this segment.
- Outdoor:Street, roadway, and perimeter lighting where peri-urban municipalities seek grid-independence through solar-LED hybrid configurations. Spanish and French municipalities deploy off-grid luminaires with integrated photovoltaic panels to reduce connection costs for street furniture. Gallium nitride semiconductor advances above 150 lumens per watt reduce wattage requirements for equivalent lumen output in these applications.
- Residential:Homeowner-driven bulb replacement and fixture upgrades, now saturated in Western European markets with limited growth trajectory.
- Industrial:High-bay and task lighting for manufacturing and warehousing environments, prioritizing durability and maintenance access over spectral quality.
Commercial applications anchor revenue concentration, though outdoor installations are expanding most quickly.
Technology:
Intelligence integration and energy autonomy differentiate premium tiers from basic illumination, with firmware capabilities increasingly decisive in competitive positioning.
- Smart Lighting:Luminaires with embedded sensors, wireless controls, and interoperability protocols for occupancy detection and daylight harvesting. Healthcare and education facilities in Germany and Austria specify tunable white systems for circadian rhythm optimization. The EU AI Act's emerging requirements for autonomous control systems favor firms with established regulatory affairs functions.
- Solar LED:Off-grid luminaires combining photovoltaic generation, battery storage, and efficient LED output for grid-independent operation. Peri-urban French and Spanish municipalities favor these configurations to avoid infrastructure connection costs for remote street furniture.
- RGB:Multi-channel LED arrays enabling dynamic color tuning for architectural accent and entertainment environments.
- Traditional:Fixed-output LED sources without connectivity or spectral tuning capabilities, facing displacement by regulatory efficiency mandates.
Smart lighting commands the premium tier, while solar LED is climbing the fastest.
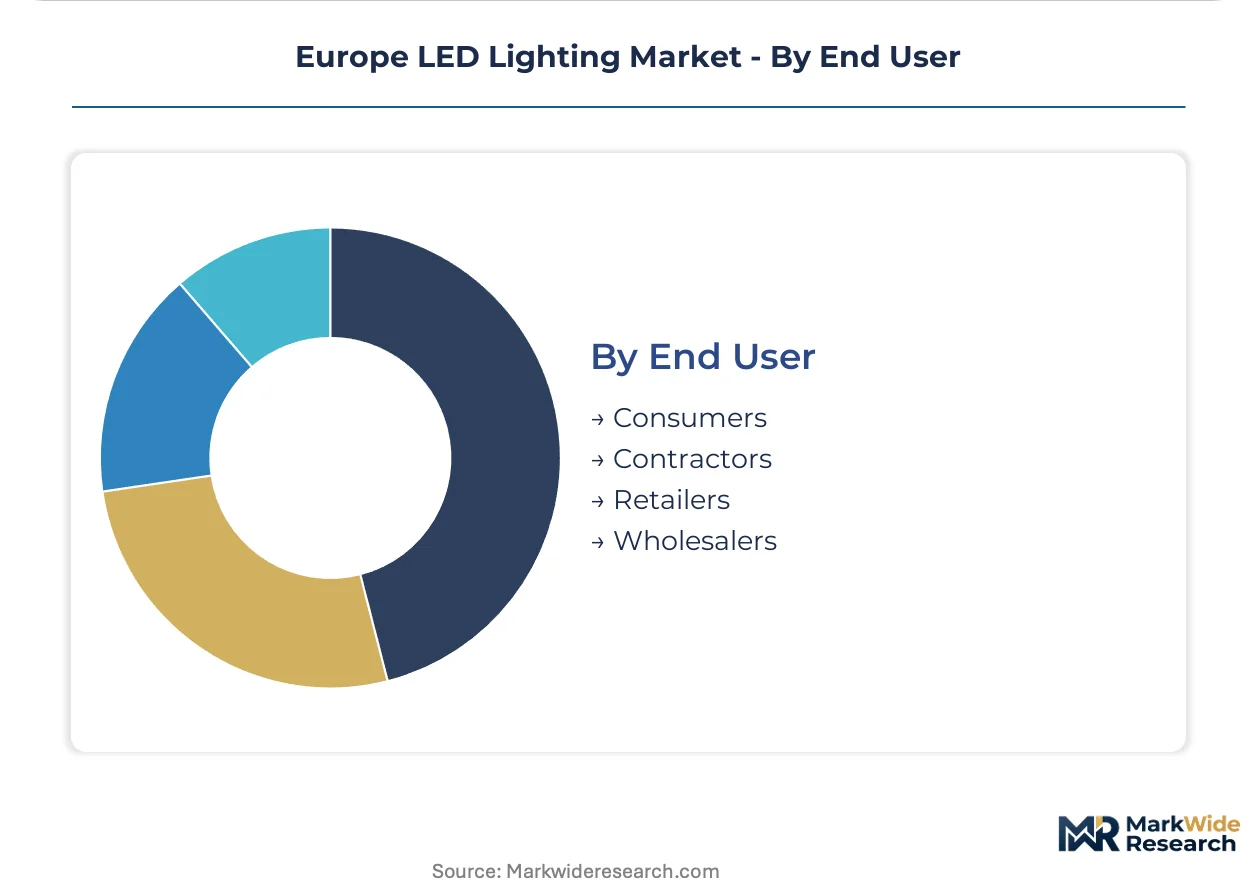
End User:
Channel control and specification authority determine margin capture, with direct contractor relationships outperforming wholesale distribution in value extraction.
- Contractors:Electrical installation firms with direct specification influence in commercial and municipal projects, increasingly engaged through split-package tendering that separates fixture supply from labor. French and Swedish commercial developers leverage this channel for energy performance contracting guarantees requiring independent efficacy verification.
- Wholesalers:German and Italian electrical distributors clearing remaining legacy fluorescent stock through discount channels ahead of Ecodesign Directive enforcement deadlines, while accelerating integrated LED troffer and linear system specifications.
- Consumers:Individual purchasers of residential replacement bulbs, a price-sensitive segment with minimal brand loyalty.
- Retailers:Big-box and specialty stores serving residential and small commercial DIY markets with standardized product ranges.
Contractors hold the dominant procurement position, though wholesalers are gaining specification influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal anchors demand concentration across member states, with national renovation mandates reshaping procurement patterns. Municipal infrastructure cycles and commercial real estate financing structures create distinct growth velocities by country.
Germany
Municipal street and roadway upgrades accelerate fixture replacement cycles across Baden-Württemberg and Bavaria. The national implementation of Ecodesign Directive 2019/2020 enforces minimum luminous efficacy thresholds that eliminate legacy fluorescent alternatives. Stuttgart's electrical engineering cluster concentrates solid-state lighting design talent for healthcare and industrial applications.
France
Commercial real estate retrofits dominate demand as ESG-linked financing structures prioritize deep energy renovations with guaranteed performance outcomes. The country's national building regulator enforces tightening efficiency requirements for installed luminaires under EU Green Deal transposition. Paris office developers split-package tendering separates fixture supply from installation labor to meet independent verification standards.
Spain
Peri-urban municipalities deploy solar-LED hybrid configurations to avoid grid-connection costs for remote street furniture. ECHA REACH restrictions on hazardous substances in electronics force rapid reformulation of solder alloys and encapsulant materials. Valencia and Barcelona metropolitan areas concentrate architectural specification relationships for premium commercial developments.
Netherlands
Healthcare facility designers specify compact chip-on-board LED arrays for surgical task lighting where heat sink mass reduction enables suspended cable mounting systems. The national market surveillance authority enforces CE marking verification procedures that extend product launch timelines. Eindhoven's semiconductor ecosystem sustains technology leadership in tunable white spectral outputs.
Sweden
Commercial developers leverage energy performance contracting guarantees requiring independent verification of installed efficacy. The country's building code transposes EU Green Deal renovation targets into mandatory minimum efficiency thresholds. Stockholm's renovation projects exhibit pronounced disintermediation as owners unbundle lighting procurement from general electrical contracts.
Europe LED Lighting Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with capital-rich incumbents controlling chip-to-fixture cost curves while mid-tier firms compete through architectural specification relationships. The competitive landscape bifurcates between semiconductor packaging capabilities and regulatory affairs functions. Three archetypes dominate: integrated semiconductor-to-fixture manufacturers, architectural specification specialists, and controls-integrated smart lighting providers. Dominant competitive moves include backward integration into semiconductor packaging and geographic expansion through municipal infrastructure partnerships.
Among Netherlands-based integrated leaders, Signify exemplifies the semiconductor-to-fixture archetype through in-house packaging capabilities. Austrian specification specialist Zumtobel Group occupies a position within the architectural tier, while German semiconductor manufacturer ams-OSRAM anchors the technology leadership vector for tunable white applications. These three represent distinct competitive positioning strategies across the value chain.
| Leading Market Players |
|---|
| Signify |
| Zumtobel Group |
| ams-OSRAM |
| Schréder |
| Fagerhult Group |
| LEDVANCE GmbH |
| Legrand |
| Schneider Electric |
| ERCO |
| Others |
Supply Flow & Price Mechanics
CE marking verification under Ecodesign Directive 2019/2020 gates supplier qualification while simultaneously stratifying price tiers across fixture categories. German and French electrical wholesalers enforce these compliance layers through procurement specifications that separate premium architectural luminaires from economy-grade replacement lamps. The dual function of regulatory certification—supply access and price positioning—compresses margin pools for non-compliant inventory while rewarding firms with established regulatory affairs functions.
Pricing Analysis
Price spreads between German and Spanish municipalities for street lighting fixtures reflect divergent procurement sophistication and ESG-linked financing availability. Three-tier pricing structure across premium architectural, standard commercial, and economy residential levels dominates fixture categories, with certification grade and volume scale as primary differentiation drivers. Cost compression in economy bulb tiers is intensifying due to mature residential penetration and wholesale discounting of legacy fluorescent clearance stock. Municipal contractors exhibit lowest price sensitivity given energy performance contracting guarantees, while residential consumers remain most price-sensitive with minimal brand loyalty.
Supply Chain Analysis
Inventory strategy bifurcates between just-in-time driver electronics procurement and strategic stockpiling of gallium nitride wafers subject to foundry allocation cycles. Semiconductor packaging concentrates in Germany, Taiwan, and South Korea, while phosphor materials for white LED production draw from concentrated Asian supply chains. Rare earth element dependencies for phosphor formulations and indium gallium nitride epitaxy wafers create single-source vulnerability for European fixture assemblers. Distribution runs through German and Italian electrical wholesalers clearing legacy stock while accelerating integrated LED troffer specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as building owners unbundle lighting procurement from general electrical contracts, creating specification niches for specialized design consultants and controls-integrated providers. This demand-side disintermediation rewards focused positioning over broad portfolio coverage.
For Market Incumbents: Secure architectural specification relationships through direct engagement with Paris and Stockholm commercial developers executing split-package tendering. Invest in in-house semiconductor packaging capabilities to control chip-to-fixture cost curves against emerging Asian competitors. Prioritize regulatory affairs capacity expansion to navigate EU AI Act autonomous controls compliance before enforcement timelines crystallize.
For New Entrants and Emerging Players: Anchor in Spanish peri-urban solar-LED hybrid deployments where grid-independence requirements favor nimble configuration specialists over integrated incumbents. Target French ESG-linked financing structures for deep energy renovation projects with performance-guaranteed retrofit offerings. Pursue direct contractor relationships in healthcare and education verticals specifying tunable white systems for circadian optimization.
For Investors and Strategic Acquirers: Ecodesign Directive enforcement timelines reshape the acquisition landscape toward firms with validated CE marking pathways and established national market surveillance authority relationships. Long-term viability centers on semiconductor-to-fixture integration depth and regulatory compliance infrastructure rather than pure volume scale. Monitor ECHA REACH substance restriction evaluations as inflection indicators for reformulation cost exposure across solder alloy and encapsulant supply chains.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Packaging | Signify's captive GaN wafer processing controls cost curves for high-efficacy street lighting chips. |
| Architectural Specification Partnership | Zumtobel Group's premium developer relationships in Vienna and Berlin secure margin-rich healthcare projects. |
| Regulatory Affairs Capacity Expansion | ams-OSRAM's Brussels compliance function positions for EU AI Act autonomous lighting controls enforcement. |
| Solar-LED Hybrid System Development | Schréder's off-grid configurations capture Spanish municipal grid-independence procurement. |
| Human-Centric Spectral Tuning R&D | Fagerhult Group's tunable white platforms address German healthcare circadian rhythm specifications. |
Methodological Framework
Initial hypotheses were tested against primary input from solid-state lighting design engineers, municipal procurement officers, commercial real estate developers, and electrical installation contractors and refined through secondary validation. Primary fieldwork encompassed specification interviews with architectural lighting consultants in Stuttgart, Eindhoven, and Paris alongside distributor channel assessments across German and Italian wholesale networks. Secondary sources included Ecodesign Directive enforcement documentation from national market surveillance authorities, ECHA REACH substance restriction timelines, EU Green Deal national transposition filings, and customs trade data for LED component imports. Bottom-up fixture shipment estimates were triangulated against top-down construction spend allocation models.
Variance decomposition across product type, application context, technology tier, and end-user channel anchored the analytical framework over the projection horizon. Segmentation dimensions encompassed fixture form factor, installation setting, intelligence integration level, and procurement authority type. CAGRs were derived from replacement cycle velocity assumptions tied to regulatory enforcement timelines and ESG-linked financing penetration rates. Industry-specific forecast inputs incorporated gallium nitride semiconductor efficacy improvement curves and solar-LED hybrid battery cost trajectories.
Decision-makers should treat outputs as directional under base assumptions of sustained EU Green Deal renovation funding and stable rare earth element supply access; material deviation would warrant model refresh. Forecasts reflect these assumptions without incorporating extreme scenarios of trade restriction escalation or technology substitution acceleration. Revision becomes warranted when Ecodesign Directive enforcement intensity or phosphor material cost volatility crosses thresholds that alter fixture replacement economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Dual-Digit 7 Segment LED Displays Market
LED
Light Emitting Diode (LED) Backlight Display Market
LED
Led Video Walls Market
LED
South America LED Lighting Market
LED
Vietnam LED Lighting Market
LED
Mini LED Market
LED
Thailand LED Market
LED
Programmable LED Drivers Market
LED
Global Industrial and Commercial LED Lighting Market
LED
East Africa LED Lighting Market
LED
Middle East and Africa Outdoor LED Lighting Market
LED
UK Outdoor LED Lighting Market
LED
US LED Downlight Market
LED
LED Light Bar Market
LED
North America Micro-LED Display Market
LED
Four-Digit 7 Segment LED Displays Market